
 Nutritional Labeling Market | 2026-2036
Nutritional Labeling Market Size, Share, and Industry Trends Forecast 2026-2036
Nutritional Labeling Market Analytics
Food manufacturers are gaining procurement influence as institutional buyers unwind their historical dominance over label specification. Amcor Plc leverages its integrated film and label platform to capture multi-category food accounts. Avery Dennison Corporation dominates the premium adhesive substrate segment through direct R&D partnerships with European regulators. CCL Industries specializes in high-speed digital printing lines that serve mid-tier snack producers seeking compliant variable data runs.
Nutritional labeling denotes the printed, adhered, or digitally rendered information systems that communicate caloric content, macronutrient breakdown, ingredient provenance, and allergen warnings on consumer-packaged goods, typically manufactured through flexographic, digital, or thermal transfer processes onto pressure-sensitive films or direct-print substrates. The primary commercial purpose is to satisfy mandatory disclosure laws while enabling brand differentiation at the point of purchase. Packaged Foods leads volume as legacy SKUs require retrofitting for updated FDA and EU serving-size rules, while Allergen Information commands premium positioning due to liability exposure and specialized ink formulations. Ingredient List formats face margin compression from template-standardized layouts, though digital hybrid presses are creating new margin pools in short-run customization for regional recipe variants.
The FDA enforces nutritional fact panel modernization through updated Daily Value reference levels and added-sugar line-item mandates, directly dictating label redesign cycles and substrate sizing across the US packaged food sector. EFSA and the EU Green Deal framework impose recyclability targets on multi-layer label constructions, forcing converters to reformulate adhesives and face stocks. Health Canada maintains parallel but non-identical allergen threshold rules, fragmenting North American production planning. Stakeholders must monitor divergence between US and EU serving-size measurement protocols, as misalignment in portion definitions threatens to bifurcate inventory and escalate compliance costs for brands operating across both jurisdictions.
Market Dynamics
Regulatory divergence between the FDA and EFSA is fragmenting label design standards, forcing converters to maintain parallel substrate inventories and dual-format printing capabilities across transatlantic supply chains.
Growth Catalysts
- EU Green Deal recyclability mandates:The framework compels food brands to source mono-material pressure-sensitive labels, stimulating converter R&D in wash-off adhesives and compatible face stocks.
- Digital hybrid press adoption:Mid-tier snack producers deploy these systems for compliant variable data runs, collapsing minimum order quantities and enabling regional recipe variants without plate changeover costs.
- Germany:Food processing sector digitization of supply chain traceability concentrates demand for serialized nutritional labels with embedded authentication features.
Market Restraints
- Petrochemical resin volatility:Pressure-sensitive adhesive formulations depend on acrylic and rubber-based feedstocks subject to energy-price-driven cost swings.
- Specialized ink supply concentration:Low-migration UV and water-based formulations for food-contact labels concentrate among German and Swiss chemical suppliers.
- Multi-layer construction complexity:EFSA recyclability targets conflict with legacy silicone release liner systems, creating technical dead-ends for existing capital equipment.
Strategic Opportunities
- India FSSAI alignment:The regulator's pending harmonization with Codex Alimentarius standards creates first-mover advantage for converters offering pre-compliant label templates.
- Blockchain-integrated smart labels:Convergence of NFC inlays with nutritional data printing enables real-time ingredient provenance verification for premium protein brands.
- Direct-to-retailer digital portals:Private-label grocers bypass traditional distributors to specify custom nutritional panels, opening channel access for agile converters.
Industry Challenges
- Color management certification:G7 Master qualification requirements for consistent nutritional fact panel reproduction strain smaller converter operations.
- ERP integration friction:Legacy MIS systems at family-owned label shops resist seamless data exchange with food manufacturer PLM platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutritional Labeling Market |
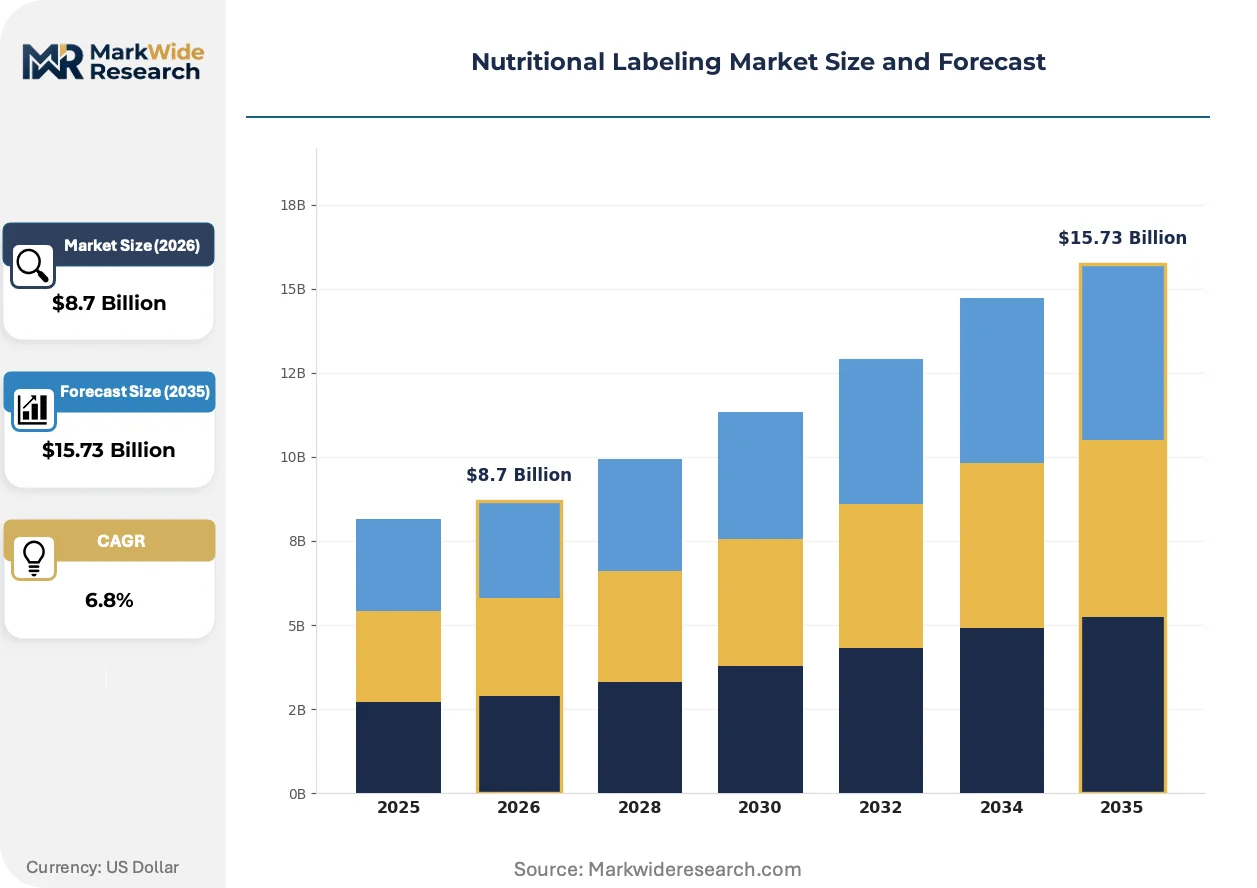
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Packaged Foods, Beverages, Supplements, Snacks Label Format: Nutritional Facts, Ingredient List, Allergen Information, Serving Size End User: Food Manufacturers, Retailers, Restaurants, Consumers Regulatory Compliance: FDA Standards, EU Regulations, Health Claims, Organic Certification |
| Companies Covered | Amcor Plc, Berry Global Inc, Sealed Air Corporation, Avery Dennison Corporation, 3M Company, Fuji Seal International, CCL Industries, Mondi Group, Tetra Laval Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutritional Labeling Market Evolving Landscape
Digital printing architectures and adhesive chemistry are converging to collapse production economics for short-run nutritional labels while regulatory pressure on material circularity intensifies substrate innovation cycles.
Water-based inkjet systems are bifurcating the narrow-web converter base. Premium food brands in France and Switzerland adopt these presses for allergen-highlight color consistency, while commodity snack producers retain flexographic lines for volume stability. The technology split is compressing margin pools at mid-tier equipment tiers as buyers polarize toward either speed or customization.
REACH Annex XVII restrictions on persistent organic pollutants now capture certain silicone release coatings used in thermal transfer label constructions. German converters reformulate adhesive platforms to eliminate affected chemistries ahead of sunset dates. The regulation most impacts dairy and ready-meal segments where direct thermal labels dominate variable weight pricing applications.
Retail buyers now unbundle nutritional label procurement from primary packaging contracts. Discounters in Poland and Spain source labels separately through specialized converters, fragmenting historical supplier relationships. Food manufacturers respond by building in-house specification teams to retain design control, reversing decades of outsourced procurement delegation.
Nutritional Labeling Market Segmentation
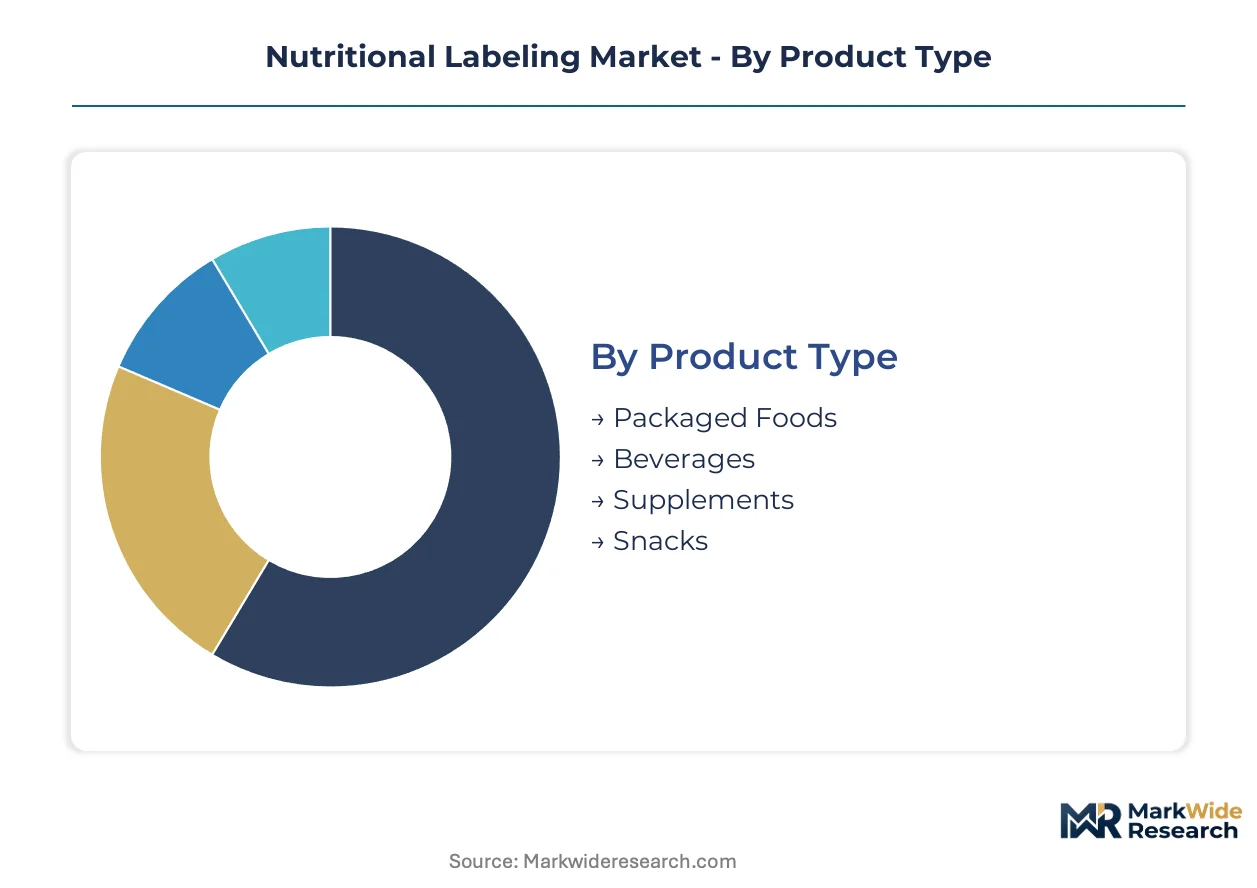
Converters configure production lines around segment-specific substrate and ink requirements. Divergent regulatory deadlines across product categories force parallel inventory strategies rather than unified capacity planning.
Product Type:
Domestic consumption patterns dominate Packaged Foods and Snacks demand, while Supplements and Beverages carry heavier export certification burdens for cross-border compliance.
- Packaged Foods:Flexographic and digital hybrid presses print pressure-sensitive films for legacy SKU retrofitting. German food processors drive volume for updated EU serving-size rules combined with supply chain traceability mandates.
- Snacks:High-speed narrow-web lines handle variable data runs for regional recipe variants. Mid-tier producers in Poland and Spain collapse minimum order quantities through digital press adoption.
- Beverages:Curved-surface adhesive compatibility and moisture-resistant face stocks define technical specifications.
- Supplements:Health claims panels require specialized low-migration ink formulations for direct-contact applications.
Packaged Foods commands the established base. The steepest expansion runs through Snacks.
Label Format:
Cost tiers separate standardized template formats from premium liability-sensitive applications requiring specialized material engineering.
- Allergen Information:High-visibility color blocks and specialized UV-stable inks reduce liability exposure. French and Swiss premium brands adopt water-based inkjet systems for color consistency alongside REACH-compliant adhesive platforms.
- Nutritional Facts:FDA and EFSA serving-size measurement divergence forces dual-format substrate inventories. Transatlantic brands face escalated compliance costs from misaligned portion definitions.
- Ingredient List:Template-standardized layouts compress margins despite digital hybrid press opportunities in short-run regional customization.
- Serving Size:Variable weight pricing applications in dairy and ready-meal segments depend on direct thermal constructions facing REACH Annex XVII silicone coating restrictions.
Nutritional Facts absorbs the volume base. Allergen Information captures the premium tier expansion.
End User:
Customer type determines specification control—food manufacturers rebuild in-house teams while retailers fragment historical supplier relationships through unbundled procurement.
- Food Manufacturers:Integrated film and label platforms serve multi-category accounts requiring synchronized redesign cycles for FDA modernized Daily Value mandates.
- Retailers:Private-label grocers in Poland and Spain bypass distributors to specify custom panels through direct digital portals.
- Restaurants:Menu labeling mandates for chain establishments drive thermal transfer demand for variable data durability.
- Consumers:Blockchain-integrated smart labels with NFC inlays enable real-time provenance verification for premium protein subscription brands.
Food Manufacturers retain the volume foundation. Retailers are climbing the fastest through procurement restructuring.
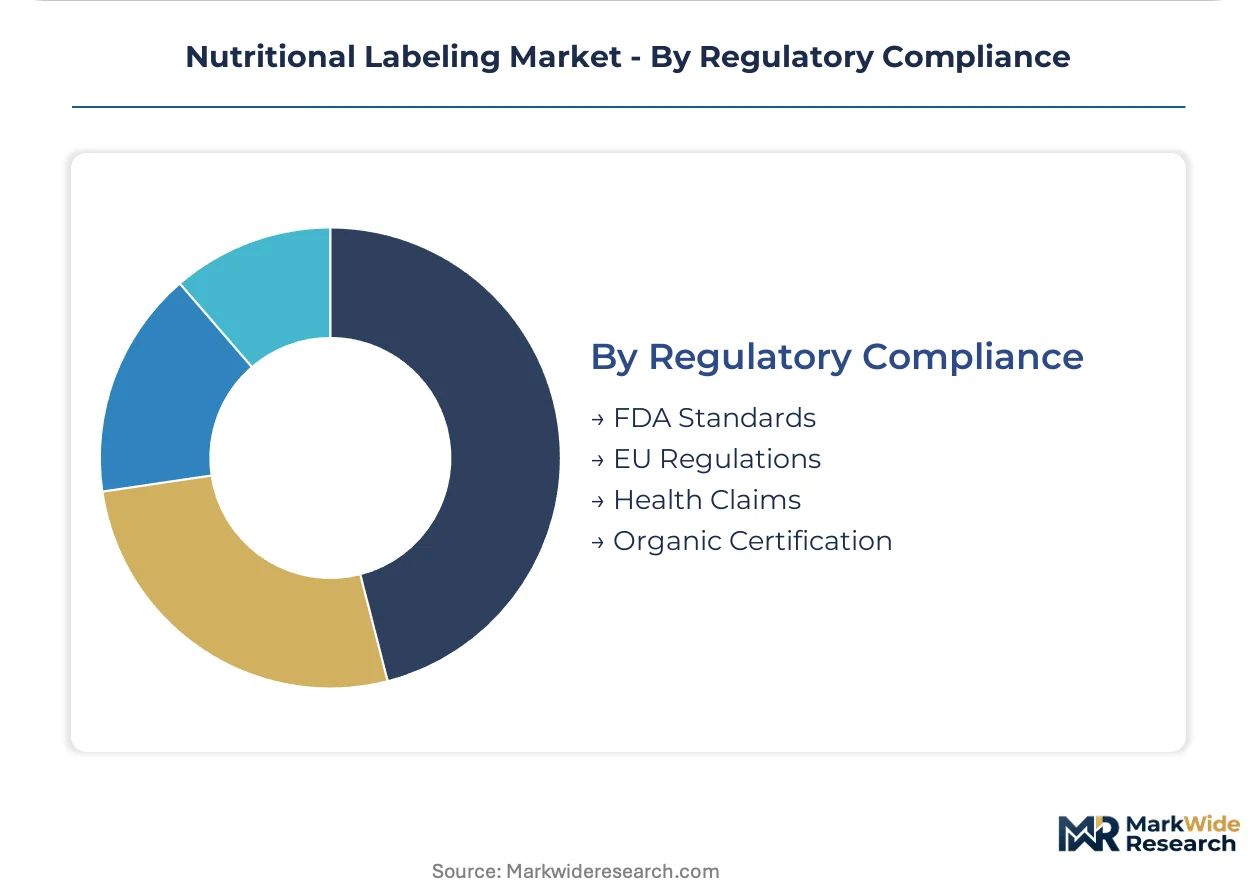
Regulatory Compliance:
Application maturity separates legacy disclosure standards from emerging certification frameworks requiring converter pre-compliance investment.
- FDA Standards:Modernized fact panels with added-sugar line items dictate substrate resizing across US packaged food production.
- EU Regulations:EFSA recyclability targets and F-Gas Regulation compliance push converters toward wash-off adhesives and mono-material constructions.
- Health Claims:Substantiation documentation requirements concentrate premium label production among G7 Master qualified converters.
- Organic Certification:India FSSAI alignment with Codex Alimentarius standards creates first-mover template opportunities for export-ready converters.
FDA Standards and EU Regulations anchor the compliance base. Organic Certification is expanding most quickly through emerging market harmonization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in European label substrate distribution, connecting Ruhr industrial converters to Atlantic trade routes. This infrastructure anchors transatlantic supply chains for pressure-sensitive adhesive films.
Germany
Bavarian food processors digitize supply chain traceability, concentrating demand for serialized nutritional labels with embedded authentication. The EU F-Gas Regulation and REACH Annex XVII compel Baden-Württemberg converters to reformulate wash-off adhesives ahead of silicone coating sunset dates. The Stuttgart industrial corridor hosts specialized narrow-web digital press clusters serving premium dairy brands.
United States
Midwestern packaged food manufacturers retrofit legacy SKUs for FDA modernized Daily Value mandates, driving substrate resizing across Illinois and Ohio production basins. The FDA's added-sugar line-item disclosure rules force synchronized redesign cycles for multi-category accounts. Greater Chicago hosts integrated film and label platforms capturing volume from institutional buyers.
France
Parisian premium brands adopt water-based inkjet systems for allergen-highlight color consistency, separating specification control from commodity snack producers. EFSA recyclability targets under the EU Green Deal push converters toward mono-material constructions. The Lyon chemical corridor supplies low-migration UV formulations for direct-contact supplement applications.
India
Maharashtra's food processing sector prepares for FSSAI harmonization with Codex Alimentarius standards, creating template demand for export-ready converters. The regulator's pending alignment with international disclosure rules drives pre-compliance investment in Mumbai-anchored label shops. Gujarat's specialty chemical cluster develops REACH-compatible adhesive platforms for European-bound shipments.
Poland
Private-label discounters unbundle nutritional label procurement from primary packaging contracts, fragmenting historical supplier relationships in the Warsaw logistics basin. Retail buyers source directly through specialized converters, bypassing traditional distributors. The Silesian industrial zone hosts agile digital press operations serving variable data runs for regional recipe variants.
Nutritional Labeling Market Competitive Landscape
Concentration sits with integrated packaging conglomerates and specialized adhesive substrate developers. Three structural tiers separate global film-label platforms from regional digital converters and niche compliance specialists. Strategic moves cluster around backward integration into adhesive resin production and technology licensing for wash-off formulations.
Among diversified packaging platforms, Amcor Plc and Avery Dennison Corporation occupy positions spanning film extrusion through finished label delivery. CCL Industries exemplifies the mid-tier digital specialist archetype, with equipment configurations targeting variable data runs. These three entities represent distinct competitive vectors: integrated supply chain control, premium adhesive substrate dominance, and agile short-run customization capability.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Inc |
| Sealed Air Corporation |
| Avery Dennison Corporation |
| 3M Company |
| Fuji Seal International |
| CCL Industries |
| Mondi Group |
| Tetra Laval Group |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German food processors and Baden-Württemberg converters lock in acrylic resin supply and flatten price volatility across the EU F-Gas compliance cycle. These arrangements tether label pricing to petrochemical index movements while securing wash-off adhesive capacity ahead of REACH Annex XVII sunset dates.
Pricing Analysis
Volume-discount tiering structures stratify across premium allergen-compliant labels, standard nutritional fact panels, and economy ingredient list formats. Premium tiers capture G7 Master certification costs and specialized low-migration UV ink formulations, while economy tiers face margin compression from template-standardized layouts. Pricing pressure intensifies in mid-tier digital hybrid press segments as buyers polarize toward either speed or customization. Private-label grocers in Poland and Spain exhibit highest price sensitivity through unbundled procurement, whereas French premium brands show lowest sensitivity for allergen-highlight color consistency.
Supply Chain Analysis
Strategic stockpile preferences dominate German and Swiss converter operations facing REACH Annex XVII silicone coating restrictions, while just-in-time inventory governs commodity snack producers in Poland and Spain. Raw material dependencies center on acrylic and rubber-based petrochemical resins, low-migration UV formulations from the Lyon chemical corridor, and pressure-sensitive films extruded in Bavaria. Single-source vulnerability concentrates in German and Swiss chemical suppliers for food-contact ink formulations. Distribution runs through the Port of Hamburg's container infrastructure connecting Ruhr industrial converters to Atlantic trade routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nutritional labeling market sits in a cyclical recovery phase driven by FDA modernized Daily Value mandates forcing synchronized redesign cycles across legacy packaged food SKUs.
For Market Incumbents: Shield margin pools by backward integrating into adhesive resin production to offset petrochemical volatility, while accelerating G7 Master certification investment to capture health claims panel premiums. Digital hybrid press capacity expansion in the Stuttgart industrial corridor defends against agile mid-tier competitors collapsing minimum order quantities for regional recipe variants.
For New Entrants and Emerging Players: Lead with blockchain-integrated smart label platforms targeting premium protein subscription brands seeking real-time ingredient provenance verification. India's pending FSSAI harmonization with Codex Alimentarius standards offers the most penetrable geography for pre-compliant template offerings. Direct-to-retailer digital portals bypassing traditional distributors provide the critical go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized adhesive substrate developers with REACH-compliant wash-off formulation pipelines. Long-term viability over the next decade hinges on converter positioning for EU Green Deal recyclability mandates and FDA-EFSA regulatory divergence management. Watch for inflection when India FSSAI alignment deadlines trigger export-ready converter acquisition demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Wash-off Adhesive R&D Partnership | REACH Annex XVII compliance secures dairy and ready-meal segment access ahead of silicone coating bans. |
| Digital Hybrid Press Deployment | Mid-tier snack producers in Poland collapse minimum order quantities for compliant variable data runs. |
| G7 Master Certification Investment | Health claims panel production concentrates among qualified converters serving French premium brands. |
| Blockchain-NFC Label Integration | Premium protein brands adopt real-time provenance verification to differentiate at point of purchase. |
| Direct-to-Retailer Portal Launch | Private-label grocers in Spain bypass distributors to specify custom nutritional panels. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA guidance documents, EFSA scientific opinions, EU F-Gas Regulation filings, and customs trade data for pressure-sensitive adhesive films. Primary interviews engaged label converter operations managers, food manufacturer packaging procurement leads, regulatory affairs specialists at adhesive chemical suppliers, and retail category buyers at private-label grocers. Bottom-up triangulation across converter capacity surveys and top-down validation through packaged food production volume estimates anchor the analytical framework.
Segmentation dimensions modeled span product type, label format, end user archetype, and regulatory compliance tier across the projection horizon. CAGRs derive from regression analysis of historical label substrate demand against packaged food SKU proliferation rates and regulatory redesign cycle frequency. Forecast inputs incorporate EU Green Deal recyclability mandate implementation timelines and FDA serving-size measurement protocol divergence scenarios.
Underlying assumptions cover petrochemical resin price stability and REACH enforcement consistency, with deviation risk concentrated in tariff exposure for acrylic imports and FSSAI alignment schedule delays. Revision becomes warranted when regulatory divergence between FDA and EFSA serving-size protocols crosses thresholds forcing inventory bifurcation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety and Standards
Food Authenticity Market
Food Safety and Standards
Food Certification Market
Food Safety and Standards
Pathogen Reduction Systems Market
Food Safety and Standards
Blockchain Food Traceability Market
Food Safety and Standards
Natural Antimicrobials Market
Food Safety and Standards
GMO Labeled Food Market
Food Safety and Standards
Food Safety Software Market
Food Safety and Standards
Quality Assurance and Quality Control Market
Food Safety and Standards
Global Cold Chain Monitoring Market
Food Safety and Standards
Precision Food Thermometers Market
Food Safety and Standards
Bar Inspection System Market
Food Safety and Standards
Food and Beverage Industrial Disinfection and Cleaning Market
Food Safety and Standards
Cold-Chain Friendly Post-Harvest Sanitizing Mist Market
Food Safety and Standards
Food Irradiation Market
Food Safety and Standards
Automatic Distillation Analyzer Market
Food Safety and Standards
Testing, Inspection, and Certification Market