
 Food Irradiation Market | 2026-2036
Food Irradiation Market Size, Share, and Industry Trends Forecast 2026-2036
Food Irradiation Market Analysis
Maintenance contracts for cobalt-60 source replenishment and dosimetry calibration is recalibrating what irradiation providers actually sell. Sterigenics International leverages its integrated logistics network to control source supply chains across North America. STERIS Corporation anchors its position through specialized electron beam systems for protein processing. Ionisos SA dominates European medical-to-food crossover irradiation capacity.
Food irradiation exposes packaged or bulk foodstuffs to ionizing radiation at doses between 1 and 10 kilograys to eliminate pathogens, delay spoilage, or halt insect reproduction. Electron beam technology leads capital deployment due to its absence of radioactive source management obligations. Gamma ray systems retain margin concentration in spices and dried ingredients where deep penetration outweighs throughput speed. Application demand tilts toward preservation as exporters seek shelf-life extension for ocean freight routes.
The FDA regulates food irradiation as a food additive under 21 CFR 179, while the USDA's FSIS mandates specific labeling for irradiated meat and poultry. The EFSA reviews updated toxicological data periodically, influencing member state adoption thresholds. Stakeholders must monitor cobalt-60 supply volatility from nuclear reactor decommissioning schedules and pivot sourcing strategies accordingly.
Market Dynamics
Cobalt-60 supply volatility from aging nuclear reactors is forcing irradiation providers to accelerate electron beam capacity deployment and renegotiate long-term source contracts with revised pricing mechanisms.
Growth Catalysts
- FSMA enforcement:The FDA's updated Food Safety Modernization Act mandates validated pathogen reduction methods for high-risk commodities, pushing processors toward irradiation as a proven intervention.
- Spice export requirements:Phytosanitary standards from importing nations now mandate insect disinfestation for dried ingredients, concentrating demand in gamma ray systems with deep penetration capability.
- Cold-chain expansion:Southeast Asian food exporters are adopting irradiation to extend shelf life for ocean freight routes where refrigeration infrastructure remains fragmented.
Market Restraints
- Radioisotope supply concentration:Cobalt-60 production concentrates in a handful of aging CANDU reactors in Canada and Russia, creating sourcing vulnerability for gamma-dependent facilities.
- Capital intensity barrier:Electron beam systems require shielding vaults and high-voltage infrastructure that lock up capital for seven to ten years before operational breakeven.
- Consumer acceptance friction:Mandatory radura labeling under 21 CFR 179 triggers purchase hesitation in retail channels despite safety validation from EFSA and WHO.
Strategic Opportunities
- India facility licensing:The Food Safety and Standards Authority of India is accelerating commercial irradiation facility approvals, opening capacity gaps for equipment suppliers and service operators.
- Pharmaceutical crossover:Medical sterilization providers possess underutilized cobalt-60 capacity that can pivot to food applications during off-peak scheduling windows.
- X-ray technology maturation:High-energy X-ray systems are converging with electron beam architecture to offer penetration depth approaching gamma without radioactive source obligations.
Industry Challenges
- Dosimetry certification backlog:Third-party validation laboratories face six-to-nine month queues for dose mapping studies, delaying facility commissioning timelines.
- Legacy ERP integration:Food processors running SAP or Oracle systems require custom middleware to connect irradiation lot tracking with existing inventory management workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Irradiation Market |
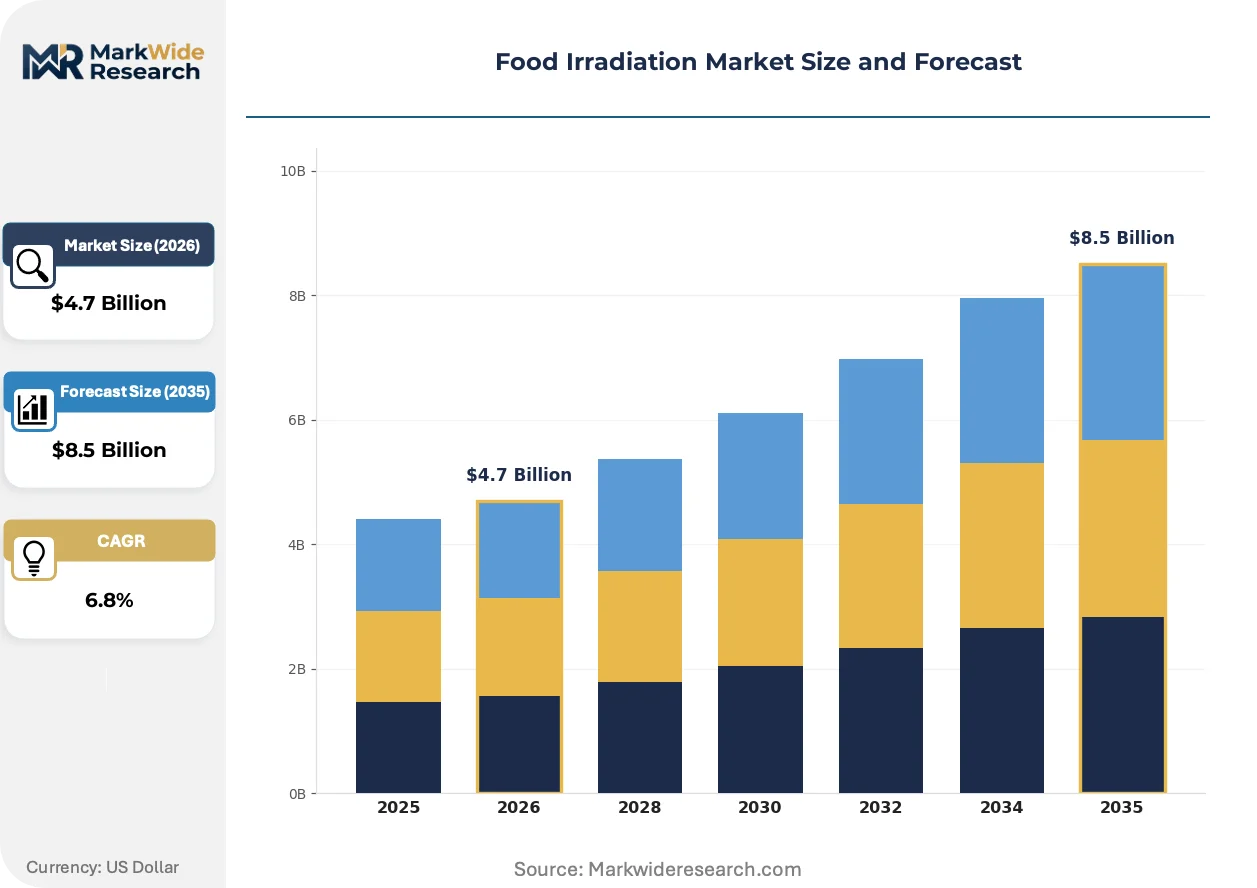
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gamma Rays, Electron Beams, X-Rays, UV Radiation Product Type: Meat, Fruits, Vegetables, Grains End User: Food Manufacturers, Retailers, Restaurants, Exporters Application: Preservation, Sterilization, Disinfestation, Quality Improvement |
| Companies Covered | Sterigenics International, Food Technology Service, Gray Star, Ionisos SA, Nordion, Sadex Corporation, Scantech Sciences, STERIS Corporation, IBA Industrial Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Irradiation Market Emerging Trajectories
Real-time dosimetry and automated material handling are compressing unit processing costs while regulatory harmonization efforts across major trading blocs are reducing compliance fragmentation for multinational operators.
Robotic pallet handling systems paired with continuous beam scanning technology are automating throughput optimization in high-volume facilities. Spice processors in India and Vietnam are adopting these configurations to meet export volume requirements without proportional labor expansion. The technology is automating dose uniformity assurance that previously required manual repositioning and extended dwell times.
The EU Green Deal's chemical reduction targets are accelerating substitution of fumigants with physical pasteurization methods in imported dried goods. Member state food safety authorities are aligning national implementation timelines with EFSA's updated toxicological opinions on irradiated commodities. Dried aromatic herb processors in Southern Europe are responding fastest, driven by organic certification requirements that prohibit chemical residues.
Exporters are consolidating irradiation service procurement under multi-year tolling agreements rather than spot-market transactions. Large spice traders in the Netherlands and Singapore are negotiating dedicated capacity blocks with facility operators, displacing fragmented spot purchasing. This concentration is most visible in Rotterdam and Mumbai port zones where inspection and processing co-location reduces logistics friction.
Food Irradiation Market Segmentation
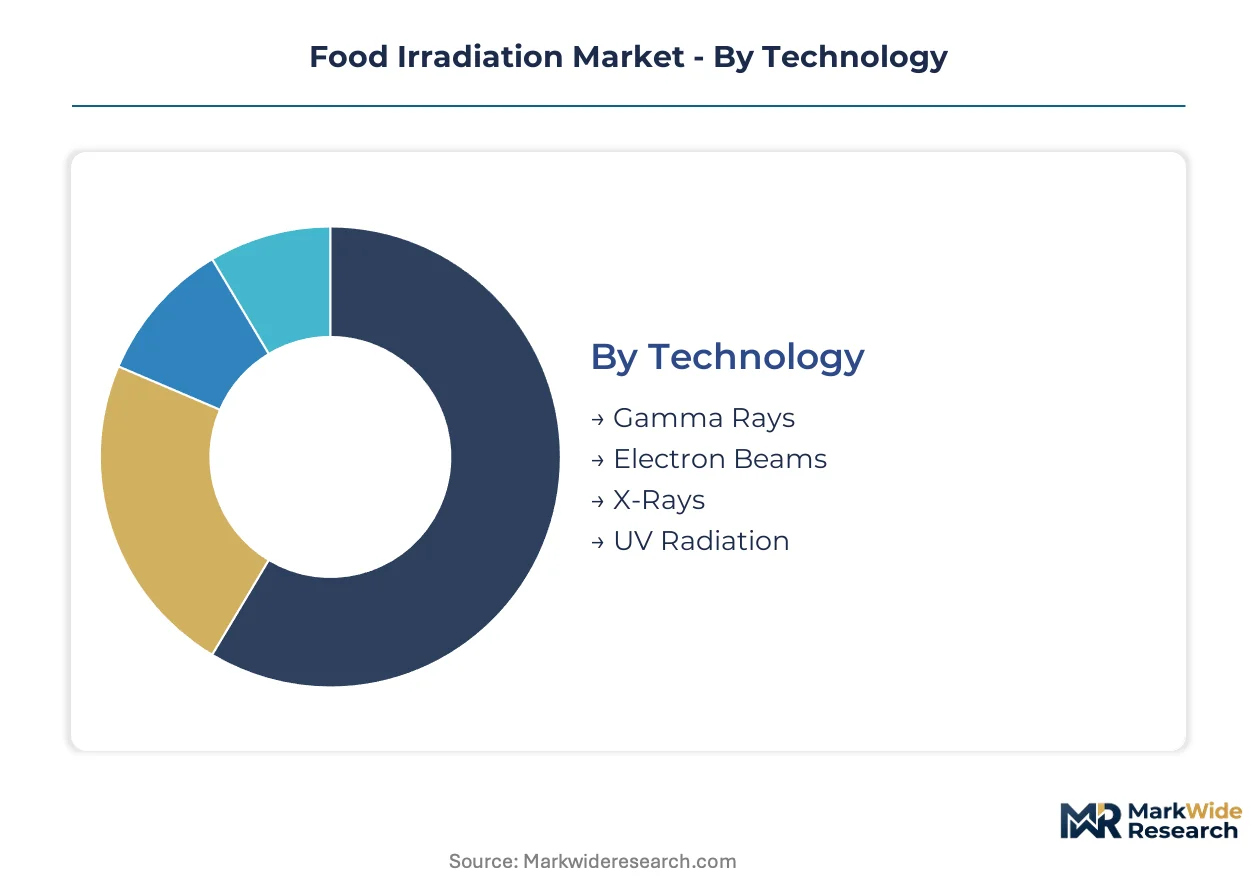
Technology selection dictates capital deployment patterns and regulatory compliance obligations across food irradiation operations. Product type and application combinations determine dose requirements and facility configuration decisions for processors.
Technology:
Capital intensity and source management obligations drive buyer decisions between radioactive and accelerator-based systems.
- Gamma Rays:Cobalt-60 emission delivers penetration depths exceeding 40 centimeters through dense spice loads and frozen protein blocks. Demand concentrates in India and Vietnam where phytosanitary export requirements for dried ingredients favor deep-penetration capability over throughput speed.
- Electron Beams:High-voltage accelerators generate ionizing radiation without radioactive isotope handling obligations, reducing regulatory burden and security costs. Food manufacturers in the US and Germany are prioritizing electron beam deployment to eliminate cobalt-60 supply volatility from aging CANDU reactors.
- X-Rays:Bremsstrahlung conversion of electron energy achieves gamma-comparable penetration without source replenishment contracts.
- UV Radiation:Surface-level decontamination for liquid processing and packaging materials where penetration depth requirements remain minimal.
Volume sits with Gamma Rays; growth tilts toward Electron Beams.
Product Type:
Perishability windows and pathogen risk profiles shape irradiation adoption intensity across commodity categories.
- Meat:Poultry and ground beef processors deploy irradiation as a validated intervention against Salmonella and E. coli under USDA FSIS enforcement mandates. Exporters from Brazil and Thailand are integrating irradiation into cold-chain gaps for ocean freight to European ports.
- Fruits:Mango and papaya shipments to the US and Japan require fruit fly disinfestation certification that irradiation provides without methyl bromide residue concerns.
- Vegetables:Leafy green processors address Listeria contamination risks through low-dose treatment.
- Grains:Rice and wheat exporters deploy irradiation for insect population control in bulk storage and containerized shipment.
Procurement concentrates in Meat; steepest expansion trajectory emerges in Fruits.
End User:
Supply chain position determines whether irradiation occurs at origin, processing, or distribution stages.
- Food Manufacturers:Integrated processing facilities with captive irradiation capacity or tolling agreements for ingredient pasteurization.
- Retailers:Private-label meat and produce programs requiring pathogen reduction for brand protection.
- Restaurants:Chain operators with centralized commissary operations exploring irradiation for supply consistency.
- Exporters:Trading houses in Rotterdam, Mumbai, and Singapore contracting dedicated capacity blocks for phytosanitary compliance.
Revenue concentrates with Food Manufacturers; contract volume is climbing fastest among Exporters.
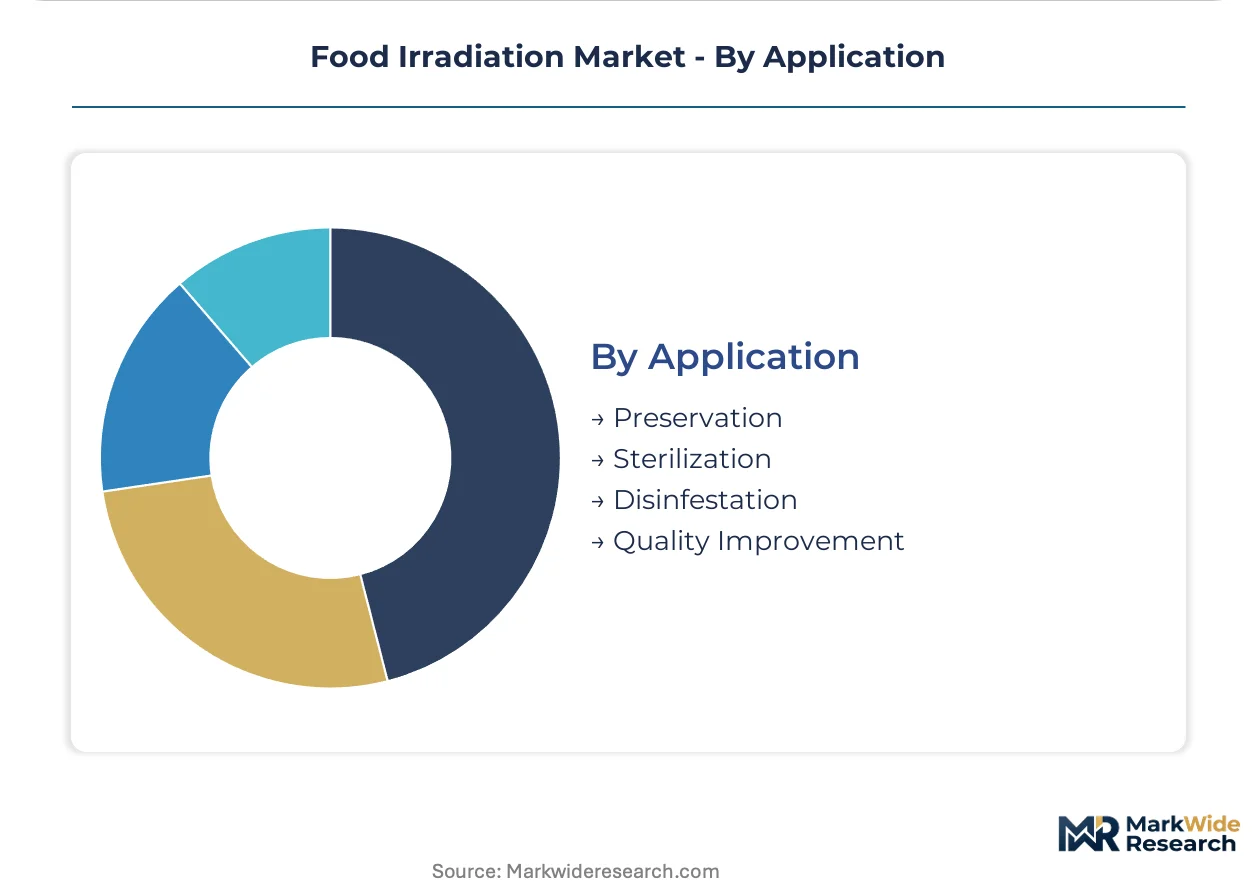
Application:
Dose specification varies by intended biological outcome, from shelf-life extension to commercial sterilization.
- Preservation:Low-dose treatment delays spoilage microbial growth in refrigerated and ambient distribution channels.
- Sterilization:High-dose elimination of spoilage and pathogenic organisms for shelf-stable meal components and hospital food service.
- Disinfestation:Targeted insect mortality in stored grains, dried fruits, and spices without chemical fumigant residues prohibited under EU organic certification.
- Quality Improvement:Sprout inhibition in potatoes and onions through cell division disruption.
Facility utilization centers on Disinfestation; capacity additions favor Preservation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in North America and Europe while consumption growth accelerates across Asian export corridors. Facility operators in Canada and Russia control cobalt-60 supply chains that gamma-dependent processors require. Cold-chain gaps in Southeast Asia and Latin America are driving irradiation adoption as an alternative to refrigeration infrastructure.
United States
Poultry processors and spice importers deploy irradiation to satisfy FDA Food Safety Modernization Act mandates for validated pathogen reduction. The USDA FSIS maintains strict labeling requirements under 21 CFR 179 that shape retail channel acceptance. Chicago and Houston host the densest concentration of commercial gamma and electron beam facilities serving domestic protein processors.
India
Mango and rice exporters require phytosanitary certification for US and European markets that irradiation provides without methyl bromide residues. The Food Safety and Standards Authority accelerates commercial facility licensing through streamlined approval pathways. Mumbai and Navi Mumbai cluster the majority of operational gamma installations serving spice trading houses.
Vietnam
Shrimp and dragon fruit exporters adopt irradiation to extend shelf life for ocean freight routes to Japan and Australia. The Ministry of Agriculture and Rural Development aligns national standards with CODEX Alimentarius guidelines for international trade acceptance. Ho Chi Minh City port zones concentrate new facility investment backed by Singapore-based logistics operators.
Germany
Organic dried herb processors substitute irradiation for chemical fumigants prohibited under EU organic certification rules. The EFSA periodic review of toxicological data influences member state implementation timelines for permitted food categories. Bavaria and North Rhine-Westphalia house electron beam specialists serving Central European ingredient manufacturers.
Brazil
Beef and poultry exporters integrate irradiation into cold-chain gaps for European and Middle Eastern port destinations. The National Health Surveillance Agency regulates facility licensing under Mercosur harmonized standards. São Paulo state dominates operational capacity with gamma installations serving the southeastern protein processing corridor.
Food Irradiation Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent technology deployment models. Gamma facility operators absorb cobalt-60 source replenishment obligations and shielding maintenance costs that electron beam providers avoid entirely. Three archetypes dominate: integrated logistics networks controlling isotope supply chains, specialized accelerator manufacturers, and medical sterilization providers pivoting excess capacity. Competitive moves center on long-term tolling agreements with spice traders and accelerated electron beam deployment to escape radioisotope volatility.
Among North American integrated service providers, Sterigenics International and STERIS Corporation exemplify contrasting technology commitments. Sterigenics leverages logistics network control across source-dependent gamma operations. STERIS anchors positioning through accelerator-based systems that eliminate radioactive material handling obligations. Ionisos SA represents the European medical-to-food crossover archetype, utilizing cobalt-60 capacity flexibility between healthcare and commodity processing schedules.
| Leading Market Players |
|---|
| Sterigenics International |
| Food Technology Service |
| Gray Star |
| Ionisos SA |
| Nordion |
| Sadex Corporation |
| Scantech Sciences |
| STERIS Corporation |
| IBA Industrial Solutions |
| Others |
Supply Flow & Price Mechanics
Electron beam capacity deployment is reshaping cost economics while concentrating supply leverage among accelerator manufacturers in Germany and the United States. This technology shift eliminates cobalt-60 replenishment contracts but locks capital into high-voltage infrastructure with decade-long payback horizons, tilting procurement power toward equipment financiers.
Pricing Analysis
Margin tightening in gamma-dependent operations traces to cobalt-60 contract renegotiations with aging CANDU reactor operators. Contract-based long-term offtake agreements dominate, with volume scale and certification tier (FDA-validated versus general phytosanitary) as primary price differentiation drivers. Cost-down pressure accelerates as spice traders consolidate procurement under multi-year tolling arrangements. Exporters with dedicated capacity blocks show least price sensitivity; spot-market processors face squeeze.
Supply Chain Analysis
Cobalt-60 supply rests on Canadian and Russian nuclear reactor output, with high-voltage accelerator components drawing from German and Japanese precision engineering. Electron beam systems hinge on specialized power supply units and vacuum chamber assemblies. Single-source vulnerability concentrates in isotope processing facilities. Distribution runs through port-zone irradiation hubs in Rotterdam, Mumbai, and Singapore where inspection and processing co-location reduces logistics friction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cobalt-60 supply constraints from reactor decommissioning schedules prop pricing power for electron beam operators with secured isotope alternatives.
For Market Incumbents: Anchor position through backward integration into accelerator component supply and captive cobalt-60 contracting with Russian reactor operators. Sterigenics-style logistics network control defends against STERIS-type electron beam specialists. Priority lever: India facility licensing acceleration to capture FSSAI approval pipeline. For New Entrants and Emerging Players: EU Green Deal chemical reduction targets in Europe open a window for X-ray technology deployment in organic dried herb processing. White-space targets: Vietnam shrimp export corridor and Brazil beef cold-chain gaps. Go-to-market angle: pharmaceutical sterilization provider pivot with underutilized cobalt-60 capacity. For Investors and Strategic Acquirers: Re-rating potential sits with medical-to-food crossover operators given EFSA harmonization tailwinds. Long-term viability frames around 5-10 year technology transition window. Acquisition target archetype: electron beam specialists with FDA-validated protein processing installations. Signal to watch: FSSAI licensing velocity as India demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Accelerator Capacity Expansion | Electron beam deployment in Germany and the US escapes cobalt-60 supply volatility entirely. |
| Long-term Tolling Agreements | Rotterdam and Mumbai spice traders lock dedicated capacity blocks, displacing spot procurement. |
| Regulatory Certification Investment | FDA validation under 21 CFR 179 commands premium positioning in US poultry processing. |
| Backward Integration into Isotope Supply | Cobalt-60 contract control with Canadian reactor operators secures gamma facility margins. |
| Geographic Licensing Acceleration | FSSAI commercial facility approvals in India open capacity gaps for equipment suppliers. |
Methodological Framework
Trade databases, reactor decommissioning schedules, and national regulatory filings formed the secondary backbone for this analysis. Primary interviews with irradiation facility operators, spice trading house procurement leads, and food safety regulatory affairs specialists combined with secondary validation. Bottom-up facility capacity modeling and top-down export volume analysis provided triangulation across data sources.
Historical trendline analysis of installed capacity and utilization rates informed projection mechanics across the modeling period. Segmentation dimensions included technology type (gamma, electron beam, X-ray), product category (meat, fruits, spices, grains), and end-user archetype (manufacturer, exporter, retailer). CAGRs derived from capacity expansion announcements and phytosanitary certification velocity. Industry-specific inputs: cobalt-60 supply contract durations and FSSAI licensing throughput rates.
The model assumes a particular technology adoption path; alternative pathways for X-ray maturation would alter the outlook. Forecasts reflect assumptions around EFSA regulatory harmonization timelines and CANDU reactor operational extensions. Specific risks that could revise projections: cobalt-60 supply disruption, electron beam capital cost inflation, and consumer acceptance friction from radura labeling mandates. A small set of named triggers—FSSAI licensing velocity, EU organic certification rule changes, and Japan-Australia phytosanitary reciprocity agreements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety and Standards
Blockchain Food Traceability Market
Food Safety and Standards
Testing, Inspection, and Certification Market
Food Safety and Standards
Automatic Distillation Analyzer Market
Food Safety and Standards
GMO Labeled Food Market
Food Safety and Standards
Food Certification Market
Food Safety and Standards
Natural Antimicrobials Market
Food Safety and Standards
Nutritional Labeling Market
Food Safety and Standards
Food and Beverage Industrial Disinfection and Cleaning Market
Food Safety and Standards
Quality Assurance and Quality Control Market
Food Safety and Standards
Bar Inspection System Market
Food Safety and Standards
Global Cold Chain Monitoring Market
Food Safety and Standards
Pathogen Reduction Systems Market
Food Safety and Standards
Precision Food Thermometers Market
Food Safety and Standards
Cold-Chain Friendly Post-Harvest Sanitizing Mist Market
Food Safety and Standards
Food Grade Biofilms Market
Food Safety and Standards
Food Safety Software Market