
 Pathogen Reduction Systems Market | 2026-2036
Pathogen Reduction Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Pathogen Reduction Systems Market Analytics
Direct procurement channels between pathogen reduction technology vendors and national blood services is reshaping how systems reach end users. Cerus Corporation dominates the INTERCEPT platform segment through specialized photochemical pathogen inactivation systems for platelets and plasma. Terumo BCT, Inc. leverages its integrated blood component automation portfolio to anchor positions in apheresis and processing workflows. Haemonetics Corporation competes through sustained manufacturing scale in plasma collection and hospital blood management solutions.
Pathogen reduction systems employ UV light, riboflavin-based photochemical agents, or solvent-detergent methods to inactivate viruses, bacteria, and parasites in blood products, typically achieving greater than four-log reduction in clinically relevant pathogens. These technologies primarily serve transfusion medicine by converting single-donor or pooled blood components into pathogen-reduced therapeutic products with extended shelf life and reduced transfusion-transmitted infection risk. UV treatment leads technology adoption in platelet and plasma applications due to established regulatory clearances and compatibility with existing blood bank infrastructure, while microbial filtration occupies growing positions in therapeutic protein manufacturing where prion and virus retention requirements intensify. Chemical treatment segments differentiate through riboflavin and amotosalen platforms that target nucleic acid inactivation without residual toxicity concerns, with margin pools concentrating in consumable reagent kits tied to processing volumes.
The FDA's Blood Products Advisory Committee and EMA's Committee for Medicinal Products for Human Use shape demand through divergent approval pathways for photochemical versus physical pathogen inactivation methods, with FDA 510(k) clearances enabling faster US commercialization of INTERCEPT-treated components. The EU Medical Device Regulation and ISO 13485 quality management standards enforce design control and post-market surveillance requirements that filter market access for emerging platform developers. Stakeholders must monitor how health technology assessment bodies in France, Germany, and England evaluate cost-effectiveness of universal versus targeted pathogen reduction implementation in national blood supplies.
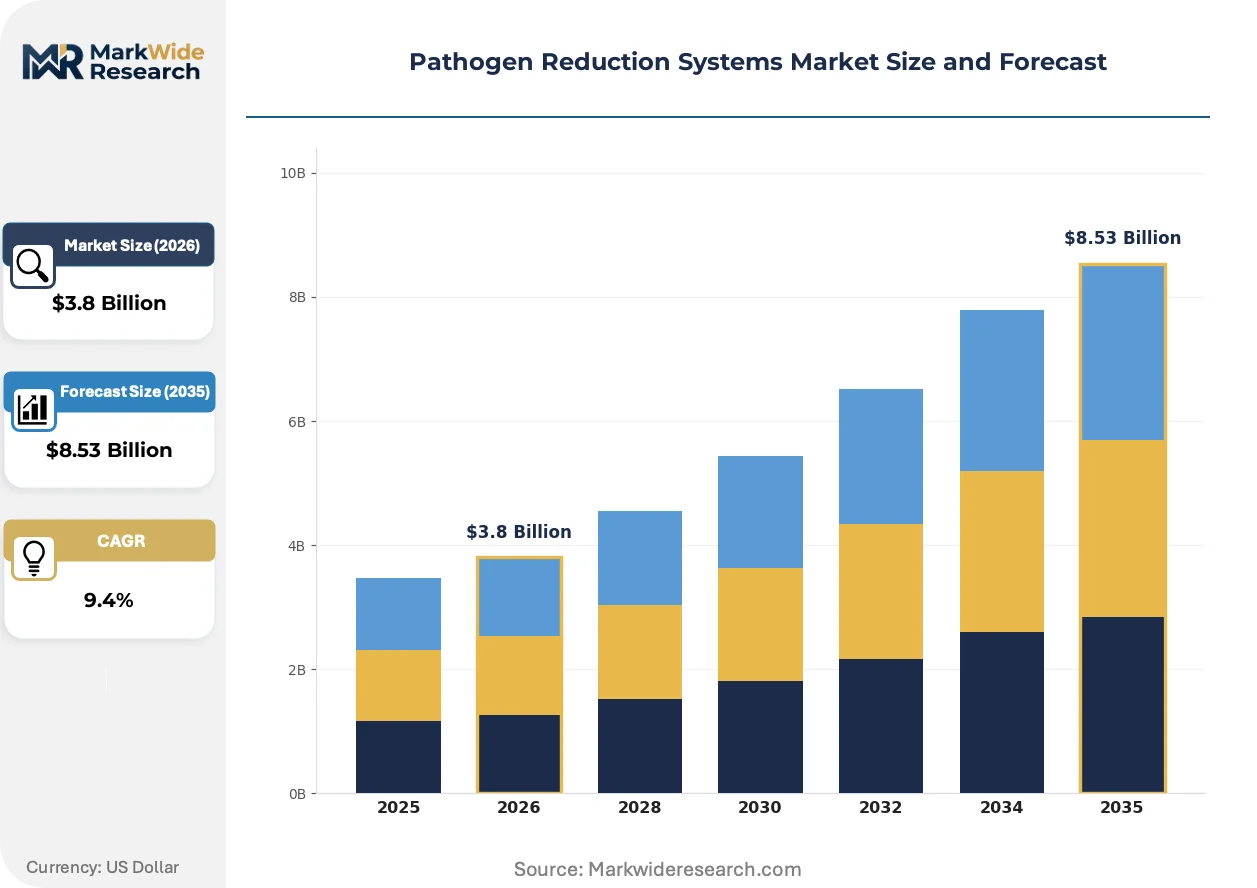
Market Dynamics
Photochemical pathogen inactivation systems are consolidating procurement relationships between national blood services and specialized technology vendors, compressing distribution layers and locking in multi-year consumable supply agreements that reshape competitive positioning across transfusion medicine.
Growth Catalysts
- EMA's Committee for Medicinal Products for Human Use:Accelerated assessment pathways for INTERCEPT-treated platelets in Germany and France are expanding reimbursement coverage for pathogen-reduced blood components.
- Apheresis collection workflows:Integration of inline pathogen reduction with automated blood component separation is reducing processing time and labor costs at high-volume plasma centers.
- Riboflavin photochemistry:Amotosalen-free nucleic acid inactivation is eliminating residual photosensitizer concerns and opening regulatory pathways in markets with stringent toxicity thresholds.
Market Restraints
- Consumable reagent concentration:Proprietary riboflavin and amotosalen kits tie processing economics to single-source chemical supply agreements with limited substitution options.
- UV lamp replacement cycles:Mercury-vapor lamp degradation and disposal regulations in the European Union impose recurring capital burdens on blood bank infrastructure.
- Solvent-detergent pooling minimums:Minimum batch size requirements for plasma protein fractionation restrict adoption at smaller regional blood centers with limited collection volumes.
Strategic Opportunities
- Red blood cell pathogen reduction:Riboflavin-based systems targeting erythrocyte inactivation represent unaddressed clinical need with substantial addressable volume beyond platelet and plasma applications.
- Direct-to-hospital procurement:Bypassing traditional blood bank intermediaries through centralized hospital network contracts is capturing margin previously allocated to distribution.
- India's CDSCO:Emerging regulatory harmonization with WHO prequalification standards is creating first-mover advantage for platforms achieving dual US-India market clearance.
Industry Challenges
- ISO 13485 design control documentation:Blood component device manufacturers face extended certification timelines for software-controlled photochemical dosing systems with integrated quality verification.
- Legacy LIS integration:Hospital information system interoperability with pathogen reduction device data logging requires customized middleware development and validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pathogen Reduction Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: UV Treatment, Chemical Treatment, Microbial Filtration, Heat Treatment Product Type: Systems, Devices, Solutions, Consumables Application: Food & Beverage, Pharmaceuticals, Water Treatment, Healthcare End User: Manufacturers, Hospitals, Research Institutions, Laboratories |
| Companies Covered | Terumo BCT, Inc., Cerus Corporation, Macopharma SA, Octapharma AG, AngioDynamics, Inc., Pathogen Reduction Solutions Ltd., Asahi Kasei Medical Co., Ltd., Grifols, S.A., Haemonetics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pathogen Reduction Systems Market Evolving Landscape
LED-based UV sources are displacing mercury-vapor lamp architectures across pathogen reduction platforms, triggering redesign cycles in device electronics and forcing recertification of established photochemical protocols.
Amotosalen nucleic acid cross-linking chemistry is rendering obsolete solvent-detergent methods for platelet pathogen inactivation, as blood centers in the United States accelerate INTERCEPT platform deployment under FDA 510(k) clearances. Hospital transfusion services are consolidating purchasing decisions at the health system level, compressing vendor negotiation cycles and favoring integrated platform providers over standalone device manufacturers.
The EU Medical Device Regulation's post-market surveillance requirements are mandating real-world performance data collection for CE-marked pathogen reduction systems, compelling manufacturers to fund extended clinical follow-up studies in German and French blood services. Device makers are responding by embedding automated data transmission modules that stream processing parameters directly to notified body registries.
Consolidated procurement by multi-hospital networks is displacing decentralized blood bank purchasing decisions, with group purchasing organizations in the United States capturing volume commitments across three-to-five-year contract horizons. This concentration is most visible in integrated delivery networks spanning Texas and California, where standardized pathogen reduction protocols are becoming a network-level quality metric.
Pathogen Reduction Systems Market Segmentation
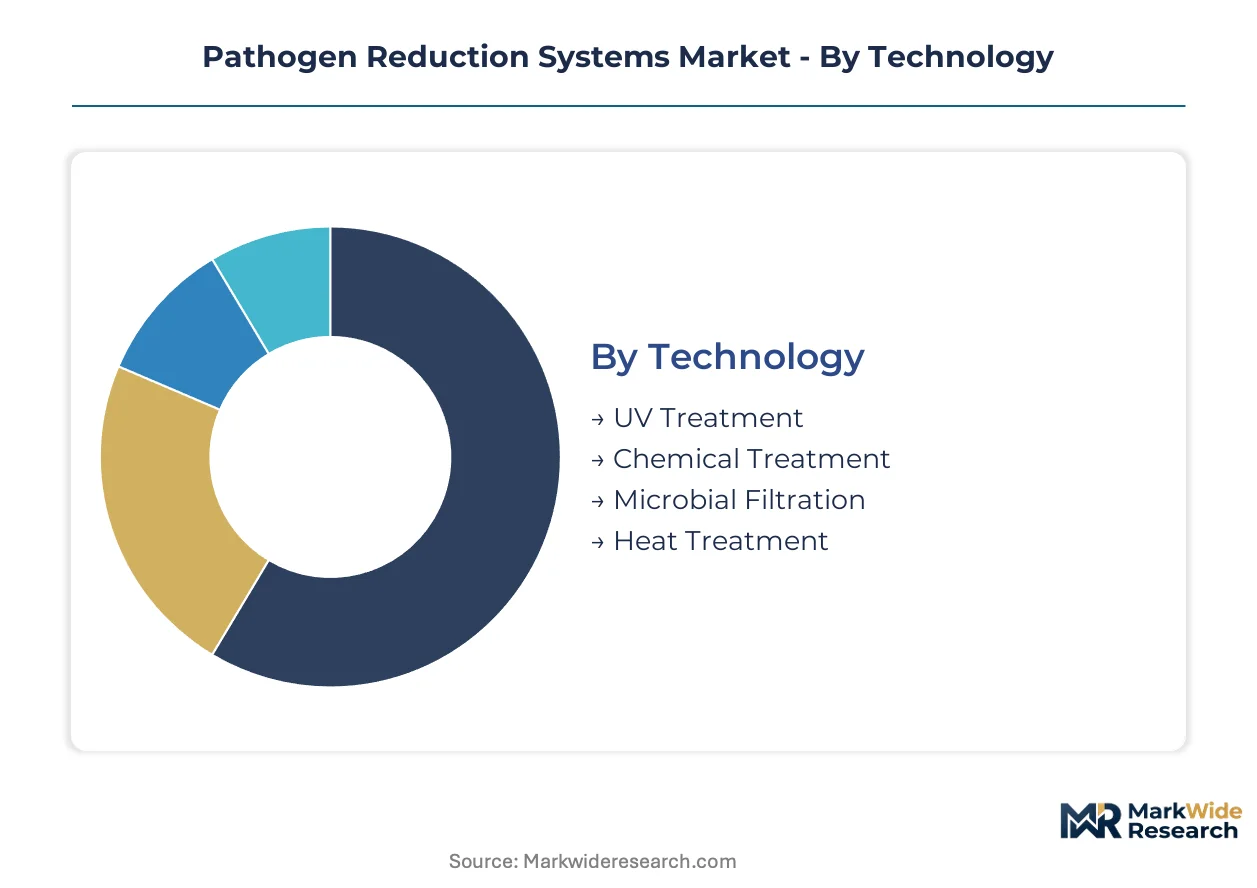
Technology-platform selection in pathogen reduction determines capital intensity, consumable economics, and regulatory pathway complexity. Each segment exhibits distinct procurement patterns tied to end-use sterilization requirements and compliance frameworks.
Technology:
UV photochemistry spans low-pressure mercury and emerging LED architectures for nucleic acid disruption without thermal degradation.
- UV Treatment:Mercury-vapor and solid-state LED sources deliver 254-280nm wavelengths for nucleic acid cross-linking in platelet and plasma processing. German and French blood services prioritize UV platforms under EMA accelerated assessment pathways for INTERCEPT-treated components.
- Chemical Treatment:Riboflavin and amotosalen photosensitizers enable pathogen inactivation through reactive oxygen species generation. United States hospital networks favor amotosalen-free riboflavin protocols to eliminate residual toxicity concerns in pediatric and immunocompromised patient populations.
- Microbial Filtration:Nanopore membranes retain prions, viruses, and bacteria through size exclusion and adsorption mechanisms.
- Heat Treatment:Pasteurization and dry-heat protocols inactivate enveloped viruses in plasma protein fractionation with established solvent-detergent pooling infrastructure.
Established volume favors UV Treatment; emerging adoption favors Chemical Treatment.
Product Type:
Hardware-software integration intensity separates capital equipment from recurring revenue streams.
- Systems:Integrated photochemical processing platforms combine UV illumination chambers, reagent dosing modules, and automated quality verification. United States blood centers demand 510(k)-cleared systems with embedded data logging for FDA compliance documentation.
- Consumables:Proprietary riboflavin and amotosalen reagent kits tie processing economics to single-source supply agreements. German hospital procurement offices negotiate multi-year consumable contracts with volume-tiered pricing structures.
- Devices:Standalone illumination units and filtration cartridges for retrofit installation in existing blood bank workflows.
- Solutions:Turnkey service packages encompassing equipment validation, staff training, and regulatory submission support.
Revenue concentration tilts toward Consumables; margin expansion concentrates in Systems.
Application:
Sterilization stringency varies from log-reduction targets to absolute bioburden elimination.
- Healthcare:Blood component processing for transfusion medicine demands four-log pathogen reduction with extended shelf-life preservation. United States transfusion services prioritize platelet and plasma pathogen reduction under AABB quality standards.
- Pharmaceuticals:Biologic drug manufacturing requires viral clearance validation under ICH Q5A guidelines for recombinant protein and monoclonal antibody production.
- Water Treatment:UV disinfection for municipal and industrial water systems targets Cryptosporidium and Giardia inactivation.
- Food & Beverage:Non-thermal pasteurization for juices and dairy products preserves sensory attributes while achieving microbial safety thresholds.
Regulatory complexity peaks in Healthcare; standardization advances fastest in Water Treatment.
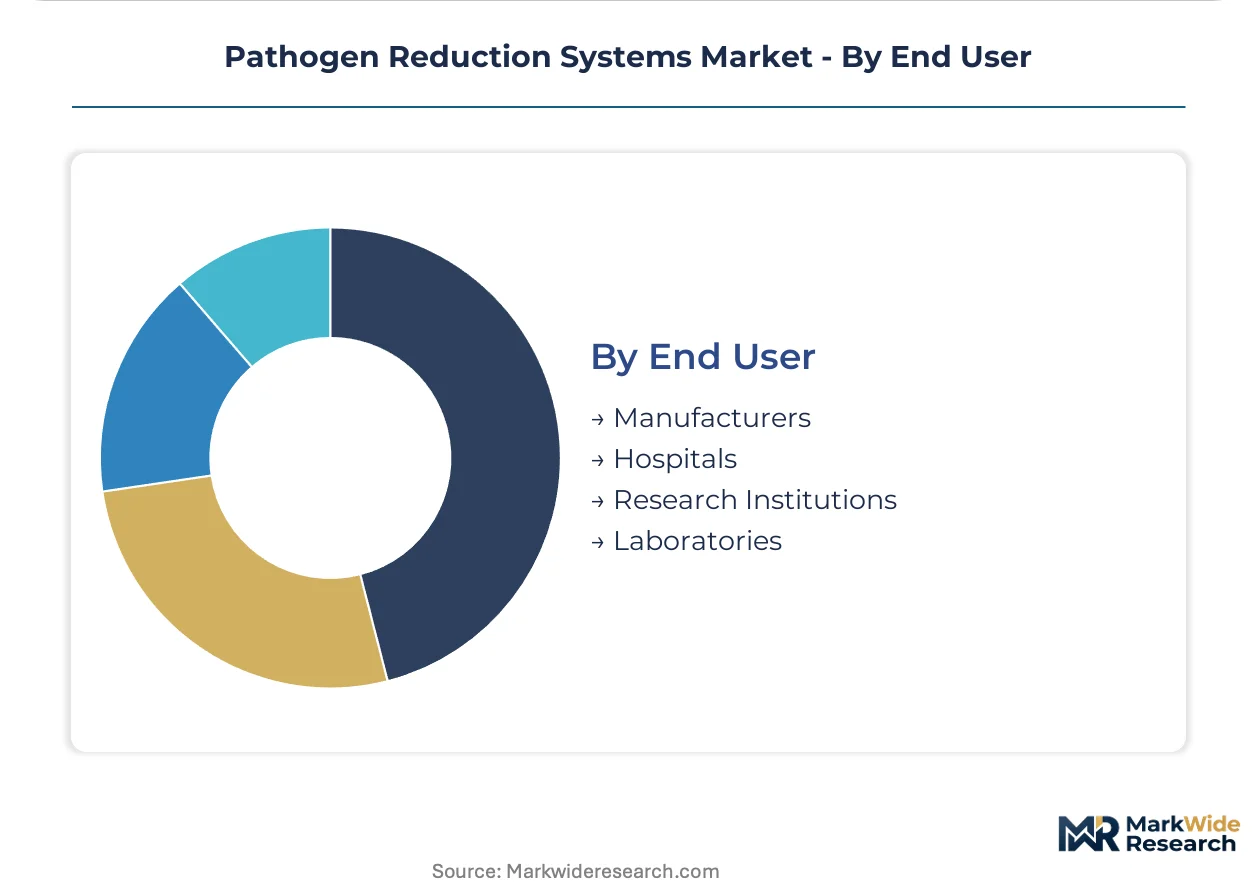
End User:
Procurement authority concentration shapes vendor relationship structures and contract duration.
- Hospitals:Integrated delivery networks in Texas and California consolidate pathogen reduction purchasing at the health system level. Group purchasing organizations capture three-to-five-year volume commitments with standardized quality metrics.
- Manufacturers:Plasma protein fractionators and biologic drug producers require validated viral clearance platforms with batch release documentation.
- Laboratories:Reference laboratories and contract research organizations employ pathogen reduction for cell therapy and tissue engineering applications.
- Research Institutions:Academic medical centers evaluate emerging LED-UV and riboflavin platforms for red blood cell pathogen reduction protocols.
Contract scale favors Manufacturers; decision velocity favors Hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in pathogen reduction systems tilts toward German procurement offices negotiating multi-year consumable contracts, while blood centers in India face cost premiums on imported photochemical reagent kits. This asymmetry reflects divergent regulatory maturities and domestic manufacturing capabilities across transfusion medicine markets.
United States
FDA 510(k) clearances for INTERCEPT-treated platelets accelerate hospital network adoption in Texas and California integrated delivery systems. The Blood Products Advisory Committee shapes reimbursement pathways through accelerated assessment frameworks. Greater Boston's academic medical centers pilot LED-UV architectures for red blood cell pathogen reduction protocols.
Germany
EMA accelerated assessment pathways expand national health insurance coverage for pathogen-reduced blood components in Bavaria and North Rhine-Westphalia. The EU Medical Device Regulation enforces post-market surveillance through real-world performance data collection. Frankfurt's blood services consolidate procurement through centralized hospital network contracts capturing three-to-five-year volume commitments.
France
ANSM evaluates cost-effectiveness of universal versus targeted pathogen reduction implementation in national blood supplies. The Haute Autorité de Santé issues health technology assessment guidance favoring riboflavin-based photochemistry for pediatric populations. Paris-region transfusion centers deploy inline pathogen reduction with automated apheresis collection workflows.
India
CDSCO regulatory harmonization with WHO prequalification standards creates first-mover advantage for dual US-India market clearance holders. Maharashtra's hospital networks prioritize pathogen inactivation protocols for platelet supplies in Mumbai and Pune metropolitan clusters. Domestic manufacturing constraints force reliance on imported consumable reagent kits at 15-20% cost premiums.
Japan
PMDA marketing authorization pathways for photochemical pathogen inactivation systems align with ICH Q5A viral clearance validation standards. METI funding supports LED-UV platform development for blood component processing. Osaka-Kobe industrial corridor hosts plasma protein fractionators requiring validated pathogen reduction with batch release documentation.
Pathogen Reduction Systems Market Competitive Landscape
Photochemistry specialists and blood processing automation incumbents split the market through divergent capital intensity models. The vendor base concentrates around three strategic archetypes: integrated platform providers bundling hardware with proprietary consumables, standalone device manufacturers retrofitting existing blood bank infrastructure, and plasma fractionation specialists with captive pathogen reduction requirements. Dominant competitive moves include multi-year consumable supply agreements locking in national blood services and LED-UV technology licensing to displace mercury-vapor lamp architectures.
Among integrated platform providers, Cerus Corporation and Terumo BCT, Inc. exemplify the photochemistry-automation convergence. Haemonetics Corporation occupies a position within the scale-driven manufacturing tier. These three companies anchor the competitive structure through divergent approaches to regulatory pathway complexity and hospital network procurement consolidation.
| Leading Market Players |
|---|
| Terumo BCT, Inc. |
| Cerus Corporation |
| Macopharma SA |
| Octapharma AG |
| AngioDynamics, Inc. |
| Pathogen Reduction Solutions Ltd. |
| Asahi Kasei Medical Co., Ltd. |
| Grifols, S.A. |
| Haemonetics Corporation |
| Others |
Value Network & Pricing Analysis
Single-source dependency on proprietary riboflavin and amotosalen reagent kits determines both the three-tier pricing spread across consumable contracts and the elongated supply chain structure anchored in specialized chemical manufacturing. Blood centers face locked-in procurement economics where multi-year supply agreements with photochemistry specialists compress margin flexibility and reshape inventory risk allocation.
Pricing Analysis
Configured-to-order pricing for integrated pathogen reduction systems commands substantial premiums over standard illumination units, with customization premiums reflecting embedded data logging modules and FDA 510(k) compliance documentation. Price differentiation hinges on certification tier—CE-marked devices under EU Medical Device Regulation versus FDA-cleared systems—and volume scale commitments negotiated through group purchasing organizations. Pricing pressure stems from consolidated hospital network procurement in Texas and California, where three-to-five-year volume contracts compress vendor margins. Regional blood centers exhibit highest price sensitivity due to constrained capital budgets, while national blood services leverage scale for tiered consumable pricing.
Supply Chain Analysis
Contract manufacturing concentration for UV illumination chambers rests with specialized medical device electronics producers in Germany, Japan, and the United States. Raw material dependencies include mercury-vapor and solid-state LED sources, quartz glass for UV transmission, and pharmaceutical-grade riboflavin synthesized through controlled fermentation processes. Single-source vulnerability pervades proprietary reagent kit supply, where photochemistry specialists maintain exclusive manufacturing relationships. Distribution runs through direct vendor-to-blood-service channels for consumables, supplemented by regional medical device distributors for capital equipment installation and service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where consumable-anchored revenue models and LED-UV technology transitions are reshaping competitive boundaries through interoperability demands and ecosystem lock-in effects.
For Market Incumbents: Insulate installed base positions by deepening captive supply relationships for riboflavin reagent manufacturing and accelerating LED-UV platform recertification ahead of mercury-vapor lamp phase-outs. Vertical integration into solid-state illumination component sourcing mitigates supply disruption risk from Asian electronics foundries. Prioritize software module development for automated data transmission to EU notified body registries under post-market surveillance mandates.
For New Entrants and Emerging Players: Pursue regulatory pathway arbitrage by securing dual FDA-CDSCO clearance for India's emerging hospital network procurement, where WHO prequalification alignment creates first-mover structural advantage. Red blood cell pathogen reduction represents the most penetrable white-space segment, with academic medical centers in Greater Boston and Frankfurt piloting riboflavin-based erythrocyte protocols. Lead with turnkey validation service packages that compress hospital staff training timelines and accelerate clinical adoption.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated platform providers with consumable recurring revenue over standalone device manufacturers with transactional hardware models. Acquisition target archetypes include LED-UV technology specialists with pending photochemical protocol recertification and regional service organizations with established blood center relationships. The signal to watch is EMA accelerated assessment pathway expansion for riboflavin-based systems, which would validate platform economics scalability beyond amotosalen-dependent incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| LED-UV Platform Recertification | Displaces mercury-vapor architectures ahead of EU disposal regulations, locking in next-generation market positions. |
| Consumable Supply Agreement Extension | Captures multi-year riboflavin kit commitments from German and French national blood services under volume-tiered structures. |
| Red Blood Cell Protocol Development | Addresses unmet clinical need with substantial addressable volume beyond established platelet and plasma applications. |
| Direct Hospital Network Contracting | Bypasses blood bank intermediaries in Texas and California integrated delivery systems, capturing distribution margin. |
| Dual FDA-CDSCO Regulatory Filing | Secures first-mover advantage in India's Maharashtra hospital networks through harmonized WHO prequalification pathways. |
Research Methodology
The analysis maps photochemical pathogen inactivation, UV treatment, microbial filtration, and heat treatment segments, each validated through blood bank operations directors, hospital transfusion service chiefs, biomedical engineers, and GPO contracts managers. Primary interviews with procurement officers at national blood services in Germany, France, and the United States combined with secondary validation from FDA 510(k) filings, EMA accelerated assessment pathway documentation, hospital procurement databases, and ISO 13485 certification records. Bottom-up unit economics for consumable reagent kits triangulated against top-down national blood component processing volumes.
Assumptions held fixed include regulatory pathway timelines for photochemical protocol clearances and LED-UV device recertification schedules, while variables included hospital network procurement consolidation velocity and CDSCO-WHO harmonization progress. Segmentation dimensions modeled span technology platform, product type, application, and end-user procurement authority concentration. CAGRs derived from installed base growth for pathogen reduction systems coupled with consumable processing volume projections. Industry-specific inputs encompass blood collection center automation adoption rates and health technology assessment body evaluations in France, Germany, and England.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles, blood component demand volatility, or regulatory harmonization timelines would shift the trajectory. Forecasts reflect assumptions regarding EMA accelerated assessment pathway expansion and FDA guidance alignment on photochemical methods. Cross-checking against hospital procurement database trends and national blood service annual reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety and Standards
Testing, Inspection, and Certification Market
Food Safety and Standards
Nutritional Labeling Market
Food Safety and Standards
Natural Antimicrobials Market
Food Safety and Standards
Automatic Distillation Analyzer Market
Food Safety and Standards
Bakery Cleaning and Disinfection Products Market
Food Safety and Standards
Food and Beverage Industrial Disinfection and Cleaning Market
Food Safety and Standards
Food Grade Biofilms Market
Food Safety and Standards
Food Certification Market
Food Safety and Standards
Global Cold Chain Monitoring Market
Food Safety and Standards
Food Authenticity Market
Food Safety and Standards
Food Safety Software Market
Food Safety and Standards
Blockchain Food Traceability Market
Food Safety and Standards
Cold-Chain Friendly Post-Harvest Sanitizing Mist Market
Food Safety and Standards
Bar Inspection System Market
Food Safety and Standards
Food Irradiation Market
Food Safety and Standards
Precision Food Thermometers Market