

Blockchain Food Traceability Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain Food Traceability Market Insights
Large retail chains is collapsing the distance between farm-origin verification and checkout-line transparency. Walmart anchors North American deployment with supplier mandates that require blockchain-logged harvest data. Provenance specializes in ethical sourcing narratives that differentiate European seafood and coffee brands. JD.com dominates Chinese fresh-food e-commerce by integrating ledger-based cold-chain monitoring into its fulfillment network.
Blockchain food traceability systems use distributed ledger architectures to cryptographically link batch identifiers, timestamps, and custody transfers across multi-party supply chains. Smart Contracts automate compliance checks when sensor data breaches temperature thresholds or origin documentation fails validation. Supply Chain Transparency solutions currently occupy the largest application share as retailers face liability exposure from undetected contamination events. Cloud-Based Platforms represent the fastest-expanding solution category because processors prefer subscription models over capital-intensive on-premises infrastructure. Edge Computing deployments are gaining traction among logistics providers tracking perishables across remote cold-storage corridors.
The FDA's Food Safety Modernization Act traceability rules and the EU's General Food Law impose record-keeping densities that paper systems cannot satisfy, directly accelerating ledger adoption among importers. China's SAMR enforces national food origin standards that MIIT-aligned blockchain platforms help exporters demonstrate. Stakeholders must weigh interoperability protocols against proprietary network effects when selecting consortium partners for multi-tier agricultural tracking.
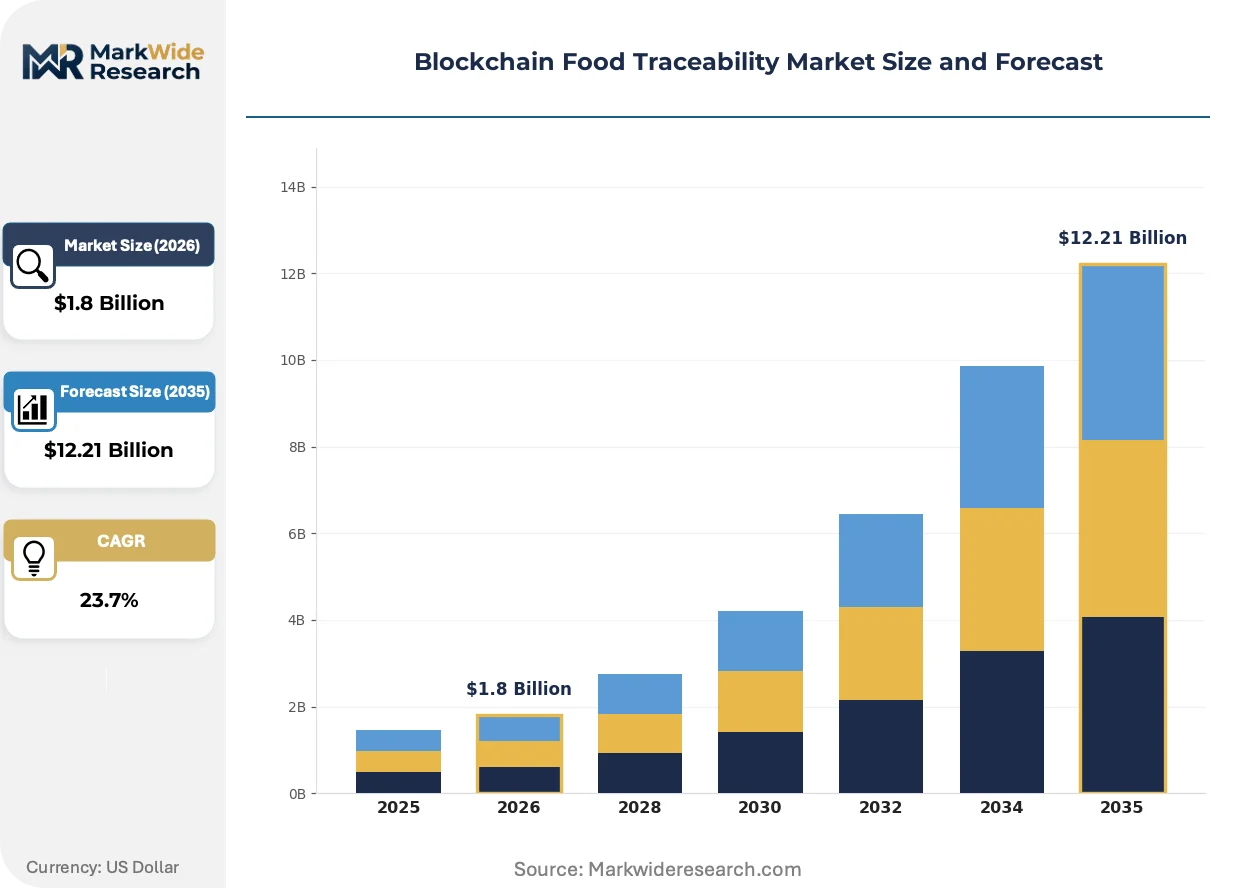
Market Dynamics
Retail grocery chains are collapsing the distance between farm-origin verification and checkout-line transparency, forcing processors to adopt immutable ledger systems or lose shelf access.
Growth Catalysts
- EU General Food Law:Digital traceability mandates compel processors to replace paper documentation with cryptographically linked batch records.
- Cloud migration:Subscription-based platforms eliminate capital-intensive infrastructure barriers for mid-tier agricultural cooperatives.
- Germany's import enforcement:The Federal Office for Food and Agriculture demands strict origin documentation for commodity imports, accelerating ledger deployment.
Market Restraints
- Interoperability friction:Proprietary network effects among competing consortium platforms fragment data exchange standards.
- Sensor hardware costs:Cold-chain IoT devices for perishable tracking require upfront capital that smaller logistics providers cannot absorb.
- Legacy system integration:ERP silos in established food conglomerates resist API connectivity with distributed ledger architectures.
Strategic Opportunities
- Protein and dairy expansion:Retail pilots are migrating from premium produce into animal protein categories with complex custody chains.
- Edge computing corridors:Remote cold-storage facilities in rural logistics networks lack real-time monitoring coverage.
- Smart contract automation:Temperature threshold breaches trigger automatic compliance alerts without manual intervention.
Industry Challenges
- Cryptographic talent scarcity:Supply chain engineers with distributed ledger expertise command premium compensation that processors struggle to match.
- Multi-party data governance:Competing suppliers resist sharing sensitive harvest data on shared consortium platforms.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain Food Traceability Market Trends and Innovations
Blockchain food traceability is decomposing traditional audit relationships into automated verification protocols, compressing the time between contamination detection and consumer notification.
Edge computing nodes paired with distributed ledgers are decomposing centralized cloud dependencies for cold-chain monitoring. Logistics providers operating remote storage corridors deploy localized processing units that timestamp custody transfers without continuous connectivity. This architecture is decomposing the latency gap between sensor breach and stakeholder alert, enabling perishable recovery rather than total loss.
The FDA's Food Safety Modernization Act traceability rules impose record-keeping densities that paper systems cannot satisfy. Importers face liability exposure from undetected contamination events that immutable ledgers can prevent. North American seafood and produce distributors are responding by mandating supplier participation in blockchain-logged harvest data programs.
Retail procurement departments now require ethical sourcing narratives as standard contract terms. European seafood and coffee brands differentiate through provenance storytelling that ledger verification enables. German supermarket chains lead this shift, using origin documentation as a competitive weapon against discount competitors.
Blockchain Food Traceability Market Segmentation
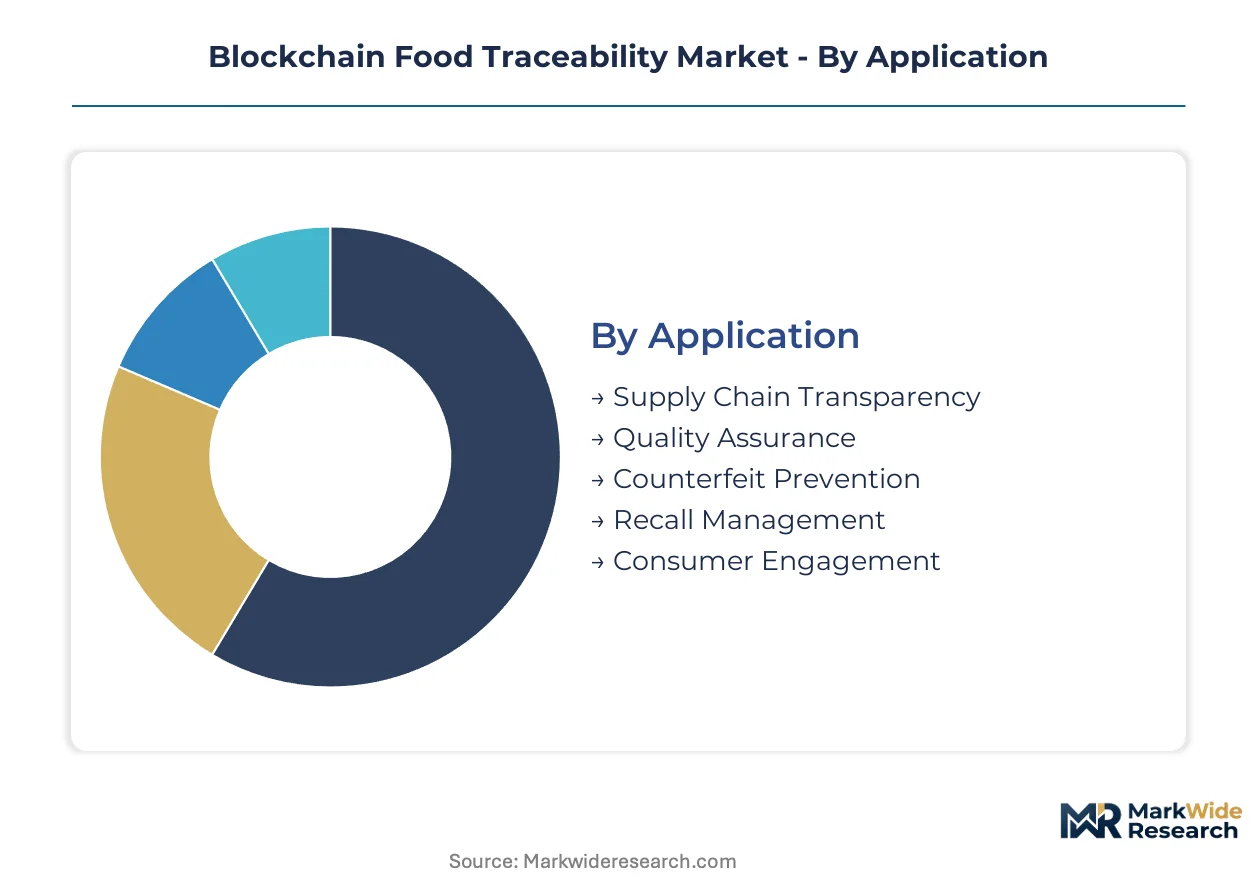
Segmentation in blockchain food traceability reveals how regulatory pressure, infrastructure maturity, and custody-chain complexity concentrate investment across distinct solution architectures. Each category maps to specific compliance burdens and operational constraints that processors must navigate.
Application:
EU General Food Law and FDA Food Safety Modernization Act traceability rules create divergent compliance densities across use cases, with liability exposure driving prioritization.
- Supply Chain Transparency:Distributed ledger architectures cryptographically link batch identifiers, timestamps, and custody transfers across multi-party agricultural networks. German retailers under Federal Office for Food and Agriculture mandates deploy these systems for imported commodity verification, with cloud-based platforms eliminating capital barriers for mid-tier cooperatives.
- Quality Assurance:Sensor-integrated ledgers automate compliance checks when temperature thresholds breach or origin documentation fails validation. Demand concentrates among North American seafood distributors facing FDA liability exposure, with smart contracts compressing detection-to-notification timelines.
- Counterfeit Prevention:Immutable provenance records protect premium European coffee and seafood brands from substitution fraud.
- Recall Management:Cryptographic batch tracking enables precision withdrawals without full product-line destruction.
- Consumer Engagement:QR-linked harvest narratives differentiate retail offerings in German supermarket chains.
Established volume favors Supply Chain Transparency; emerging adoption favors Quality Assurance.
Solution:
Cost tier differentiation separates capital-intensive infrastructure from subscription models preferred by agricultural cooperatives with constrained IT budgets.
- Cloud-Based Platforms:Subscription architectures eliminate on-premises hardware investments, accelerating deployment among mid-tier processors. Germany's strict origin documentation requirements for commodity imports drive fastest expansion here, with processors preferring operational expenditure models over capital-intensive alternatives.
- Smart Contracts:Self-executing compliance protocols trigger automatic alerts when sensor data breaches thresholds, eliminating manual intervention latency. Demand concentrates in cold-chain logistics where perishable recovery depends on instantaneous stakeholder notification.
- Distributed Ledger:Core cryptographic infrastructure anchors consortium networks across competing supplier platforms.
- Data Analytics:Pattern recognition tools identify contamination vectors from immutable transaction histories.
- Cryptocurrency Integration:Tokenized incentive structures reward supplier data sharing on shared platforms.
Cloud migration is climbing the fastest; distributed ledger foundations remain the largest installed base.
Deployment:
Geography and connectivity infrastructure determine architecture selection, with remote corridors forcing localized processing solutions.
- Edge Computing:Localized processing units timestamp custody transfers without continuous connectivity, enabling perishable tracking across rural cold-storage corridors. Logistics providers in remote logistics networks deploy these nodes to decompose latency gaps between sensor breach and stakeholder alert.
- Cloud:Centralized infrastructure dominates urban-proximate processing facilities with reliable bandwidth.
- Hybrid:Mixed architectures balance sensitive data on-premises with shared ledger synchronization.
- On-Premises:Capital-intensive deployments persist among established conglomerates with legacy ERP silos.
- Hosted Services:Managed infrastructure reduces cryptographic talent requirements for smaller processors.
Cloud deployments hold current volume leadership; edge computing is gaining share fastest in remote corridor applications.
End User:
Customer type segmentation reflects custody-chain position and corresponding data governance authority.
- Retailers:Walmart-style supplier mandates force upstream blockchain adoption by conditioning shelf access on harvest data logging. German supermarket chains leverage origin documentation as competitive differentiation against discount competitors, with procurement departments requiring ethical sourcing narratives as standard contract terms.
- Food Processors:Mid-tier agricultural cooperatives face EU digital traceability mandates that paper systems cannot satisfy, driving cloud platform subscription demand.
- Producers:Farm-origin data creation points resist sharing sensitive harvest information on shared consortium platforms.
- Logistics Providers:Cold-chain operators absorb sensor hardware costs for perishable custody verification.
- Certification Bodies:Audit relationships transform into automated verification protocol administration.
Retail procurement power favors Retailers; regulatory compliance burden favors Food Processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Europe's blockchain food traceability infrastructure, connecting German retail mandates with Mediterranean produce origins. Cold-chain corridors from this hub distribute ledger-verified commodities across the continent's processing networks.
United States
Walmart's supplier mandates drive blockchain adoption across domestic produce and protein supply chains. The FDA's Food Safety Modernization Act traceability rules impose record-keeping densities that paper systems cannot satisfy. Cold-chain logistics clusters in California's Central Valley deploy sensor-integrated ledgers for perishable custody verification.
Germany
The Federal Office for Food and Agriculture enforces strict origin documentation for imported commodities, accelerating ledger deployment among processors. EU General Food Law digital traceability mandates compel replacement of paper documentation with cryptographically linked batch records. Retail concentration in the Rhine-Ruhr metropolitan region leverages origin documentation as competitive differentiation against discount competitors.
China
JD.com's fresh-food e-commerce dominance integrates ledger-based cold-chain monitoring into fulfillment networks. SAMR enforces national food origin standards that MIIT-aligned blockchain platforms help exporters demonstrate. Yangtze River Delta logistics corridors deploy edge computing nodes for remote cold-storage timestamping without continuous connectivity.
United Kingdom
Provenance specializes in ethical sourcing narratives that differentiate domestic seafood and coffee brands. Post-Brexit import documentation requirements increase compliance burdens that distributed ledgers can streamline. London-based fintech clusters develop cryptocurrency incentive structures for supplier data sharing on shared platforms.
Australia
Remote cold-storage facilities across the continent's interior lack real-time monitoring coverage, creating edge computing deployment opportunities. The country's national food regulator imposes traceability standards that favor immutable ledger systems for export verification. Queensland's beef processing corridors pilot blockchain-logged harvest data for Asian market access.
Blockchain Food Traceability Market Competitive Landscape
Listed leaders compete with private specialists across technology platform and retail deployment dimensions, creating a tiered competitive structure. Cloud infrastructure providers anchor the enterprise solution tier, while retail conglomerates drive downstream adoption through supplier mandate programs. Strategic archetypes include enterprise software vendors, retail ecosystem orchestrators, and specialized provenance platform developers. Dominant competitive moves encompass strategic partnerships between technology providers and retail chains, plus portfolio diversification into adjacent cold-chain monitoring capabilities.
Among technology platform providers, IBM and Microsoft occupy positions as enterprise infrastructure anchors, while Provenance exemplifies the specialized provenance narrative tier. Walmart represents retail ecosystem orchestration, leveraging procurement power to force upstream blockchain adoption across its supplier base. These three archetypes illustrate the market's segmentation between horizontal technology platforms, vertical retail integration, and niche ethical sourcing differentiation.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Walmart |
| Carrefour |
| JD.com |
| Albertsons Companies |
| Provenance |
| FoodLogiQ |
| TraceX Technologies |
| Others |
Pricing and Supply Chain Analysis
Take-or-pay subscription contracts lock mid-tier processors into multi-year cloud platform commitments that guarantee supply access while flattening price volatility across the forecast window. German importers under Federal Office for Food and Agriculture mandates favor these arrangements to secure immutable ledger capacity ahead of compliance deadlines.
Pricing Analysis
Volume-discount tiering separates enterprise deployments from cooperative-scale subscriptions, with per-node pricing collapsing at thresholds above 500 connected suppliers. Cloud-based platforms anchor the mid-market with SaaS-tiered models, while on-premises installations command premiums for data sovereignty. Certification-grade differentiation separates FDA-compliant systems from baseline traceability offerings. Pricing pressure stems from sensor hardware commoditization in cold-chain monitoring. Agricultural cooperatives exhibit highest price sensitivity; retail conglomerates with procurement mandates show lowest.
Supply Chain Analysis
Rotterdam port throughput underwrites European ledger infrastructure, channeling Mediterranean produce origins into German processing networks. Component supply draws from Taiwan for edge-computing chipsets, China for IoT sensor assemblies, and Ireland for cloud data center capacity. Single-source vulnerability concentrates in consortium software providers with proprietary protocol lock-in. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidating retail procurement power is shifting leverage toward buyers, with Walmart-style supplier mandates forcing upstream technology adoption across fragmented processor bases.
For Market Incumbents: Fortify consortium network effects by deepening API interoperability with ERP systems that resist ledger integration. Invest in cryptographic talent retention as supply chain engineers command premium compensation. Defend against emerging cloud-native challengers by embedding smart contract automation deeper into cold-chain workflows. For New Entrants and Emerging Players: Anchor in edge computing deployments across Australia's remote beef processing corridors, where connectivity gaps exclude centralized cloud competitors. Target mid-tier dairy cooperatives in Germany facing EU General Food Law deadlines with hosted-service offerings that eliminate capital barriers. Lead with temperature-threshold automation as the entry wedge. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated cold-chain monitoring specialists with captive sensor hardware and ledger software stacks. Long-term viability hinges on consolidation of fragmented logistics provider networks into unified data governance platforms. Watch for FDA enforcement acceleration on traceability rule compliance as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Consortium Platform Interoperability | IBM and Microsoft anchor enterprise infrastructure by bridging proprietary network protocols. |
| Edge Computing Node Deployment | JD.com integrates localized processing into Yangtze River Delta fulfillment corridors. |
| Smart Contract Automation | Temperature threshold breaches trigger instantaneous compliance alerts without manual intervention. |
| Sensor Hardware Backward Integration | Logistics providers absorb IoT device costs to secure perishable custody verification. |
| Retail Supplier Mandate Programs | Walmart conditions shelf access on blockchain-logged harvest data submission. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA enforcement disclosures, EU regulatory filings, cloud provider capex reports, and customs trade data. Supply chain directors at retail conglomerates, compliance officers at agricultural cooperatives, platform engineers at logistics technology providers, and procurement leads at food processors provided structured input. Bottom-up deployment estimates triangulate against top-down market sizing from cloud infrastructure spend allocation.
Segmentation dimensions modeled encompass application type, solution architecture, deployment topology, and end-user category across the projection horizon. CAGRs derive from fitted growth curves against historical cloud platform subscription trajectories and regulatory compliance deadline clustering. Forecast inputs incorporate sensor hardware cost decline rates and cold-chain logistics expansion patterns.
Decision-makers should treat outputs as directional under stable regulatory enforcement assumptions; material deviation in FDA or EU mandate timing would warrant model refresh. Practitioners should keep alternative scenarios live as interoperability protocol standardization and cryptographic talent availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.