
 Quality Assurance and Quality Control Market | 2026-2036
Quality Assurance and Quality Control Market Size, Share, and Industry Trends Forecast 2026-2036
Quality Assurance and Quality Control Market Outlook
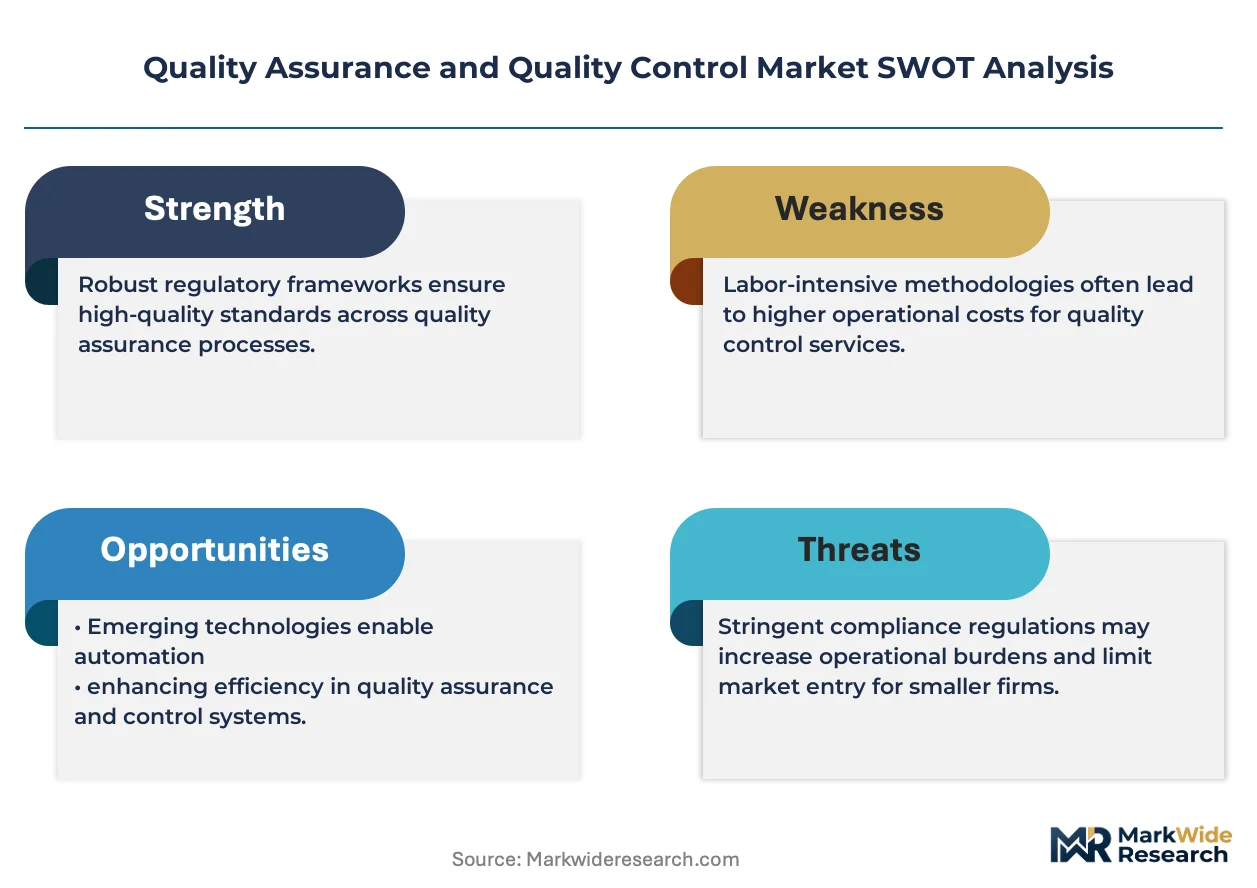
ISO 9001:2015 certification is redrawing competitive boundaries by filtering out under-resourced entrants. SGS leverages its global laboratory footprint to dominate physical testing workflows. Bureau Veritas anchors its position through maritime and industrial inspection depth. Eurofins Scientific differentiates via bioanalytical specialization in pharmaceutical quality verification.
Quality assurance and quality control encompass systematic activities that verify products, services, and processes against predefined specifications through statistical sampling, automated inspection protocols, and documented corrective action loops. These disciplines ensure conformance to customer requirements, regulatory standards, and operational consistency across production cycles. Software solutions command the largest revenue pool among product types, while testing services generate the highest margins within service categories due to specialized equipment and certified personnel requirements. Manufacturing applications absorb the greatest QA/QC spend, though pharmaceutical applications exhibit the fastest adoption velocity as batch-release complexity intensifies.
FDA cGMP enforcement, EMA GMP inspections, and ISO 17025 laboratory accreditation collectively shape compliance expenditure thresholds and vendor qualification criteria. The EU AI Act introduces emerging algorithmic audit requirements that will extend quality frameworks into automated decision systems. Stakeholders must calibrate investment between legacy compliance infrastructure and predictive quality analytics capabilities.
Market Dynamics
Pharmaceutical serialization mandates from FDA and EMA are compressing batch-release timelines, forcing manufacturers to restructure quality infrastructure around real-time data verification rather than post-hoc sampling.
Growth Catalysts
- EMA serialization deadlines:European drug manufacturers must upgrade track-and-trace systems by enforcement dates, triggering capital deployment into integrated QA/QC platforms.
- Biologics manufacturing expansion:Cell and gene therapy production requires contamination control protocols that exceed small-molecule standards, elevating specialized testing demand.
- Cloud-based quality management:Distributed manufacturing sites in Germany and the United States adopt centralized document control to harmonize multi-facility compliance.
Market Restraints
- Certified personnel scarcity:ISO 17025-accredited analytical chemists command wage premiums that inflate laboratory operating costs by double-digit percentages.
- Equipment import dependencies:High-precision chromatography and mass spectrometry systems concentrate production in Germany, Japan, and the United States, exposing buyers to currency and logistics volatility.
- Validation timeline compression:FDA cGMP computer system validation requirements extend software deployment cycles, delaying ROI realization for quality platform investments.
Strategic Opportunities
- EU AI Act algorithmic auditing:Automated manufacturing decision systems will require quality frameworks that extend beyond traditional equipment qualification, opening new service categories for verification providers.
- Indian pharmaceutical export compliance:CDSCO-aligned manufacturers serving regulated markets need ISO 17025 laboratory partnerships to satisfy FDA and EMA import requirements.
- Digital twin integration:Convergence of process analytical technology with predictive modeling enables real-time release testing, reducing quarantine inventory carrying costs.
Industry Challenges
- Multi-standard harmonization:Quality teams must reconcile FDA cGMP, EMA GMP Annex 11, and ISO 13485 requirements for combination products, multiplying documentation burden.
- Legacy system interoperability:Paper-based batch records and isolated manufacturing execution systems resist integration with cloud quality platforms, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quality Assurance and Quality Control Market |
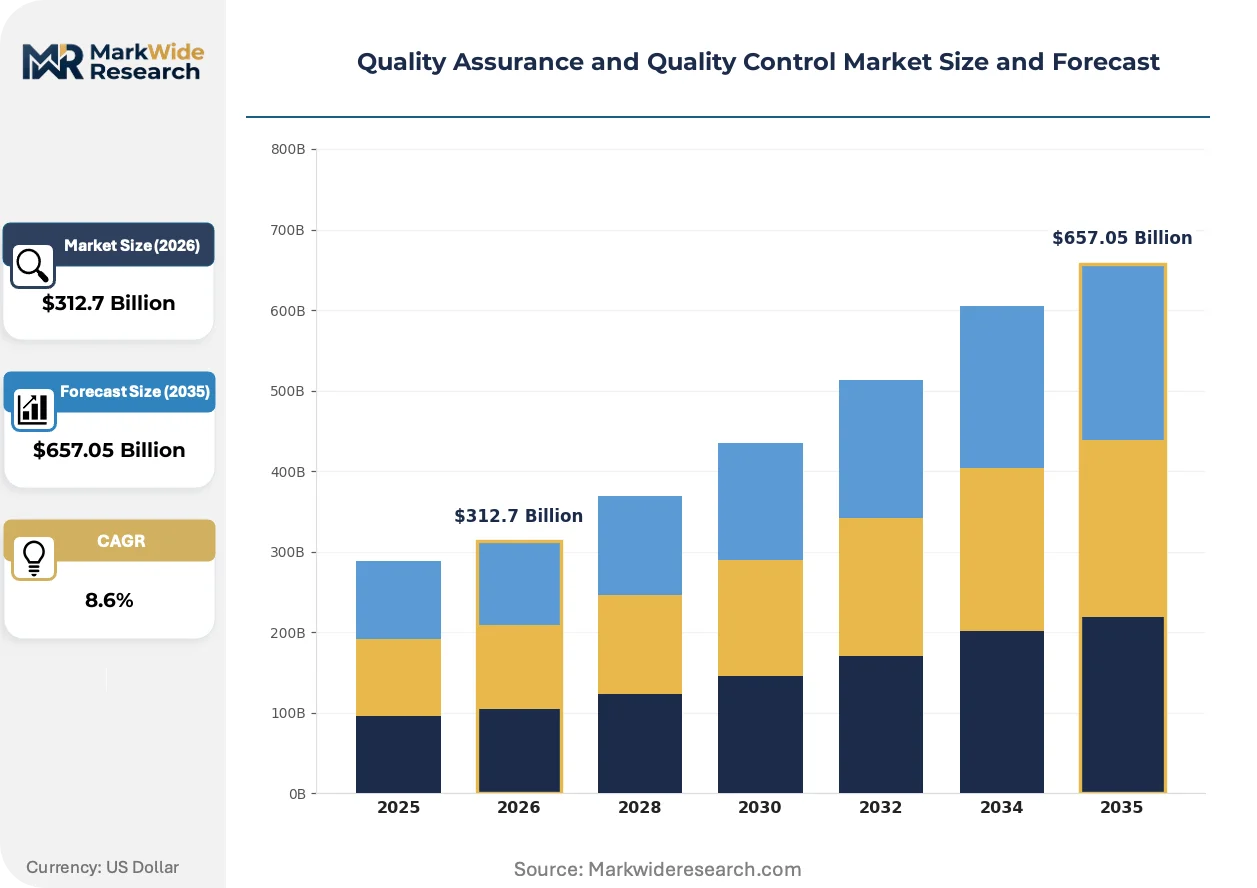
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $657.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Tools, Consulting Services, Training Application: Manufacturing, Pharmaceuticals, Food Safety, IT Services End User: Healthcare Providers, Manufacturers, Laboratories, Retailers Service Type: Audit Services, Compliance Consulting, Testing Services, Process Improvement |
| Companies Covered | Infosys, SGS, Deloitte, Intertek, Bureau Veritas, Accenture, Capgemini, Eurofins Scientific, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quality Assurance and Quality Control Market Strategic Shifts
Quality verification is migrating from laboratory benches to production lines, with sensor networks and machine learning compressing detection timelines from days to minutes while redefining the role of human inspectors.
Process analytical technology is displacing end-point testing in sterile injectable manufacturing. Large-molecule drug producers in Massachusetts and North Rhine-Westphalia deploy in-line spectroscopy and chromatography to monitor critical quality attributes during fermentation. Real-time release testing eliminates quarantine warehousing, compressing working capital cycles by weeks.
REACH and RoHS substance restrictions are recasting material qualification protocols for medical device manufacturers. Suppliers must document full chemical composition down to 0.1% threshold concentrations, extending supplier audit depth and documentation volume. European notified bodies now embed substance compliance into ISO 13485 surveillance audits, elevating procurement due diligence requirements.
Buyer concentration among contract development and manufacturing organizations is consolidating vendor relationships. Large CDMOs in Switzerland and Ireland now mandate single-platform quality data exchange, disqualifying smaller testing laboratories lacking API-connected laboratory information management systems. This procurement compression favors integrated providers with multi-site accreditation over specialized regional laboratories.
Quality Assurance and Quality Control Market Segmentation
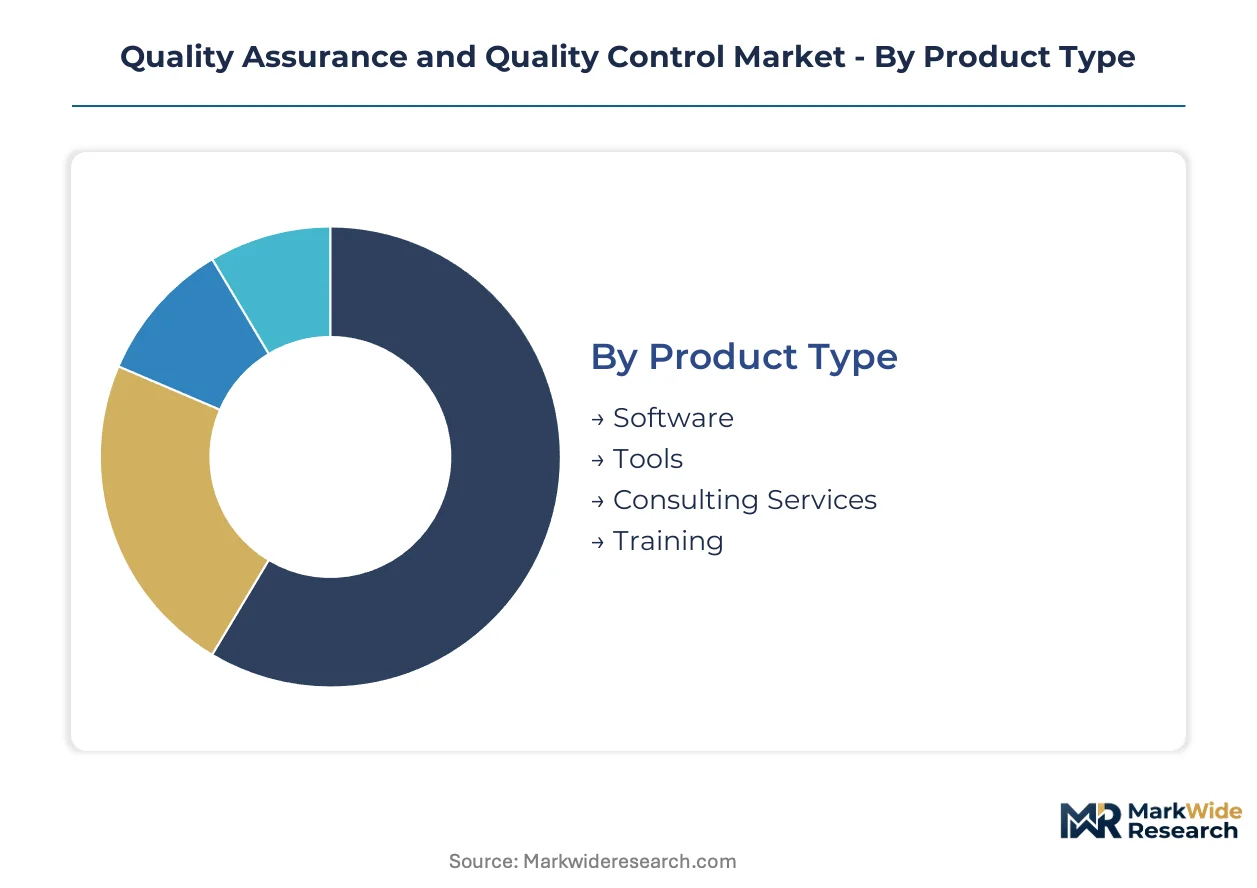
QA/QC procurement patterns diverge sharply across product and service categories, with regulatory stringency dictating whether buyers prioritize capital-intensive software platforms or outsourced verification expertise. Pharmaceutical serialization mandates and FDA cGMP enforcement create tiered compliance thresholds that reshape segment economics.
Product Type:
FDA 21 CFR Part 11 and EU Annex 11 requirements for electronic records create divergent validation burdens across product categories, favoring vendors with pre-validated software architectures over unqualified tool suppliers.
- Software:Enterprise quality management systems integrate document control, CAPA tracking, and training records into unified platforms that satisfy FDA cGMP computer system validation requirements. Pharmaceutical manufacturers in Germany and the United States deploy these systems to harmonize multi-site compliance across distributed production networks, though validation timeline compression delays ROI realization.
- Tools:Physical measurement instruments, automated inspection equipment, and calibration devices provide the hardware substrate for statistical process control. Demand concentrates in biologics manufacturing where in-line spectroscopy and chromatography monitor critical quality attributes during fermentation, displacing end-point testing in sterile injectable production.
- Consulting Services:Regulatory strategy, gap assessments, and remediation planning support compliance navigation for mid-cap manufacturers lacking internal quality infrastructure.
- Training:ISO 17025 laboratory accreditation and FDA investigator training programs address certified personnel scarcity that inflates laboratory operating costs.
Software handles the majority of throughput; Consulting Services is gaining share fastest as serialization deadlines compress internal capability gaps.
Application:
Cost tier differentiation separates capital-intensive pharmaceutical deployments from leaner manufacturing implementations, with batch-release complexity determining per-site expenditure levels.
- Manufacturing:Statistical sampling protocols, automated optical inspection, and corrective action loops verify dimensional tolerances and functional specifications across discrete and process production. Automotive and aerospace clusters in Germany and the United States absorb substantial QA/QC spend on dimensional metrology and non-destructive testing.
- Pharmaceuticals:Cell and gene therapy production requires contamination control protocols exceeding small-molecule standards, elevating specialized testing demand. EMA serialization deadlines force European manufacturers to upgrade track-and-trace systems, triggering capital deployment into integrated QA/QC platforms with real-time data verification.
- Food Safety:HACCP implementation, allergen management, and pathogen testing protect supply chain integrity for processors and retailers under FDA FSMA and EFSA oversight.
- IT Services:Software development lifecycle quality, cybersecurity validation, and cloud infrastructure compliance address ISO 27001 and SOC 2 requirements for financial and healthcare technology providers.
Manufacturing captures the largest absolute spend; Pharmaceuticals exhibits the steepest expansion trajectory as biologics manufacturing scales.
End User:
Customer type determines procurement modality, with concentrated buyers mandating platform standardization while fragmented purchasers favor flexible service arrangements.
- Healthcare Providers:Hospital systems and integrated delivery networks implement clinical quality management and patient safety protocols under Joint Commission and CMS oversight.
- Manufacturers:Industrial producers deploy the full spectrum of QA/QC capabilities from incoming material inspection through final release testing, with contract development and manufacturing organizations consolidating vendor relationships around single-platform data exchange.
- Laboratories:ISO 17025-accredited analytical facilities serve as outsourced verification partners for manufacturers lacking internal testing capacity, particularly in Indian pharmaceutical export corridors requiring CDSCO-aligned partnerships for FDA and EMA market access.
- Retailers:Private label quality programs and supplier audit networks protect brand integrity across fragmented global sourcing bases.
Manufacturers dominate procurement volume; Laboratories is expanding most quickly as outsourcing accelerates among mid-cap pharmaceutical exporters.
Service Type:
Margin concentration favors testing services due to specialized equipment and certified personnel requirements, while audit and consulting services compete on expertise differentiation rather than capital barriers.
- Audit Services:Third-party facility inspections, supplier qualification assessments, and regulatory mock inspections provide independent verification of GMP, GDP, and ISO compliance status.
- Compliance Consulting:Regulatory strategy development, submission preparation, and remediation planning navigate FDA cGMP enforcement and EMA inspection findings for manufacturers facing consent decrees or warning letters.
- Testing Services:Analytical chemistry, microbiological examination, and stability studies generate the highest margins within service categories. Eurofins Scientific and SGS leverage global laboratory footprints to dominate physical testing workflows, while Bureau Veritas anchors position through maritime and industrial inspection depth.
- Process Improvement:Lean Six Sigma deployment, statistical process control implementation, and digital twin integration enable real-time release testing that reduces quarantine inventory carrying costs.
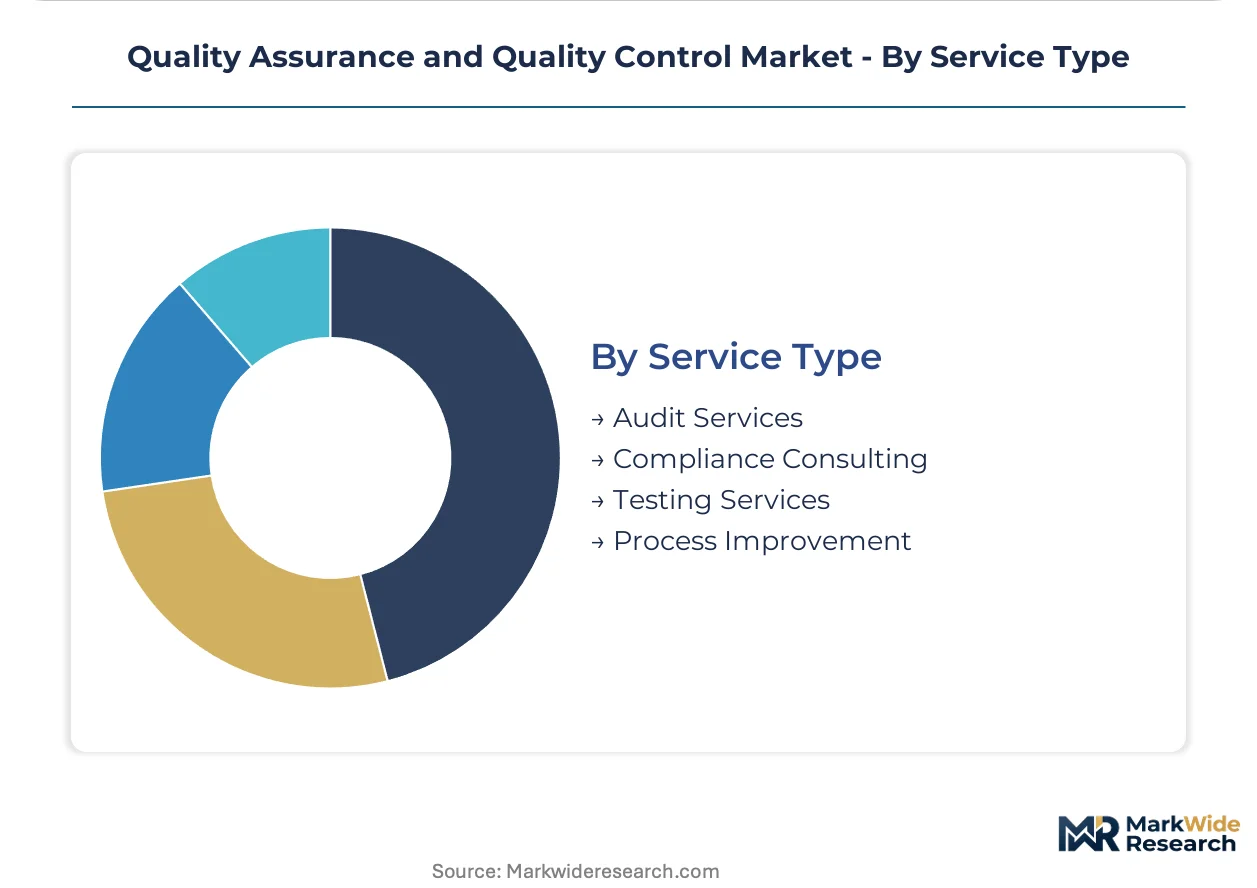
Testing Services commands the highest margin pool; Process Improvement is climbing the fastest as predictive analytics capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics corridor underwrites the Netherlands' role as Europe's quality verification gateway, connecting German chemical clusters to Atlantic shipping lanes.
United States
FDA serialization mandates and biologics manufacturing expansion drive QA/QC infrastructure investment. The 21 CFR Part 11 electronic records requirements force pharmaceutical manufacturers to upgrade validation protocols. Massachusetts and North Carolina biotech clusters deploy process analytical technology for real-time release testing.
Germany
Automotive precision manufacturing and pharmaceutical exports sustain demand for metrology and contamination control systems. EMA GMP Annex 11 inspections tighten documentation standards for batch release. North Rhine-Westphalia chemical parks integrate cloud-based quality management across multi-site production networks.
India
CDSCO-aligned export manufacturers require ISO 17025 laboratory partnerships to access FDA-regulated markets. The PLI scheme for pharmaceuticals incentivizes domestic quality infrastructure buildout. Gujarat and Maharashtra pharmaceutical corridors expand analytical testing capacity to satisfy import market entry requirements.
Switzerland
Contract development and manufacturing organizations consolidate vendor relationships around single-platform data exchange. Swissmedic inspection protocols exceed standard GMP requirements for biologics. Basel and Zurich life sciences clusters mandate API-connected laboratory information management systems from testing partners.
China
NMPA data integrity enforcement and biologics manufacturing scale-up elevate specialized quality platform demand. GB standards alignment for medical devices requires enhanced supplier audit depth. Yangtze River Delta pharmaceutical manufacturers adopt centralized document control to harmonize multi-facility compliance.
Quality Assurance and Quality Control Market Competitive Environment
Listed leaders compete with private specialists across accreditation breadth and geographic coverage. The vendor base separates into three tiers: integrated multinationals with multi-site laboratory networks, mid-cap specialists concentrating on regional regulatory expertise, and software-driven platforms automating document control workflows. Strategic moves center on laboratory acquisition to expand testing menus and cloud platform partnerships to embed quality management into manufacturing execution systems.
Within the integrated testing tier, SGS and Bureau Veritas occupy positions anchored by global laboratory footprints and maritime inspection depth. Eurofins Scientific exemplifies the bioanalytical specialization archetype, with pharmaceutical quality verification capabilities concentrated in European and North American clusters. Accenture and Capgemini represent the consulting-technology hybrid model, deploying quality management software implementations alongside regulatory strategy advisory.
| Leading Market Players |
|---|
| Infosys |
| SGS |
| Deloitte |
| Intertek |
| Bureau Veritas |
| Accenture |
| Capgemini |
| Eurofins Scientific |
| IBM |
| Others |
Value Chain & Pricing Dynamics
Cloud-based quality management platforms displacing on-premise installations simultaneously redraw supply geography toward software hubs in the United States and Germany while compressing pricing premiums for legacy hardware-dependent verification services. This substitution dynamic concentrates vendor power among SaaS providers with pre-validated FDA 21 CFR Part 11 architectures, forcing traditional testing laboratories into margin-defensive positioning.
Pricing Analysis
Certification level creates the primary spread between ISO 17025-accredited laboratories and unqualified regional competitors, with three-tier pricing structure across premium, standard, and economy levels dominating procurement. Subscription-based enterprise quality management systems command recurring revenue premiums against project-based consulting engagements, while pharmaceutical manufacturers exhibit lowest price sensitivity due to consent decree exposure. Pricing pressure stems from buyer consolidation among contract development and manufacturing organizations mandating single-platform data exchange, compressing margins for non-integrated regional laboratories.
Supply Chain Analysis
Extended lead times for high-precision chromatography and mass spectrometry systems from Germany, Japan, and the United States expose buyers to currency and logistics volatility. Equipment production concentrates in these three manufacturing clusters, with analytical chemistry consumables and certified reference materials feeding from specialized chemical suppliers. Single-source vulnerability runs through German precision optics and Japanese detector components. Distribution runs through direct manufacturer relationships for capital equipment and third-party laboratory networks for outsourced testing services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality assurance and quality control functions as a defensive-moat market where regulatory entrenchment creates switching costs that lock pharmaceutical manufacturers into validated vendor relationships. ISO 17025 accreditation and FDA cGMP inspection histories constitute irreproducible assets for incumbent testing providers.
For Market Incumbents: Consolidate laboratory footprints in Indian pharmaceutical export corridors before CDSCO-aligned manufacturers complete ISO 17025 partnership arrangements. Acquire cloud-based quality management platforms to embed document control into manufacturing execution systems, defending against software-native entrants threatening to disintermediate physical testing workflows. Vertical integration into real-time release testing capabilities anchors position as process analytical technology displaces end-point verification. For New Entrants and Emerging Players: Lead with EU AI Act algorithmic auditing capabilities targeting automated manufacturing decision systems in German chemical parks and Massachusetts biotech clusters. White-space concentration exists in digital twin integration for cell and gene therapy producers lacking predictive quality analytics infrastructure. Position as API-connected laboratory information management system specialists serving mid-cap contract development and manufacturing organizations disqualified by large platform mandates. For Investors and Strategic Acquirers: FDA serialization deadline enforcement reshapes the acquisition landscape toward integrated providers with multi-site accreditation and pre-validated software architectures. Long-term viability favors testing networks with pharmaceutical specialization over generalist industrial inspection portfolios. Monitor EMA inspection finding patterns as signal for quality infrastructure investment velocity among European manufacturers facing batch-release timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Accreditation Expansion | ISO 17025 multi-site certification unlocks CDSCO-aligned pharmaceutical export corridors in Gujarat and Maharashtra. |
| Cloud Platform Integration | FDA 21 CFR Part 11 pre-validated architectures embed quality management into distributed manufacturing execution systems. |
| Real-Time Release Testing Capability | Process analytical technology convergence eliminates quarantine inventory carrying costs for sterile injectable producers. |
| Algorithmic Auditing Service Launch | EU AI Act compliance verification extends quality frameworks into automated manufacturing decision systems. |
| Digital Twin Partnership | Predictive modeling integration enables pharmaceutical manufacturers to compress batch-release timelines by weeks. |
Study Parameters
The analysis maps software platforms, testing services, consulting engagements, and training programs, each validated through quality assurance directors, regulatory affairs managers, laboratory operations heads, and pharmaceutical procurement leads. Primary interviews with these stakeholders combine with secondary validation against FDA warning letter databases, EMA inspection finding reports, ISO 17025 accreditation registries, and SEC filings from listed testing providers. Bottom-up segmentation sizing triangulates against top-down market envelope estimates.
Consistency checks against external benchmarks validate projection outputs across the modeling period. The analytical framework segments by product type, application, end user, and service category, with additional dimensioning by regulatory jurisdiction cluster and manufacturing complexity tier. CAGRs derive from segment-level growth trajectory analysis incorporating pharmaceutical serialization mandate enforcement timelines and biologics manufacturing expansion rates.
Underlying assumptions cover sustained FDA cGMP enforcement intensity and EMA serialization deadline adherence, with deviation risk concentrated in equipment import logistics disruptions and certified personnel availability constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety and Standards
Precision Food Thermometers Market
Food Safety and Standards
Food Certification Market
Food Safety and Standards
Bar Inspection System Market
Food Safety and Standards
Pathogen Reduction Systems Market
Food Safety and Standards
Food Irradiation Market
Food Safety and Standards
Testing, Inspection, and Certification Market
Food Safety and Standards
Global Cold Chain Monitoring Market
Food Safety and Standards
Food and Beverage Industrial Disinfection and Cleaning Market
Food Safety and Standards
Automatic Distillation Analyzer Market
Food Safety and Standards
Natural Antimicrobials Market
Food Safety and Standards
GMO Labeled Food Market
Food Safety and Standards
Food Safety Software Market
Food Safety and Standards
Cold-Chain Friendly Post-Harvest Sanitizing Mist Market
Food Safety and Standards
Blockchain Food Traceability Market
Food Safety and Standards
Nutritional Labeling Market
Food Safety and Standards
Food Authenticity Market