
 Food and Beverage Industrial Disinfection and Cleaning Market | 2026-2036
Food and Beverage Industrial Disinfection and Cleaning Market Size, Share, and Industry Trends Forecast 2026-2036
Food and Beverage Industrial Disinfection and Cleaning Market Foresight
REACH compliance in Europe is recalibrating the cost-of-entry calculus for chemical formulators entering the food and beverage sanitation space. Ecolab leverages its integrated water and hygiene platform to sustain service contracts across major dairy cooperatives. Diversey Holdings anchors its competitive position through specialized clean-in-place formulations for beverage bottlers. Kersia Group differentiates via peracetic acid technologies that navigate tightening residue thresholds in meat processing corridors.
Food and beverage industrial disinfection and cleaning encompasses chemically formulated agents and mechanical systems designed to eliminate pathogenic microorganisms, biofilms, and organic residues from production surfaces, processing equipment, and facility environments, typically operating within pH ranges of 2-12 and contact times of 30 seconds to 10 minutes depending on target organism lethality requirements. These solutions serve the primary industrial purpose of ensuring microbiological safety compliance, preventing cross-contamination between production batches, and maintaining operational uptime in continuous-processing food manufacturing facilities. Sanitizers and disinfectants command the largest volume share within product type classifications due to their mandated deployment frequency under HACCP protocols, while equipment cleaning applications generate premium margin pools as OEM-integrated dosing systems lock in recurring chemical supply agreements. Dairy processing plants represent the most concentrated end-user segment, driven by stringent thermophile control requirements and the sector's structural shift toward extended production runs with minimal intervention windows.
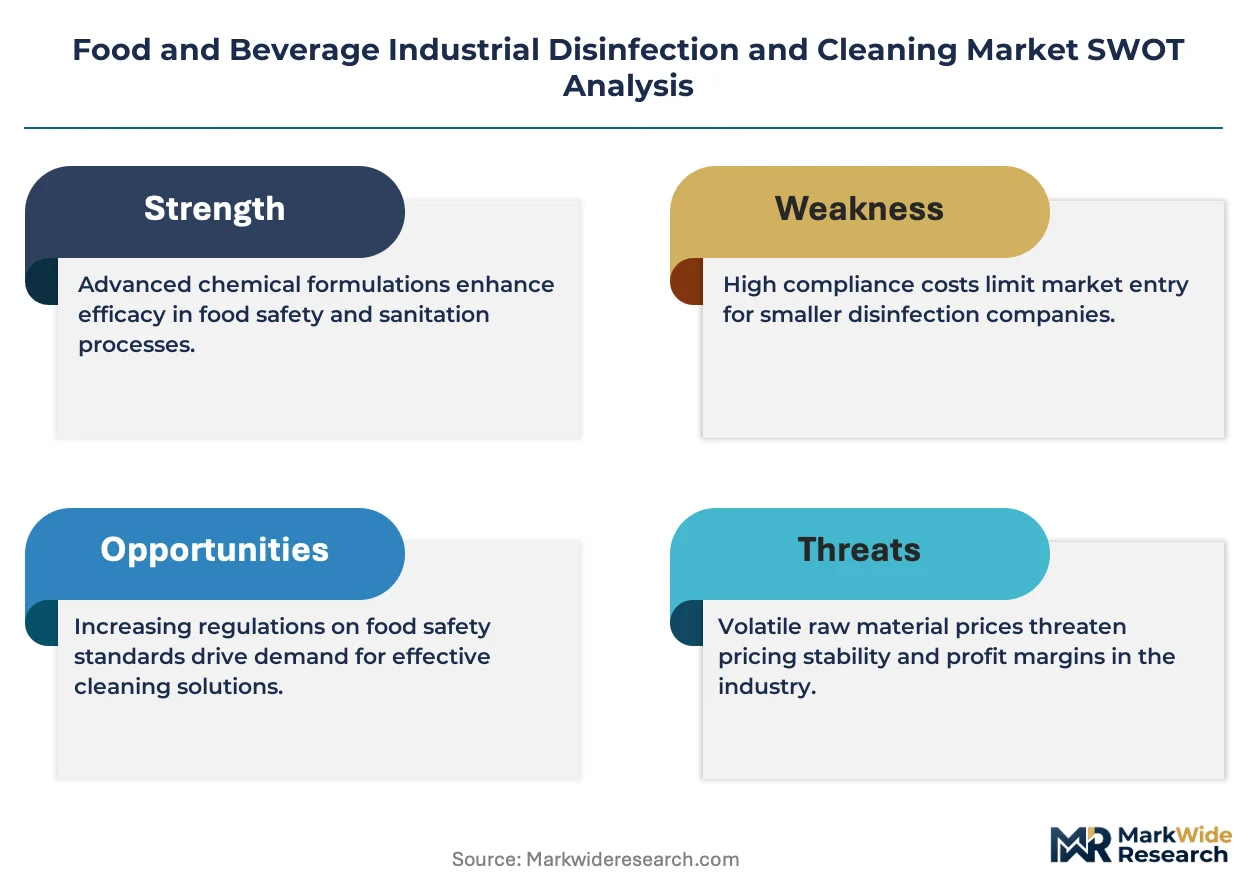
The EPA governs antimicrobial efficacy claims and toxicological profiles for food-contact sanitizers in the United States, while the FDA enforces Current Good Manufacturing Practice regulations that mandate documented cleaning validation protocols. EFSA and national regulators across EU member states are converging on maximum residue limits for chlorine-releasing compounds, forcing reformulation investments among legacy suppliers. Stakeholders must monitor the divergence between U.S. and European approval pathways for novel biocidal active substances, as asynchronous regulatory timelines threaten to fragment product portfolios and inflate compliance overhead for multinational operators.
Market Dynamics
Automated clean-in-place systems are compressing intervention windows in dairy processing corridors, forcing chemical formulators to engineer faster-acting biocidal actives that maintain efficacy at reduced contact times and lower temperatures.
Growth Catalysts
- REACH compliance recalibration:European chemical formulators are investing in novel active substance dossiers to secure biocidal product authorization ahead of 2025 review cycles.
- Extended dairy production runs:Thermophile control mandates in ultra-high-temperature processing lines are accelerating specification upgrades for acid-anionic sanitizers.
- Germany's KBA protocols:Strict residue thresholds for food-contact surfaces are pulling peracetic acid formulations into meat processing applications.
Market Restraints
- Quaternary ammonium compound tightening:EPA and FDA residue limit reductions are forcing legacy suppliers into costly reformulation cycles without guaranteed approval timelines.
- Specialized chemical concentration:North American chlor-alkali supply constraints are elevating sodium hypochlorite input costs for beverage bottlers.
- Asynchronous approval pathways:Divergent U.S. and European biocidal active substance timelines threaten portfolio fragmentation for multinational operators.
Strategic Opportunities
- Clean-in-place OEM integration:Dosing system lock-in agreements with dairy cooperatives are creating captive chemical supply channels.
- Water-hygiene convergence:Integrated platform models combining sanitation chemistry with wastewater treatment are penetrating beverage manufacturing clusters.
- EFSA residue harmonization:Converging chlorine-releasing compound limits across EU member states are consolidating demand for peracetic acid alternatives.
Industry Challenges
- Validation documentation burden:FDA Current Good Manufacturing Practice mandates require continuous cleaning protocol verification that strains quality assurance staffing.
- Legacy system integration:Retrofitting automated dosing hardware into aging dairy processing infrastructure demands extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food and Beverage Industrial Disinfection and Cleaning Market |
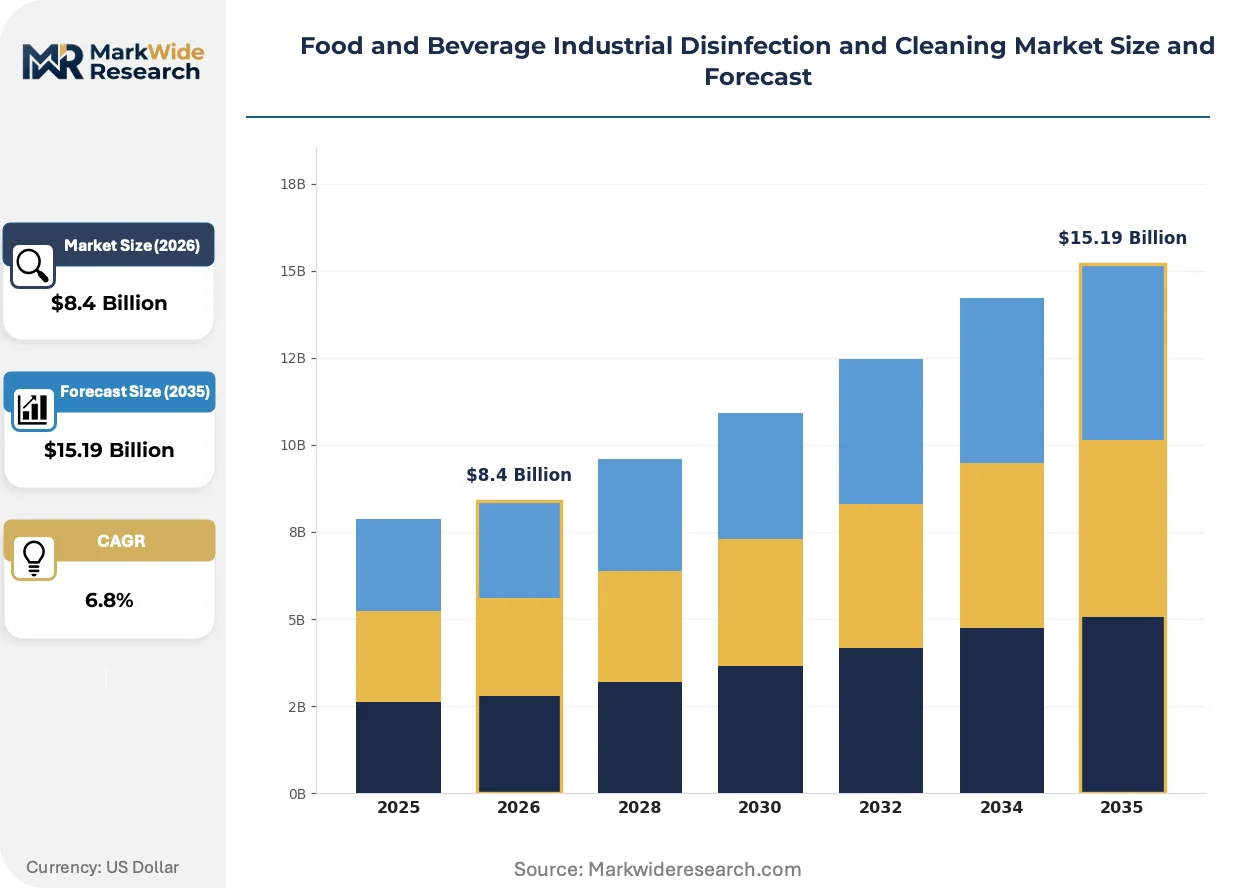
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sanitizers, Detergents, Disinfectants, Degreasers, Foams Application: Equipment Cleaning, Surface Sanitization, Wastewater Treatment, Floor Disinfection, Packaging Sterilization End User: Dairy Processing Plants, Beverage Manufacturers, Meat Processing Facilities, Confectionery Production Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesalers, Specialized Suppliers |
| Companies Covered | Diversey Holdings Ltd., The Clorox Company, Ecolab Inc., Christeyns, Kersia Group, Evonik Industries AG, STERIS plc, 3M Company, Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food and Beverage Industrial Disinfection and Cleaning Market Shifts & Advancements
Peracetic acid technologies are displacing legacy chlorine-based chemistries across thermally sensitive processing environments, while regulatory residue harmonization compresses formulation approval cycles.
Electrochemical activation systems are rewriting sanitation economics in beverage bottling corridors. These on-site generators produce hypochlorous acid from salt and water, eliminating bulk chemical transport and storage liabilities. Mid-sized craft breweries in the United States are deploying compact units to bypass distributor markups. The technology is rewriting procurement patterns by shifting volume risk from chemical suppliers to capital-equipment financiers.
REACH biocidal product regulation is forcing active substance portfolio consolidation across European formulators. Legacy quaternary ammonium compound suppliers face 2025 dossier resubmission deadlines with incomplete toxicological datasets. Meat processing corridors in Germany and the Netherlands are accelerating peracetic acid qualification to preempt supply discontinuity.
Service unbundling is fragmenting procurement decision-making in dairy cooperatives. Equipment maintenance contracts are separating from chemical supply agreements, enabling direct negotiation with specialty formulators. This pattern is most visible in Wisconsin and California processing clusters where cooperative scale supports dedicated technical staffing.
Food and Beverage Industrial Disinfection and Cleaning Market Segmentation
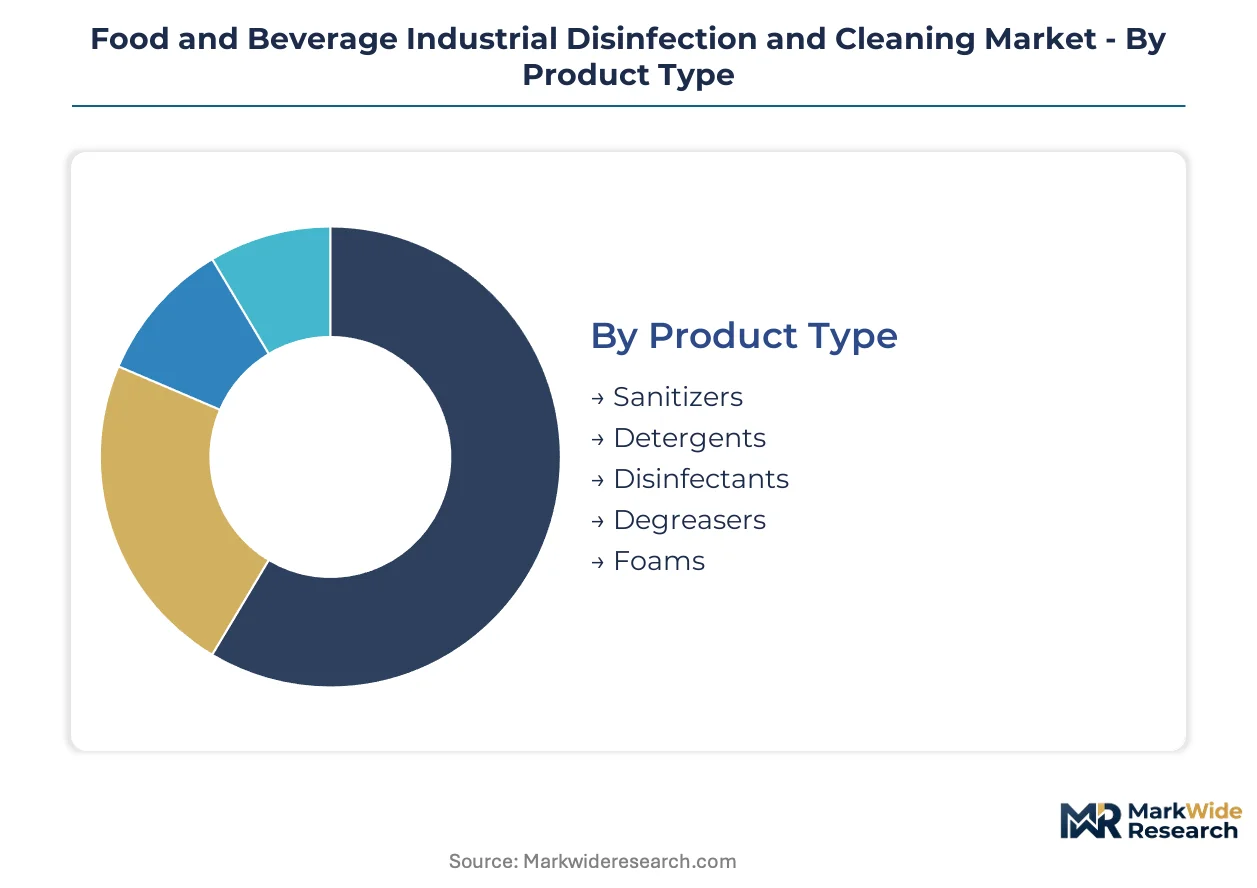
Segmentation in food and beverage industrial disinfection and cleaning reveals how procurement patterns diverge between integrated service contracts and standalone chemical purchases. Understanding these splits exposes where margin pools concentrate and which channels lock in recurring revenue.
Product Type:
Standalone chemical formulations dominate spot purchasing, while embedded system chemistries tie into automated dosing infrastructure with long-term supply agreements.
- Sanitizers:Acid-anionic and peracetic acid formulations engineered for 30-second to 10-minute contact times against pathogenic microorganisms. Demand concentrates in dairy processing corridors where thermophile control mandates drive specification upgrades under FDA and EFSA protocols.
- Disinfectants:Chlorine-releasing compounds and quaternary ammonium solutions operating across pH 2-12 ranges for biofilm elimination. Germany's KBA enforces strict residue thresholds that pull peracetic acid alternatives into meat processing applications.
- Detergents:Alkaline and enzymatic cleaners for organic residue removal in beverage bottling lines.
- Degreasers:Solvent-based and surfactant formulations targeting lipid deposits in frying and rendering operations.
- Foams:Cling-extended formulations for vertical surface coverage in slaughterhouse environments.
Sanitizers lead volumes today; disinfectants are gaining share fastest as residue regulations tighten.
Application:
Cost tier stratification separates capital-intensive automated systems from labor-dependent manual protocols, with premium margins attaching to validation-intensive equipment cleaning.
- Equipment Cleaning:Clean-in-place systems and manual protocols for processing vessels, heat exchangers, and filling machinery. OEM-integrated dosing systems in Wisconsin and California dairy cooperatives lock in recurring chemical supply agreements with extended production run requirements.
- Surface Sanitization:Food-contact and non-contact surface protocols using spray, fog, or wipe application methods. REACH compliance recalibration across European formulators is accelerating peracetic acid qualification ahead of biocidal product authorization deadlines.
- Wastewater Treatment:Disinfection of process effluent prior to discharge under environmental permits.
- Floor Disinfection:High-traffic area protocols using foaming and misting systems in production corridors.
- Packaging Sterilization:Pre-fill decontamination of bottles, cartons, and flexible films.
Equipment cleaning commands the steepest expansion trajectory; surface sanitization retains the largest installed base.
End User:
Customer type segmentation tracks how cooperative scale, regulatory exposure, and production continuity requirements reshape procurement authority between integrated platforms and specialty formulators.
- Dairy Processing Plants:Ultra-high-temperature and extended shelf-life operations with minimal intervention windows. Thermophile control mandates in continuous-processing lines specify acid-anionic sanitizers with reduced contact times.
- Beverage Manufacturers:Carbonated soft drink, juice, and bottled water operations with high-volume filling lines. Electrochemical activation systems are rewriting procurement economics by shifting volume risk from chemical suppliers to capital-equipment financiers in mid-sized craft breweries.
- Meat Processing Facilities:Slaughter, cutting, and further processing operations with biofilm control priorities.
- Confectionery Production:Sugar and chocolate handling environments with specialized soil profiles.
Dairy processing plants anchor revenue concentration; beverage manufacturers are expanding most quickly through OEM integration.
Distribution Channel:
Supply concentration patterns reveal how direct technical service relationships compete against distributor networks for procurement decision-making authority in fragmented end-user bases.
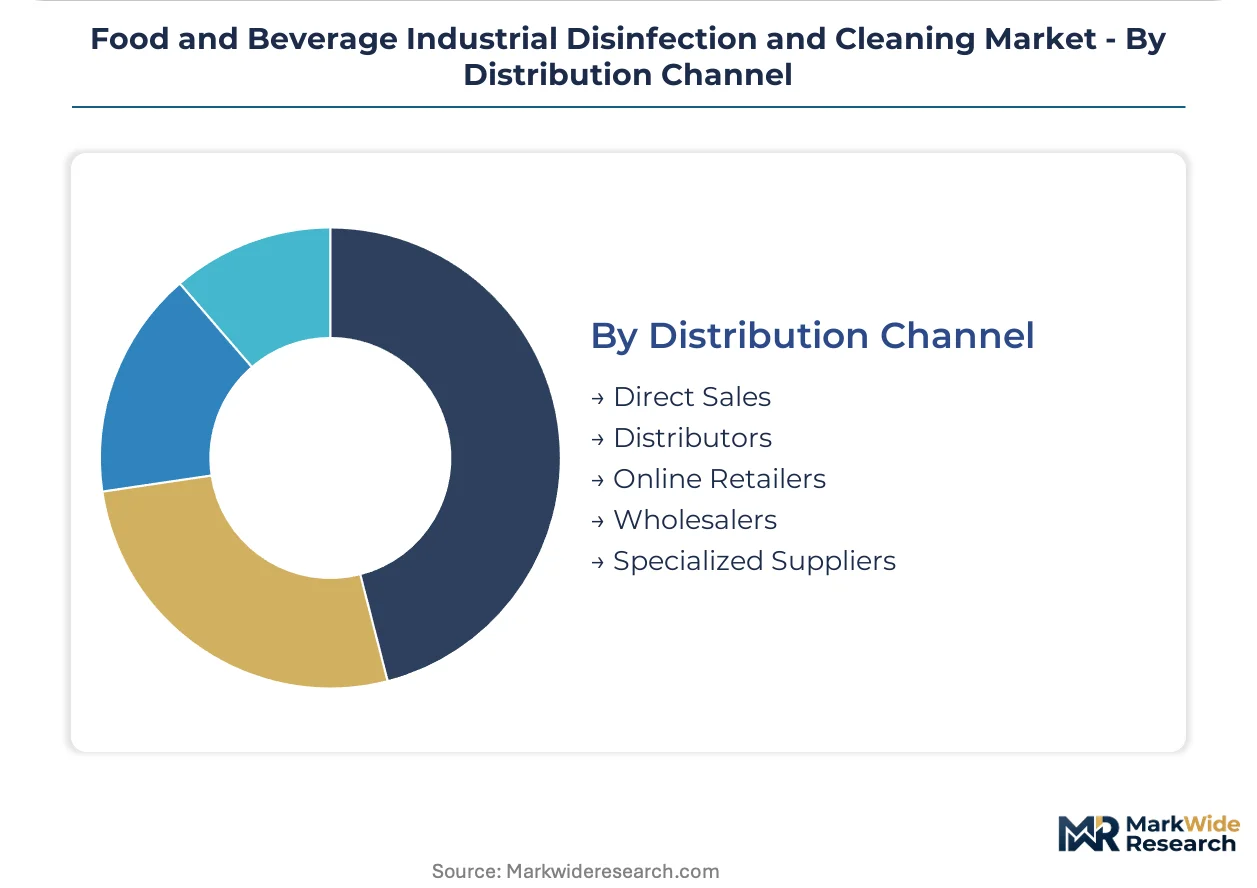
- Direct Sales:Manufacturer-to-end-user contracts with embedded technical service and validation support. Ecolab leverages integrated water and hygiene platforms to sustain service contracts across major dairy cooperatives.
- Distributors:Regional chemical and janitorial supply houses with local inventory and delivery capabilities. Service unbundling in Wisconsin and California processing clusters enables direct negotiation with specialty formulators as equipment maintenance contracts separate from chemical supply agreements.
- Online Retailers:E-commerce platforms for standardized product procurement in smaller operations.
- Wholesalers:Volume aggregation points for multi-site operators with centralized purchasing.
- Specialized Suppliers:Niche formulators focused on specific application technologies or regulatory compliance support.
Direct sales capture premium margins; distributors retain volume leadership in fragmented geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineering talent clusters in Germany's Rhineland and Wisconsin's dairy processing corridors anchor the industry's geographic concentration. Technical service expertise concentrates near major food manufacturing hubs where regulatory compliance demands on-site validation support.
Germany
Dairy cooperatives in Bavaria and Lower Saxony drive specification demand for acid-anionic sanitizers with reduced contact times. The KBA enforces strict residue thresholds for food-contact surfaces that pull peracetic acid formulations into meat processing applications. The Cologne-Düsseldorf corridor hosts formulator R&D facilities serving pan-European meat processing clients.
United States
Extended production runs in Wisconsin and California dairy cooperatives compress intervention windows for thermophile control. The EPA governs antimicrobial efficacy claims while FDA mandates documented cleaning validation protocols under Current Good Manufacturing Practice regulations. Electrochemical activation systems are penetrating mid-sized craft breweries in the Pacific Northwest to bypass distributor markups.
Netherlands
Ultra-high-temperature processing lines in North Brabant and Gelderland specify faster-acting biocidal actives for minimal intervention windows. EFSA convergence on maximum residue limits for chlorine-releasing compounds forces reformulation investments among legacy suppliers. The Rotterdam-Antwerp port cluster concentrates bulk chemical import infrastructure for beverage bottlers.
France
Cheese manufacturing cooperatives in Normandy and Brittany anchor demand for specialized biofilm control chemistries. ANSM and national regulators enforce biocidal product authorization timelines that threaten supply discontinuity for legacy quaternary ammonium compound suppliers. The Lyon corridor hosts peracetic acid qualification programs preempting 2025 dossier deadlines.
Canada
Large-scale dairy processing in Ontario and Quebec drives adoption of automated clean-in-place systems with OEM-integrated dosing. Health Canada and PMRA regulate antimicrobial efficacy claims with timelines diverging from U.S. EPA pathways. The Toronto-Waterloo corridor concentrates technical service staffing for cross-border cooperative clients.
Food and Beverage Industrial Disinfection and Cleaning Market Competitive Landscape
The competitive structure tilts toward integrated platform providers with captive water-hygiene convergence capabilities. Tier-one operators sustain multi-year service contracts through embedded validation documentation and dosing system lock-in agreements. Three archetypes dominate: integrated hygiene-water platforms, specialty peracetic acid formulators, and electrochemical activation equipment-chemistry hybrids. Consolidation pressure concentrates among legacy quaternary ammonium compound suppliers facing asynchronous regulatory resubmission timelines.
Within the integrated platform tier, Ecolab Inc. and Diversey Holdings Ltd. exemplify service-contract anchoring through technical staffing density in dairy processing corridors. Specialty biocidal positioning is occupied by Kersia Group, which sits within the peracetic acid qualification wave sweeping German and Dutch meat processing facilities. These three represent divergent strategic responses to REACH-driven active substance portfolio consolidation.
| Leading Market Players |
|---|
| Diversey Holdings Ltd. |
| The Clorox Company |
| Ecolab Inc. |
| Christeyns |
| Kersia Group |
| Evonik Industries AG |
| STERIS plc |
| 3M Company |
| Solvay S.A. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up chemical formulators anchor supply concentration in Germany's Rhineland and Wisconsin's dairy corridors, translating technical staffing density into pricing discipline through multi-year service contracts with embedded validation documentation.
Pricing Analysis
The bundled-vs-unbundled service split separates integrated water-hygiene platforms from standalone chemical procurement. Pricing stratifies across premium, standard, and economy tiers based on certification grade under FDA Current Good Manufacturing Practice protocols and volume scale in cooperative purchasing. Cost compression in standard-tier chlorine-releasing compounds is intensifying because of North American chlor-alkali supply constraints. Dairy cooperatives in Wisconsin and California exhibit the least price sensitivity due to thermophile control mandates, while mid-sized craft breweries in the Pacific Northwest drive hardest bargain negotiations.
Supply Chain Analysis
Reverse-logistics flows for electrochemical activation equipment refurbishment are emerging as equipment-chemistry hybrids extend service lifecycles through on-site generator maintenance programs. Raw material supply concentrates in Germany, the Netherlands, and the United States, drawing from sodium hypochlorite feedstocks, peracetic acid precursors, and quaternary ammonium compound intermediates. Single-source vulnerability in European biocidal active substance authorization under REACH threatens supply continuity for legacy formulators. Distribution runs through direct technical service relationships with dairy cooperatives and regional chemical distributors serving fragmented beverage bottlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium-tier peracetic acid formulations as residue regulations tighten and electrochemical activation shifts volume risk downstream.
For Market Incumbents: Cement captive supply channels through clean-in-place OEM integration with extended dosing system lock-in agreements in Wisconsin and California dairy corridors. Deepen backward integration into peracetic acid precursor production to preempt EFSA-driven reformulation cycles. Vertical integration of validation documentation services offsets FDA Current Good Manufacturing Practice staffing strains. For New Entrants and Emerging Players: The price-point gap between premium integrated platforms and economy-tier distributor chemicals opens white-space in mid-sized craft brewery electrochemical activation equipment financing. Target Pacific Northwest beverage clusters with on-site hypochlorous acid generator deployment bypassing traditional chemical supply chains. Lead with capital-equipment-as-a-service models shifting procurement from chemical volume to utility-based sanitation economics. For Investors and Strategic Acquirers: Valuations sit cheapest among legacy quaternary ammonium compound suppliers facing asynchronous EPA and EFSA resubmission timelines. Five-to-ten year viability hinges on successful active substance portfolio pivot toward peracetic acid and electrochemical alternatives. Watch for REACH biocidal product authorization completion rates as inflection indicator for European supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-in-Place OEM Integration | Dosing system lock-in with Wisconsin dairy cooperatives creates captive chemical supply channels. |
| Backward Integration into Precursors | In-house peracetic acid production secures margin against EFSA residue limit convergence. |
| Electrochemical Activation Deployment | On-site hypochlorous acid generators shift volume risk from suppliers to equipment financiers. |
| Validation Documentation Services | Embedded FDA Current Good Manufacturing Practice compliance staffing sustains multi-year contracts. |
| REACH Dossier Resubmission | Biocidal product authorization completion determines European supply continuity for legacy actives. |
Research Methodology
Direct dialogue with plant sanitation managers, dairy cooperative procurement leads, chemical formulator technical directors, and EPA regulatory affairs specialists grounds qualitative findings. Secondary validation draws from FDA 483 inspection observations, EFSA scientific opinions, EPA antimicrobial efficacy registrations, and Cefic chemical industry statistics. Bottom-up and top-down triangulation cross-checks facility-level procurement patterns against national production data.
Bottom-up modeling builds from individual dairy processing plant and beverage bottler capacity installations, while top-down analysis tracks national chemical consumption aggregates. Segmentation dimensions span product type, application protocol, end-user industry, and distribution channel complexity. CAGRs derive from regression against historical adoption curves of clean-in-place automation and electrochemical activation penetration. Forecast inputs incorporate REACH authorization timelines and FDA residue limit revision patterns.
Caveats apply where asynchronous EPA and EFSA approval pathways or chlor-alkali supply disruptions could materially shift the outlook. Forecasts rest on assumptions regarding cooperative scale consolidation and electrochemical activation capital cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety and Standards
Nutritional Labeling Market
Food Safety and Standards
Cold-Chain Friendly Post-Harvest Sanitizing Mist Market
Food Safety and Standards
Natural Antimicrobials Market
Food Safety and Standards
Testing, Inspection, and Certification Market
Food Safety and Standards
Food Authenticity Market
Food Safety and Standards
Bar Inspection System Market
Food Safety and Standards
Food Grade Biofilms Market
Food Safety and Standards
Bakery Cleaning and Disinfection Products Market
Food Safety and Standards
Pathogen Reduction Systems Market
Food Safety and Standards
Automatic Distillation Analyzer Market
Food Safety and Standards
Global Cold Chain Monitoring Market
Food Safety and Standards
GMO Labeled Food Market
Food Safety and Standards
Food Safety Software Market
Food Safety and Standards
Food Irradiation Market
Food Safety and Standards
Blockchain Food Traceability Market
Food Safety and Standards
Food and Beverage Air Filtration Market