
 Precision Food Thermometers Market | 2026-2036
Precision Food Thermometers Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Food Thermometers Market Insights
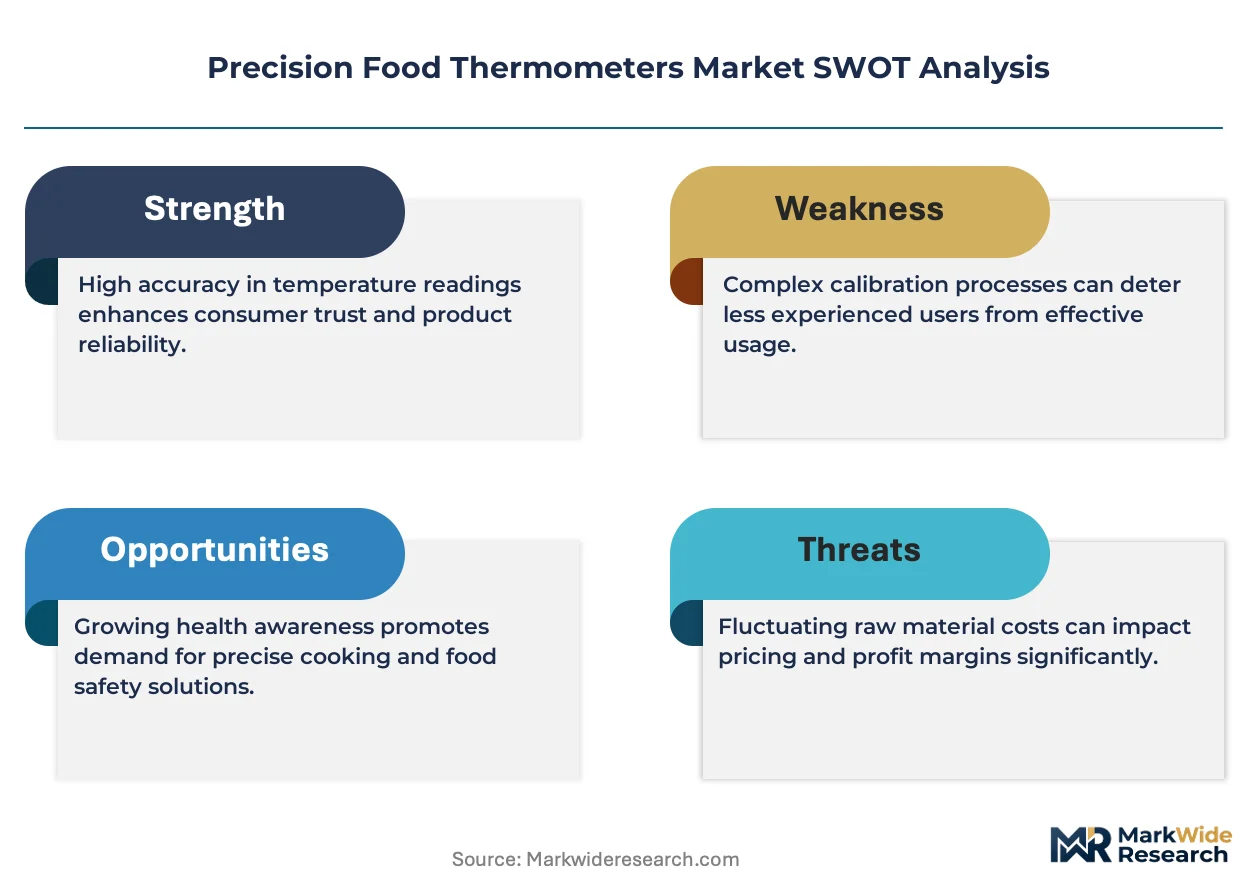
Equipment leasing and subscription-based sensor networks is narrowing the capital barrier for mid-sized food manufacturers seeking real-time temperature monitoring. Testo SE and Co. KGaA leverages its calibration-service infrastructure to anchor long-term contracts with European meat processors. ThermoWorks specializes in high-accuracy probe designs that dominate competition among artisanal bakeries and craft breweries. Hanna Instruments Inc. extends its pH-meter distribution channels to position complementary thermometer SKUs in Latin American beverage plants.
Precision food thermometers are electromechanical or semiconductor-based temperature-sensing instruments engineered to measure internal or surface temperatures of food matrices within tolerances of ±0.5°C, employing thermocouple, thermistor, or infrared detector technologies to prevent pathogen survival zones during cooking, cooling, or storage operations. Digital thermometers and smart thermometers concentrate margin pools where app-integrated logging satisfies chain-restaurant audit requirements, while infrared thermometers occupy high-throughput conveyor lines in frozen-food plants. Probe thermometers sustain volume leadership across catering services and institutional kitchens where penetration depth and response speed determine purchasing decisions.
The FDA Food Code and USDA FSIS directives mandate continuous temperature documentation in commercial food preparation, compelling equipment upgrades toward data-logging models. EFSA guidelines and EU Hygiene Regulation 852/2004 enforce comparable traceability standards across member-state food manufacturers, while China's SAMR food-safety inspections are accelerating replacement of analog bimetallic units with certified digital alternatives. Stakeholders must weigh interoperability investments against the risk that emerging wireless protocols will strand current-generation hardware before depreciation cycles complete.
Market Dynamics
Bluetooth-enabled smart probes are compressing replacement cycles for wired thermometer units across commercial food manufacturing, while HACCP documentation mandates force capital deployment toward data-logging architectures that satisfy third-party audit requirements.
Growth Catalysts
- FDA Food Code mandates:Continuous temperature documentation requirements in US commercial kitchens compel equipment upgrades toward digital logging models that eliminate paper-based recordkeeping.
- Quick-service restaurant expansion:Chain operators deploy probe networks across thousands of locations to standardize food safety protocols and reduce liability exposure from pathogen incidents.
- Thermocouple miniaturization:Advances in sensor packaging enable faster response times in high-throughput frozen-food processing lines where conveyor speed demands sub-second readings.
Market Restraints
- Semiconductor input volatility:Thermistor and thermocouple element costs fluctuate with rare earth metal pricing, squeezing margins on economy-tier digital units.
- Calibration infrastructure concentration:Accredited calibration services cluster in Germany, Japan, and the United States, creating logistics burdens for food manufacturers in secondary markets.
- Wireless protocol fragmentation:Competing Bluetooth, LoRa, and proprietary RF standards risk strandeding hardware investments before depreciation cycles complete.
Strategic Opportunities
- Latin American beverage processing:pH-meter distribution channels in Brazil and Mexico offer established pathways for complementary thermometer SKU placement in craft brewery quality labs.
- EU Green Deal alignment:Battery-efficient probe designs qualify for sustainability procurement preferences across European institutional catering contracts.
- Cloud-analytics convergence:Integration of temperature logging with predictive spoilage algorithms creates subscription revenue streams for equipment vendors serving cold-chain logistics.
Industry Challenges
- Metrology technician scarcity:Food manufacturers struggle to hire personnel capable of executing NIST-traceable calibration protocols in-house.
- Legacy system integration:Smart probes must interface with decades-old SCADA architectures in frozen-food plants, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Food Thermometers Market |
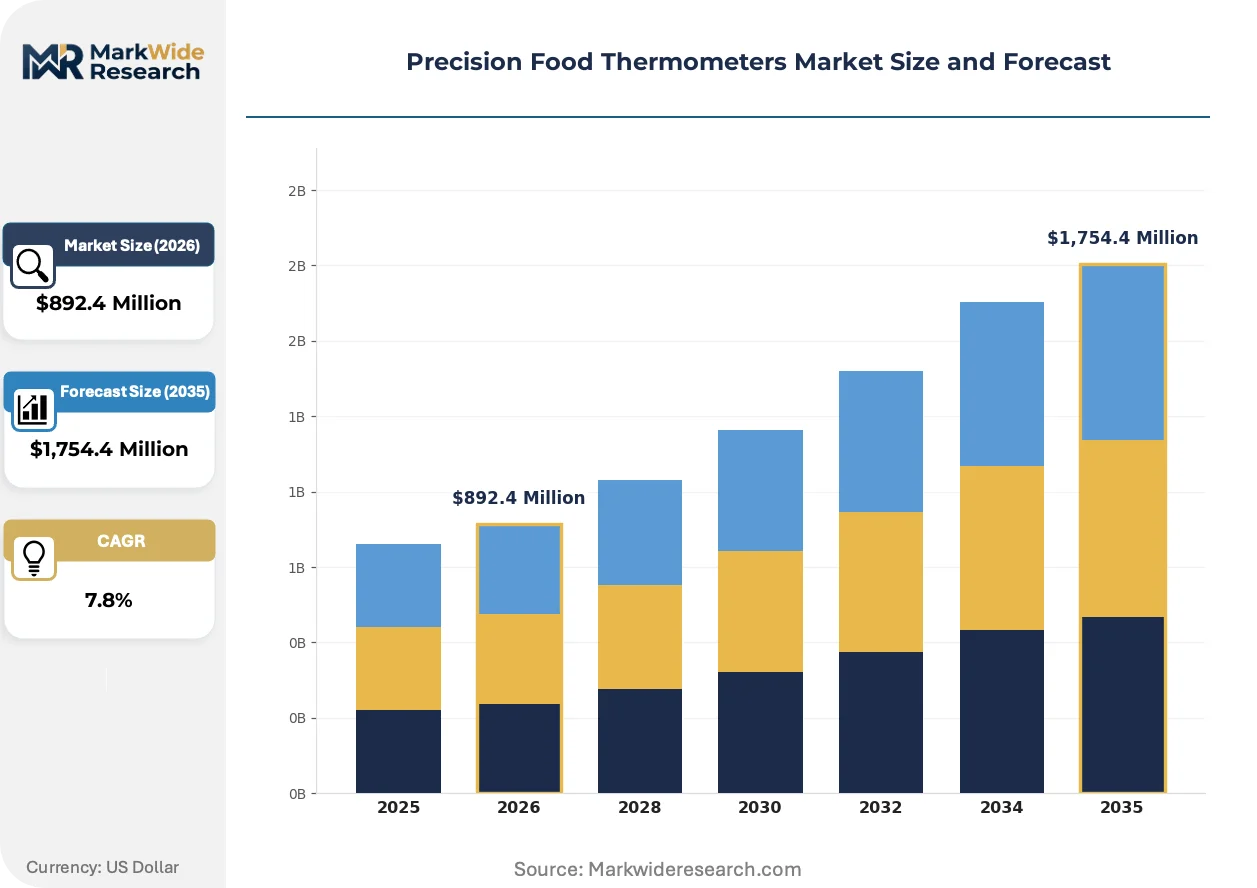
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,754.4 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Thermometers, Infrared Thermometers, Probe Thermometers, Bimetallic Thermometers End User: Restaurants, Home Cooks, Food Manufacturers, Catering Services Temperature Range: Sub-Zero, Ambient, High Heat, Industrial Connectivity: Wired, Wireless, Bluetooth, Smart Thermometers |
| Companies Covered | Antylia Scientific, Fortive Corp., Endress Hauser Group Services AG, Testo SE and Co. KGaA, Xylem Inc., ThermoWorks, Hanna Instruments Inc., CHINO Corp., B B Thermo Technik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Food Thermometers Market Trends and Innovations
Sensor fusion and wireless telemetry are collapsing the distinction between handheld inspection tools and permanent monitoring infrastructure, reshaping how food safety data flows from production line to regulatory filing.
Multi-sensor probe arrays combining temperature with humidity and pH sensing are digitizing quality assurance workflows in artisanal cheese aging facilities and craft chocolate tempering operations. Small-batch producers adopt these units to replace manual spot-checks with continuous environmental logging. The technology is digitizing compliance documentation into automated audit trails that satisfy both FDA Food Code and EFSA traceability requirements without clerical overhead.
EFSA guidelines and EU Hygiene Regulation 852/2004 now mandate machine-readable temperature records across member-state food manufacturers, accelerating replacement of analog bimetallic dial thermometers with certified digital alternatives. Industrial consequence includes forced obsolescence of equipment lacking data-export capabilities. Frozen-food processors in Germany and France respond fastest, embedding probe networks directly into conveyor control systems to trigger automatic line stops when temperature excursions occur.
Equipment-as-a-service contracting is displacing outright purchase in mid-sized meat processing operations, with vendors retaining ownership of probe hardware while charging per-inspection fees tied to HACCP documentation volume. This model spreads through US regional packing plants and Brazilian beef exporters seeking to conserve working capital. The shift concentrates vendor-buyer relationships around long-term calibration and firmware update obligations rather than transactional hardware sales.
Precision Food Thermometers Market Segmentation
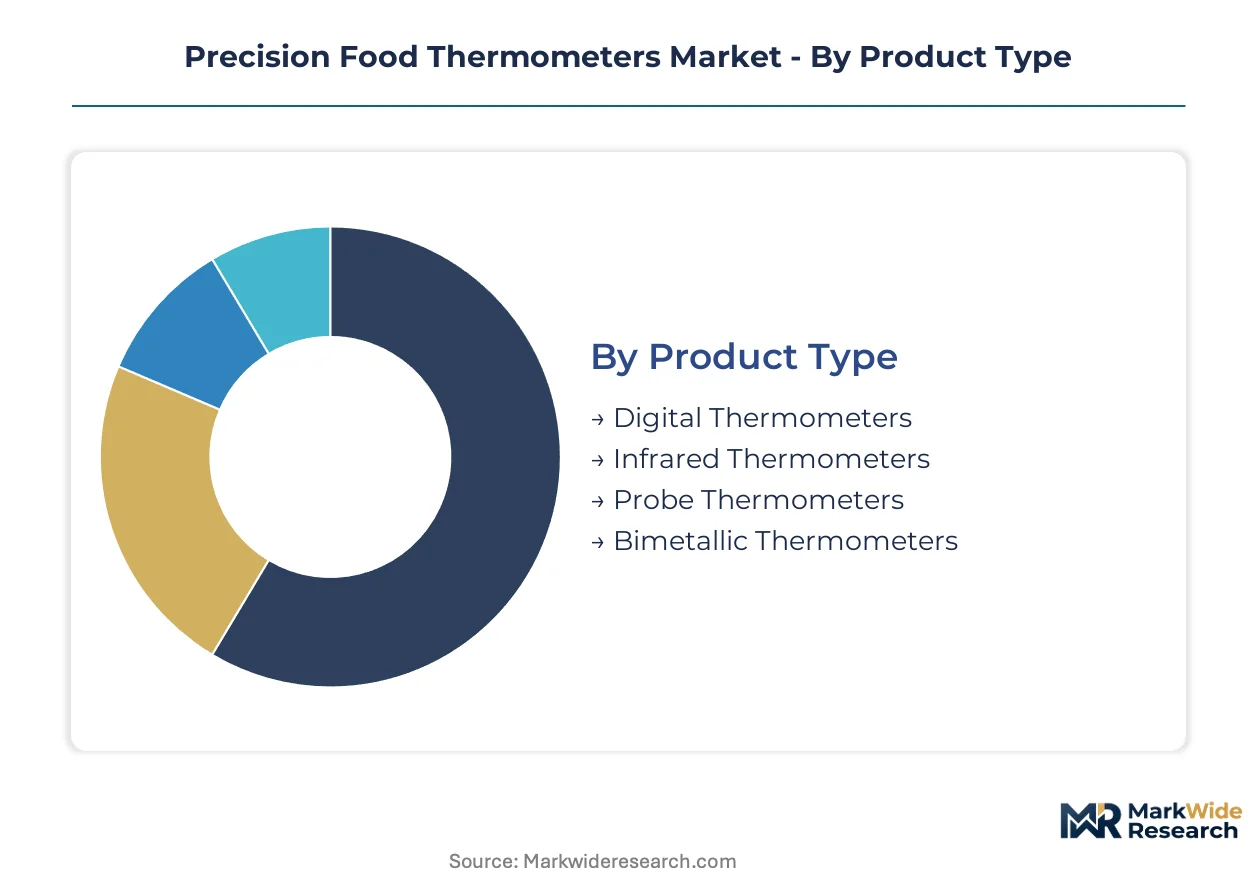
Precision food thermometer segmentation reveals divergent replacement rhythms across product architectures and connectivity tiers. Cycle times stretch from five-year depreciation for wired industrial probes to eighteen-month refresh rates for Bluetooth-enabled smart units chasing firmware obsolescence.
Product Type:
Digital thermometers turn over fastest as app-integrated logging becomes mandatory for chain-restaurant audit trails, while bimetallic units persist longest in legacy institutional kitchens resisting capital expenditure.
- Digital Thermometers:Semiconductor-based units with LCD readouts and data-logging memory satisfy FDA Food Code continuous documentation mandates. Quick-service restaurant chains deploy these across thousands of locations to standardize HACCP compliance and eliminate paper recordkeeping liability gaps.
- Probe Thermometers:Penetration-style sensors with thermocouple or thermistor elements deliver ±0.5°C accuracy for internal food matrices. Catering services and institutional kitchens specify these for response speed and durability under high-frequency sanitization cycles.
- Infrared Thermometers:Non-contact surface temperature measurement via thermal radiation detection dominates frozen-food plant conveyor lines.
- Bimetallic Thermometers:Analog dial mechanisms with coiled metal strips persist in budget-constrained operations despite lacking data-export capabilities.
Probe thermometers dominate installed base. Digital thermometers are where expansion concentrates.
End User:
Food manufacturers absorb the highest per-site equipment spend as automated production lines demand networked sensor arrays, while home cooks drive volume through e-commerce impulse purchases of single-unit smart probes.
- Restaurants:Full-service and quick-service operators deploy probe networks to satisfy third-party audit requirements and reduce pathogen incident liability. HACCP documentation mandates force capital deployment toward data-logging architectures with cloud backup.
- Food Manufacturers:Industrial-scale operations embed thermocouple arrays directly into SCADA-controlled production lines. Frozen-food processors in Germany and the United States trigger automatic line stops when temperature excursions breach critical control points.
- Catering Services:Mobile food operations prioritize handheld durability and rapid sanitization compatibility.
- Home Cooks:Consumer segment purchases Bluetooth-enabled smart probes through retail and direct-to-consumer channels for precision cooking applications.
Food manufacturers command highest average selling prices. Restaurants are climbing the fastest in unit deployment.
Temperature Range:
High-heat specifications command premium pricing for foundry-grade thermocouple materials, while sub-zero applications face compressed margins from commodity sensor proliferation in cold-chain logistics.
- High Heat:Thermocouple probes rated above 300°C serve industrial frying operations and oven calibration. Artisanal bakeries and craft breweries specify these for caramelization and Maillard reaction control.
- Sub-Zero:Cryogenic-rated sensors monitor blast freezing and deep cold storage. Frozen-food plants in Japan and the United States deploy these across high-throughput conveyor lines where sub-second readings prevent thermal drift.
- Ambient:Standard-range units cover refrigeration and room-temperature holding applications.
- Industrial:Extended-range probes withstand steam injection and pressure-cooking environments.
Ambient-range units dominate installed base. Sub-zero sensors are gaining share fastest from cold-chain automation.
Connectivity:
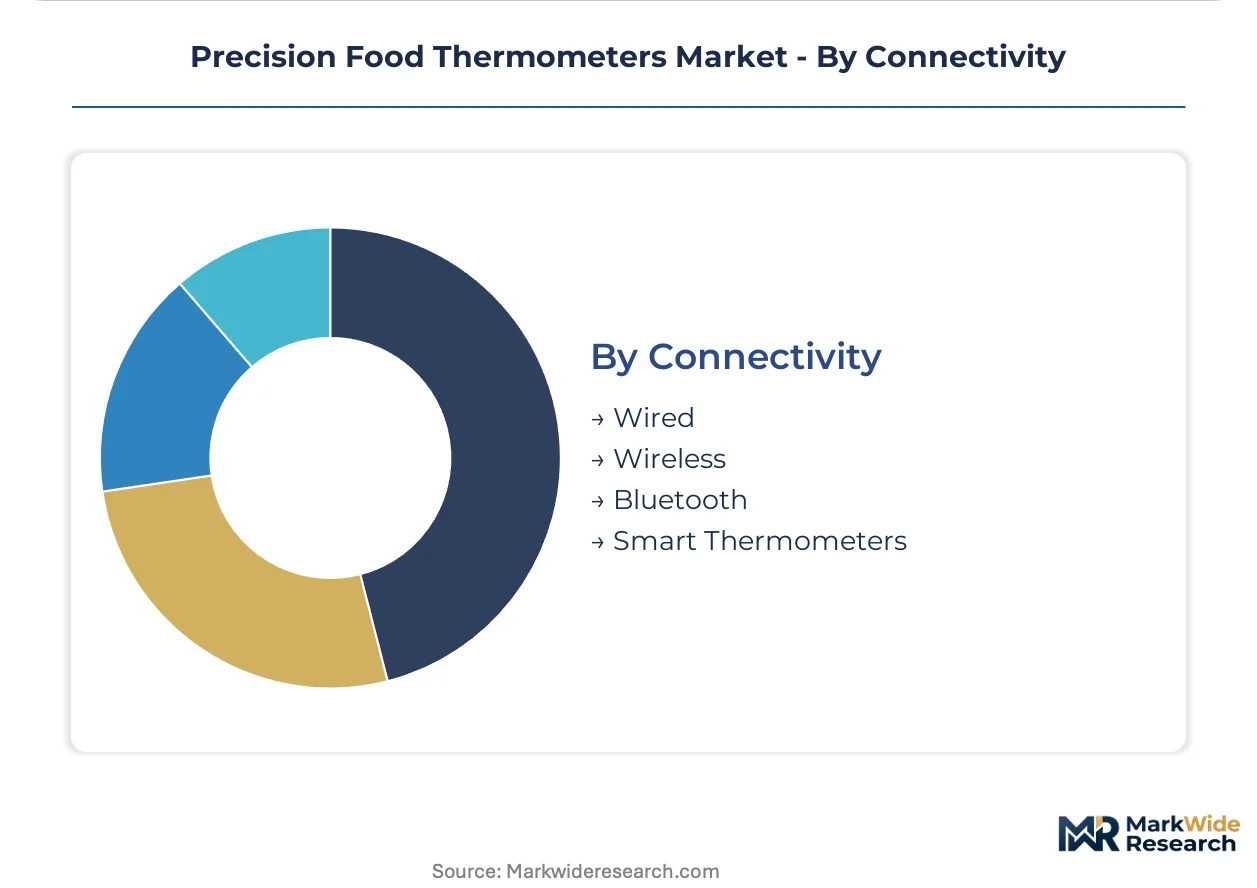
Wireless protocols fragment procurement decisions as food manufacturers weigh interoperability investments against stranded hardware risk before depreciation cycles complete.
- Smart Thermometers:App-integrated probes with cloud analytics and predictive spoilage algorithms create subscription revenue streams. Equipment-as-a-service contracting spreads through US regional meat packing plants seeking working capital conservation.
- Bluetooth:Short-range wireless units displace wired connections in commercial kitchens and small-batch production. EFSA machine-readable record mandates accelerate replacement of analog alternatives across EU member-state food manufacturers.
- Wired:Hardwired probes persist in legacy SCADA architectures requiring custom middleware for smart probe integration.
- Wireless:LoRa and proprietary RF protocols serve extended-range applications in warehouse-scale cold storage.
Wired connections dominate legacy installed base. Smart thermometers are where vendor business models concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented precision food thermometer manufacturing clusters in Germany, Japan, and the United States supply equipment to food processing hubs across Latin America and Southeast Asia. Import dependence for calibration services and certified sensor elements concentrates value capture in these three origin markets. Regional regulatory divergence around data-logging mandates is accelerating replacement cycles in some jurisdictions while prolonging analog equipment lifespans in others.
United States
Quick-service restaurant chains deploy probe networks across thousands of locations to standardize HACCP compliance and eliminate paper-based liability gaps. FDA Food Code mandates for continuous temperature documentation compel equipment upgrades toward digital logging models. Chicago and Dallas-Fort Worth metropolitan areas host dense concentrations of meat processing operations embedding thermocouple arrays into automated production lines.
Germany
Frozen-food processors in Bavaria and North Rhine-Westphalia embed probe networks directly into conveyor control systems to trigger automatic line stops during temperature excursions. EFSA guidelines and EU Hygiene Regulation 852/2004 enforce machine-readable record standards that accelerate replacement of analog bimetallic units. Stuttgart's precision instrumentation cluster anchors calibration-service infrastructure for European meat processors seeking NIST-traceable protocols.
Japan
High-throughput frozen-food plants in Osaka and Nagoya deploy cryogenic-rated sensors across conveyor lines where sub-second readings prevent thermal drift. METI industrial standards for food manufacturing equipment interoperability shape procurement specifications for smart probe integration. Tokyo-Yokohama corridor concentration of sensor manufacturers supplies thermocouple miniaturization advances to domestic and export markets.
Brazil
Beef exporters in São Paulo and Minas Gerais states adopt equipment-as-a-service contracting to conserve working capital while satisfying international audit requirements. ANVISA food safety inspections accelerate replacement of uncalibrated analog units with certified digital alternatives. Craft brewery quality labs in Rio Grande do Sul create demand pathways for pH-meter distribution channels extending into complementary thermometer SKUs.
China
SAMR food-safety inspections in Yangtze River Delta processing hubs accelerate replacement of analog bimetallic thermometers with certified digital alternatives. Domestic manufacturers in Shenzhen and Dongguan supply Bluetooth-enabled smart probes displacing wired connections in commercial kitchens. Cold-chain logistics automation in Pearl River Delta warehouse complexes drives fastest share gains for sub-zero sensor specifications.
Precision Food Thermometers Market Competitive Landscape
On the supply side, the industry is consolidating around calibration-service anchoring and long-term contract structures that displace transactional hardware sales. Three strategic archetypes dominate: European instrumentation conglomerates leveraging metrology infrastructure, specialized high-accuracy probe designers serving artisanal segments, and diversified sensor manufacturers extending pH-meter distribution into complementary temperature SKUs. Competitive moves concentrate on strategic partnerships for cloud-analytics integration and geographic expansion through equipment-as-a-service contracting models.
Among German-based precision instrumentation specialists, Testo SE and Co. KGaA and Endress Hauser Group Services AG occupy positions anchored by calibration-service infrastructure and SCADA integration capabilities. Testo exemplifies the European archetype leveraging metrology networks for long-term contract retention, while Endress Hauser represents industrial automation integration expertise. ThermoWorks, identifiable by its functional naming convention, sits within the high-accuracy specialist tier serving craft production segments. These three entities illustrate the competitive structure without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Antylia Scientific |
| Fortive Corp. |
| Endress Hauser Group Services AG |
| Testo SE and Co. KGaA |
| Xylem Inc. |
| ThermoWorks |
| Hanna Instruments Inc. |
| CHINO Corp. |
| B B Thermo Technik GmbH |
| Others |
Pricing and Supply Chain Analysis
Rare earth metal price volatility in thermistor and thermocouple element sourcing determines both the spread between economy-tier and certified digital units and the geographic clustering of precision thermometer manufacturing. Semiconductor input costs fluctuate with dysprosium and neodymium spot markets, squeezing margins on entry-level digital thermometers while concentrating premium pricing power with vendors holding backward-integrated sensor foundries.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command spreads based on NIST-traceable calibration certificates and FDA Food Code compliance documentation, while economy units face cost compression from commodity sensor proliferation. Price differentiation hinges on certification grade and after-sales service bundling. Margins are tightening due to rare earth metal input volatility. Quick-service restaurant chains exhibit lowest price sensitivity given liability exposure from pathogen incidents, while institutional catering services in secondary markets drive hardest bargain hunting.
Supply Chain Analysis
Contract manufacturing for precision thermometer assemblies concentrates with electronics manufacturing services in Shenzhen, Dongguan, and Taipei holding dedicated capacity for sensor packaging and calibration fixture production. Thermocouple wire drawing feeds from specialty metal processors in Japan and Germany, while semiconductor die sourcing rests on foundry output from Taiwan and South Korea. Single-source vulnerability in rare earth element refining creates tariff exposure for vendors without diversified magnet alloy suppliers. Distribution runs through instrumentation distributors anchoring relationships with meat processors and frozen-food plant engineering departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NIST-traceable calibration capability scarcity separates vendors capable of long-term contract retention from commodity hardware suppliers facing churn. The gap between accredited metrology infrastructure and food manufacturer demand for in-house technician deployment creates sustainable competitive moats.
For Market Incumbents: Harden calibration-service infrastructure as the primary retention mechanism against equipment-as-a-service entrants. Anchor long-term contracts with European meat processors through firmware update obligations and SCADA integration capabilities. Defend against Bluetooth-enabled smart probe displacement by embedding predictive spoilage algorithms into subscription tiers that raise switching costs. For New Entrants and Emerging Players: Mid-market Brazilian beef exporters and Mexican craft brewery quality labs represent the most penetrable entry points for complementary thermometer SKU placement through established pH-meter distribution channels. Latin American beverage processing operations seek working capital conservation through per-inspection contracting models rather than capital expenditure. Target ANVISA inspection acceleration as the regulatory trigger for analog-to-digital replacement cycles. For Investors and Strategic Acquirers: The market sits at a protocol-consolidation phase that favors vendors with calibration-service density over pure hardware manufacturers. Long-term viability across the analysis window rests on cloud-analytics convergence and predictive spoilage algorithm integration. Target acquisition archetypes include regional calibration-service providers with NIST-traceable protocols and middleware developers bridging smart probes to legacy SCADA architectures. Watch Bluetooth SIG standardization progress as the inflection signal for stranded hardware risk resolution.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration-Service Infrastructure Expansion | NIST-traceable protocols anchor multi-year contracts with FDA-inspected meat processors. |
| Cloud-Analytics Platform Integration | Predictive spoilage algorithms create recurring subscription revenue from cold-chain logistics. |
| Equipment-as-a-Service Contracting | Per-inspection fees conserve working capital for Brazilian beef exporters facing ANVISA audits. |
| Legacy SCADA Middleware Development | Smart probe integration with decades-old frozen-food plant architectures requires custom engineering. |
| EU Green Deal Battery-Efficient Design | Sustainability procurement preferences favor European institutional catering contract winners. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with food safety officers, plant engineers at frozen-food processors, calibration laboratory managers, and quick-service restaurant operations directors; alongside secondary validation through FDA Food Code enforcement records, EFSA guidance documents, USDA FSIS inspection data, and customs trade statistics for thermocouple and thermistor element flows. Bottom-up unit deployment estimates across quick-service restaurant chains, meat processing operations, and craft production facilities were triangulated against top-down market value reconstruction from vendor revenue disclosures and distributor channel checks.
Forecast inputs span product architecture replacement rhythms from eighteen-month smart probe cycles to five-year wired industrial depreciation, connectivity protocol adoption curves, and regulatory mandate enforcement intensity across FDA, EFSA, and SAMR jurisdictions. Segmentation dimensions modeled include thermometer product type, end-user industry vertical, temperature range specification, and connectivity tier. CAGRs were derived from logistic diffusion curves fitted to digital logging mandate penetration rates and equipment-as-a-service contracting uptake patterns in regional meat processing hubs.
Macroeconomic conditions sit as an overlay; deviation in rare earth metal pricing, cold-chain logistics automation capital expenditure cycles, or HACCP audit enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding Bluetooth protocol standardization timelines and calibration-service infrastructure expansion rates. Quarterly review of FDA Food Code adoption by state health departments and EFSA machine-readable record mandate compliance deadlines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety and Standards
Cold-Chain Friendly Post-Harvest Sanitizing Mist Market
Food Safety and Standards
Bakery Cleaning and Disinfection Products Market
Food Safety and Standards
Global Cold Chain Monitoring Market
Food Safety and Standards
Food and Beverage Air Filtration Market
Food Safety and Standards
Bar Inspection System Market
Food Safety and Standards
Food Irradiation Market
Food Safety and Standards
Quality Assurance and Quality Control Market
Food Safety and Standards
GMO Labeled Food Market
Food Safety and Standards
Food Grade Biofilms Market
Food Safety and Standards
Natural Antimicrobials Market
Food Safety and Standards
Food Certification Market
Food Safety and Standards
Food Safety Software Market
Food Safety and Standards
Food and Beverage Industrial Disinfection and Cleaning Market
Food Safety and Standards
Testing, Inspection, and Certification Market
Food Safety and Standards
Pathogen Reduction Systems Market
Food Safety and Standards
Food Authenticity Market