
 Automatic Distillation Analyzer Market | 2026-2036
Automatic Distillation Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Distillation Analyzer Market Outlook
Petrochemical instrumentation talent is reorganizing around mechatronics and software integration, forcing vendors to recalibrate hiring pipelines and training curricula. PAC LP leverages its Houston-based engineering base to sustain aftermarket service density across North American refineries. Anton Paar GmbH anchors European demand through precision optical measurement systems calibrated to EN ISO 3405. Grabner Instruments specializes in portable analyzer configurations that dominate field-testing deployments at pipeline terminals and storage facilities.
An automatic distillation analyzer measures the boiling range of petroleum products, solvents, and chemicals through controlled vaporization and condensation cycles, typically operating across temperature ranges from ambient to 400°C with resolution to 0.1°C. Laboratory analyzers occupy the dominant revenue position due to their integration with centralized quality control workflows in large refineries. Portable analyzers represent the fastest-expanding configuration as midstream operators prioritize at-site fuel certification at remote storage terminals. Online analyzers command premium positioning through continuous process integration, though deployment complexity limits penetration outside integrated petrochemical complexes.
ASTM International governs precision requirements through D86 and D1160 protocols that directly shape analyzer calibration standards and certification costs. The EPA enforces fuel volatility limits under Clean Air Act mandates, compelling gasoline blenders to maintain distillation curve documentation for regulatory audit trails. California Air Resources Board imposes additional Reid Vapor Pressure constraints that exceed federal baselines, creating specialized demand in that state. Stakeholders must weigh capital deployment toward online process integration against the flexibility of portable and laboratory platforms as fuel specifications continue tightening.
Market Dynamics
Refinery automation mandates under EPA Tier 3 sulfur specifications are compressing manual distillation workflows, forcing capital redeployment toward ASTM D86-compliant analyzers integrated with real-time quality control systems.
Growth Catalysts
- EPA Tier 3 sulfur limits:Gasoline blenders must maintain continuous distillation curve documentation for regulatory audit trails, accelerating analyzer procurement across downstream processing clusters.
- Midstream terminal expansion:Pipeline operators at remote storage facilities require portable certification capabilities to verify fuel volatility before custody transfer.
- Optical sensor miniaturization:Advances in precision photonics enable field-deployable units matching laboratory-grade resolution without climate-controlled infrastructure.
Market Restraints
- Specialized quartz glass supply:Vaporization chamber components depend on high-purity borosilicate sourced from concentrated European suppliers, exposing lead times to geopolitical friction.
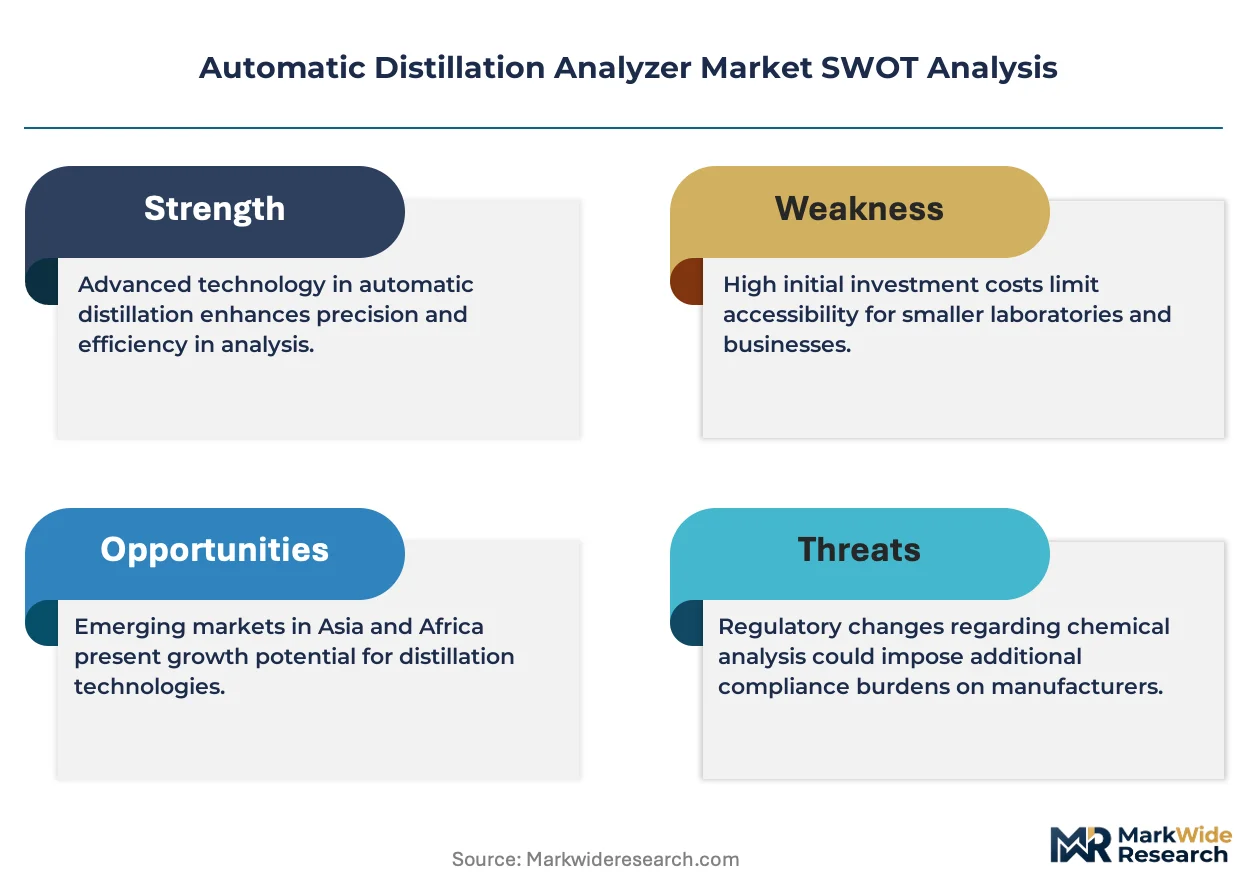
- ASTM D86 calibration complexity:Certification protocols require reference standards traceable to NIST, creating recurring compliance costs that burden smaller independent refiners.
- Manual method persistence:Legacy distillation setups in aging Midwest facilities resist replacement due to embedded maintenance workflows and union operator certification.
Strategic Opportunities
- California CARB vapor pressure rules:Reid Vapor Pressure constraints exceeding federal baselines create specialized demand for enhanced-resolution analyzers in West Coast blending operations.
- Biofuel distillation monitoring:Renewable diesel and sustainable aviation fuel producers need modified temperature protocols for oxygenate-laden feedstocks, opening application-specific configurations.
- Cloud-connected diagnostics:Predictive maintenance platforms integrating analyzer telemetry with refinery distributed control systems enable subscription-based service models.
Industry Challenges
- Mechatronics talent scarcity:Vendors struggle to hire engineers fluent in both precision thermal systems and industrial software integration, elongating product development cycles.
- Legacy DCS interoperability:Online analyzer deployment requires custom protocol bridges to connect with Honeywell, Yokogawa, or Emerson control architectures, complicating commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Distillation Analyzer Market |
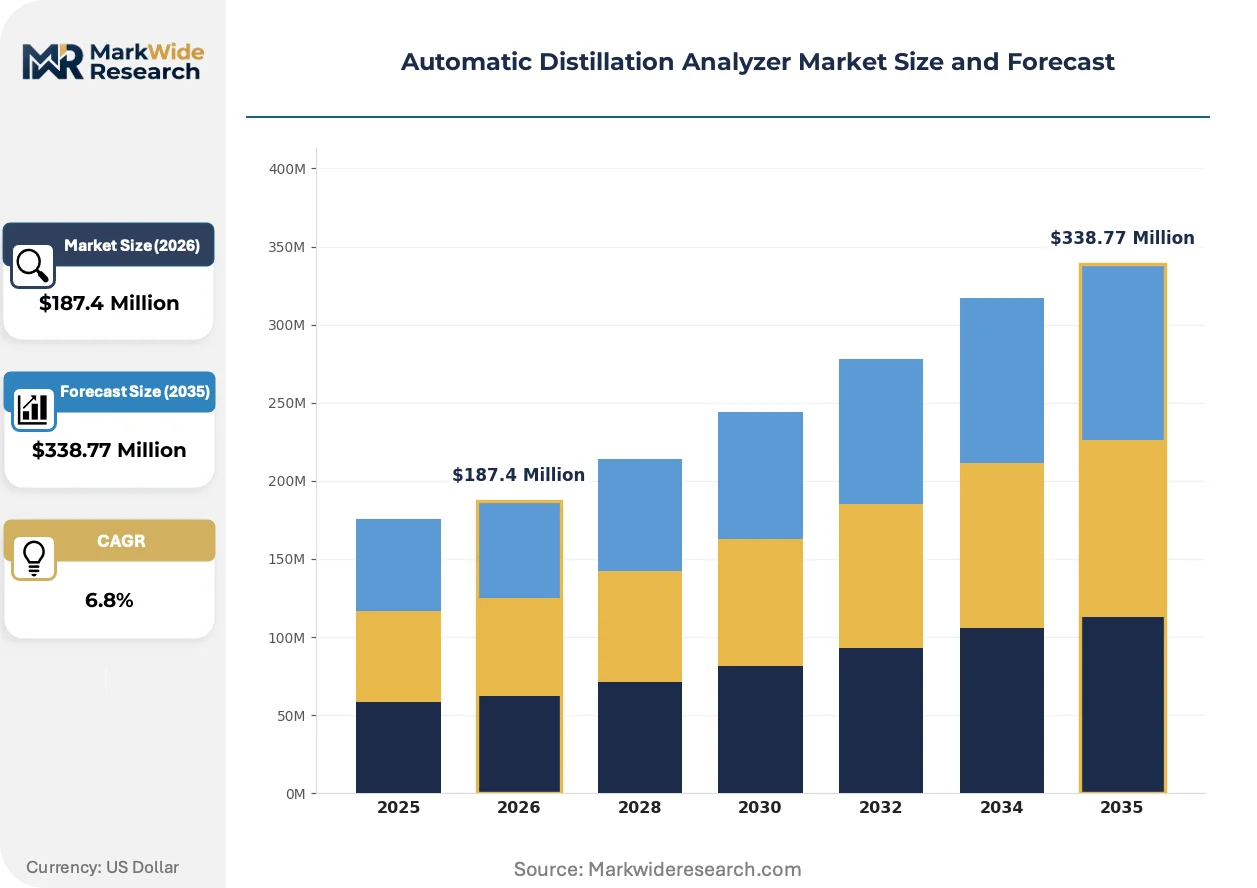
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laboratory Analyzers, Portable Analyzers, Online Analyzers, Automated Workstations End User: Petrochemical Industry, Chemical Manufacturing, Research Laboratories, Quality Control Laboratories Technology: Gas Chromatography, Infrared Spectroscopy, Optical Measurement, Thermal Conductivity Application: Fuel Analysis, Water Quality Testing, Chemical Composition Analysis, Solvent Purity Testing |
| Companies Covered | PAC LP, Koehler Instrument Company, Grabner Instruments, Tanaka Scientific Ltd., Anton Paar GmbH, LabTech S.r.l., Normalab France S.A.S., Petrolab Company, Estanit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Distillation Analyzer Market Strategic Shifts
Analyzer architectures are converging around modular sensor platforms that separate measurement hardware from data processing layers, enabling faster firmware updates and remote calibration adjustments without field service visits.
Micro-electromechanical systems are displacing traditional capillary-based vapor detection in next-generation portable units. Field-testing contractors at Gulf Coast pipeline terminals now specify MEMS-equipped analyzers for rapid Reid Vapor Pressure verification. The technology is displacing incumbent thermal conductivity detectors by delivering comparable precision at one-third the power draw, extending battery life for remote deployments.
REACH chemical registration requirements in Europe are restricting certain heat-transfer fluids used in analyzer thermal baths. Equipment vendors serving EU refineries must reformulate working fluids to maintain EN ISO 3405 compliance without compromising temperature uniformity. German and Dutch blending facilities report extended procurement cycles as suppliers recertify modified instrument configurations.
After-sales service unbundling is fragmenting traditional maintenance contracts. Large Texas refineries now procure analyzers and calibration support through separate RFP processes, pressuring vendors to disclose hourly labor rates and spare parts markups. This purchasing pattern is most pronounced among integrated operators with centralized instrumentation procurement functions, who negotiate multi-site service agreements independent of initial capital equipment awards.
Automatic Distillation Analyzer Market Segmentation
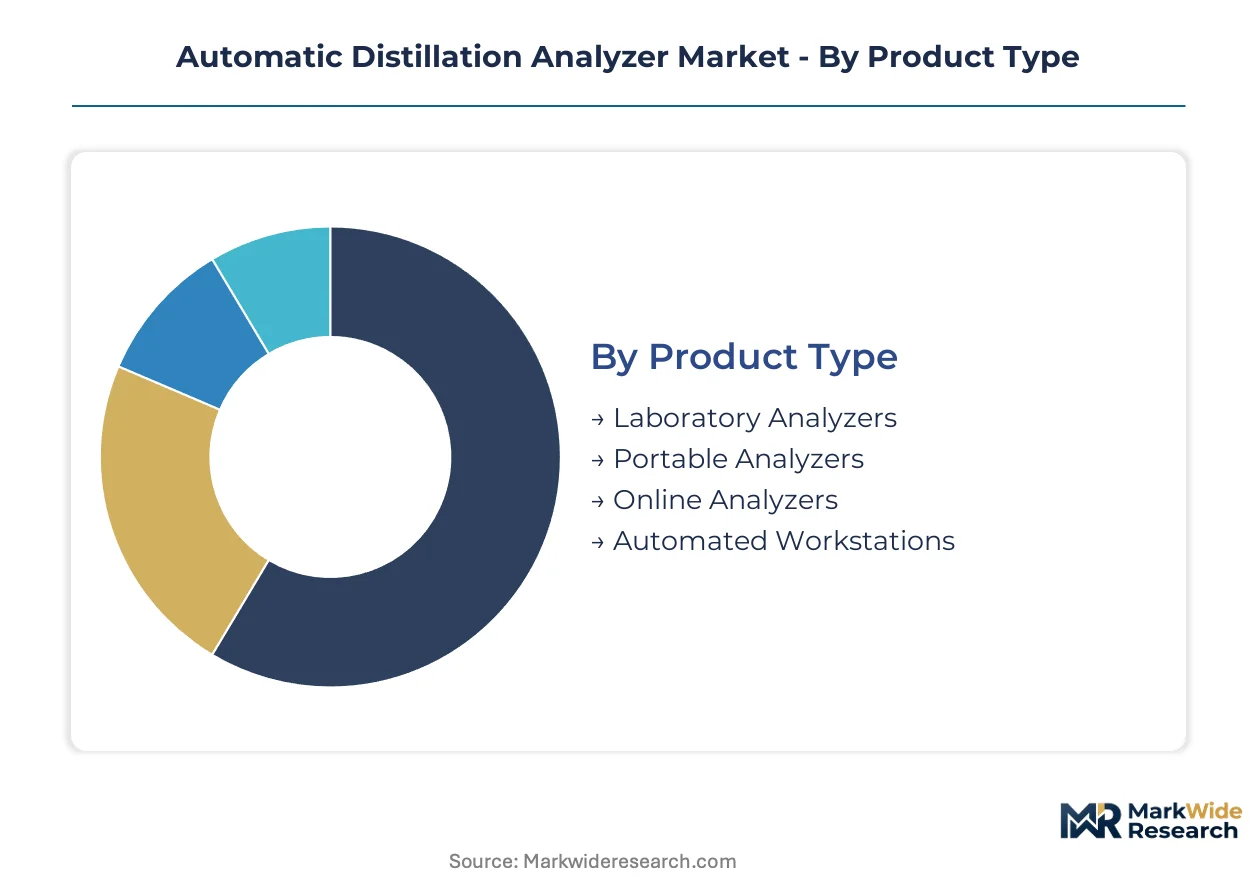
Analyzer procurement patterns diverge sharply across operating environments, with refinery-scale installations demanding continuous process integration while field operations prioritize rapid deployment over laboratory precision. Segmentation reveals where capital concentrates and which configurations face displacement from emerging sensor architectures.
Product Type:
Substitution pressure weighs heaviest on laboratory analyzers as optical miniaturization enables portable units to match historical resolution benchmarks without climate-controlled infrastructure.
- Laboratory Analyzers:These systems integrate with centralized quality control workflows in large refineries, operating across ambient-to-400°C ranges with 0.1°C resolution. Demand concentrates in Texas and Louisiana downstream clusters where ASTM D86 compliance mandates continuous documentation. Gulf Coast facilities favor these units for their integration with Honeywell and Yokogawa distributed control systems.
- Portable Analyzers:Pipeline terminals and remote storage facilities specify these configurations for at-site fuel certification before custody transfer. Midstream operators at Gulf Coast facilities are displacing laboratory workflows with MEMS-equipped field units that deliver comparable precision at one-third power draw.
- Online Analyzers:Continuous process integration commands premium positioning despite deployment complexity limiting penetration outside integrated petrochemical complexes.
- Automated Workstations:Multi-sample batch processing systems serve high-throughput quality control laboratories with robotic sample handling and automated report generation.
Laboratory analyzers retain volume leadership; portable configurations hold the steepest expansion curve.
End User:
Cost tier stratification separates integrated refinery operators from independent blenders and contract testing services, with capital intensity determining analyzer sophistication.
- Petrochemical Industry:Integrated refineries and fuel blenders deploy the full spectrum of analyzer configurations to meet EPA Tier 3 sulfur documentation requirements. Texas and California facilities lead procurement volume due to processing scale and specialized CARB vapor pressure rules.
- Chemical Manufacturing:Solvent producers and specialty chemical operations require modified temperature protocols for oxygenate-laden feedstocks, creating demand for application-specific instrument configurations.
- Research Laboratories:Academic and government facilities prioritize flexibility over throughput, favoring modular platforms supporting multiple ASTM and EN ISO methods.
- Quality Control Laboratories:Third-party testing services unbundle procurement and calibration support through separate RFP processes, pressuring vendors to disclose hourly labor rates.
Petrochemical industry accounts for dominant procurement volume; quality control laboratories are gaining share fastest as outsourcing expands.
Technology:
Technology maturity curves determine where precision photonics displaces legacy detection methods, with power efficiency and miniaturization driving substitution economics.
- Gas Chromatography:Established separation technology maintains installed base in central laboratories despite longer analysis cycles compared to optical alternatives.
- Infrared Spectroscopy:Non-destructive molecular identification enables rapid fuel adulteration screening at pipeline terminals.
- Optical Measurement:Precision photonics systems calibrated to EN ISO 3405 anchor European demand, with Anton Paar GmbH configurations dominating German and Dutch blending facilities.
- Thermal Conductivity:Legacy detection method faces displacement by MEMS architectures delivering comparable resolution with extended battery life for remote deployments.
Optical measurement retains the largest installed base; MEMS-based thermal detection is climbing the fastest as field specifications tighten.
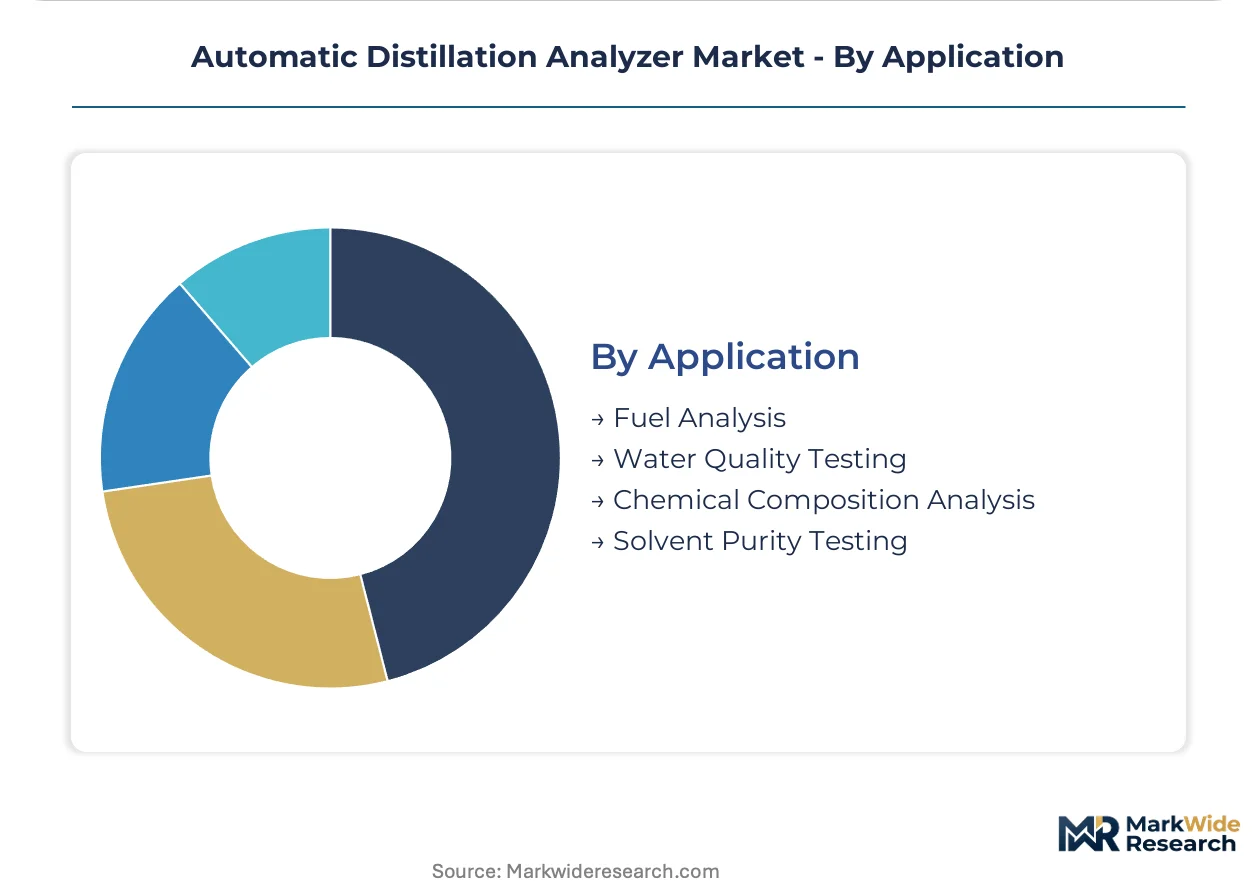
Application:
Application segmentation tracks regulatory enforcement intensity, with fuel volatility documentation commanding capital priority over environmental testing.
- Fuel Analysis:Gasoline and diesel distillation curve documentation dominates procurement, driven by EPA Clean Air Act mandates and California CARB Reid Vapor Pressure constraints exceeding federal baselines.
- Water Quality Testing:Environmental compliance monitoring applies analyzer technology to volatile organic compound detection in wastewater streams.
- Chemical Composition Analysis:Petrochemical feedstock characterization supports process optimization and product certification across downstream operations.
- Solvent Purity Testing:Pharmaceutical and electronics manufacturing require high-resolution boiling range verification for process solvent grades.
Fuel analysis commands dominant capital allocation; biofuel distillation monitoring for renewable diesel and sustainable aviation fuel is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in North American downstream clusters while European vendors absorb REACH compliance costs that compress margins. Texas and Louisiana refineries command volume discounts on ASTM D86-certified systems that German and Dutch blenders cannot match under EN ISO 3405 protocols.
United States
Gulf Coast refineries in Texas and Louisiana drive procurement volume for laboratory and online analyzer configurations. EPA Tier 3 sulfur documentation mandates compel continuous distillation curve monitoring at integrated downstream facilities. Houston hosts PAC LP's engineering base, sustaining aftermarket service density across regional petrochemical complexes.
Germany
Precision optical measurement systems anchor European demand, with EN ISO 3405 calibration requirements shaping vendor certification cycles. REACH chemical registration restricts certain heat-transfer fluids in analyzer thermal baths, forcing equipment recertification. The Rhine-Ruhr industrial corridor reports extended procurement timelines as suppliers validate modified instrument configurations.
China
State-owned refinery operators accelerate automation of manual distillation workflows to meet tightening fuel quality standards under MIIT supervision. GB standards for petroleum product testing converge with ASTM protocols, simplifying import substitution for domestic analyzer manufacturers. Yangtze River Delta petrochemical clusters prioritize online analyzer integration with Honeywell and Yokogawa distributed control systems.
Japan
METI industrial standards for petroleum product characterization sustain demand for high-resolution laboratory analyzers. Specialty chemical manufacturers in the Kansai region require modified temperature protocols for oxygenate-laden feedstocks. Chubu-area refineries balance capital deployment between portable field units and centralized quality control infrastructure.
India
Bureau of Indian Standards certification requirements for fuel volatility testing create compliance-driven procurement at public sector refineries. Reliance Industries and Indian Oil Corporation expand quality control laboratory capacity at Gujarat and Maharashtra processing sites. PLI scheme incentives for petrochemical equipment manufacturing attract joint venture proposals from European analyzer vendors.
Automatic Distillation Analyzer Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with precision optical specialists commanding premium positioning while scale fabricators compete on unit economics. The vendor base organizes around three strategic tiers: integrated instrumentation conglomerates with multi-product portfolios, specialized analyzer firms focused on distillation and volatility measurement, and regional equipment fabricators serving emerging market price sensitivity. Dominant competitive moves include geographic expansion through local assembly partnerships and technology licensing agreements that accelerate regulatory certification in new jurisdictions.
Among precision measurement specialists, Anton Paar GmbH and Grabner Instruments exemplify divergent strategic positioning within European quality control instrumentation. PAC LP anchors North American aftermarket service density from its Houston operational base. Koehler Instrument Company occupies a position bridging laboratory and field-deployable configurations for midstream fuel certification workflows.
| Leading Market Players |
|---|
| PAC LP |
| Koehler Instrument Company |
| Grabner Instruments |
| Tanaka Scientific Ltd. |
| Anton Paar GmbH |
| LabTech S.r.l. |
| Normalab France S.A.S. |
| Petrolab Company |
| Estanit |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at European borosilicate glass foundries shapes price floors for vaporization chamber components, concentrating supply leverage among German and Dutch thermal bath manufacturers while compressing margins for analyzer vendors absorbing REACH recertification costs.
Pricing Analysis
The customization-premium spread separates ASTM D86-certified laboratory systems from portable field units, with configured-to-order pricing commanding substantial premiums over standard configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in the mid-tier is intensifying because Texas refineries now unbundle procurement and calibration support through separate RFP processes. Independent Midwest refiners exhibit highest price sensitivity due to embedded legacy maintenance workflows, while integrated Gulf Coast operators prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies dominate analyzer assembly, though strategic stockpiling of high-purity quartz glass components buffers against European supply disruption. Manufacturing concentrates in Germany, the United States, and China, with vaporization chambers drawing from concentrated borosilicate suppliers in the Rhine-Ruhr corridor. Single-source vulnerability in specialized optical sensor substrates exposes lead times to geopolitical friction. Distribution runs through authorized service networks anchored by Houston-based engineering hubs serving North American refineries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in biofuel distillation monitoring, where renewable diesel and sustainable aviation fuel producers demand modified temperature protocols that established vendors have not fully addressed.
For Market Incumbents: Shield installed base revenue by embedding cloud-connected diagnostics into existing analyzer fleets, converting capital equipment relationships into subscription-based service models. Deepen backward integration into precision photonics manufacturing to reduce exposure to European borosilicate supply constraints. Prioritize certification investment for oxygenate-laden feedstock protocols before specialty chemical entrants capture renewable fuel workflows.
For New Entrants and Emerging Players: Anchor in California CARB compliance workflows, where Reid Vapor Pressure constraints exceeding federal baselines create specialized demand for enhanced-resolution portable units. The most penetrable segment lies in midstream terminal field-testing, where MEMS-equipped analyzers displace laboratory workflows. Pursue go-to-market partnerships with pipeline operators seeking rapid custody transfer certification without climate-controlled infrastructure.
For Investors and Strategic Acquirers: Precision optical measurement specialists with EN ISO 3405 calibration capabilities represent the most defensible acquisition archetype, given regulatory moats around European fuel testing protocols. Long-term viability hinges on software integration competence bridging legacy DCS architectures. Watch for inflection when biofuel distillation monitoring procurement crosses threshold share of total analyzer demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Diagnostics Platform | Enables predictive maintenance subscriptions integrating analyzer telemetry with Honeywell and Yokogawa DCS architectures. |
| MEMS Sensor Architecture Transition | Delivers laboratory-grade resolution at one-third power draw, extending battery life for remote Gulf Coast deployments. |
| REACH-Compliant Thermal Bath Reformulation | Maintains EN ISO 3405 temperature uniformity while satisfying ECHA chemical registration restrictions on heat-transfer fluids. |
| California CARB Certification Investment | Captures specialized demand from West Coast blenders facing Reid Vapor Pressure constraints exceeding EPA Tier 3 baselines. |
| Biofuel Protocol Development Partnership | Opens application-specific configurations for renewable diesel and sustainable aviation fuel oxygenate-laden feedstocks. |
Study Parameters
Desk research of ASTM International protocol documentation, EPA regulatory filings, and SEC 10-K instrument manufacturer disclosures preceded structured interviews with refinery quality control managers, petrochemical procurement leads, and aftermarket service heads. Primary fieldwork with laboratory instrumentation directors and midstream terminal operators combined with secondary validation against customs trade data and ACC downstream processing reports. Bottom-up unit shipment estimates triangulated against top-down capital expenditure patterns across Texas, Louisiana, and California refining clusters.
Variance decomposition across product type, end user, technology, and application dimensions structured the analytical framework throughout the forecast period. CAGRs derived from regression analysis of historical procurement cycles against regulatory enforcement intensity, particularly EPA Tier 3 sulfur documentation mandates and California CARB vapor pressure rule expansion. Modeled inputs incorporated optical sensor miniaturization curves and MEMS displacement rates for thermal conductivity detection methods.
Material uncertainties — ASTM D86 protocol revision timelines, REACH chemical registration scope expansion, and biofuel blending mandate acceleration — sit outside the modeled envelope. Forecasts reflect assumptions regarding refinery automation capex continuity and midstream terminal expansion schedules. Revision becomes warranted when European borosilicate supply disruption crosses thresholds affecting analyzer manufacturer delivery commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety and Standards
Food Safety Software Market
Food Safety and Standards
Food Authenticity Market
Food Safety and Standards
Precision Food Thermometers Market
Food Safety and Standards
GMO Labeled Food Market
Food Safety and Standards
Pathogen Reduction Systems Market
Food Safety and Standards
Food Certification Market
Food Safety and Standards
Bakery Cleaning and Disinfection Products Market
Food Safety and Standards
Nutritional Labeling Market
Food Safety and Standards
Cold-Chain Friendly Post-Harvest Sanitizing Mist Market
Food Safety and Standards
Testing, Inspection, and Certification Market
Food Safety and Standards
Food Grade Biofilms Market
Food Safety and Standards
Blockchain Food Traceability Market
Food Safety and Standards
Food and Beverage Industrial Disinfection and Cleaning Market
Food Safety and Standards
Food and Beverage Air Filtration Market
Food Safety and Standards
Food Irradiation Market
Food Safety and Standards
Quality Assurance and Quality Control Market