
 Food Grade Biofilms Market | 2026-2036
Food Grade Biofilms Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Biofilms Market Analytics
Petroleum-based plastic wrap is rebalancing toward polysaccharide-derived alternatives in fresh produce economics. Tipa leverages its compostable film technology to anchor European supermarket supply chains. Apeel Sciences sustains plant-derived barrier coatings that extend shelf life without synthetic packaging. Mantrose-Haeuser specializes in edible coating systems for confectionery and nut applications.
Food grade biofilms constitute thin, edible barriers engineered from polysaccharides, proteins, lipids, or starches, typically ranging 0.05–0.25 mm in thickness and manufactured through solvent casting or extrusion methods. These structures control moisture migration, oxygen permeation, and oil absorption to prolong food stability and reduce waste. Polysaccharide-based formulations dominate current volume due to favorable film-forming properties and cost structures, while protein-derived segments command premium positioning in high-barrier applications. Gelatin-based products occupy niche pharmaceutical-adjacent food markets where clarity and thermoreversibility justify higher unit economics.
EFSA novel food contact material assessments, FDA food additive petitions, and EU Packaging and Packaging Waste Regulation revisions collectively determine market access timelines and compositional permissibility. REACH compliance for migrating substances imposes testing burdens that favor established suppliers with toxicology databases. Stakeholders must monitor regulatory divergence between European precautionary frameworks and U.S. substantial equivalence pathways when allocating R&D and registration budgets.
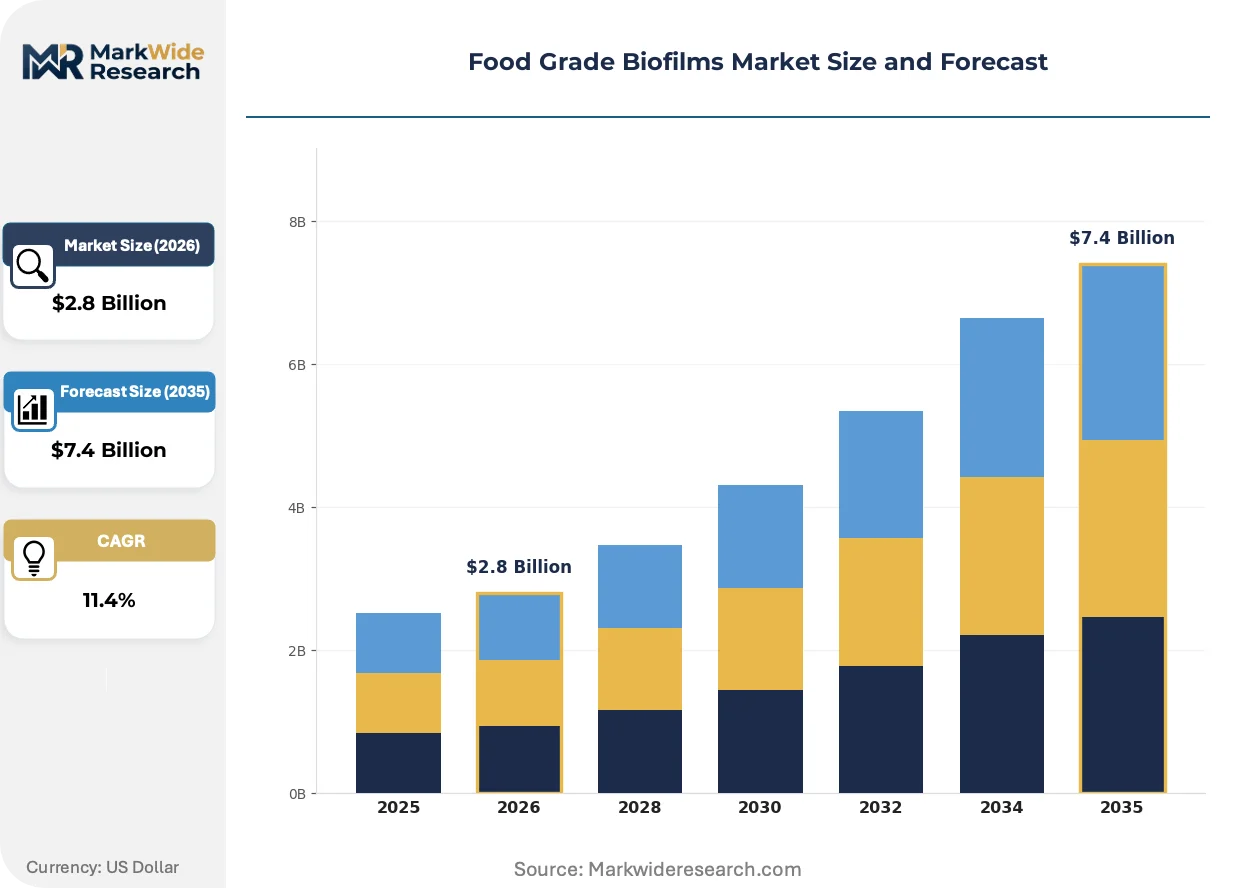
Market Dynamics
Fresh produce shelf-life extension economics are compressing acceptable packaging cost thresholds, forcing converters to absorb EFSA migration testing burdens while supermarket chains mandate compostable alternatives. This structural pressure redistributes margin across the value chain.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content targets and extended producer responsibility schemes accelerate substitution of petroleum-derived films with polysaccharide barriers in German and French retail channels.
- Modified atmosphere packaging integration:Biofilm oxygen permeability tuning enables passive respiration control for berries and leafy greens, eliminating active gas-flushing equipment capex for mid-size processors.
- Netherlands cluster concentration:Wageningen University research consortia and pilot-scale extrusion facilities reduce formulation-to-commercialization timelines for alginate-pectin blends.
Market Restraints
- Chitosan supply concentration:Over 70% of food-grade chitosan derives from Chinese crustacean processing, exposing formulators to tariff volatility and cold-chain spoilage risk during trans-Pacific shipment.
- REACH migration testing costs:ECHA substance evaluation fees for novel polysaccharide derivatives exceed €150,000 per notification, freezing SME participation in EU food contact applications.
- High-barrier performance gap:Protein-based films exhibit moisture sensitivity above 65% relative humidity, limiting deployment in tropical distribution corridors where synthetic EVOH dominates.
Strategic Opportunities
- India cold-chain buildout:FSSAI recognition of edible coatings for tropical fruit export compliance creates first-mover positioning for starch-zein formulations in mango and banana value chains.
- Active biofilm convergence:Integration of bacteriocin-releasing layers with pH-responsive chitosan matrices enables self-sanitizing packaging for ready-to-eat meat segments without synthetic preservatives.
- Direct-to-retail channel emergence:Subscription produce boxes and e-grocery fulfillment centers bypass traditional converter-distributor relationships, allowing biofilm suppliers to capture margin through specification partnerships.
Industry Challenges
- Extrusion scale-up engineering:Solvent-cast laboratory formulations face shear-thinning failures during industrial blown-film conversion, requiring rheology expertise scarce in traditional polymer processing talent pools.
- Dual certification synchronization:FDA food additive petitions and EFSA novel food contact opinions proceed on divergent evidentiary timelines, forcing parallel track investments without guaranteed reciprocity.
- Legacy equipment retrofit costs:Existing form-fill-seal lines optimized for polyolefin heat-seal windows demand $200,000-$400,000 modification investments to handle lower-temperature biofilm sealing profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Biofilms Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Edible Films, Coatings, Wraps, Gelatin-Based Products Material: Polysaccharides, Proteins, Lipids, Starches Application: Food Preservation, Packaging, Texture Modification, Flavor Release End User: Food Manufacturers, Restaurants, Retailers, Catering Services |
| Companies Covered | Tipa, Apeel Sciences, WikiCell Designs, Biofilm, Mantrose-Haeuser, Innovia Films, Ecovative Design, SELTIVA, Nagase America Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Biofilms Market Evolving Landscape
Active and intelligent packaging functionalities are migrating from synthetic substrates to edible matrices, redefining performance benchmarks beyond passive barrier properties. This shift compresses the boundary between packaging and food ingredient classifications.
Electrospun nanofiber biofilms is rewriting moisture management protocols for minimally processed vegetables. These sub-micron cellulose structures create tortuous path barriers with water vapor transmission rates approaching synthetic alternatives. Dutch vegetable processors are piloting electrospun carrot-pulp matrices for pre-cut salad mixes. The technology is rewriting cost structures by eliminating secondary absorbent pads and reducing freight weight.
EFSA's 2023 updated guidance on recycled plastics in food contact establishes precedent for enzymatic depolymerization validation pathways that biofilm suppliers can leverage for circularity claims. Industrial consequence includes accelerated investment in closed-loop collection systems tethered to composting infrastructure rather than mechanical recycling. Fresh produce packaging categories face the steepest compliance timelines, driving German retailers to pre-approve biofilm suppliers with established industrial composting partnerships.
Supermarket private-label procurement teams now specify shelf-life extension guarantees rather than material inputs, transferring performance risk upstream to film suppliers. This displaces traditional resin-grade contracting in favor of outcome-based agreements where biofilm vendors absorb spoilage cost exposure. The shift is most visible in UK and Scandinavian retail chains where food waste reduction targets carry executive compensation weight.
Food Grade Biofilms Market Segmentation
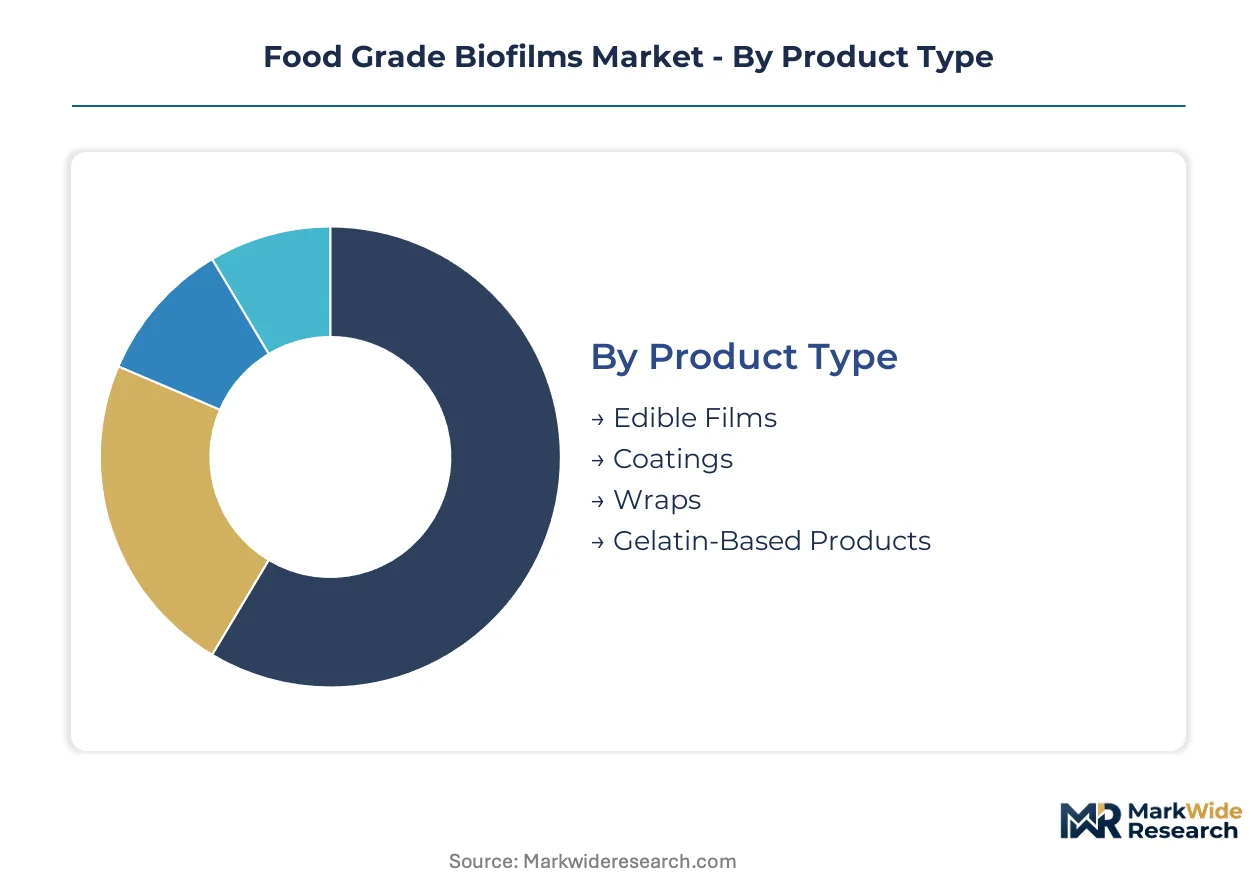
Segmentation in food grade biofilms reveals how material science capabilities, regulatory pathways, and end-use economics create distinct competitive arenas. Buyers prioritize different performance attributes—barrier properties, edibility, compostability, or cost—depending on their position in the value chain.
Product Type:
Buyers differentiate by functional integration depth—surface application versus structural replacement of conventional packaging.
- Edible Films:Standalone barriers manufactured through solvent casting or extrusion, typically 0.05–0.25 mm thick, serving as primary packaging for discrete food items. German supermarket chains specify these for private-label fresh produce where industrial composting infrastructure exists. EFSA novel food contact assessments remain the critical gating factor for formulation approval.
- Coatings:Directly applied surface layers that merge with food substrate, eliminating separate packaging removal. Demand concentrates in Netherlands vegetable processing for pre-cut salads, where electrospun carrot-pulp matrices from Wageningen consortia eliminate secondary absorbent pads. Shelf-life extension guarantees now dominate procurement specifications over material inputs.
- Wraps:Flexible sheets requiring manual or semi-automated application, positioned between films and coatings in labor intensity. UK subscription produce boxes and e-grocery fulfillment centers bypass traditional converter relationships through direct specification partnerships.
- Gelatin-Based Products:Thermoreversible, high-clarity barriers occupying pharmaceutical-adjacent confectionery and nut applications where clarity justifies premium unit economics.
Volume sits with coatings; growth tilts toward edible films.
Material:
Raw material selection determines barrier performance, supply security, and regulatory testing burden simultaneously.
- Polysaccharides:Alginate, pectin, and chitosan formulations dominate current volume through favorable film-forming properties and cost structures. Chitosan supply concentration—over 70% from Chinese crustacean processing—exposes formulators to tariff volatility and cold-chain spoilage risk during trans-Pacific shipment. Netherlands cluster facilities accelerate alginate-pectin blend commercialization timelines.
- Proteins:Zein, whey, and collagen derivatives command premium positioning in high-barrier applications. Moisture sensitivity above 65% relative humidity limits deployment in tropical distribution corridors where synthetic EVOH dominates.
- Lipids:Wax and fatty acid derivatives providing hydrophobicity in composite formulations. REACH migration testing costs exceeding €150,000 per notification freeze SME participation in EU food contact applications.
- Starches:Cost-competitive base materials with limited barrier performance, finding traction in India FSSAI-recognized tropical fruit export coatings for mango and banana value chains.
Polysaccharides anchor current supply; proteins are climbing the fastest as barrier specifications tighten.
Application:
Application segmentation tracks how biofilm functionality expands from passive barrier toward active food system integration.
- Food Preservation:Moisture and oxygen control to prolong stability, the foundational use case where passive barrier properties dominate. German and French retail channels drive substitution under EU Packaging and Packaging Waste Regulation mandates.
- Packaging:Structural replacement of petroleum-derived films, requiring blown-film extrusion scale-up that faces shear-thinning failures absent scarce rheology expertise. Fresh produce categories face steepest compliance timelines.
- Texture Modification:Surface engineering for mouthfeel and appearance in confectionery, where Mantrose-Haeuser specializes in edible coating systems for nut applications.
- Flavor Release:Controlled release matrices merging packaging with ingredient functionality, compressing boundaries between packaging and food classifications. Bacteriocin-releasing layers with pH-responsive chitosan enable self-sanitizing ready-to-eat meat packaging.
Packaging commands investment; preservation retains volume leadership.
End User:
End user type determines specification authority, volume scale, and outcome-based contracting exposure.
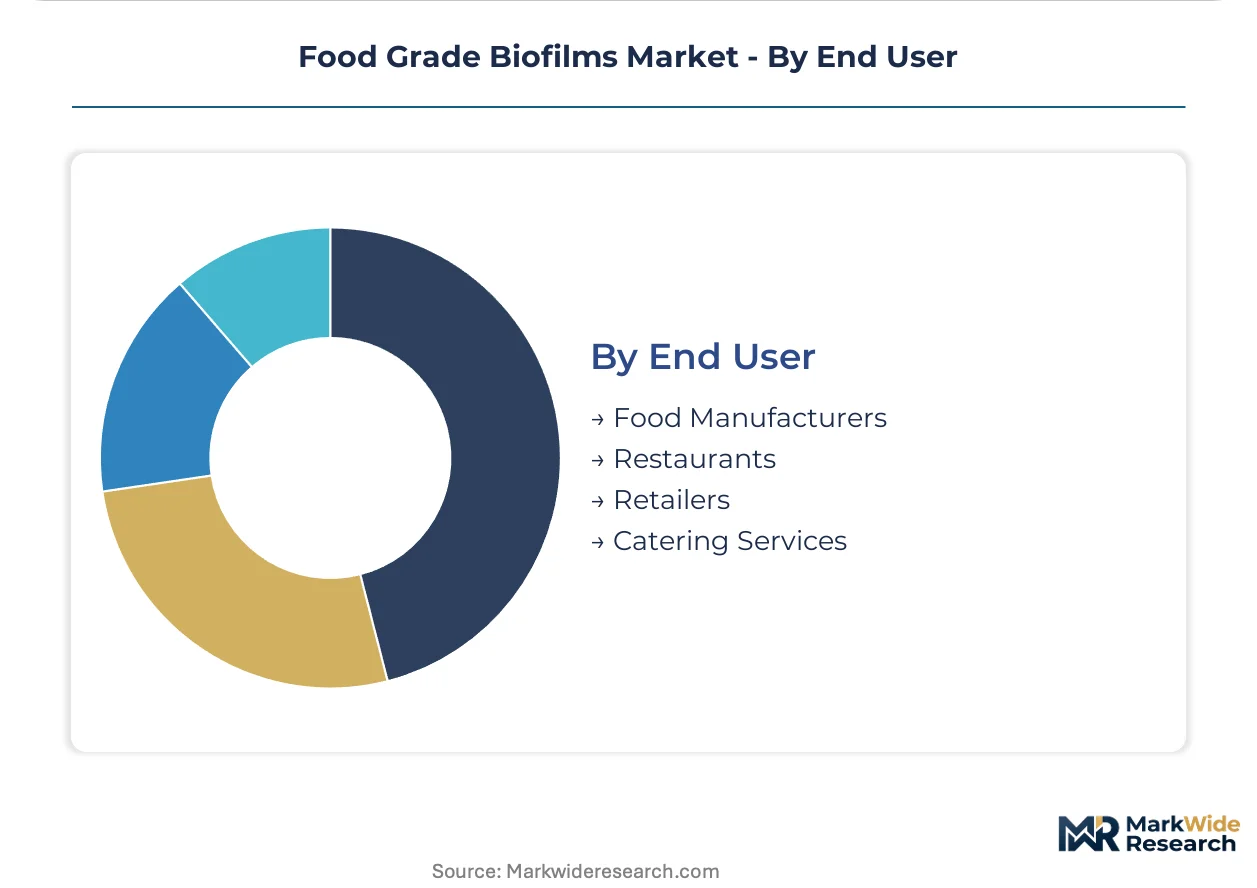
- Food Manufacturers:Processors with direct formulation control, absorbing EFSA migration testing burdens while supermarket chains mandate compostable alternatives. Modified atmosphere packaging integration enables passive respiration control for berries without gas-flushing equipment capex.
- Restaurants:Limited direct procurement, primarily through distributor intermediaries with minimal specification influence.
- Retailers:Supermarket private-label procurement teams now specify shelf-life extension guarantees rather than material inputs, transferring spoilage cost exposure upstream. UK and Scandinavian chains weight food waste reduction targets in executive compensation.
- Catering Services:Fragmented demand with sustainability signaling value but limited volume concentration.
Food manufacturers hold volume; retailers are gaining share fastest through specification authority capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German supermarket chains and food processors anchor current demand concentration, sourcing compostable barrier solutions through active procurement mandates. EFSA approval pathways for novel food contact materials accelerate commercialization timelines across Northern European retail channels. Fresh produce packaging economics in Germany are compressing acceptable cost thresholds while redistributing margin across converter value chains.
Germany
Supermarket private-label procurement teams specify shelf-life extension guarantees rather than material inputs, transferring spoilage cost exposure upstream to film suppliers. EU Packaging and Packaging Waste Regulation mandates recycled content targets and extended producer responsibility schemes that accelerate polysaccharide barrier substitution. The Baden-Württemberg industrial corridor hosts pilot-scale extrusion facilities reducing formulation-to-commercialization timelines for alginate-pectin blends.
United States
Modified atmosphere packaging integration enables passive respiration control for berries and leafy greens, eliminating active gas-flushing equipment capex for mid-size processors. FDA food additive petitions proceed on evidentiary timelines divergent from European pathways, forcing parallel track investments without guaranteed reciprocity. California vegetable processors pilot electrospun carrot-pulp matrices for pre-cut salad mixes, rewriting moisture management protocols.
Netherlands
Wageningen University research consortia concentrate formulation expertise and pilot-scale testing infrastructure for biofilm commercialization. REACH compliance for migrating substances imposes testing burdens that favor established suppliers with toxicology databases. The Randstad cluster reduces alginate-pectin blend development cycles through proximity between academic research and industrial extrusion facilities.
India
FSSAI recognition of edible coatings for tropical fruit export compliance creates first-mover positioning for starch-zein formulations in mango and banana value chains. Cold-chain infrastructure buildout exposes protein-based films to moisture sensitivity above 65% relative humidity in tropical distribution corridors. Maharashtra and Gujarat processing hubs concentrate export-oriented coating application capacity for European retail compliance.
United Kingdom
Subscription produce boxes and e-grocery fulfillment centers bypass traditional converter-distributor relationships, allowing biofilm suppliers to capture margin through direct specification partnerships. Food waste reduction targets carry executive compensation weight in UK and Scandinavian retail chains, accelerating outcome-based contracting adoption. London-based procurement teams mandate compostable alternatives while absorbing EFSA migration testing burdens through consolidated supplier relationships.
Food Grade Biofilms Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers align with supermarket chains and research consortia to secure specification authority. The vendor base fragments across material science specialists, agricultural technology firms, and traditional packaging converters adapting biofilm portfolios. Three archetypes occupy distinct positions: compostable film technology developers, plant-derived barrier coating innovators, and edible coating system specialists for confectionery applications. M&A activity and technology licensing agreements represent the primary competitive moves as firms seek formulation expertise and regulatory approval databases.
Within the technology-specialist tier, Tipa and Apeel Sciences exemplify divergent approaches to supermarket supply chain integration. Tipa anchors European retail channel relationships through compostable film platforms. Apeel Sciences occupies a position at the intersection of agricultural technology and packaging functionality. Mantrose-Haeuser represents the confectionery-focused edible coating archetype with pharmaceutical-adjacent positioning. These three companies illustrate how material science capabilities, regulatory pathways, and end-use economics create distinct competitive arenas without overlapping core market segments.
| Leading Market Players |
|---|
| Tipa |
| Apeel Sciences |
| WikiCell Designs |
| Biofilm |
| Mantrose-Haeuser |
| Innovia Films |
| Ecovative Design |
| SELTIVA |
| Nagase America Corporation |
| Others |
Value Network & Pricing Analysis
Captive chitosan sourcing from Chinese crustacean processors anchors both supply security and pricing power for polysaccharide formulators, creating tiered margin structures that favor vertically integrated players with cold-chain control over trans-Pacific shipments.
Pricing Analysis
Volume concentrates in standard-grade polysaccharide films while margin accrues to protein-based high-barrier formulations. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA certification status and alginate-pectin blend complexity. Cost compression in standard grades intensifies because supermarket chains mandate compostable alternatives without absorbing migration testing burdens. Small and mid-size converters exhibit highest price sensitivity, while pharmaceutical-adjacent confectionery buyers accept premium positioning for gelatin clarity.
Supply Chain Analysis
Chitosan feedstock rests on Chinese crustacean processing concentration exceeding seventy percent of food-grade supply, with alginate sourcing from Norwegian kelp operations and pectin from Spanish citrus peel processors. Raw material dependencies span crustacean shell waste, kelp biomass, and citrus processing byproducts. Single-source vulnerability in chitosan exposes formulators to tariff volatility and spoilage risk during trans-Pacific cold-chain transit. Distribution runs through converter-distributor relationships to supermarket procurement teams, though direct-to-retail channels are displacing traditional intermediaries in UK and Scandinavian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food grade biofilm supply remains constrained by REACH migration testing capacity bottlenecks at ECHA-certified laboratories, propping pricing for approved suppliers while freezing SME participation.
For Market Incumbents: Deploy toxicology database leverage to accelerate EFSA novel food contact opinions before regulatory divergence widens. Absorb converter margin compression through backward integration into pilot-scale extrusion facilities in the Netherlands cluster. Defensive consolidation around alginate-pectin formulation expertise protects against protein-based film entrants targeting high-barrier applications. For New Entrants and Emerging Players: The premium-economy price-point gap in Indian tropical fruit export coatings offers white-space positioning for starch-zein formulations with FSSAI recognition. Target Maharashtra and Gujarat processing hubs with direct specification partnerships bypassing converter relationships. Subscription produce box channels in UK markets provide the most penetrable go-to-market angle for wrap applications. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by packaging converters seeking biofilm formulation expertise and regulatory approval databases. Long-term viability hinges on industrial composting infrastructure buildout pacing ahead of synthetic film substitution mandates. Acquisition target archetype: mid-cap specialists with established EFSA opinions and Wageningen research consortia relationships. Watch EFSA guidance updates on enzymatic depolymerization validation as inflection indicator for circularity claim monetization.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Contact Assessment | Accelerates commercialization timelines for alginate-pectin blends in German retail channels. |
| Backward Integration into Chitosan Sourcing | Reduces tariff exposure and cold-chain spoilage risk from Chinese crustacean processing concentration. |
| Industrial Composting Partnership | Enables supermarket private-label procurement teams to specify shelf-life extension guarantees with verified end-of-life pathways. |
| Electrospun Nanofiber Scale-Up | Rewrites moisture management protocols for Dutch vegetable processors eliminating secondary absorbent pads. |
| Direct-to-Retail Channel Development | Captures margin through specification partnerships with UK subscription produce boxes bypassing converter-distributor relationships. |
Research Methodology
EFSA guidance documents, EU Packaging and Packaging Waste Regulation filings, and Wageningen University research consortium publications formed the secondary backbone. Primary interviews with biofilm formulation scientists, supermarket private-label procurement managers, EFSA regulatory affairs consultants, and industrial composting facility operators combined with secondary validation. Customs data on chitosan imports and SEC filings from packaging converters provided demand-side triangulation. Bottom-up volume estimates from application segments and top-down cross-checks against EU regulatory timelines anchored the analytical framework.
Historical trendline analysis traced polysaccharide adoption curves against synthetic film substitution patterns across the analysis window. Segmentation dimensions modeled include material type, product form, application function, and end-user procurement authority. CAGRs derived from curve-fitting approaches to EFSA approval velocity and supermarket mandate implementation schedules. Industry-specific forecast inputs encompassed REACH migration testing queue lengths and industrial composting infrastructure deployment rates.
Inputs from EFSA opinion databases and Netherlands pilot-scale facility capacity reports were available through the study window; gaps in real-time supermarket procurement contract terms introduce uncertainty bands around outcome-based pricing adoption trajectories. Forecasts reflect assumptions on regulatory timeline stability and composting infrastructure investment continuity. A small set of named triggers warrants ongoing watch: EFSA guidance updates on recycled plastics validation, FSSAI coating recognition expansion, and German extended producer responsibility scheme enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety and Standards
Food Safety Software Market
Food Safety and Standards
Pathogen Reduction Systems Market
Food Safety and Standards
Natural Antimicrobials Market
Food Safety and Standards
Food Certification Market
Food Safety and Standards
Food Authenticity Market
Food Safety and Standards
Testing, Inspection, and Certification Market
Food Safety and Standards
Global Cold Chain Monitoring Market
Food Safety and Standards
Blockchain Food Traceability Market
Food Safety and Standards
Automatic Distillation Analyzer Market
Food Safety and Standards
GMO Labeled Food Market
Food Safety and Standards
Precision Food Thermometers Market
Food Safety and Standards
Food and Beverage Industrial Disinfection and Cleaning Market
Food Safety and Standards
Bakery Cleaning and Disinfection Products Market
Food Safety and Standards
Cold-Chain Friendly Post-Harvest Sanitizing Mist Market
Food Safety and Standards
Bar Inspection System Market
Food Safety and Standards
Nutritional Labeling Market