
 Cosmetic Filling Machines Market | 2026-2036
Cosmetic Filling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Filling Machines Market Outlook
Stainless steel is broadening its dominance over aluminum in contact-part construction as cosmetic brands prioritize corrosion resistance during acidic serum filling. Krones AG leverages captive supply of pharmaceutical-grade stainless to anchor premium positioning across European installations. Syntegon competes through modular platform architectures that reduce changeover downtime between cream and liquid formats. IMA Group specializes in integrated isolator technology for preservative-free cosmetic lines.
Cosmetic filling machines are automated dispensing systems engineered to meter viscous and non-viscous products into primary packaging with fill accuracy typically within plus or minus one percent by volume; these units employ piston, peristaltic, or vacuum-assisted mechanisms to handle shear-sensitive emulsions without compromising rheological stability. Liquid fillers lead installed capacity due to serum and toner proliferation, while gel fillers represent the fastest-growing category as transparent hydrogel masks and hair styling gels expand formulation pipelines. Electric technology dominates new orders for energy efficiency, though pneumatic systems retain share in explosive-atmosphere environments where intrinsically safe operation remains mandatory.
FDA cGMP guidelines and EU MDR-adjacent machinery safety directives shape validation protocols for equipment qualification, while REACH substance restrictions limit lubricant and sealant chemistries permitted in European-sold machines. China's GB standards for food-contact materials extend to cosmetic filling components, creating dual-certification burdens for exporters. Stakeholders must monitor evolving ESG disclosure rules under CSRD that will soon require documented carbon footprints per installed filling line.
Market Dynamics
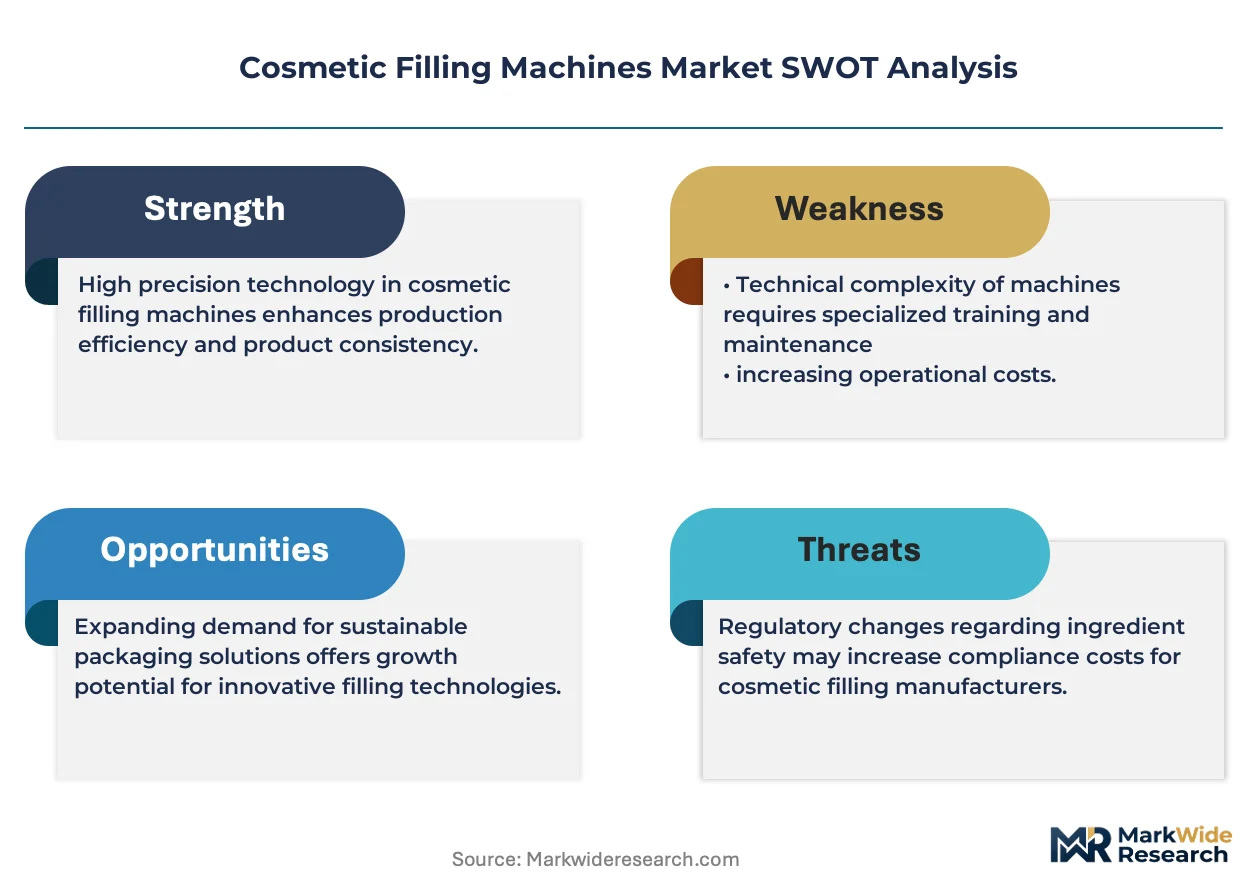
Precision servo-motor integration and aseptic isolator architecture are compressing changeover windows while elevating validation burdens for cosmetic filling equipment manufacturers serving premium skincare brands.
Growth Catalysts
- REACH substance restrictions:European lubricant chemistry constraints are accelerating stainless steel adoption over aluminum in contact-part construction, forcing equipment upgrades across preservative-free cosmetic lines.
- Serum formulation proliferation:South Korean premium skincare brands are driving demand for aseptic liquid filling systems capable of handling shear-sensitive acidic emulsions without rheological degradation.
- Servo-driven precision engineering:German cleanroom installations are commanding priority placement for electric filler technology, displacing pneumatic systems in non-explosive environments.
Market Restraints
- Pharmaceutical-grade stainless supply concentration:Captive supply chains anchored in Central European steel mills create input cost volatility for contact-part fabricators.
- Dual-certification compliance burdens:China's GB standards for food-contact materials extend to cosmetic components, forcing exporters to maintain parallel validation protocols.
- Pneumatic system lock-in:Explosive-atmosphere manufacturing environments mandate intrinsically safe pneumatic operation, blocking electric technology penetration in solvent-heavy hair care facilities.
Strategic Opportunities
- Preservative-free cosmetic isolator integration:Integrated barrier technology represents white space as brands eliminate parabens and formaldehyde releasers from formulations.
- CSRD carbon footprint documentation:Upcoming ESG disclosure rules will require installed line-level emissions accounting, creating service revenue streams for equipment vendors.
- Hydrogel mask pipeline expansion:Transparent gel fillers are capturing fastest-growing category status as K-beauty sheet mask demand rotates toward gel-based delivery systems.
Industry Challenges
- Cleanroom-qualified technician scarcity:Servo calibration and isolator maintenance require specialized skill sets concentrated in pharmaceutical equipment sectors.
- FDA cGMP validation timeline compression:Equipment qualification protocols are extending from months to years as documentation requirements tighten for contact surface integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Filling Machines Market |
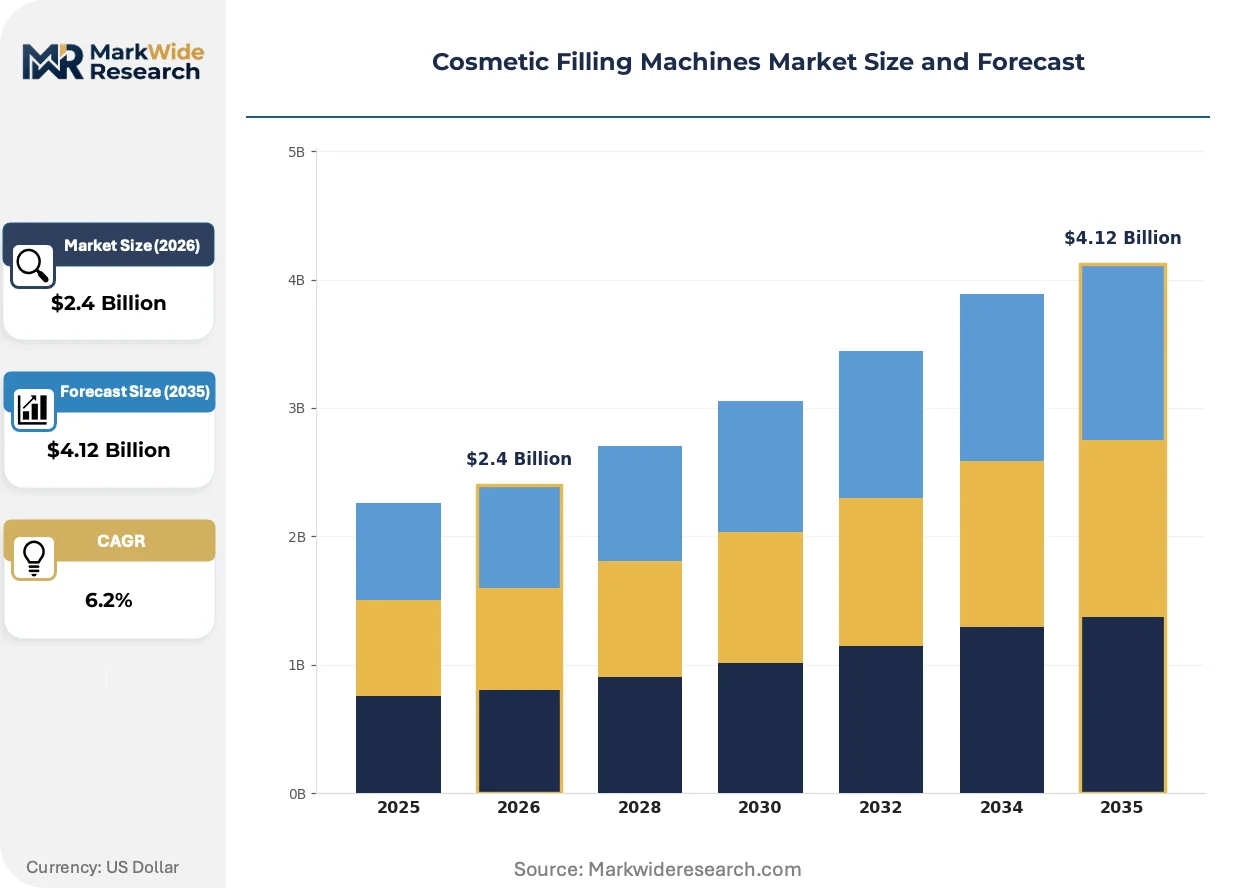
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Fillers, Cream Fillers, Powder Fillers, Gel Fillers Technology: Pneumatic, Electric, Vacuum, Gravity End User: Manufacturers, Contract Packagers, Retailers, Wholesalers Packaging Type: Glass Bottles, Plastic Tubes, Jars, Sachets |
| Companies Covered | Yundu, Xinyi Machinery, FULUKE, LIENM, IMA Group, Syntegon, Groninger, Krones AG, Accutek Packaging Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Filling Machines Market Strategic Shifts
Modular platform architectures and isolator-integrated designs are collapsing the boundary between pharmaceutical and cosmetic equipment standards while reshaping buyer procurement criteria.
Single-use fluid path technology is unifying sterile product contact surfaces with rapid format changeover capability. Premium skincare contract manufacturers in Germany and South Korea are adopting disposable tubing assemblies for preservative-free serum filling. This convergence is unifying pharmaceutical aseptic standards with cosmetic production economics, compressing the historical gap between equipment categories.
EU MDR-adjacent machinery safety directives are mandating redundant safety circuits and documented risk assessments for filling line installations. European equipment vendors are embedding functional safety modules into servo control architectures. Preservative-free cosmetic lines with integrated isolator technology face the steepest compliance burden as isolator integrity becomes a critical control point under expanded CE marking requirements.
Buyer preference is rotating toward outcome-based equipment performance contracts rather than capital purchase models. Large cosmetic brand owners in Germany are unbundling after-sales service and demanding guaranteed uptime commitments with penalty clauses. This contractual evolution is most visible in cleanroom installations where downtime costs exceed equipment depreciation schedules.
Cosmetic Filling Machines Market Segmentation
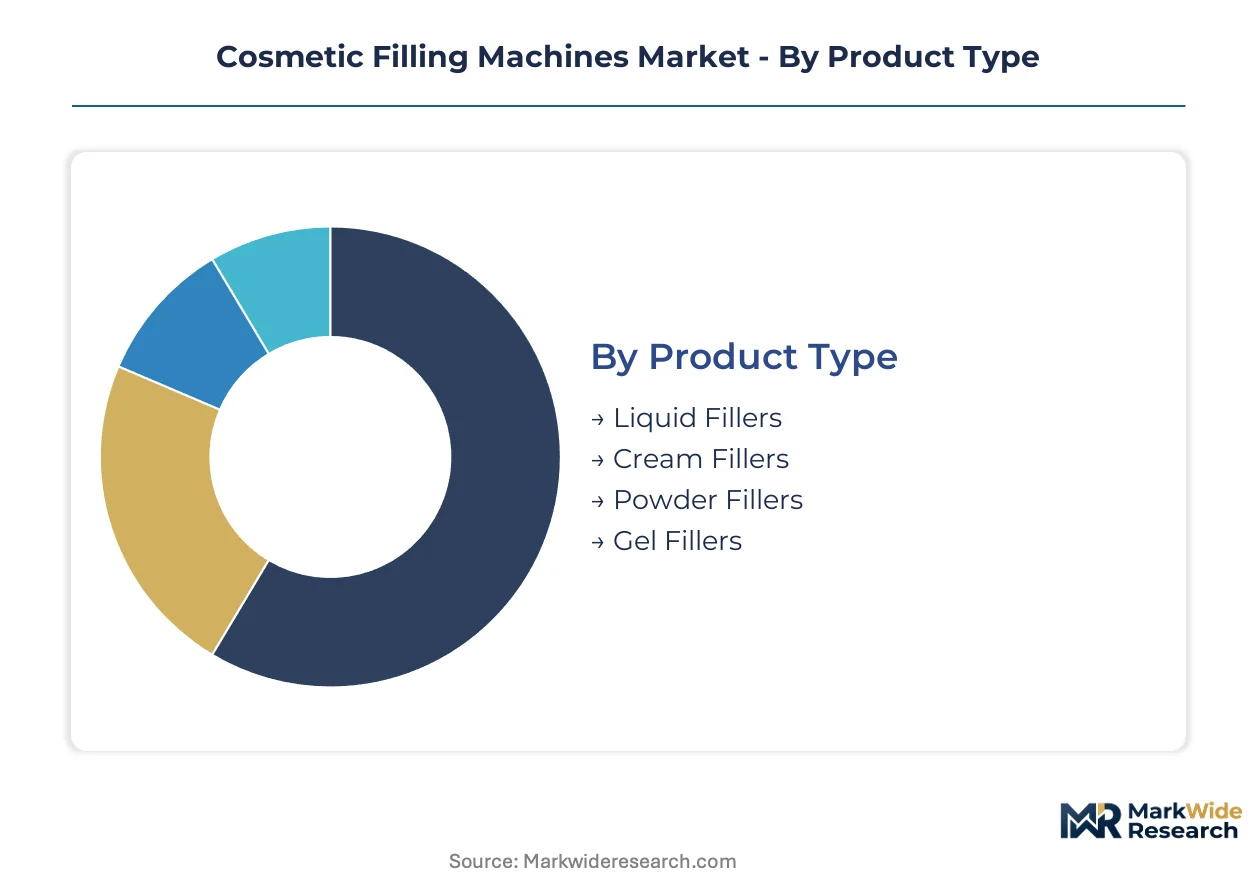
Cosmetic filling machine procurement decisions hinge on formulation compatibility, cleanroom classification, and validation burden. Each segment carries distinct certification requirements that shape total cost of ownership and supplier selection criteria.
Product Type:
FDA cGMP validation timelines stretch longest for liquid and gel fillers handling preservative-free serums, while powder fillers face simpler surface-integrity protocols under EU MDR-adjacent machinery directives.
- Liquid Fillers:Piston and peristaltic mechanisms dominate serum and toner applications where fill accuracy within plus or minus one percent by volume is mandatory. South Korean premium skincare brands are commanding priority placement for aseptic isolator-integrated systems in cleanroom installations.
- Gel Fillers:Vacuum-assisted and servo-driven architectures handle shear-sensitive hydrogels without rheological degradation. Transparent hydrogel mask pipelines are expanding fastest among K-beauty contract manufacturers in Seoul and Busan.
- Cream Fillers:Viscous emulsion handling requires heated product paths and precision piston metering for hair conditioners and body butters.
- Powder Fillers:Auger and cup-fill mechanisms serve compact and loose powder cosmetics with simpler contact-surface validation requirements.
Leading the category by volume: Liquid Fillers. Growing fastest: Gel Fillers.
Technology:
Cost tiers separate electric servo systems from pneumatic alternatives, with vacuum and gravity technologies occupying mid-market positions based on automation depth and energy consumption profiles.
- Electric:Servo-motor integration delivers precision fill control and energy efficiency for non-explosive cleanroom environments. German installations are displacing pneumatic systems in serum and essence production lines.
- Pneumatic:Intrinsically safe operation remains mandatory in solvent-heavy hair care facilities where explosive atmospheres preclude electric actuation. REACH lubricant restrictions are elevating maintenance costs for European-sold pneumatic units.
- Vacuum:Negative-pressure filling prevents oxidation in fragrance and essential oil applications.
- Gravity:Simple open-nozzle designs serve low-viscosity toners and micellar waters at lowest capital cost.
Electric systems command the premium tier. Vacuum technology is climbing the fastest as fragrance houses upgrade oxidation-sensitive lines.
End User:
Procurement patterns diverge sharply between integrated manufacturers and outsourced packagers, with retailers and wholesalers driving equipment-as-a-service adoption.
- Manufacturers:In-house filling operations at L'Oréal, Estée Lauder, and Amorepacific demand validated isolator technology for preservative-free lines. FDA cGMP documentation burdens extend qualification timelines to multiple years.
- Contract Packagers:Modular platform architectures from Syntegon and IMA Group reduce changeover downtime between cream and liquid formats. German contract manufacturers are unbundling after-sales service into outcome-based performance contracts.
- Retailers:Private-label cosmetic brands are piloting compact tabletop fillers for in-store personalization services.
- Wholesalers:Bulk repackaging operations favor gravity and pneumatic systems for lowest capital deployment.
Contract Packagers lead order volume. Retailers are expanding most quickly as private-label personalization trends accelerate.
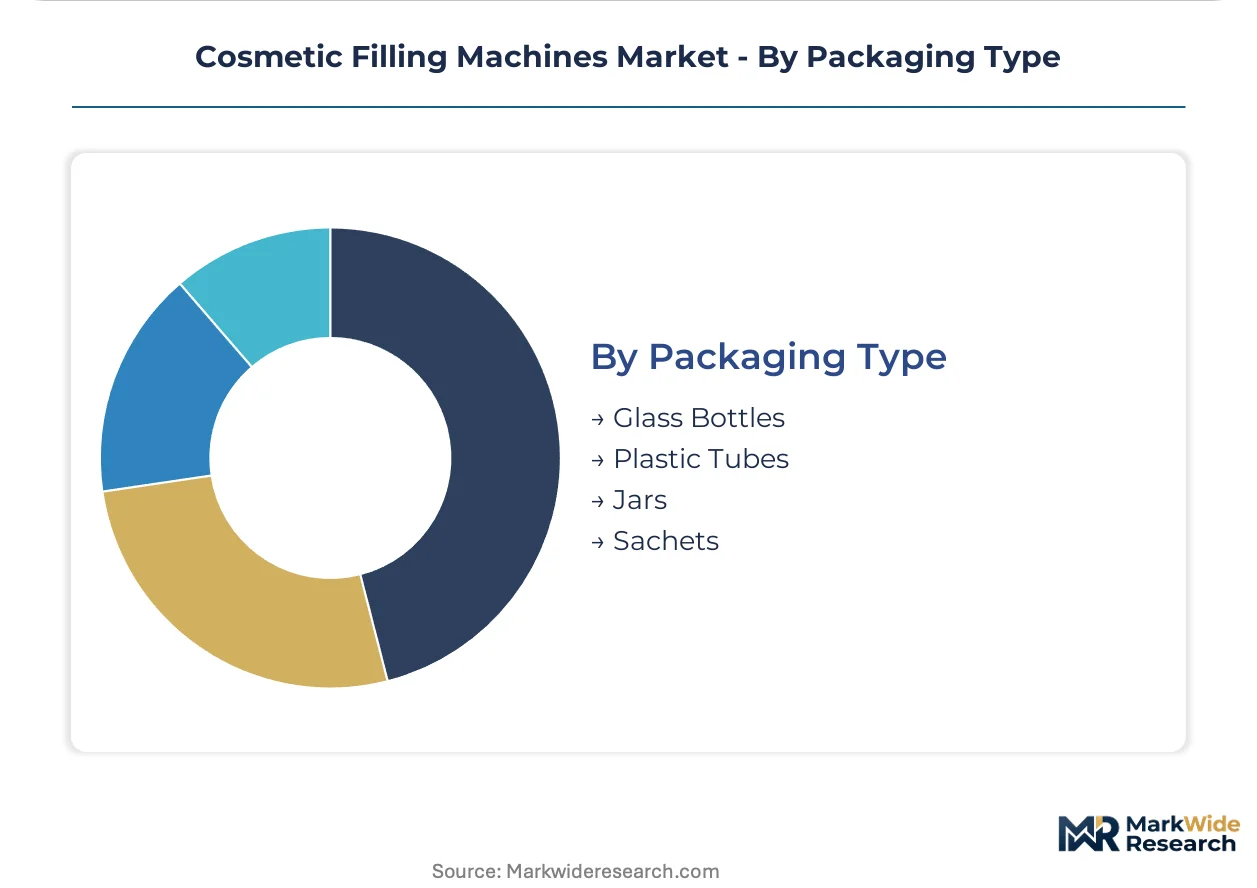
Packaging Type:
Container material and geometry dictate filling mechanism selection, with glass and plastic formats separating premium from mass-market positioning.
- Glass Bottles:Pharmaceutical-grade borosilicate and amber glass for serums and essences requires precision nozzle alignment and anti-breakage handling systems. South Korean cleanroom installations prioritize glass-compatible aseptic isolators.
- Plastic Tubes:LDPE and laminated tubes for creams and lotions demand hot-air sealing integration downstream of fill stations. European tube-filling lines face CE marking pressure under expanded machinery safety directives.
- Jars:Wide-mouth containers for balms and masks suit piston fillers with programmable dwell times for viscous product settling.
- Sachets:Horizontal form-fill-seal integration dominates single-use sample and travel-size production.
Plastic Tubes lead by installed base. Glass Bottles are gaining share fastest as premium skincare elevates perceived value through pharmaceutical-grade packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium skincare brands in South Korea and precision-engineered equipment demand in Germany concentrate procurement volumes for aseptic liquid filling systems. Cleanroom installations in Seoul and Busan compete with Bavarian pharmaceutical-grade steel clusters for supplier priority placement.
Germany
Precision servo-driven fillers command priority placement in cleanroom installations across Bavaria and Baden-Württemberg. REACH compliance tightens validation requirements for contact surfaces, accelerating stainless steel adoption over aluminum. The Stuttgart industrial corridor anchors captive supply chains for pharmaceutical-grade steel mills serving contact-part fabricators.
South Korea
Premium skincare brands in Seoul and Busan accelerate demand for aseptic liquid filling systems handling shear-sensitive acidic emulsions. MFDS cosmetic safety standards extend to manufacturing equipment validation, elevating documentation burdens for isolator-integrated lines. The Seoul Capital Area concentrates K-beauty contract manufacturers expanding transparent hydrogel mask pipelines.
United States
Cosmetic manufacturers face FDA cGMP validation timelines stretching multiple years for preservative-free serum filling equipment. EPA chemical safety oversight intersects with state-level clean air regulations in California and New Jersey manufacturing zones. The New York Metro and Greater Boston clusters drive demand for modular platform architectures serving contract packagers.
China
GB standards for food-contact materials extend to cosmetic filling components, creating dual-certification burdens for exporters targeting European and North American markets. NMPA cosmetic registration requirements tighten manufacturing equipment documentation. The Yangtze River Delta and Pearl River Delta house the majority of domestic filler fabricators serving both local brands and export-oriented contract manufacturers.
France
Luxury cosmetic houses in Île-de-France demand isolator-integrated systems for preservative-free fragrance and skincare lines. ANSM oversight of cosmetic manufacturing equipment intensifies validation protocols for aseptic processing. The Paris-Saclay corridor attracts precision equipment vendors serving L'Oréal and LVMH production facilities.
Cosmetic Filling Machines Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade equipment vendors capturing premium positioning while regional fabricators serve mid-market volume. The vendor base organizes around three strategic archetypes: European precision-engineering houses with captive steel supply, Asian modular platform specialists, and North American packaging integration firms. Competitive moves concentrate on M&A for isolator technology capabilities and capacity expansion in South Korean and German cleanroom corridors.
Among European precision-engineering houses, Krones AG anchors the premium tier through captive supply of pharmaceutical-grade stainless steel, while Syntegon occupies a position exemplifying modular platform architectures. IMA Group represents the integrated isolator technology archetype for preservative-free cosmetic lines. These three firms collectively illustrate how validation burden and cleanroom qualification separate premium positioning from commodity fabrication.
| Leading Market Players |
|---|
| Yundu |
| Xinyi Machinery |
| FULUKE |
| LIENM |
| IMA Group |
| Syntegon |
| Groninger |
| Krones AG |
| Accutek Packaging Equipment |
| Others |
Value Chain & Pricing Dynamics
Cleanroom-qualified technician scarcity in Germany and South Korea amplifies labor-cost differentials that separate premium isolator-integrated systems from economy-grade pneumatic fillers. Servo calibration specialists command wage premiums that equipment vendors pass through to buyers, widening spreads between electric and pneumatic technology tiers.
Pricing Analysis
High-volume contract packagers negotiate standard-tier pricing while premium manufacturers absorb isolator premiums for preservative-free lines. Price differentiation hinges on FDA cGMP validation depth and REACH-compliant stainless steel grade in contact-part construction. Cost compression in economy pneumatic systems intensifies as Chinese fabricators expand export capacity. Contract packagers exhibit highest price sensitivity due to unbundled after-sales service demands, whereas integrated manufacturers prioritize uptime guarantees over capital cost.
Supply Chain Analysis
Dual-sourcing requirements from German and South Korean buyers mandate parallel qualification of Central European and East Asian steel suppliers for pharmaceutical-grade stainless contact parts. Raw material flows draw from German steel mills, Chinese component fabricators, and Japanese servo-motor manufacturers. Single-source vulnerability concentrates in pharmaceutical-grade stainless supply chains anchored to Stuttgart-area mills. Distribution runs through OEM direct sales for premium installations and regional distributors for mid-market pneumatic systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cosmetic filling equipment is transitioning from pneumatic to electric servo architectures as cleanroom installations displace intrinsically safe systems in non-explosive environments. This technology shift compresses margins for legacy pneumatic vendors while elevating validation burdens for electric system adopters.
For Market Incumbents: Anchor premium positioning through captive pharmaceutical-grade stainless supply and isolator technology acquisition. Krones AG's steel supply integration exemplifies defensive moat construction against modular platform competitors. Capacity expansion in South Korean cleanroom corridors captures K-beauty serum formulation demand. Certification investment in FDA cGMP documentation capabilities extends qualification timeline advantages.
For New Entrants and Emerging Players: The premium-economy price-point gap in contract packaging creates white-space opportunity for mid-market electric servo systems with simplified isolator architectures. Target German regional fabricators serving private-label cosmetic brands with modular platforms that reduce changeover downtime. Penetrate through outcome-based performance contracts that unbundle after-sales service from capital purchase.
For Investors and Strategic Acquirers: Re-rating potential sits with isolator technology specialists given REACH substance restrictions accelerating preservative-free line adoption. Long-term viability favors vendors with documented carbon footprint capabilities ahead of CSRD disclosure mandates. Watch MFDS cosmetic safety standard expansion as inflection signal for South Korean equipment demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Acquisition | REACH compliance pressures are forcing preservative-free line upgrades across European cosmetic manufacturers. |
| South Korean Cleanroom Expansion | MFDS validation requirements elevate documentation burdens that local presence mitigates for K-beauty contract manufacturers. |
| Pharmaceutical-Grade Steel Backward Integration | Captive supply chains insulate contact-part fabricators from Central European mill input cost volatility. |
| Outcome-Based Service Contract Launch | German cosmetic brand owners now demand guaranteed uptime commitments with penalty clauses for cleanroom installations. |
| Servo-Motor Platform Standardization | Electric technology displacement of pneumatic systems accelerates as energy efficiency mandates tighten across EU manufacturing. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this cosmetic filling equipment analysis. Primary interviews with plant engineers at L'Oréal and Amorepacific, aftermarket service heads at Syntegon and IMA Group, and procurement leads at German contract packagers validated demand assumptions. FDA 483 inspection databases, ECHA REACH substance registrations, and MFDS cosmetic manufacturing facility listings supplemented shipment data. Bottom-up equipment installation counts triangulated against top-down market value estimates.
Data-stream reconciliation across technology type, end-user category, and cleanroom classification dimensions shaped the analytical framework. Segmentation modeling incorporated formulation compatibility, packaging format, and regional regulatory cluster variables. CAGRs derived from slope-log analysis of validated installation data and replacement cycle assumptions. Servo-motor adoption curves and isolator technology penetration rates served as industry-specific forecast inputs across the projection horizon.
Inputs from FDA warning letter databases and ECHA substance restriction timelines were available through the study window; gaps in Chinese GB standard enforcement data introduce uncertainty bands around dual-certification compliance cost estimates. Deviation in REACH substance restriction expansion or MFDS equipment validation scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Automatic Banding Machine Market
Packaging Machinery
Food Packaging Machinery Market
Packaging Machinery
Vacuum Sealing Machine Market
Packaging Machinery
Wraparound Case Packers Market
Packaging Machinery
Flow Wrapper Market
Packaging Machinery
Corrugated Box Machines Market
Packaging Machinery
Induction Sealing Machine Market
Packaging Machinery
Box Sealing Machines Market
Packaging Machinery
Global Food and Beverage Packaging Machinery Market
Packaging Machinery
Cup Filling Machine Market
Packaging Machinery
Glue Machine Market
Packaging Machinery
Blow Fill Seal (BFS) Technology Market
Packaging Machinery
Tray Sealing Machines Market
Packaging Machinery
Carton Erecting Machinery Market
Packaging Machinery
Box Filling Machine Market
Packaging Machinery
Air Cushion Machine Market