
 Cigarette Packaging Machine Market | 2026-2036
Cigarette Packaging Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Cigarette Packaging Machine Market Analysis
Contract packaging companies is realigning procurement patterns across the cigarette packaging machine landscape as tobacco manufacturers outsource secondary packaging operations to specialized service providers. Hauni Maschinenbau leverages its deep integration with primary processing equipment to anchor integrated line offerings. G.D S.p.A sustains dominance in high-speed filter assembly and packing systems through precision engineering scale. Molins PLC differentiates via specialized retrofit services that extend legacy asset life.
Cigarette packaging machines are precision-engineered systems designed to form, fill, seal, and wrap tobacco products at speeds exceeding 10,000 units per minute, utilizing servo-driven motion control and vision-based quality inspection to maintain pack integrity. Their primary commercial purpose is to convert bulk cigarette rods into market-ready packs, cartons, and outer cases while minimizing material waste and ensuring regulatory traceability. Automatic machines command the largest installed base due to labor cost pressures and throughput requirements, though hybrid machines represent the fastest-growing category as manufacturers seek flexible platforms accommodating both conventional and reduced-risk product formats. Digital printing technology within the technology segment is expanding as brand owners pursue serialization compliance and regional customization without plate changeover delays.
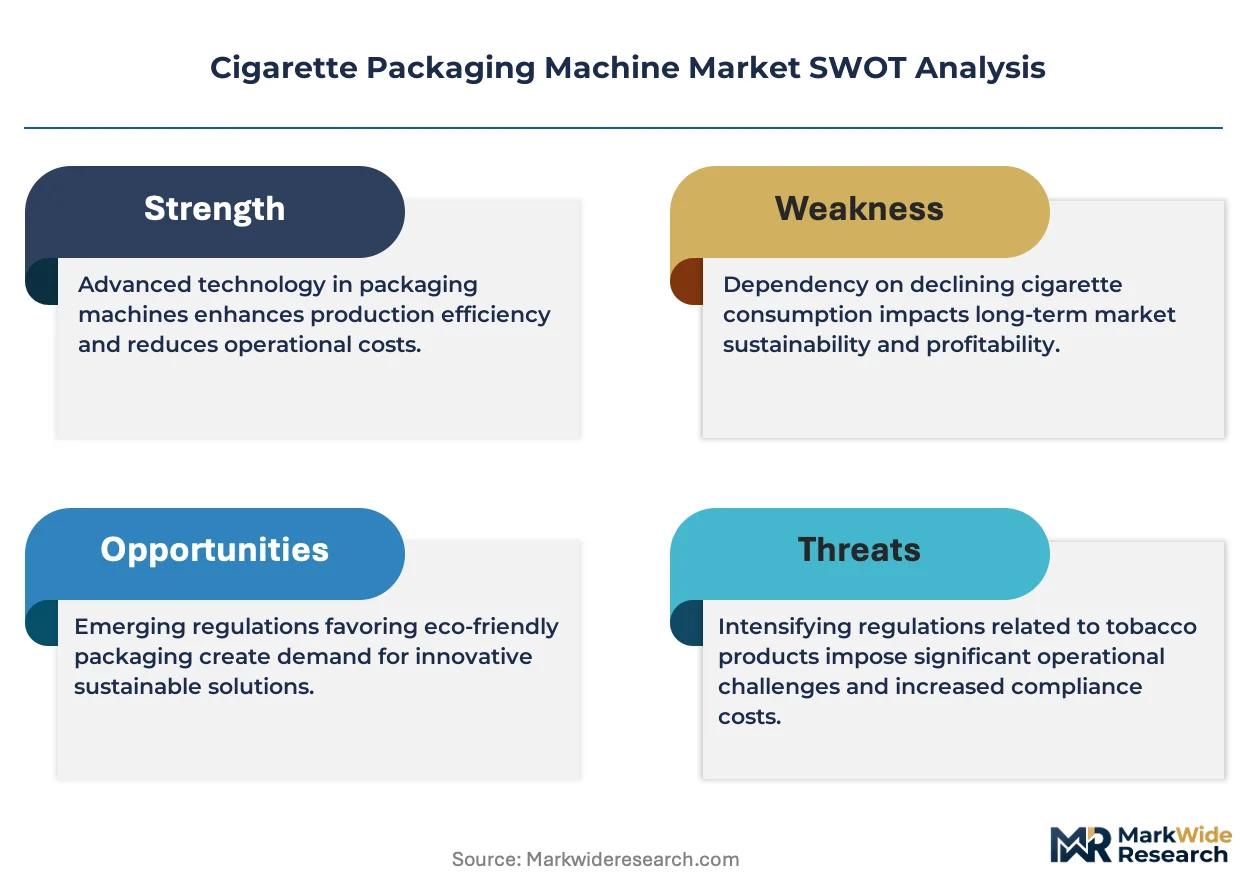
The EU Tobacco Products Directive and FCTC plain packaging protocols are forcing equipment redesigns toward neutral-format handling capabilities, while FDA regulatory pathways for modified-risk tobacco products create divergent packaging validation requirements. China's SAMR and NMPA-aligned tobacco quality standards impose additional mechanical and materials compliance layers on equipment sold into that market. Stakeholders must monitor how evolving nicotine product taxonomies across jurisdictions reshape machine specification requirements and capital allocation timelines.
Market Dynamics
Plain packaging mandates across multiple jurisdictions are forcing cigarette packaging machine manufacturers to engineer rapid format-changeover capabilities that accommodate standardized pack geometries without brand-specific tooling. This regulatory compression is restructuring capital allocation timelines and equipment specification priorities across the installed base.
Growth Catalysts
- EU Tobacco Products Directive:Plain packaging protocols in Europe are accelerating replacement cycles for legacy machines unable to handle neutral-format specifications, creating pull for flexible servo-driven platforms.
- Contract packaging expansion:Tobacco manufacturers outsourcing secondary packaging operations to specialized service providers are driving equipment procurement at third-party facilities.
- China tobacco production scale:Sustained domestic cigarette manufacturing volume sustains continuous investment in high-speed automated lines with integrated quality inspection systems.
Market Restraints
- Steel and precision component volatility:Servo motors, motion control systems, and hardened tooling materials face input cost fluctuations that compress equipment margins.
- Regulatory fragmentation:Divergent FDA modified-risk tobacco product pathways versus EU neutral-format requirements force manufacturers to maintain multiple validation protocols.
- Heat-not-burn substitution:Reduced-risk product formats are displacing conventional cigarette volumes in developed markets, constraining demand for traditional rod-handling equipment.
Strategic Opportunities
- India tobacco processing modernization:BIS-aligned quality standards and expanding domestic manufacturing capacity create white space for automated packaging system deployment.
- Digital printing convergence:Inline serialization and regional customization capabilities are opening service revenue streams beyond equipment sales.
- Hybrid machine platforms:Flexible architectures accommodating both conventional and reduced-risk product formats capture share as product portfolios diversify.
Industry Challenges
- Mechatronics talent scarcity:Servo system programming and vision-based quality inspection expertise remains concentrated among specialized engineers, constraining deployment velocity.
- Legacy system integration:Retrofitting digital control layers onto mechanical cam-driven machines requires custom engineering that extends project timelines.
- Multi-jurisdiction certification:Simultaneous FDA, EU MDR, and China NMPA compliance pathways create documentation burdens that delay commercial launch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cigarette Packaging Machine Market |
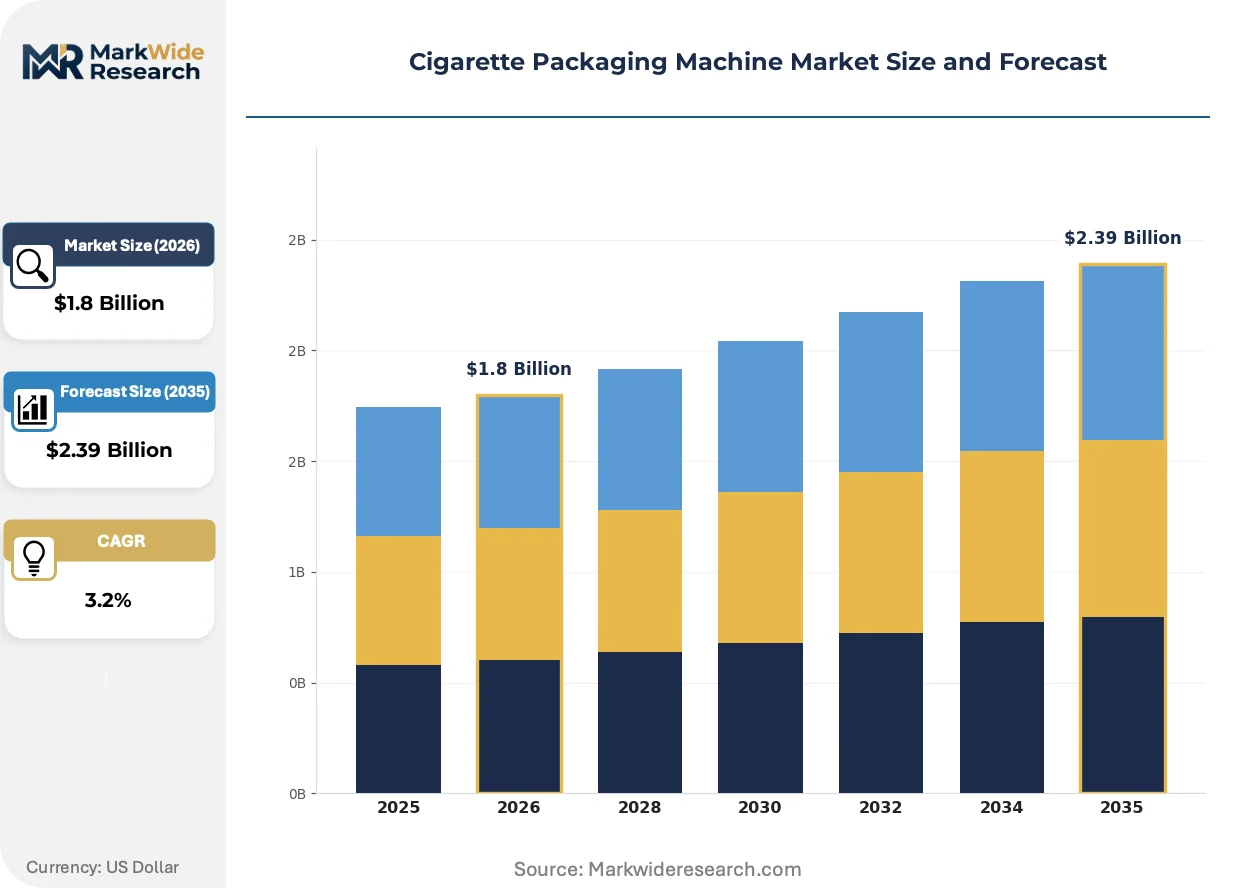
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Machines, Semi-Automatic Machines, Manual Machines, Hybrid Machines End User: Tobacco Manufacturers, Contract Packaging Companies, Retailers, Distributors Technology: Digital Printing, Flexographic Printing, Offset Printing, Gravure Printing Packaging Type: Cigarette Packs, Cartons, Tins, Sleeves |
| Companies Covered | G.D S.p.A, Hauni Maschinenbau, ITM Group, Focke & Co, Molins PLC, Proco Machinery, Sasib, Jornen Machinery, AMF Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cigarette Packaging Machine Market Emerging Trajectories
Digital control architectures and inline inspection systems are converging with regulatory traceability requirements to redefine equipment specification priorities. Machine builders are repositioning around data-enabled service models rather than standalone hardware sales.
Servo-driven motion control is replacing mechanical cam systems in high-speed packing modules, enabling format changeovers without physical tooling swaps. Contract packaging operators in Europe and North America are adopting these platforms to accommodate batch-size compression. This technology is converging with cloud-based predictive maintenance systems that reduce unplanned downtime across distributed equipment fleets.
The EU Tobacco Products Directive and FCTC plain packaging protocols are mandating standardized pack geometries that eliminate brand-differentiated tooling. Equipment manufacturers must engineer neutral-format handling capabilities that maintain throughput without product-specific change parts. Filter assembly and cartoning segments face the steepest redesign requirements as pack dimensions homogenize across member states.
After-sales service unbundling is separating maintenance contracts from original equipment purchases, particularly among mid-sized tobacco processors. Third-party technical service providers are capturing recurring revenue streams that machine builders previously monopolized. This shift is most visible in China, where domestic engineering firms are building alternative service networks around imported European equipment.
Cigarette Packaging Machine Market Segmentation
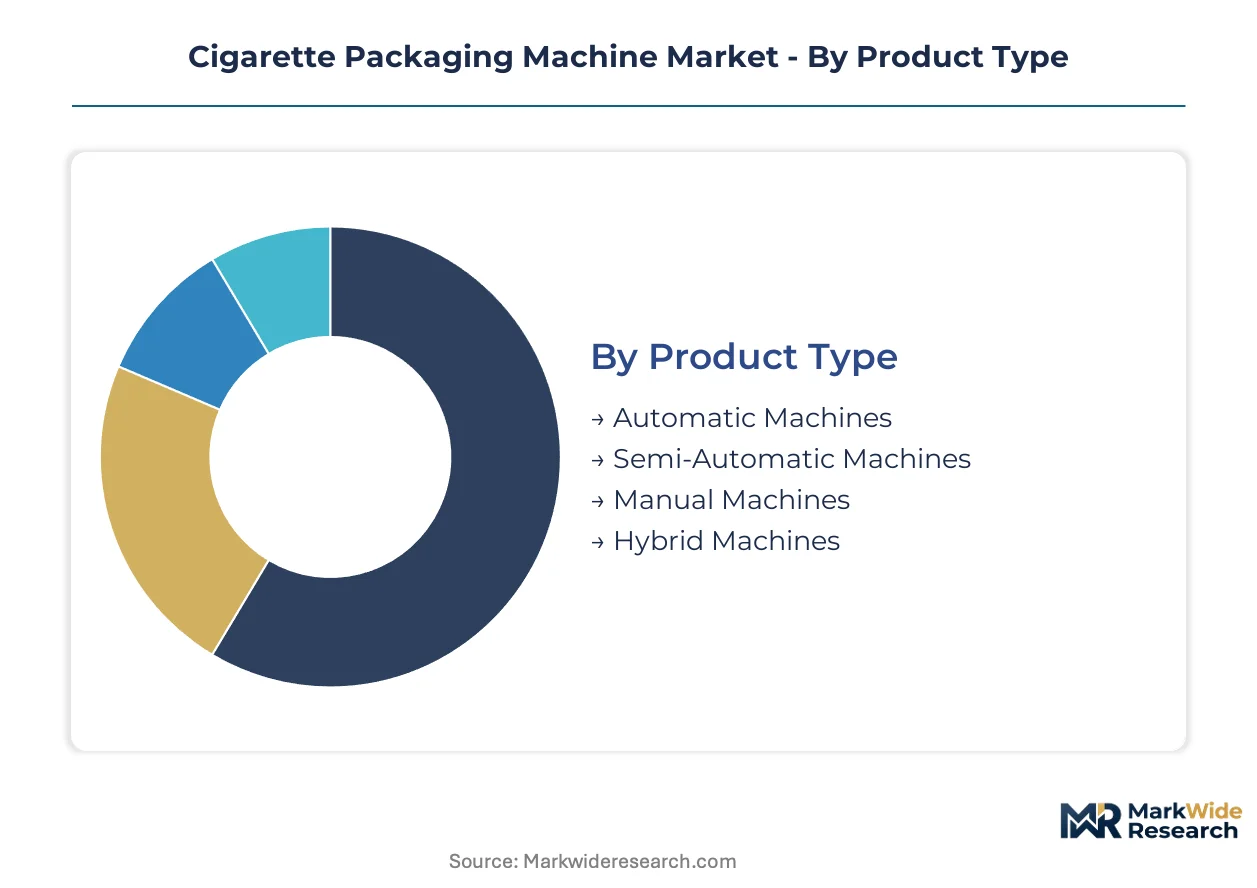
Cigarette packaging machine segmentation reflects divergent capital intensity requirements across tobacco industry stakeholders. Equipment specification priorities vary sharply between high-volume integrated manufacturers and flexible contract packaging operators serving fragmented brand portfolios.
Product Type:
The customization-to-standardization spectrum spans purpose-built high-speed lines at one extreme and adaptable hybrid platforms at the other, with procurement decisions hinging on product format diversity and batch-size economics.
- Automatic Machines:Servo-driven systems achieve speeds exceeding 10,000 units per minute with integrated vision inspection and minimal operator intervention. China tobacco production scale sustains the largest installed base of these lines, though EU Tobacco Products Directive plain packaging mandates are accelerating replacement cycles for legacy mechanical platforms. Most installed capacity flows through Automatic Machines. Expansion is steepest in Hybrid Machines.
- Hybrid Machines:Modular architectures accommodate both conventional cigarette rods and reduced-risk product formats through software-configurable handling modules rather than physical change parts. Contract packaging companies in Europe and North America are deploying these platforms to manage batch-size compression across diversified brand portfolios without dedicated tooling inventories.
- Semi-Automatic Machines:Intermediate automation levels suit regional tobacco processors with moderate throughput requirements and limited technical staffing.
- Manual Machines:Minimal capital outlay equipment persists in artisanal and small-batch premium cigar operations where hand-finishing remains a quality marker.
Procurement concentrates in automatic platforms for volume manufacturing, while hybrid configurations gain share fastest among outsourcing service providers managing format diversity.
End User:
Customer-type segmentation tracks the structural shift from captive manufacturing toward outsourced packaging services, with capital deployment patterns diverging between asset-heavy integrated producers and asset-light third-party operators.
- Tobacco Manufacturers:Integrated producers deploy continuous high-speed lines with dedicated quality inspection systems and direct ERP integration. China's state tobacco monopoly maintains the most concentrated demand, with SAMR-aligned quality standards imposing additional mechanical compliance layers on equipment specifications.
- Contract Packaging Companies:Third-party operators prioritize rapid format-changeover capabilities and modular line configurations to service multiple brand owners under short-term agreements. These firms are expanding equipment procurement as tobacco manufacturers outsource secondary packaging operations.
- Retailers:Limited direct procurement concentrates in private-label packaging arrangements for captive distribution channels.
- Distributors:Minimal equipment ownership; occasional investment in repackaging lines for regional assortment customization.
Integrated manufacturers retain the dominant installed base. Contract packaging operators are expanding capacity most aggressively.
Technology:
Print technology selection determines regulatory compliance capabilities and brand customization economics, with digital platforms displacing conventional plate-based methods in markets with serialization mandates.
- Digital Printing:Inkjet and toner-based systems enable inline serialization, regional customization, and plain packaging compliance without plate changeover delays. EU Tobacco Products Directive traceability requirements are accelerating adoption across European installations.
- Flexographic Printing:Rotary relief printing with photopolymer plates delivers cost efficiency at extended run lengths for stable brand portfolios.
- Offset Printing:Lithographic methods persist for high-graphic-quality cartons in premium market segments.
- Gravure Printing:Engraved cylinder processes maintain niche application for metallic and specialty substrate finishing.
Conventional plate-based technologies dominate current installed capacity. Digital platforms are climbing the fastest as regulatory traceability requirements expand.
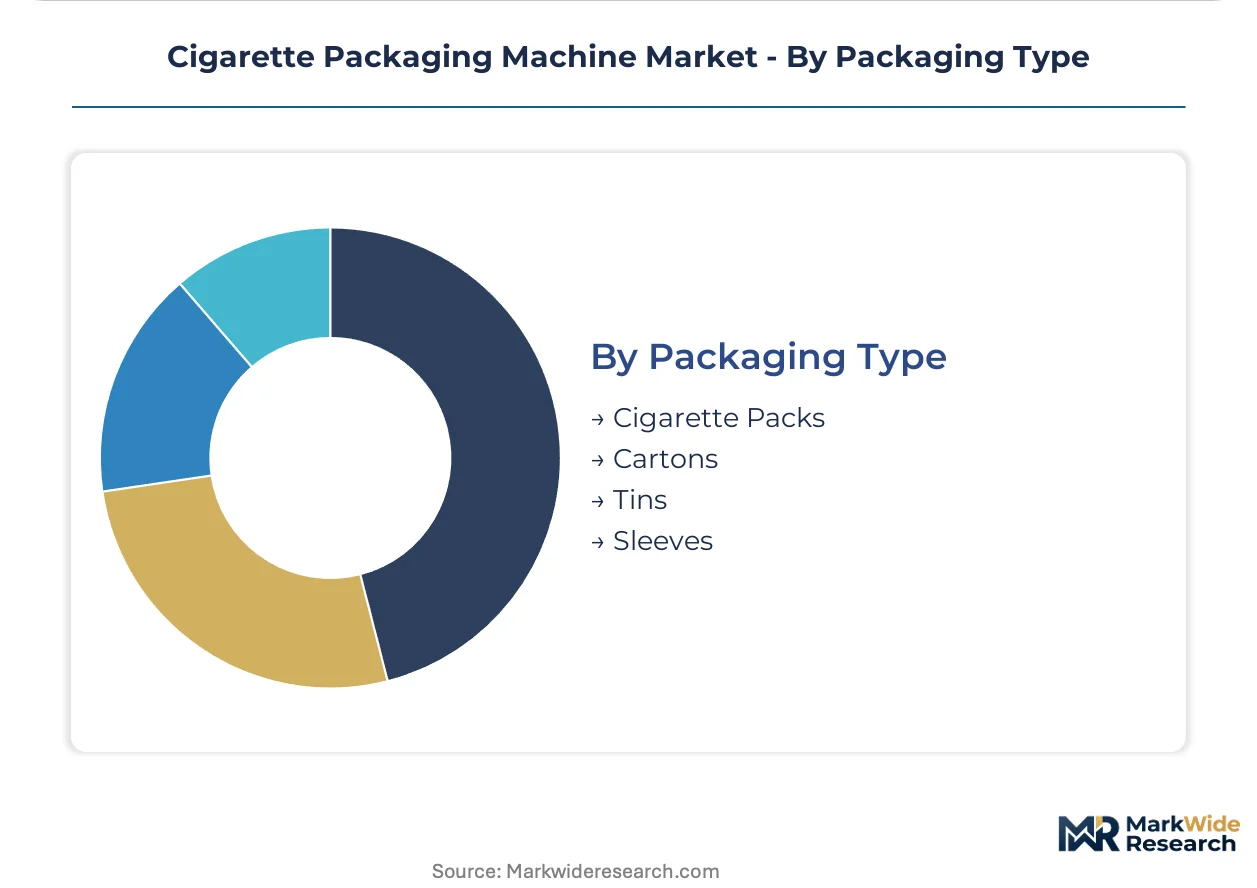
Packaging Type:
Format segmentation tracks the physical handling requirements from individual consumer units through wholesale distribution configurations, with equipment modularity enabling line reconfiguration across pack geometries.
- Cigarette Packs:Primary packaging lines form, fill, and seal 20-unit hinge-lid or soft packs at the highest speeds, with FCTC plain packaging protocols forcing neutral-format handling capabilities that eliminate brand-specific tooling.
- Cartons:Secondary bundling systems aggregate packs into 10-unit cartons for retail distribution, facing steepest redesign requirements as standardized pack dimensions homogenize across EU member states.
- Tins:Metal container handling persists in premium and travel-retail formats requiring moisture protection.
- Sleeves:Shrink-film outer wrapping for promotional and multi-pack configurations.
Pack and carton lines constitute the bulk of operational capacity. Carton handling systems face the most intensive reengineering pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing cigarette packaging machine procurement as manufacturers relocate production to jurisdictions with lower compliance-cost burdens, while plain packaging mandates in developed markets accelerate equipment replacement cycles.
China
State tobacco monopoly operations sustain the world's largest installed base of high-speed automated lines, with continuous capital deployment into integrated quality inspection systems. SAMR-aligned quality standards impose additional mechanical compliance layers on equipment specifications sold into this market. Production gravity concentrates in Yunnan and Shanghai, where domestic manufacturers operate continuous processing facilities at massive scale.
Germany
Precision engineering heritage anchors European demand for servo-driven motion control platforms capable of rapid format changeovers. EU Tobacco Products Directive plain packaging protocols force equipment redesigns toward neutral-format handling without brand-specific tooling. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host specialized retrofit service providers extending legacy asset life.
United States
Contract packaging operators are expanding equipment procurement as domestic tobacco manufacturers outsource secondary packaging operations to specialized third-party facilities. FDA modified-risk tobacco product pathways create divergent packaging validation requirements distinct from EU protocols. Manufacturing activity clusters in North Carolina and Virginia, where regional processors modernize aging mechanical cam-driven installations.
India
BIS-aligned quality standards and expanding domestic manufacturing capacity create deployment opportunities for automated packaging systems serving regional tobacco processors. Central excise structures and state-level value-added tax regimes influence capital allocation timing across the subcontinent. Industrial corridors in Gujarat and Maharashtra attract equipment investment as contract manufacturers build capacity for both domestic and export markets.
Italy
Specialized engineering firms maintain strong positions in filter assembly and cartoning segments facing steep redesign requirements from standardized pack dimension homogenization. EU MDR compliance pathways intersect with national workplace safety regulations to extend equipment certification timelines. Manufacturing concentration in Emilia-Romagna and Lombardy supports precision component supply chains for pan-European machine builders.
Cigarette Packaging Machine Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated line providers commanding premium positioning in high-volume installations while modular platform builders capture flexible-format demand. The vendor landscape organizes around three archetypes: precision-engineering houses with deep primary processing integration, specialized retrofit service providers extending legacy equipment life, and emerging modular platform builders targeting batch-size compression. Competitive moves concentrate on strategic partnerships for regional service network expansion and portfolio diversification into reduced-risk product handling capabilities.
Among European precision-engineering houses, G.D S.p.A and Hauni Maschinenbau exemplify the integrated-line archetype, with the former representing Italian engineering concentration in high-speed filter systems and the latter anchoring German mechanical processing heritage. Molins PLC occupies a distinct position within the retrofit-specialist tier, exemplifying UK-based service capabilities that extend operational life of mechanical cam-driven legacy assets. These three entities represent divergent strategic postures: full-line integration versus aftermarket service depth versus hybrid platform flexibility.
| Leading Market Players |
|---|
| G.D S.p.A |
| Hauni Maschinenbau |
| ITM Group |
| Focke & Co |
| Molins PLC |
| Proco Machinery |
| Sasib |
| Jornen Machinery |
| AMF Automation |
| Others |
Supply Flow & Price Mechanics
Captive in-house production of servo motors and precision tooling by Hauni Maschinenbau and G.D S.p.A anchors both supply security and premium pricing power for integrated line providers serving high-volume tobacco manufacturers. This backward integration insulates tier-one vendors from steel and component volatility while forcing modular competitors toward cost-plus pricing models.
Pricing Analysis
Distributor margins on European precision-engineered equipment compress pricing realization by 15-25 points before final customer delivery. Contract-based long-term offtake agreements dominate procurement between integrated manufacturers and tier-one vendors, with pricing stratifying across premium servo-driven platforms, standard mechanical retrofits, and economy-tier semi-automatic units. Cost compression in economy-tier equipment intensifies as Chinese domestic manufacturers expand export capacity. Contract packaging operators exhibit highest price sensitivity due to batch-size compression and short-term agreement structures, while state tobacco monopolies prioritize specification compliance over unit cost.
Supply Chain Analysis
CE marking and FDA equipment validation requirements gate component sourcing to qualified precision engineering suppliers concentrated in Germany, Italy, and Switzerland. Motion control systems and hardened tooling materials draw from specialized metalworking clusters in Baden-Württemberg and Lombardy. Single-source vulnerability around servo motor controllers creates procurement risk given limited qualified alternative suppliers. Distribution runs through direct OEM relationships for large installations and regional technical distributors for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by contract packaging operators trading up to flexible servo-driven platforms despite 40% capital cost premiums over mechanical alternatives.
For Market Incumbents: Extend aftermarket service unbundling to capture recurring revenue streams previously ceded to third-party technical providers, particularly in China where domestic engineering firms are building alternative networks. Deepen backward integration into motion control system production to defend margin position against steel and precision component volatility. Prioritize certification investment for FDA modified-risk tobacco product pathways alongside EU MDR compliance to maintain multi-jurisdiction coverage. For New Entrants and Emerging Players: Launch via regional technical service partnerships targeting India's BIS-aligned modernization wave, where automated packaging system deployment lags China by a full replacement cycle. White space concentrates in hybrid machine platforms for contract packaging operators managing format diversity across conventional and reduced-risk product portfolios. Prioritize modular architectures with software-configurable handling modules rather than physical change parts. For Investors and Strategic Acquirers: Roll-up economics work for specialized retrofit service providers because legacy mechanical cam-driven machines constitute 60% of installed base and face accelerating replacement pressure from plain packaging mandates. Long-term viability favors vendors with integrated line capabilities spanning primary processing through secondary packaging. Watch FDA modified-risk tobacco product approval velocity as inflection indicator for capital allocation toward reduced-risk handling platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Control Architecture Migration | Servo-driven platforms enable format changeovers without physical tooling swaps, addressing EU Tobacco Products Directive requirements. |
| Backward Integration into Motion Control | In-house servo motor production insulates Hauni Maschinenbau from component volatility and sustains premium pricing. |
| Regional Service Network Expansion | Third-party technical providers in China capture recurring maintenance revenue from imported European equipment fleets. |
| Hybrid Platform Development | Modular architectures accommodate both conventional cigarettes and reduced-risk formats for contract packaging diversification. |
| Inline Digital Printing Convergence | Serialization compliance and regional customization capabilities open service revenue streams beyond hardware sales. |
Methodological Framework
Multiple input streams — executive interviews with equipment procurement directors at tobacco manufacturers, technical consultations with contract packaging operators, and regulatory affairs discussions with compliance officers — were reconciled against secondary validation from EU Tobacco Products Directive implementation reports, FDA modified-risk tobacco product pathway filings, and China SAMR quality standard documentation. Bottom-up equipment shipment tallies and top-down tobacco production capacity estimates were triangulated to anchor market sizing.
Historical replacement cycle patterns were cross-referenced against panel input from plant engineers and aftermarket service heads to construct demand projections across the analysis window. Segmentation modeling incorporated machine type, end-user category, print technology, and packaging format dimensions. CAGRs were derived from equipment procurement intention surveys and capital expenditure disclosure patterns, with specific weighting applied to China's state tobacco monopoly investment schedules and EU plain packaging mandate compliance timelines.
Several conditions sit outside the modeled scope, including potential heat-not-burn product substitution velocity beyond baseline assumptions and unforeseen tariff restructuring affecting precision component trade flows. Forecasts reflect documented assumptions about regulatory implementation timing and capital allocation continuity. Deviation in FDA modified-risk tobacco product approval rates or EU member state plain packaging enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Global Pet Stretch Blow Molding Machines Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Carton Erecting Machinery Market
Packaging Machinery
Tamper Evidence Machinery Market
Packaging Machinery
Tissue Paper Embosser Machine Market
Packaging Machinery
Vial Capping Machines Market
Packaging Machinery
Plastic Extruding Equipment Market
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Multi-Head Filling Machines Market
Packaging Machinery
Enveloping & Stacking Machine Market
Packaging Machinery
Piston Fillers Market
Packaging Machinery
Auger Powder Filling Machines Market
Packaging Machinery
Horizontal Strapping Machine Market
Packaging Machinery
Cup Filling Machine Market
Packaging Machinery
Europe Blow Molding Machine Market
Packaging Machinery
Thermoform Fill Sealing Machine Market