
 Corrugated Box Machines Market | 2026-2036
Corrugated Box Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Box Machines Market Outlook
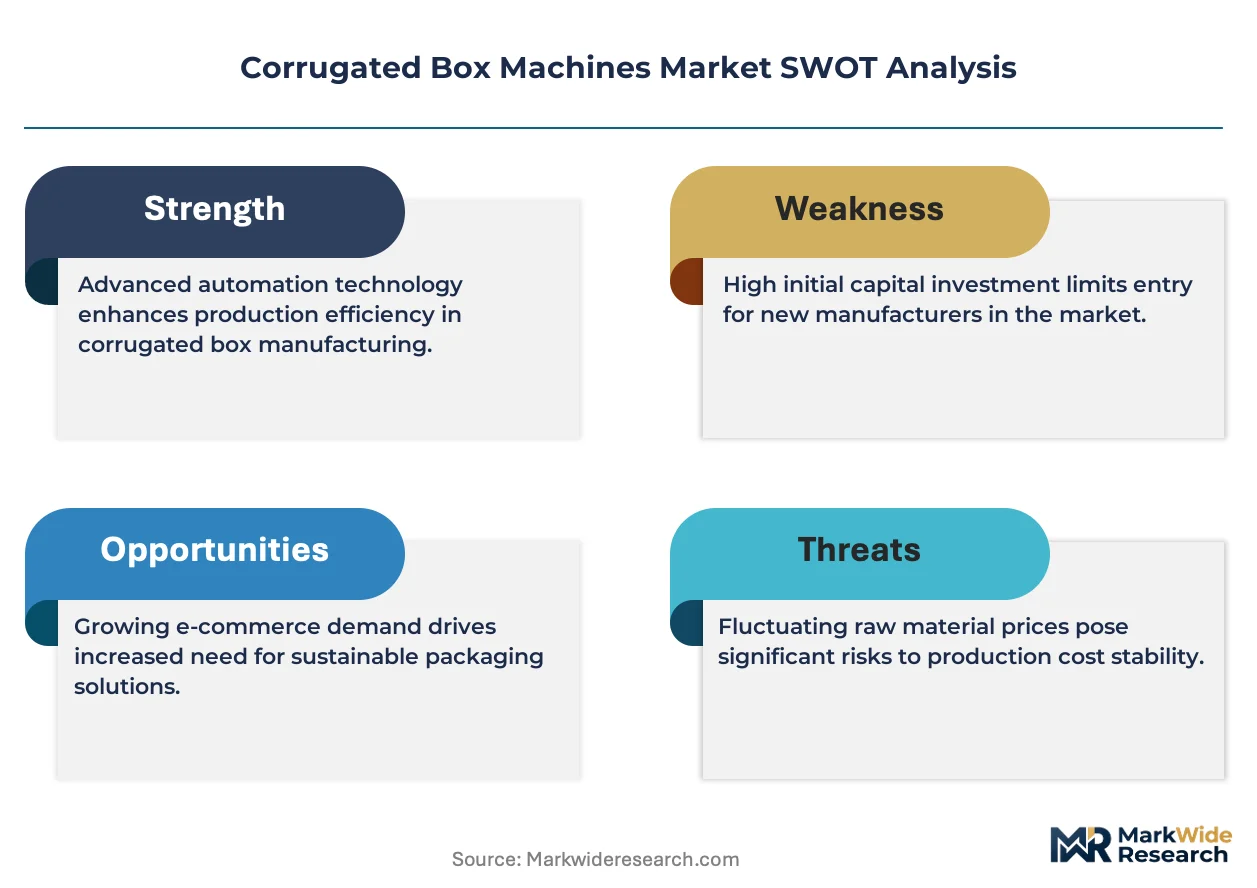
China's corrugated board capacity expansion is rewriting supply dynamics across Asia. BHS Corrugated Maschinen- und Anlagenbau GmbH anchors German engineering credibility in high-speed corrugators. Shengli Carton Equipment Manufacturing Co., Ltd. dominates domestic replacement cycles with cost-competitive folder-gluer lines. Bobst Group SA leverages its Swiss precision heritage to control premium die-cutter installations across European packaging converters.
Corrugated box machines form a capital equipment category encompassing slotters, gluers, die cutters, and folders that convert kraft linerboard and fluted medium into finished shipping containers through sequential cutting, creasing, folding, and adhesive bonding operations. Electric drive technology leads new installations for energy efficiency and servo-controlled registration accuracy, while semi-automated solutions retain strong positions among mid-tier converters balancing throughput against capital constraints. The pharmaceutical end-user segment demands validated washdown-capable machines with full batch traceability, creating margin pools distinct from commodity food and beverage applications.
EU F-Gas Regulation and REACH compliance shape refrigerant choices in heated glue systems and limit certain adhesive chemistries, while China's GB standards enforce energy efficiency ratings on electric motor drives. ISO 9001 quality management and CE marking remain baseline requirements for export market access. Stakeholders must weigh automation depth against labor cost trajectories and energy price volatility when configuring machine procurement portfolios.
Market Dynamics
Converter consolidation across China's Yangtze River Delta manufacturing cluster is compressing procurement timelines and forcing equipment vendors to bundle digital controls with mechanical platforms. This concentration dynamic is reshaping how corrugator lines are specified, financed, and commissioned across Asia's board-producing heartland.
Growth Catalysts
- E-commerce fulfillment infrastructure:Automated sortation hubs in Germany are expanding high-speed folder-gluer procurement as parcel volumes surge through centralized distribution nodes.
- EU Green Deal packaging directives:Tightened waste reduction mandates are accelerating replacement of solvent-based adhesive systems with hot-melt alternatives in heated glue applications.
- Servo-controlled registration technology:Electric drive retrofits are penetrating mid-tier converter installations seeking registration accuracy without full line replacement.
Market Restraints
- Kraft linerboard input volatility:Pulp price swings compress converter margins and delay capital equipment commitments across cyclical demand periods.
- German engineering supply concentration:High-speed corrugator technology clusters among a narrow vendor base in Baden-Württemberg, creating procurement bottlenecks during capacity crunches.
- REACH adhesive chemistry restrictions:ECHA limitations on specific bonding agents force formulation changes that extend machine validation cycles.
Strategic Opportunities
- Indian pharmaceutical packaging:Washdown-capable die-cutters with full batch traceability remain underdeployed in Mumbai-Pune corridor converter networks.
- Japan METI carbon efficiency standards:Energy performance mandates for industrial electric motors create upgrade incentives for aging corrugator drive systems.
- Digital twin integration:Convergence of predictive maintenance software with legacy mechanical platforms opens service revenue streams for equipment vendors.
Industry Challenges
- Servo technician scarcity:Converter maintenance teams lack depth in electric drive diagnostics, extending downtime during registration drift events.
- CE marking timeline compression:Accelerated EU market entry requirements strain documentation resources for Asian equipment exporters.
- Legacy mechanical integration:Pneumatic-to-electric control retrofits encounter synchronization failures with existing folder section timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Box Machines Market |
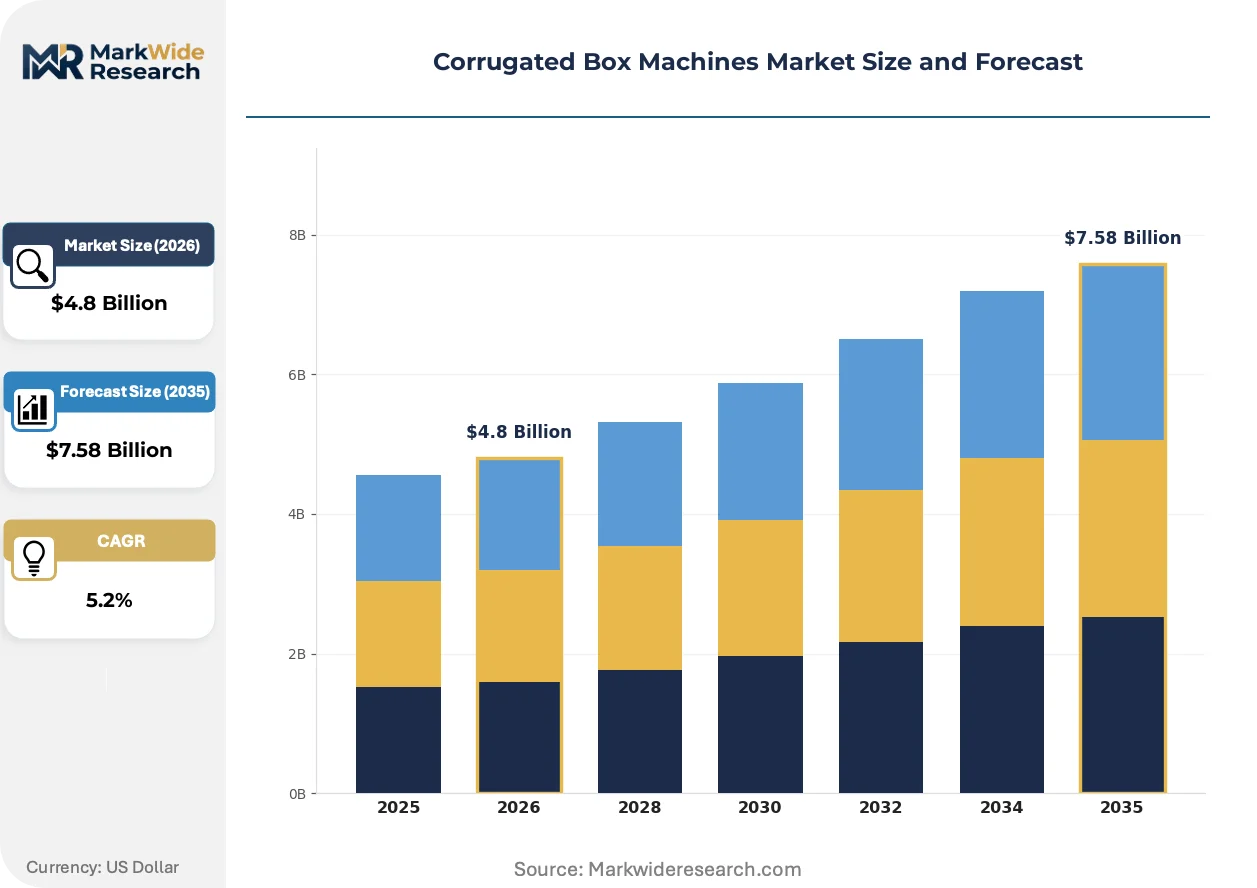
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slotter, Gluer, Die Cutter, Folder Technology: Hydraulic, Pneumatic, Electric, Mechanical End User: Packaging, Food & Beverage, Electronics, Pharmaceutical Solution: Automated, Semi-Automated, Manual, Customizable |
| Companies Covered | Shengli Carton Equipment Manufacturing Co., Ltd., Natraj Corrugating Machinery Company, BHS Corrugated Maschinen- und Anlagenbau GmbH, Shanghai Printyoung International Industry Co., Ltd., QINGDAO AOPACK ON DEMAND PACKAGING Co., Ltd., Bobst Group SA, Foshan Fuli Packaging Machinery Co., Ltd., Acme Machinery India Pvt. Ltd., Mitsubishi Heavy Industries (MHI) Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Box Machines Market Strategic Shifts
Digital control architectures are penetrating corrugated box machinery faster than mechanical platform replacement cycles, creating a bifurcated market where software-defined performance separates vendor tiers. This shift is compressing the value capture window for pure hardware suppliers.
Servo-actuated die-cutting technology is hybridizing mechanical precision with software-controlled registration adjustment. Pharmaceutical converters in Switzerland and Germany are adopting these platforms for validated short-run production. The technology is hybridizing quality assurance protocols with throughput optimization, enabling batch-size-one economics previously confined to folding carton applications.
China's GB standards for electric motor energy efficiency are tightening enforcement timelines through provincial environmental bureaus. Converter procurement committees in Guangdong and Jiangsu provinces now require Tier-1 efficiency ratings as gate criteria. High-speed corrugator installations in these provinces are accelerating motor replacement ahead of regulatory deadlines.
Maintenance contract unbundling is fragmenting traditional equipment vendor relationships. Mid-tier converters in Italy and Spain are sourcing predictive analytics from third-party industrial software providers rather than OEM service departments. This pattern is most visible among independent converter networks with multi-vendor machine parks seeking unified downtime visibility.
Corrugated Box Machines Market Segmentation
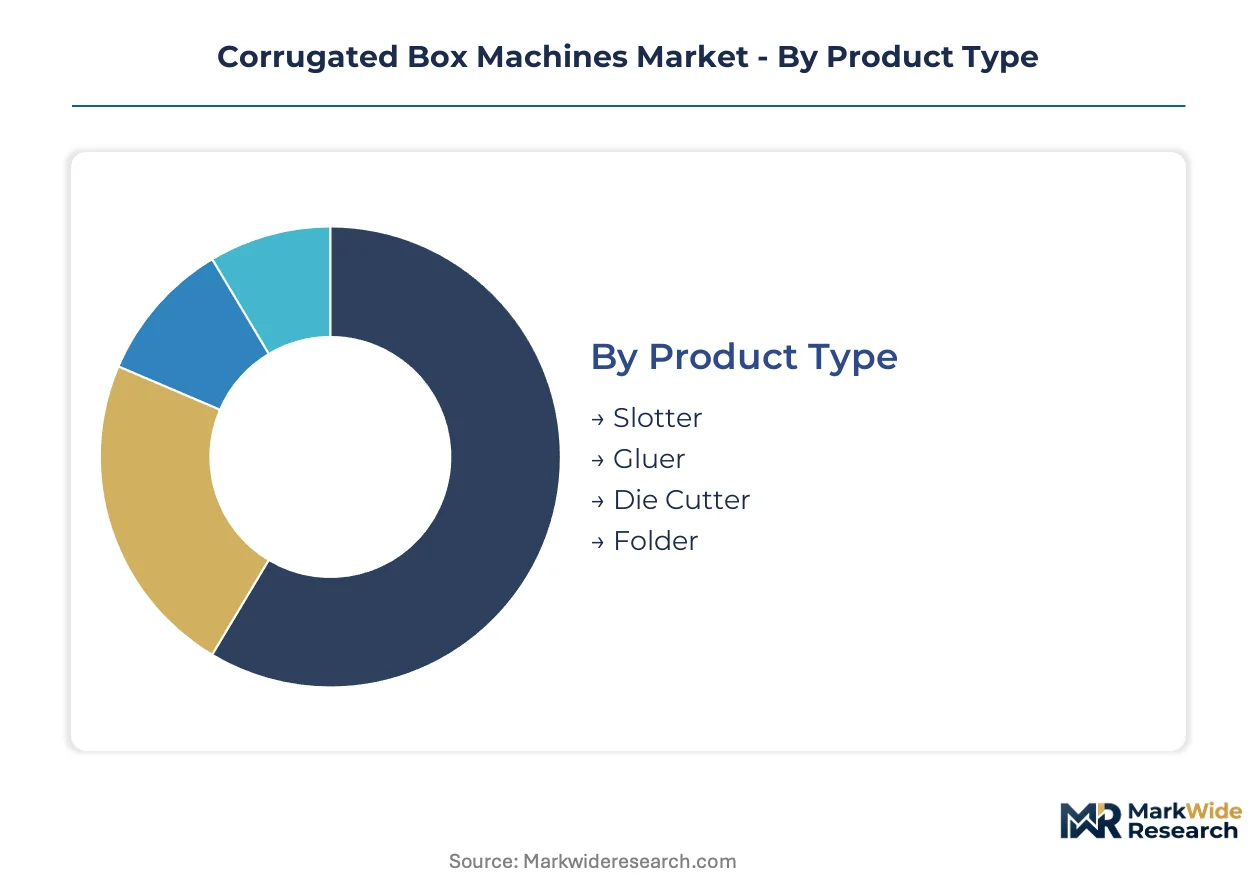
Corrugated box machine procurement patterns diverge sharply by production scale and end-use validation requirements. Converter capital allocation decisions cascade across technology choices, automation depth, and regulatory compliance tiers.
Product Type:
Machine selection tracks the complexity of finished container specifications demanded by downstream fulfillment networks.
- Slotter:Rotary and platen configurations score corrugated board for folding along precise geometric axes. E-commerce fulfillment centers in Germany specify high-speed rotary slotters to match automated sortation hub throughputs.
- Gluer:Folder-gluer lines apply hot-melt or cold adhesives to form sealed container joints. China's Yangtze River Delta converters are consolidating procurement around servo-controlled gluers with heated glue systems that satisfy EU Green Deal adhesive chemistry mandates.
- Die Cutter:Flatbed and rotary die cutters stamp complex geometries including display windows and hand holes.
- Folder:Inline folding sections integrate with corrugator exits to collapse board into flattened box blanks.
The dominant share belongs to gluer installations, while die cutter specifications are climbing fastest on pharmaceutical validation requirements.
Technology:
Drive system choices reflect the tension between energy efficiency mandates and legacy infrastructure amortization schedules.
- Electric:Servo motor architectures deliver sub-millimeter registration accuracy with programmable motion profiles. Japan's METI carbon efficiency standards for industrial motors are accelerating electric drive retrofits in Osaka-Kobe packaging clusters.
- Pneumatic:Compressed air systems retain installed base dominance among mid-tier European converters.
- Hydraulic:High-force applications in heavy-board corrugators maintain niche demand.
- Mechanical:Cam-driven timing systems persist in emerging market installations where capital constraints outweigh precision requirements.
Electric platforms now command the technology mix, with pneumatic-to-electric conversions expanding most quickly in energy-price-volatile jurisdictions.
End User:
Validation protocols and washdown requirements fragment demand across sector-specific specification tiers.
- Pharmaceutical:Washdown-capable machines with full batch traceability and IQ/OQ/PQ documentation support FDA and EMA compliance. Swiss and German converters serving Novartis and Roche networks specify validated short-run die-cutting platforms.
- Food & Beverage:Hygienic design standards for direct food contact packaging drive stainless-steel specification clauses.
- Electronics:Anti-static materials handling and precision void-fill integration characterize semiconductor packaging lines.
- Packaging:General-purpose converter networks serving multi-sector demand prioritize changeover speed over specialized validation.
Pharmaceutical specifications capture the premium tier, while food and beverage replacement cycles are gaining share fastest on sustainability-driven format changes.
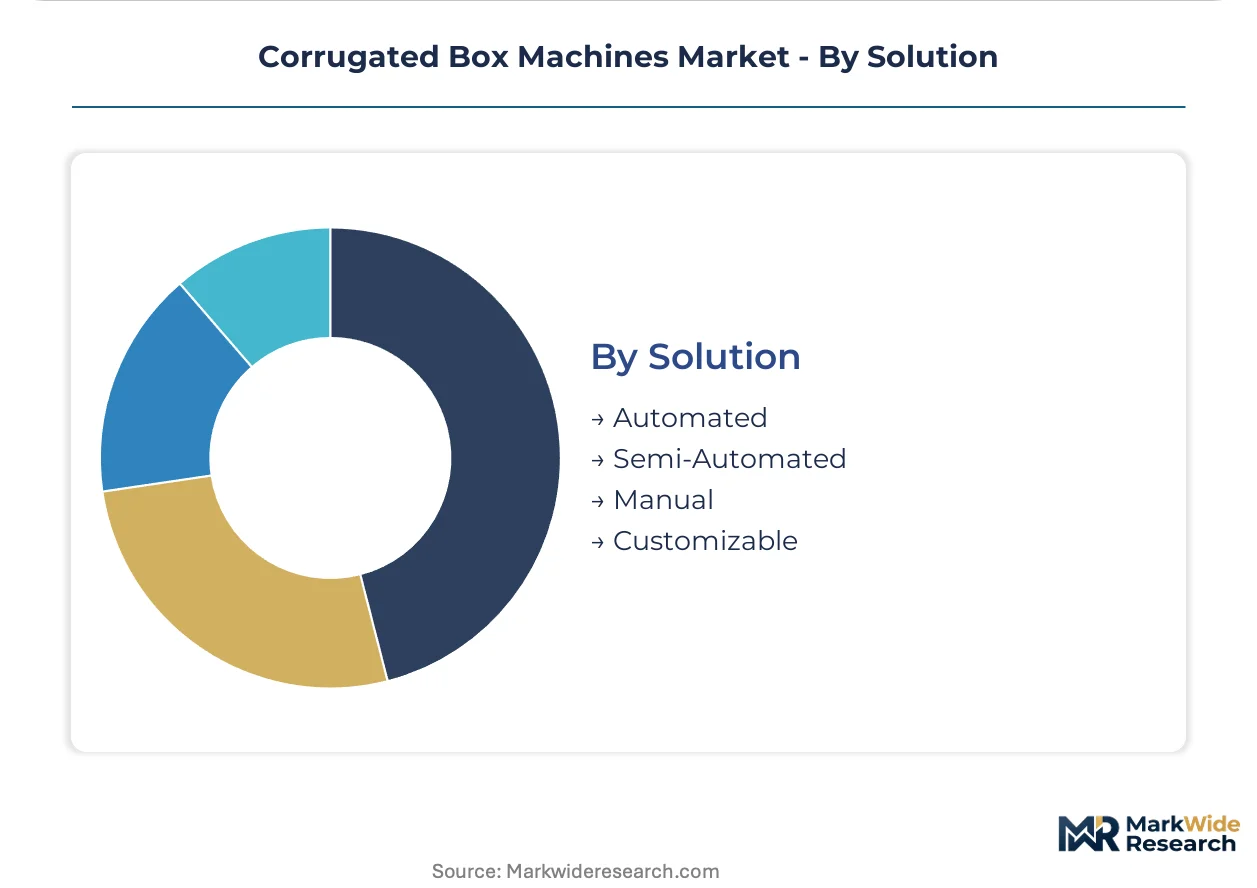
Solution:
Automation depth selection correlates with labor cost trajectories and order lot size distributions.
- Automated:Fully integrated lines with robotic material handling and automated setup changeover minimize operator intervention. Amazon and Zalando fulfillment networks in Germany specify lights-out folder-gluer installations for parcel volume peaks.
- Semi-Automated:Operator-assisted loading and quality inspection balance throughput against capital deployment.
- Manual:Hand-fed configurations persist in artisanal packaging and prototype short runs.
- Customizable:Modular architectures allow field reconfiguration between box styles and board grades.
Semi-automated solutions retain volume leadership, though automated lines are expanding most quickly in labor-constrained Northern European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB standards for electric motor energy efficiency are tightening enforcement timelines through provincial environmental bureaus. Converter procurement committees in Guangdong and Jiangsu provinces now require Tier-1 efficiency ratings as gate criteria. This regulatory pressure is reshaping equipment replacement cycles across Asia's board-producing heartland.
Germany
Automated sortation hubs in Germany are expanding high-speed folder-gluer procurement as parcel volumes surge through centralized distribution nodes. The EU Green Deal packaging directives are tightening waste reduction mandates and accelerating replacement of solvent-based adhesive systems with hot-melt alternatives. Baden-Württemberg engineering clusters anchor high-speed corrugator technology development.
China
Converter consolidation across the Yangtze River Delta manufacturing cluster is compressing procurement timelines and forcing equipment vendors to bundle digital controls with mechanical platforms. GB standards enforce energy efficiency ratings on electric motor drives through provincial environmental bureaus. Guangdong and Jiangsu provinces now require Tier-1 efficiency ratings as procurement gate criteria.
India
Washdown-capable die-cutters with full batch traceability remain underdeployed in Mumbai-Pune corridor converter networks serving pharmaceutical packaging demand. CDSCO pharmaceutical regulations drive validated equipment specifications for FDA and EMA compliance. The Maharashtra industrial belt is seeing accelerated converter investment in IQ/OQ/PQ documentation-capable platforms.
Japan
METI carbon efficiency standards for industrial electric motors are creating upgrade incentives for aging corrugator drive systems in Osaka-Kobe packaging clusters. Energy performance mandates are accelerating electric drive retrofits among mid-tier converters. The Kansai region is experiencing concentrated motor replacement activity ahead of regulatory enforcement deadlines.
Switzerland
Swissmedic pharmaceutical regulations and precision manufacturing heritage are driving adoption of servo-actuated die-cutting technology for validated short-run production. Swiss and German converters serving Novartis and Roche networks specify platforms with full batch traceability. The Basel pharmaceutical corridor is concentrating premium die-cutter installations with hybrid mechanical-software control architectures.
Corrugated Box Machines Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. German engineering specialists anchor high-speed corrugator technology through precision manufacturing heritage. Chinese fabricators dominate domestic replacement cycles with cost-competitive folder-gluer lines. Swiss precision players control premium die-cutter installations across European pharmaceutical converters. Competitive dynamics center on bundling digital control software with mechanical platforms and accelerating predictive maintenance service revenue streams.
Among German-based engineering specialists, BHS Corrugated Maschinen- und Anlagenbau GmbH exemplifies the high-speed corrugator archetype rooted in Baden-Württemberg manufacturing clusters. Bobst Group SA occupies a position within the Swiss precision tier, representing validated short-run production capabilities for pharmaceutical converter networks. Shengli Carton Equipment Manufacturing Co., Ltd. anchors the Chinese domestic replacement cycle segment, exemplifying cost-competitive folder-gluer supply for Yangtze River Delta converter consolidation.
| Leading Market Players |
|---|
| Shengli Carton Equipment Manufacturing Co., Ltd. |
| Natraj Corrugating Machinery Company |
| BHS Corrugated Maschinen- und Anlagenbau GmbH |
| Shanghai Printyoung International Industry Co., Ltd. |
| QINGDAO AOPACK ON DEMAND PACKAGING Co., Ltd. |
| Bobst Group SA |
| Foshan Fuli Packaging Machinery Co., Ltd. |
| Acme Machinery India Pvt. Ltd. |
| Mitsubishi Heavy Industries (MHI) Group |
| Others |
Value Chain & Pricing Dynamics
Baden-Württemberg's precision engineering clusters concentrate high-speed corrugator manufacturing capacity, granting German OEMs substantial pricing leverage over converter procurement committees across Europe and Asia. This geographic concentration of technical capability translates into premium capture for servo-controlled registration systems and extended validation documentation.
Pricing Analysis
German-to-Chinese price spreads of 40-60% persist across equivalent mechanical specifications, though the gap narrows for digitally bundled platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by automation depth and after-sales service bundling. Pricing pressure stems from Yangtze River Delta converter consolidation demanding volume discounts for multi-line orders. Mid-tier European converters exhibit highest price sensitivity due to kraft linerboard margin compression, while pharmaceutical end-users prioritize validation capability over unit cost.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk calculations for European converter networks sourcing Asian-manufactured folder-gluer components. Equipment manufacturing concentrates in Germany, China, and Switzerland, with servo motor drives drawing from Japanese and South Korean component suppliers. Raw material dependencies span precision-machined steel frames, high-torque electric motors, and heated glue system ceramics. Distribution runs through OEM-direct sales for large corrugator lines and regional distributor networks for mid-tier folder-gluer installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. CE marking and FDA validation documentation create switching costs that lock pharmaceutical converters into established vendor relationships.
For Market Incumbents: Insulate service revenue streams by embedding predictive maintenance software into legacy mechanical platforms before third-party industrial analytics providers capture converter relationships. Accelerate backward integration into servo motor supply to offset Japanese and South Korean component vulnerability. Prioritize certification investment for EU F-Gas Regulation compliance in heated glue systems to preempt formulation-forced validation cycles. For New Entrants and Emerging Players: Build out digital twin integration capabilities for mid-tier Italian and Spanish converter networks seeking unified downtime visibility across multi-vendor machine parks. The most penetrable white space sits in Mumbai-Pune corridor pharmaceutical packaging, where washdown-capable die-cutters with IQ/OQ/PQ documentation remain underdeployed. Pursue channel partnerships with regional distributor networks rather than OEM-direct competition. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because converter procurement committee consolidation across China's Yangtze River Delta compresses vendor counts and rewards scale. Target acquisition archetypes include Swiss precision die-cutter specialists with validated short-run pharmaceutical capabilities and German engineering firms with stranded mechanical platforms ripe for digital retrofit. Watch for inflection when METI carbon efficiency standards trigger accelerated motor replacement waves in Japan's Kansai region.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Control Bundling | Bundling servo-controlled registration software with mechanical platforms captures converter upgrade budgets in Guangdong. |
| Predictive Maintenance Service | Third-party analytics unbundling threatens OEM service revenue across Italian and Spanish converter networks. |
| Energy Efficiency Retrofit | GB Tier-1 motor ratings enforcement in Jiangsu province accelerates replacement demand for aging drive systems. |
| Pharmaceutical Validation Investment | Swissmedic and CDSCO compliance documentation opens margin pools distinct from commodity food packaging. |
| Regional Distributor Channel Control | Mid-tier converter consolidation in Yangtze River Delta rewards distributors with localized technical service capability. |
Study Parameters
Cross-validation between primary interviews with converter maintenance directors and secondary analysis of customs equipment import data anchors the qualitative findings. Plant engineers, OEM procurement teams, aftermarket service heads, and regulatory compliance officers at pharmaceutical packaging operations provided operational perspective. Trade association publications, provincial environmental bureau enforcement notices, and equipment vendor technical documentation supplied external validation. Bottom-up demand modeling triangulated against top-down sectoral capex estimates.
Calibration against historical procurement cycle timing and regulatory enforcement phase-ins shaped the projection framework. Segmentation dimensions span machine type, drive technology, automation depth, end-use validation tier, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and capacity expansion announcements. Kraft linerboard price volatility and EU Green Deal implementation pace served as key forecast sensitivity inputs.
Stress conditions across pulp input cost spikes, REACH adhesive chemistry restriction expansions, and METI enforcement acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding converter consolidation velocity and digital adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Tablet Packing Machine Market
Packaging Machinery
Straw Machine Market
Packaging Machinery
Box Sealing Machines Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Vial Capping Machines Market
Packaging Machinery
Horizontal Flow Wrapping Machines Market
Packaging Machinery
Hardgel Liquid Capsule Filling Machines Market
Packaging Machinery
EPS Pre-Expander Machines Market
Packaging Machinery
Global Filling Machines Market
Packaging Machinery
Screw Capping Machines Market
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Wicketed Bagging Machines Market
Packaging Machinery
Enveloping & Stacking Machine Market
Packaging Machinery
Pre-Made Pouch Packaging Machines Market
Packaging Machinery
Blow Fill Seal (BFS) Technology Market
Packaging Machinery
Pallet Drum Filler Capper Market