
 Global Food and Beverage Packaging Machinery Market | 2026-2036
Global Food and Beverage Packaging Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food and Beverage Packaging Machinery Market Analysis
After-sales service contracts and predictive maintenance software is expanding as a recurring revenue layer that reshapes how OEMs monetize installed bases. Krones AG leverages its global service network to lock in long-term client retention. Syntegon Technology GmbH differentiates through deep specialization in pharmaceutical-grade hygiene systems that cross-apply to sensitive beverage segments. GEA Group anchors its position with extensive backward integration into control systems and process engineering.
Food and beverage packaging machinery encompasses integrated equipment systems that form, fill, seal, label, and wrap consumable products at throughput rates ranging from 100 to 2,000 units per minute, with primary functions spanning material handling, product metering, atmosphere modification, and final package closure. Form-fill-seal machines dominate capital deployment across high-volume snack and dairy operations where line efficiency determines unit economics. Ultrasonic sealing technology is displacing conventional heat-seal methods in flexible packaging lines for confectionery, driven by narrower seal widths that reduce film usage and energy draw. Vacuum packaging equipment sustains premium positioning in protein and prepared meal segments where shelf-life extension commands disproportionate margin capture.
EU F-Gas Regulation and FDA cGMP standards jointly dictate refrigerant choices in cooling tunnels and hygienic design protocols for liquid filling systems, raising compliance costs for equipment sold into transatlantic supply chains. ECHA REACH restrictions on chemical additives in food-contact materials are forcing machinery OEMs to validate seal and conveyor components for migration compliance before system commissioning. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's packaging reuse targets redirect R&D spending toward modular, format-flexible platforms that accommodate regulatory shifts without full line replacement.
Market Dynamics
Ultrasonic sealing technology is compressing film consumption in flexible packaging lines while EU F-Gas Regulation forces refrigerant retrofits in cooling tunnels, creating simultaneous cost and compliance pressures across transatlantic supply chains.
Growth Catalysts
- EU Green Deal packaging reuse targets:Mandatory recyclable-compatible format requirements are accelerating equipment replacement cycles among dairy processors seeking to avoid non-compliance penalties.
- Aseptic filling automation:Dairy and sensitive beverage segments are deploying automated lines to reduce contamination risk and extend shelf-life capture in premium positioning.
- Germany machinery cluster concentration:Dense supplier networks around Krones AG and Syntegon Technology are shortening procurement lead times and technical service response for European processors.
Market Restraints
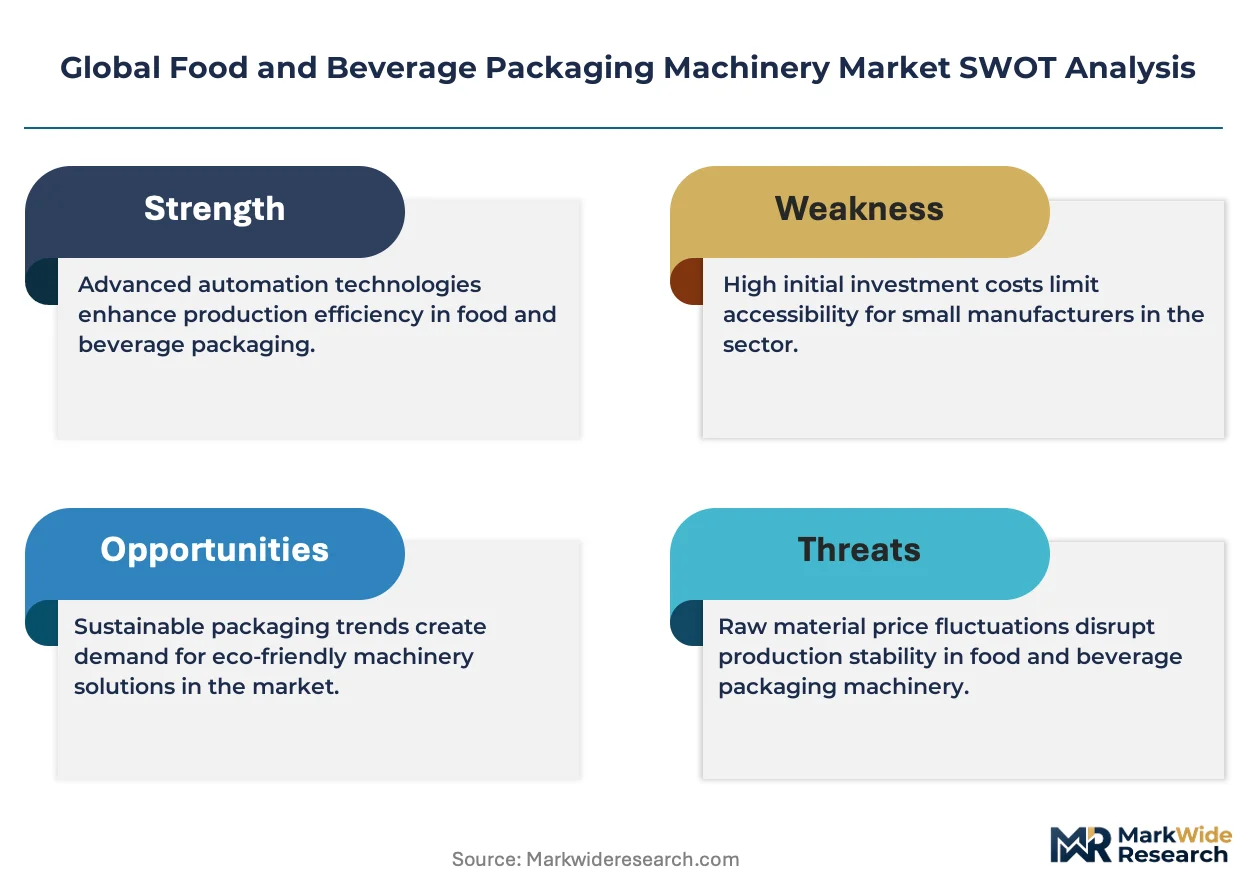
- Fluorinated gas input cost volatility:F-Gas phase-down quotas are constraining refrigerant supply for cooling tunnel retrofits, inflating service contract pricing for legacy installed bases.
- Control systems supply concentration:Backward-integrated OEMs dominate proprietary automation architectures, limiting third-party maintenance access and inflating total cost of ownership.
- Heat-seal technical limitation:Conventional thermal sealing methods face energy efficiency ceilings and wider seal widths that increase film waste versus ultrasonic alternatives.
Strategic Opportunities
- India PLI scheme manufacturing incentives:Production-linked incentives for food processing equipment are attracting machinery OEMs to establish local assembly for domestic dairy and beverage demand.
- Predictive maintenance software convergence:Integration of IoT sensors with machine learning analytics is enabling outcome-based service contracts that monetize uptime guarantees rather than spare parts.
- Modular platform regulatory tailwind:Format-flexible line architectures that accommodate EU packaging waste directive shifts without full replacement are capturing premium positioning among risk-averse buyers.
Industry Challenges
- Migration compliance certification timelines:ECHA REACH validation requirements for food-contact seal and conveyor components are extending commissioning schedules and inflating pre-market testing costs.
- Legacy control architecture integration friction:Retrofitting predictive maintenance modules into existing PLC systems requires specialized automation engineering talent that concentrates in German and Swiss machinery clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food and Beverage Packaging Machinery Market |
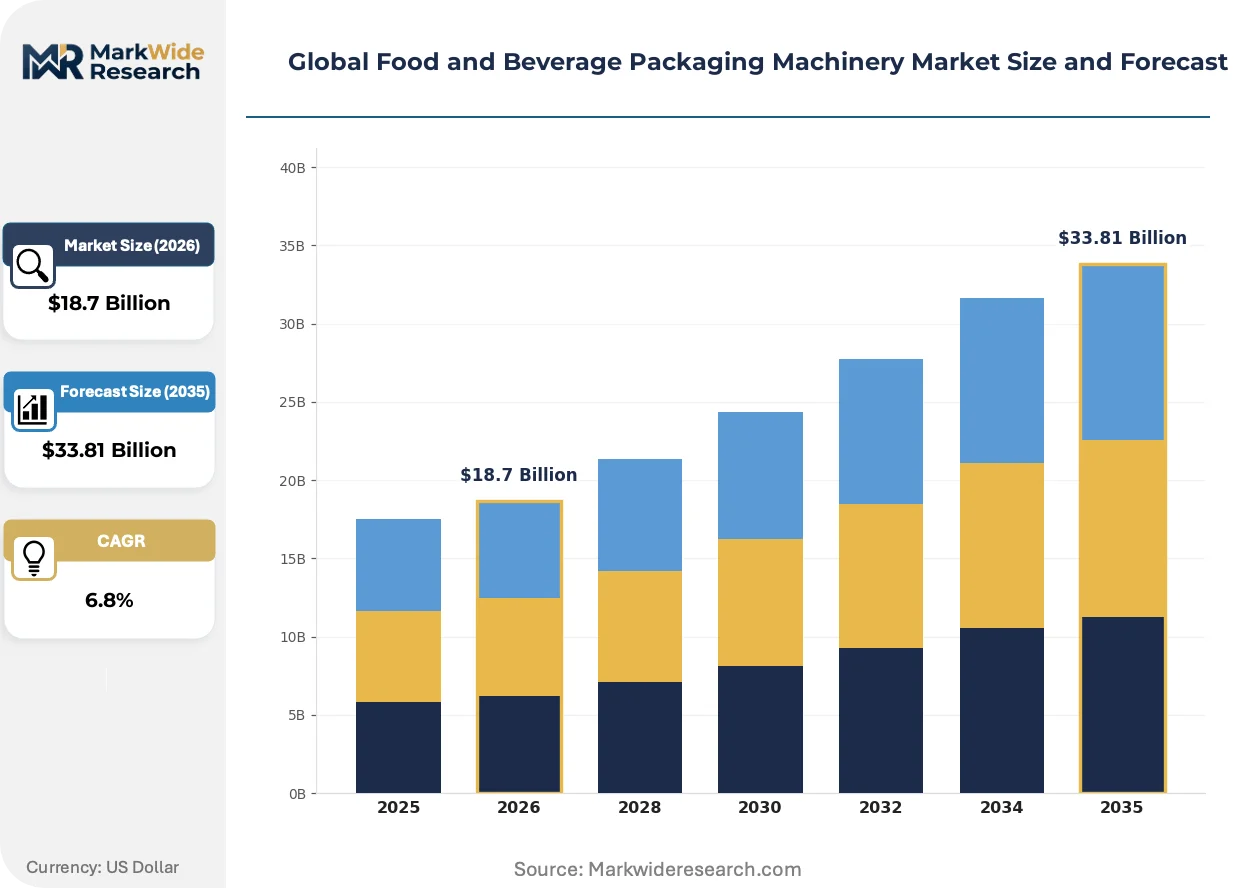
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Form-Fill-Seal Machines, Labeling Machines, Wrapping Machines, Capping Machines Technology: Vacuum Packaging, Inert Gas Flush, Thermoforming, Ultrasonic Sealing End User: Snack Foods, Beverages, Dairy Products, Confectionery Automation Level: Fully Automated, Semi-Automated, Manual, Flexible |
| Companies Covered | Krones AG, Tetra Pak International S.A., Syntegon Technology GmbH, IMA Group, GEA Group, MULTIVAC Group, KHS Group, SIG Combibloc Group Ltd., Coesia S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food and Beverage Packaging Machinery Market Emerging Trajectories
Equipment intelligence and regulatory compliance are converging to redefine how packaging lines are specified, operated, and monetized across the forecast period.
Robotic pick-and-place systems with machine vision integration are automating secondary packaging operations in high-speed snack lines. Confectionery and bakery processors are deploying these systems to eliminate manual case packing bottlenecks. This automation is compressing labor cost structures while enabling format changeovers without mechanical retooling.
REACH restrictions on chemical additives in food-contact materials are forcing seal component redesigns across European supply chains. Machinery OEMs must now validate elastomer and polymer formulations for migration limits before system handover. Liquid filling and dairy segments face the steepest compliance burden as ECHA expands restricted substance lists.
After-sales service unbundling is fragmenting traditional maintenance contract structures. Dairy and protein processors are selectively sourcing predictive analytics from software specialists while retaining mechanical service from OEM networks. This behavior is most visible in Germany where machinery density supports competitive third-party technician pools.
Global Food and Beverage Packaging Machinery Market Segmentation
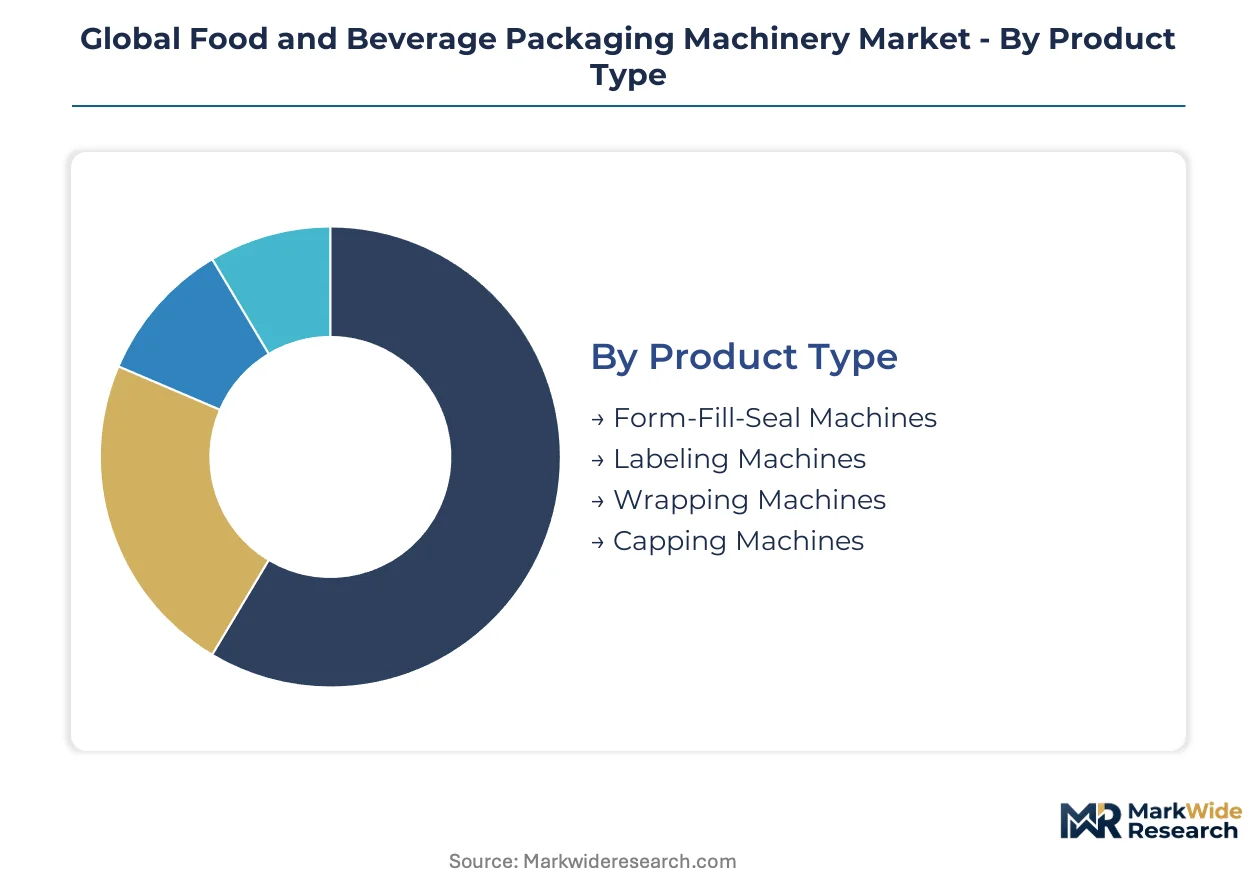
Equipment specification in food and beverage packaging machinery diverges sharply between high-throughput commodity lines and precision-sensitive premium formats. Segmentation reveals how capital deployment priorities shift across automation intensity, regulatory exposure, and shelf-life extension requirements.
Product Type:
Volume concentration clusters in standardized forming and sealing equipment, while premium capture concentrates in precision labeling and controlled-atmosphere systems.
- Form-Fill-Seal Machines:Integrated systems extrude, fill, and seal flexible films in continuous motion at throughputs exceeding 1,500 units per minute. Snack food processors in Germany deploy these lines for potato chip and extruded snack formats where film waste reduction directly compresses unit costs.
- Labeling Machines:Pressure-sensitive, sleeve, and hot-melt adhesive applicators handle container decoration at speeds matching upstream filling equipment. Beverage bottlers in China prioritize servo-driven rotary labelers that accommodate shrink-sleeve formats demanded by domestic retail chains.
- Wrapping Machines:Overwrap and shrink-wrap systems bundle multi-unit configurations for distribution efficiency.
- Capping Machines:Torque-controlled screw cappers and snap-fit applicators secure container integrity across liquid and viscous product ranges.
Mature deployment sits with Form-Fill-Seal Machines across established snack and dairy operations. Newer deployment is concentrated in Labeling Machines as beverage processors retrofit for recyclable-compatible sleeve formats.
Technology:
Cost tier separation distinguishes legacy thermal methods from emerging energy-efficient alternatives that command 15-30% capital premiums.
- Vacuum Packaging:Chamber and thermoforming systems evacuate atmosphere before sealing to extend protein and prepared meal shelf life. Premium meat processors in the United States specify these lines for case-ready retail programs where display life determines distribution radius.
- Inert Gas Flush:Modified atmosphere packaging replaces oxygen with nitrogen or carbon dioxide mixtures to retard oxidation. Coffee roasters and nut processors in Italy deploy these systems for volatile product categories where flavor retention supports price positioning.
- Thermoforming:Heated film draping over molds creates rigid trays for fresh and frozen applications.
- Ultrasonic Sealing:High-frequency vibration generates localized heat at material interfaces without thermal mass. Confectionery lines in Switzerland adopt this technology for narrow seal widths that reduce film consumption versus conventional heat-seal bars.
Standard thermal platforms dominate Thermoforming in frozen and fresh tray segments. Ultrasonic Sealing is climbing the fastest among sustainability-focused confectionery and snack producers seeking film reduction credentials.
End User:
Application-driven specification separates ambient-stable formats from cold-chain-dependent categories with stringent hygiene protocols.
- Snack Foods:High-speed vertical form-fill-seal and flow-wrap equipment handles irregular geometries and fragile textures. Extruded snack manufacturers in India scale automated lines under PLI scheme incentives to serve domestic retail expansion.
- Beverages:Aseptic filling, carbonation, and hot-fill systems manage liquid product integrity across glass, PET, and aluminum formats. Bottled water and soft drink producers in Brazil deploy these lines for tropical climate distribution where package barrier properties determine shelf stability.
- Dairy Products:ESL and aseptic liquid filling equipment extends freshness windows for milk and cultured products.
- Confectionery:Precision depositing, enrobing, and wrapping systems protect moisture-sensitive and temperature-vulnerable formulations.
Established automation characterizes Snack Foods with standardized bag and pouch formats. Dairy Products show the steepest expansion trajectory as processors retrofit for EU Green Deal recyclable-compatible packaging mandates.
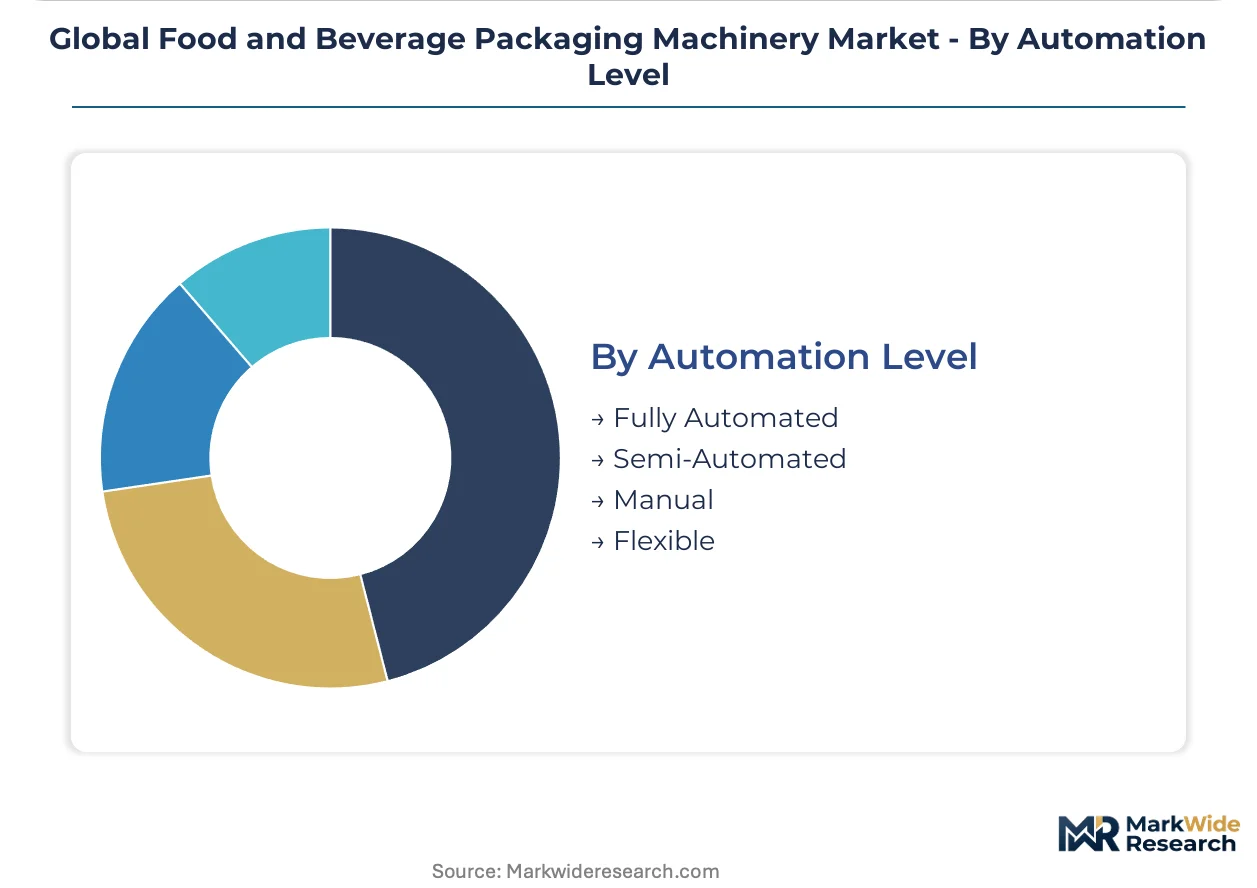
Automation Level:
Customer type stratification separates multinational processors with capital access from regional operators prioritizing labor flexibility.
- Fully Automated:Integrated lines with robotic handling, vision inspection, and centralized HMI control operate with minimal operator intervention. Large dairy cooperatives in the Netherlands specify these configurations for 24-hour continuous operation where labor cost arbitrage justifies capital intensity.
- Semi-Automated:Modular stations combine automatic core functions with manual feeding or case packing. Mid-sized confectionery producers in Turkey favor these systems for seasonal demand fluctuations where workforce scaling offers operational flexibility.
- Manual:Operator-dependent equipment serves micro-scale and artisanal production.
- Flexible:Quick-changeover platforms accommodate multiple formats without mechanical retooling.
Installed base concentration remains with Fully Automated lines among top-tier processors. Flexible automation is gaining share fastest among contract packagers serving multiple brand owners with volatile SKU portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures packaging machinery at scale exceeding domestic absorption, while China and India import precision systems to serve expanding food processing bases. Brazil and the United States round out demand concentration as beverage and protein processors retrofit for automation and compliance.
Germany
Dairy cooperatives and beverage bottlers drive capital deployment toward aseptic filling and recyclable-compatible format lines. EU F-Gas Regulation mandates refrigerant retrofits in cooling tunnels, compressing equipment replacement cycles. Machinery clusters concentrate around Krones AG in Neutraubling and Syntegon Technology in Waiblingen, shortening technical service response times for European processors.
China
Bottled water and soft drink producers scale automated lines for tropical climate distribution where barrier properties determine shelf stability. Dual carbon goals redirect R&D spending toward energy-efficient sealing technologies and modular platforms. Yangtze River Delta manufacturing bases assemble format-flexible equipment serving domestic retail chain demands for recyclable packaging.
India
Extruded snack manufacturers scale vertical form-fill-seal lines under PLI scheme incentives to capture domestic retail expansion. FSSAI hygiene mandates accelerate dairy processor adoption of automated aseptic filling systems. Maharashtra and Gujarat host emerging machinery assembly operations targeting regional dairy and beverage demand with shortened procurement lead times.
Brazil
Protein processors deploy vacuum packaging equipment for case-ready retail programs where display life determines distribution radius. ANVISA sanitary regulations dictate hygienic design protocols for liquid filling systems exported to transatlantic supply chains. São Paulo industrial corridors concentrate service networks for multinational OEMs serving Latin American retrofit cycles.
United States
Premium meat processors specify thermoforming and modified atmosphere systems for retail programs commanding margin capture through extended shelf life. FDA cGMP standards raise compliance costs for equipment sold into integrated transatlantic supply chains. Midwest dairy belts and Southeast poultry processing corridors anchor regional machinery service density.
Global Food and Beverage Packaging Machinery Market Vendor Landscape
Top-tier vendors anchor premium-tier positioning through backward integration into control systems and global service networks, while mid-scale specialists occupy format-flexible niches and regional fabricators compete on procurement lead times. Market structure tilts toward consolidation among full-line providers capable of integrating forming, filling, and sealing operations. Three archetypes dominate: integrated systems houses with captive automation engineering, hygiene-specialized precision vendors cross-applying pharmaceutical protocols, and modular platform builders enabling regulatory adaptation without full line replacement. Competitive moves concentrate on M&A for control systems capabilities and geographic expansion through local assembly partnerships.
Among German-based integrated systems houses, Krones AG and Syntegon Technology GmbH exemplify the full-line archetype with extensive backward integration into process engineering and hygienic design protocols. GEA Group occupies a position within the precision-tier through upstream control over automation architectures and dairy-focused application engineering. These three anchors demonstrate how European machinery clusters leverage regulatory proximity to EU Green Deal and F-Gas mandates for competitive differentiation.
| Leading Market Players |
|---|
| Krones AG |
| Tetra Pak International S.A. |
| Syntegon Technology GmbH |
| IMA Group |
| GEA Group |
| MULTIVAC Group |
| KHS Group |
| SIG Combibloc Group Ltd. |
| Coesia S.p.A. |
| Others |
Supply Flow & Price Mechanics
Automation engineering talent concentration in German and Swiss machinery clusters compresses labor-cost differentials into pricing-tier spreads across premium precision systems and standard commodity equipment.
Pricing Analysis
Margin tightening in standard equipment tiers reflects ultrasonic sealing technology penetration that reduces film waste claims for buyer procurement committees. Three-tier pricing structure across premium, standard, and economy levels separates aseptic dairy lines with full FDA cGMP validation from snack-food form-fill-seal platforms with basic CE marking. Price differentiation hinges on after-sales service bundling and predictive maintenance software integration. Dairy processors in the Netherlands exhibit lowest price sensitivity given 24-hour continuous operation requirements, while Indian extruded snack manufacturers under PLI scheme incentives prioritize capital efficiency over feature depth.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated aseptic filling lines, while regional distributors serve mid-scale retrofit cycles in Brazil and India. Component supply concentrates in Germany, China, and Switzerland, with servo motors and hygienic-grade stainless steel drawing from established industrial bases. Raw material dependencies include food-contact elastomers, high-frequency transducers for ultrasonic sealing, and proprietary PLC architectures. Single-source vulnerability concentrates in backward-integrated control systems from Krones AG and Syntegon Technology that limit third-party maintenance access. Distribution runs through machinery clusters anchored by technical service density rather than pure logistics optimization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultrasonic sealing technology is displacing conventional heat-seal methods across confectionery and flexible packaging lines, compressing replacement cycles for legacy thermal equipment.
For Market Incumbents: Anticipate margin compression in standard form-fill-seal tiers as Indian and Chinese OEMs exploit PLI scheme manufacturing incentives to capture domestic dairy and beverage demand. Defensive consolidation should prioritize captive control systems engineering talent concentrated in German clusters and predictive maintenance software capabilities that lock in recurring revenue from installed bases. Backward integration into food-contact elastomer validation for ECHA REACH compliance represents a certification moat against emerging competitors lacking migration testing infrastructure. For New Entrants and Emerging Players: Enter via modular platform architectures that accommodate EU Green Deal packaging waste directive shifts without requiring full line replacement, targeting risk-averse dairy cooperatives facing mandatory recyclable-compatible format deadlines. White-space concentration sits with predictive analytics software specialists serving third-party maintenance demand from processors unbundling traditional OEM service contracts. A software-first go-to-market angle bypasses capital-intensive mechanical fabrication while capturing recurring revenue from uptime guarantee contracts. For Investors and Strategic Acquirers: The window for entry favors control systems capabilities and format-flexible platform engineering over pure mechanical fabrication assets. Long-term viability rests on regulatory adaptation capacity across EU F-Gas refrigerant mandates and ECHA REACH migration limits rather than volume scale alone. The signal to watch is unbundling velocity in after-sales service contracts as dairy and protein processors selectively source predictive analytics from software specialists while retaining mechanical service from incumbent networks.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Software Integration | IoT sensor convergence with machine learning analytics enables outcome-based uptime guarantees that monetize installed bases beyond spare parts. |
| Backward Integration into Control Systems | Captive automation engineering talent in German machinery clusters limits third-party maintenance access and inflates competitor total cost of ownership. |
| Modular Platform Development | Format-flexible line architectures accommodate EU packaging waste directive shifts without full replacement, capturing premium positioning among risk-averse buyers. |
| Food-Contact Material Validation Investment | ECHA REACH compliance for seal and conveyor components extends commissioning timelines and creates certification barriers for undercapitalized entrants. |
| Regional Assembly Partnership Expansion | Local production under India PLI scheme incentives shortens procurement lead times for domestic dairy and beverage demand growth. |
Methodological Framework
SEC filings from Krones AG and GEA Group, EU F-Gas Regulation implementation reports, and ECHA REACH restricted substance databases formed the secondary backbone for equipment specification and compliance cost modeling. Primary interviews with dairy processing plant engineers, beverage bottler procurement leads, machinery OEM aftermarket service heads, and food-contact material compliance officers validated secondary assumptions on replacement cycle timing and pricing sensitivity. Bottom-up triangulation across installed base estimates and top-down cross-check against capital expenditure disclosures from European dairy cooperatives anchored volume and value outputs.
Historical trendline analysis of aseptic filling line deployments across German dairy belts and Brazilian beverage corridors established baseline growth patterns without assuming linear extrapolation. Segmentation dimensions modeled include equipment automation level, end-use application, technology type, and regional regulatory cluster intensity. CAGRs were derived from equipment shipment data correlated with dairy processor capacity expansion announcements and EU Green Deal compliance deadline proximity. Industry-specific forecast inputs incorporated F-Gas refrigerant phase-down quota constraints on cooling tunnel retrofit demand and PLI scheme incentive uptake rates in Indian food processing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ECHA REACH substance list expansion or accelerated EU packaging reuse mandate implementation. Forecasts reflect assumptions on regulatory timeline adherence and technology substitution elasticity that stress-testing should periodically revisit. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Pouch Sealing Machine Market
Packaging Machinery
Food Powder Packaging Machine Market
Packaging Machinery
Auger Powder Filling Machines Market
Packaging Machinery
Paper Napkin Converting Lines Market
Packaging Machinery
Vertical Strapping Machines Market
Packaging Machinery
Powder Packing Machine Market
Packaging Machinery
Capsule Filling Machines Market
Packaging Machinery
Labeling Machines Market
Packaging Machinery
Flow Pack Machine Market
Packaging Machinery
Air Cushion Machine Market
Packaging Machinery
Product Dispensing Machinery Market
Packaging Machinery
Kraft Paper Machines Market
Packaging Machinery
Paper Napkins Converting Machines Market
Packaging Machinery
Laminating Machines Market
Packaging Machinery
Global Pet Stretch Blow Molding Machines Market
Packaging Machinery
Global Wrapping Machine Market