
 Phosphorescent Pigments Market | 2026-2036
Phosphorescent Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Phosphorescent Pigments Market Analysis
Strontium aluminate is repositioning phosphorescent pigment economics by delivering tenfold luminance duration versus legacy zinc sulfide systems. Nemoto & Co., Ltd. leverages proprietary encapsulation methods to sustain premium positioning in safety-grade applications. Zhejiang Minhui Luminous Technology Co., Ltd. anchors volume supply through integrated rare-earth sourcing in eastern China. Honeywell International Inc. competes on formulation consistency for aerospace certification requirements.
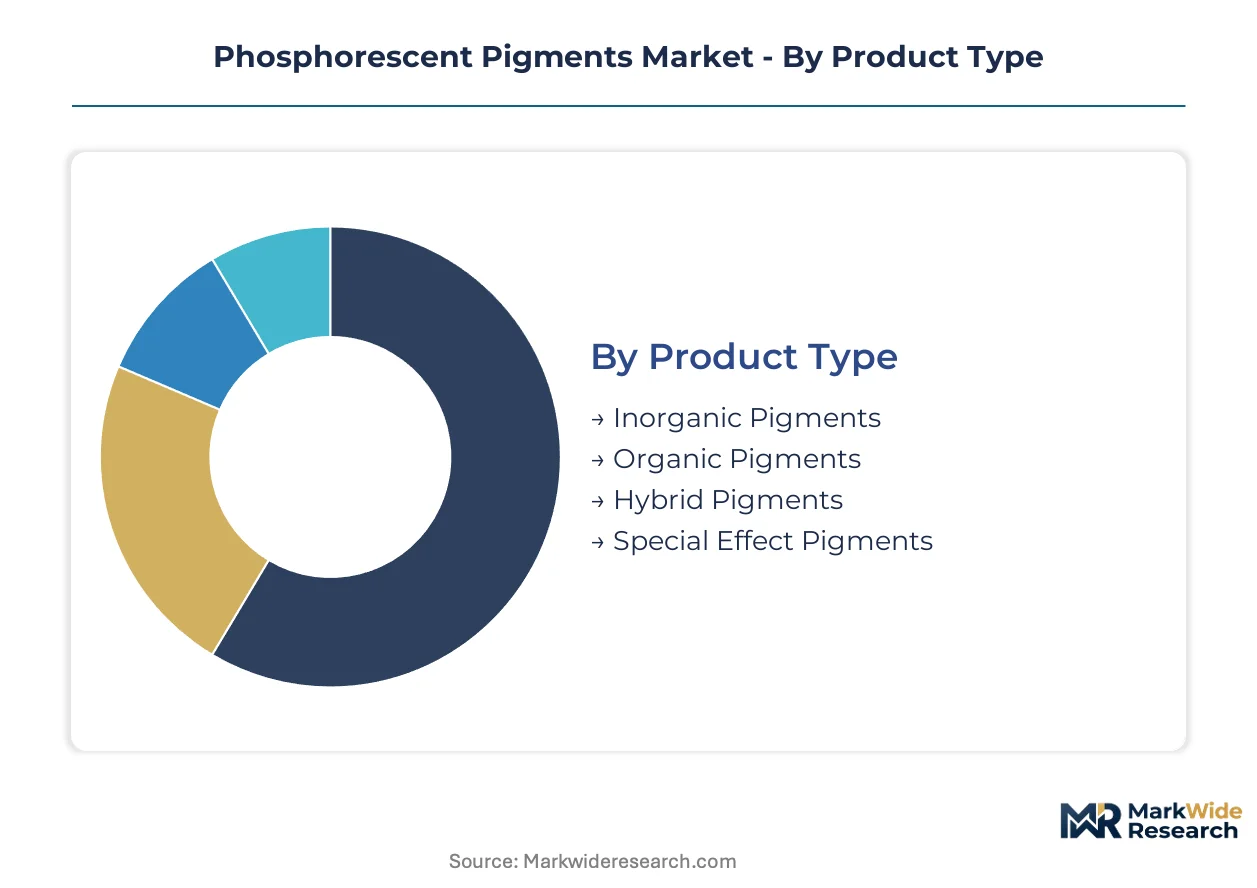
Phosphorescent pigments are photoluminescent materials that absorb and store electromagnetic energy, then emit visible light over extended durations after excitation ceases; strontium aluminate doped with europium and dysprosium dominates technical performance with afterglow exceeding twelve hours. These materials serve critical visibility functions in emergency egress systems, automotive instrumentation, and consumer safety products. Inorganic pigments dominate current revenue owing to proven durability and lower unit costs, while hybrid pigments represent the fastest-expanding category as formulators balance performance against sustainability mandates. Coatings applications capture the deepest margin pools due to stringent certification requirements and reformulation complexity.
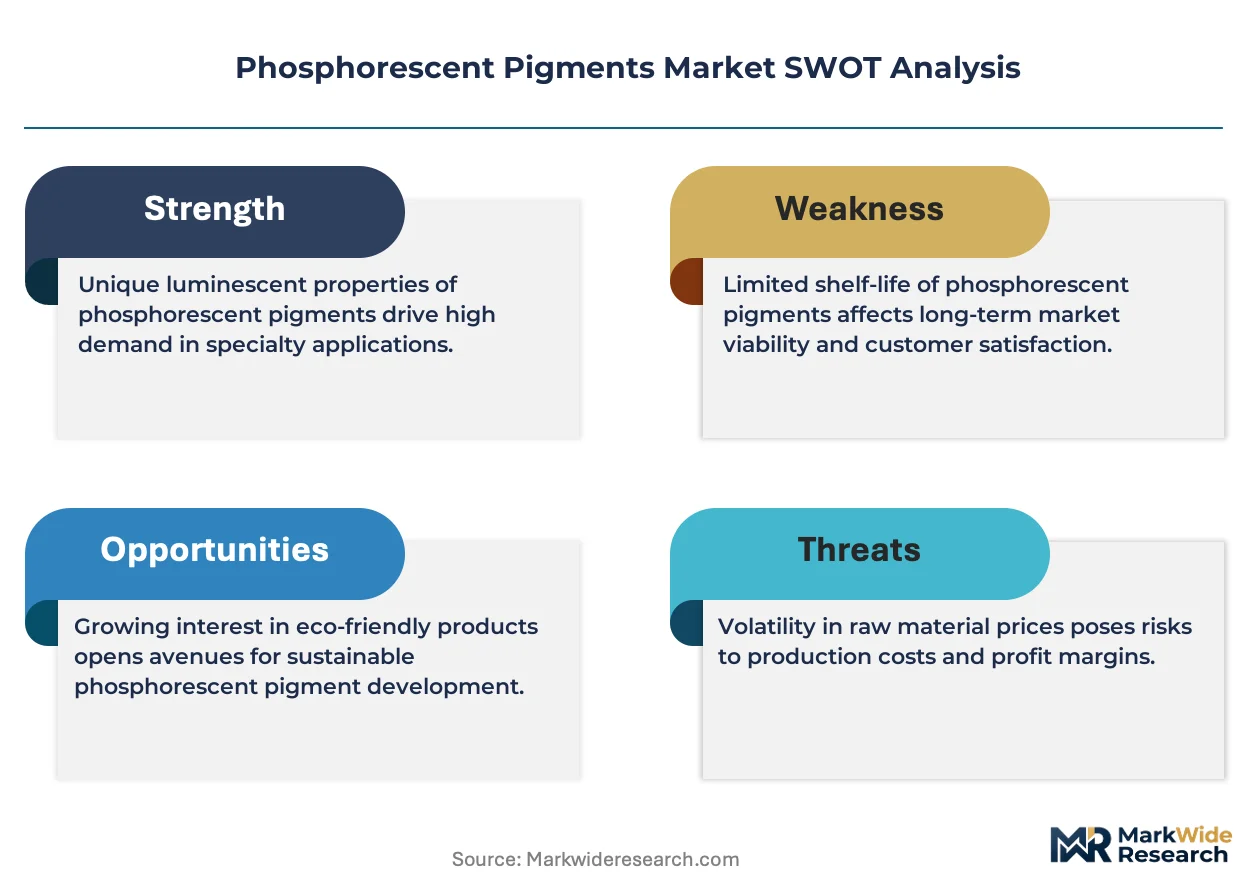
The EPA regulates heavy-metal content under TSCA provisions, while REACH restricts cadmium and lead thresholds across European supply chains; China's GB standards and MEE oversight govern domestic manufacturing emissions and export compliance. These frameworks elevate compliance costs for smaller producers while advantaging integrated manufacturers with in-house testing laboratories. Stakeholders must monitor evolving state-level chemical disclosure rules and assess captive strontium supply arrangements before committing capacity investments.
Market Dynamics
Strontium aluminate's displacement of zinc sulfide is restructuring phosphorescent pigment supply chains around rare-earth sourcing security and REACH-compliant encapsulation capabilities. This material transition concentrates production advantages with integrated manufacturers possessing captive europium and dysprosium access.
Growth Catalysts
- Emergency egress mandates:NFPA 101 and IBC code updates in the United States now require photoluminescent pathway marking in commercial high-rises. Building owners retrofit existing structures with strontium aluminate-based systems.
- REACH heavy-metal thresholds:ECHA's tightened cadmium and lead restrictions are accelerating zinc sulfide replacement across European safety signage. Formulators reformulate coatings to maintain CE marking eligibility.
- Automotive interior illumination:Instrument cluster and ambient lighting designers specify phosphorescent elements for battery-electric vehicles. OEMs source pigments meeting NHTSA durability standards.
Market Restraints
- Rare-earth price volatility:Europium and dysprosium spot markets fluctuate with Chinese export quota announcements. Smaller pigment houses lack hedging mechanisms against oxide price spikes.
- Strontium carbonate supply concentration:Qinghai and Sichuan provinces control 70% of global strontium ore refining. Western formulators face single-source dependency for high-purity carbonate feedstock.
- Encapsulation IP thickets:Proprietary moisture-barrier coatings around activated aluminates limit second-source qualification. Buyers encounter licensing fees that compress formulation margins.
Strategic Opportunities
- India infrastructure buildout:Metro rail expansion in Mumbai, Delhi, and Bengaluru creates demand for platform-edge safety marking. Domestic BIS certification opens procurement to qualified suppliers.
- Photovoltaic integration:Bifacial solar panel manufacturers embed phosphorescent layers for nighttime identification and anti-theft marking. This application bypasses traditional coatings channels.
- EU Green Deal procurement rules:Public tenders above threshold values now preference products with verified lifecycle assessments. Pigment houses with ISO 14040-compliant data capture specification advantages.
Industry Challenges
- Color consistency calibration:Batch-to-batch luminance variation in strontium aluminate synthesis requires spectrophotometric testing infrastructure that mid-tier producers underinvest in.
- Dual-use export classification:Long-afterglow pigments with aerospace-grade performance fall under controlled technology lists. Shippers navigate end-user certificate requirements that delay fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosphorescent Pigments Market |
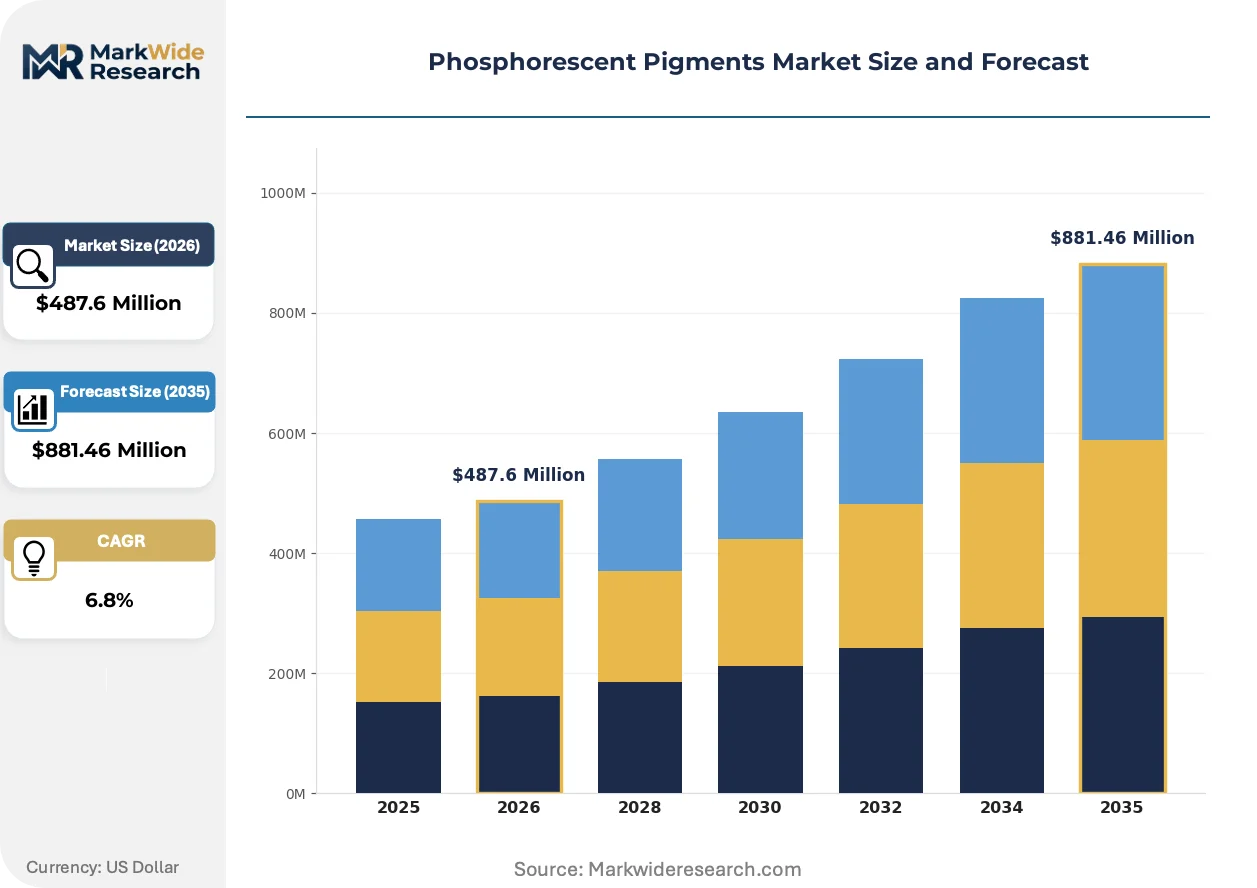
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inorganic Pigments, Organic Pigments, Hybrid Pigments, Special Effect Pigments Application: Coatings, Plastics, Inks, Textiles End User: Consumer Goods, Automotive, Aerospace, Electronics Distribution Channel: Online Retail, Direct Sales, Distributors, Resellers |
| Companies Covered | Nemoto & Co., Ltd., Zhejiang Minhui Luminous Technology Co., Ltd., United Mineral and Chemical Corp., OliKrom, Solstice Advanced Materials Inc., Zegen Advanced Materials, Honeywell International Inc., Badger Color Concentrates Inc., GloTech International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosphorescent Pigments Market Emerging Trajectories
Formulation science is advancing along three vectors: hybrid organic-inorganic systems, regulatory-driven heavy-metal elimination, and supply-chain-proximate manufacturing. These developments compress qualification timelines while fragmenting technical specifications across end-use verticals.
Nano-encapsulated strontium aluminate is converging with waterborne polyurethane dispersions to enable direct-to-substrate application without solvent-based intermediates. Marine safety equipment manufacturers in Norway and South Korea are piloting these systems for lifeboat marking. The convergence is collapsing the traditional coatings-converter value chain by eliminating separate primer and topcoat steps.
EPA TSCA Section 6 restrictions on persistent, bioaccumulative substances are forcing reformulation of legacy zinc sulfide pigments still used in toy and novelty applications. Domestic U.S. manufacturers face 180-day compliance windows for existing inventory. The rule most impacts small-batch specialty houses serving promotional products, which lack in-house toxicology testing.
Building operators in Germany and Japan now specify pigment systems with third-party verified afterglow duration rather than supplier datasheets. TÜV Rheinland and JQA certification programs are displacing self-declared performance claims in commercial construction procurement. This behavioral shift elevates testing costs for entrants while locking in incumbents with established laboratory relationships.
Phosphorescent Pigments Market Segmentation
Phosphorescent pigment supply chains fragment across technical specifications, regulatory compliance tiers, and channel access levels. Manufacturers configure production assets around specific formulation families, creating distinct competitive arenas with divergent margin profiles and qualification barriers.
Product Type:
Rare-earth sourcing concentration and encapsulation IP ownership stratify competitive position across formulation categories.
- Inorganic Pigments:Strontium aluminate doped with europium and dysprosium delivers afterglow durations exceeding twelve hours. Safety signage manufacturers in Germany and Japan specify these formulations for NFPA 101-compliant egress systems. REACH cadmium thresholds and EPA TSCA Section 6 provisions are accelerating displacement of legacy zinc sulfide stocks.
- Hybrid Pigments:Nano-encapsulated strontium aluminate converges with waterborne polyurethane dispersions to enable direct-to-substrate application. Marine safety equipment producers in Norway and South Korea pilot these systems for lifeboat marking, collapsing traditional coatings-converter value chains by eliminating separate primer steps.
- Organic Pigments:Synthetic photoluminescent compounds serve toy and novelty applications with shorter afterglow requirements. EPA reformulation deadlines under persistent bioaccumulative substance restrictions compress compliance windows for small-batch specialty houses.
- Special Effect Pigments:Custom-formulated systems target premium automotive ambient lighting and aerospace instrument clusters. NHTSA durability standards and dual-use export classifications constrain supplier qualification.
Inorganic pigments absorb the bulk of installed capacity; hybrid pigments are expanding most quickly.
Application:
Certification complexity and reformulation cost create tiered margin pools across downstream conversion processes.
- Coatings:Photoluminescent pathway marking systems for commercial high-rises command premium pricing due to TÜV Rheinland and JQA third-party verification requirements. Building operators in Germany now reject self-declared performance claims, elevating testing infrastructure barriers.
- Plastics:Injection-molded safety components for automotive instrument clusters and battery-electric vehicle interior elements. OEMs specify pigments meeting combined thermal stability and luminance retention criteria.
- Inks:Screen-printed emergency egress signage and promotional products face divergent regulatory pressures. EPA TSCA compliance costs disproportionately impact small-batch specialty houses serving novelty applications.
- Textiles:Photoluminescent yarns for high-visibility workwear and safety apparel. Performance requirements center on wash-cycle durability and color consistency calibration.
Coatings command the deepest margin pools; plastics applications are climbing the fastest.
End User:
Procurement sophistication and specification authority concentrate demand within vertically integrated manufacturing ecosystems.
- Automotive:Battery-electric vehicle programs specify phosphorescent elements for instrument clusters and ambient lighting. OEM sourcing teams prioritize formulation consistency and NHTSA durability certification over unit cost.
- Aerospace:Long-afterglow pigments with extended performance duration fall under controlled technology export classifications. Shippers navigate end-user certificate requirements that delay fulfillment timelines.
- Electronics:Bifacial solar panel manufacturers embed phosphorescent layers for nighttime identification and anti-theft marking. This application bypasses traditional coatings distribution channels entirely.
- Consumer Goods:Toy and novelty applications face EPA TSCA Section 6 reformulation mandates. Domestic U.S. manufacturers confront 180-day compliance windows for existing zinc sulfide inventory.
Automotive absorbs the bulk of specification-grade volume; electronics is gaining share fastest.
Distribution Channel:
Technical support requirements and order fragmentation shape channel economics across customer segments.
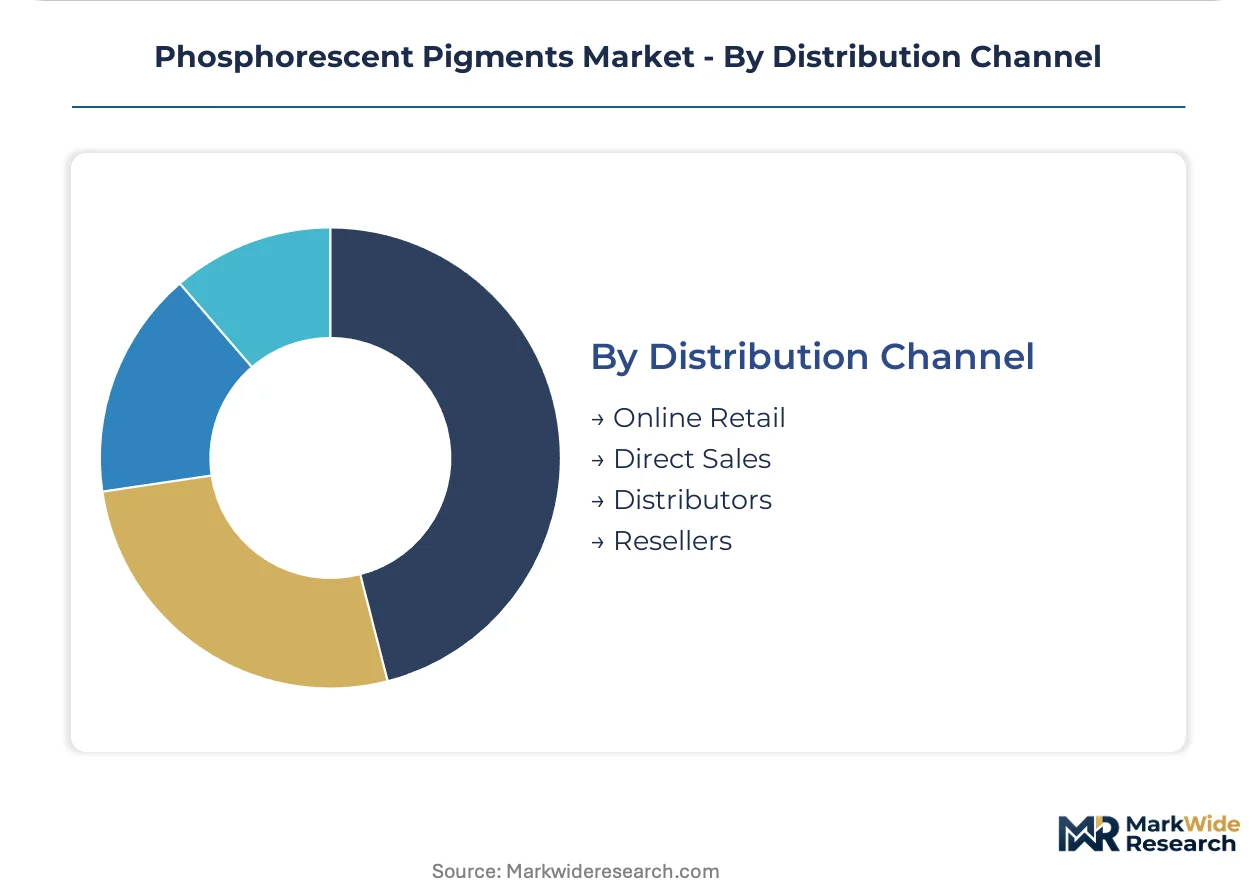
- Direct Sales:Integrated manufacturers with captive rare-earth sourcing and in-house testing laboratories serve high-volume safety signage and automotive programs. Qinghai and Sichuan province strontium carbonate concentration advantages reinforce this channel's dominance for certified formulations.
- Distributors:Regional stocking points support mid-tier coatings converters and plastics compounders with shorter lead time requirements. Channel partners carry inventory risk against europium and dysprosium spot price volatility.
- Online Retail:Small-batch specialty pigments for hobbyist and prototyping applications. Limited technical support and self-service specification create price transparency pressures.
- Resellers:Value-added repackaging and custom blending for niche textile and ink applications. Margin compression from encapsulation IP licensing fees constrains profitability.
Direct sales captures the bulk of value; distributor relationships are deepening fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates phosphorescent pigment demand through domestic manufacturing scale and export infrastructure. Qinghai and Sichuan provinces control strontium carbonate refining that feeds formulation plants across eastern industrial zones.
China
Emergency egress retrofits in Shanghai and Shenzhen commercial towers drive specification-grade consumption. MEE oversight enforces GB standards on manufacturing emissions and export compliance documentation. Zhejiang province hosts integrated producers with captive rare-earth sourcing and in-house spectrophotometric testing laboratories.
United States
NFPA 101 code updates mandate photoluminescent pathway marking in commercial high-rises across major metro areas. EPA TSCA Section 6 restrictions compress reformulation timelines for legacy zinc sulfide inventories. Texas and Ohio plastics compounders serve automotive OEMs with NHTSA-certified pigment systems for battery-electric vehicle interiors.
Germany
REACH cadmium and lead thresholds accelerate displacement of zinc sulfide across safety signage supply chains. ECHA compliance documentation requirements elevate testing infrastructure barriers for imported formulations. The Ruhr industrial cluster concentrates coatings converters supplying TÜV Rheinland-verified egress systems to building operators.
Japan
JQA certification programs displace self-declared performance claims in commercial construction procurement. METI guidelines shape industrial safety equipment specifications for manufacturing facilities. The Kansai region hosts pigment houses with established laboratory relationships serving Osaka and Kyoto metro rail expansion projects.
India
Mumbai, Delhi, and Bengaluru metro rail expansion creates procurement demand for platform-edge safety marking systems. BIS certification opens specification-grade supply to qualified domestic and international producers. Gujarat chemical complexes develop strontium aluminate formulation capacity for regional safety infrastructure programs.
Phosphorescent Pigments Market Vendor Landscape
Capacity expansion dominates the current landscape as integrated manufacturers add spectrophotometric testing infrastructure to capture specification-grade contracts. The vendor base stratifies around rare-earth sourcing security, encapsulation IP ownership, and certification laboratory access. Three archetypes define positioning: captive-feedstock integrated producers, specialty formulation houses with aerospace qualifications, and regional compounders serving mid-tier coatings converters. Geographic expansion into India and Southeast Asia accompanies technology licensing deals for moisture-barrier encapsulation methods.
Within the premium-tier vector, Nemoto & Co., Ltd. exemplifies proprietary encapsulation capabilities, while Zhejiang Minhui Luminous Technology Co., Ltd. anchors the scale-driven end through integrated rare-earth sourcing in eastern China. Honeywell International Inc. occupies a position tied to formulation consistency requirements for aerospace certification programs.
| Leading Market Players |
|---|
| Nemoto & Co., Ltd. |
| Zhejiang Minhui Luminous Technology Co., Ltd. |
| United Mineral and Chemical Corp. |
| OliKrom |
| Solstice Advanced Materials Inc. |
| Zegen Advanced Materials |
| Honeywell International Inc. |
| Badger Color Concentrates Inc. |
| GloTech International Ltd. |
| Others |
Supply Flow & Price Mechanics
Spectrophotometric testing specialists concentrated in Zhejiang and Qinghai provinces command wage premiums that widen spreads between certified premium formulations and commodity-grade alternatives. Labor-cost differentials between integrated producers with in-house laboratories and mid-tier compounders lacking batch-calibration infrastructure directly map to three-tier pricing structures across safety-grade, industrial-grade, and novelty applications.
Pricing Analysis
Volume-mass commodity transactions anchor the economy tier while specification-grade safety formulations capture disproportionate margin pools. Three-tier pricing structure across premium, standard, and economy levels separates TÜV Rheinland-certified egress systems from industrial coatings and toy-grade novelty pigments. Pricing pressure stems from europium and dysprosium spot volatility that compresses formulation margins for non-integrated producers. Automotive OEMs exhibit lowest price sensitivity given NHTSA durability certification requirements, while promotional products distributors face acute cost compression from EPA TSCA reformulation deadlines.
Supply Chain Analysis
Strontium carbonate feedstock rests on Qinghai and Sichuan province refining concentration that supplies formulation plants across eastern China. Rare-earth oxide dependencies draw from Inner Mongolia and Jiangxi separation facilities, while waterborne polyurethane dispersions source from South Korean specialty chemical producers. Single-source vulnerability in high-purity strontium carbonate creates exposure to Chinese export quota announcements. Distribution runs through direct sales channels for certified safety signage programs and regional distributor networks serving mid-tier coatings converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over rare-earth oxide supply and in-house spectrophotometric testing infrastructure determines pricing power. Players are pursuing backward integration into strontium carbonate refining and europium separation capacity to defend margin position against feedstock volatility.
For Market Incumbents: Anticipate REACH cadmium threshold tightening by pre-qualifying alternative dopant formulations before ECHA enforcement windows. Secure long-term offtake agreements with Qinghai strontium refiners to lock in carbonate supply ahead of quota restrictions. Invest in JQA and TÜV Rheinland laboratory partnerships to entrench third-party verification advantages that mid-tier competitors cannot replicate. For New Entrants and Emerging Players: BIS certification requirements in India open a window for qualified suppliers to capture metro rail platform-edge marking contracts in Mumbai, Delhi, and Bengaluru. Target photovoltaic anti-theft marking applications where bifacial panel manufacturers bypass traditional coatings channels entirely. Pursue waterborne polyurethane dispersion partnerships with South Korean marine safety equipment producers to establish direct-to-substrate formulation credibility. For Investors and Strategic Acquirers: Re-rating potential sits with integrated producers possessing captive rare-earth sourcing given strontium aluminate displacement acceleration. Long-term viability favors asset-light formulation houses with aerospace dual-use qualifications and established laboratory relationships over commodity compounders. Watch Chinese MEE emission enforcement intensity as the inflection signal for domestic production cost compression and export compliance advantage shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strontium Carbonate | Qinghai province refining access insulates against single-source supply disruption and quota volatility. |
| Spectrophotometric Testing Infrastructure | TÜV Rheinland and JQA laboratory partnerships lock in specification-grade contract eligibility. |
| Waterborne Polyurethane Dispersion Partnerships | South Korean marine safety pilots validate direct-to-substrate application without primer steps. |
| BIS Certification Investment | India metro rail expansion opens procurement to qualified domestic and international suppliers. |
| Alternative Dopant Formulation R&D | REACH cadmium threshold compliance maintains CE marking eligibility ahead of ECHA enforcement. |
Methodological Framework
Trade databases, chemical industry association filings, and regulatory submission records formed the secondary backbone for supply chain mapping and compliance timeline tracking. Primary interviews with pigment plant managers, coatings converter procurement leads, automotive OEM specification engineers, and rare-earth oxide traders combined with secondary validation to triangulate production capacity and pricing dynamics. Bottom-up facility-level capacity estimates and top-down end-use demand segmentation were cross-referenced to anchor volume projections.
Historical trendline analysis of strontium aluminate displacement rates against zinc sulfide stocks informed technology adoption curve modeling across the projection horizon. Segmentation dimensions included formulation type, application channel, end-use vertical, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to verified base-year consumption data, incorporating rare-earth price elasticity coefficients and building code mandate implementation schedules as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for nano-encapsulated hybrid systems would alter the outlook if waterborne dispersion convergence accelerates beyond pilot scale. Forecasts reflect documented assumptions regarding REACH enforcement timing, Chinese export quota continuity, and NFPA 101 retrofit completion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Thermochromic Pigments Market
Dyes and Pigments
Europe Natural Dyes and Pigments Market
Dyes and Pigments
Asia-Pacific Pigments Market
Dyes and Pigments
Global Architectural Paint Oxide Market
Dyes and Pigments
Acrylic Colors Market
Dyes and Pigments
Material Color Matching Booth Market
Dyes and Pigments
France Aluminium Pigments Market
Dyes and Pigments
Bio Based Pigments and Dyes Market
Dyes and Pigments
Ponceau 4R Colors Market
Dyes and Pigments
Inorganic Color Pigments Market
Dyes and Pigments
Inorganic Pigments Market
Dyes and Pigments
Acid Stable Blue Market
Dyes and Pigments
Special Effect Pigments Market
Dyes and Pigments
Complex Inorganic Color Pigments Market
Dyes and Pigments
Mulch Colorants Market
Dyes and Pigments
Arylamide Pigments Market