
 Automotive Coatings Market | 2026-2036
Automotive Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Coatings Market Intelligence
IATF 16949 qualification is rotating supplier rosters across automotive coating tiers, forcing non-certified regional blenders out of direct OEM supply chains. PPG Industries leverages captive resin synthesis to sustain margin control across North American assembly plants. Axalta Coating Systems anchors its position through electrodeposition technology leadership in commercial vehicle programs. BASF SE differentiates via integrated color-matching platforms that dominate European luxury OEM specifications.
Automotive coatings are formulated polymer systems—typically acrylic, polyurethane, or epoxy-based layers ranging from 15 to 150 micrometers total dry film thickness—engineered to protect vehicle substrates from corrosion, UV degradation, and mechanical abrasion while delivering aesthetic finish. Waterborne coatings command the largest volume share among coating types, though powder coatings are gaining structural ground in commercial vehicle wheel and chassis applications where zero-VOC compliance is mandatory. Spray application technology still leads in OEM body shops, yet electrodeposition retains its lock on primer-layer uniformity for complex stamped geometries.
EPA VOC regulations in the United States and REACH chemical restrictions in Europe are converging to eliminate high-solvent formulations from new vehicle production lines, compelling reformulation investments across all major suppliers. China's MEE enforces comparable emission thresholds for automotive manufacturing clusters, creating a tripartite regulatory ceiling that shapes global product development priorities. Stakeholders must monitor how battery enclosure coating specifications evolve as thermal management and dielectric properties become design-critical for electric mobility platforms.
Market Dynamics
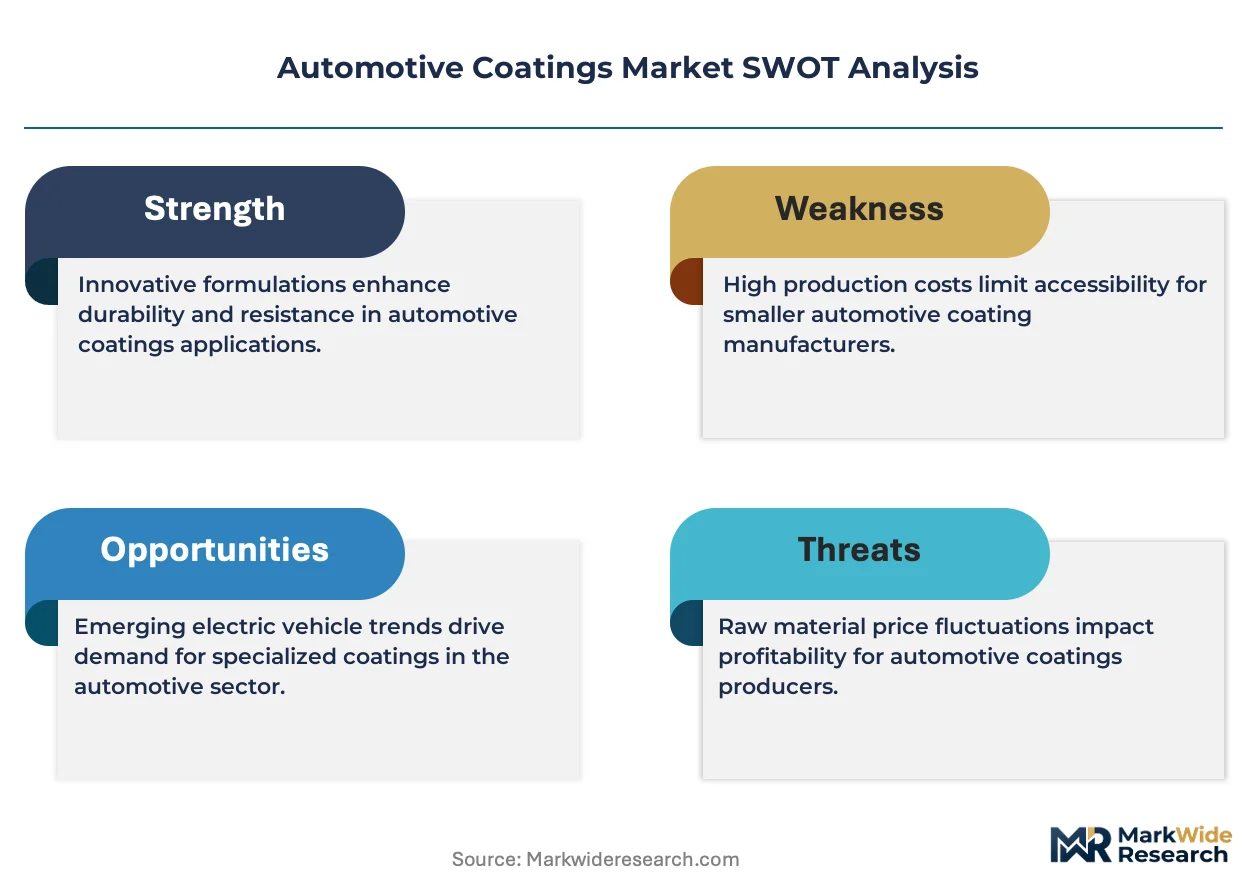
Waterborne chemistry conversion is compressing solvent-borne capacity across automotive coating supply chains, forcing reformulation investments that favor integrated resin manufacturers over standalone blenders.
Growth Catalysts
- EU Green Deal mandates:REACH compliance deadlines are accelerating waterborne primer adoption in German and Italian assembly plants, eliminating high-VOC alternatives from certified supplier lists.
- Battery enclosure thermal coatings:Electric vehicle platforms require dielectric and flame-retardant layer specifications that command premium formulation complexity and multi-year supply contracts.
- China MEE enforcement:Yangtze River Delta manufacturing clusters face emission threshold tightening that redirects procurement toward domestic coating majors with captive environmental compliance infrastructure.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and polyurethane resin precursors track naphtha and propylene pricing, compressing blender margins during upstream commodity spikes.
- Electrodeposition technology concentration:Automotive OEMs source cathodic epoxy primers from a narrow supplier base with patented tank chemistry, creating single-source risk for new model launches.
- High-solvent formulation bans:EPA VOC rules and REACH annex restrictions are structurally eliminating solvent-borne clearcoat capacity without compensating demand recovery elsewhere in the portfolio.
Strategic Opportunities
- Commercial vehicle powder coating:Zero-VOC mandates for heavy-duty truck wheels and chassis components in North American and European markets open specification windows outside traditional liquid coating dominance.
- Integrated color-matching platforms:Digital spectrophotometry and cloud-based formula databases enable remote tinting services that compress OEM body shop inventory requirements and aftermarket refinish cycle times.
- India PLI scheme for EV manufacturing:Domestic electric vehicle production subsidies are attracting coating suppliers to establish local compounding facilities ahead of import substitution requirements.
Industry Challenges
- IATF 16949 certification backlog:Regional blenders face 12-18 month audit queues that freeze new OEM supplier qualification during platform renewal cycles.
- Legacy solvent-borne asset strandedness:Spray booth and curing oven configurations designed for high-VOC chemistries require complete replacement rather than retrofit for waterborne compatibility.
- Cross-functional coating-electronics integration:Battery pack coatings must simultaneously satisfy thermal management, dielectric isolation, and electromagnetic shielding specifications that span supplier engineering silos.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Coatings Market |
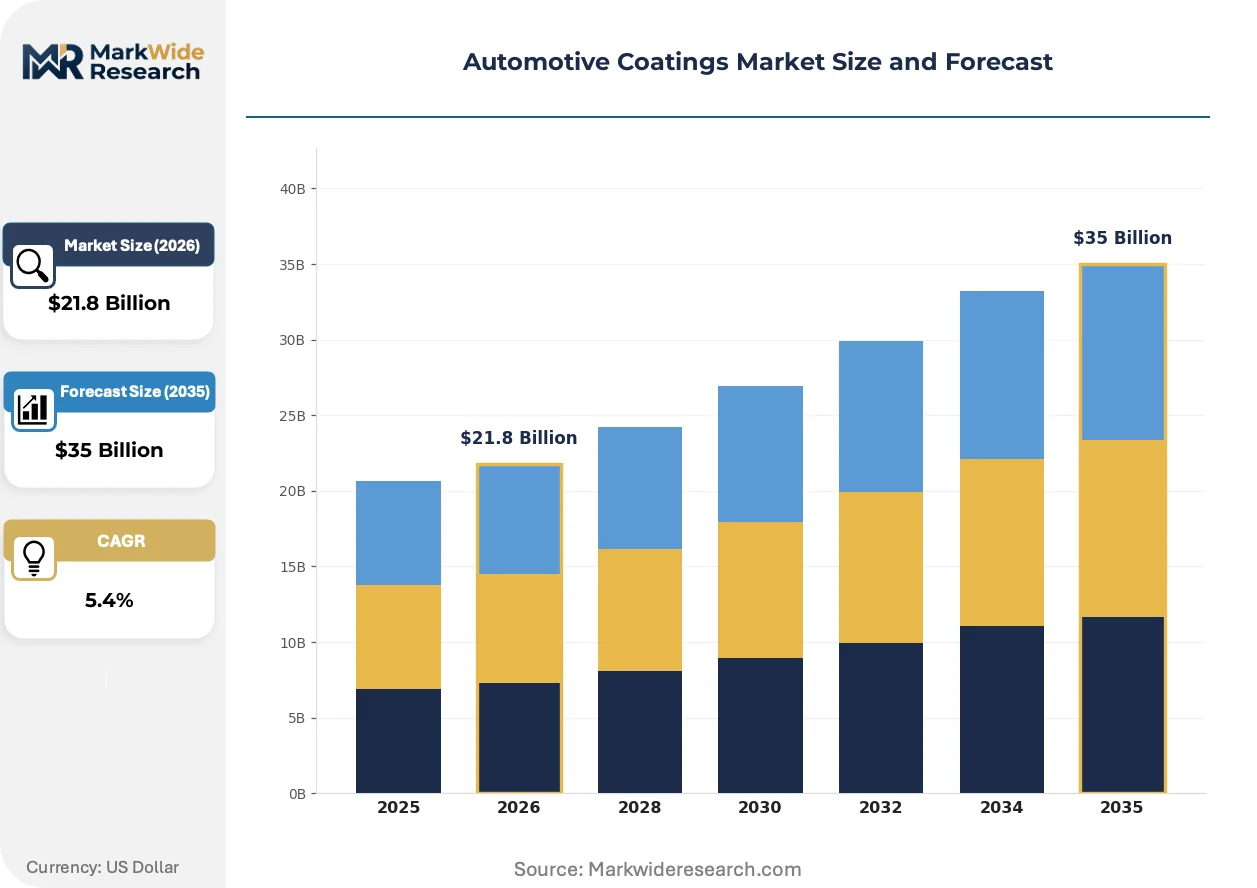
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $35 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Waterborne, Solventborne, Powder Coatings, Electrocoat, UV Curable, Ceramic Technology: Spray Application, Electrodeposition, Roll Coating, Dip Coating, Brush Coating, Flow Coating Vehicle Category: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Off-road Vehicles, Electric Mobility Vans End User Type: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Service Providers |
| Companies Covered | PPG Industries, Inc., The Sherwin-Williams Company, Akzo Nobel N.V., Axalta Coating Systems, BASF SE, Nippon Paint Holdings Co., Ltd., RPM International Inc., Kansai Paint Co., Ltd., NIPSEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Coatings Market Strategic Shifts & Innovations
Functional coating layers are multiplying as vehicle electrification and autonomous sensor integration demand properties beyond corrosion protection and aesthetics. Formulation science now converges with thermal engineering and electromagnetic compatibility design.
Self-healing clearcoat technology is decomposing the traditional damage-repair value chain in premium automotive segments. Polyurethane microcapsule systems containing latent crosslinkers activate upon scratch penetration, restoring gloss without body shop intervention. German luxury OEMs are piloting these formulations on high-touch surface areas, compressing warranty claim volumes and aftermarket refinish demand.
REACH authorization procedures are tightening scrutiny on chromium-based corrosion inhibitors and certain isocyanate hardeners used in automotive primers. ECHA sunset date pressures are forcing reformulation toward silane-based adhesion promoters and aliphatic polyurethane alternatives. Tier-1 suppliers serving European OEM export programs face compressed qualification timelines to maintain cross-border shipment eligibility.
Direct-to-OEM digital specification platforms are replacing distributor-mediated color matching and small-batch ordering in North American and European refinish markets. Cloud-based formula libraries enable collision repair networks to access real-time OEM color variants without physical chip inventory. This channel compression is most visible in US consolidated repair chain procurement, where national accounts negotiate directly with coating manufacturers for volume pricing and technical service bundling.
Automotive Coatings Market Segmentation

Automotive coatings segment by chemistry, application method, vehicle platform, and supply chain position. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier strategy and OEM procurement decisions.
Coating Type:
Waterborne formulations command premium pricing in regulated markets where VOC compliance is non-negotiable, while powder coatings capture margin in heavy-duty segments with zero-emission mandates.
- Waterborne:Acrylic and polyurethane dispersions suspended in water carrier systems, achieving sub-100 g/L VOC content. German and Italian OEM assembly plants under EU Green Deal deadlines have eliminated solvent-borne alternatives from certified supplier lists, concentrating procurement with integrated resin manufacturers.
- Solventborne:Traditional high-solvent acrylic and alkyd formulations delivering superior flow and gloss in ambient cure conditions. Stranded capacity is mounting as EPA VOC rules and REACH annex restrictions structurally eliminate this chemistry from new vehicle production without compensating demand recovery elsewhere.
- Powder Coatings:Thermoset polymer particles applied electrostatically and cured at elevated temperature; zero-VOC compliance drives specification in commercial vehicle wheels and chassis.
- Electrocoat:Cathodic epoxy primer systems deposited via electrical current for uniform coverage on complex stamped geometries; patented tank chemistry creates single-source supply risk.
- UV Curable:Acrylate oligomer formulations instantaneously polymerized under ultraviolet radiation; energy efficiency and line speed advantages attract premium segment interest.
- Ceramic:Inorganic silicate or alumina-based coatings delivering extreme thermal resistance for exhaust components and emerging battery enclosure applications.
Waterborne holds installed capacity. Powder Coatings is rotating up the share rankings.
Technology:
Application technology segmentation tracks capital intensity and line integration depth, with electrodeposition and spray systems representing divergent paths to coating uniformity.
- Spray Application:Robotic or manual atomized deposition of liquid coatings through pneumatic or electrostatic guns. OEM body shops in North American passenger vehicle plants retain this dominance for basecoat and clearcoat layers despite waterborne conversion investments.
- Electrodeposition:Immersion-based electrical deposition of primer films ensuring complete coverage in recessed areas and weld seams. Commercial vehicle programs specify this technology for corrosion warranty compliance in harsh operating environments.
- Roll Coating:Metered application via engraved cylinders for flat or coil substrates; limited automotive relevance outside specialty trim components.
- Dip Coating:Submersion-based application for small parts and fasteners; batch processing constrains throughput for high-volume vehicle production.
- Brush Coating:Manual touch-up and repair applications; aftermarket refinish segment retains this method for localized damage correction.
- Flow Coating:Controlled flooding of coating over substrate surfaces; niche deployment in hollow structural members and frame rails.
Spray Application dominates unit volume. Electrodeposition is climbing the fastest in commercial vehicle specification intensity.
Vehicle Category:
Platform segmentation reveals divergent coating specifications between mass-market passenger production and specialized commercial or electrified applications with thermal management requirements.
- Passenger Vehicles:High-volume sedan and SUV production driving standardized coating systems with color-matching complexity and scratch resistance priorities. Chinese domestic OEMs are reshaping procurement patterns through captive supplier relationships and scale-driven formulation negotiations.
- Electric Mobility Vans:Low-emission commercial platforms requiring dielectric and flame-retardant coating specifications for battery enclosures and high-voltage components. Premium formulation complexity commands multi-year supply contracts with thermal engineering integration.
- Commercial Vehicles:Heavy-duty trucks and buses with extreme durability requirements; chassis and wheel applications specify powder coatings under zero-VOC mandates.
- Two-wheelers:Motorcycles and scooters with cost-optimized coating specifications; emerging markets dominate volume with solvent-borne chemistry persistence.
- Off-road Vehicles:Agricultural and construction equipment with abrasion-resistant topcoat requirements; seasonal production patterns create demand volatility.
Passenger Vehicles holds installed capacity. Electric Mobility Vans is gaining share fastest.
End User Type:
Supply chain position determines technical service intensity and contract structure, with direct OEM relationships requiring IATF 16949 certification that excludes regional blenders.
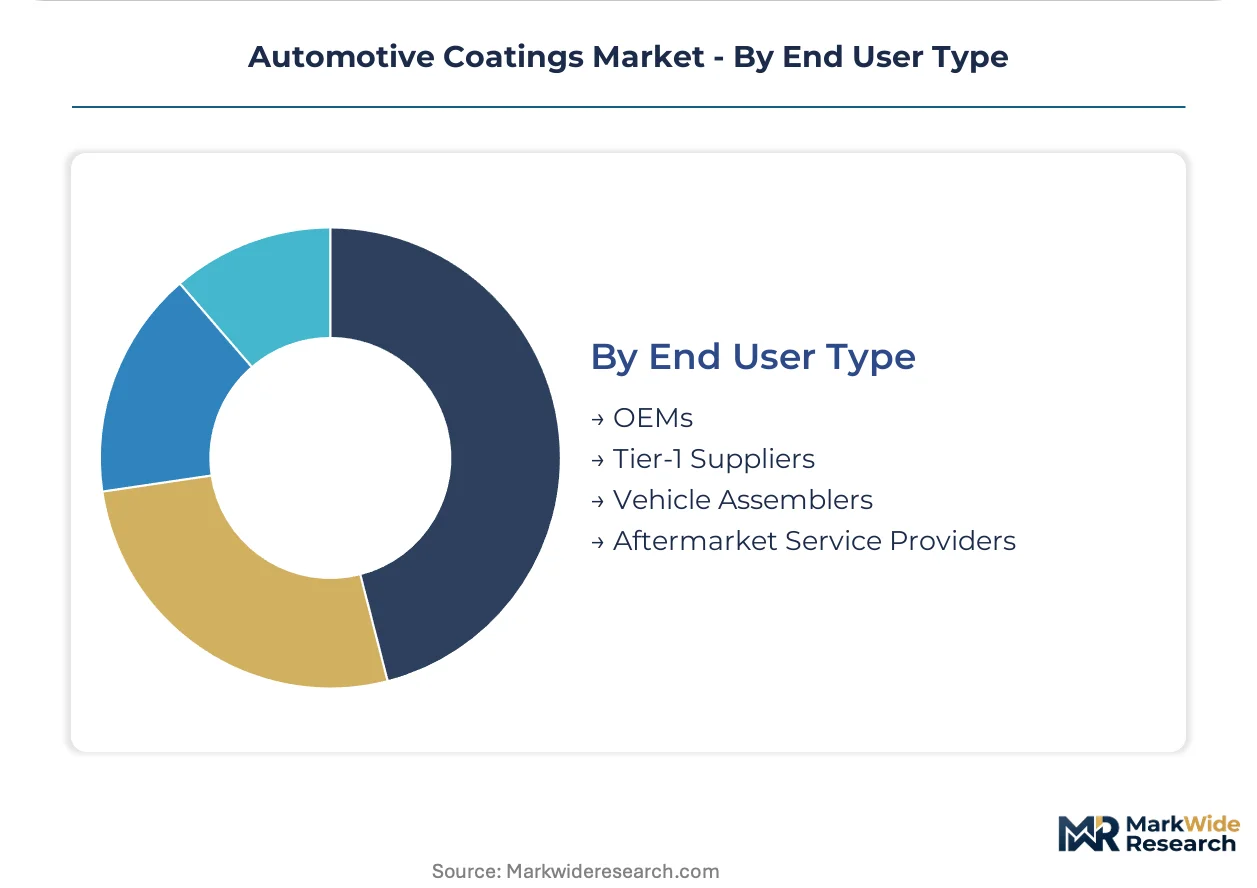
- OEMs:Original equipment manufacturers specifying coating systems for new vehicle production. REACH and EU Green Deal compliance deadlines in European assembly plants are accelerating waterborne primer adoption and eliminating uncertified suppliers from approved vendor lists.
- Tier-1 Suppliers:Component manufacturers coating parts prior to vehicle assembly. IATF 16949 certification queues of 12-18 months freeze new supplier qualification during platform renewal cycles, concentrating procurement with established certified players.
- Vehicle Assemblers:Contract manufacturing and kit assembly operations with delegated coating responsibility; quality liability fragmentation creates specification enforcement challenges.
- Aftermarket Service Providers:Collision repair networks and refinish shops. Cloud-based color-matching platforms in US consolidated repair chains enable direct manufacturer negotiation, compressing distributor margins and inventory requirements.
OEMs holds installed capacity. Aftermarket Service Providers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes concentrate around OEM assembly plants with captive coating operations, Tier-1 component suppliers seeking IATF certification, and aftermarket refinish networks negotiating direct manufacturer contracts. Geographic procurement patterns track regulatory enforcement intensity and electric vehicle production scale.
China
Domestic EV production scale is redirecting coating procurement toward state-linked resin manufacturers with captive environmental compliance infrastructure. MEE enforcement in Yangtze River Delta manufacturing clusters tightens emission thresholds quarterly. Shanghai and Jiangsu province assembly plants now specify waterborne primer systems exclusively, eliminating uncertified regional blenders from approved vendor lists.
Germany
Luxury OEM specifications for integrated color-matching platforms concentrate demand among certified suppliers with cloud-based formula databases. EU Green Deal mandates and REACH compliance deadlines accelerate waterborne chemistry conversion in Bavarian and Baden-Württemberg assembly plants. Stuttgart and Munich metropolitan coating operations now operate under zero-VOC procurement protocols that structurally exclude solvent-borne alternatives.
United States
Commercial vehicle powder coating specifications for heavy-duty truck wheels and chassis open procurement windows outside traditional liquid coating dominance. EPA VOC regulations eliminate high-solvent formulations from Michigan and Ohio assembly plant supplier lists. Detroit and Toledo manufacturing clusters now require dielectric coating qualifications for battery enclosure applications in electric mobility platforms.
Japan
Automotive OEMs source cathodic epoxy primers from narrow supplier bases with patented tank chemistry, creating single-source concentration in Kanto and Kansai industrial corridors. METI efficiency standards push electrodeposition technology upgrades in Nagoya and Osaka coating operations. Toyota and Honda supply chain specifications now mandate thermal management coating integration for hybrid and electric powertrain components.
India
Domestic electric vehicle production subsidies under the PLI scheme attract coating suppliers to establish local compounding facilities ahead of import substitution requirements. Tamil Nadu and Maharashtra state industrial policies prioritize waterborne chemistry adoption in Chennai and Pune assembly corridors. Maruti Suzuki and Tata Motors procurement teams now require IATF 16949 certification for direct supplier qualification during platform renewal cycles.
Automotive Coatings Market Key Industry Players
Player mix skews toward integrated resin manufacturers with captive environmental compliance infrastructure and electrodeposition technology specialists holding patented tank chemistry. Market structure concentrates around three supplier tiers: multinational chemical conglomerates with backward integration into resin synthesis, regional coating blenders facing certification backlogs, and specialty powder coating operators serving commercial vehicle zero-VOC mandates. Dominant competitive moves include M&A activity targeting color-matching platform capabilities and capacity expansion in Yangtze River Delta and Bavarian manufacturing clusters.
Among North American-based coating conglomerates, PPG Industries and The Sherwin-Williams Company exemplify the integrated resin manufacturer archetype with captive supply chain control. Axalta Coating Systems represents the electrodeposition technology specialist position through its commercial vehicle program concentration. These three anchors demonstrate how patent-protected tank chemistry and backward integration into raw material production create defendable positions against regional blender competition.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Akzo Nobel N.V. |
| Axalta Coating Systems |
| BASF SE |
| Nippon Paint Holdings Co., Ltd. |
| RPM International Inc. |
| Kansai Paint Co., Ltd. |
| NIPSEA Group |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts with naphtha and propylene indexation clauses lock in resin supply access for integrated manufacturers while anchoring price visibility for OEM procurement teams facing volatile petrochemical feedstock markets.
Pricing Analysis
Cost-plus contracts with naphtha and propylene indexation dominate formulation supply agreements, tying coating prices to commodity futures movements. Price differentiation separates IATF 16949-certified suppliers from uncertified regional blenders, while volume scale and thermal management specification complexity command premium tiers. Pricing pressure stems from stranded solvent-borne capacity write-downs as EPA VOC rules and REACH deadlines eliminate high-solvent alternatives. Tier-1 suppliers show lowest price sensitivity due to multi-year platform lock-ins, while aftermarket refinish networks negotiate aggressively via consolidated national accounts.
Supply Chain Analysis
Just-in-time resin delivery dominates OEM assembly plant procurement, though strategic stockpiling of acrylic and polyurethane precursors is rising among integrated manufacturers anticipating MEE enforcement volatility in Chinese manufacturing clusters. Supply concentrates in China, Germany, and the United States, with coating formulation draws from naphtha crackers, propylene oxide plants, and specialty isocyanate facilities. Single-source vulnerability concentrates in cathodic epoxy primer electrodeposition tank chemistry held by patent-protected suppliers. Distribution runs through direct OEM specification channels and Tier-1 component supplier networks, with cloud-based color-matching platforms compressing traditional distributor roles in refinish segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive coatings are transitioning toward platform-economics dynamics as cloud-based color-matching databases and integrated specification systems create winner-take-most concentration among certified suppliers with captive resin infrastructure.
For Market Incumbents: Compound electrodeposition technology leadership through patent-protected tank chemistry investments that deepen switching costs for commercial vehicle OEMs. Defend margin position by accelerating backward integration into acrylic and polyurethane resin synthesis ahead of naphtha price volatility. Prioritize IATF 16949 certification pipeline expansion to capture Tier-1 supplier procurement frozen by audit queue backlogs. For New Entrants and Emerging Players: Lead with zero-VOC powder coating specialization targeting heavy-duty truck wheel and chassis specifications in North American markets outside liquid coating dominance. Target India PLI scheme EV manufacturing subsidies by establishing local compounding facilities ahead of import substitution mandates. Deploy direct-to-OEM digital color-matching platforms to bypass stranded distributor networks in consolidated US collision repair chains. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated resin manufacturers with captive environmental compliance infrastructure over standalone blenders facing certification barriers. Long-term viability centers on suppliers with backward integration into propylene and naphtha derivative production. Acquisition targets should demonstrate cloud-based formula database capabilities and thermal management coating integration for battery enclosure applications. Watch battery enclosure dielectric specification evolution as the inflection signal for premium formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive naphtha and propylene derivative production insulates margin from petrochemical volatility. |
| Cloud-Based Color-Matching Platform Deployment | Digital spectrophotometry compresses OEM body shop inventory and aftermarket refinish cycle times. |
| Electrodeposition Tank Chemistry Patent Expansion | Cathodic epoxy primer concentration creates single-source lock-in for commercial vehicle corrosion warranties. |
| IATF 16949 Certification Infrastructure Investment | Audit queue capacity captures Tier-1 supplier procurement frozen during platform renewal cycles. |
| Battery Enclosure Thermal Coating Qualification | Dielectric and flame-retardant specifications command multi-year supply contracts with EV platform engineering integration. |
Research Approach
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement directors, aftermarket refinish network operators, and electrodeposition technology specialists, then refined through secondary validation against vehicle production databases, IHS Markit registration data, SEC 10-K filings, and customs/trade flow records. Bottom-up coating volume estimates triangulated with top-down OEM procurement spend analysis across the analysis window.
Variance decomposition across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic automotive production indicators. Industry-specific forecast inputs incorporated MEE enforcement timelines in Chinese manufacturing clusters and EU Green Deal compliance deadlines affecting German and Italian assembly plant chemistry specifications.
The analysis sits within stated boundaries; outcomes outside sustained EV platform adoption rates, REACH authorization sunset schedules, or naphtha-propylene price correlation stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and battery enclosure coating specification evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Global Exterior Architectural Coatings Market
Paints & Coatings
Saudi Arabia Architectural Paints Market
Paints & Coatings
Egypt Paints and Coatings Market
Paints & Coatings
Polyolefin Resin Paints Market
Paints & Coatings
South Africa Paints and Coatings Market
Paints & Coatings
Morocco Paints and Coatings Market
Paints & Coatings
Paint and Coating Stripper Market
Paints & Coatings
Qatar Paints and Coatings Market
Paints & Coatings
Global Primer Market
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
Hybrid Paint Cans Market
Paints & Coatings
Paint Defoamers Market
Paints & Coatings
Floor Paints Market
Paints & Coatings
US Paints and Coatings Market
Paints & Coatings
India Automotive OEM Coatings Market
Paints & Coatings
Faux Finish Coatings Market