
 Fluorescent Pigments Market | 2026-2036
Fluorescent Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorescent Pigments Market Intelligence
Capital-intensity divergence between integrated resin producers and pigment compounders is collapsing as DayGlo Color Corp leverages captive polymer synthesis to capture margin upstream, while Radiant Color NV sustains European regulatory certification depth to anchor premium safety-marker supply. Sinloihi Co., Ltd. competes through dye-doped polymer specialization in Asian electronics packaging, and Brilliant Group Inc. differentiates via UV-fluorescent ink leadership for narrow-web printing.
Fluorescent pigments are colorants that absorb electromagnetic radiation at specific wavelengths and re-emit it at longer visible wavelengths, typically formulated from organic dye carriers fixed into thermoset or thermoplastic resin matrices with particle sizes ranging from 1 to 10 microns for optimal dispersion. Their primary industrial purpose is to deliver high-visibility coloration under daylight or UV excitation for safety, branding, and authentication applications where standard pigments lack luminosity. Organic pigments occupy the dominant volume position across printing inks and textiles due to cost efficiency and color breadth, while quantum dots represent the fastest-expanding technology segment as electronics manufacturers specify narrower emission spectra for display backlights and photonic components. Polymer-based pigments command margin concentration in automotive interior applications where migration resistance and thermal stability above 200°C are mandatory.
EPA regulations on volatile organic compound emissions from ink formulations and REACH restrictions on aromatic amine content in colorants are restricting conventional dye chemistry and accelerating reformulation toward polymer-encapsulated systems. CE marking requirements for personal protective equipment visibility standards and OSHA high-visibility apparel mandates are embedding fluorescent pigment performance into procurement specifications across safety equipment supply chains. Stakeholders must monitor evolving EU Green Deal chemical hazard classifications and dual carbon implementation timelines in China, as these frameworks will determine which pigment chemistries retain market access and which face phased substitution.
Market Dynamics
REACH and RoHS restrictions on heavy-metal content in colorants are redirecting formulation investment toward organic and polymer-based alternatives, collapsing the historical cost advantage of inorganic fluorescent pigment production.
Growth Catalysts
- Transportation infrastructure mandates:Safety signage and high-visibility road markings in Germany, France, and the United States are expanding uptake of daylight-fluorescent formulations for traffic management systems.
- REACH compliance deadlines:The European Chemicals Agency's phased restrictions on cadmium and lead-based pigments are forcing automotive OEMs to certify polymer-encapsulated alternatives for interior components.
- Quantum dot integration:Display backlight manufacturers are specifying narrower emission spectra for photonic components, creating specification pull for advanced fluorescent materials in electronics packaging.
Market Restraints
- Petrochemical feedstock volatility:Thermoset and thermoplastic resin matrices depend on styrene and acrylic monomer pricing, which fluctuates with crude oil indices and refinery capacity constraints.
- Specialized synthesis concentration:Captive polymer synthesis capabilities for daylight-fluorescent formulations cluster among integrated producers in the Ohio River Valley and the Antwerp-Rotterdam chemical corridor.
- Thermal stability ceiling:Organic dye carriers degrade above 220°C, excluding fluorescent pigments from high-temperature automotive underhood applications where ceramic colorants dominate.
Strategic Opportunities
- Indian safety equipment procurement:Bureau of Indian Standards certification for high-visibility apparel in mining and construction sectors remains underpenetrated by polymer-encapsulated pigment suppliers.
- EU Green Deal chemical hazard reclassification:Anticipated hazard category expansions for aromatic amines will accelerate substitution timelines, rewarding early reformulators with locked procurement contracts.
- UV-fluorescent narrow-web printing:Brand authentication applications in pharmaceutical packaging are converging with track-and-trace serialization requirements, opening specification channels distinct from commodity ink markets.
Industry Challenges
- Migration resistance certification timelines:Automotive OEM specifications for interior polymer components require 1000-hour lightfastness testing under SAE J1885 protocols, extending qualification cycles to 18-24 months.
- Particle size dispersion expertise:Optimal 1-10 micron distribution for thermoplastic compounding demands specialized milling and classification equipment, constraining toll manufacturing options for mid-scale compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorescent Pigments Market |
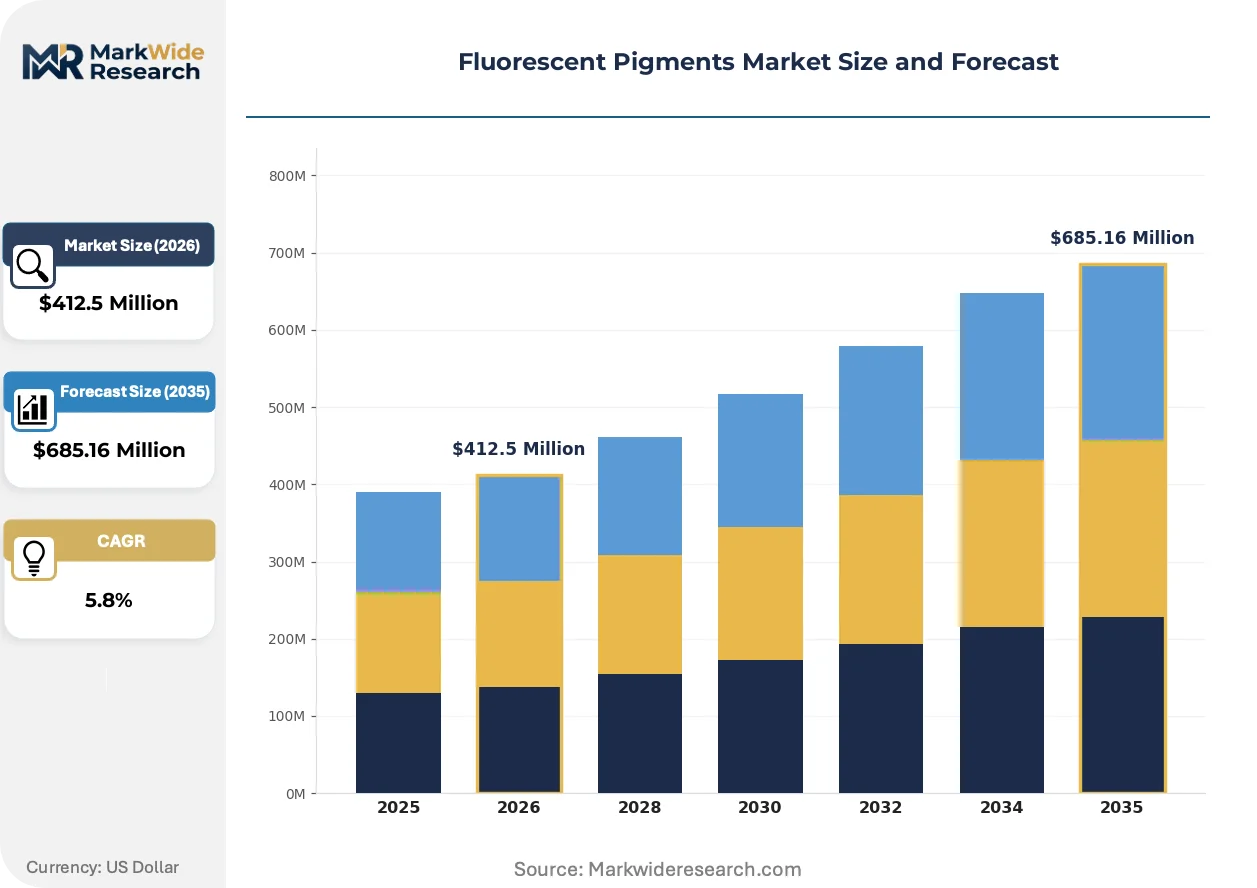
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Pigments, Inorganic Pigments, Polymer-Based Pigments, Phosphorescent Pigments Application: Printing Inks, Textiles, Plastics, Safety Markers, Cosmetics, Signage Technology: UV Fluorescence, Visible Spectrum Fluorescence, Quantum Dots, Dye-Doped Polymers End User Industry: Packaging, Automotive Components, Electronics, Consumer Goods |
| Companies Covered | Wanlong Chemical Co., Ltd., Aron Universal Limited, DayGlo Color Corp, Brilliant Group Inc., Vicome Corp, Radiant Color NV, Sinloihi Co., Ltd., Wuxi Minghui International Trading Co., Ltd., Luminochem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorescent Pigments Market Strategic Shifts & Innovations
Polymer encapsulation technology is compressing the performance gap between organic and inorganic fluorescent pigments, enabling substitution in applications previously reserved for heavy-metal-based colorants.
Quantum dot phosphor technology is miniaturizing emission control for display backlights and photonic components. Electronics manufacturers in Taiwan and South Korea are specifying sub-10 nanometer particle distributions for narrower spectral output. This miniaturization is compressing the addressable market for conventional organic fluorescent pigments in premium display applications.
ECHA's 2025 sunset date for cadmium pigments under REACH Annex XVII is forcing reformulation across European safety equipment supply chains. Industrial consequence includes accelerated qualification of polymer-encapsulated alternatives for CE-marked personal protective equipment. German automotive suppliers are responding with captive migration resistance testing protocols that exceed baseline regulatory requirements.
Specification-driven procurement is consolidating buyer power among tier-one automotive and electronics OEMs. Direct pigment qualification by Volkswagen, BMW, and Samsung SDI is displacing distributor-led specification in high-performance segments. This concentration is most visible in southern Germany and the Seoul metropolitan area, where procurement teams maintain dedicated colorant engineering functions.
Fluorescent Pigments Market Segmentation
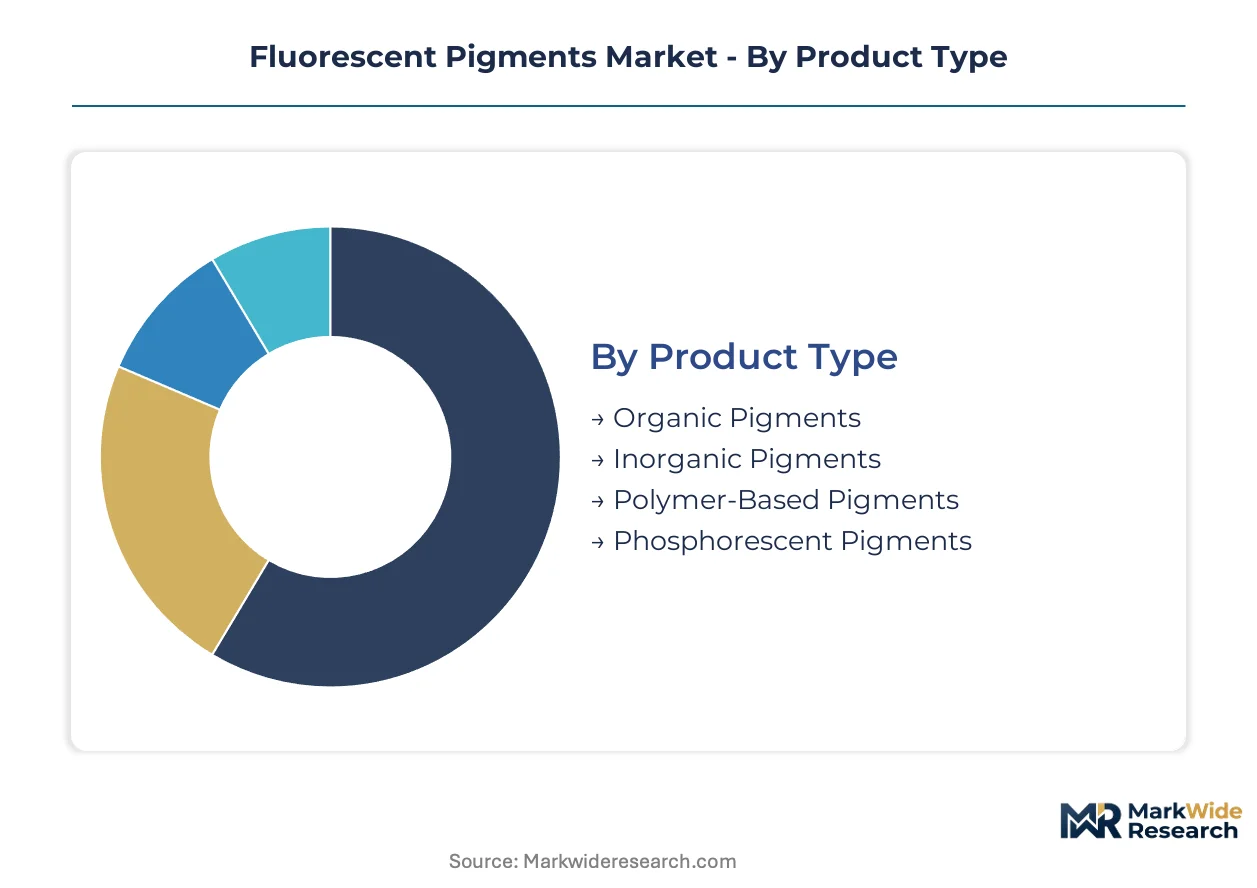
Fluorescent pigment segmentation reveals distinct channel economics across product chemistries and application verticals. Specification requirements from automotive OEMs and electronics manufacturers fragment procurement pathways, creating divergent margin structures between commodity safety markers and certified polymer-encapsulated grades.
Product Type:
Channel mix varies sharply by chemistry class, with organic pigments flowing through distributor networks for printing applications while polymer-based grades require direct technical sales to automotive tier-one suppliers.
- Organic Pigments:These dye-based formulations disperse in solvent and waterborne systems for commercial printing and textile finishing. Demand concentrates in Indian textile hubs and European packaging converters where REACH aromatic amine restrictions are forcing reformulation toward polymer-encapsulated alternatives. Cost efficiency sustains volume leadership despite regulatory pressure.
- Polymer-Based Pigments:Thermoset and thermoplastic resin matrices encapsulate fluorescent dyes for migration-resistant automotive interior components. German OEM specifications for lightfastness above SAE J1885 thresholds are concentrating procurement among qualified compounders in the Ohio River Valley and Antwerp-Rotterdam corridor. Thermal stability above 200°C enables substitution for heavy-metal colorants.
- Inorganic Pigments:Cadmium and lead-based formulations face phased REACH Annex XVII restrictions, collapsing channel access for European safety equipment supply chains.
- Phosphorescent Pigments:Strontium aluminate and zinc sulfide compositions deliver afterglow illumination for emergency egress signage and military applications.
By volume, organic pigments lead. By growth pace, polymer-based formulations are climbing the fastest.
Application:
Application segmentation tracks end-use performance requirements, with safety markers commanding certification premiums and cosmetics applications driving particle size miniaturization.
- Safety Markers:High-visibility road markings and personal protective equipment demand daylight-fluorescent formulations meeting CE marking and OSHA mandates. German transportation infrastructure spending and Indian mining sector procurement are expanding specification channels. Bureau of Indian Standards certification remains underpenetrated by polymer-encapsulated suppliers.
- Printing Inks:UV-fluorescent narrow-web formulations serve pharmaceutical authentication and track-and-trace serialization. Brand protection requirements from FDA-regulated drug packaging are converging with state-level cannabis tracking mandates in the United States.
- Textiles:Apparel and industrial fabric applications face substitution pressure from digital printing technologies.
- Plastics:Thermoplastic compounding for consumer goods and electronics housings requires 1-10 micron particle distribution.
- Cosmetics:Facial and body coloration applications drive FDA and EU Cosmetics Regulation compliance for skin contact safety.
- Signage:Outdoor advertising and wayfinding systems specify fade resistance under extended UV exposure.
Safety markers generate the highest margin concentration. Printing inks show the steepest technology-driven expansion.
Technology:
Technology segmentation reflects excitation mechanism and emission control precision, with quantum dots displacing conventional organics in premium display applications.
- Quantum Dots:Sub-10 nanometer semiconductor nanocrystals deliver narrow emission spectra for LCD and OLED backlight enhancement. Samsung SDI and Taiwan-based display manufacturers are specifying cadmium-free formulations to meet RoHS and REACH substance restrictions. Miniaturization is compressing addressable volume for conventional organic alternatives in premium electronics.
- UV Fluorescence:Invisible-under-daylight formulations activate under 365nm excitation for security printing and brand authentication. Pharmaceutical packaging serialization requirements are opening specification channels distinct from commodity ink markets.
- Visible Spectrum Fluorescence:Daylight-activated colorants dominate traffic management and safety equipment applications.
- Dye-Doped Polymers:Sinloihi Co., Ltd. specializes in this technology for Asian electronics packaging applications requiring thermal processing stability.
Visible spectrum fluorescence holds volume dominance. Quantum dots are gaining share fastest in value terms.
End User Industry:
End user segmentation maps to specification intensity, with automotive and electronics OEMs consolidating direct pigment qualification authority.
- Automotive Components:Interior polymer specifications from Volkswagen and BMW require 1000-hour lightfastness testing and migration resistance certification. German supplier captive testing protocols extend qualification cycles to 18-24 months, concentrating procurement among integrated resin producers.
- Electronics:Display backlight and photonic component manufacturers in South Korea and Taiwan specify narrow emission spectra. Quantum dot integration is displacing distributor-led specification in high-performance segments.
- Packaging:Food contact and pharmaceutical applications face FDA and EFSA migration limits.
- Consumer Goods:Toys, stationery, and novelty products compete on cost with lower regulatory barriers.
Packaging leads by unit volume. Automotive components command the highest value per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes fluorescent pigments primarily for automotive interior certification, while India and the United States concentrate procurement in safety equipment and transportation infrastructure respectively. This consumption-mix differential shapes distinct regulatory exposure and supply chain configurations across major markets.
Germany
Automotive OEM specifications from Volkswagen and BMW drive polymer-encapsulated pigment demand for interior polymer components. REACH Annex XVII cadmium restrictions under ECHA enforcement are accelerating reformulation timelines. Supplier concentration clusters in southern Germany, where captive migration resistance testing protocols exceed baseline regulatory requirements.
United States
OSHA high-visibility apparel mandates and state-level cannabis tracking programs expand specification channels for UV-fluorescent narrow-web printing. EPA regulations on volatile organic compound emissions from ink formulations restrict conventional dye chemistry. Ohio River Valley integrated producers maintain captive polymer synthesis capabilities for daylight-fluorescent formulations.
India
Bureau of Indian Standards certification for high-visibility apparel in mining and construction sectors remains underpenetrated by polymer-encapsulated suppliers. DGFT import monitoring on chemical raw materials influences formulation sourcing decisions. Textile hubs in Gujarat and Tamil Nadu concentrate organic pigment demand for commercial printing and fabric finishing applications.
China
Dual carbon implementation timelines and MEE enforcement on industrial chemical emissions are reshaping pigment production compliance costs. Display backlight manufacturers in the Yangtze River Delta specify narrow emission spectra for photonic components. Yangtze River Delta electronics packaging clusters drive dye-doped polymer specialization for thermal processing stability.
South Korea
Samsung SDI and display manufacturers in the Seoul metropolitan area specify quantum dot formulations for LCD and OLED backlight enhancement. MFDS pharmaceutical packaging regulations converge with track-and-trace serialization requirements. Seoul-based procurement teams maintain dedicated colorant engineering functions for direct pigment qualification.
Fluorescent Pigments Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in fluorescent pigment supply. Integrated resin producers with captive polymer synthesis capabilities command margin concentration in automotive and safety equipment segments. Specialist compounders compete through regulatory certification depth and application-specific particle size expertise. Strategic moves center on backward integration into resin matrices and geographic expansion into underpenetrated certification markets.
Among integrated leaders, DayGlo Color Corp exemplifies the captive polymer synthesis archetype, while Radiant Color NV occupies a position within the European regulatory certification tier. Sinloihi Co., Ltd. represents the Asian electronics packaging specialist archetype. These three companies anchor distinct competitive vectors: upstream resin control, regulatory compliance depth, and dye-doped polymer miniaturization respectively.
| Leading Market Players |
|---|
| Wanlong Chemical Co., Ltd. |
| Aron Universal Limited |
| DayGlo Color Corp |
| Brilliant Group Inc. |
| Vicome Corp |
| Radiant Color NV |
| Sinloihi Co., Ltd. |
| Wuxi Minghui International Trading Co., Ltd. |
| Luminochem |
| Others |
Cost & Logistics Intelligence
REACH Annex XVII cadmium pigment sunset clauses gate both supplier qualification and price tiering in European safety equipment procurement. Automotive OEMs in Germany demand migration resistance certification that extends qualification cycles to 18-24 months, compressing margin for uncertified compounders while concentrating premium pricing among qualified polymer-encapsulated suppliers.
Pricing Analysis
Long-term offtake contracts dominate automotive and electronics procurement, with spot purchasing limited to textile and packaging commodity grades. Three-tier pricing structure across premium, standard, and economy levels separates polymer-encapsulated automotive grades from organic printing formulations and inorganic legacy stocks. Cost compression in organic pigment tiers intensifies because Indian textile hubs drive volume bidding. Safety equipment manufacturers show highest price sensitivity, while German automotive tier-one suppliers accept certification premiums.
Supply Chain Analysis
Antwerp-Rotterdam chemical corridor transit underwrites European polymer synthesis supply for daylight-fluorescent formulations. Captive production clusters in the Ohio River Valley, Germany, and China draw from styrene and acrylic monomer feedstocks. Single-source vulnerability concentrates in specialized milling equipment for 1-10 micron particle distribution. Distribution runs through direct technical sales for automotive grades and distributor networks for printing applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification fragmentation across quantum dot displays, polymer-encapsulated automotive interiors, and UV-fluorescent pharmaceutical authentication creates defendable niches for differentiated entrants. REACH compliance deadlines and ECHA hazard reclassifications accelerate substitution timelines, rewarding early reformulators.
For Market Incumbents: Compound regulatory certification depth with backward integration into resin matrices to capture margin upstream from compounders. DayGlo Color Corp's captive polymer synthesis model demonstrates how integrated production defends against styrene price volatility. Lock 18-24 month automotive qualification cycles through proprietary migration resistance testing protocols that exceed SAE J1885 baselines. For New Entrants and Emerging Players: Lead with Bureau of Indian Standards certification for high-visibility mining apparel, where polymer-encapsulated penetration remains underdeveloped. UV-fluorescent narrow-web printing for pharmaceutical serialization offers specification channels distinct from commodity ink markets. Partner with Indian state procurement agencies on safety equipment tenders to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: ECHA's 2025 cadmium pigment sunset reshapes the acquisition landscape toward polymer-encapsulated specialists with locked automotive contracts. Five-to-ten year viability favors compounders with dual REACH-RoHS certification depth and display backlight quantum dot partnerships. Monitor EU Green Deal aromatic amine hazard reclassifications as inflection signals for accelerated substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Matrices | Captive styrene-acrylic synthesis captures margin from Ohio River Valley petrochemical complexes. |
| REACH Annex XVII Certification Investment | ECHA compliance locks procurement contracts with Volkswagen and BMW interior component suppliers. |
| Quantum Dot Partnership with Display Manufacturers | Samsung SDI and Taiwan OEMs specify cadmium-free formulations for LCD-OLED backlight enhancement. |
| Bureau of Indian Standards Safety Equipment Entry | DGFT import monitoring creates first-mover advantage in underpenetrated mining sector procurement. |
| UV-Fluorescent Pharmaceutical Serialization Capacity | FDA track-and-trace mandates and state cannabis tracking programs converge on authentication demand. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with pigment compounders, automotive tier-one procurement officers, and ECHA regulatory affairs specialists; and secondary validation through customs trade data, SEC chemical sector filings, and REACH Annex XVII substance restriction databases. Bottom-up volume modeling triangulated against top-down value estimates from production capacity disclosures.
Across the projection horizon, the analytical framework segmented by chemistry class, application vertical, and end-use industry intensity. CAGRs derived from production volume trajectories and specification-driven price tier movements. Key inputs included automotive OEM content-per-vehicle forecasts and display backlight quantum dot penetration curves.
Forecasts assume regulatory continuity in REACH and RoHS enforcement regimes; material policy shifts would require re-modeling cadmium substitution timelines and aromatic amine hazard classifications. Practitioners should keep alternative scenarios live as EU Green Deal chemical hazard reclassifications and China dual carbon implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
LAMEA Optical Brighteners Market
Dyes and Pigments
Indigo Carmine Market
Dyes and Pigments
Mulch Colorants Market
Dyes and Pigments
Phthalocyanine Blue Market
Dyes and Pigments
Thermochromic Pigments Market
Dyes and Pigments
Complex Inorganic Color Pigments Market
Dyes and Pigments
Plastic Color Concentrates Market
Dyes and Pigments
Acid Stable Blue Market
Dyes and Pigments
Global White Inorganic Pigments Market
Dyes and Pigments
Oil-Dispersible Colors Market
Dyes and Pigments
Acid Violet 43 Market
Dyes and Pigments
Iridescent Pigments Market
Dyes and Pigments
Dyes and Pigments Market
Dyes and Pigments
Global Organic Pigments Market
Dyes and Pigments
Photochromic Pigments Market
Dyes and Pigments
Ponceau 4R Colors Market