
 Floating Covers Market | 2026-2036
Floating Covers Market Size, Share, and Industry Trends Forecast 2026-2036
Floating Covers Market Analysis
The floating covers industry is restructuring around a sharp split between premium engineered systems and commodity-grade polyethylene sheeting. Raven Industries leverages its vertical integration in geomembrane manufacturing to dominate the high-performance tier for industrial containment. Cooley Group differentiates through specialized coating technologies that extend product lifespans in harsh chemical environments. Nilex Inc. competes aggressively on installation scale across North American municipal contracts.
Floating covers are impermeable barrier systems, typically fabricated from reinforced polyethylene or EPDM rubber with thicknesses ranging from 30 to 150 mils, designed to suppress evaporation, control odors, and prevent contamination in liquid storage reservoirs. The multi-span product category leads installed base due to its structural adaptability across large-diameter tanks, while the modular segment records the fastest growth trajectory as operators prioritize phased capital deployment and maintenance access. HDPE material formulations anchor the commodity volume tier, though EPDM commands premium positioning in high-temperature and chemically aggressive wastewater environments.
EPA effluent limitation guidelines under the Clean Water Act shape product specifications for municipal wastewater applications, while ECHA REACH restrictions on phthalate plasticizers redirect European material formulation strategies toward bio-based alternatives. California's State Water Resources Control Board enforces the nation's most stringent evaporation control mandates for agricultural reservoirs, directly stimulating regional demand. Stakeholders must monitor the divergence between state-level water loss regulations and federal infrastructure funding cycles to time capacity investments effectively.
Market Dynamics
The floating covers market is bifurcating sharply between engineered multi-span systems for industrial containment and modular polyethylene sheeting for agricultural reservoirs, as municipal wastewater utilities confront EPA effluent standards while California growers face evaporation mandates.
Growth Catalysts
- EPA effluent limitation guidelines:Municipal wastewater treatment plants across the United States are retrofitting anaerobic digesters with gas-tight covers to capture biogas and meet Clean Water Act discharge standards.
- California State Water Resources Control Board mandates:Agricultural districts in the Central Valley must deploy evaporation suppression systems on irrigation reservoirs exceeding specific surface area thresholds.
- EPDM material advances:Formulation improvements extending service life in high-temperature wastewater environments are displacing HDPE in chemically aggressive industrial containment applications.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and propylene price swings directly compress geomembrane producer margins and destabilize project quoting cycles.
- Installation labor scarcity:Certified geomembrane welding technicians concentrate in the US Gulf Coast and Western Europe, creating deployment bottlenecks for remote municipal contracts.
- ECHA REACH compliance costs:European manufacturers face reformulation expenses to eliminate phthalate plasticizers from PVC-based cover systems.
Strategic Opportunities
- Floating solar integration:Photovoltaic panel mounting systems on reservoir covers are creating dual-revenue streams for water utilities in Australia and Japan.
- Phased capital deployment:Modular cover segments allow agricultural cooperatives to install evaporation barriers incrementally across multi-year budget cycles.
- Biogas capture optimization:Anaerobic digester covers with integrated gas collection are penetrating underpenetrated municipal markets in Brazil and India.
Industry Challenges
- Geomembrane welding certification timelines:The shortage of International Association of Geosynthetic Installers-certified technicians delays project commissioning for municipal utilities.
- Legacy reservoir structural assessment:Pre-installation geotechnical evaluation of aging concrete tanks adds cost and schedule risk to retrofit projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floating Covers Market |
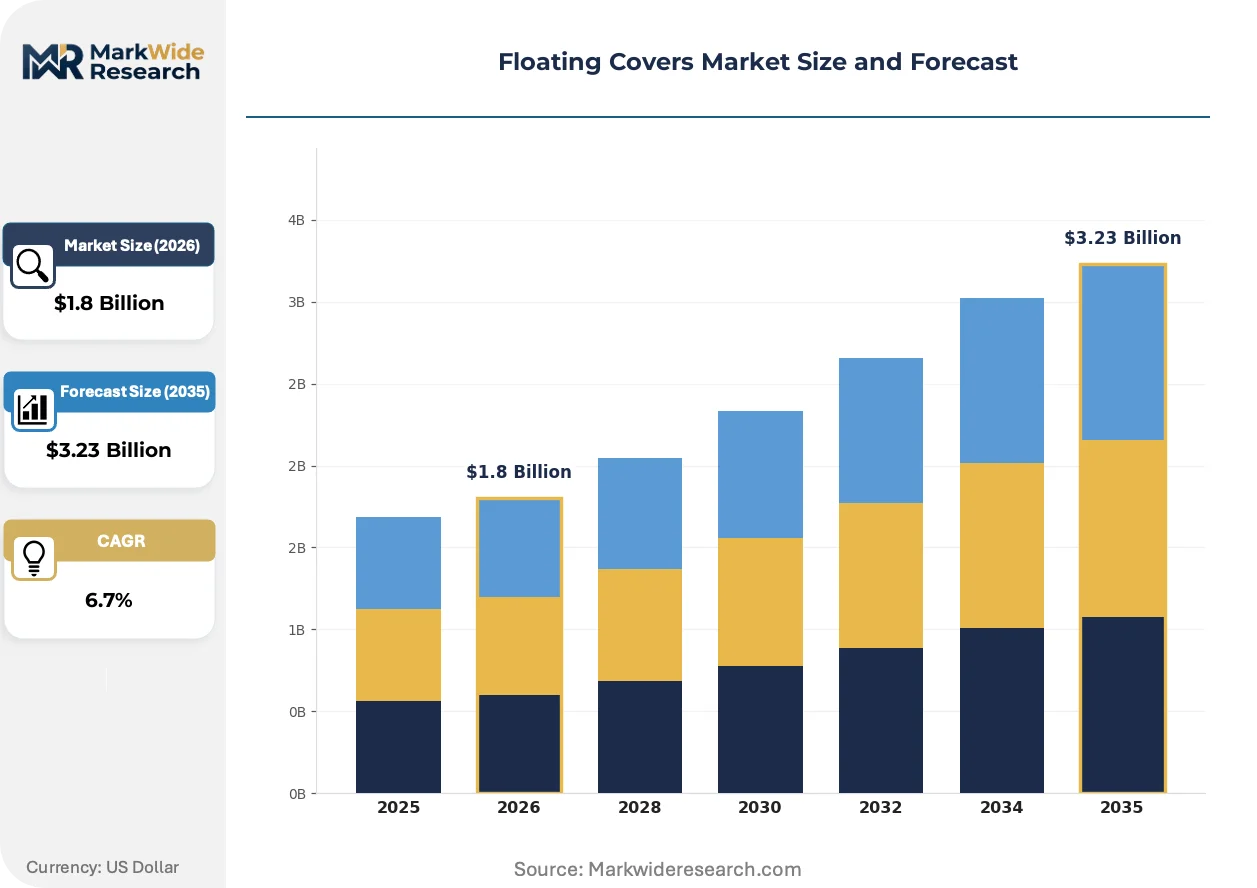
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Span, Multi-Span, Geodesic, Modular End User: Agriculture, Wastewater Treatment, Industrial, Aquaculture Material: Polyethylene, PVC, HDPE, EPDM Application: Water Conservation, Pollution Control, Energy Management, Environmental Protection |
| Companies Covered | Raven Industries Inc., GSE Environmental, Inc., Royal TenCate, Cooley Group, Nilex Inc., Hexa-Cover A/S, FLI France SAS, Advanced Water Treatment Technologies, Aquatan (Pty) Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floating Covers Market Emerging Trajectories
Material science breakthroughs and regulatory tightening are compressing product lifecycles while opening new application frontiers for advanced barrier systems. Three developments are restructuring competitive positioning.
Reinforced ethylene propylene diene monomer (EPDM) formulations with enhanced UV stabilizers and puncture resistance are electrifying the high-performance tier of industrial wastewater containment. Municipal utilities in the US Northeast are specifying these systems for anaerobic digesters operating at elevated temperatures. The technology is compressing replacement cycles for commodity HDPE installations while commanding premium positioning in chemically aggressive environments.
ECHA REACH restrictions on persistent organic pollutants and phthalate plasticizers are forcing European geomembrane producers toward bio-based polymer alternatives and non-toxic curing agents. Industrial compounders in Germany and the Netherlands are reformulating standard PVC cover systems to maintain CE marking compliance. The regulatory pressure is accelerating R&D investment in thermoplastic elastomer substitutes across the EU manufacturing base.
Water utilities are unbundling cover system procurement from installation services, creating specialized contracting opportunities for regional geosynthetic installers. Municipal buyers in California and Texas now separate material supply contracts from field welding and deployment work. This purchasing pattern shift is most visible in large-diameter agricultural reservoirs where phased installation across multiple growing seasons reduces capital strain on irrigation districts.
Floating Covers Market Segmentation
Floating cover procurement splits sharply between engineered systems for industrial containment and commodity-grade solutions for agricultural reservoirs. Understanding these segment boundaries clarifies where specification intensity drives premium pricing versus where volume scale dominates supplier selection.
Product Type:
Volume deployment concentrates in standardized geometries for agricultural reservoirs, while premium engineered systems command municipal and industrial specifications.
- Multi-Span:Reinforced membrane systems spanning 100+ meter diameters with tension cable support networks. Demand concentrates in US municipal wastewater treatment plants retrofitting anaerobic digesters to capture biogas under EPA effluent guidelines. The structural adaptability across irregular tank geometries sustains specification dominance.
- Modular:Interconnected panel arrays allowing phased installation and maintenance access. California Central Valley irrigation districts deploy these across multi-year budget cycles to comply with State Water Resources Control Board evaporation mandates. The segment is gaining share fastest among capital-constrained agricultural cooperatives.
- Single-Span:Unitary membrane designs for small-diameter tanks under 30 meters. Aquaculture operators in Vietnam and Indonesia specify these for shrimp farm oxidation ponds.
- Geodesic:Rigid structural frameworks supporting membrane tension. Industrial containment facilities in Germany's chemical corridor deploy these for stormwater retention basins under ECHA REACH compliance requirements.
Mature deployment sits with Multi-Span systems. Newer deployment is concentrated in Modular configurations.
End User:
Application intensity varies dramatically across customer types, with regulatory pressure intensity determining specification grade and replacement frequency.
- Wastewater Treatment:Municipal utilities deploy gas-tight covers for anaerobic digesters and odor control basins. US plants confront EPA Clean Water Act effluent limitations driving biogas capture retrofits. The segment commands the highest specification intensity and longest service contracts.
- Agriculture:Irrigation districts suppress reservoir evaporation under water loss regulations. California's Central Valley represents the most concentrated demand geography globally. Volume scale here dwarfs other segments but at compressed price points.
- Industrial:Chemical processors and mining operations contain stormwater and process liquids. Australian iron ore facilities specify heavy-duty EPDM formulations for UV and abrasion resistance.
- Aquaculture:Fish and shrimp farms control temperature and prevent predation. Southeast Asian operators prioritize low-cost polyethylene sheeting for oxidation pond coverage.
Procurement sophistication peaks with Wastewater Treatment. Price sensitivity concentrates in Aquaculture.
Material:
Formulation selection tracks chemical exposure severity and temperature exposure, creating a clear performance hierarchy.
- EPDM:Ethylene propylene diene monomer rubber formulations with enhanced UV stabilizers for high-temperature wastewater environments. US Northeast municipal digesters specify these for service temperatures exceeding 60°C. The material commands premium positioning in chemically aggressive containment.
- HDPE:High-density polyethylene anchors the commodity volume tier for agricultural evaporation control. California irrigation districts source these in 30-60 mil thicknesses for cost-efficient reservoir coverage. The material dominates installed base by area covered.
- Polyethylene:Linear low-density formulations for temporary or seasonal deployment. Small-scale aquaculture operators in Brazil and Mexico utilize these for budget-constrained projects.
- PVC:Polyvinyl chloride systems face reformulation pressure under ECHA REACH phthalate restrictions. European manufacturers are shifting toward bio-based plasticizer alternatives to maintain CE marking compliance.
Specification intensity clusters with EPDM. Volume deployment aggregates around HDPE.
Application:
Functional requirements determine cover system complexity, with single-purpose agricultural solutions contrasting against multi-function industrial installations.
- Water Conservation:Evaporation suppression for irrigation reservoirs and municipal storage. California's agricultural districts drive specification volume under state-mandated water loss reduction targets. The application represents the largest addressable surface area.
- Energy Management:Biogas capture from anaerobic digesters combined with floating solar mounting. Japanese water utilities are pioneering photovoltaic integration for dual revenue streams. The application commands the highest system integration complexity.
- Pollution Control:Odor containment and volatile organic compound suppression. US municipal plants near residential boundaries specify gas-tight EPDM systems under EPA air quality enforcement.
- Environmental Protection:Stormwater containment and spill prevention at industrial facilities. German chemical producers deploy these under Federal Water Act incident prevention requirements.
Deployment maturity centers on Water Conservation. Technology integration is advancing fastest in Energy Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fresno anchors global deployment intensity for agricultural floating covers, with California's Central Valley irrigation districts driving concentrated demand under state evaporation mandates.
United States
Municipal wastewater utilities across the US Northeast retrofit anaerobic digesters with gas-tight covers to capture biogas. EPA effluent limitation guidelines under the Clean Water Act mandate these upgrades. Fresno and Bakersfield agricultural clusters deploy HDPE covers on irrigation reservoirs exceeding state-mandated surface area thresholds.
Germany
Chemical producers in the Rhine-Ruhr corridor specify geodesic floating covers for stormwater retention basins. ECHA REACH restrictions on phthalate plasticizers force geomembrane reformulation toward bio-based alternatives. Stuttgart industrial compounders accelerate R&D investment in thermoplastic elastomer substitutes to maintain CE marking compliance.
Australia
Iron ore mining facilities in Western Australia deploy heavy-duty EPDM formulations for UV and abrasion resistance. State-level water management authorities enforce evaporation control on process water ponds. Perth-based engineering contractors specialize in floating solar integration atop reservoir covers for dual revenue streams.
Brazil
Municipal utilities in São Paulo and Rio de Janeiro penetrate underpenetrated anaerobic digester markets with integrated biogas capture systems. The national water regulator establishes effluent quality benchmarks for wastewater treatment plants. Campinas agricultural cooperatives deploy modular polyethylene covers incrementally across multi-year budget cycles.
Japan
Water utilities pioneer photovoltaic panel mounting systems on reservoir covers for electricity generation and evaporation suppression. METI promotes renewable energy integration in water infrastructure. Osaka and Tokyo metropolitan districts lead technology adoption for dual-function energy management applications.
Floating Covers Market Vendor Landscape
Capital-heavy producers compete with asset-light designers as the floating covers market structures around a sharp split between premium engineered systems and commodity-grade polyethylene sheeting. Three archetypes dominate: vertically integrated geomembrane manufacturers controlling resin-to-fabrication workflows, specialized coating technology houses extending product lifespans in harsh chemical environments, and regional installation contractors competing aggressively on municipal contract scale. Competitive moves concentrate on backward integration into resin supply and geographic expansion through certified installer networks.
Within the premium engineered tier, Raven Industries Inc. and Cooley Group exemplify technology-forward positioning, while Nilex Inc. anchors the scale-driven installation contracting segment. Raven Industries Inc. represents vertically integrated geomembrane manufacturing, Cooley Group occupies specialized coating technology positioning, and Nilex Inc. sits within the regional deployment contracting archetype.
| Leading Market Players |
|---|
| Raven Industries Inc. |
| GSE Environmental, Inc. |
| Royal TenCate |
| Cooley Group |
| Nilex Inc. |
| Hexa-Cover A/S |
| FLI France SAS |
| Advanced Water Treatment Technologies |
| Aquatan (Pty) Ltd. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap geomembrane producers in Germany and the Netherlands anchor supply discipline through multi-decade resin relationships, translating captive polymer access into pricing stability for EPDM formulations while commodity HDPE sheeting faces margin compression from spot ethylene exposure.
Pricing Analysis
Outcome-based pricing tied to evaporation suppression yield anchors municipal wastewater contracts, where gas-tight EPDM systems command premiums against throughput guarantees. Price differentiation separates CE-marked REACH-compliant formulations from standard PVC alternatives. Cost compression in agricultural HDPE tiers intensifies because California irrigation districts unbundle material procurement from installation services. Aquaculture operators in Southeast Asia exhibit highest price sensitivity, while US Northeast municipal utilities prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale municipal demand, while regional installer networks serve fragmented agricultural buyers. Manufacturing concentrates in the United States, Germany, and China. Resin supply draws from ethylene and propylene feedstocks, with UV stabilizers and reinforcement scrim as critical additives. Single-source vulnerability sits with International Association of Geosynthetic Installers-certified welding technicians concentrated on the US Gulf Coast. Distribution runs through specialized geosynthetic distributors and EPC contractors for integrated deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as ECHA REACH reformulation costs force smaller European PVC compounders toward distressed exits or strategic sale.
For Market Incumbents: Lock in resin supply through captive ethylene offtake agreements or backward integration into polymer production. Secure IAGI-certified installer networks in California and Texas to control deployment capacity. The regulatory shift toward bio-based plasticizers threatens legacy PVC formulators lacking R&D scale. For New Entrants and Emerging Players: Regional geosynthetic installation contractors offer partnership pathways into municipal wastewater retrofit cycles. Brazil and India present the most penetrable geographies for anaerobic digester biogas capture systems. A specialized coating technology angle—extending EPDM service life in high-temperature environments—opens differentiated positioning against commodity HDPE suppliers. For Investors and Strategic Acquirers: Distressed-cycle entries favor European PVC compounders facing REACH compliance cost overruns in Germany and the Netherlands. Long-term viability centers on material science capabilities transferable across geomembrane formulations. Watch for EPA effluent guideline enforcement intensity as the inflection signal for US municipal retrofit acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive ethylene access insulates EPDM producers from petrochemical volatility in Germany. |
| Certified Installer Network Expansion | IAGI-trained welding technicians reduce commissioning delays for California municipal contracts. |
| REACH-Compliant Formulation R&D | Bio-based plasticizer development preserves CE marking for European geomembrane manufacturers. |
| Floating Solar Integration Partnerships | Photovoltaic mounting systems create dual-revenue streams for Japanese water utilities. |
| Modular Cover Product Line Extension | Phased deployment aligns with agricultural cooperative budget cycles in Brazil. |
Methodological Framework
Trade association filings, customs export records, and EPA enforcement databases formed the secondary backbone, cross-referenced against primary interviews with municipal wastewater procurement officers, geomembrane plant managers, certified welding technicians, and agricultural district engineers. Bottom-up and top-down triangulation validated volume estimates across product tiers.
Bottom-up modeling anchored demand projections across material formulation, end-use application, and regional regulatory cluster dimensions, while top-down macroeconomic filters tested sensitivity to infrastructure spending cycles. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EPDM service life extension data and California evaporation mandate compliance timelines.
Caveats apply where ECHA REACH enforcement intensity or EPA effluent guideline revisions could materially shift the outlook. Forecasts reflect assumptions about petrochemical feedstock stability and certified labor availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Agricultural Trailer Market
Agricultural Equipment
Vegetable Sorting Machines Market
Agricultural Equipment
Manure Separator Market
Agricultural Equipment
Solar Insect Trap Market
Agricultural Equipment
Sheep Shearing Equipment Market
Agricultural Equipment
Global Grain Bin Management Solution Market
Agricultural Equipment
Agriculture Seeder Market
Agricultural Equipment
Battery-Operated Knapsack Sprayer Market
Agricultural Equipment
Garden Tools Market
Agricultural Equipment
Irrigation Syringe Market
Agricultural Equipment
Heavy Tooth Drag Harrows Market
Agricultural Equipment
Grafting Knives Market
Agricultural Equipment
Gardening Tools Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Battery Powered Sprayer Market
Agricultural Equipment
Livestock Grow Lights Market