
 Global Grain Bin Management Solution Market | 2026-2036
Global Grain Bin Management Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Global Grain Bin Management Solution Market Foresight
Precision agriculture engineering talent is rotating toward IoT-enabled storage infrastructure, tightening labor availability for legacy mechanical systems. AGI SureTrack leverages its channel dominance across North American grain cooperatives to sustain recurring software revenue. TSGC anchors its position through deep specialization in temperature cabling and sensor hardware for commercial elevators. OPI Systems differentiates via integrated carbon monitoring features that respond to emerging sustainability audit requirements.
Grain bin management solutions encompass hardware-software systems that monitor and control stored grain conditions through IoT sensor networks, cloud platforms, and automated aeration or conditioning equipment, typically maintaining temperatures between 10-15°C and moisture below 14% to prevent spoilage, mold, and pest infestation across months-long storage cycles. Environmental monitoring and automation control segments lead current revenue as baseline investments for large operators, while AI and machine learning integration within data analytics represents the fastest-expanding margin pool as predictive spoilage models reduce insurance and write-off costs. Edge computing architectures are gaining traction in remote farming regions with unreliable connectivity, enabling real-time local decision-making without full cloud dependency.
The EPA enforces air quality and fumigation chemical handling standards that shape ventilation system specifications and sensor calibration protocols for U.S. grain facilities. ECHA's REACH framework and the EU F-Gas Regulation restrict certain refrigerants and chemical treatments used in European grain preservation, pushing adoption toward non-chemical monitoring alternatives. China's GB standards for grain storage safety and NMPA-aligned food security mandates accelerate domestic sensor deployment. Stakeholders must weigh regulatory compliance timelines against technology refresh cycles when committing to platform investments.
Market Dynamics
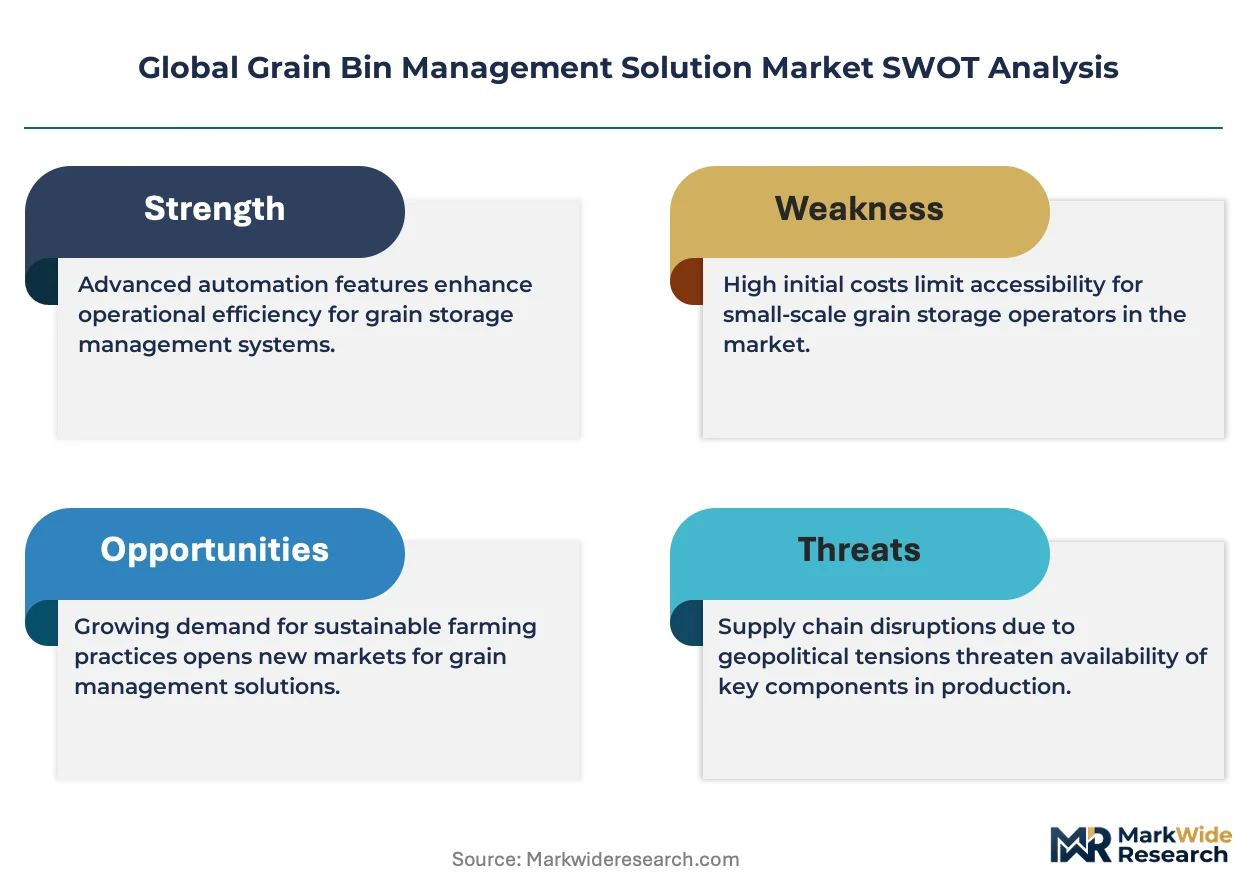
The convergence of EPA emissions mandates with EU Farm to Fork sustainability requirements is forcing grain operators to replace legacy mechanical aeration with sensor-driven, condition-based preservation systems that generate auditable environmental data.
Growth Catalysts
- IoT Sensor Networks:Cloud-connected temperature and moisture probes enable real-time spoilage alerts across multi-bin facilities, reducing insurance deductibles for commercial elevators in the United States Corn Belt.
- REACH Chemical Restrictions:ECHA's tightening limits on phosphine fumigants push European grain cooperatives toward non-chemical monitoring alternatives using automated aeration triggers.
- Carbon Accounting Mandates:The EU Green Deal's embedded emissions tracking requirements create demand for integrated carbon monitoring modules that quantify storage-phase energy and spoilage-related CO2.
Market Restraints
- Copper and Semiconductor Input Costs:Temperature cabling and edge computing hardware face raw material price volatility that compresses hardware margins for system integrators.
- Connectivity Infrastructure Gaps:Remote farming regions in Brazil's Mato Grosso corridor lack reliable cellular coverage, limiting cloud-dependent platform deployment without costly satellite uplink investment.
- Legacy Equipment Lock-in:Decades-old steel bin infrastructure with incompatible access points creates retrofit friction that slows upgrade cycles at family-owned farming operations.
Strategic Opportunities
- Ukraine Post-Conflict Reconstruction:Black Sea grain hub modernization will require complete sensor infrastructure replacement, creating first-mover advantage for integrated platform vendors.
- AI Predictive Models:Machine learning spoilage forecasting trained on historical weather and grain-quality datasets enables outcome-based pricing tied to guaranteed preservation performance.
- India FSSAI Cold Chain Alignment:India's food safety regulator is extending traceability mandates from processing back to storage, opening premium market entry for certified monitoring systems.
Industry Challenges
- Precision Agriculture Talent Migration:Embedded systems engineers and IoT firmware developers are exiting mechanical agriculture equipment firms for software-centric storage technology vendors, hollowing legacy R&D benches.
- Multi-Protocol Integration Complexity:Grain operators demand seamless data flow between bin sensors, elevator management software, and commodity trading platforms, requiring costly custom API development.
- Calibration Certification Burden:EPA and state-level weights-and-measures authorities impose recurring sensor accuracy verification that adds operational overhead and downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Grain Bin Management Solution Market |
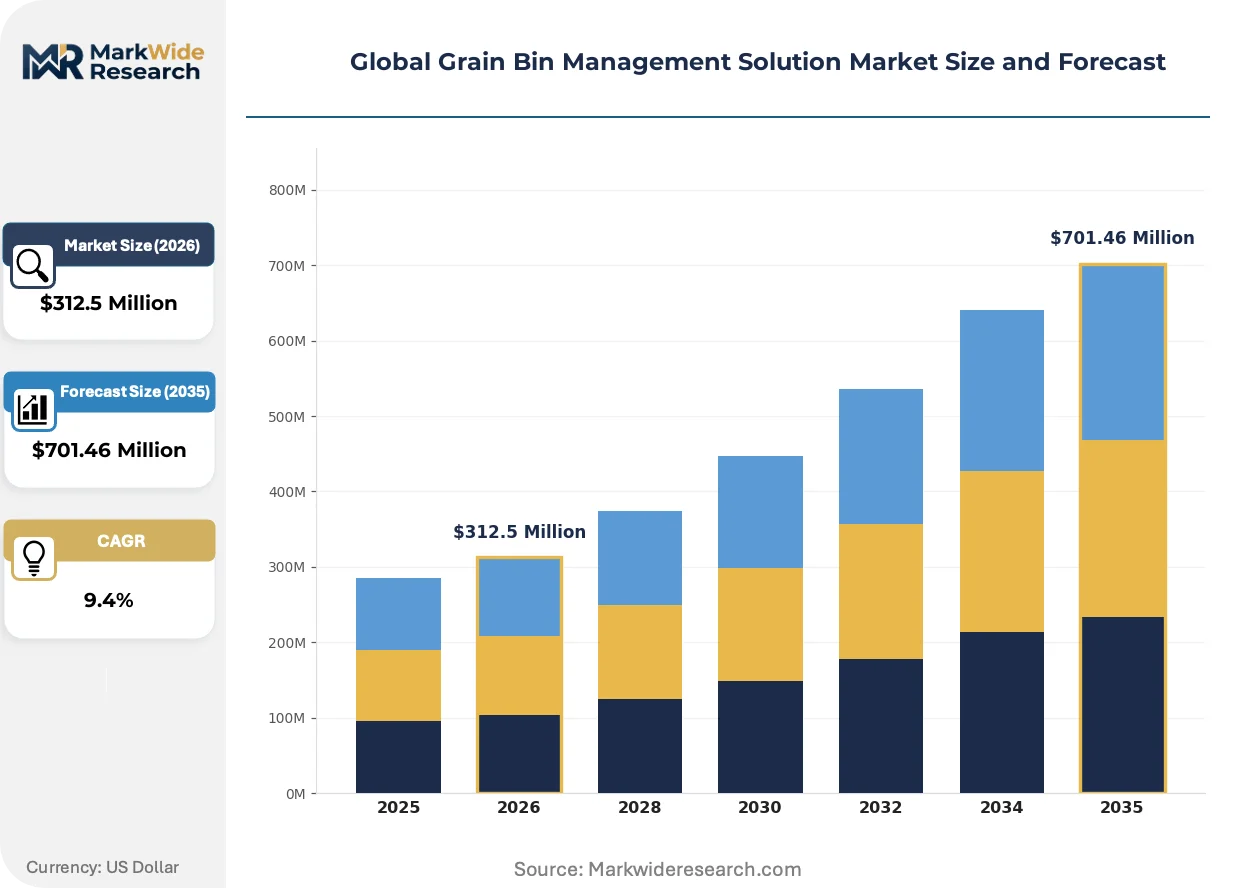
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $701.46 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Environmental Monitoring, Inventory Tracking, Automation Control, Data Analytics, Remote Management Technology: IoT Sensors, Cloud Computing, Wireless Communication, AI & Machine Learning, Edge Computing Application: Temperature Control, Humidity Regulation, Grain Level Measurement, Pest Detection, Grain Quality Assessment End User: Farmers, Grain Processors, Agricultural Cooperatives, Commodity Traders, Storage Facility Operators |
| Companies Covered | Ergson GmbH, TGM, AGI SureTrack, Cultura Technologies, InfoTech Solutions, TSGC, AGCO, BinManager, OPI Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Grain Bin Management Solution Market Shifts & Advancements
Edge computing architectures and predictive analytics are reconfiguring how grain operators balance capital investment against operational risk, shifting value capture from hardware sales toward data-driven service models.
LoRaWAN-enabled wireless sensor meshes is supplanting hardwired temperature cabling in new bin construction and retrofit projects across North American commercial elevators. Large cooperatives in Iowa and Illinois are specifying battery-powered, multi-year deployment nodes to eliminate conduit installation costs. This wireless migration is compressing infrastructure deployment timelines from weeks to days while reducing total installed cost.
ECHA's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in mechanical grain cooling systems, redirecting European investment toward ambient aeration with intelligent fan control. Dutch and German grain traders now require supplier documentation of refrigerant-free preservation methods to satisfy procurement sustainability scorecards. Equipment vendors are responding with expanded variable-frequency drive portfolios optimized for partial-load efficiency.
Service contract unbundling is fragmenting traditional bundled hardware-software offerings into separately priced monitoring subscriptions, aeration-as-a-service, and predictive analytics tiers. North American grain cooperatives are negotiating month-to-month sensor data access rather than perpetual licenses, pressuring vendors to demonstrate measurable spoilage reduction. This shift is most pronounced among mid-scale operators in Nebraska and Kansas seeking to convert capex into opex for cash-flow management.
Global Grain Bin Management Solution Market Segmentation
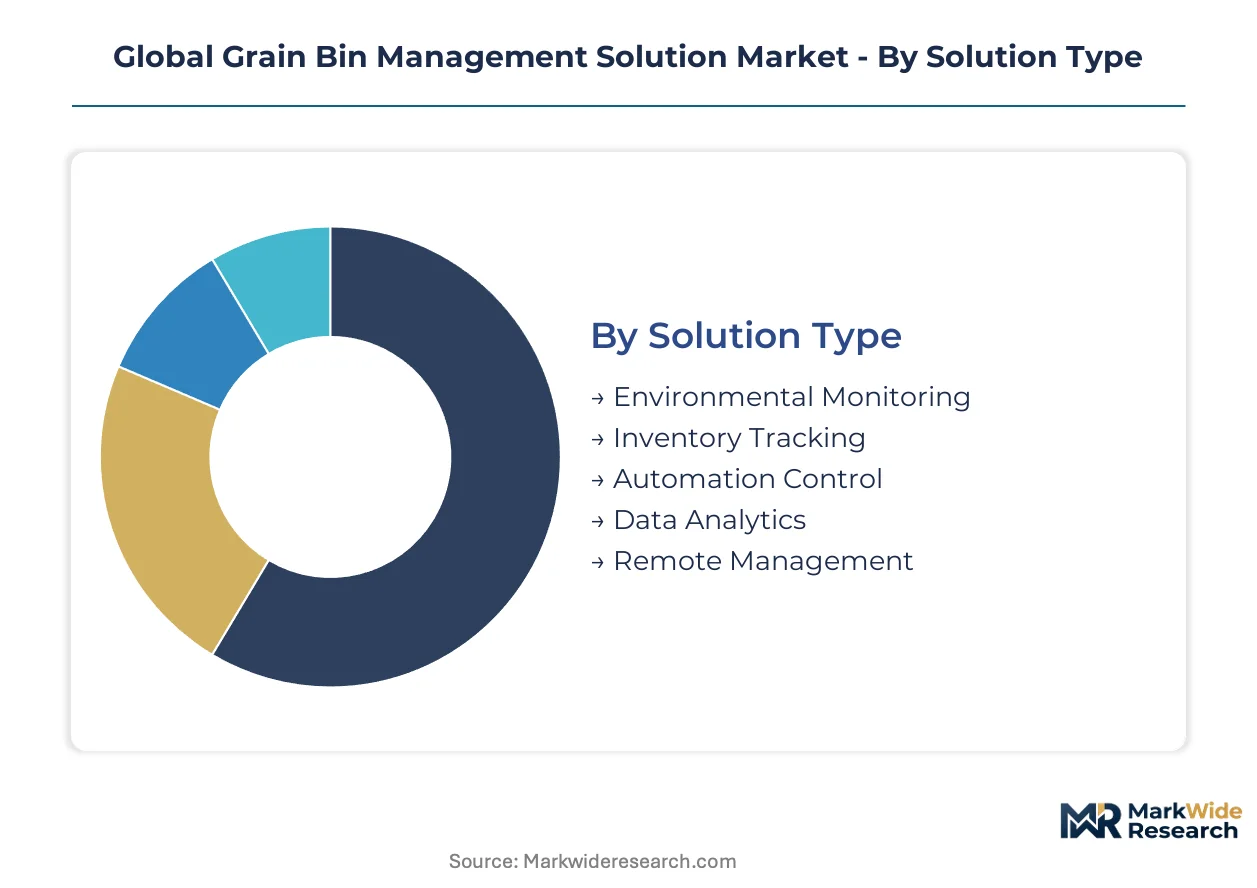
Grain bin management solutions fragment across hardware, software, and service layers that align differently with regulatory mandates and operational scale. Segmentation reveals where capital concentrates versus where subscription models are displacing perpetual licenses.
Solution Type:
EPA emissions documentation requirements and ECHA chemical handling audits are driving divergence between baseline compliance modules and premium predictive systems.
- Environmental Monitoring:Temperature and moisture sensor networks form the foundational layer for spoilage prevention, with probe density calibrated to bin volume and commodity type. Commercial elevators in the United States Corn Belt deploy multi-point cable arrays to satisfy insurance underwriters and satisfy EPA air quality record-keeping mandates.
- Data Analytics:Machine learning platforms trained on historical weather patterns and grain quality datasets enable predictive spoilage modeling that shifts pricing toward outcome-based guarantees. Agricultural cooperatives in Iowa and Illinois are unbundling analytics subscriptions from hardware procurement to convert capital expenditure into operational expenditure.
- Automation Control:Aeration fan and conditioning equipment triggers based on real-time sensor thresholds.
- Inventory Tracking:Level sensors and mass flow measurement for quantity verification and logistics planning.
- Remote Management:Cloud dashboards and mobile applications for distributed facility oversight.
Established volume favors Environmental Monitoring; emerging adoption favors Data Analytics.
Technology:
Connectivity infrastructure maturity in target geographies determines deployment feasibility and total cost of ownership.
- IoT Sensors:Hardwired temperature cabling dominates commercial elevator retrofits for reliability, while LoRaWAN wireless nodes gain share in new construction. Battery-powered multi-year deployment sensors eliminate conduit installation costs and compress deployment timelines across North American grain cooperatives.
- Edge Computing:Local processing architectures enable real-time aeration decisions without cloud dependency, critical for Brazil's Mato Grosso corridor where cellular coverage gaps would otherwise require costly satellite uplink investment. Dutch grain traders specify edge-capable systems to satisfy EU Green Deal embedded emissions tracking without connectivity interruption risk.
- Cloud Computing:Centralized data storage and analytics processing for multi-facility operators.
- Wireless Communication:Cellular, LoRaWAN, and satellite protocols for sensor data transmission.
- AI & Machine Learning:Predictive algorithms for spoilage forecasting and optimal aeration scheduling.
Hardware procurement concentrates with IoT Sensors; recurring revenue expansion concentrates with Edge Computing.
Application:
Climate severity and commodity value density determine which preservation parameters receive capital allocation priority.
- Temperature Control:Aeration systems and cooling infrastructure maintain 10-15°C thresholds to arrest insect metabolism and mold proliferation. Ukraine's Black Sea grain hub operators prioritize temperature management given extended storage cycles and export logistics bottlenecks.
- Humidity Regulation:Moisture content suppression below 14% prevents hot spot formation and mycotoxin accumulation. German grain cooperatives invest in automated humidity control to satisfy ECHA REACH framework documentation requirements for chemical-free preservation alternatives.
- Grain Level Measurement:Continuous inventory visibility for logistics and commodity trading integration.
- Pest Detection:Acoustic and infrared monitoring for insect infestation early warning.
- Grain Quality Assessment:Protein, moisture, and foreign matter testing integration.
Baseline compliance spending flows to Temperature Control; premium service contracting flows to Humidity Regulation.
End User:
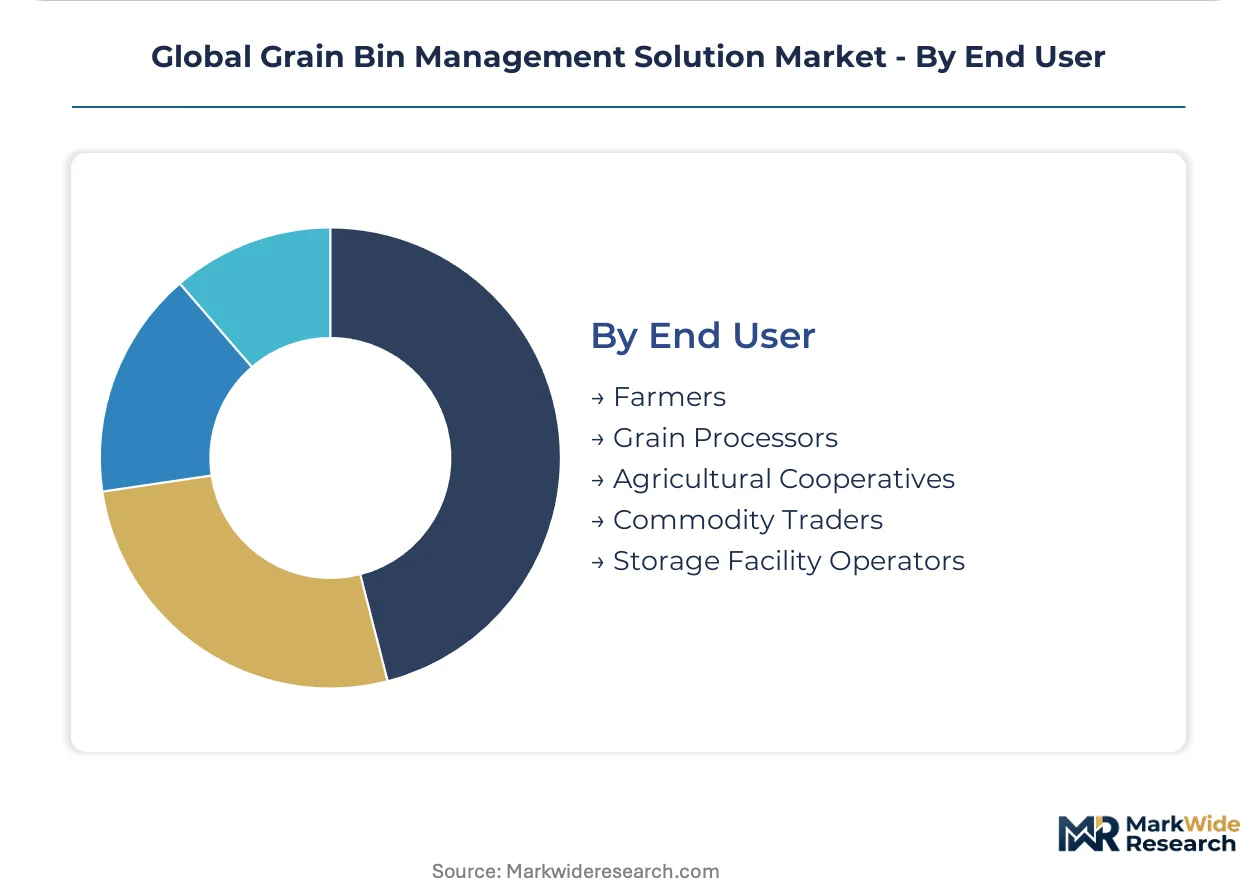
Balance sheet capacity and regulatory exposure create divergent procurement patterns across operator types.
- Grain Processors:Integrated milling and ethanol operations require seamless bin-to-plant flow visibility with ERP integration. Large-scale processors in Nebraska and Kansas specify API-connected monitoring platforms to unify elevator management software with commodity trading systems.
- Agricultural Cooperatives:Member-owned operations spread technology investment across pooled volumes, enabling sensor deployment at scale otherwise unaffordable to individual farmers. Iowa and Illinois cooperatives negotiate month-to-month sensor data access rather than perpetual licenses, pressuring vendors toward subscription pricing.
- Farmers:Family-owned operations face legacy equipment lock-in and retrofit friction.
- Commodity Traders:Storage-phase quality verification for contract fulfillment and insurance.
- Storage Facility Operators:Third-party logistics providers with multi-tenant service obligations.
Procurement standardization dominates among Agricultural Cooperatives; integration complexity concentrates among Grain Processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grain bin management solution pricing power concentrates in United States Corn Belt cooperatives, while Brazilian Mato Grosso operators absorb connectivity infrastructure premiums that compress vendor margins.
United States
EPA emissions documentation mandates and insurance underwriter requirements drive sensor deployment across Iowa and Illinois grain elevators. The agency's air quality record-keeping standards force commercial operators toward automated monitoring systems with auditable data trails. Nebraska and Kansas cooperatives negotiate month-to-month sensor subscriptions, converting capital expenditure into operational expenditure for cash-flow flexibility.
Brazil
Soybean corridor expansion in Mato Grosso creates demand for edge-computing architectures where cellular coverage gaps would otherwise require costly satellite uplinks. ANVISA-aligned food security protocols accelerate domestic sensor deployment for export quality verification. Large-scale farming operations around Rondonópolis specify battery-powered wireless nodes to eliminate conduit installation across remote bin clusters.
Germany
ECHA's REACH framework restrictions on phosphine fumigants redirect investment toward non-chemical monitoring alternatives using automated aeration triggers. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants in mechanical cooling systems. Dutch and German grain traders in Hamburg and Bremen procurement networks now require supplier documentation of refrigerant-free preservation methods.
Ukraine
Black Sea grain hub modernization will require complete sensor infrastructure replacement, creating first-mover positioning for integrated platform vendors. Extended storage cycles and export logistics bottlenecks prioritize temperature management systems. Odessa and Mykolaiv port corridor operators face reconstruction capital allocation decisions between legacy mechanical aeration and predictive analytics platforms.
India
FSSAI cold chain alignment extends traceability mandates from processing back to storage, opening premium market entry for certified monitoring systems. The regulator's food safety protocols create compliance-driven demand among grain processors in Punjab and Haryana. Maharashtra agricultural cooperatives pilot IoT-enabled inventory tracking to satisfy emerging commodity trading platform integration requirements.
Global Grain Bin Management Solution Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the grain bin management solution market. The vendor base organizes into three tiers: integrated agricultural equipment conglomerates with channel dominance, specialized sensor hardware fabricators with deep technical expertise, and software-centric platform vendors capturing recurring revenue through data analytics subscriptions. Competitive dynamics center on strategic partnerships between hardware manufacturers and cloud platform developers, alongside geographic expansion into post-conflict reconstruction markets where infrastructure replacement creates greenfield opportunities.
Among North American platform specialists, AGI SureTrack and TSGC occupy distinct positioning within the cooperative and commercial elevator segments. AGI SureTrack leverages channel relationships across grain cooperative networks to sustain software subscription revenue, while TSGC anchors its market presence through temperature cabling and sensor hardware specialization. OPI Systems exemplifies the sustainability-integrated archetype, with carbon monitoring capabilities responding to EU Green Deal embedded emissions tracking requirements. Ergson GmbH represents European engineering-focused competition, reflecting ECHA regulatory alignment in its market approach.
| Leading Market Players |
|---|
| Ergson GmbH |
| TGM |
| AGI SureTrack |
| Cultura Technologies |
| InfoTech Solutions |
| TSGC |
| AGCO |
| BinManager |
| OPI Systems |
| Others |
Supply & Pricing Matrix
Long-term subscription contracts with grain cooperatives in Iowa and Illinois lock in both sensor hardware supply and predictable SaaS revenue streams, insulating vendors from spot-market volatility while binding buyers to multi-year technology refresh cycles aligned with EPA calibration mandates.
Pricing Analysis
North American pricing runs 15-20% above Brazilian Mato Grosso equivalents due to connectivity infrastructure premiums and satellite uplink requirements. The market operates on a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by probe density per bin volume and EPA audit-trail certification grade. Cost compression in the standard tier is intensifying because LoRaWAN wireless nodes displace hardwired cabling installation labor. Mid-scale agricultural cooperatives in Nebraska and Kansas exhibit highest price sensitivity, negotiating month-to-month data access, while integrated grain processors absorb premium analytics subscriptions for ERP integration.
Supply Chain Analysis
Port congestion on the Shanghai-to-Los Angeles lane elevates inbound logistics costs for copper temperature cabling and semiconductor sensor components sourced from Chinese contract manufacturers. Hardware fabrication concentrates in China, Mexico, and Germany, with final assembly drawing from Taiwanese edge-computing module suppliers. Raw material dependencies span copper wiring, lithium battery cells for wireless nodes, and silicon MEMS sensors. Single-source vulnerability in MEMS foundry capacity represents the dominant supply chain risk. Distribution runs through North American agricultural equipment dealer networks and European grain cooperative procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded firmware engineering talent for IoT sensor networks has become the constraining asset, with precision agriculture developers migrating toward software-centric storage platforms and hollowing legacy mechanical equipment R&D benches.
For Market Incumbents: Consolidate channel control across grain cooperative networks before subscription unbundling fragments customer relationships. Acquire edge-computing firmware specialists to defend against platform-only entrants. Prioritize backward integration into MEMS sensor fabrication to reduce single-source foundry exposure. For New Entrants and Emerging Players: Predictive spoilage analytics as a standalone service layer represents the most penetrable white-space target, as incumbents under-serve mid-scale operators with bundled hardware-software lock-in. Ukraine post-conflict reconstruction offers greenfield sensor infrastructure deployment without legacy retrofit friction. Pursue outcome-based pricing models tied to guaranteed preservation performance to differentiate from capex-heavy incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward verticalized platform vendors with captive sensor hardware production and recurring SaaS revenue concentration. Long-term viability across the projection horizon hinges on regulatory compliance automation capabilities for EPA and ECHA audit requirements. Monitor ECHA phosphine fumigant restriction enforcement timelines as inflection indicator for non-chemical monitoring alternative demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Architecture Deployment | Enables real-time aeration decisions in Brazil's Mato Grosso cellular coverage gaps without satellite uplink dependency. |
| Carbon Monitoring Module Integration | Satisfies EU Green Deal embedded emissions tracking requirements for Dutch and German grain trader procurement scorecards. |
| LoRaWAN Wireless Sensor Migration | Compresses North American commercial elevator deployment timelines from weeks to days while eliminating conduit installation costs. |
| AI Predictive Spoilage Model Development | Shifts vendor pricing toward outcome-based guarantees tied to measurable insurance deductible reduction. |
| Ukraine Reconstruction Market Entry | Captures first-mover advantage in Black Sea grain hub sensor infrastructure replacement with greenfield platform deployment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with grain elevator managers, agricultural cooperative procurement officers, IoT platform engineers, and EPA compliance auditors. Secondary validation drew from EPA air quality enforcement records, ECHA REACH substance restriction updates, USDA grain storage safety bulletins, and SEC filings of publicly traded agricultural equipment manufacturers. Bottom-up sensor deployment counts by facility type were triangulated against top-down market size estimates derived from hardware bill-of-materials analysis.
Across the analysis window, volume and value outputs were modeled through segmentation by solution type, technology architecture, application priority, and end-user scale. CAGRs were derived from regression analysis of historical adoption curves in comparable precision agriculture equipment categories. Forecast inputs incorporated EPA emissions mandate implementation timelines, ECHA F-Gas Regulation phase-down schedules, and Black Sea grain corridor logistics normalization assumptions.
Underlying assumptions cover regulatory compliance timeline adherence and copper-semiconductor input cost stabilization, with deviation risk concentrated in Ukraine reconstruction capital allocation delays and Brazil connectivity infrastructure buildout pace. Practitioners should keep alternative scenarios live as ECHA chemical restriction enforcement intensity and EPA sensor calibration certification burden evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Powder Feed Center Market
Agricultural Equipment
Smart Egg Incubators Market
Agricultural Equipment
Bulk Reception Feeder Market
Agricultural Equipment
Grafting Knives Market
Agricultural Equipment
Plows Market
Agricultural Equipment
Heavy Tooth Drag Harrows Market
Agricultural Equipment
Lawn Aerators Market
Agricultural Equipment
Tree Transplanters Market
Agricultural Equipment
Fishing Net Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market
Agricultural Equipment
Pre-Harvest Equipment Market
Agricultural Equipment
North America Electric Zero Turn Mower Market
Agricultural Equipment
Global Infrared Heater for Agriculture Market
Agricultural Equipment
Floating Covers Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Aquarium Pumps and Filters Market