
 Online Food Delivery Market | 2026-2036
Online Food Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Online Food Delivery Market Intelligence
AI-powered route optimization is reconfiguring how orders move from kitchen to doorstep, compressing delivery windows while lowering per-unit labor costs. DoorDash leverages its logistics density across North American suburbs to sustain margin advantages in lower-population zones. Uber Eats anchors its position through cross-selling with ride-hail infrastructure, sharing driver pools across both services. Meituan dominates in China by integrating grocery, pharmacy, and restaurant delivery within a single super-app architecture.
Online food delivery encompasses digital platforms that connect consumers with prepared meals through algorithmic matching, real-time GPS tracking, and dynamic pricing engines operating on commission-based or subscription revenue models. The primary commercial purpose is to reduce friction between demand aggregation and last-mile fulfillment, replacing phone orders with data-driven dispatch systems. Direct delivery services currently occupy the largest volume share as consumers prioritize speed and convenience over pickup alternatives. Subscription models represent the fastest-growing structural segment, locking in recurring revenue through waived delivery fees and exclusive restaurant access. The marketplace delivery model retains the deepest margin pool by externalizing fleet costs to independent contractors while collecting commissions on gross order value.
The US Food and Drug Administration and the European Food Safety Authority enforce traceability standards that shape how platforms verify restaurant hygiene credentials and ingredient sourcing. China's State Administration for Market Regulation imposes algorithmic transparency rules that limit excessive driver dispatch pressures and mandate rest-period protocols. India's Food Safety and Standards Authority mandates hygiene ratings display, directly influencing consumer choice architecture on aggregator interfaces. Stakeholders must monitor how gig-worker reclassification rulings across multiple jurisdictions reshape cost structures and platform liability exposure.
Market Dynamics
Algorithmic dispatch systems are compressing delivery windows while fragmenting labor pools across gig-economy platforms, forcing operators to balance speed guarantees against driver retention costs.
Growth Catalysts
- Hybrid Work Normalization:Corporate meal allowances embedded in return-to-office policies are expanding B2B order volumes. Enterprises in the United States and Germany now contract directly with aggregators for subsidized employee dining programs.
- Cloud Kitchen Infrastructure:FSSAI-mandated hygiene digitization in India and ANVISA traceability protocols in Brazil are accelerating licensed dark-kitchen deployments. These regulations reduce compliance friction for delivery-only brands.
- Super-App Convergence:Integration of grocery, pharmacy, and restaurant ordering within single interfaces is virtualizing consumer wallet share. Meituan's architecture demonstrates how cross-category bundling drives platform stickiness.
Market Restraints
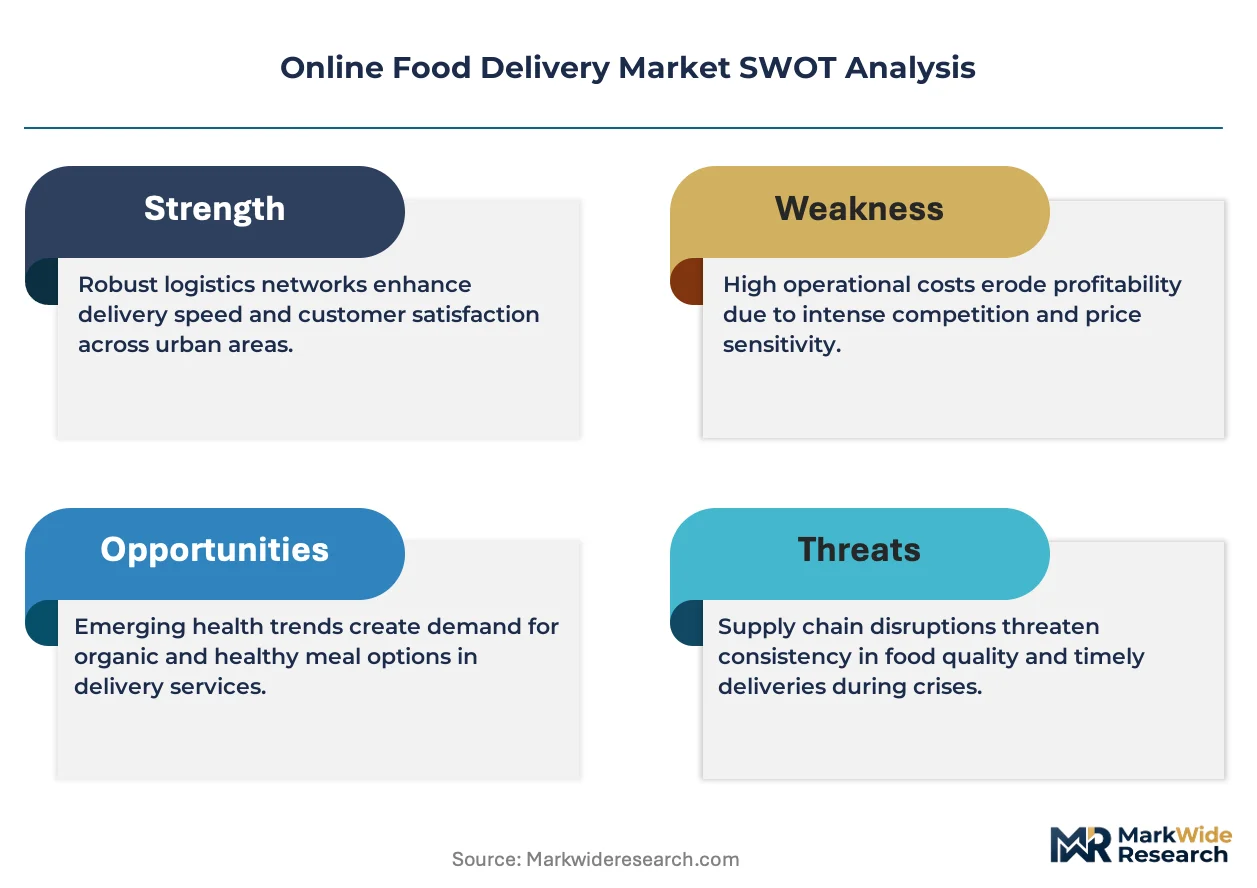
- Driver Supply Volatility:Fuel cost fluctuations and gig-worker reclassification rulings across multiple jurisdictions are destabilizing last-mile labor economics. Platforms face margin pressure from wage floor mandates.
- Commission Rate Compression:Restaurant pushback against 15-30% platform fees is forcing revenue model experimentation. Independent operators in France and Italy are organizing collective bargaining coalitions.
- Food Safety Liability:FDA traceability requirements and EFSA cold-chain standards impose documentation burdens that smaller kitchens struggle to satisfy. Compliance costs disproportionately affect single-location establishments.
Strategic Opportunities
- Suburban Penetration:Lower-density zones in the United States remain underserved relative to urban cores. DoorDash's logistics density investments demonstrate viable unit economics in exurban markets.
- Subscription Lock-In:Monthly fee structures that waive delivery charges and offer exclusive restaurant access are capturing predictable revenue streams. This model reduces per-order acquisition costs.
- EU Green Deal Alignment:Electric vehicle mandates and packaging waste directives create competitive differentiation for platforms investing in sustainable fleet transitions. Early compliance builds regulatory goodwill.
Industry Challenges
- Algorithmic Management Backlash:SAMR-mandated rest-period protocols in China and emerging EU platform work directives require fundamental dispatch system redesigns. Technical debt from legacy routing engines complicates adaptation.
- Kitchen-to-Door Coordination:Synchronizing food preparation timing with driver arrival windows demands real-time inventory integration. Fragmented POS systems across independent restaurants create data interoperability gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Food Delivery Market |
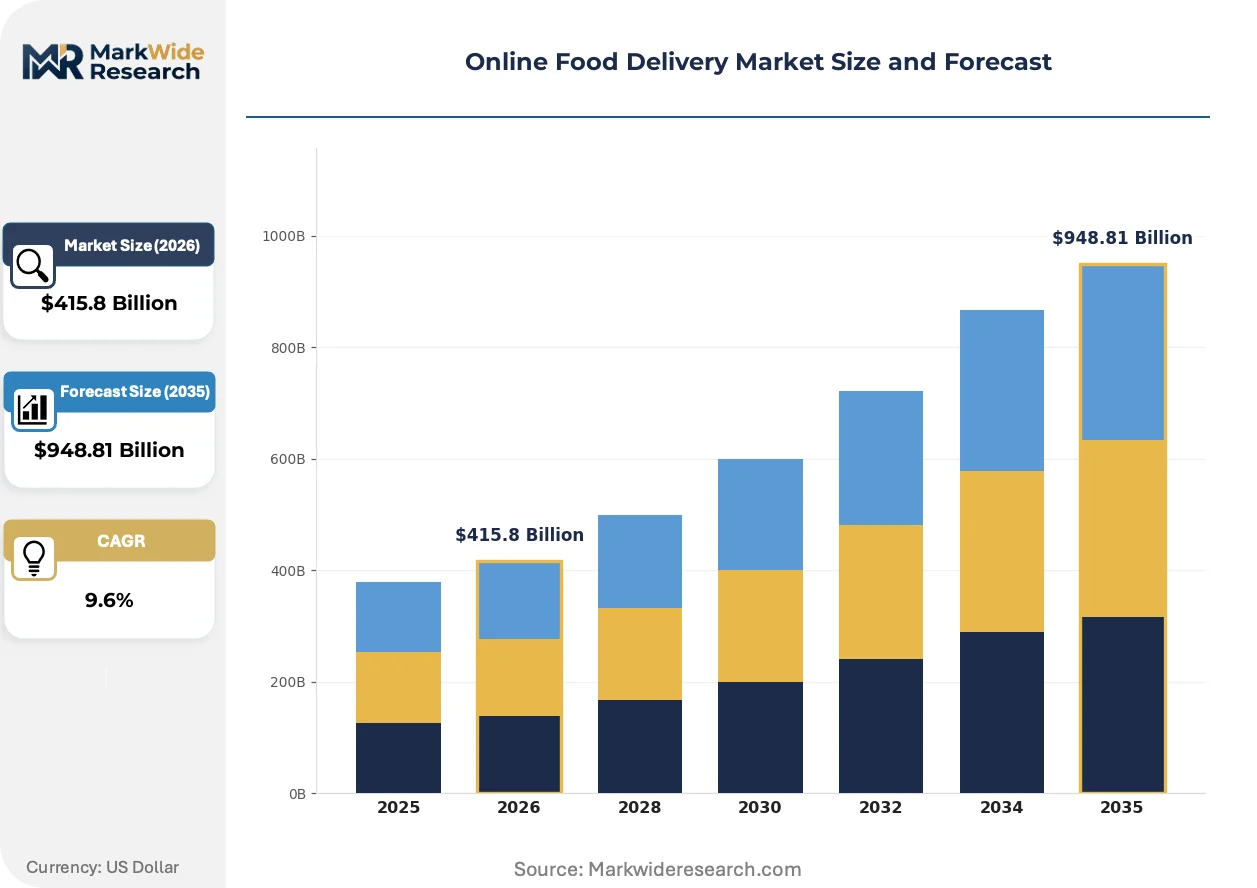
| Market Size in 2026 | $415.8 Billion |
| Market Size in 2035 | $948.81 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Direct Delivery, Pickup, Subscription, Group Ordering Customer Type: Corporate Clients, Families, Students, Singles Cuisine Type: Italian, Chinese, Indian, Mexican Delivery Model: Marketplace, Restaurant-Direct, Hybrid, Franchise |
| Companies Covered | DoorDash, Uber Eats, Meituan, Zomato, Just Eat Takeaway.com, Delivery Hero, Swiggy, Deliveroo, Grab Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Food Delivery Market Strategic Shifts & Innovations
Digital infrastructure is collapsing the traditional restaurant value chain, replacing fixed-location dining with variable-capacity production nodes and algorithmic demand forecasting.
Dark kitchen networks are virtualizing real estate requirements for food service entry. Real estate investors and restaurant groups are deploying modular production facilities in industrial zones rather than prime retail corridors. This infrastructure shift is virtualizing the capital barrier between concept launch and scaled operations.
SAMR algorithmic transparency rules and EU platform work directives are reclassifying driver status across multiple jurisdictions. These frameworks impose rest-period mandates and limit dispatch optimization intensity. Gig-economy platforms in China and Germany are responding by restructuring incentive architectures to maintain throughput under regulatory ceilings.
Corporate procurement of subsidized meal programs is displacing individual consumer decision-making in urban employment centers. Human resources departments now negotiate enterprise rates with aggregators, consolidating order volume under contracted terms. This concentration is most visible in technology and financial services clusters across the United States and United Kingdom.
Online Food Delivery Market Segmentation
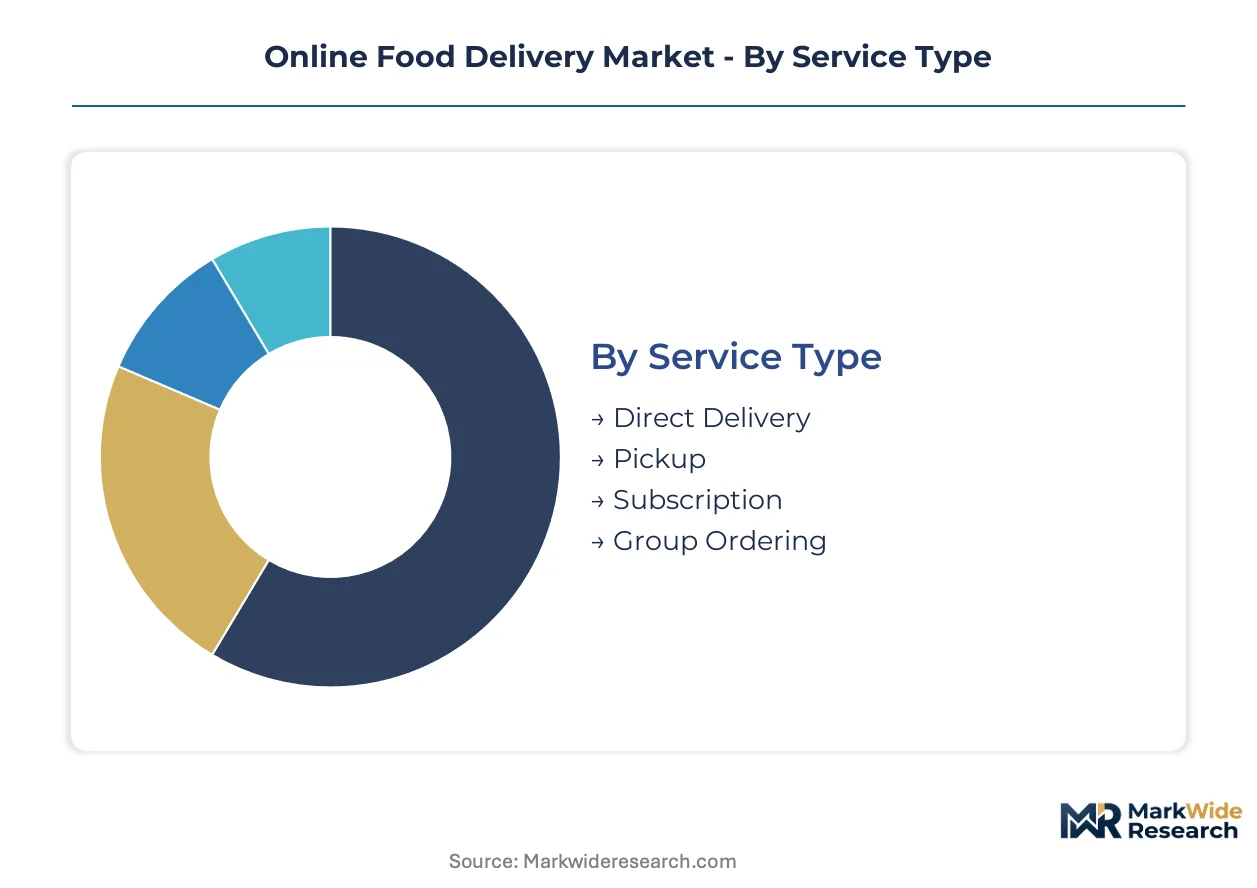
Segmentation in online food delivery reveals how distinct user behaviors and operational architectures create divergent margin profiles. Each dimension—service mechanism, customer identity, cuisine preference, and fulfillment structure—carries unique unit economics and regulatory exposure that shape platform strategy.
Service Type:
Speed expectations and fee tolerance fragment the use-case spectrum from impulse convenience to planned consumption.
- Direct Delivery:Algorithmic dispatch matches orders with nearest available drivers through GPS-tracked routing. Demand concentrates in urban employment clusters across the United States and Germany, where lunch-hour compression rewards sub-30-minute guarantees.
- Subscription:Monthly fee structures waive per-order delivery charges and unlock exclusive restaurant access. Corporate procurement teams in London and Singapore are negotiating enterprise subscriptions for hybrid workforces, locking in predictable revenue streams.
- Pickup:Consumers collect pre-ordered meals from designated counters, eliminating last-mile labor costs entirely.
- Group Ordering:Consolidated cart functionality serves office teams and family gatherings, reducing per-capita delivery fees through order aggregation.
Established volume favors Direct Delivery; emerging adoption favors Subscription.
Customer Type:
Lifetime value and order frequency separate stable revenue pools from volatile transactional demand.
- Corporate Clients:Human resources departments contract directly with aggregators for subsidized employee dining programs. Enterprise accounts in technology and financial services clusters across the United States and United Kingdom demonstrate highest retention rates and lowest acquisition costs.
- Families:Multi-person orders generate higher average ticket values but demand broader cuisine variety and dietary accommodation.
- Students:Price-sensitive cohorts cluster around discount codes and late-night availability windows.
- Singles:Individual portions dominate, with convenience prioritization over per-meal cost optimization.
Corporate Clients deliver margin stability; Students drive volume expansion through promotional elasticity.
Cuisine Type:
Preparation complexity and ingredient sourcing requirements create divergent platform commission tolerance.
- Italian:Pizza and pasta categories benefit from standardized production and thermal stability during transport. Demand concentrates in suburban United States markets where family dining occasions sustain higher per-order values.
- Chinese:Wok-based dishes and dim sum require precise timing coordination between kitchen and driver. Urban clusters in the United Kingdom and Australia show strongest adoption, driven by established diaspora populations and late-night availability.
- Indian:Spice-forward menus and vegetarian specialization attract health-conscious segments.
- Mexican:Assembly-line production models enable rapid fulfillment and consistent quality.
Italian commands suburban penetration; Chinese anchors urban density advantages.
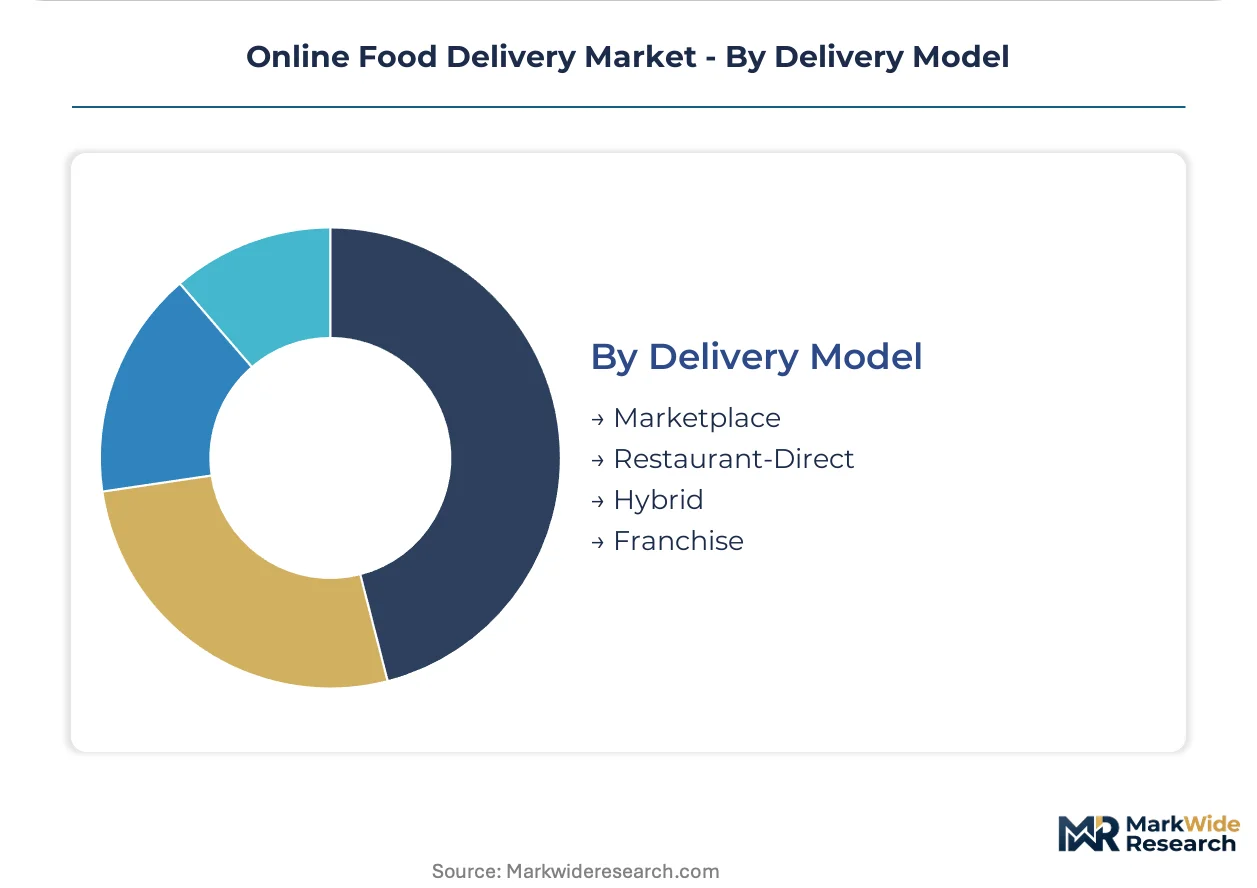
Delivery Model:
Capital deployment and liability exposure separate asset-light intermediaries from vertically integrated operators.
- Marketplace:Platforms externalize fleet costs to independent contractors while collecting commissions on gross order value. This architecture dominates in France and Italy, where restaurant density supports multi-hailing efficiency.
- Restaurant-Direct:Individual operators maintain proprietary driver pools and customer relationships. Chains in Japan and South Korea favor this model to preserve brand control and data ownership.
- Hybrid:Combines platform reach with selective in-house fulfillment for high-volume locations.
- Franchise:Standardized operations enable rapid geographic replication under centralized brand standards.
Marketplace retains deepest margin pool; Restaurant-Direct gains share where brand equity exceeds platform dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports super-app architecture and logistics density models to Southeast Asian markets, while the United States and Germany import regulatory frameworks governing gig-worker classification and algorithmic transparency.
United States
Suburban logistics density and corporate meal allowance programs drive platform expansion beyond urban cores. The Department of Labor and state-level regulators in California enforce gig-worker reclassification standards under AB5 and its subsequent refinements. Dallas-Fort Worth and Atlanta metropolitan clusters demonstrate viable unit economics in exurban delivery zones where competitor presence remains thin.
China
Super-app convergence and grocery-pharmacy-restaurant bundling concentrate consumer wallet share within single interfaces. SAMR mandates algorithmic transparency and rest-period protocols that limit dispatch optimization intensity. Shanghai and Beijing anchor the highest delivery frequency corridors, where Meituan's infrastructure enables sub-30-minute guarantees across dense urban grids.
Germany
Enterprise procurement of subsidized employee dining programs and hybrid work normalization expand B2B order volumes. The EU Platform Work Directive and national labor courts impose driver status reclassification requirements that reshape cost structures. Berlin and Munich technology clusters demonstrate highest corporate account retention rates among European employment centers.
India
Cloud kitchen proliferation and FSSAI-mandated hygiene digitization accelerate licensed dark-kitchen deployments. The Food Safety and Standards Authority requires hygiene ratings display on aggregator interfaces, directly influencing consumer choice architecture. Bangalore and Mumbai metropolitan regions concentrate highest delivery frequency among tier-one cities, with late-night availability windows driving student segment volume.
Brazil
ANVISA traceability protocols and food safety digitization reduce compliance friction for delivery-only brands entering the market. The national health surveillance agency enforces cold-chain documentation standards that reshape kitchen-to-door coordination requirements. São Paulo anchors the deepest restaurant density and driver pool concentration across Latin America.
Online Food Delivery Market Key Industry Players
Channel-controlling players compete with product-specialist players across three structural tiers: super-app ecosystems that bundle multiple service categories, pure-play delivery platforms that optimize single-use-case logistics density, and restaurant-direct operators that preserve brand control through proprietary fulfillment. Consolidation pressure concentrates among North American and Chinese markets, while European and Indian landscapes retain fragmentation. Dominant competitive moves include geographic expansion into suburban and exurban zones, and subscription model deployment to lock in recurring revenue and reduce per-order acquisition costs.
Within the super-app ecosystem tier, Meituan exemplifies cross-category bundling that virtualizes consumer wallet share across grocery, pharmacy, and restaurant verticals. Among pure-play delivery specialists, DoorDash and Uber Eats occupy positions defined by logistics density advantages and cross-selling synergies with ride-hail infrastructure. These three companies represent the dominant archetypes through which platform economics are being reconfigured across their respective home markets.
| Leading Market Players |
|---|
| DoorDash |
| Uber Eats |
| Meituan |
| Zomato |
| Just Eat Takeaway.com |
| Delivery Hero |
| Swiggy |
| Deliveroo |
| Grab Holdings |
| Others |
Cost & Logistics Intelligence
Overcapacity in China's cloud kitchen clusters compresses per-order economics while forcing platforms to absorb driver retention costs through subsidy pools. Utilization rates below break-even thresholds in tier-two cities reshape supplier negotiations and platform pricing posture across Asia-Pacific markets.
Pricing Analysis
Legacy dispatch-technology platforms face margin erosion against next-generation AI-routing systems that compress delivery windows and reduce per-unit labor. Three-tier pricing structure across premium, standard, and economy levels segments consumer willingness-to-pay by speed guarantee and restaurant exclusivity. Pricing pressure stems from restaurant pushback against commission ceilings in France and Italy. Students demonstrate highest price sensitivity, while corporate procurement teams negotiate lowest effective rates through volume guarantees.
Supply Chain Analysis
Export-control scrutiny on mapping and routing algorithms limits technology transfer between US and Chinese platform operators, fragmenting logistics software supply. Cloud kitchen equipment concentrates manufacturing in China, South Korea, and Germany; thermal packaging draws from petrochemical feedstocks anchored in Saudi Arabia and the United States. Single-source vulnerability runs through GPS chipset suppliers for driver tracking. Distribution runs through modular dark-kitchen networks rather than traditional restaurant supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from employer-subsidized meal programs that displace individual consumer decision-making with contracted enterprise procurement.
For Market Incumbents: Build data-network moats by integrating POS systems directly with kitchen inventory APIs, reducing coordination friction that fragments competitor dispatch. Consolidate suburban logistics density in exurban United States corridors where DoorDash has demonstrated viable unit economics. Threat: gig-worker reclassification rulings reshape labor cost structures. Lever: backward integration into cloud kitchen real estate to capture rent spreads and lock in restaurant supply. For New Entrants and Emerging Players: Tier-three Indian cities with FSSAI-mandated hygiene digitization present underpenetrated corridors where licensed dark-kitchen deployment outpaces platform coverage. Target late-night student segments in Bangalore and Mumbai where availability gaps persist. Go-to-market: subscription-first models that waive delivery fees and capture predictable revenue before per-order acquisition cost competition intensifies. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because delivery networks are consolidating toward natural monopoly economics in dense urban grids. Acquisition archetype: regional platforms with proprietary driver pools and enterprise contract books in underserved exurban zones. Signal to watch: SAMR-mandated algorithmic transparency enforcement in China as template for EU platform work directive implementation speed.| Strategic Initiative | Industry Significance |
|---|---|
| AI Routing Engine Deployment | Meituan's sub-30-minute guarantees in Shanghai demonstrate compression potential against legacy dispatch. |
| Enterprise Subscription Launch | Corporate procurement teams in London technology clusters negotiate locked-in revenue pools. |
| Cloud Kitchen Real Estate Acquisition | FSSAI compliance requirements in India favor licensed facilities over unregulated pop-up operations. |
| Electric Fleet Transition | EU Green Deal alignment builds regulatory goodwill ahead of packaging waste directive enforcement. |
| Super-App Category Integration | Grocery-pharmacy-restaurant bundling virtualizes consumer wallet share within single interfaces. |
Research Approach
Initial hypotheses were tested against primary input from cloud kitchen operators, fleet dispatch managers, restaurant procurement leads, and corporate HR benefits administrators and refined through secondary validation against SEC filings, EU Platform Work Directive implementation trackers, FSSAI hygiene rating databases, and customs records for thermal packaging imports. Bottom-up restaurant density modeling and top-down consumer expenditure triangulation anchored value estimates.
Demand-supply-balance dynamics across the analysis window incorporated segmentation by service type, customer archetype, cuisine complexity, and fulfillment model. CAGRs derived from logistic curve fitting to platform adoption saturation patterns. Forecast inputs included gig-worker reclassification probability weights and cloud kitchen license issuance trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated super-app operators would shift outcomes. Material shifts in SAMR algorithmic transparency enforcement or EU driver status reclassification rulings would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Commercial Pizza Oven Market
Food Service
Inflight Catering Market
Food Service
Saudi Arabia Foodservice Market
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
Japan Foodservice Market
Food Service
Global Virtual Restaurant and Ghost Kitchens Market
Food Service
Brazil Foodservice Market
Food Service
Canada Food Service Market
Food Service
Portable Buffet and Drop-In Ranges Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
Commercial Beverage Dispenser Market
Food Service
GCC Online Grocery Market
Food Service
Vietnam Food Service Market
Food Service
Global Delivery Takeaway Food Market
Food Service
Full-Service Restaurants Market