
 Fiber-Optic Strain Sensing Systems for Composite Wing Structures Market | 2026-2036
Fiber-Optic Strain Sensing Systems for Composite Wing Structures Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber-Optic Strain Sensing Systems for Composite Wing Structures Market Insights
Photonic integration with composite autoclave curing is narrowing the gap between manufacturing quality control and in-service structural health monitoring. Boeing leverages captive fiber-optic R&D in its Seattle-area facilities to embed sensing during wing fabrication. Luna Innovates sustains technology leadership through specialized interrogator designs for high-channel-count Bragg grating arrays. Safran anchors European supply chains via its Composites Morocco facility, where strain-sensor embedding accompanies winglet production.
Fiber-optic strain sensing systems for composite wing structures comprise interferometric and grating-based fiber sensors laminated within carbon-fiber-reinforced polymer wing skins to measure strain, temperature, and vibration with electromagnetic immunity. These systems operate at wavelengths near 1550 nm, with Bragg grating arrays providing spatial resolution down to millimeters along fibers spanning meters of wing chord and span. Fiber Bragg Grating products dominate current procurement for their multiplexing density and proven aerospace pedigree. Distributed Sensor configurations represent the fastest-expanding category, as manufacturers seek continuous strain mapping across full wing boxes rather than discrete point measurements. Wavelength-Division Multiplexing technology leads deployment where hundreds of sensors must share single fiber runs, reducing wiring weight and complexity in modern composite wings.
FAA airworthiness standards under Part 25 and EASA CS-25 certification specifications increasingly require validated strain monitoring for composite primary structures, directly expanding OEM procurement of qualified sensing systems. The EU AI Act and emerging MDR-equivalent frameworks for aerospace autonomy are beginning to shape requirements for sensor data integrity in self-monitoring aircraft architectures. Stakeholders must weigh the capital cost of embedded sensing against deferred maintenance and extended certification intervals as composite wing programs multiply across next-generation narrowbody and regional aircraft platforms.
Market Dynamics
Photonic integration with composite autoclave curing is collapsing the historical separation between manufacturing quality control and in-service structural health monitoring, forcing OEMs to redesign wing fabrication workflows around embedded sensing architectures rather than bolt-on retrofit approaches.
Growth Catalysts
- FAA Part 25 and EASA CS-25 mandates:Airworthiness standards now require validated strain monitoring for composite primary structures, compelling OEMs to procure qualified sensing systems during initial certification rather than post-delivery retrofit.
- Carbon-fiber-reinforced polymer wing skin proliferation:Next-generation narrowbody and regional aircraft platforms are embedding fiber-optic arrays during layup, creating captive demand for Bragg grating and distributed sensor configurations.
- German industrial clustering:Airbus Hamburg operations and Munich-area sensor integrators concentrate procurement volume, with composite winglet production at Safran's Morocco facility extending embedding demand across European supply chains.
Market Restraints
- Capital intensity of photonic interrogator hardware:High-channel-count Bragg grating array readers require specialized semiconductor foundry capacity, constraining supplier scaling and inflating upfront OEM procurement costs.
- Technical limitation in signal attenuation:Fiber runs exceeding tens of meters in full wing boxes experience wavelength degradation, limiting single-fiber sensor density and forcing redundant routing that adds weight.
- Substitution threat from wireless piezoelectric networks:Electromagnetic-immune alternatives are gaining traction in non-primary structure applications, threatening fiber-optic addressable market expansion in secondary wing components.
Strategic Opportunities
- EU AI Act compliance architectures:Emerging aerospace autonomy frameworks are mandating sensor data integrity for self-monitoring aircraft, creating demand for embedded fiber-optic systems with cryptographic verification layers.
- Technology convergence with additive manufacturing:Direct energy deposition of metal wing fittings with co-embedded fiber channels enables continuous strain mapping at traditional bolted joint locations previously inaccessible to sensing.
- Underpenetrated distributed sensor configurations:Continuous strain mapping across full wing boxes remains nascent relative to discrete point measurements, offering white space for interrogator vendors with spatial resolution capabilities below millimeter scale.
Industry Challenges
- Skill scarcity in photonics-composite hybrid engineering:Workforce capable of managing both optical signal processing and autoclave cure cycle parameters remains concentrated at a handful of OEM and tier-one supplier facilities.
- Certification timeline compression:FAA and EASA special conditions on composite damage tolerance are accelerating qualification schedules, forcing sensor integrators to parallel-track hardware validation with wing program development rather than sequential certification.
- Standardization delays in multiplexing protocols:Absence of unified Wavelength-Division Multiplexing standards across Boeing and Airbus supplier bases fragments procurement specifications and inflates non-recurring engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber-Optic Strain Sensing Systems for Composite Wing Structures Market |
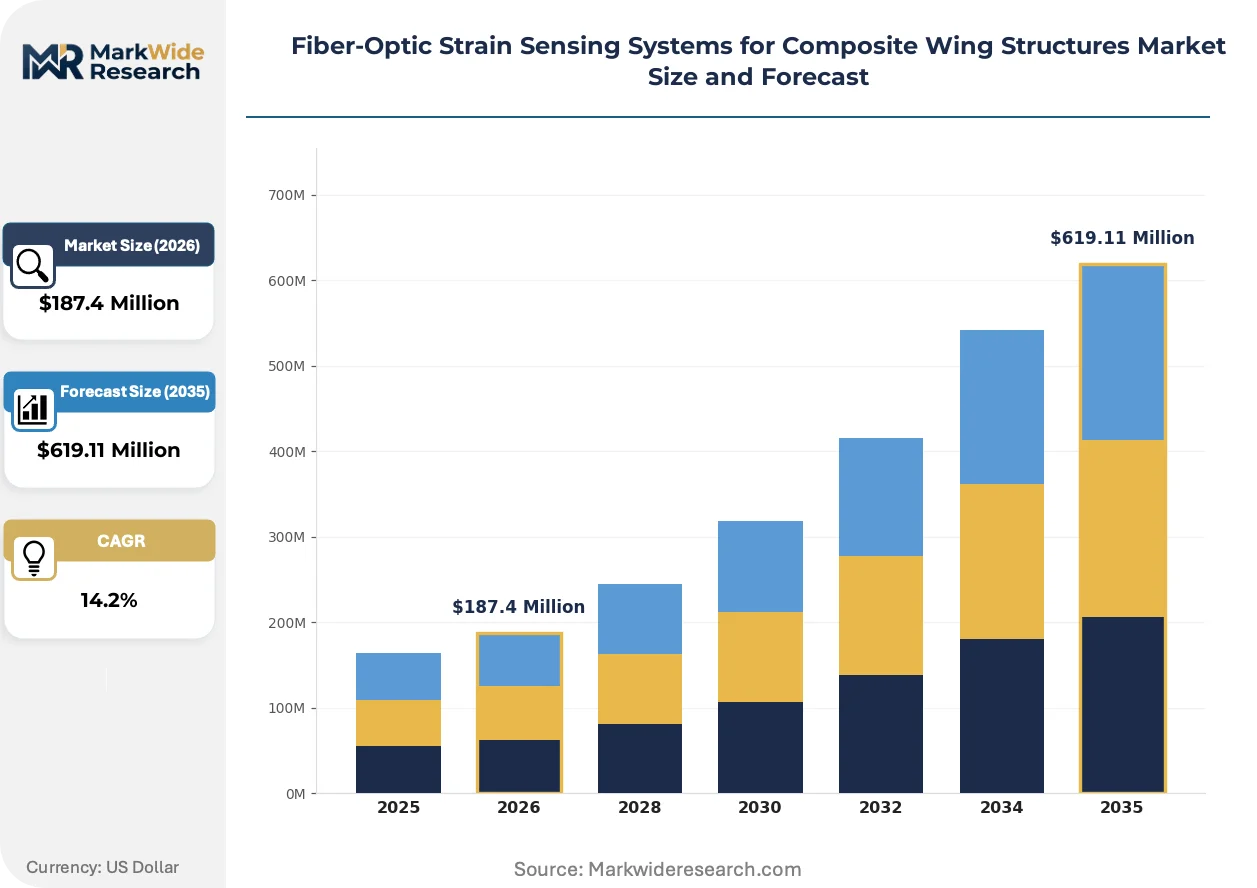
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Bragg Grating, Fabry-Perot Interferometer, Distributed Sensor, Polarimetric Sensor, Photonic Crystal Fiber, Optical Time Domain Reflectometry Technology: Wavelength-Division Multiplexing, Intensity Modulation, Phase Modulation, Polarization Modulation, Time-Domain Analysis, Frequency-Domain Analysis Application: Fixed-Wing Aircraft, Rotary-Wing Vehicles, Unmanned Aerial Systems, Space Launch Vehicles, Aerodynamic Testing, Structural Health Monitoring End User: Aircraft OEMs, Aerospace Tier-1 Suppliers, Defense Contractors, Flight Test Agencies, Research Laboratories, Certification Authorities |
| Companies Covered | Honeywell, Airbus, Boeing, Safran, Lockheed Martin, BAE Systems, Luna Innovations, FBGS Technologies, Sensuron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber-Optic Strain Sensing Systems for Composite Wing Structures Market Trends and Innovations
Real-time strain verification is migrating from diagnostic afterthought to design-in imperative, with regulatory pressure and fabrication technology convergence jointly redefining where sensing hardware resides in the value chain.
Multiplexed Fiber Bragg Grating arrays operating near 1550 nm are collapsing the cost and complexity barriers that historically restricted high-channel-count deployment to experimental or military platforms. Commercial aviation OEMs now specify these configurations as baseline for new wing programs, with embedding during autoclave cure eliminating post-fabrication fiber routing labor and signal loss risks. The structural consequence is compression of the retrofit sensor market as in-fabrication embedding becomes the default procurement mode.
EASA special conditions on composite damage tolerance and FAA airworthiness directives are mandating validated strain data streams from primary structure elements previously exempt from continuous monitoring. This regulatory architecture forces sensor suppliers to pre-qualify interrogator designs against certification timelines rather than awaiting post-entry-into-service retrofit demand. European narrowbody programs are responding fastest, with Hamburg and Toulouse engineering centers embedding compliance verification into supplier selection criteria ahead of North American counterparts.
Buyer concentration among tier-one aerostructures suppliers is compressing negotiation cycles and unbundling historical sensor-interrogator package deals. Airbus and Boeing procurement organizations now separately source fiber arrays from composite specialists and interrogator hardware from photonics vendors, forcing former integrated suppliers to defend position on component performance rather than system architecture. Germany and France exhibit this disaggregation most visibly, with Munich-area integrators losing sole-source status on bundled wing sensing contracts.
Fiber-Optic Strain Sensing Systems for Composite Wing Structures Market Segmentation
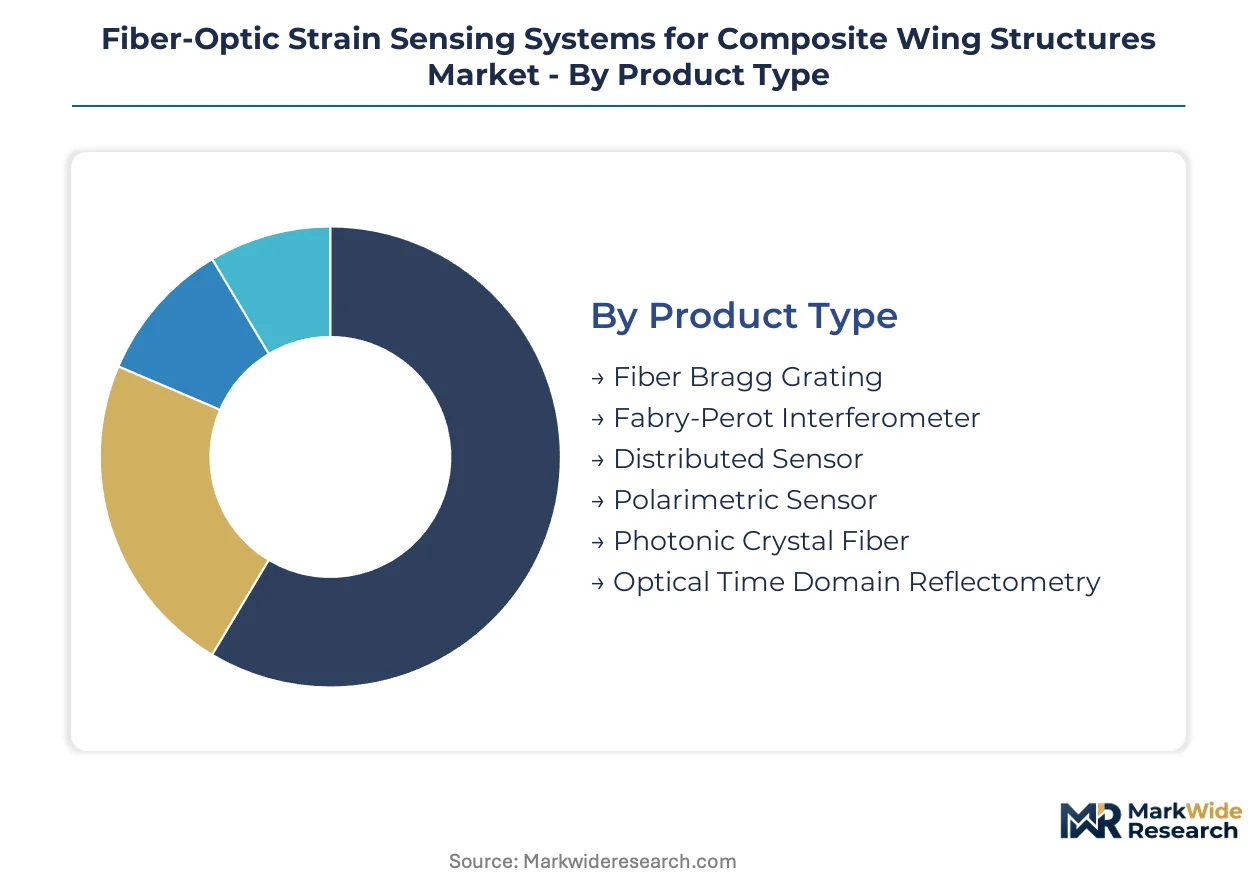
Segmentation in fiber-optic strain sensing reveals how procurement decisions split between mature, flight-proven technologies and emerging architectures demanding new qualification pathways. OEMs now weight multiplexing density against certification heritage when specifying sensors for composite wing programs.
Product Type:
Mature interferometric designs coexist with emerging distributed configurations as manufacturers balance proven airworthiness records against continuous mapping capabilities.
- Fiber Bragg Grating:Arrays of periodic refractive index variations inscribed in single-mode fiber reflect specific wavelengths proportional to strain. Airbus Hamburg specifies these for A320-family wing boxes where multiplexing hundreds of sensors on single fibers reduces harness weight. EASA CS-25 damage tolerance mandates favor this technology's extensive certification pedigree.
- Distributed Sensor:Continuous strain measurement along entire fiber lengths replaces discrete point sensing with spatial resolution down to centimeters. Boeing's Seattle facilities embed these for full wing-box monitoring on next-generation narrowbody programs where discrete grating placement leaves coverage gaps.
- Fabry-Perot Interferometer:Cavity-based sensors offer high sensitivity for localized strain concentration zones at wing root fittings.
- Polarimetric Sensor:Birefringence measurement suits applications requiring simultaneous strain and temperature discrimination.
- Photonic Crystal Fiber:Hollow-core designs resist radiation and temperature extremes for space launch vehicle applications.
- Optical Time Domain Reflectometry:Backscatter analysis enables fault location in embedded fiber runs during manufacturing quality control.
Fiber Bragg Grating handles the majority of throughput; Distributed Sensor is gaining share fastest as continuous mapping replaces point-measurement architectures.
Technology:
Cost tiering separates premium wavelength-multiplexed architectures from simpler intensity-based alternatives suited to secondary structure monitoring.
- Wavelength-Division Multiplexing:Hundreds of Bragg gratings at distinct wavelengths share single fiber runs through spectral separation. Munich-area integrators specify WDM for high-channel-count wing applications where fiber count directly impacts weight budgets and installation labor.
- Phase Modulation:Interferometric phase detection achieves picostrain resolution for acoustic emission monitoring in composite damage detection. Flight test agencies at NASA Dryden and DLR Braunschweig deploy these for ground vibration testing where signal fidelity outweighs hardware cost.
- Intensity Modulation:Simpler encoding suits low-cost health monitoring of non-critical wing components.
- Polarization Modulation:State-of-polarization tracking addresses applications with severe electromagnetic interference.
- Time-Domain Analysis:Pulse propagation timing enables distributed sensing without spectral encoding complexity.
- Frequency-Domain Analysis:Sweep-based interrogation reduces hardware cost for moderate channel counts.
Wavelength-Division Multiplexing dominates premium wing applications; Phase Modulation shows the steepest expansion trajectory in flight test and research installations.
Application:
Volume concentration in commercial fixed-wing programs contrasts with emerging demand from unmanned platforms and space launch systems.
- Fixed-Wing Aircraft:Composite wing skins on narrowbody and regional jets constitute the primary demand center. FAA Part 25 certification requirements for primary structure strain verification compel embedding during autoclave cure at Airbus Hamburg, Boeing Charleston, and Safran Morocco facilities.
- Unmanned Aerial Systems:Class III UAVs and urban air mobility prototypes adopt fiber-optic sensing for electromagnetic immunity in electric propulsion environments. German sensor integrators near Munich supply these programs with reduced qualification overhead versus manned aviation.
- Rotary-Wing Vehicles:Main rotor blade monitoring demands fatigue-resistant fiber routing through dynamic flexure zones.
- Space Launch Vehicles:Cryogenic tank strain monitoring leverages fiber-optic immunity to spark hazards in oxygen-rich environments.
- Aerodynamic Testing:Wind tunnel models instrumented with dense sensor arrays validate computational fluid dynamics predictions.
- Structural Health Monitoring:Retrofit installations on legacy composite structures extend service life through damage tracking.
Fixed-Wing Aircraft absorbs the bulk of procurement volume; Unmanned Aerial Systems is expanding most quickly as certification barriers lower for autonomous platforms.
End User:
Customer type determines whether procurement emphasizes system integration capability or component supply economics.
- Aircraft OEMs:Boeing and Airbus specify complete sensing architectures embedding during wing fabrication, forcing tier-one aerostructures suppliers to source qualified fiber arrays and interrogators separately. This disaggregation favors Munich photonics vendors for hardware and Hamburg composite specialists for embedding execution.
- Defense Contractors:Classified programs at Lockheed Martin Skunk Works and Northrop Grumman demand domestic supply chains with ITAR-compliant interrogator manufacturing.
- Aerospace Tier-1 Suppliers:Spirit AeroSystems and GKN Aerospace procure sensors as directed by OEM specifications with limited design authority.
- Flight Test Agencies:NASA, DLR, and ONERA instrument research aircraft with experimental configurations ahead of commercial qualification.
- Research Laboratories:University programs and national labs advance interrogator algorithms and packaging miniaturization.
- Certification Authorities:FAA and EASA technical centers validate sensor performance against airworthiness standards.
Aircraft OEMs control the dominant share of procurement decisions; Defense Contractors are climbing fastest as military composite wing programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German sensor integrators near Munich export embedded fiber-optic interrogator hardware to Airbus final assembly lines in Hamburg and Toulouse, establishing a trade corridor that channels European procurement volume through Bavarian photonics clusters.
United States
Boeing's Seattle-area facilities embed fiber-optic arrays during 737 and 777X wing fabrication, creating captive demand for high-channel-count interrogators. FAA Part 25 airworthiness directives mandate validated strain monitoring for composite primary structures, compelling domestic OEMs to source qualified sensing systems during initial certification rather than retrofit. Washington state and South Carolina host the principal Boeing wing fabrication and final assembly sites where embedding workflows concentrate.
Germany
Airbus Hamburg operations drive continental demand for Bragg grating arrays laminated within A320-family wing boxes during autoclave cure cycles. EASA CS-25 special conditions on composite damage tolerance require real-time strain verification, accelerating procurement timelines for Munich-area sensor integrators. Bavaria's photonics corridor supplies interrogator hardware that feeds into Hamburg's composite winglet production lines.
France
Safran's Composites Morocco facility extends French supply chain control into North African winglet manufacturing with co-embedded strain sensing. EU AI Act emerging frameworks for aerospace autonomy shape requirements for sensor data integrity in self-monitoring architectures. Toulouse engineering centers embed compliance verification into supplier selection criteria ahead of formal qualification deadlines.
United Kingdom
BAE Systems and GKN Aerospace procure fiber-optic sensing for military composite wing programs under UK Ministry of Defence specifications. The country's national aerospace regulator aligns with EASA certification standards while maintaining independent military airworthiness authority. Southwest England and Northwest England host tier-one aerostructures suppliers executing OEM-directed sensor embedding contracts.
China
Commercial Aircraft Corporation of China evaluates fiber-optic strain sensing for C919 and CR929 composite wing programs, though qualification timelines lag Western counterparts. MIIT national standards for civil aviation equipment establish domestic certification pathways parallel to FAA and EASA frameworks. Shanghai and Xi'an concentrate COMAC engineering and final assembly operations where sensor integration trials proceed.
Fiber-Optic Strain Sensing Systems for Composite Wing Structures Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated aerospace primes controlling embedding workflows and specialized photonics vendors supplying interrogator hardware. Tier-one aerostructures suppliers occupy an intermediate position executing OEM specifications with limited design authority. Three strategic archetypes dominate: captive R&D divisions of major OEMs, independent sensor technology specialists, and composite fabrication contractors with embedding capabilities. Competitive dynamics center on M&A activity consolidating photonics intellectual property and strategic partnerships linking interrogator vendors with composite manufacturers.
Among US-based technology developers, Luna Innovations and Sensuron occupy positions within the specialized sensor tier, while European supply chains anchor through FBGS Technologies. Honeywell represents the diversified industrial conglomerate archetype with cross-sector photonics capabilities. These named entities exemplify how competitive positioning splits between technology originators and system integrators rather than unified solution providers.
| Leading Market Players |
|---|
| Honeywell |
| Airbus |
| Boeing |
| Safran |
| Lockheed Martin |
| BAE Systems |
| Luna Innovations |
| FBGS Technologies |
| Sensuron |
| Others |
Pricing and Supply Chain Analysis
Transatlantic air freight corridors connecting Munich-area photonics clusters to Boeing Charleston and Airbus Hamburg autoclave facilities impose fuel-surcharge volatility that amplifies cost spreads between premium WDM interrogators and standard FBG arrays, compressing margins for mid-tier suppliers while reinforcing pricing power at semiconductor-foundry-backed vendors.
Pricing Analysis
Prior-generation Fabry-Perot interferometer systems trade at substantial discounts to current Wavelength-Division Multiplexing architectures, while next-generation distributed sensor configurations command project-based premiums for unproven qualification pathways. Three-tier pricing structure across premium, standard, and economy levels separates ITAR-compliant defense-grade interrogators from commercial aviation hardware and research-lab intensity-modulated alternatives. Cost compression in standard FBG arrays is intensifying because Munich-area integrators face buyer consolidation at Airbus and Boeing procurement desks. Defense contractors exhibit lowest price sensitivity due to classified program budgets, whereas university research laboratories and flight test agencies demonstrate highest sensitivity to per-channel interrogator costs.
Supply Chain Analysis
Specialty optical fiber feedstock draws from Corning operations in New York, Fujikura facilities in Japan, and YOFC production in China, with germanium-doped preform supply concentrated among three global chemical processors. Photonic interrogator assembly rests on indium phosphide semiconductor foundry capacity anchored in Taiwan and the United States, plus precision optical packaging equipment sourced from Germany and Switzerland. Single-source vulnerability in 1550-nm laser diode supply creates exposure to foundry allocation shocks during aerospace program ramp-ups. Distribution runs through tier-one aerostructures suppliers executing OEM-directed embedding contracts rather than direct sensor vendor-to-airline sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating at Airbus and Boeing procurement organizations, which now unbundle historical sensor-interrogator package deals and separately source fiber arrays from composite specialists and interrogator hardware from photonics vendors.
For Market Incumbents: Entrench through backward integration into specialty optical fiber preform production, securing captive supply of germanium-doped feedstock against foundry allocation shocks. Lock in long-term embedding partnerships with tier-one aerostructures suppliers at Airbus Hamburg and Boeing Charleston before qualification timelines compress further. Wireless piezoelectric substitution in secondary wing components represents the priority threat requiring defensive patent positioning. For New Entrants and Emerging Players: Distributed sensor configurations for full wing-box continuous mapping represent the most penetrable entry point, as established vendors optimize for discrete Bragg grating density rather than spatial resolution below millimeter scale. Unmanned aerial systems in German urban air mobility clusters offer reduced FAA Part 25 qualification overhead versus manned aviation programs. A go-to-market angle emphasizing EU AI Act cryptographic verification layers for autonomous aircraft architectures bypasses incumbent certification heritage advantages. For Investors and Strategic Acquirers: Photonics-composite hybrid engineering boutiques with demonstrated autoclave cure cycle integration capabilities present the highest-value acquisition profile for aerospace autonomy buildouts. Long-term viability hinges on sensor data integrity becoming mandatory for self-monitoring aircraft architectures under emerging regulatory frameworks. Watch for EASA special conditions expanding beyond damage tolerance into real-time load monitoring as the inflection signal triggering OEM procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Interrogator Qualification | FAA Part 25 pre-certification of high-channel-count WDM hardware eliminates retrofit market dependency for Luna Innovations-tier vendors. |
| Embedding Workflow Integration | Autoclave cure cycle co-location at Safran Morocco extends European supply chain control into North African winglet production. |
| Defense Supply Chain Compliance | ITAR-compliant interrogator manufacturing in domestic facilities secures Lockheed Martin Skunk Works program access against foreign vendor exclusion. |
| AI Act Data Integrity Architecture | Cryptographic verification layers embedded in fiber-optic interrogators address EU emerging requirements for autonomous aircraft sensor trust. |
| Distributed Sensor R&D Partnership | Collaboration with DLR Braunschweig flight test agencies accelerates spatial resolution capabilities below millimeter scale for Boeing next-generation programs. |
Research Methodology
The analysis maps Fiber Bragg Grating arrays, distributed sensor configurations, interferometric designs, and photonic crystal fiber variants, each validated through composite manufacturing engineers, photonics R&D directors, OEM procurement managers, and FAA certification specialists. Primary interviews with tier-one aerostructures suppliers and sensor integrators combined with secondary validation against EASA CS-25 special condition filings, FAA airworthiness directive databases, and SEC 10-K aerospace segment disclosures. Bottom-up channel checks across Munich-area photonics clusters and top-down procurement flow analysis at Airbus Hamburg and Boeing Charleston enabled triangulation.
Assumptions held fixed include current FAA Part 25 and EASA CS-25 regulatory frameworks, while composite wing program launch timing and photonic interrogator foundry capacity expansion were varied across sensitivity scenarios. The analytical framework modeled product type, technology tier, application segment, and end-user category dimensions across the analysis window. CAGRs derived from installation volume projections weighted by channel-count complexity and certification heritage premiums. Industry-specific inputs included autoclave cure cycle integration rates and OEM unbundling of sensor-interrogator procurement packages.
Practitioners should monitor EASA special condition expansion scope, ITAR compliance threshold adjustments, and indium phosphide foundry allocation shocks for early signals requiring forecast revision. Cross-checking against FAA certification timeline disclosures and Airbus Boeing procurement contract announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Light Electric Aircraft Market
Aircraft
Helicopter Wheels Market
Aircraft
Asia-Pacific General Aviation Market
Aircraft
Asia-Pacific Light and Very Light Jets Market
Aircraft
Aircraft Aerostructures Market
Aircraft
Drone Turbojet Engine Market
Aircraft
North America Aircraft Band Clamps Market
Aircraft
Onboard Oxygen Generating System (OBOGS) Market
Aircraft
US Aviation Market
Aircraft
General Aviation Market
Aircraft
Aircraft Galley Systems Market
Aircraft
Afterburner Market
Aircraft
Helicopter Lighting Market
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
Glider Aircraft Market
Aircraft
Anti Rolling Gyro (ARG) Market