
 Solder Materials Market | 2026-2036
Solder Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Solder Materials Market Outlook
Lead-free alloy formulation is fragmenting traditional solder supply chains as electronics assemblers face divergent thermal profiles and wetting behavior across tin-silver-copper, tin-copper, and bismuth-bearing systems. Indium Corporation leverages its indium-tin oxide and specialty alloy portfolio to anchor premium segments in aerospace and medical reliability tiers. Henkel AG & Co. KGaA sustains broad formulation depth across paste, wire, and flux chemistries for automotive module production. Senju Metal Industry Co., Ltd. dominates Asian supply channels with integrated bar and paste manufacturing for contract electronics manufacturers.
Solder materials are fusible metal alloys, typically tin-based with additions of silver, copper, bismuth, or antimony, engineered to melt below 450°C and form metallurgical bonds between conductive substrates upon cooling; their primary industrial purpose is permanent electrical and mechanical interconnection in printed circuit board assembly, semiconductor packaging, and discrete component attachment. Lead-free alloys now lead volume in electronics assembly applications as RoHS-aligned OEM mandates harden, while high-temperature formulations for automotive under-hood environments represent the fastest-expanding margin pool. Soft solder in repair and hobbyist channels remains structurally mature with compressed pricing and commodity sourcing dynamics.
REACH substance restrictions, RoHS hazardous substance limits, and ISO 9453 alloy composition standards collectively shape material eligibility, supplier qualification timelines, and cross-border shipment protocols for solder products entering European and North American assembly operations. China's GB standards and NMPA-adjacent quality frameworks impose additional compositional testing on imports serving domestic medical device and automotive electronics supply chains. Stakeholders must monitor evolving alloy patent estates and regional substance restriction timelines to anticipate reformulation investments and qualification cycle disruptions.
Market Dynamics
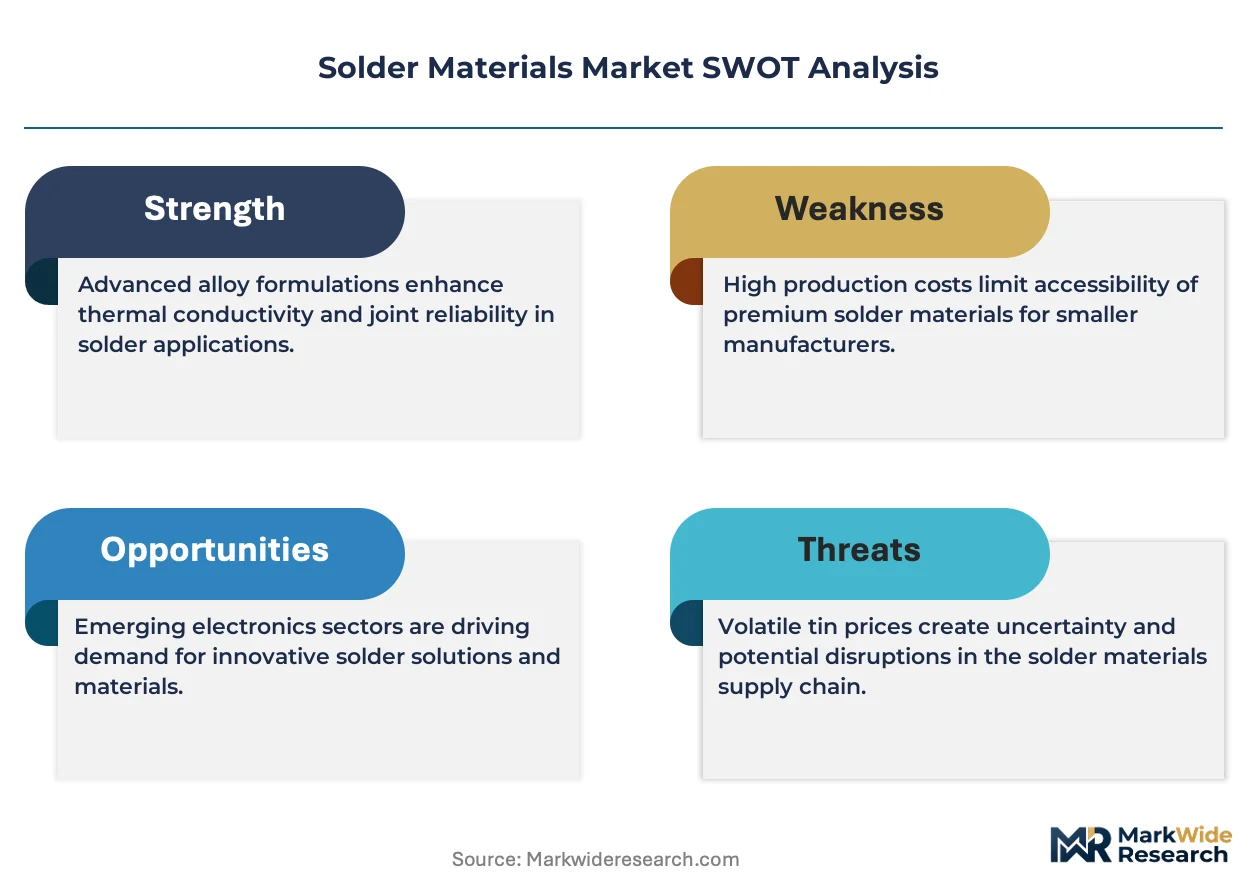
Lead-free alloy mandates are fragmenting established supply chains as electronics assemblers confront divergent thermal profiles and wetting behaviors across competing metallurgical systems. This regulatory compression is forcing simultaneous reformulation investments across paste, wire, and bar product lines while OEM qualification timelines extend.
Growth Catalysts
- EV Powertrain Electrification:Battery management systems and inverter modules demand high-reliability alloys capable of thermal cycling endurance under hood. Automotive electronics assemblers in Germany and China are qualifying new alloy portfolios.
- REACH Substance Restrictions:ECHA's evolving candidate list is accelerating substitution of legacy solders containing cadmium, lead, and certain flux activators. European contract manufacturers face hard reformulation deadlines.
- Semiconductor Packaging Miniaturization:Flip-chip and wafer-level packaging processes require ultra-fine pitch solder spheres and pastes. Advanced packaging foundries in Taiwan and South Korea are expanding alloy consumption.
Market Restraints
- Indium Supply Concentration:Over 80% of primary indium originates as zinc smelter byproduct concentrated in Chinese and Korean refining complexes. Price volatility in indium-tin oxide feedstock compresses margin on premium alloys.
- Silver Cost Exposure:SAC305 and similar tin-silver-copper formulations carry significant precious metal cost. Electronics assemblers face margin pressure when silver spot prices spike.
- RoHS Exemption Uncertainty:Expiring exemptions for high-lead solders in specific aerospace and medical applications create qualification risk. European OEMs must dual-source lead-free alternatives before deadline.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and PCB assembly are attracting contract manufacturers. Domestic alloy blending capacity remains underdeveloped versus projected demand.
- Bi-Based Low-Temperature Alloys:Bismuth-tin systems enable step-soldering of temperature-sensitive components in medical devices. Japanese equipment manufacturers are qualifying these formulations for disposable diagnostic hardware.
- Repair Channel Premiumization:Specialized hobbyist and industrial repair segments seek certified lead-free wire with documented thermal profiles. Direct-to-technician e-commerce channels bypass traditional distribution.
Industry Challenges
- Metallurgical Expertise Scarcity:Alloy formulation chemistry and flux-solvent interaction knowledge is concentrating at senior levels. Mid-tier suppliers struggle to replicate qualification data packages without experienced staff.
- Dual-Carbon Compliance Costs:China's MEE carbon intensity targets and EU CBAM border adjustments require scope-three emissions documentation. Smelters and alloy blenders face capital requirements for lifecycle tracking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solder Materials Market |
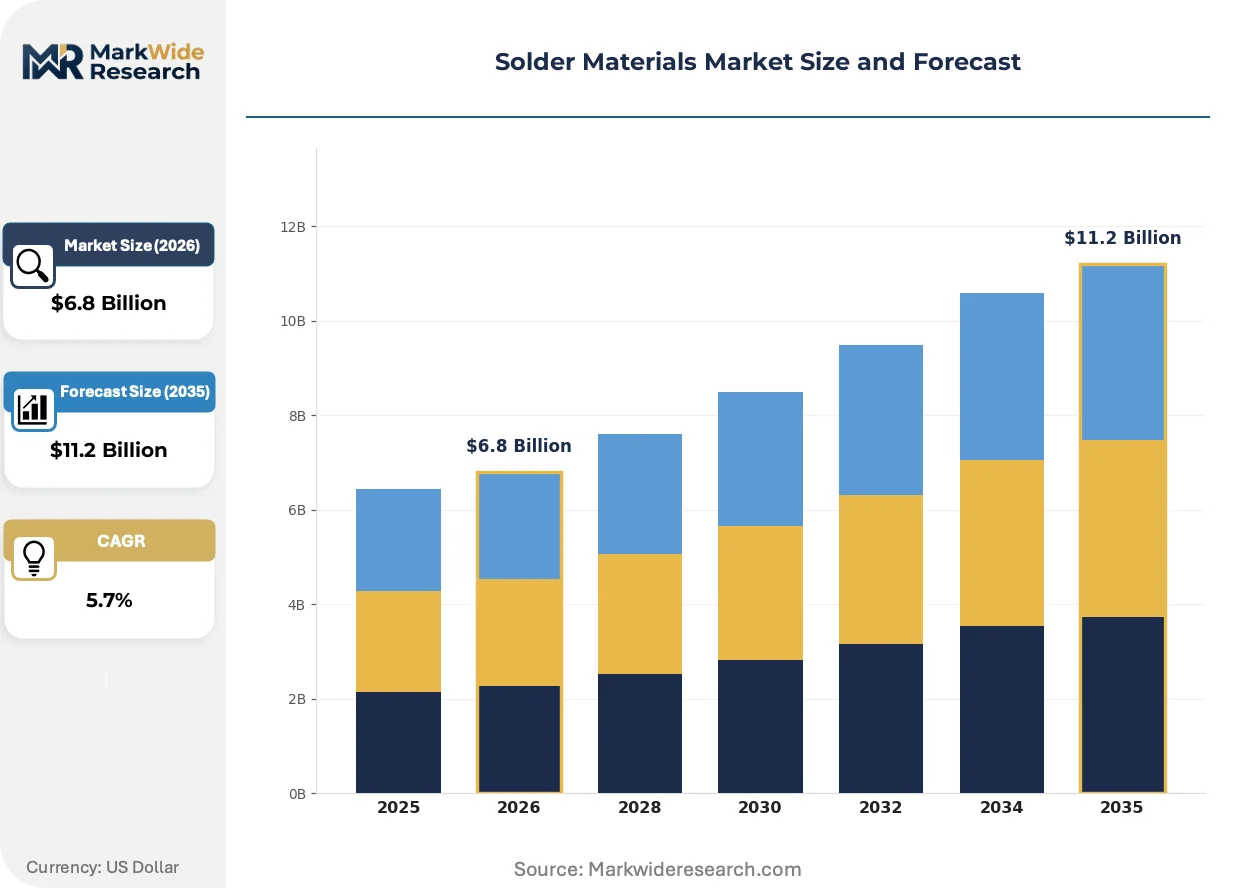
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tin-lead, Lead-free, High-temperature, Soft solder Application: Electronics Assembly, Automotive, Aerospace, Medical Devices Form: Wire, Bar, Paste, Flux End User: Contract Manufacturers, OEMs, Repair Service Providers, Hobbyists |
| Companies Covered | Indium Corporation, Henkel AG & Co. KGaA, Senju Metal Industry Co., Ltd., Qualitek International, Inc., KOKI Company Ltd., Lucas Milhaupt, Inc., Element Solutions Inc, Fusion Inc., Alpha Assembly Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solder Materials Market Strategic Shifts
Computational materials science is compressing traditional alloy development cycles, enabling rapid screening of multi-component phase diagrams before physical casting. This digital acceleration is reshaping how formulation houses respond to customer-specific thermal requirements.
Machine learning-driven alloy design platforms are virtualizing decades of empirical solder development. Automotive electronics suppliers in Stuttgart and Detroit are adopting these tools to predict creep resistance and thermal fatigue life. The technology is virtualizing the competitive moat once held by legacy formulation houses with extensive physical databases.
EU F-Gas Regulation amendments are restricting fluorinated greenhouse gases used in certain reflow atmosphere control systems. Electronics assemblers operating nitrogen reflow lines face retrofit requirements or alternative atmosphere sourcing. German automotive tier-one suppliers are accelerating conversion to hydrogen-forming gas atmospheres to maintain process certification.
Contract manufacturers are consolidating supplier relationships around alloy-agnostic technical service capabilities. Large EMS providers in Mexico and Vietnam now specify performance outcomes rather than compositional standards. This specification shift favors formulation houses with embedded process engineering support over commodity alloy traders.
Solder Materials Market Segmentation
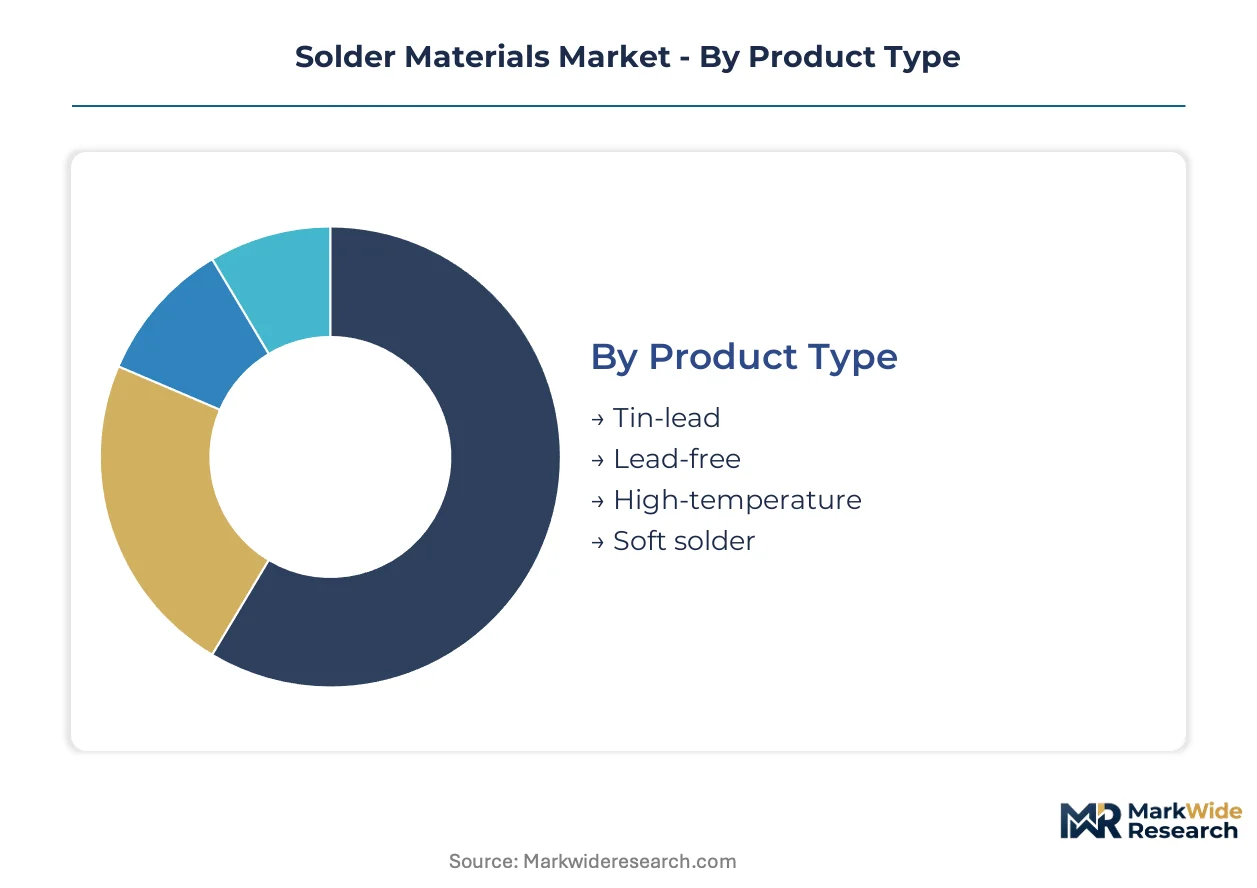
Solder materials fragment across alloy chemistry, thermal performance requirements, and delivery format. Each dimension carries distinct qualification protocols and margin structures that reshape supplier competitiveness.
Product Type:
Cost tier stratification separates commodity formulations from premium reliability grades with distinct raw material exposures.
- Lead-free:SAC305 and tin-copper systems dominate RoHS-aligned electronics assembly. German automotive tier-one suppliers and Taiwanese contract manufacturers are driving qualification of next-generation low-silver variants to reduce precious metal cost exposure.
- High-temperature:Gold-tin and antimony-bearing alloys withstand thermal cycling in power module substrates. Chinese EV battery pack assemblers and Japanese industrial inverter manufacturers are expanding consumption of these formulations for under-hood reliability.
- Tin-lead:Legacy eutectic systems persist in exempted aerospace and medical device applications.
- Soft solder:Low-melting bismuth-tin and indium-bearing alloys serve temperature-sensitive component attachment.
Lead-free commands the established base. The steepest expansion runs through high-temperature.
Application:
End-use thermal environment dictates alloy selection and supplier qualification intensity.
- Electronics Assembly:Surface-mount and through-hole PCB interconnection consumes paste and wire in high volumes. Mexican and Vietnamese contract manufacturing clusters are absorbing alloy shipments for consumer electronics and computing hardware production.
- Automotive:Powertrain electrification is reshaping material specifications. Battery management systems and inverter modules in Stuttgart and Detroit design centers demand alloys with verified thermal fatigue resistance across -40°C to 150°C operating windows.
- Aerospace:High-reliability formulations face extended qualification cycles under FAA and EASA airworthiness protocols.
- Medical Devices:Implantable and diagnostic equipment requires biocompatibility-tested alloys with documented flux residue behavior.
Electronics assembly anchors volume consumption. Automotive applications are climbing the fastest.
Form:
Physical delivery format determines process integration and customer technical service requirements.
- Paste:Alloy powder suspended in flux-vehicle systems enables stencil printing for surface-mount assembly. South Korean and Taiwanese advanced packaging foundries are qualifying Type 6 and Type 7 powder sizes for ultra-fine pitch flip-chip interconnect.
- Wire:Solid and cored configurations feed robotic and manual soldering stations. German automotive electronics suppliers specify diameter tolerances and oxide levels for laser soldering of camera module assemblies.
- Bar:Bulk ingot forms supply wave and dip soldering equipment in high-volume consumer electronics.
- Flux:Liquid and gel activators complement alloy forms for specific substrate metallizations.
Paste captures the premium margin pool. Wire maintains the broadest geographic penetration.
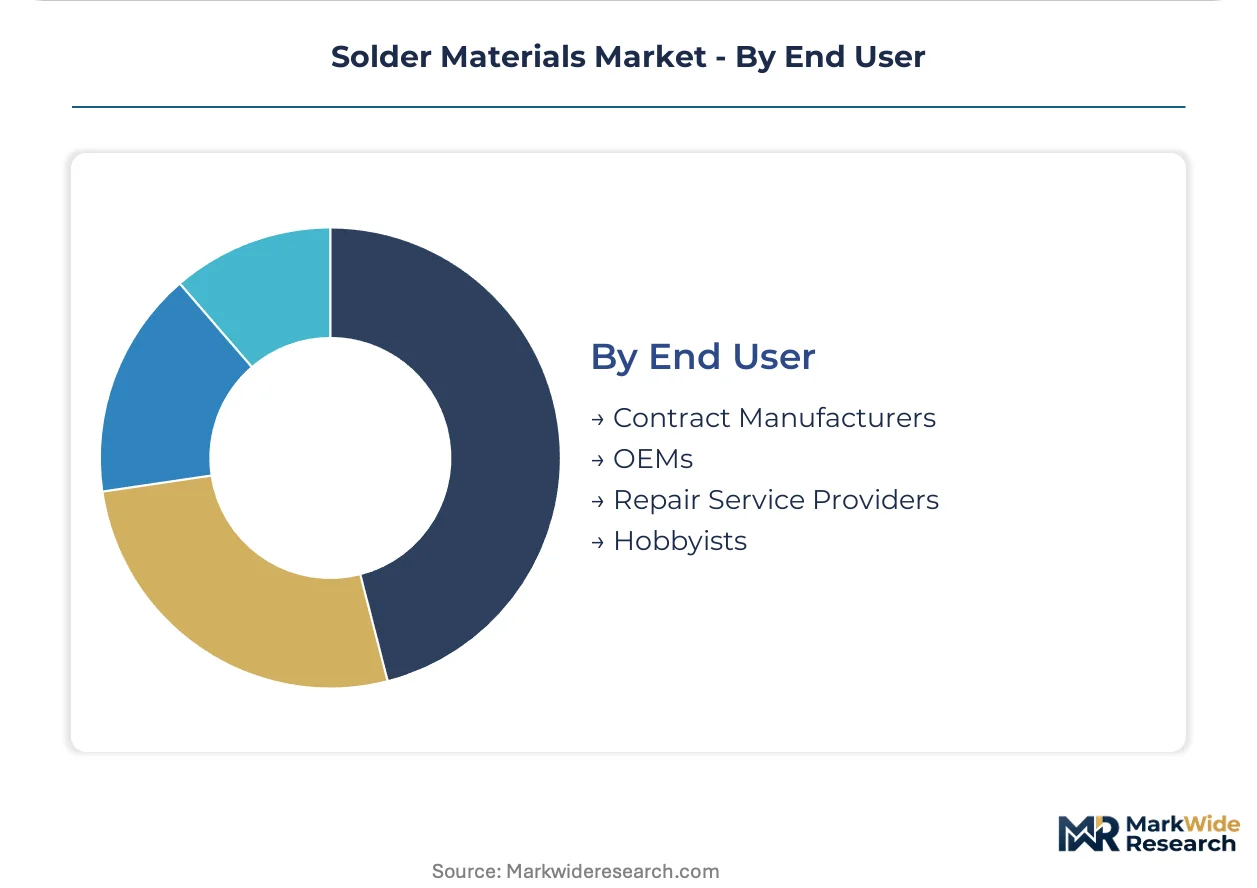
End User:
Customer scale and technical capability determine specification authority and procurement patterns.
- Contract Manufacturers:Foxconn, Jabil, and Flex operate global alloy specification programs. These entities consolidate supplier relationships around technical service capabilities rather than commodity pricing alone.
- OEMs:Bosch, Siemens, and Continental maintain captive alloy approval lists for automotive module production. Direct qualification with smelters and formulation houses bypasses distribution layers.
- Repair Service Providers:Industrial maintenance operations and authorized service networks consume certified wire and paste for field replacement.
- Hobbyists:Individual technicians and makers purchase small-format wire through e-commerce channels with documented thermal profiles.
Contract manufacturers concentrate procurement volume. OEM direct relationships are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports solder materials to Germany, Mexico, and Vietnam as contract manufacturers in those markets expand electronics assembly capacity. Trade flows concentrate through Shanghai and Shenzhen port complexes for alloy paste and wire shipments.
China
Domestic PCB and semiconductor packaging output drives alloy consumption across the Yangtze River Delta. GB standards and MEE carbon intensity targets impose compositional testing and emissions documentation on smelters. Shenzhen and Dongguan clusters absorb high volumes of SAC305 paste for consumer electronics contract manufacturing.
Germany
Automotive tier-one suppliers in Stuttgart and Munich qualify high-reliability alloys for EV battery management systems. REACH substance restrictions and RoHS mandates accelerate lead-free reformulation investments. Bavarian electronics assemblers operate nitrogen reflow lines under tightening EU F-Gas Regulation protocols.
United States
Detroit automotive design centers specify thermal fatigue-resistant alloys for powertrain electrification programs. EPA and FAA regulations govern flux residue documentation for aerospace applications. Mexican border maquiladoras import alloy wire for camera module laser soldering operations.
Japan
Industrial inverter manufacturers in Nagoya and Osaka expand consumption of antimony-bearing high-temperature formulations. METI and JIS standards govern alloy composition for medical device applications. Kyushu-based packaging foundries qualify ultra-fine pitch solder spheres for flip-chip interconnect.
South Korea
Advanced packaging foundries in Seoul and Suwon drive Type 6 and Type 7 powder paste consumption. MFDS quality frameworks apply to medical device solder imports. Busan-Ulsan chemical complexes supply flux-vehicle systems for domestic electronics assemblers.
Solder Materials Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Alloy blenders and formulation houses occupy distinct positions based on technical service depth versus commodity scale. Three archetypes dominate: integrated metals processors with captive smelter relationships, formulation specialists with embedded process engineering, and regional distributors with logistics concentration. Competitive moves center on backward integration into powder atomization capacity and strategic partnerships with advanced packaging foundries.
Within the premium reliability tier, Indium Corporation and Henkel AG & Co. KGaA represent formulation specialists with deep alloy chemistry portfolios. Senju Metal Industry Co., Ltd. anchors Asian supply channels as an integrated processor. These three exemplify how technical service capabilities and geographic positioning separate premium-tier suppliers from commodity blenders competing on spot metal pricing.
| Leading Market Players |
|---|
| Indium Corporation |
| Henkel AG & Co. KGaA |
| Senju Metal Industry Co., Ltd. |
| Qualitek International, Inc. |
| KOKI Company Ltd. |
| Lucas Milhaupt, Inc. |
| Element Solutions Inc |
| Fusion Inc. |
| Alpha Assembly Solutions |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Shenzhen freight corridors absorb alloy paste and wire shipments bound for contract manufacturers in Mexico and Vietnam, with container rate volatility compressing margins on spot-priced SAC305 formulations while reinforcing price premiums for long-term offtake agreements with German automotive tier-one suppliers.
Pricing Analysis
SAC305 and tin-copper systems command current-generation premiums, legacy tin-lead formulations trade at compressed spot pricing in exempted aerospace channels, and next-generation low-silver variants are climbing the cost curve as precious metal hedging costs embed in quotes. Three-tier pricing structure across premium reliability, standard electronics, and economy repair grades separates alloys by certification intensity and thermal profile documentation. Pricing pressure stems from silver spot volatility and indium feedstock concentration, with cost compression running through mid-tier blenders lacking captive smelter relationships. Contract manufacturers exhibit highest price sensitivity due to consolidated procurement volumes, while medical device OEMs show lowest sensitivity given biocompatibility qualification barriers.
Supply Chain Analysis
Foxconn, Jabil, and Flex concentrate global assembly capacity and dictate alloy specification authority through consolidated supplier programs. China, South Korea, and Japan anchor primary supply, with Yangtze River Delta smelters feeding powder atomization for paste production and Kyushu-based foundries sourcing ultra-fine pitch spheres. Raw material dependencies center on zinc smelter byproduct indium, silver bullion from precious metal refiners, and tin concentrate from Indonesian and Chinese mining complexes. Single-source vulnerability in indium-tin oxide feedstock creates qualification risk for premium aerospace alloys. Distribution runs through direct technical service relationships with formulation houses rather than commodity metal traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solder materials markets track electronics capital expenditure cycles, with EV powertrain electrification programs in Stuttgart and Detroit extending the current upcycle through sustained alloy qualification demand.
For Market Incumbents: Pre-empt qualification timeline compression by embedding process engineering teams at advanced packaging foundries in Taiwan and South Korea, defending against formulation specialists with computational alloy design platforms. Backward integration into powder atomization capacity in the Yangtze River Delta secures supply security for Type 6 and Type 7 paste shipments to semiconductor packaging customers. For New Entrants and Emerging Players: India's PLI-scheme electronics manufacturing clusters represent the most penetrable entry point, with domestic alloy blending capacity underdeveloped versus projected PCB and semiconductor assembly demand. Bismuth-tin low-temperature formulations for Japanese medical device manufacturers offer a technical differentiation angle against entrenched SAC305 suppliers. Direct-to-technician e-commerce channels for certified lead-free repair wire bypass traditional distribution layers controlled by incumbents. For Investors and Strategic Acquirers: Regional formulation houses with embedded flux chemistry expertise and existing automotive OEM approvals present acquisition targets with defensible technical moats. Long-term viability hinges on carbon intensity documentation capabilities under EU CBAM and China's MEE dual-carbon targets. Watch indium price volatility and RoHS exemption expiration timelines as inflection indicators for margin compression in premium reliability tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Atomization | Captive Type 6 and Type 7 powder supply secures qualification timelines with Taiwanese advanced packaging foundries. |
| Computational Alloy Design Platform Deployment | Machine learning-driven thermal fatigue prediction virtualizes legacy formulation house empirical databases. |
| Carbon Intensity Documentation System | Scope-three emissions tracking satisfies EU CBAM border adjustments and China's MEE reporting requirements. |
| Direct Technical Service Embedding | On-site process engineering at German automotive tier-one suppliers locks in specification authority against commodity competitors. |
| Low-Temperature Bi-Based Formulation Qualification | Bismuth-tin systems enable step-soldering for temperature-sensitive medical device components in Japanese diagnostic hardware. |
Study Parameters
The analysis maps lead-free alloy formulations, high-temperature automotive grades, and soft solder repair channels, each validated through procurement directors at contract manufacturers, technical service leads at formulation houses, and plant managers at powder atomization facilities. Primary interview data triangulates against customs trade records for tin and silver concentrate shipments, SEC filings from diversified materials corporations, ECHA REACH candidate list updates, and GB standards documentation from Chinese standardization authorities. Bottom-up alloy consumption estimates at individual PCB and semiconductor packaging facilities reconcile with top-down smelter production data across the analysis window.
Assumptions held fixed include REACH and RoHS regulatory trajectories, EV powertrain electrification penetration curves, and semiconductor packaging miniaturization rates; variables tested include silver price volatility bands, indium supply disruption scenarios, and F-Gas Regulation amendment timelines. Segmentation modeling incorporates alloy chemistry tier, thermal performance specification, delivery format, and end-user procurement authority. CAGRs derive from installed base growth in automotive electronics and advanced packaging capacity expansion, with indium-tin oxide feedstock availability and dual-carbon compliance cost curves as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in electronics capital expenditure cycles, precious metal commodity prices, or cross-border trade policy would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory deadline adherence and qualification timeline norms. Quarterly review of ECHA substance restriction proposals, RoHS exemption expiration schedules, and MEE carbon intensity enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Laminated Steel Market
Metals & Minerals
Tantalum Pentoxide Market
Metals & Minerals
Gold Recycling Market
Metals & Minerals
Recycled Lead Market
Metals & Minerals
Global Base Metal Mining Market
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
US Lithium Market
Metals & Minerals
Zinc Citrate Market
Metals & Minerals
Middle-East and Africa Lithium Market
Metals & Minerals
Nickel Mining Market
Metals & Minerals
20MnCr5 Steel Market
Metals & Minerals
Zinc Sulphate Market
Metals & Minerals
Steel Powder Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
Global Magnesium Hydroxide Market
Metals & Minerals
Global Magnesium Carbonate Minerals Market