
 Two Wheeler Handlebars Market | 2026-2036
Two Wheeler Handlebars Market Size, Share, and Industry Trends Forecast 2026-2036
Two Wheeler Handlebars Market Analytics
The gap between premium CNC-machined aluminum handlebars and commodity welded steel variants is restructuring procurement tiers across the motorcycle supply chain. ProTaper dominates the off-road racing segment with its tapered-wall 7075 aluminum construction. Renthal sustains its position in motocross OEM supply through captive extrusion capabilities in the United Kingdom. Neken S.A.S. differentiates via forged handlebar architecture for European enduro manufacturers.
Two wheeler handlebars are steering control interfaces manufactured from tubular stock—typically 22mm or 28.6mm clamp diameters with wall thicknesses between 1.6mm and 4.0mm—engineered to transmit rider inputs to the fork assembly while absorbing vibration and impact loads. Carbon fiber handlebars represent the fastest-growing material category as electric motorcycle producers pursue mass reduction targets, though aluminum retains the dominant volume position across ICE platforms. Aftermarket installation channels capture elevated margin pools relative to OEM supply due to customization demand from enthusiast segments, while replacement volumes track fleet age and crash incidence rates.
India's BIS mandates fatigue testing and dimensional tolerances for handlebar assemblies sold in domestic and export markets, forcing component suppliers to upgrade metallurgical certification. The EPA in the United States and the EU's REACH framework restrict hexavalent chromium plating processes traditionally applied to steel handlebars, accelerating conversion to anodized aluminum finishes. Stakeholders must monitor evolving electric two-wheeler platform architectures where integrated throttle-by-wire and display mounting requirements are altering handlebar design specifications and supplier qualification criteria.
Market Dynamics
Electric two-wheeler platform architectures are forcing handlebar redesigns that integrate throttle-by-wire systems, display mounts, and sensor housings into single aluminum extrusions, compressing supplier qualification timelines and favoring manufacturers with captive CNC machining capabilities.
Growth Catalysts
- REACH material compliance:Europe's restriction on hexavalent chromium plating accelerates conversion to anodized aluminum finishes across steel-dependent supply chains.
- Carbon fiber mass reduction:Electric motorcycle producers pursue battery range extension through handlebar lightweighting, creating specification pull for composite tubular architectures.
- Tamil Nadu manufacturing corridor:India's concentration of two-wheeler OEM assembly plants generates localized demand for BIS-certified handlebar suppliers with fatigue testing documentation.
Market Restraints
- 7075 aluminum billet volatility:Aerospace-grade aluminum pricing fluctuations compress margin pools for CNC-machined premium handlebar producers.
- Chinese extrusion concentration:Raw aluminum tubular stock for commodity handlebars sources predominantly from Zhejiang and Guangdong provinces, creating single-geography supply risk.
- Welded steel fatigue limits:Traditional mild steel construction cannot meet emerging vibration damping specifications for electric scooter platforms above 50km/h top speeds.
Strategic Opportunities
- Vietnam assembly hub emergence:Honda and Yamaha expansion in Vinh Phuc and Hanoi provinces creates unfilled demand for locally qualified handlebar suppliers with ISO welding certification.
- Throttle-by-wire integration:Convergence of electronic throttle control with handlebar grip interfaces enables premium pricing for sensor-embedded tubular assemblies.
- India PLI scheme:Production-linked incentives for advanced automotive components subsidize capital equipment upgrades for domestic aluminum forging capacity.
Industry Challenges
- Metallurgical certification timelines:BIS fatigue testing protocols require 18-24 month validation cycles for new aluminum alloy grades, delaying product launches.
- CNC programming talent scarcity:Complex tapered-wall 7075 machining requires specialized CAM expertise concentrated in UK and Italian supplier bases.
- Legacy steel tooling stranded assets:Chromium plating line investments face accelerated obsolescence under REACH Annex XVII restrictions, forcing write-downs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two Wheeler Handlebars Market |
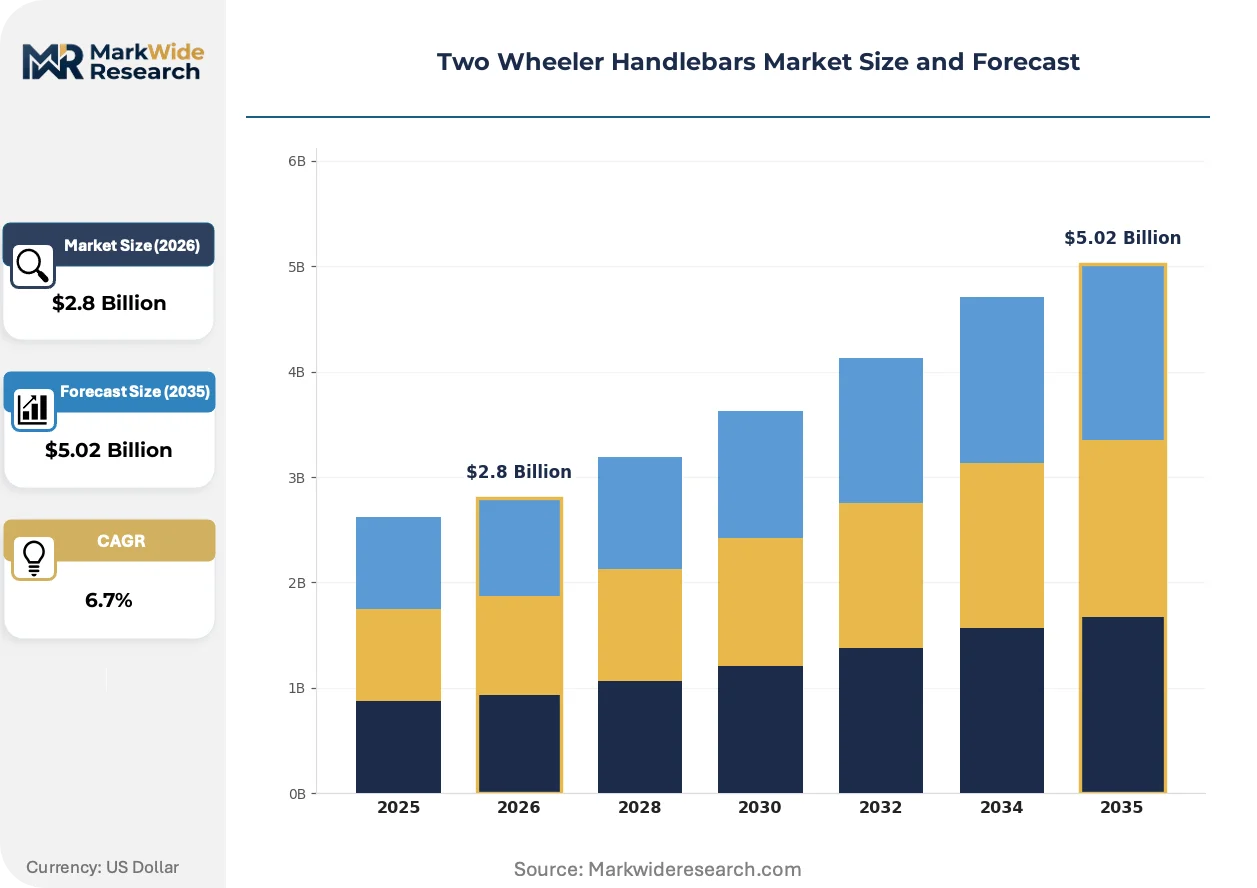
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
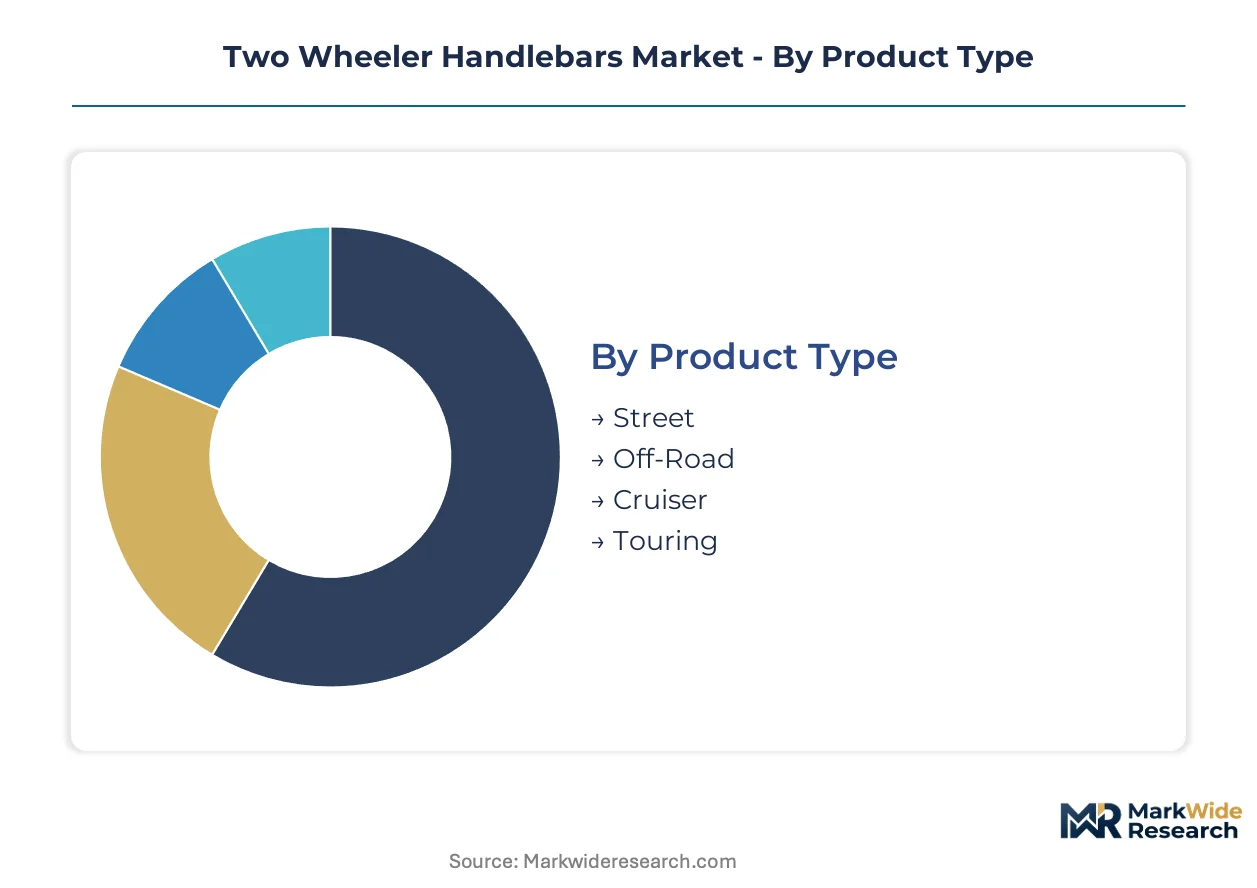
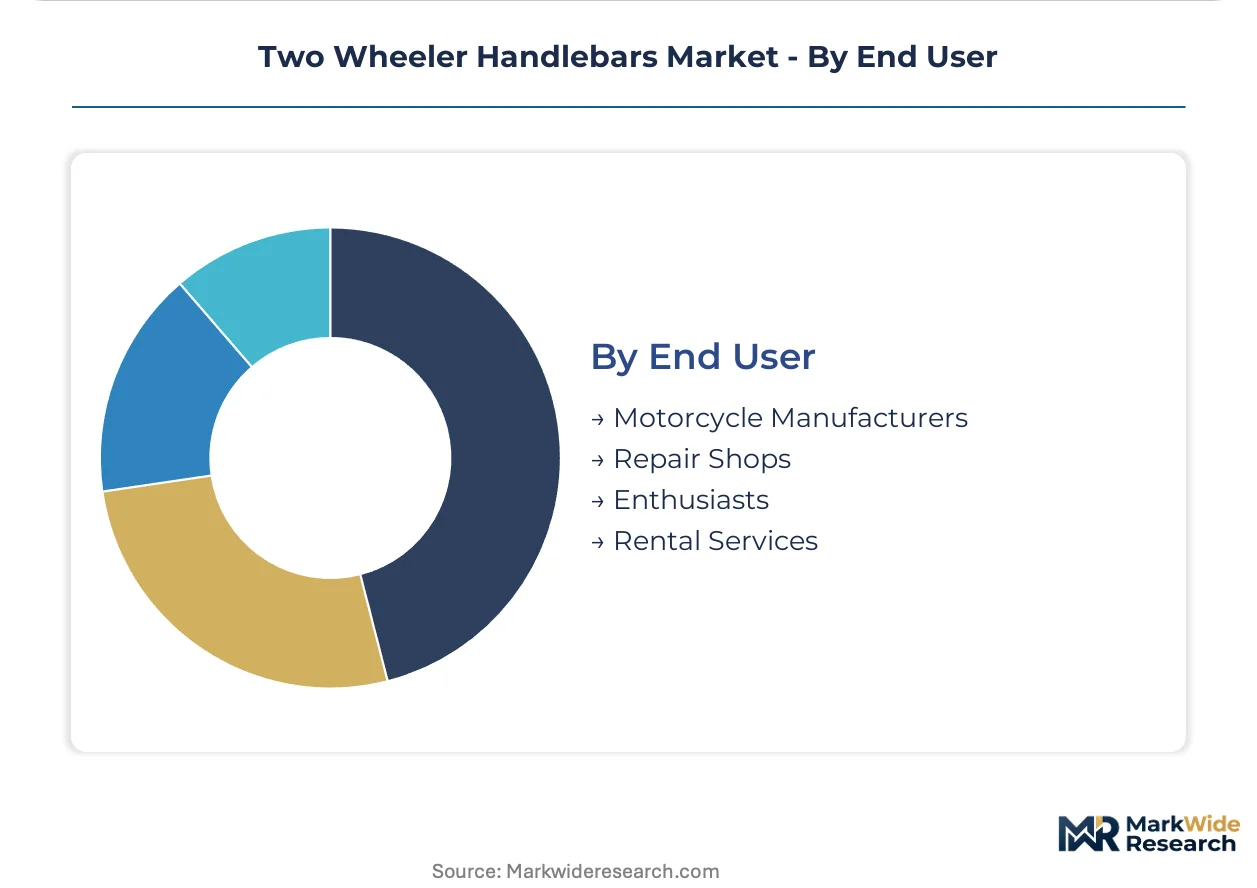
| Segmentation | Product Type: Street, Off-Road, Cruiser, Touring Material: Aluminum, Steel, Carbon Fiber, Plastic Installation: OEM, Aftermarket, Custom, Replacement End User: Motorcycle Manufacturers, Repair Shops, Enthusiasts, Rental Services |
| Companies Covered | ProTaper, Renthal, Biltwell, Performance Machine, Twisted Choppers, MOTECH GmbH & Co. KG, Flanders Company, Accel Motorcycle Products, Neken S.A.S., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two Wheeler Handlebars Market Evolving Landscape
Handlebar engineering is pivoting from passive structural members to active electronic integration platforms, with material science and regulatory chemistry driving simultaneous evolution in manufacturing processes and surface finishing specifications.
Carbon fiber reinforced polymer handlebar construction is converging with electric motorcycle mass reduction targets. Premium European and North American electric motorcycle assemblers specify 28.6mm clamp diameter carbon bars at 40% weight reduction versus 7075 aluminum equivalents. This convergence is compressing the addressable market for welded steel variants in performance segments while expanding composite prepreg layup capacity requirements among tier-1 suppliers.
REACH Annex XVII restrictions on hexavalent chromium compounds are eliminating decorative and corrosion-resistant plating from European-market steel handlebars. The regulation forces immediate conversion to trivalent chromium or anodized aluminum finishes across supply chains serving KTM, BMW Motorrad, and Ducati assembly plants. Component suppliers with captive anodizing lines in Austria and Germany capture margin expansion as plating-dependent competitors face process retooling costs.
Aftermarket customization demand is fragmenting procurement toward direct-to-consumer channels. Enthusiast segments in California, Bavaria, and Victoria now specify handlebar bend geometry, rise height, and sweep angle through online configurators rather than dealer inventory. This pattern is visible most acutely in motocross and enduro verticals where ProTaper and Renthal brand equity drives premium pricing outside OEM supply agreements.
Two Wheeler Handlebars Market Segmentation
Handlebar procurement patterns diverge sharply across product categories and installation channels, with upgrade cycles in enthusiast segments running 3-5 years versus 7-10 year replacement horizons for commuter OEM supply. Material selection and end-user specifications create distinct margin pools that suppliers must navigate through differentiated certification and distribution strategies.
Product Type:
Upgrade frequency varies dramatically across riding disciplines, with competitive off-road segments demanding seasonal replacement while touring applications prioritize fatigue longevity over weight reduction.
- Street:Standard 22mm clamp diameter configurations dominate urban commuter and sportbike applications across India's Maharashtra and Tamil Nadu assembly corridors. Demand concentrates in 1.8mm-2.5mm wall thickness aluminum extrusions for electric scooter platforms where integrated display mounts are becoming mandatory.
- Off-Road:Tapered-wall 7075 aluminum construction with 28.6mm clamp diameters withstands repeated impact loads in motocross and enduro disciplines. European REACH compliance is forcing rapid conversion from chromoly steel to anodized finishes across KTM and BMW Motorrad supplier networks.
- Cruiser:Wide-sweep steel geometries with chrome-plated finishes retain dominance in North American heavyweight motorcycle segments despite EPA restrictions on hexavalent chromium processes accelerating trivalent conversion timelines.
- Touring:Vibration-damping aluminum architectures with integrated heated grip channels and GPS mounting interfaces command premium positioning in long-distance motorcycle specifications from Germany's KBA-regulated manufacturers.
Street handlebars sit at the top of the volume ranking, with Off-Road climbing the fastest as electric dirt bike platforms expand competition calendars.
Material:
Cost tiers stratify procurement with aerospace-grade aluminum commanding 3-4x commodity steel pricing, while carbon fiber occupies a narrow premium niche constrained by layup cycle times.
- Aluminum:6061-T6 and 7075-T6 alloys deliver the strength-to-weight ratio required for electric two-wheeler mass reduction targets. India's BIS fatigue testing mandates are concentrating supply among domestic extruders with captive metallurgical certification capabilities in Pune and Chennai.
- Steel:Welded mild steel and chromoly tubular stock retains cost advantage in emerging market commuter segments. REACH Annex XVII restrictions are eliminating decorative hexavalent chromium plating from European supply chains, forcing process retooling investments.
- Carbon Fiber:Prepreg layup construction achieves 40% weight reduction versus aluminum equivalents for premium electric motorcycle platforms. Limited autoclave capacity in European and North American supplier bases constrains volume expansion despite specification pull from range-focused OEMs.
- Plastic:Glass-filled nylon and ABS composite handlebars serve low-speed electric scooter applications below 50km/h where impact loads remain minimal and cost positioning dominates procurement criteria.
Aluminum commands the dominant revenue position across ICE and electric platforms, with carbon fiber expanding most quickly as battery range optimization drives lightweighting specifications.
Installation:
Channel margins vary 2-3x between bulk OEM contracts and direct-to-consumer aftermarket sales, with customization demand fragmenting procurement toward online configurators.
- OEM:Long-term supply agreements with Honda, Yamaha, and TVS Motor anchor volume production in India and Vietnam assembly corridors. BIS certification and ISO welding documentation requirements create qualification barriers for new entrants.
- Aftermarket:Direct-to-consumer channels in California, Bavaria, and Victoria capture elevated margins through bend geometry customization and brand equity from ProTaper and Renthal. Enthusiast segments specify rise height and sweep angle through online platforms rather than dealer inventory.
- Custom:Small-batch CNC machining operations serve boutique motorcycle builders and racing teams with non-standard clamp diameters or integrated sensor housings. Lead times extend 8-12 weeks versus 2-3 weeks for catalog aftermarket products.
- Replacement:Crash damage and fatigue failure drive recurring demand through repair shops and dealer service departments. Replacement volumes track fleet age distributions and incident rates in high-density urban riding environments.
OEM installation maintains volume leadership through captive supply agreements, with Aftermarket gaining share fastest as enthusiast customization fragments procurement patterns.
End User:
Customer sophistication determines specification complexity, with manufacturers demanding integrated electronic architectures while rental operators prioritize damage tolerance and interchangeability.
- Motorcycle Manufacturers:Tier-1 suppliers to Hero MotoCorp, Bajaj Auto, and Royal Enfield manage BIS fatigue testing documentation and REACH material compliance across export programs. Throttle-by-wire integration requirements are compressing supplier qualification timelines.
- Repair Shops:Independent service networks in India's secondary cities and Vietnam's Hanoi province source BIS-certified replacement handlebars through regional distributors. Inventory breadth across diameter and bend specifications determines supplier selection.
- Enthusiasts:Motocross and enduro riders in North American and European markets specify premium 7075 aluminum or carbon fiber constructions through direct channels. Brand loyalty to ProTaper, Renthal, and Neken S.A.S. sustains pricing power outside OEM agreements.
- Rental Services:Fleet operators in Southeast Asian tourism corridors and Indian metropolitan areas prioritize steel construction for damage tolerance and cost-efficient replacement cycles. Standardized 22mm clamp diameters simplify inventory management across mixed motorcycle fleets.
Motorcycle Manufacturers represent the largest addressable revenue pool, with Enthusiasts showing the steepest expansion trajectory as electric performance segments mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized CNC programming talent concentrates in the United Kingdom and northern Italy, anchoring premium aluminum machining capabilities for tapered-wall handlebar production.
India
Domestic OEM demand from Hero MotoCorp and Bajaj Auto drives handlebar procurement volumes. BIS fatigue testing mandates force suppliers to maintain 18-24 month metallurgical certification cycles. Tamil Nadu and Maharashtra manufacturing corridors host qualified extruders with captive Pune and Chennai certification facilities.
Germany
KBA-regulated manufacturers specify integrated GPS mounting and heated grip channels for touring motorcycle platforms. REACH Annex XVII restrictions eliminate hexavalent chromium plating from steel handlebar supply chains. Bavarian anodizing specialists capture margin expansion as plating-dependent competitors retool.
United States
EPA restrictions on chromium processes accelerate trivalent conversion timelines for cruiser segment chrome finishes. California enthusiast segments drive direct-to-consumer aftermarket channels through online geometry configurators. Midwest distribution hubs service repair shop replacement demand across high-density urban riding environments.
Vietnam
Honda and Yamaha expansion in Vinh Phuc and Hanoi provinces generates unfilled demand for ISO-welding-certified suppliers. Local assembly growth outpaces domestic handlebar qualification capacity. Northern industrial zones attract regional distributors seeking BIS-certified replacement inventory.
United Kingdom
Renthal sustains motocross OEM supply relationships through captive extrusion capabilities. Specialized CAM expertise for 7075 aluminum tapered-wall machining concentrates in Midlands fabrication clusters. British suppliers export REACH-compliant anodized finishes to European KTM and BMW Motorrad networks.
Two Wheeler Handlebars Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the handlebar supply base. The market structure tiers between integrated extrusion operators and specialized CNC machining houses. Three archetypes dominate: captive foundry operators with in-house aluminum billet processing, contract manufacturers serving multiple OEM programs, and direct-to-consumer premium brands leveraging enthusiast loyalty. Capacity expansion and strategic partnerships represent the primary competitive vectors as electric platform integration requirements compress supplier qualification timelines.
Among premium-tier specialists, ProTaper occupies a position exemplifying off-road racing segment focus, while Renthal anchors OEM motocross supply relationships through geographic concentration. Neken S.A.S. represents European enduro manufacturing alignment with forged architecture specialization. These three names illustrate how brand equity and captive technical capabilities stratify competitive positioning across procurement channels.
| Leading Market Players |
|---|
| ProTaper |
| Renthal |
| Biltwell |
| Performance Machine |
| Twisted Choppers |
| MOTECH GmbH & Co. KG |
| Flanders Company |
| Accel Motorcycle Products |
| Neken S.A.S. |
| Others |
Value Network & Pricing Analysis
Aerospace-grade 7075 aluminum billet costs cascade through three distinct pricing tiers as raw material volatility from Zhejiang and Guangdong extrusion centers compresses margin pools for CNC-machined premium handlebar producers while commodity welded steel variants absorb cost pressure through volume scale.
Pricing Analysis
Bundle-unbundle dynamics split procurement between OEM long-term supply agreements with integrated fatigue testing documentation and aftermarket direct-to-consumer channels where bend geometry customization commands premium positioning. Three-tier pricing structure across premium CNC-machined, standard extruded aluminum, and economy welded steel levels reflects certification grade differentiation and captive anodizing capability. Pricing pressure stems from REACH-mandated process retooling costs as plating-dependent competitors face stranded asset write-downs. Fleet rental operators in Southeast Asian tourism corridors exhibit highest price sensitivity, while European enduro enthusiasts sustain lowest sensitivity through brand loyalty to forged architecture specialists.
Supply Chain Analysis
Regional distribution centers in Pune and Chennai anchor hub-and-spoke patterns for BIS-certified inventory serving Tamil Nadu and Maharashtra assembly corridors, with secondary nodes emerging in Vinh Phuc and Hanoi provinces. Raw aluminum tubular stock draws from Zhejiang and Guangdong extrusion clusters, 7075 aerospace-grade billet sources from UK and Italian supplier bases, and carbon fiber prepreg feeds from limited European and North American autoclave capacity. Single-geography concentration in Chinese extrusion creates tariff exposure vulnerability. Distribution runs through tier-1 OEM supply agreements, regional aftermarket distributors, and direct-to-consumer online configurators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as electric two-wheeler platform integration forces recurring supplier qualification cycles that favor incumbents with captive metallurgical certification capabilities.
For Market Incumbents: Cement defensive positioning through backward integration into captive aluminum extrusion capacity in Pune or Chennai corridors, insulating against Zhejiang supply disruption. Prioritize BIS fatigue testing protocol investments to compress 18-24 month validation timelines before emerging competitors qualify. Channel control through exclusive OEM supply agreements with Hero MotoCorp and Bajaj Auto anchors volume stability against aftermarket fragmentation. For New Entrants and Emerging Players: Aftermarket distributors in Vietnam's northern industrial zones present the most penetrable white-space target, as Honda and Yamaha expansion outpaces local ISO-welding-certified supplier capacity. Direct-to-consumer online configurators for enthusiast segments in Bavaria and Victoria enable brand building outside incumbent OEM relationships. Target electric scooter platforms below 50km/h with glass-filled nylon handlebar architectures where impact load specifications remain minimal and cost positioning dominates procurement. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap CNC machining specialists because fragmented CAM expertise concentration in UK and Italian clusters creates scarcity value for tapered-wall 7075 capability. Five-to-ten year viability rests on electric motorcycle battery range optimization sustaining lightweighting specification pull. Acquisition targets should demonstrate captive anodizing lines or forged architecture patents. Monitor BIS certification backlog duration as inflection indicator for domestic Indian supplier scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive Pune or Chennai capacity insulates ProTaper-tier suppliers from Zhejiang supply disruption and REACH compliance delays. |
| Throttle-by-Wire Sensor Integration | Embedded tubular assemblies for electric platforms command premium positioning as KTM and BMW Motorrad specifications converge. |
| BIS Certification Acceleration | Compressed 18-24 month validation cycles for new alloy grades unlock Hero MotoCorp and Bajaj Auto supply contract eligibility. |
| Carbon Fiber Autoclave Capacity Expansion | Limited European and North American prepreg layup infrastructure constrains volume for 40% weight reduction specifications. |
| Direct-to-Consumer Channel Development | Online geometry configurators in California and Victoria capture elevated margins outside Renthal-dominated OEM relationships. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM procurement managers at Honda and Yamaha, tier-1 supplier metallurgical certification leads, aftermarket distributor inventory planners, and electric motorcycle platform engineers with secondary validation against BIS fatigue testing protocols, REACH Annex XVII regulatory filings, customs trade data for aluminum tubular stock movements, and vehicle production databases tracking two-wheeler assembly volumes. Bottom-up channel sizing triangulated against top-down OEM spend allocation estimates.
Segment-weighting approaches distributed value across material tiers, installation channels, and end-user archetypes with electric platform content per vehicle serving as primary demand driver. CAGRs derived from production forecast linkages to handlebar specification rates across ICE and electric architectures. Modeled dimensions included clamp diameter configurations, wall thickness gradients, surface finish requirements, and regional regulatory compliance clusters. Forecast inputs incorporated BIS certification timeline assumptions and REACH implementation pace for chromium plating phase-out.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electric motorcycle adoption trajectory, 7075 aluminum aerospace demand competition, and Vietnam assembly hub localization policy shifts. Forecasts reflect documented assumptions about supplier qualification timelines and regulatory enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Adventure Motorcycle Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
Motorcycle ADAS Market
Bikes and Motorcycles
Ride on Bikes Market
Bikes and Motorcycles
Europe Two-Wheeler Market
Bikes and Motorcycles
Motorcycle Exhaust Mounting Brackets Market
Bikes and Motorcycles
Fixed Gear Bikes Market
Bikes and Motorcycles
Used Bike Market
Bikes and Motorcycles
South Africa Two-Wheeler Market
Bikes and Motorcycles
Electric Motorsport Market
Bikes and Motorcycles
North America Bicycle Market
Bikes and Motorcycles
300cc Motorcycle Market
Bikes and Motorcycles
Motorcycle Fuel Hoses Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
Motorsport Components Market
Bikes and Motorcycles
Smart Bicycle Accessories Market