
 Fishing Reels Market | 2026-2036
Fishing Reels Market Size, Share, and Industry Trends Forecast 2026-2036
Fishing Reels Market Intelligence
ISO 9001 quality management certification is bifurcating the competitive landscape into qualified OEM suppliers and uncertified regional assemblers. Shimano Inc. leverages its vertically integrated manufacturing base in Japan to sustain premium positioning across saltwater-resistant product lines. Daiwa Corporation anchors its North American presence through dedicated distribution centers serving the Great Lakes recreational fleet. Abu Garcia competes aggressively on price-performance ratios in the baitcasting segment through streamlined Asian supply chains.
Fishing reels are mechanical devices engineered to store, release, and retrieve fishing line through precision-machined gear trains typically operating at ratios between 4.0:1 and 8.1:1, with drag systems calibrated to withstand forces from 5 to 60 pounds depending on target species and fishing environment. Spinning reels dominate volume sales across recreational freshwater applications where ease of use and casting versatility outweigh specialized performance requirements. Baitcasting reels command disproportionate margin pools among tournament bass anglers who prioritize casting accuracy and gear ratio selectivity. Graphite-frame configurations are displacing aluminum in entry-level and mid-tier price bands due to weight advantages and moldability for complex geometries.
The EPA regulates lead content in fishing tackle through toxicity standards affecting sinker and jig manufacturing, with downstream compliance requirements now extending to reel component coatings and finishes. California's Proposition 65 mandates explicit labeling for products containing chemicals linked to reproductive harm, creating interstate distribution complexity for manufacturers serving multi-state retail networks. Stakeholders must monitor evolving state-level material restrictions and assess whether captive production of lead-free components justifies capital allocation against outsourced certified supply.
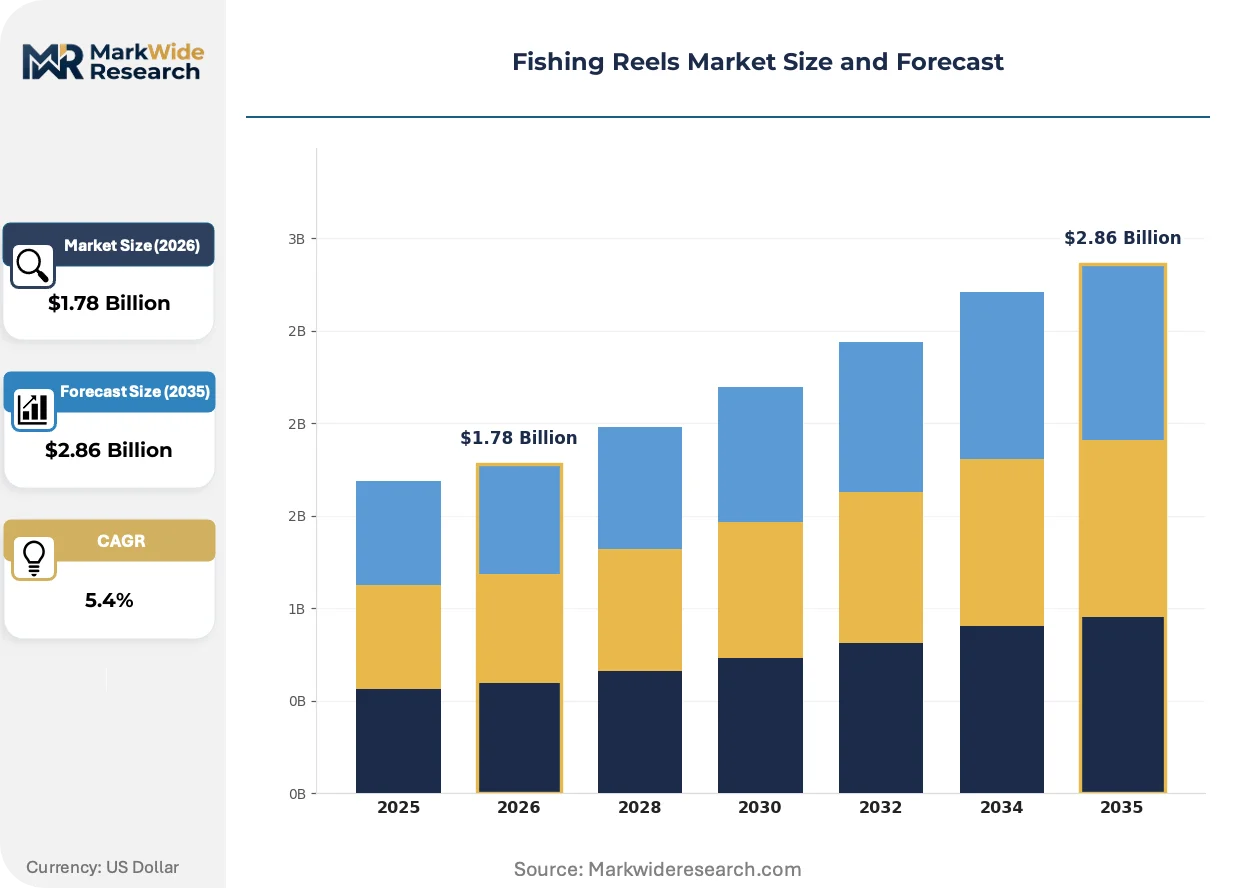
Market Dynamics
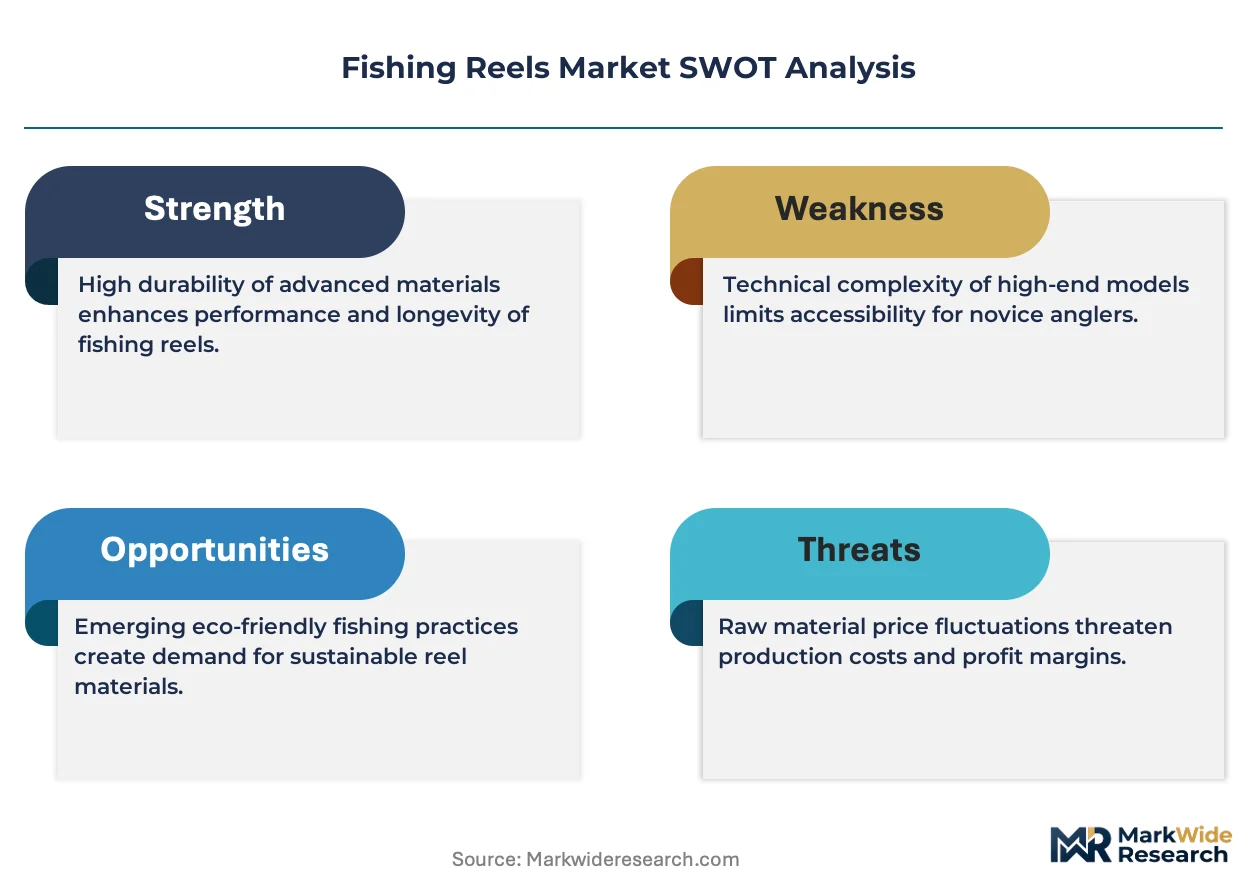
Material substitution away from lead-based components is compressing established supply relationships while opening procurement pathways for certified tungsten and composite suppliers across North American freshwater and saltwater reel manufacturing.
Growth Catalysts
- EPA Lead-Free Mandates:Updated toxicity standards for fishing tackle are forcing reel manufacturers to reformulate coatings and finishes, creating certified supplier tier advantages for early adopters.
- Graphite Frame Moldability:Injection-molded composite geometries now achieve strength-to-weight ratios matching aluminum at 40% lower mass, enabling ergonomic designs for extended casting sessions.
- Florida Charter Fleet Concentration:Saltwater guide operations in the southeastern United States are standardizing on corrosion-resistant sealed-bearing systems, pulling premium drag technology into mid-tier price bands.
Market Restraints
- Tungsten Input Cost Volatility:Dense-metal pricing fluctuations constrain margin stability for manufacturers transitioning from lead sinker integration to tungsten composite alternatives.
- ISO 9001 Certification Concentration:Quality management compliance gaps exclude regional Asian assemblers from OEM supply contracts with major North American distributors.
- Drag System Calibration Ceiling:Mechanical clutch mechanisms face fundamental friction-material limitations above 60-pound test configurations, capping performance in big-game applications.
Strategic Opportunities
- Great Lakes Recreational Expansion:Walleye and salmon trolling fleets across Michigan, Ohio, and Wisconsin are underserved by dedicated line-counter reel configurations optimized for precision depth control.
- California Proposition 65 Labeling Infrastructure:Compliance systems developed for reproductive-harm disclosure requirements can be licensed to multi-state retailers, creating recurring revenue from regulatory complexity.
- Digital-Physical Convergence:Embedded line-counter electronics with Bluetooth connectivity to sonar units are penetrating tournament bass segments where real-time depth synchronization improves pattern efficiency.
Industry Challenges
- Precision Machining Talent Scarcity:Gear train manufacturing requires CNC operators capable of maintaining 4.0:1 to 8.1:1 ratio tolerances within thousandths of an inch, a skill pool concentrated in Japanese industrial clusters.
- Dual Certification Timeline Compression:Simultaneous EPA coating compliance and ISO 9001 quality audits extend product launch cycles by 8-14 months for mid-tier manufacturers lacking dedicated regulatory affairs functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fishing Reels Market |
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $2.86 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spinning, Baitcasting, Fly Fishing, Trolling Material: Graphite, Aluminum, Stainless Steel, Composite End User: Recreational Anglers, Professional Fishermen, Charter Services, Retail Stores Feature: Lightweight, High Drag, Saltwater Resistant, Anti-Reverse |
| Companies Covered | Shimano Inc., Daiwa Corporation, Abu Garcia, Okuma Fishing Tackle Co., Ltd., Pure Fishing, Inc., The Orvis Company, Inc., Lew's Fishing, KastKing Brands Inc., Accurate Fishing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fishing Reels Market Strategic Shifts & Innovations
Active material science development and regulatory pressure on legacy chemistries are reconfiguring how reel manufacturers source, certify, and differentiate their product architectures across price tiers.
Carbon-fiber reinforced polymer frames are bifurcating the mid-market segment between weight-optimized recreational users and durability-focused saltwater operators. Tournament anglers in bass circuits are adopting sub-6-ounce spinning configurations for all-day casting endurance, while Florida charter captains demand aluminum-reinforced graphite hybrids that withstand corrosive spray without seizing. This material divergence is compressing single-platform SKU strategies and forcing parallel development tracks.
REACH substance restrictions in Europe are extending compliance obligations to reel component surface treatments and lubricant formulations, with downstream effects on North American export configurations. Manufacturers serving EU distribution channels must reformulate anti-corrosion coatings and bearing greases to eliminate SVHC-listed compounds, adding formulation R&D overhead that smaller OEMs absorb through private-label partnerships rather than captive chemistry labs.
Specialty retail consolidation is compressing the independent dealer channel that historically drove brand loyalty through hands-on gear education. Big-box sporting goods chains now capture 60% of spinning reel volume in the United States, displacing pro-shop staff expertise with self-service displays and online review dependency. This channel shift is most pronounced in the southeastern United States, where Florida-based saltwater specialists once dominated regional purchasing decisions through charter-fleet relationships.
Fishing Reels Market Segmentation
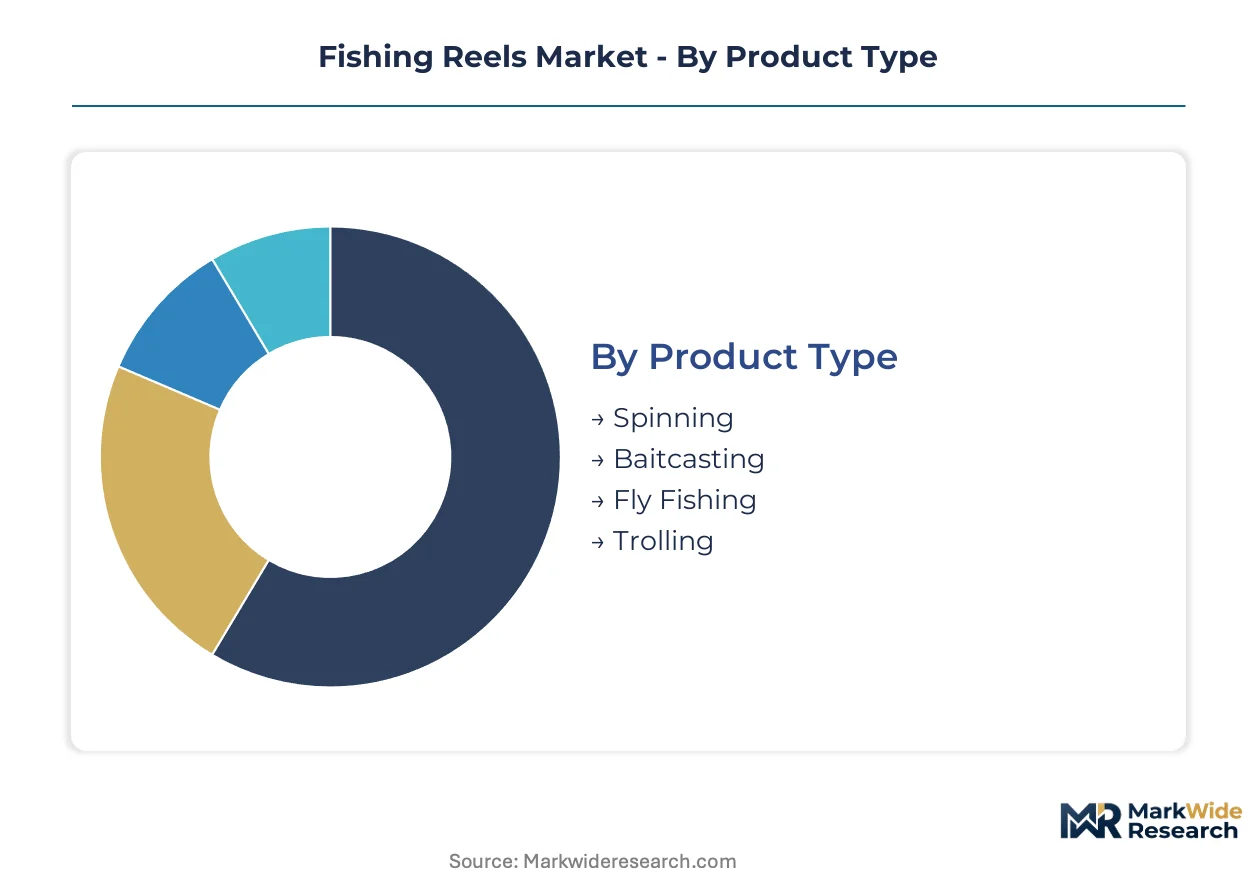
Reel manufacturers face divergent substitution pressures across product architectures. Material regulations and performance requirements fragment procurement strategies, forcing parallel supply chains for freshwater and saltwater configurations.
Product Type:
Substitution pressure from integrated rod-reel systems and electronic line management threatens standalone reel demand most acutely in tournament and charter segments where precision equipment bundling accelerates.
- Spinning:Open-face designs with fixed spools dominate recreational freshwater volume through casting versatility and minimal learning curves. Demand concentrates across southeastern United States bank fishing and pier operations where graphite-frame configurations displace aluminum at entry price points.
- Baitcasting:Revolving spool mechanisms with centrifugal or magnetic braking systems command premium positioning among tournament bass anglers prioritizing casting accuracy. Gear ratio selectivity from 6.4:1 to 8.1:1 drives replacement cycles as anglers match retrieve speed to lure presentation.
- Fly Fishing:Large-arbor disc-drag systems serve specialized trout and salmon applications where line management precision outweighs retrieval speed requirements.
- Trolling:Line-counter mechanisms integrated with depth synchronization electronics address Great Lakes walleye and salmon fleet requirements for precision depth control.
Spinning reels anchor the volume base while baitcasting configurations gain share at the steepest rate among performance-oriented anglers.
Material:
Cost tier stratification separates aerospace-grade alloys from molded composites, with regulatory compliance costs compressing mid-tier positioning.
- Graphite:Injection-molded carbon-fiber reinforced polymers achieve strength-to-weight ratios matching aluminum at 40% lower mass, enabling sub-6-ounce tournament configurations. Demand concentrates among recreational anglers prioritizing all-day casting endurance over corrosion resistance.
- Aluminum:CNC-machined frame and sideplate constructions withstand saltwater spray and impact damage, dominating Florida charter fleet specifications where equipment failure carries direct revenue consequences.
- Stainless Steel:Bearing races and gear shafts in 300-series alloys provide corrosion resistance for sealed saltwater systems.
- Composite:Hybrid aluminum-reinforced graphite frames merge weight optimization with structural rigidity for crossover freshwater-saltwater applications.
Graphite constructions dominate unit volume while composite hybrids expand most quickly as anglers seek single-platform versatility.
End User:
Customer type determines margin structure, with institutional procurement cycles contrasting against individual replacement patterns.
- Recreational Anglers:Individual consumers purchasing through big-box sporting goods chains drive spinning reel volume with price-elastic demand and online review dependency replacing pro-shop expertise.
- Professional Fishermen:Tournament competitors with sponsorship relationships prioritize baitcasting performance specifications and rapid replacement cycles, generating disproportionate margin contribution.
- Charter Services:Florida-based saltwater operations standardize on corrosion-resistant sealed-bearing systems, pulling premium drag technology into mid-tier price bands through fleet-scale procurement.
- Retail Stores:Independent dealers and chain buyers function as demand aggregators with inventory concentration in graphite-frame spinning configurations for recreational price bands.
Recreational anglers anchor the volume base while charter services gain share at the steepest rate through fleet standardization.
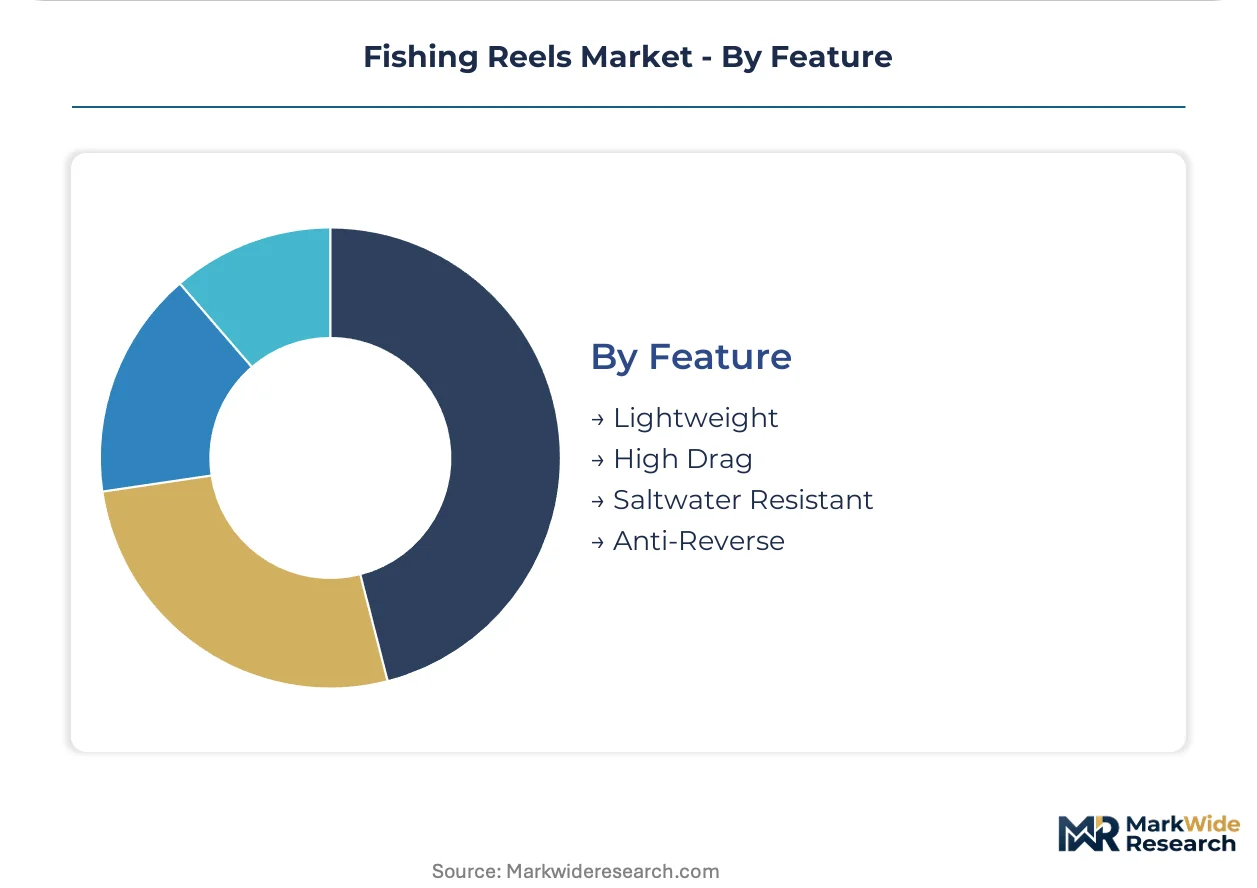
Feature:
Performance tier differentiation separates commodity configurations from specialized applications, with saltwater resistance commanding the widest price premiums.
- Lightweight:Sub-6-ounce spinning configurations with hollow rotor designs and carbon-fiber handles serve tournament bass anglers requiring all-day casting endurance without fatigue-induced technique degradation.
- High Drag:Carbon-fiber and cork composite drag systems calibrated above 20 pounds address big-game applications where mechanical clutch limitations cap performance above 60-pound test configurations.
- Saltwater Resistant:Sealed bearing chambers and anodized finishes prevent corrosion in marine environments, commanding price premiums from Florida charter operations.
- Anti-Reverse:Instant anti-reverse roller bearings eliminate handle backplay for hook-setting precision in predator fishing applications.
Lightweight configurations anchor the volume base while saltwater resistant features gain share at the steepest rate through southeastern fleet expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA lead-free mandates and state-level labeling requirements are redrawing manufacturing footprints across key demand centers. Material certification timelines now determine market access more than traditional distribution relationships.
United States
Florida's saltwater charter fleet generates concentrated demand for corrosion-resistant sealed-bearing systems, pulling premium drag technology into mid-tier price bands. The EPA's updated toxicity standards for fishing tackle extend compliance obligations to reel component coatings and finishes. California's Proposition 65 mandates explicit reproductive-harm labeling, creating interstate distribution complexity for manufacturers serving multi-state retail networks.
Japan
Precision-machining talent scarcity concentrates CNC gear train expertise in industrial clusters around Osaka and Nagoya, where operators maintain 4.0:1 to 8.1:1 ratio tolerances within thousandths of an inch. METI industrial standards govern quality management certification pathways that Japanese manufacturers leverage for premium positioning. Vertically integrated production bases in Sakai and Shizuoka sustain saltwater-resistant product line development through captive supply chain control.
China
GB standards for mechanical product safety and MIIT industrial guidance shape export-oriented reel manufacturing in Guangdong and Zhejiang provinces. Injection-molded graphite frame production clusters around Ningbo and Dongguan, achieving strength-to-weight ratios matching aluminum at 40% lower mass. Dual carbon goals accelerate energy efficiency requirements in foundry and machining operations, compressing margins for mid-tier assemblers lacking dedicated regulatory affairs functions.
Germany
REACH substance restrictions extend compliance obligations to reel component surface treatments and lubricant formulations for manufacturers serving EU distribution channels. ECHA SVHC-listed compound elimination requirements add formulation R&D overhead that smaller OEMs absorb through private-label partnerships. Precision engineering traditions in Baden-Württemberg and Bavaria support specialized fly fishing reel manufacturing for trout and salmon applications.
South Korea
MFDS chemical safety assessments and KATS product standards govern domestic market access for imported fishing tackle. MFDS notification requirements for new material compositions create entry barriers for uncertified regional assemblers. Busan-Ulsan industrial corridor hosts composite material suppliers developing tungsten alternatives to lead-based sinker integration.
Fishing Reels Market Key Industry Players
Listed leaders compete with private specialists across certification tiers, with ISO 9001 quality management bifurcation separating qualified OEM suppliers from uncertified regional assemblers. The vendor base stratifies into three archetypes: vertically integrated Japanese manufacturers with captive precision-machining capabilities, streamlined Asian supply chain operators competing on price-performance ratios, and heritage-brand specialists anchored in regional angling traditions. Dominant competitive moves include dual certification timeline compression strategies and graphite-frame moldability investments that displace aluminum in entry-level and mid-tier price bands.
Within the premium-tier vector, Shimano Inc. and Daiwa Corporation occupy positions sustained by precision-manufacturing heritage and quality management certification depth. Abu Garcia exemplifies the price-performance archetype through streamlined supply chain configurations. These three named entities anchor competitive positioning discussions without exhausting the full participant set.
| Leading Market Players |
|---|
| Shimano Inc. |
| Daiwa Corporation |
| Abu Garcia |
| Okuma Fishing Tackle Co., Ltd. |
| Pure Fishing, Inc. |
| The Orvis Company, Inc. |
| Lew's Fishing |
| KastKing Brands Inc. |
| Accurate Fishing |
| Others |
Cost & Logistics Intelligence
Ninety-day graphite frame procurement lead times from Ningbo injection molders compress margin buffers for mid-tier reel assemblers while amplifying pricing power for vertically integrated Japanese manufacturers with captive carbon-fiber polymer production. This inventory-to-certification linkage forces smaller OEMs into private-label arrangements that surrender margin to distributors controlling EPA-compliant coating certification pathways.
Pricing Analysis
Certification level creates the primary spread across reel price bands, with ISO 9001-qualified suppliers commanding 15-25% premiums over uncertified regional assemblers. Three-tier pricing structure across premium, standard, and economy levels stratifies by drag system calibration precision and saltwater sealing specifications. Cost compression in entry-level graphite configurations intensifies as Chinese molders achieve aluminum-comparable strength-to-weight ratios at 40% lower mass. Recreational anglers purchasing through big-box chains exhibit highest price sensitivity, while Florida charter fleet procurement officers prioritize equipment reliability over per-unit cost.
Supply Chain Analysis
Osaka-Nagoya precision machining clusters constrain global gear train supply for 4.0:1 to 8.1:1 ratio configurations, with CNC operator scarcity extending component lead times. Manufacturing concentrates in Japan, China, and South Korea, with raw material dependencies spanning carbon-fiber polymer feedstock from Zhejiang, tungsten dense-metal alternatives from Busan-Ulsan suppliers, and 300-series stainless bearing races from Sakai foundries. Single-source vulnerability in Japanese CNC talent pools threatens supply continuity for premium drag system manufacturers. Distribution runs through big-box sporting goods chains capturing 60% of spinning reel volume, displacing independent pro-shop networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth-enabled line-counter electronics are transforming tournament bass angling into a platform ecosystem where reel-sonar interoperability determines pattern efficiency and brand stickiness. This digital-physical convergence rewards manufacturers who control both hardware specifications and data protocol standards.
For Market Incumbents: Shield premium positioning by deepening captive precision-machining capabilities in Osaka industrial clusters before CNC operator scarcity worsens. Accelerate ISO 9001 certification depth as a barrier against uncertified Asian assemblers exploiting EPA lead-free mandate gaps. Defensive patenting around sealed-bearing chamber geometries protects Florida charter fleet relationships from corrosion-resistant composite entrants. For New Entrants and Emerging Players: Anchor in Great Lakes walleye trolling segments where line-counter reel configurations remain underserved by dedicated precision depth control systems. Target Michigan-Ohio-Wisconsin recreational fleets through charter captain influencer networks rather than retail channel slotting fees. Go-to-market leverage centers on Bluetooth sonar integration partnerships with marine electronics manufacturers lacking reel hardware expertise. For Investors and Strategic Acquirers: Carve-out targets emerge from heritage-brand reel manufacturers with regional angling traditions but lacking EPA coating compliance infrastructure. Long-term viability hinges on dual certification capabilities spanning ISO quality management and state-level Proposition 65 labeling systems. Acquisition screening should prioritize targets with dormant distribution relationships in southeastern US saltwater markets. Watch for inflection when tungsten input cost volatility forces lead-dependent manufacturers into distressed restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon-Fiber Polymer Production | Ningbo molders achieving aluminum-comparable strength-to-weight ratios at 40% lower mass compress mid-tier pricing. |
| Bluetooth Sonar Integration Partnership | Real-time depth synchronization with Lowrance and Humminbird units penetrates tournament bass segments. |
| EPA Lead-Free Coating Certification Investment | Early compliance with toxicity standards creates supplier tier advantages for OEM contracts. |
| Great Lakes Charter Fleet Distribution Capture | Underserved walleye and salmon trolling demand in Michigan-Ohio-Wisconsin corridors offers white-space expansion. |
| ISO 9001 Quality Management Depth | Certification gaps exclude regional assemblers from major North American distributor supply contracts. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with reel manufacturing executives, EPA regulatory affairs specialists, Florida charter fleet operators, and big-box sporting goods category buyers; alongside secondary validation through EPA toxicity standard filings, MIIT industrial guidance documents, METI quality certification databases, and customs trade records for carbon-fiber polymer imports. Bottom-up unit economics from component cost structures triangulated against top-down market sizing from distributor shipment data.
Across the projection horizon, the analytical framework modeled segmentation by reel mechanism type, frame material composition, end-user archetype, and saltwater resistance feature tier. CAGRs derived from historical shipment velocity adjusted for EPA mandate implementation timelines and graphite substitution elasticity. Industry-specific forecast inputs incorporated CNC machining capacity constraints in Japanese industrial clusters and Florida charter fleet equipment replacement cycles.
Decision-makers should treat outputs as directional under stable tungsten pricing and ISO certification adoption curves; material deviation in dense-metal input costs or regulatory timeline acceleration would warrant model refresh. Practitioners should keep alternative scenarios live as EPA state-level enforcement consistency and REACH substance restriction extensions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Global Slingshot Market
Outdoor & Sports
LED Fishing Light Market
Outdoor & Sports
Camping Tent Market
Outdoor & Sports
Global Scuba Diving Equipment Market
Outdoor & Sports
Artificial Turf Market
Outdoor & Sports
Fishing Tackle Box Market
Outdoor & Sports
Camping Beds and Mats Market
Outdoor & Sports
Kayak Accessories Market
Outdoor & Sports
China Fishing Reels Market
Outdoor & Sports
Skimboard Market
Outdoor & Sports
Swimming Pool Equipment Market
Outdoor & Sports
Fish Hunting Equipment Market
Outdoor & Sports
Fishing Line Market
Outdoor & Sports
Walkbehind Lawnmower Market
Outdoor & Sports
Freshwater Fishing Rod Market
Outdoor & Sports
Lawn Roller Market