
 Camping Tent Market | 2026-2036
Camping Tent Market Size, Share, and Industry Trends Forecast 2026-2036
Camping Tent Market Analysis
Modular tent systems with detachable vestibules and connectable living pods is realigning how families and group campers evaluate purchase trade-offs. Johnson Outdoors leverages its marine and outdoor portfolio to sustain year-round manufacturing utilization across Wisconsin-based plants. Hilleberg the Tentmaker anchors its reputation on four-season tunnel designs engineered for polar and alpine conditions. Coleman Company dominates mass-market retail channels through private-label exclusivity and seasonal volume commitments with big-box outdoor retailers.
A camping tent is a portable, collapsible shelter constructed from woven synthetic fabrics—typically ripstop nylon or polyester with polyurethane coatings—and supported by aluminum or fiberglass poles, designed to protect occupants from precipitation, wind, and ultraviolet exposure during temporary outdoor habitation. The structure relies on tensioned geometry, sealed seams, and ventilated rainflies to manage condensation and thermal regulation across varying elevations and climates. Family tents and dome tents command the largest volume pools due to recreational camping's accessibility and lower price entry points, while backpacking tents capture disproportionate margin contribution through technical specification premiums and specialized distribution. Pop-up tents represent the fastest-growing configuration as instant-pitch mechanisms reduce setup friction for festival-goers and casual weekend users.
The Consumer Product Safety Commission and EPA regulate flame-retardant chemical treatments and textile manufacturing emissions in the United States, while REACH restricts per- and polyfluoroalkyl substances across European supply chains. These frameworks compel brands to reformulate coatings, certify materials through third-party laboratories, and document supply chain chemistry for market access. Stakeholders must monitor evolving chemical restriction schedules and invest in alternative durable water repellent technologies before compliance deadlines eliminate incumbent product lines from key markets.
Market Dynamics
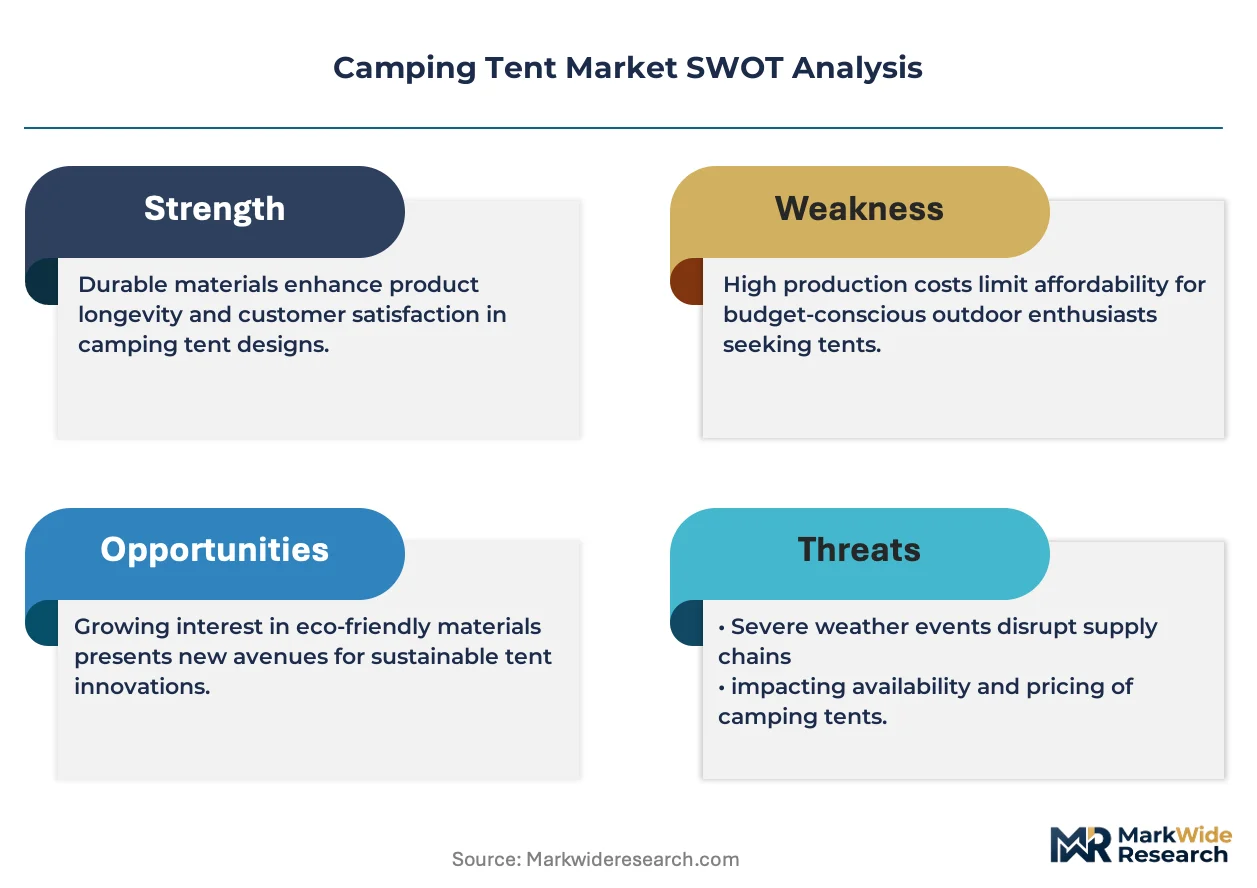
Fluorocarbon-free durable water repellent chemistry is forcing wholesale reformulation of tent fabric coatings as REACH deadlines and state-level PFAS bans eliminate incumbent C8 and C6 treatments from commercial sale.
Growth Catalysts
- EU Green Deal procurement mandates:Public-sector outdoor recreation contracts across Germany and France now require recycled-content certification, pulling premium sustainable tent volumes into institutional channels.
- Expedition tourism infrastructure:Guided polar and high-alpine routes in Norway, Iceland, and New Zealand are expanding the addressable base for four-season technical shelters.
- Silicone-impregnated nylon:This fabric technology extends seam-tape-free waterproofing to sub-kilogram backpacking designs, opening price premiums in the thru-hiker segment.
Market Restraints
- Aluminum pole supply concentration:Extruded 7000-series alloy production clusters in China's Zhejiang province create single-source vulnerability for mid-market pole suppliers.
- PFAS regulatory friction:REACH's 2025 restriction timeline for perfluorinated treatments forces inventory write-downs of legacy-coated fabric stocks held in European distribution centers.
- Inflatable air-beam substitution:Rapid-pitch air-tent designs for festival and car-camping use are capturing casual users who previously purchased traditional pole-supported dome tents.
Strategic Opportunities
- India's emerging trekking infrastructure:Himalayan trail development in Uttarakhand and Himachal Pradesh is creating first-time demand for lightweight shelters among domestic adventure tourists.
- Biomimetic surface engineering:Lotus-effect micro-structuring combined with plant-based waxes offers a convergence path to eliminate synthetic repellents entirely.
- Direct-to-consumer refurbishment channels:Pre-owned tent marketplaces are unlocking circular revenue streams and lowering trial barriers for entry-level buyers.
Industry Challenges
- Seam-sealing technician scarcity:Manual application of polyurethane tape requires skilled labor that has not scaled with automated fabric-cutting capacity.
- Multi-standard certification complexity:Simultaneous ISO 5912, EN 13538, and CPAI-84 flame-retardancy testing creates timeline risk for seasonal product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camping Tent Market |
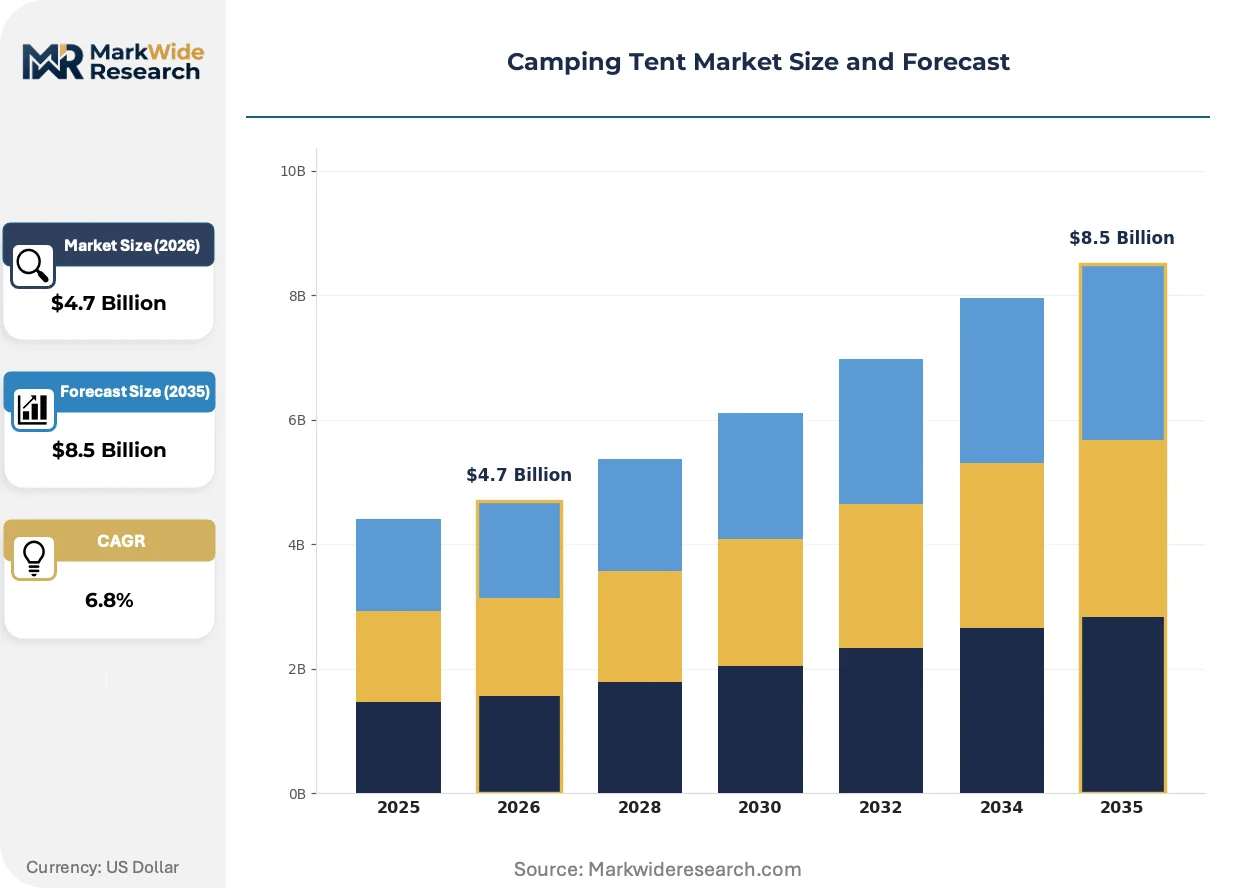
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Backpacking Tents, Family Tents, Dome Tents, Pop-up Tents Material: Nylon, Polyester, Canvas, Fiberglass Capacity: One Person, Two Person, Four Person, Six Person Application: Hiking, Camping, Festival, Emergency |
| Companies Covered | NEMO Equipment, Johnson Outdoors, The North Face, Hilleberg the Tentmaker, Dometic Group, Coleman Company, Mountain Safety Research, Berghaus Limited, Big Agnes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camping Tent Market Emerging Trajectories
Solar-integrated fabric systems are electrifying how off-grid campers manage power logistics, embedding photovoltaic threads directly into rainfly materials to eliminate separate panel transport.
Photovoltaic textile lamination is electrifying the technical tent category by embedding flexible silicon cells into polyester rainfly substrates. Alpine expedition teams and remote research stations are adopting these shelters to reduce battery payload weight. This convergence of energy generation and weather protection is compressing the traditional separation between shelter and power infrastructure in high-performance segments.
REACH's 2025 PFAS restriction is eliminating fluorocarbon water repellents from European supply chains and compelling reformulation toward paraffin and silicone alternatives. Manufacturers face accelerated R&D timelines to maintain hydrostatic head ratings without C6 chemistry. The backpacking and mountaineering segments are absorbing the steepest cost increases as technical performance specifications resist degradation.
Festival-goers and casual campers are compressing purchase cycles toward single-use or limited-use disposable shelters, treating tents as consumable event accessories rather than durable equipment. Mass-market retailers are responding with sub-fifty-dollar instant-pitch designs engineered for two-to-three deployment cycles. This behavioral shift is most pronounced in the United Kingdom and Australian music festival circuits, where waste-to-landfill concerns have yet to override convenience preferences.
Camping Tent Market Segmentation
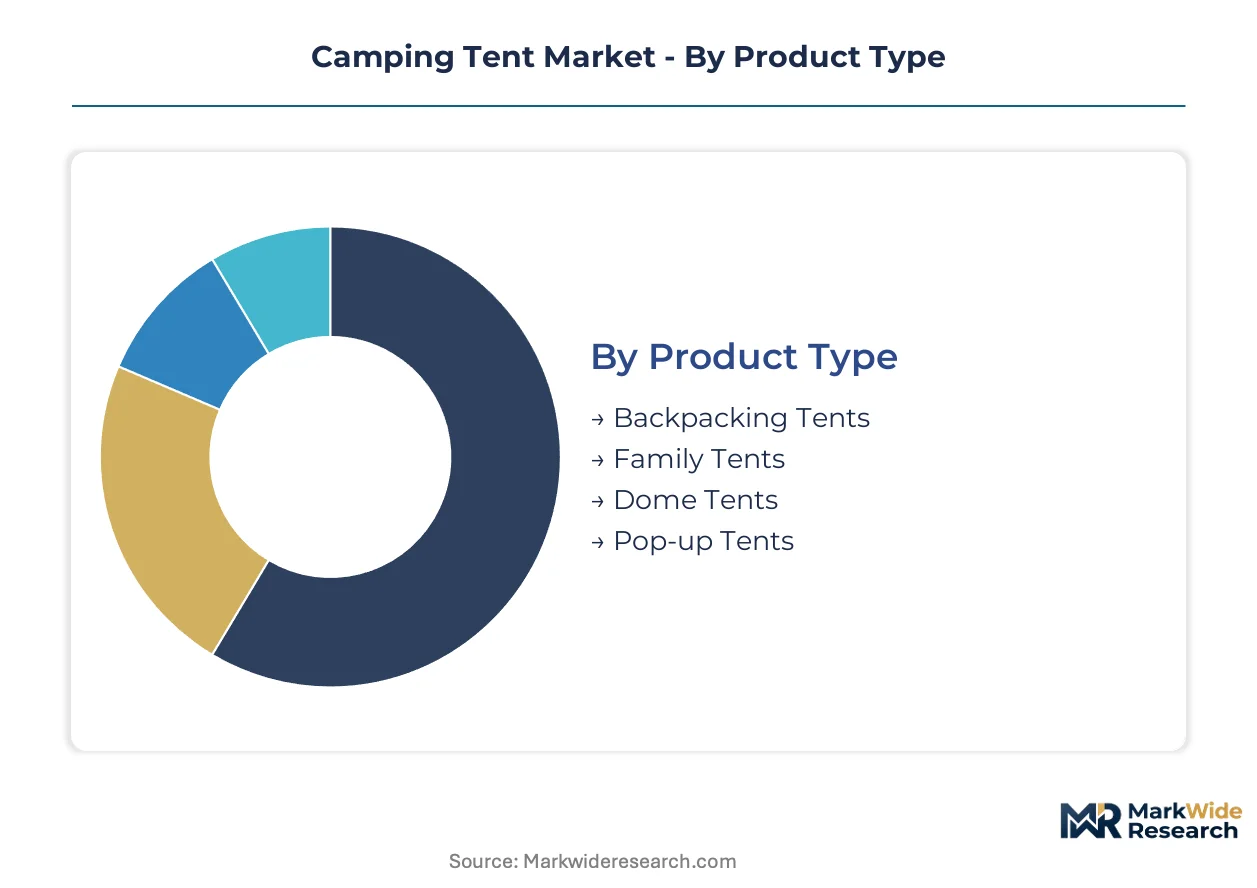
Camping tent purchasing decisions split across technical performance requirements, group size logistics, and seasonal use patterns. Manufacturers configure production lines around these divides, with fabric treatment capabilities and pole fabrication capacity determining which segments each supplier can serve profitably.
Product Type:
Supply concentration clusters around mass-market configurations where automated cutting and seam-sealing equipment achieves highest utilization rates.
- Backpacking Tents:Ultralight shelters engineered with silicone-impregnated nylon and DAC aluminum poles, prioritizing packed weight below two kilograms. Demand concentrates among thru-hikers on the Pacific Crest Trail and Tour du Mont Blanc, where gram-counting discipline justifies technical specification premiums.
- Family Tents:Multi-room structures with standing-height ceilings and detachable vestibules, constructed from heavier polyester with fiberglass pole options. Weekend campers across Germany's Black Forest and Australia's Great Ocean Road drive volume, prioritizing livable space over packed weight.
- Dome Tents:Geodesic pole architecture delivering structural stability in wind, popular with car campers and basecamp expeditions.
- Pop-up Tents:Pre-tensioned spring-pole mechanisms enabling sub-minute deployment, capturing festival-goers at Glastonbury and Coachella who treat shelters as single-event consumables.
Family tents absorb the bulk of installed capacity; pop-up tents are expanding most quickly.
Material:
Cost tier differentiation separates premium technical fabrics from commodity synthetics, with coating chemistry compliance costs widening the spread.
- Nylon:High tenacity ripstop weaves with polyurethane or silicone coatings, dominating sub-two-kilogram backpacking designs where strength-to-weight ratio determines purchase decisions.
- Polyester:UV-resistant heavier denier constructions, standard in family and car-camping tents where weight matters less than price point and colorfastness.
- Canvas:Cotton-polyester blends with natural breathability, serving glamping operators and hunting outfitters in Montana and Scotland seeking extended-season durability.
- Fiberglass:Pultruded pole material and rigid tent-peg substrate, positioned at entry price points where replacement cost trumps longevity.
Polyester commands the greatest production volume; nylon carries the steepest specification premiums.
Capacity:
Customer type segmentation aligns with trip duration and group composition, from solo ultralight missions to multi-generational basecamp gatherings.
- One Person:Minimalist bivy-compatible shelters for solo thru-hikers and bikepackers traversing the Great Divide Mountain Bike Route.
- Two Person:The standard couple configuration, balancing interior space against split-carry weight distribution on Appalachian Trail section hikes.
- Four Person:Family entry point with separate sleeping and storage zones, prevalent at developed campgrounds in Yosemite and the Lake District.
- Six Person:Maximum capacity for group camping and scout troops, requiring vehicle access and large pitch footprints.
Two-person models dominate unit shipments; four-person designs are climbing the fastest as family camping participation rises.
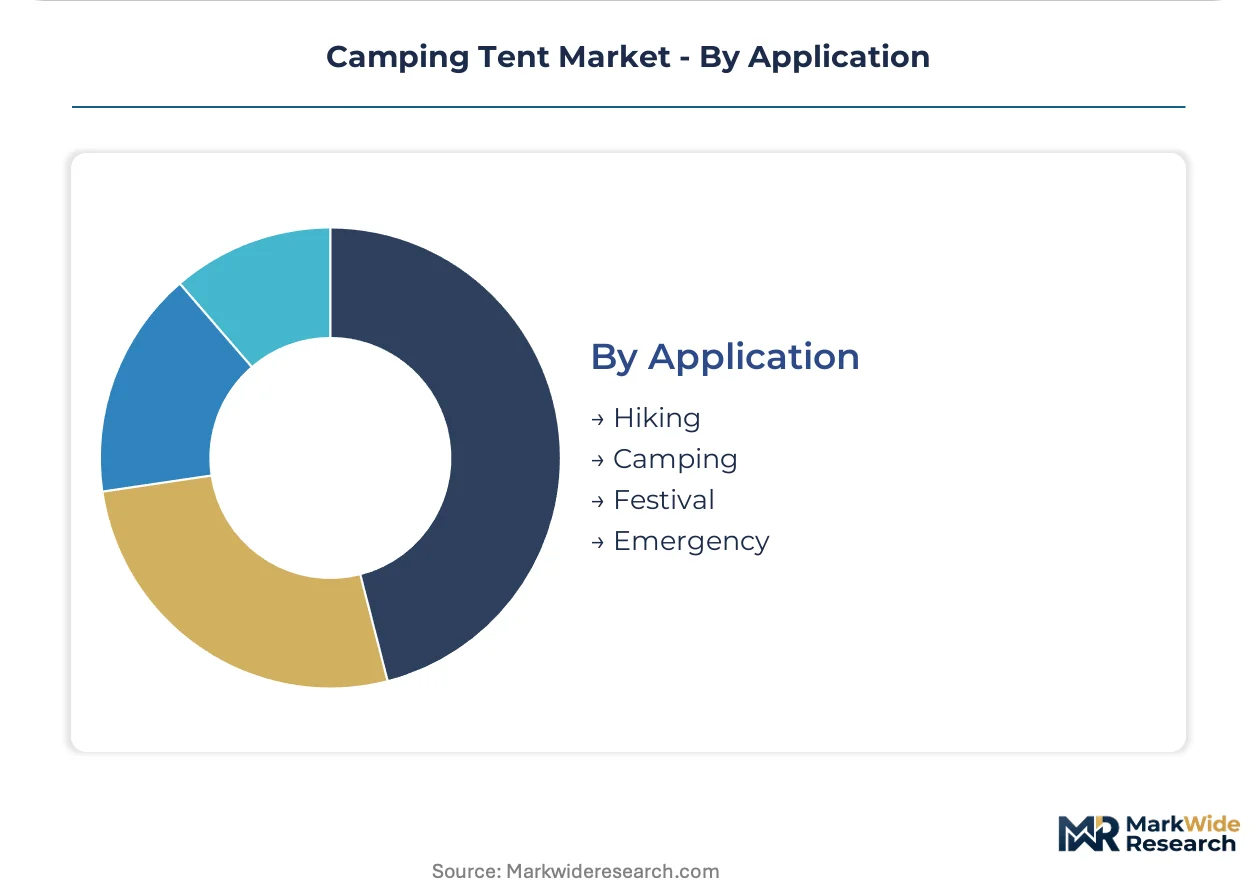
Application:
Volume distribution tracks seasonal outdoor recreation calendars, with emergency preparedness creating non-discretionary demand insulated from leisure spending cycles.
- Hiking:Technical overnight and multi-day trekking shelters, specified for alpine conditions in the Swiss Alps and Colorado Rockies.
- Camping:Recreational vehicle-accessible and backcountry overnight use, spanning developed campgrounds to dispersed Bureau of Land Management lands.
- Festival:Single-use or limited-cycle instant-pitch designs, treated as consumable accessories at music events across the United Kingdom and Australian circuits.
- Emergency:Rapid-deployment shelters for disaster relief agencies and military field operations, procured through institutional channels with stockpiling requirements.
Camping applications absorb the bulk of installed capacity; festival use is gaining share fastest despite sustainability headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Zhejiang Free Trade Zone concentrates aluminum extrusion capacity for tent pole manufacturing, drawing fabricators seeking integrated metalworking and polymer coating facilities within bonded logistics parks.
United States
Expedition tourism across the Pacific Crest Trail and Colorado Rockies sustains demand for ultralight backpacking shelters. The EPA regulates flame-retardant chemical treatments under CPAI-84 standards, compelling reformulation of polyester coatings. Seattle and Boulder anchor design clusters where brands prototype silicone-impregnated nylon for thru-hiker segments.
Germany
Family camping participation across the Black Forest and Bavarian Alps drives multi-room tent volumes with standing-height specifications. REACH restrictions on perfluorinated substances mandate fluorocarbon-free durable water repellent chemistry by 2025. Munich hosts technical fabric testing laboratories certifying hydrostatic head ratings for alpine-grade shelters.
China
Contract manufacturing for global brands concentrates in Zhejiang and Guangdong provinces, where automated cutting and seam-sealing equipment achieves scale economies. The Ministry of Ecology and Environment enforces dual carbon goals on textile coating emissions. Ningbo clusters DAC aluminum pole extrusion capacity serving mid-market and premium tent suppliers.
Australia
Great Ocean Road caravan parks and Outback trekking routes generate demand for UV-resistant polyester family tents and canvas hunting shelters. The Therapeutic Goods Administration does not regulate camping equipment, leaving compliance to voluntary ISO 5912 standards. Melbourne houses distribution centers for Asia-Pacific retail channels stocking festival and car-camping configurations.
India
Himalayan trail development in Uttarakhand and Himachal Pradesh creates first-time lightweight shelter demand among domestic adventure tourists. The Bureau of Indian Standards mandates textile labeling but lacks specific camping tent technical regulations. Dehradun emerges as a trekking outfitter hub connecting domestic manufacturers with Himalayan guide services.
Camping Tent Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price bands. The vendor base separates into three strategic archetypes: marine-and-outdoor conglomerates sustaining year-round manufacturing utilization, alpine-specialist tunnel-tent engineers, and mass-market retailers securing private-label exclusivity through seasonal volume commitments. Capacity expansion and portfolio diversification dominate competitive moves as manufacturers seek offsetting revenue streams against weather-dependent camping seasons.
Within the conglomerate tier, Johnson Outdoors leverages cross-portfolio manufacturing utilization across Wisconsin-based plants. Hilleberg the Tentmaker anchors the technical-specialist position with four-season tunnel designs engineered for polar conditions. Coleman Company exemplifies mass-market scale through big-box retail channel dominance and seasonal procurement commitments.
| Leading Market Players |
|---|
| NEMO Equipment |
| Johnson Outdoors |
| The North Face |
| Hilleberg the Tentmaker |
| Dometic Group |
| Coleman Company |
| Mountain Safety Research |
| Berghaus Limited |
| Big Agnes |
| Others |
Supply Flow & Price Mechanics
Big-box outdoor retailers and festival procurement channels concentrate demand volumes that favor contract-based pricing with seasonal volume commitments and penalty clauses for shortfall. This buyer structure compresses margin capture for manufacturers serving mass-market segments while premium technical brands maintain price autonomy through specialized distribution.
Pricing Analysis
Expedition outfitters and alpine guide services pay premiums for sub-90-day lead times on four-season tunnel designs with certified hydrostatic head ratings. Three-tier pricing structure across premium, standard, and economy levels separates DAC aluminum pole configurations from fiberglass alternatives and entry-level steel. Cost compression in the festival-disposable segment is intensifying because single-use buyers treat shelters as consumable event accessories. Price sensitivity peaks among casual weekend campers purchasing through mass-market channels, while technical users absorbing specification premiums show minimal elasticity.
Supply Chain Analysis
Direct-to-specialty-retail channels handle premium brand distribution, while mass-market volumes flow through big-box outdoor retailers and festival merchandise contractors. Fabric weaving and coating capacity clusters in China, Vietnam, and Taiwan, with DAC aluminum pole extrusion concentrated in Ningbo's Zhejiang province. Manufacturers draw from 7000-series aluminum billets, silicone-impregnated nylon yarns, and polyurethane coating resins. Single-source vulnerability runs through China's aluminum extrusion base, where bonded logistics parks integrate metalworking with polymer coating. Distribution runs through seasonal procurement cycles tied to Northern Hemisphere camping calendars.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers pursue captive supply of fluorocarbon-free coating chemistry to secure REACH compliance ahead of 2025 deadlines.
For Market Incumbents: Extend certification investment into third-party hydrostatic head and flame-retardancy testing laboratories to accelerate seasonal product launches. Build backward integration into silicone-impregnated nylon weaving capacity to offset raw material cost volatility from coating reformulation. Inflatable air-beam substitution in the casual segment threatens traditional pole-supported dome volumes, requiring defensive portfolio diversification. For New Entrants and Emerging Players: Capture India's Himalayan trekking infrastructure buildout in Uttarakhand and Himachal Pradesh before domestic manufacturers scale technical capabilities. Festival and car-camping applications offer the most penetrable white space, with sub-fifty-dollar instant-pitch designs engineered for limited deployment cycles. Direct-to-consumer refurbishment marketplaces provide a go-to-market angle with circular revenue positioning and lowered trial barriers for entry-level buyers. For Investors and Strategic Acquirers: The window for entry favors mid-market specialists with fluorocarbon-free chemistry capabilities and established third-party certification relationships. Long-term viability over the projection horizon hinges on regulatory compliance positioning rather than volume scale. Watch REACH enforcement intensity and state-level PFAS ban adoption as the inflection indicator for competitive shakeout timing.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorocarbon-Free Coating Transition | REACH's 2025 PFAS deadline eliminates C6 chemistry, forcing wholesale reformulation of fabric treatments. |
| Silicone-Impregnated Nylon Scale-Up | Seam-tape-free waterproofing opens sub-kilogram backpacking premiums for thru-hiker segments. |
| Direct-to-Consumer Refurbishment Launch | Pre-owned tent marketplaces unlock circular revenue and lower trial barriers for entry-level buyers. |
| Himalayan Distribution Partnership | Uttarakhand and Himachal Pradesh trail development creates first-time lightweight shelter demand. |
| Photovoltaic Textile Integration | Flexible silicon cell lamination into rainfly substrates reduces battery payload for alpine expeditions. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with tent brand product managers, specialty retail buyers, alpine guide services, and coating chemistry suppliers. ECHA restriction schedules, EPA CPAI-84 flame-retardancy documentation, and ISO 5912 certification databases provided compliance tracking. Bottom-up shipment data from fabric weavers and pole extruders triangulated against top-down retail audit estimates.
Granularity-level modeling separated backpacking, family, dome, and pop-up configurations by capacity tier and seasonal use case. Product type, material grade, capacity, and application dimensions were projected across the analysis window. CAGRs derived from segment-level volume trajectories and price-premium absorption rates in technical versus mass-market tiers. Silicone-impregnated nylon adoption curves and air-beam substitution elasticities informed configuration mix shifts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH enforcement intensity and Himalayan infrastructure buildout pacing. Periodic stress-testing of base assumptions is recommended, particularly regarding PFAS substitution timelines and festival-disposable demand sustainability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Artificial Turf Market
Outdoor & Sports
Riding Multi-Purpose Lawn Mower Market
Outdoor & Sports
Swimming Pool Accessories Market
Outdoor & Sports
Global Swimming Pool Market
Outdoor & Sports
Cold Plunge Pools Market
Outdoor & Sports
Fishing Line Market
Outdoor & Sports
Walkbehind Lawnmower Market
Outdoor & Sports
Global Paintball Equipment Market
Outdoor & Sports
Swimming Pool and Spa Market
Outdoor & Sports
Above Ground Swimming Pools Market
Outdoor & Sports
Portable Kayaks Market
Outdoor & Sports
Autonomous Golf Caddy Market
Outdoor & Sports
Freshwater Fishing Rod Market
Outdoor & Sports
Fishing Reels Market
Outdoor & Sports
Europe Swimming Pools and Spas Market
Outdoor & Sports
Mexico Fishing Reels Market