
 Global Scuba Diving Equipment Market | 2026-2036
Global Scuba Diving Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Scuba Diving Equipment Market Outlook
Silicone rubber is hardening its position as the dominant elastomer in mask skirts and regulator mouthpieces, displacing natural rubber latex due to superior UV resistance and hypoallergenic properties. Huish Outdoors LLC leverages its portfolio breadth across Atomic Aquatics and Zeagle brands to control the premium regulator segment. Mares S.p.A anchors European manufacturing with vertically integrated fin production at its Italian facility. Johnson Outdoors Inc. competes through its Scubapro brand's established dealer network across North American dive shops.
Scuba diving equipment encompasses the integrated life-support and protective gear systems enabling human underwater respiration and thermal management, including open-circuit regulators delivering breathing gas at ambient pressure, aluminum or steel cylinders rated to 207-300 bar, and neoprene or membrane drysuits maintaining thermal neutrality in water temperatures from 4°C to 30°C. Recreational diving applications sustain the largest revenue pool as certification agencies standardize equipment packages for Open Water through Divemaster curricula. Technical diving segments for cave and wreck penetration are generating the fastest growth in specialized gear as trimix and rebreather training expands. Wetsuit product lines face margin compression from Asian manufacturing competition while tank and regulator assemblies retain higher value-add through testing and certification requirements.
The US Coast Guard regulates commercial diving operations under 46 CFR while the EU's CE marking and MDR frameworks govern personal protective equipment sold across member states. ISO 6425 standards for dive watches and EN 250 for regulators establish baseline performance thresholds that manufacturers must satisfy for market access. Thailand's Department of Tourism and China's SAMR are tightening import inspection protocols for breathing gas compressors. Stakeholders should monitor how rebreather technology standards evolve as training agencies debate certification prerequisites.
Market Dynamics
Recreational diving certification agencies are standardizing equipment packages across training curricula, creating bundled procurement pull-through that concentrates purchasing power among a handful of training organizations and their affiliated retail networks.
Growth Catalysts
- EU F-Gas Regulation:The accelerated phase-out of refrigerants in dive tank filling compressors is forcing equipment upgrades across European dive centers, expanding the installed base of alternative gas handling systems.
- Southeast Asian dive tourism corridor:Fleet renewal cycles among operators from Phuket to Koh Tao are generating concentrated bulk orders for entry-level gear and rental equipment pools.
- Silicone rubber substitution:Superior UV resistance and hypoallergenic properties in mask skirts and regulator mouthpieces are displacing natural rubber latex, opening material upgrade cycles across replacement markets.
Market Restraints
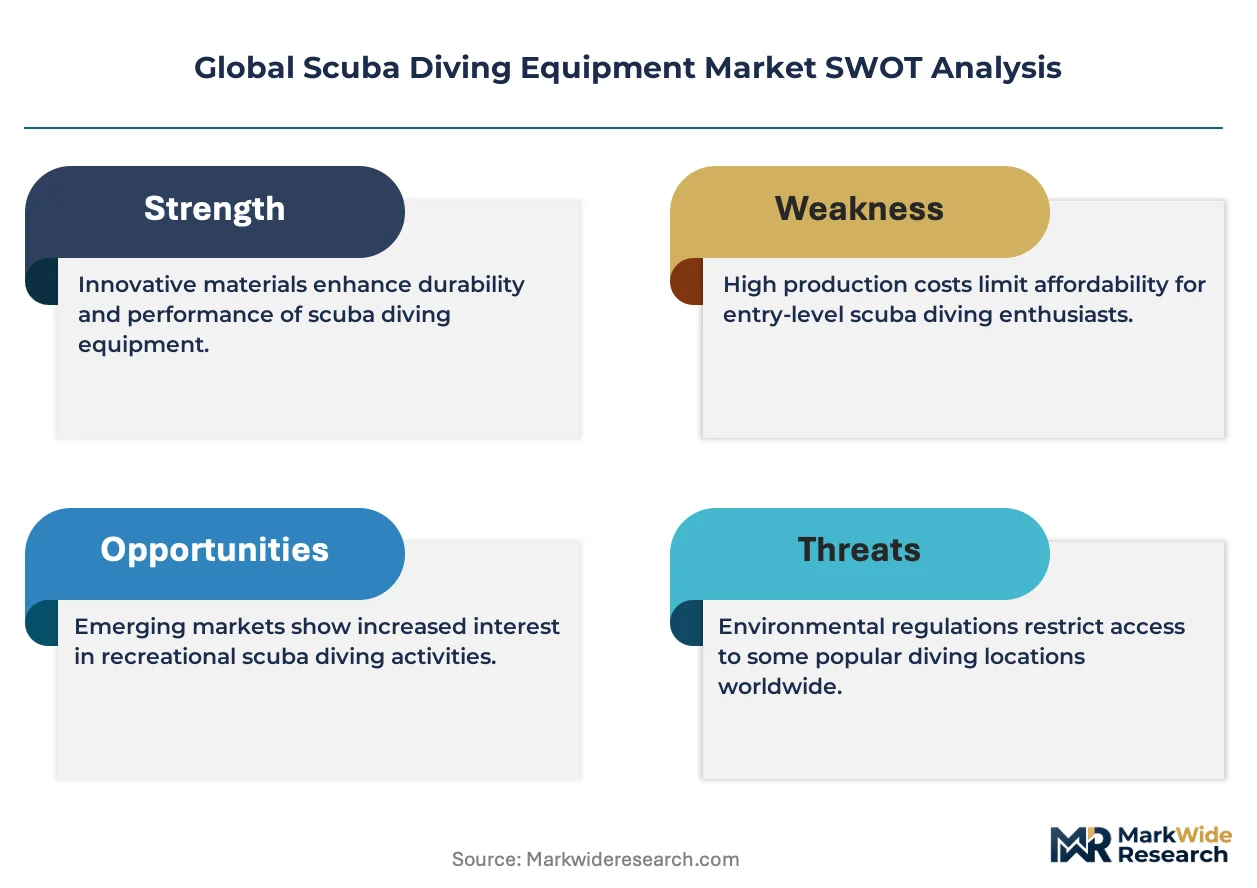
- Aluminum and steel input volatility:Cylinder manufacturing faces margin pressure from commodity price swings in high-pressure vessel alloys, compressing value retention in tank assembly segments.
- Asian manufacturing concentration:Wetsuit production gravity in low-cost assembly zones erodes pricing power for branded manufacturers unable to differentiate through proprietary neoprene formulations or membrane technologies.
- Technical diving certification bottlenecks:Extended training timelines for trimix and rebreather credentials limit addressable market expansion in the fastest-growing gear category.
Strategic Opportunities
- Technical diving training expansion:Cave and wreck penetration curricula are proliferating beyond traditional strongholds, creating equipment demand in underpenetrated markets where rebreather adoption remains nascent.
- Thailand's import inspection tightening:Breathing gas compressor certification requirements are creating compliance service opportunities for testing and validation providers aligned with Department of Tourism protocols.
- Rebreather-integrated sensor convergence:PO2 monitoring and dive computer integration are enabling premium positioning for electronics-enabled life-support systems that command higher replacement margins.
Industry Challenges
- Rebreather technician scarcity:Specialized maintenance skills for closed-circuit systems concentrate among limited service networks, constraining aftermarket revenue capture for manufacturers.
- Multi-jurisdiction certification lag:Divergence between ISO 6425, EN 250, and national regulator testing protocols extends product validation timelines and fragments homologation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Scuba Diving Equipment Market |
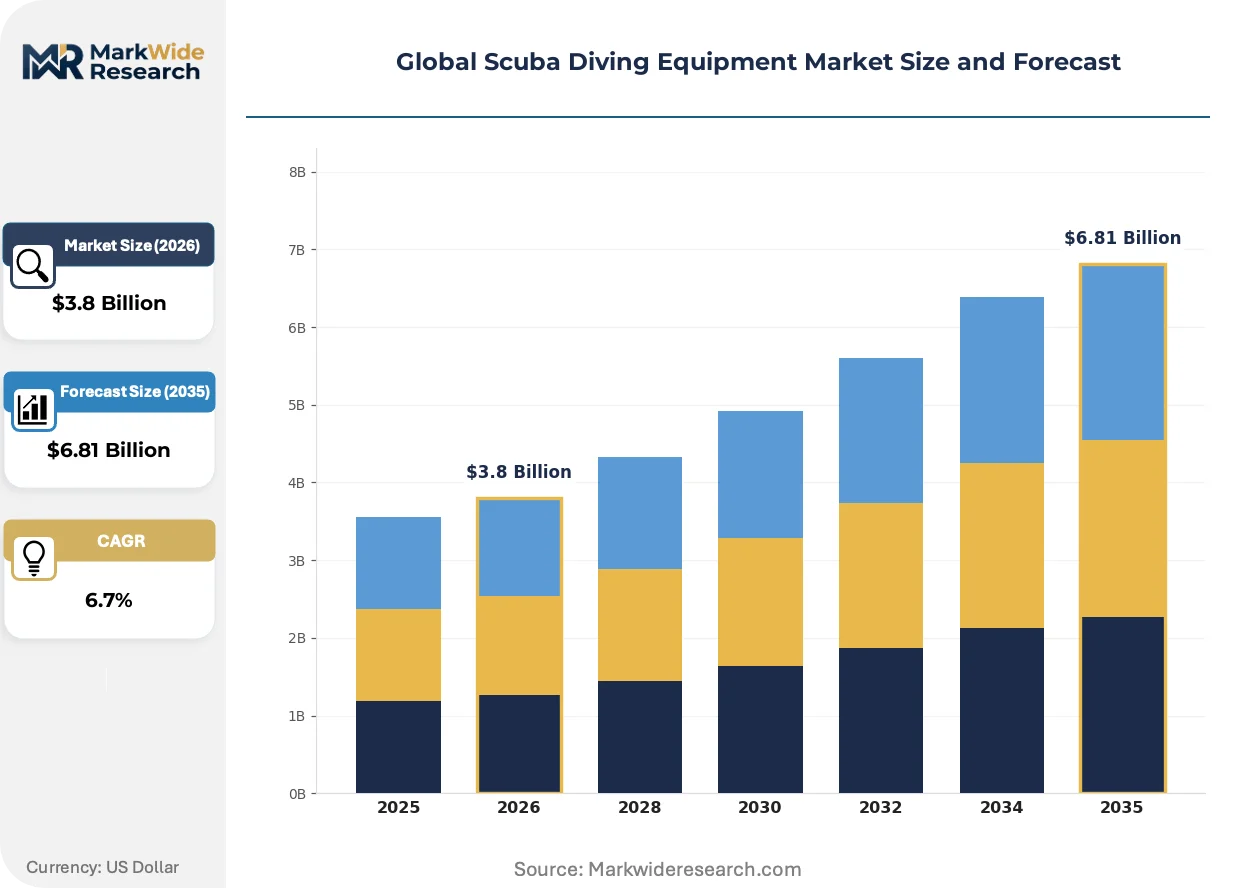
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diving Masks, Fins, Wetsuits, Tanks Technology: Single Lens, Full Face, Semi-Dry, Inflatable Application: Recreational Diving, Technical Diving, Commercial Diving, Military Diving End User: Divers, Instructors, Water Sports Centers, Research Institutions |
| Companies Covered | Huish Outdoors LLC, Mares S.p.A, Johnson Outdoors Inc., Oceanic Worldwide, Apeks Marine Equipment Ltd., Aqua Lung International, Cressi Sub S.p.A, Bauer Compressors Inc., Scubapro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Scuba Diving Equipment Market Strategic Shifts
Equipment intelligence and materials science are converging to reshape product architecture, with sensor integration and elastomer chemistry advancing faster than legacy manufacturing processes can absorb.
Closed-circuit rebreather technology is consolidating technical diving equipment architectures by integrating gas delivery, CO2 scrubbing, and electronic monitoring into unified life-support platforms. Advanced training agencies are mandating rebreather credentials for deep penetration profiles, compressing demand for conventional open-circuit configurations in the premium segment. This consolidation is enabling manufacturers to capture higher lifetime value through consumables and service attachment.
The EU's F-Gas Regulation is accelerating compressor fleet turnover by prohibiting specific refrigerants used in high-pressure breathing air systems. Dive center operators face capital replacement cycles with limited retrofit alternatives, channeling investment toward alternative gas handling technologies. Italian and German equipment suppliers are capturing this displacement through expanded service networks.
Certification-driven equipment standardization is compressing retail discretion in training-affiliated purchases. Open Water through Divemaster curricula now specify complete gear packages, shifting volume through agency-authorized channels rather than independent shop selection. This pattern concentrates most visibly in Thailand's Phuket-Koh Tao corridor where operator fleet procurement aligns with agency equipment partnerships.
Global Scuba Diving Equipment Market Segmentation
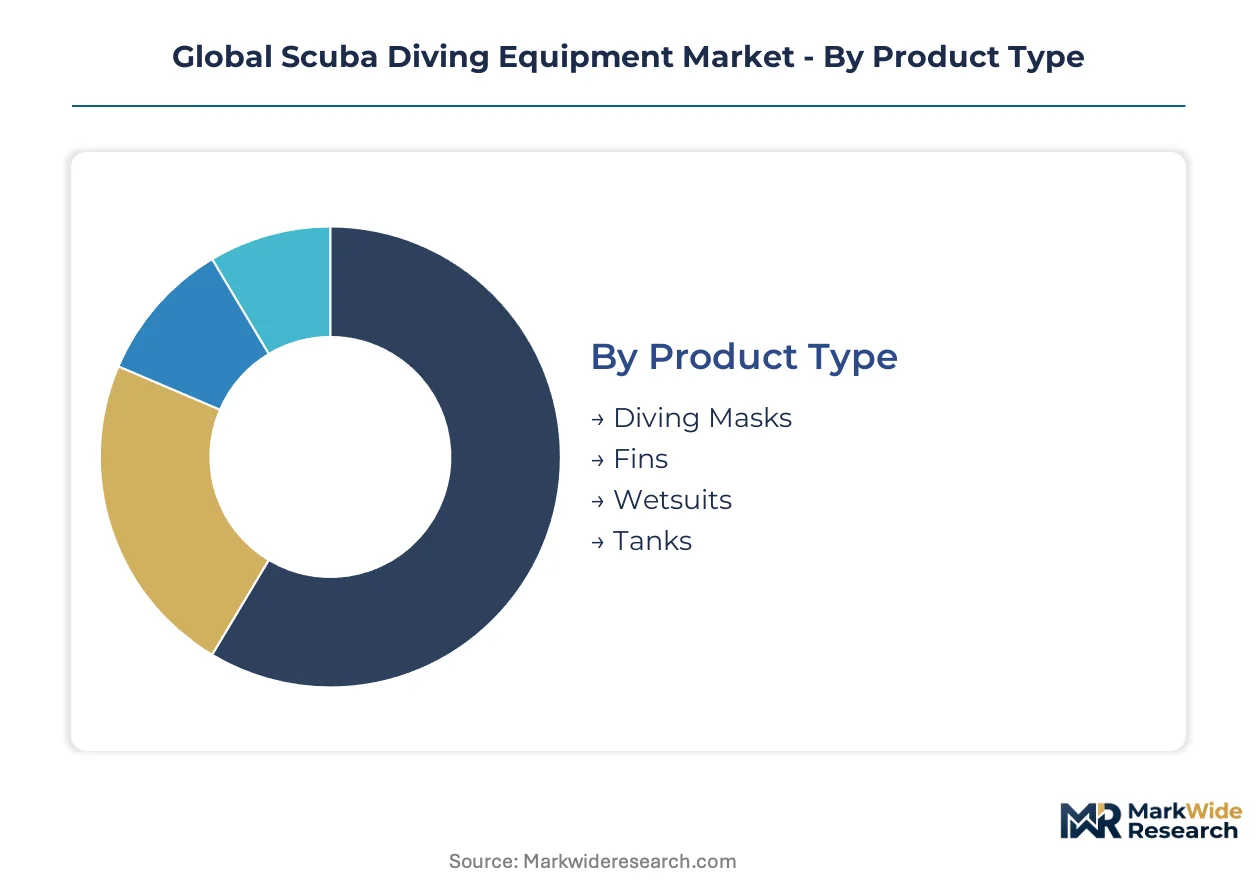
Equipment segmentation in scuba diving reflects diver certification levels, thermal protection requirements, and operational depth profiles. Product architecture varies dramatically between recreational open-water gear and closed-circuit rebreather systems for technical penetration. Understanding these splits enables manufacturers to align R&D investment with actual usage intensity and replacement cycles.
Product Type:
Volume concentrates in entry-level rental equipment pools across Southeast Asian dive tourism corridors, while premium value accumulates in life-support assemblies with certification-dependent replacement schedules.
- Diving Masks:Silicone rubber skirts with tempered glass lenses dominate recreational configurations. Phuket-to-Koh Tao operator procurement concentrates demand for dual-lens designs with prescription insert compatibility. Thailand's fleet renewal cycles drive bulk mask replacement every 18-24 months.
- Fins:Open-heel adjustable straps with spring buckles command premium positioning for boat diving, while full-foot designs serve shore-entry markets. Mares S.p.A's vertically integrated Italian production anchors European supply for blade stiffness variants optimized by finning technique.
- Wetsuits:Neoprene thickness gradients from 3mm to 7mm address tropical through temperate water exposure. Asian manufacturing concentration compresses margins for standard neoprene while proprietary membrane drysuits retain pricing power in cold-water technical segments.
- Tanks:Aluminum 80-cubic-foot cylinders sustain recreational volume, with high-pressure steel variants serving technical divers requiring extended bottom times. Hydrostatic testing mandates create aftermarket service attachment for certified fill stations.
Today's leader: Tanks. Tomorrow's challenger: Diving Masks.
Technology:
Optical clarity requirements and seal integrity standards differentiate price tiers, with electronic integration enabling premium positioning in monitoring-enabled configurations.
- Single Lens:Panoramic viewport designs eliminate frame obstruction for underwater photography applications. Demand clusters among certified divers progressing toward advanced open-water credentials with imaging equipment.
- Full Face:Integrated regulator-second-stage designs permit underwater voice communication for commercial and military operations. CE marking and MDR frameworks govern respiratory interface safety for European procurement.
- Semi-Dry:Splash guards and purge valves reduce water ingress in surface chop without full drysuit complexity. Water sports centers in Thailand specify these for introductory discover-scuba experiences.
- Inflatable:Buoyancy compensator devices with integrated weight systems enable precise trim control. Instructors require redundant bladder configurations for student safety supervision.
Single Lens configurations anchor current volume. Full Face systems are climbing the fastest as commercial safety protocols tighten.
Application:
Certification depth limits and gas mixture requirements fragment equipment specifications, with technical penetration driving specialized architecture investment.
- Recreational Diving:Open-circuit regulators and standard air mixtures sustain the largest equipment volume. Certification agencies standardize complete gear packages from Open Water through Divemaster curricula, bundling procurement through authorized channels.
- Technical Diving:Trimix and rebreather training expansion generates the steepest equipment demand growth. Cave and wreck penetration profiles mandate redundant gas delivery, CO2 scrubbing, and electronic PO2 monitoring in unified platforms.
- Commercial Diving:Surface-supplied and saturation systems fall outside recreational equipment definitions. US Coast Guard 46 CFR regulations govern commercial diver life-support in domestic waters.
- Military Diving:Closed-circuit rebreathers for covert operations require electromagnetic and acoustic signature minimization. National defense procurement operates through classified supply channels with limited vendor access.
Recreational Diving retains installed base dominance. Technical Diving shows the steepest expansion trajectory as training agency curricula proliferate.
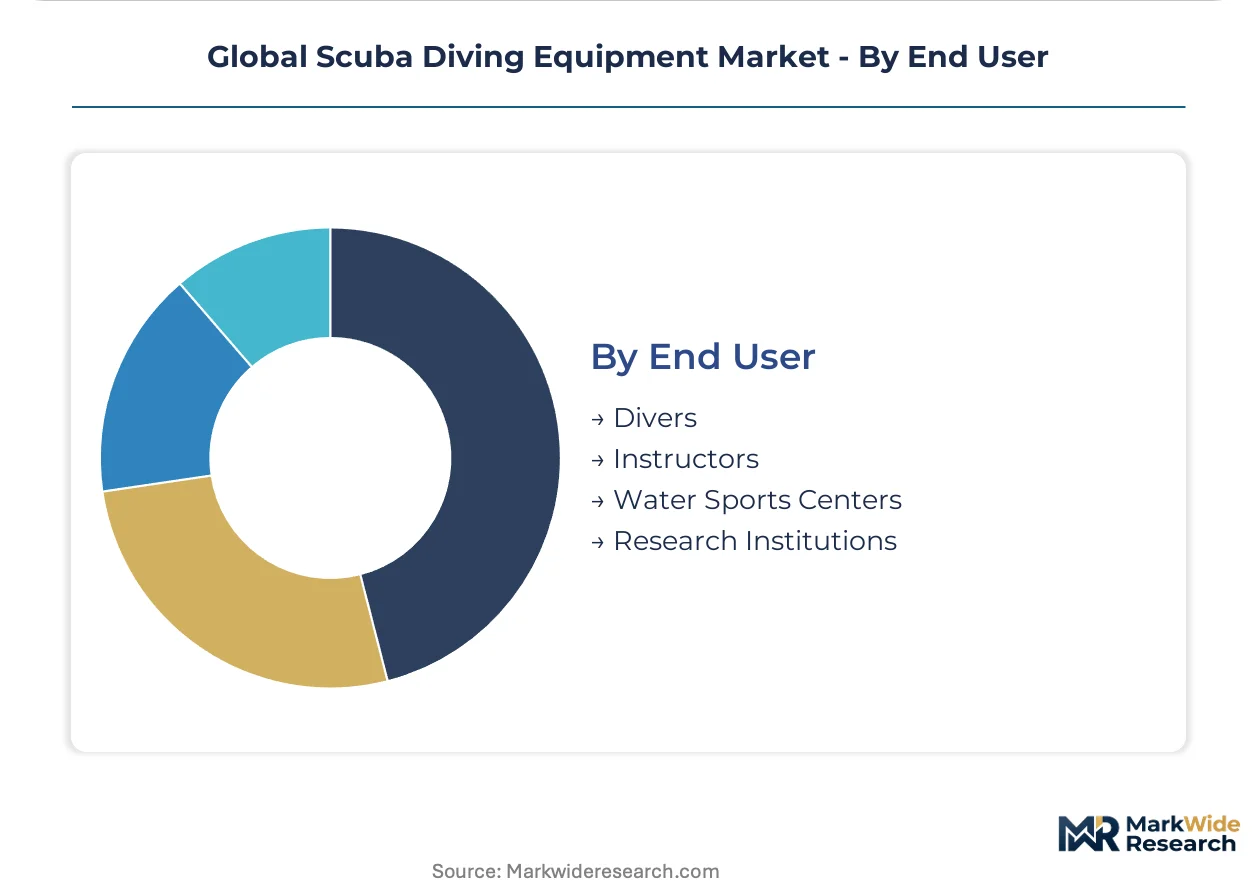
End User:
Purchasing authority splits between individual divers selecting personal gear and institutional buyers specifying rental pools with durability and sanitization priorities.
- Divers:Individual certification progression drives personal equipment investment from mask and fins through complete life-support assemblies. Replacement cycles accelerate with annual dive frequency above 50 immersions.
- Instructors:Professional liability requirements mandate current-model equipment with documented service history. Agency affiliation often specifies brand partnerships for gear standardization in training environments.
- Water Sports Centers:Fleet scale and maintenance infrastructure determine procurement specifications. Thailand's Department of Tourism import inspection protocols for breathing gas compressors influence equipment sourcing decisions.
- Research Institutions:Scientific diving programs under AAUS or equivalent frameworks require equipment traceability and calibration documentation. Sensor-integrated configurations support data collection objectives.
Water Sports Centers command bulk volume leverage. Research Institutions represent the emerging specification driver for electronics-enabled monitoring integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's dive tourism corridor from Phuket to Koh Tao concentrates equipment procurement for Southeast Asian operator fleet renewal. The United States sustains premium regulator demand through certification agency standardization. Germany and Italy anchor European manufacturing with compressor and fin production respectively. Australia's technical diving training expansion drives specialized gear adoption.
United States
Recreational certification agencies standardize complete gear packages from Open Water through Divemaster curricula, bundling procurement through authorized retail channels. The US Coast Guard regulates commercial diving operations under 46 CFR. Florida's dive tourism clusters sustain steady equipment replacement cycles among charter operators.
Germany
The EU's F-Gas Regulation accelerates compressor fleet turnover by prohibiting specific refrigerants in high-pressure breathing air systems. CE marking and MDR frameworks govern personal protective equipment sold across member states. Bavarian equipment suppliers capture displacement demand through expanded service networks.
Thailand
Operator fleet renewal from Phuket to Koh Tao generates concentrated bulk orders for entry-level gear and rental equipment pools. The Department of Tourism tightens import inspection protocols for breathing gas compressors. Koh Tao's instructor training centers drive mask and fin replacement every 18-24 months.
Italy
Vertically integrated fin production anchors European supply for blade stiffness variants optimized by finning technique. EN 250 standards for regulators establish baseline performance thresholds manufacturers must satisfy. The Italian facility serves agency-affiliated procurement across Mediterranean dive tourism markets.
Australia
Cave and wreck penetration curricula proliferate beyond traditional strongholds, creating equipment demand where rebreather adoption remains nascent. ISO 6425 standards for dive watches complement national certification requirements. Queensland's technical diving training centers drive specialized life-support system procurement.
Global Scuba Diving Equipment Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers extend brand architectures across price tiers and application segments. The vendor base organizes around three strategic archetypes: vertically integrated European specialists controlling premium life-support assemblies, North American portfolio companies aggregating multiple agency-affiliated brands, and Asian-scale manufacturers supplying rental equipment pools. M&A activity and certification-driven distribution partnerships represent the dominant competitive vectors.
Within the portfolio-company tier, Huish Outdoors LLC and Johnson Outdoors Inc. exemplify multi-brand aggregation strategies. Huish occupies a position across Atomic Aquatics and Zeagle brand holdings. Johnson Outdoors anchors North American distribution through its Scubapro brand's established dealer network. Mares S.p.A represents the vertically integrated European archetype with captive manufacturing capabilities.
| Leading Market Players |
|---|
| Huish Outdoors LLC |
| Mares S.p.A |
| Johnson Outdoors Inc. |
| Oceanic Worldwide |
| Apeks Marine Equipment Ltd. |
| Aqua Lung International |
| Cressi Sub S.p.A |
| Bauer Compressors Inc. |
| Scubapro |
| Others |
Value Chain & Pricing Dynamics
The EU's F-Gas Regulation gates qualified supply for dive tank filling compressors and premium-tier pricing access, forcing European dive centers toward certified alternative gas handling systems while Asian manufacturers capture volume tiers through lower compliance burdens.
Pricing Analysis
Aluminum and steel alloy pass-through volatility compresses margins in cylinder manufacturing while silicone rubber substitution enables material-upgrade pricing in mask and regulator components. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling. Cost compression in wetsuit manufacturing intensifies because Asian neoprene assembly erodes branded pricing power. Water sports centers in Thailand's Phuket-Koh Tao corridor exhibit highest price sensitivity, while technical divers seeking rebreather credentials show lowest sensitivity due to safety-critical specifications.
Supply Chain Analysis
Specialized technician availability constraints in Italy, Germany, and Thailand concentrate high-value life-support assembly production while limiting service network expansion. Manufacturing draws from neoprene sheet suppliers in Asia, high-pressure aluminum and steel mills in Germany and the United States, and silicone rubber compounders in Japan and South Korea. Single-source vulnerability concentrates in CO2 scrubber media and precision oxygen sensors for closed-circuit rebreathers. Distribution runs through certification agency-affiliated retail networks and independent dive shop channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as diver certification progression shifts demand toward premium life-support specifications with integrated sensor monitoring and documented service histories.
For Market Incumbents: Lock in aftermarket revenue capture by expanding certified technician training networks for closed-circuit rebreather maintenance, addressing scarcity that constrains service attachment. Deepen backward integration into silicone rubber compounding to secure mask skirt and mouthpiece supply against material substitution cycles. Defend against Asian manufacturing encroachment by emphasizing EN 250 and ISO 6425 certification tier differentiation. For New Entrants and Emerging Players: The price-point gap between premium Atomic Aquatics-tier regulators and economy rental equipment creates entry space for mid-market brands with agency partnership potential. Target Thailand's water sports center procurement for bulk entry-level gear, where Department of Tourism compressor inspection protocols favor suppliers with established compliance documentation. Pursue direct operator sales rather than retail channel dependence to bypass incumbent dealer network control. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated European specialists because fragmented certification standards across ISO 6425, EN 250, and national protocols create compliance scale advantages for consolidated players. Five-to-ten year viability hinges on rebreather technology convergence capturing technical diving growth. Monitor training agency rebreather credential standardization as inflection indicator for premium equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certification-Driven Product Bundling | Agency-standardized gear packages from Open Water through Divemaster curricula concentrate volume through authorized channels. |
| Rebreather Service Network Expansion | Specialized technician training addresses scarcity constraining aftermarket revenue capture for closed-circuit system manufacturers. |
| Silicone Rubber Backward Integration | In-house compounding secures mask skirt and mouthpiece supply against UV-resistant elastomer substitution cycles. |
| Alternative Gas Handling Technology | EU F-Gas Regulation compliance positions suppliers for European dive center compressor fleet replacement demand. |
| Thailand Compliance Service Partnership | Department of Tourism import inspection alignment creates testing and validation opportunities for breathing gas compressor providers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dive center operators, equipment manufacturers, certification agency curriculum directors, and aftermarket service technicians with secondary validation through ISO certification registries, CE marking databases, and customs import records for breathing gas compressors. Bottom-up equipment shipment data triangulated against top-down dive tourism arrival statistics and certification issuance trends.
Comparable historical periods anchored growth trajectory modeling across the projection horizon, with segmentation dimensions spanning product type, technology configuration, application depth profile, and end-user purchasing authority. CAGRs derived from equipment replacement cycle analysis, training curriculum expansion rates, and regional dive tourism infrastructure investment patterns. Forecast inputs incorporated EU F-Gas Regulation phase-out timelines and Thailand Department of Tourism inspection protocol evolution.
Caveats apply where regulatory enforcement intensity, rebreather training agency standardization delays, or commodity alloy price spikes could materially shift the outlook. Forecasts reflect assumptions about certification-driven procurement concentration and Southeast Asian tourism corridor stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Riding Multi-Purpose Lawn Mower Market
Outdoor & Sports
Global Paintball Equipment Market
Outdoor & Sports
Camping Lights and Lanterns Market
Outdoor & Sports
Skimboard Market
Outdoor & Sports
Swimming Pool Equipment Market
Outdoor & Sports
Australia Horse Riding Equipment Market
Outdoor & Sports
Above Ground Swimming Pools Market
Outdoor & Sports
Autonomous Golf Caddy Market
Outdoor & Sports
Global Canoe and Kayak Market
Outdoor & Sports
Global Slingshot Market
Outdoor & Sports
Lawn Roller Market
Outdoor & Sports
Cold Plunge Pools Market
Outdoor & Sports
Inflatable Pool Market
Outdoor & Sports
Global Sailing Dinghy Masts Market
Outdoor & Sports
Portable Kayaks Market
Outdoor & Sports
Walkbehind Lawnmower Market