
 Swimming Pool Equipment Market | 2026-2036
Swimming Pool Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Swimming Pool Equipment Market Outlook
Variable-speed pump technology is narrowing the efficiency gap between entry-level and premium equipment tiers. Pentair leverages its captive motor manufacturing to sustain margin advantages across North American distribution channels. Hayward Industries anchors its position through deep specialization in salt chlorination systems. Fluidra competes by extending its European automation expertise into connected pool management platforms.
Swimming pool equipment encompasses electromechanical systems and chemical treatment apparatus engineered to maintain water clarity, thermal comfort, and sanitary compliance in contained aquatic environments. Pumps rated between 0.5 and 3.0 horsepower circulate water through filtration media with turnover rates typically mandated at six to eight hours per pool volume. Filters, heaters, pumps, and chlorinators constitute the core product stack, with pumps representing the most mature margin pool due to regulatory minimum efficiency standards. Automated technology segments attract the fastest equipment refresh cycles as Wi-Fi-enabled chemical monitoring displaces manual testing protocols across residential and commercial installations.
EPA Energy Star specifications and DOE pump efficiency standards constrain product design parameters and disqualify single-speed models from new installations in multiple US jurisdictions. California Title 20 appliance regulations and Florida building codes collectively shape demand for variable-speed and solar thermal configurations across the largest state-level pool markets. Stakeholders must monitor state-level electrification mandates and emerging heat pump incentives to align R&D roadmaps with compliance timelines.
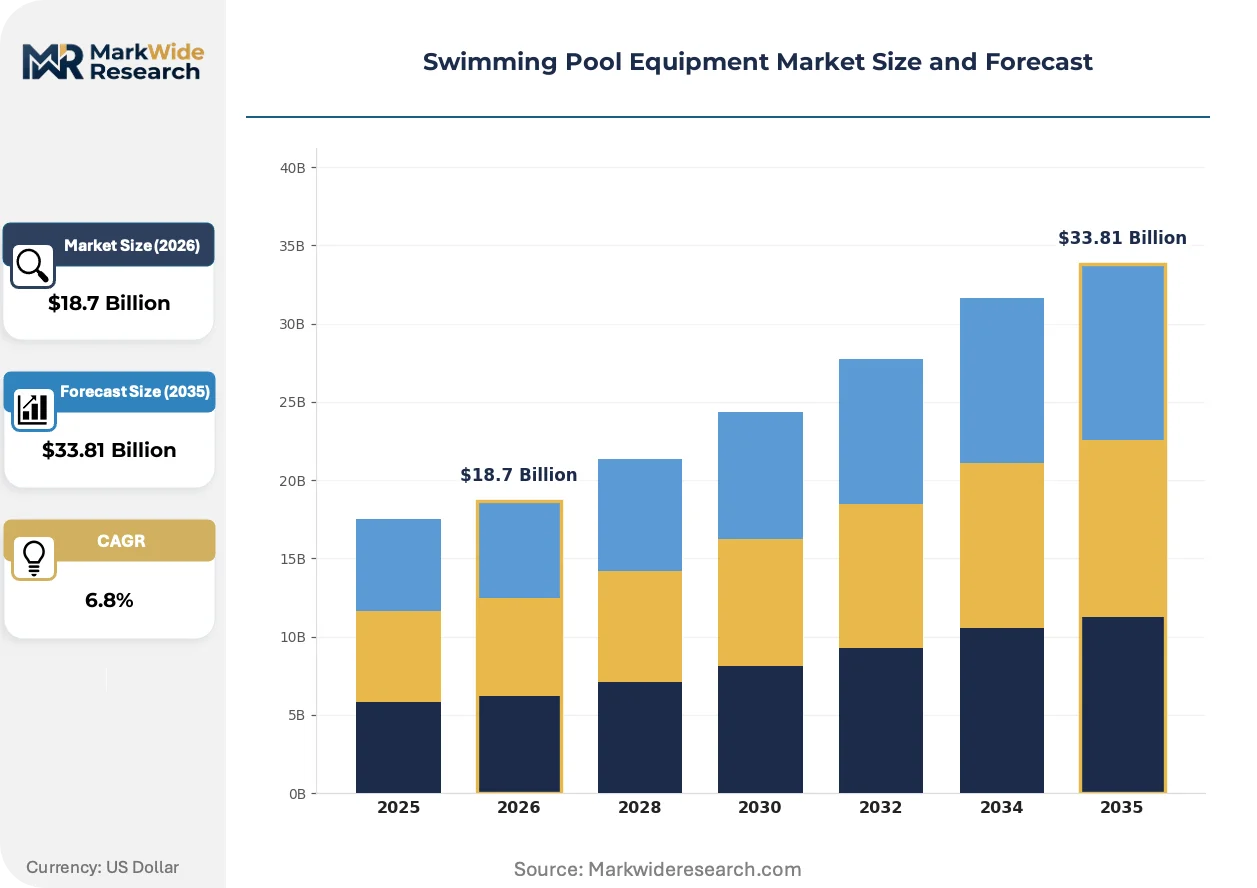
Market Dynamics
Variable-speed pump mandates are compressing the single-speed equipment base while forcing manufacturers to reconfigure motor supply chains around permanent magnet and electronically commutated architectures.
Growth Catalysts
- California Title 20 Appliance Regulations:These rules mandate minimum efficiency thresholds for pool pumps sold in the state, eliminating single-speed models from new installations and accelerating variable-speed adoption across the largest US pool market.
- Sun Belt Residential Construction:Year-round pool usage in Florida, Texas, and Arizona sustains shorter replacement cycles and consistent demand for filtration and heating equipment.
- Salt Chlorination Systems:Residential buyers increasingly specify integrated salt-to-chlorine generators as standard equipment, expanding the addressable market for automated chemical management platforms.
Market Restraints
- Copper and Rare Earth Magnet Costs:Permanent magnet motors depend on neodymium and copper windings, exposing manufacturers to commodity volatility that compresses margins on mid-tier pump lines.
- Chinese Motor Component Concentration:Stator assemblies and electronic drives concentrate among Shenzhen and Dongguan suppliers, creating vulnerability to trade policy shifts and shipping disruptions.
- Single-Speed Inventory Stranding:DOE efficiency standards effective in multiple jurisdictions render existing single-speed pump inventories non-compliant for new installations, forcing write-downs.
Strategic Opportunities
- DOE Heat Pump Incentives:Federal tax credits for energy-efficient pool heating equipment create a subsidy channel that accelerates heat pump adoption against gas-fired alternatives.
- Commercial Hospitality Retrofit:Luxury hotel and resort operators in Florida and California are upgrading legacy equipment to meet corporate sustainability targets and guest experience standards.
- Wi-Fi-Enabled Chemical Monitoring:Convergence of IoT sensors and cloud-based water quality analytics opens subscription revenue streams beyond one-time equipment sales.
Industry Challenges
- EPA Energy Star Certification Timelines:Testing and verification protocols for pump efficiency claims extend product launch schedules by six to nine months.
- Integration with Legacy Control Systems:New automation platforms must communicate with installed relay-based timers and proprietary valve actuators, complicating field deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swimming Pool Equipment Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filters, Heaters, Pumps, Chlorinators End User: Residential, Commercial, Municipal, Hotels Technology: Solar, Electric, Gas, Automated Installation Type: Above Ground, In Ground, Portable, Permanent |
| Companies Covered | Pentair, Hayward Industries, Fluidra, Zodiac Pool Solutions, Maytronics, Intex Recreation Corp, Waterco, Aqua Products, S.R. Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swimming Pool Equipment Market Strategic Shifts
Electrification mandates and connected infrastructure are rewiring competitive advantage away from mechanical reliability toward software-defined water quality management and energy optimization.
Variable-frequency drive technology is migrating from high-end commercial installations to mass-market residential pumps. Florida pool service contractors now specify VFD-equipped models as default for replacement jobs. This migration from premium to standard tier compresses price realization for incumbent manufacturers while expanding total addressable volume.
EPA Energy Star pump specifications are tightening test procedures to capture real-world energy consumption rather than laboratory conditions. Manufacturers must redesign hydraulic systems and motor controls to maintain certifications. California and Florida pool builders report specification changes within ninety days of standard updates, compressing product lifecycle planning horizons.
Commercial buyers are unbundling equipment procurement from installation and maintenance contracts. Large hospitality operators in Arizona and Texas now source pumps and heaters through direct distribution while contracting regional service firms for deployment. This pattern fragments the traditional dealer-installer channel and pressures manufacturers to support multiple fulfillment models.
Swimming Pool Equipment Market Segmentation
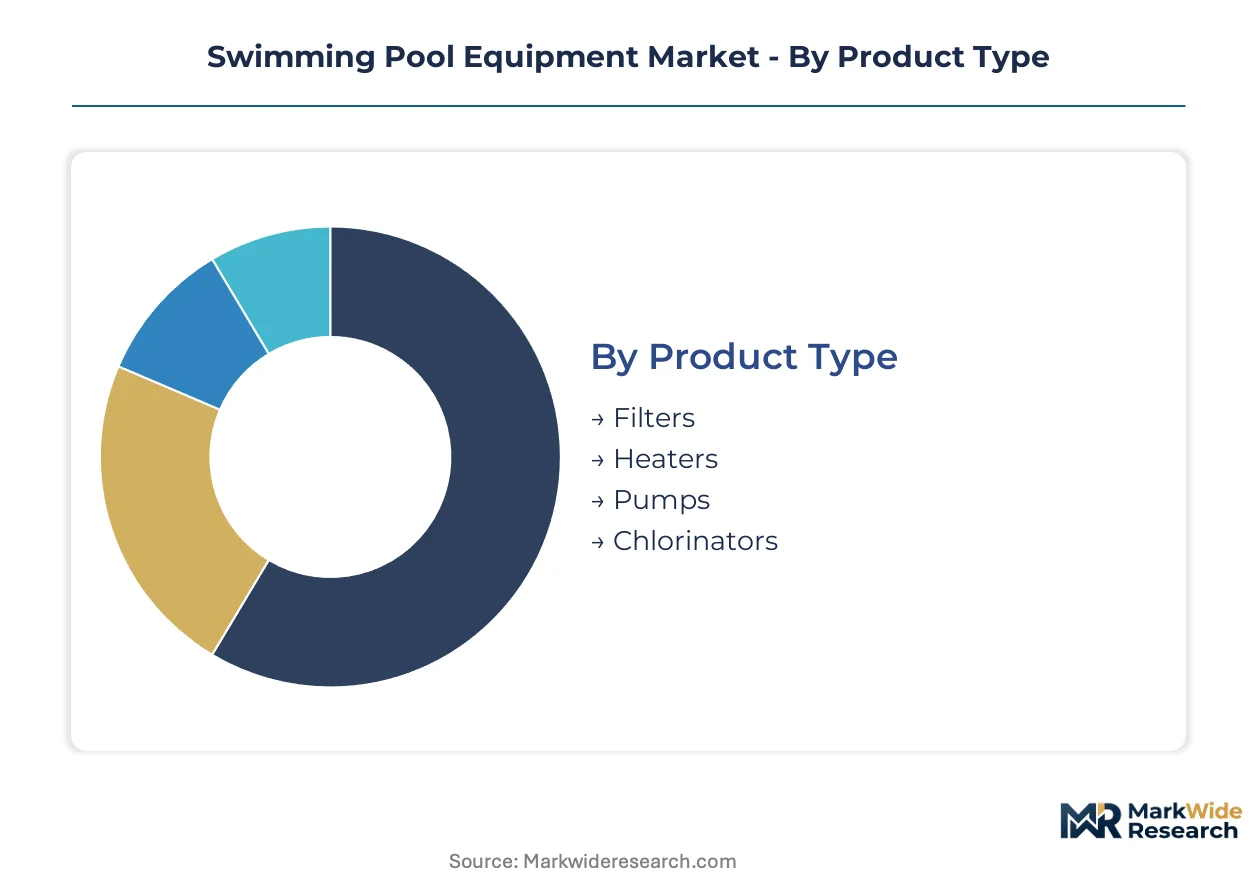
Equipment segmentation in this market tracks regulatory pressure points and replacement cycle timing. Product type determines margin structure while end-user classification shapes channel strategy and service attach rates.
Product Type:
Cost tier differentiation separates mature mechanical categories from emerging smart equipment lines with software revenue potential.
- Pumps:Variable-speed models with permanent magnet motors dominate specification sheets for California and Florida new builds. DOE efficiency standards have compressed single-speed volumes to replacement-only demand while expanding addressable market for premium electronically commutated architectures.
- Filters:Cartridge, sand, and diatomaceous earth configurations serve distinct clarity requirements across residential and commercial duty cycles. Sand filters retain share in Sun Belt service territories where contractor familiarity sustains specification inertia despite cartridge efficiency advantages.
- Heaters:Gas-fired units face electrification headwinds as heat pump incentives reshape total cost of ownership calculations for pool owners.
- Chlorinators:Salt-to-chlorine generators displace tablet feeders in residential new construction specifications.
Pumps hold installed capacity. Chlorinators are rotating up the share rankings.
End User:
Application context determines equipment durability specifications and maintenance contract structures.
- Residential:Single-family pool owners drive volume for standard-efficiency equipment with 7-10 year replacement horizons. California Title 20 compliance costs have pushed entry-level buyers toward mid-tier variable-speed pumps as base specifications.
- Commercial:Multi-tenant properties and fitness centers demand redundant filtration systems with 24-hour operational capacity. Florida apartment operators now specify automated chemical monitoring to reduce liability exposure from water quality incidents.
- Municipal:Public recreation departments face procurement constraints that favor lowest-compliant-bid awards over lifecycle cost optimization.
- Hotels:Luxury hospitality operators in Arizona and Texas unbundle equipment from installation contracts to capture sustainability reporting benefits through direct vendor relationships.
Residential holds installed capacity. Hotels are rotating up the share rankings.
Technology:
Maturity curves separate legacy combustion systems from emerging electrification and connectivity platforms.
- Automated:Wi-Fi-enabled chemical monitoring and valve actuation systems displace mechanical timers across replacement cycles. Cloud-based water quality analytics enable subscription revenue models that extend manufacturer relationships beyond point-of-sale.
- Electric:Heat pump configurations gain specification share against gas alternatives as federal tax credits improve payback periods for high-efficiency installations.
- Solar:Thermal collectors serve niche demand in Southwest markets with favorable insolation profiles and extended swim seasons.
- Gas:Combustion heaters retain position in cold-climate commercial applications where rapid temperature recovery outweighs operating cost considerations.
Gas holds installed capacity. Automated is rotating up the share rankings.
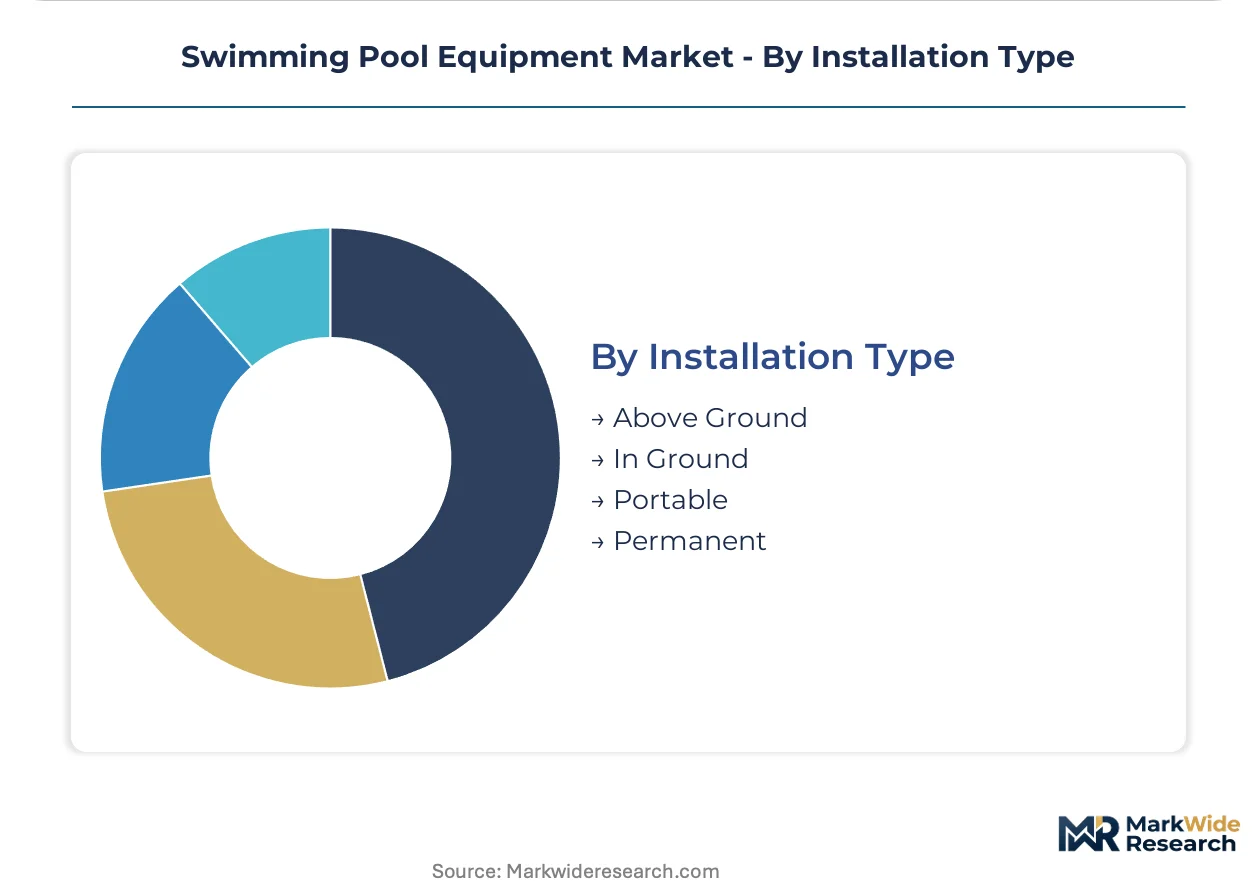
Installation Type:
Customer type and permanence expectations shape equipment durability specifications and channel economics.
- In Ground:Permanent installations support premium equipment selections with extended warranty terms and integrated automation platforms. Texas and Arizona builders report in-ground construction sustaining 15-20 year equipment depreciation schedules.
- Above Ground:Seasonal and budget-conscious buyers drive volume for simplified filtration packages with lower capital requirements. Big-box retail channels dominate above-ground equipment distribution with limited service attach.
- Portable:Temporary installations for event hospitality and rental properties create episodic demand with minimal replacement cycle value.
- Permanent:Fixed installations encompass both in-ground and hard-sided above-ground configurations requiring code-compliant electrical and plumbing infrastructure.
In Ground holds installed capacity. Above Ground is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxury hospitality operators and residential pool builders concentrate equipment procurement in Sun Belt climates where year-round usage sustains replacement demand. California and Florida regulations now dictate specification standards that manufacturers must satisfy across North American distribution channels.
United States
California Title 20 appliance regulations and Florida building codes eliminate single-speed pump installations from new construction specifications. The DOE enforces minimum efficiency standards that compress product launch timelines by six to nine months. Phoenix-Mesa-Scottsdale contractors report heat pump specifications displacing gas-fired alternatives across Arizona replacement cycles.
Australia
Queensland and New South Wales pool ownership rates sustain demand for filtration and heating equipment through extended swim seasons. The country's national energy regulator mandates efficiency labeling that shapes consumer selection criteria for variable-speed pump retrofits. Sydney-based hospitality operators unbundle equipment procurement from installation contracts to capture sustainability reporting benefits.
Spain
Costa del Sol and Balearic Islands resort operators drive commercial equipment refresh cycles through corporate sustainability mandates. The EU F-Gas Regulation constrains refrigerant selection for heat pump configurations sold across Iberian markets. Barcelona pool service contractors specify salt chlorination systems as default equipment for residential new builds.
United Arab Emirates
Dubai and Abu Dhabi luxury hotel developments specify automated chemical monitoring platforms to reduce liability exposure from water quality incidents. The country's federal energy efficiency standards shape heat pump adoption against gas-fired alternatives in commercial installations. Sharjah-based distributors report Wi-Fi-enabled valve actuation systems displacing mechanical timers across replacement cycles.
Brazil
São Paulo and Rio de Janeiro residential construction sustains demand for above-ground filtration packages with lower capital requirements. The country's national energy conservation program mandates minimum efficiency thresholds for circulating pumps sold in major metropolitan markets. Minas Gerais pool builders report cartridge filter specifications gaining share against sand configurations despite contractor familiarity advantages.
Swimming Pool Equipment Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered distribution structures. The vendor base separates into scale-driven diversified industrials, electromechanical component specialists, and automation-focused technology providers. Two strategic archetypes dominate: captive motor manufacturers leveraging backward integration advantages, and salt chlorination specialists anchoring chemical management platforms. Competitive moves concentrate on portfolio diversification toward connected pool management systems and geographic expansion through direct distribution relationships with hospitality operators.
Within the diversified industrial tier, Pentair and Hayward Industries exemplify scale-driven positioning. Pentair occupies a position as a captive motor manufacturer sustaining margin advantages across North American channels. Hayward Industries anchors specialization in salt chlorination systems. Fluidra sits within the European automation tier, extending connected pool management expertise into cloud-based water quality analytics.
| Leading Market Players |
|---|
| Pentair |
| Hayward Industries |
| Fluidra |
| Zodiac Pool Solutions |
| Maytronics |
| Intex Recreation Corp |
| Waterco |
| Aqua Products |
| S.R. Smith |
| Others |
Value Chain & Pricing Dynamics
Neodymium and copper commodity volatility determines both pricing tier spreads and supply chain shape in swimming pool equipment, compressing margins on mid-tier variable-speed pump lines while forcing manufacturers toward permanent magnet motor architectures that concentrate component sourcing in East Asian manufacturing clusters.
Pricing Analysis
Cost-plus contracts with copper and rare earth indexation dominate procurement between pump manufacturers and motor suppliers, creating automatic pass-through of commodity swings. Price differentiation rests on DOE certification tier and permanent magnet motor specification, with California Title 20 compliance commanding premium positioning. Pricing pressure stems from single-speed inventory stranding as efficiency mandates accelerate obsolescence. Residential buyers in Sun Belt states show highest price sensitivity, while hospitality operators prioritize lifecycle operating costs over upfront capital.
Supply Chain Analysis
Permanent magnet feedstock draws from Chinese rare earth processing facilities and Chilean copper smelters, creating geographic concentration risk. Stator assemblies and electronic motor drives source from Shenzhen and Dongguan manufacturing zones, with neodymium magnet supply anchored in Jiangxi province. Tariff exposure on Chinese motor components represents the primary structural vulnerability. Distribution runs through regional pool supply distributors serving contractor networks across Florida, Texas, Arizona, and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The swimming pool equipment market sits in a cyclical recovery phase driven by Sun Belt residential construction momentum and hospitality sector capital expenditure rebound following pandemic-era deferred maintenance.
For Market Incumbents: Pre-empt salt chlorination platform commoditization by deepening captive motor manufacturing advantages and accelerating Wi-Fi-enabled automation integration. Secure EPA Energy Star certification pipelines ahead of test procedure tightening to maintain specification access in California and Florida. Channel control through exclusive distributor relationships remains critical as hospitality operators unbundle procurement from installation.
For New Entrants and Emerging Players: Establish a beachhead in above-ground filtration packages for Brazilian and Southeast Asian markets where capital constraints favor simplified equipment configurations. Target cartridge filter retrofits in sand-dominant service territories by emphasizing contractor training programs and field support infrastructure. Pursue direct-to-hospitality distribution relationships in Arizona and Texas sustainability retrofit cycles.
For Investors and Strategic Acquirers: The market sits at a mid-cycle expansion phase that favors automation-focused technology providers over pure-play mechanical equipment manufacturers. Long-term viability across the next decade hinges on software-defined water quality management capabilities and recurring subscription revenue attachment. Heat pump specification share gains against gas-fired alternatives serve as the critical inflection indicator for electrification bet timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Salt Chlorination Platform Integration | Hayward Industries anchors chemical management through specialized generator architectures and residential specification capture. |
| Permanent Magnet Motor Backward Integration | Pentair sustains margin advantages through captive manufacturing of electronically commutated pump architectures. |
| Wi-Fi-Enabled Automation Launch | Fluidra extends European connected pool expertise into cloud-based water quality analytics and subscription revenue models. |
| DOE Heat Pump Incentive Positioning | Equipment manufacturers aligning with federal tax credits capture specification share against gas-fired heating alternatives. |
| Direct Hospitality Distribution Expansion | Luxury hotel operators in Florida and California unbundle procurement to capture sustainability reporting through vendor relationships. |
Study Parameters
Initial hypotheses were tested against primary input from pool equipment manufacturing executives, regional distributor principals, Florida and Arizona pool service contractors, and hospitality facilities engineering directors, then refined through secondary validation against EPA Energy Star certification databases, DOE appliance efficiency filings, California Title 20 regulatory texts, and Florida building code amendments. Bottom-up equipment unit demand estimates triangulated against top-down construction spending and replacement cycle analysis.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by pump, filter, heater, and chlorinator categories; technology tiering across automated, electric, solar, and gas configurations; and end-user classification separating residential, commercial, municipal, and hospitality demand pools. CAGRs derived from regression analysis of historical equipment shipments against housing starts and regulatory compliance timelines, with heat pump incentive elasticity and variable-speed pump mandate penetration serving as key industry-specific forecast inputs.
Stress conditions across copper and neodymium price bands, tariff rate scenarios, and California regulatory acceleration timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Sun Belt construction momentum and hospitality capital expenditure recovery. Cross-checking against AIA architectural billings indices and STR hospitality pipeline data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Australia Kids Scooter Market
Outdoor & Sports
Portable Kayaks Market
Outdoor & Sports
Paintball Field Service Market
Outdoor & Sports
Fishing Tackle Box Market
Outdoor & Sports
Camping Cookware Market
Outdoor & Sports
Above Ground Swimming Pools Market
Outdoor & Sports
Lawn Roller Market
Outdoor & Sports
Fishing Line Market
Outdoor & Sports
Sleeper Pads Market
Outdoor & Sports
Swimming Pool and Spa Market
Outdoor & Sports
Camping Lights and Lanterns Market
Outdoor & Sports
Golf Stand Bag Market
Outdoor & Sports
Riding Multi-Purpose Lawn Mower Market
Outdoor & Sports
Europe Swimming Pools and Spas Market
Outdoor & Sports
Artificial Turf Market
Outdoor & Sports
Freshwater Fishing Rod Market