
 Floor Displays Market | 2026-2036
Floor Displays Market Size, Share, and Industry Trends Forecast 2026-2036
Floor Displays Market Foresight
Aftermarket content management and remote monitoring services are reshaping margin pools in the floor displays industry. Smurfit Kappa Group Plc leverages its corrugated structural expertise to anchor permanent display programs for grocery and club retailers. DS Smith Plc sustains competitive positioning through circular design protocols that reduce material waste in temporary promotional units. WestRock Company dominates the North American landscape with integrated display-to-shelf fulfillment capabilities.
Floor displays are self-supporting visual merchandising structures, typically fabricated from corrugated fiberboard, rigid plastics, or metal framing, engineered to withstand foot traffic while presenting products at or near ground level in retail environments. LED Screens command the largest product type position due to brightness requirements in high-ambient-light settings, while Interactive Kiosks represent the fastest-expanding application segment as retailers deploy touch-enabled wayfinding and self-service interfaces. Free-Standing installations retain the dominant share by installation type, though Mobile Units are gaining traction in event promotions and pop-up retail formats where reconfiguration speed matters.
The EPA regulates volatile organic compound emissions in display coatings and adhesives under stationary source rules, while the EU REACH framework restricts hazardous substances in imported display substrates, compelling manufacturers to certify supply chains for European market access. Retailers must monitor evolving state-level extended producer responsibility laws in California and New York that will govern end-of-life recovery obligations for temporary displays.
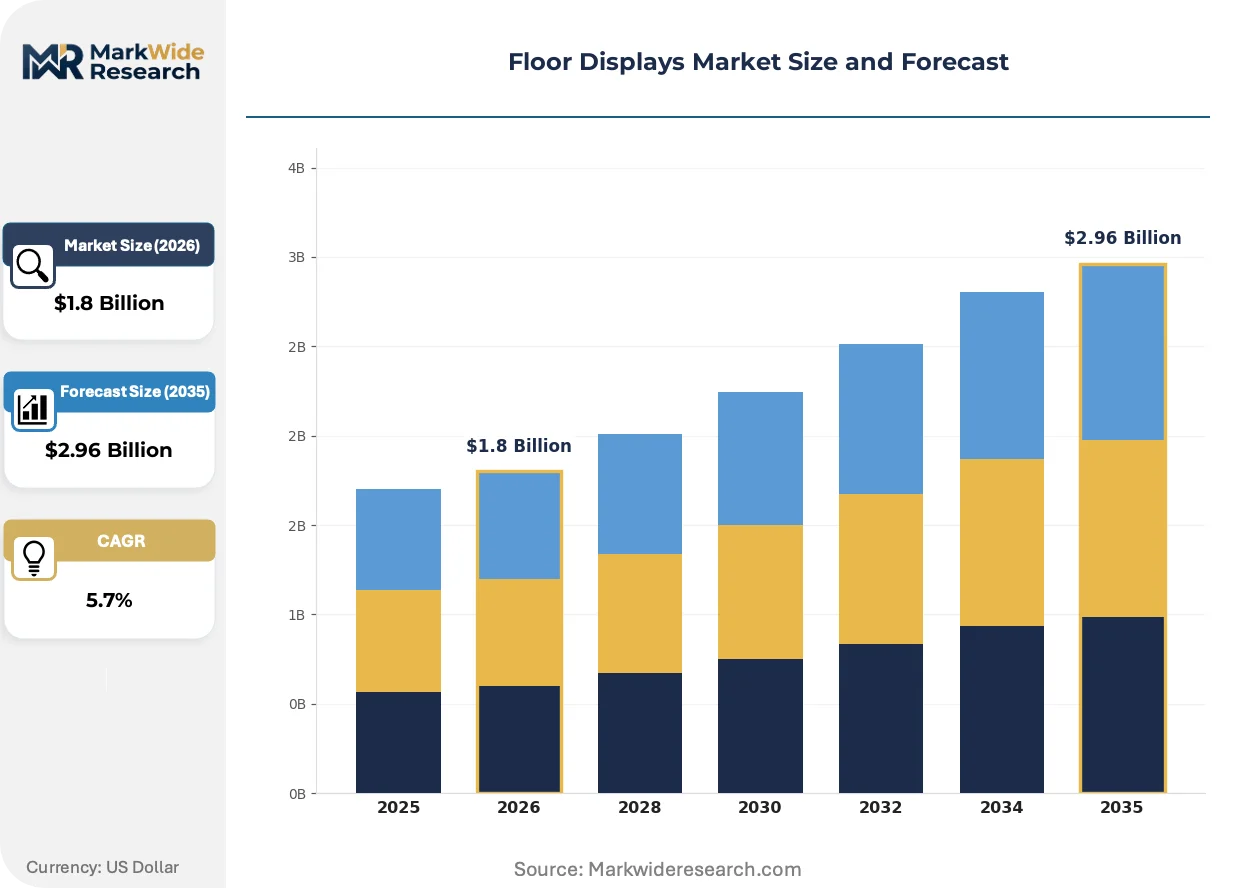
Market Dynamics
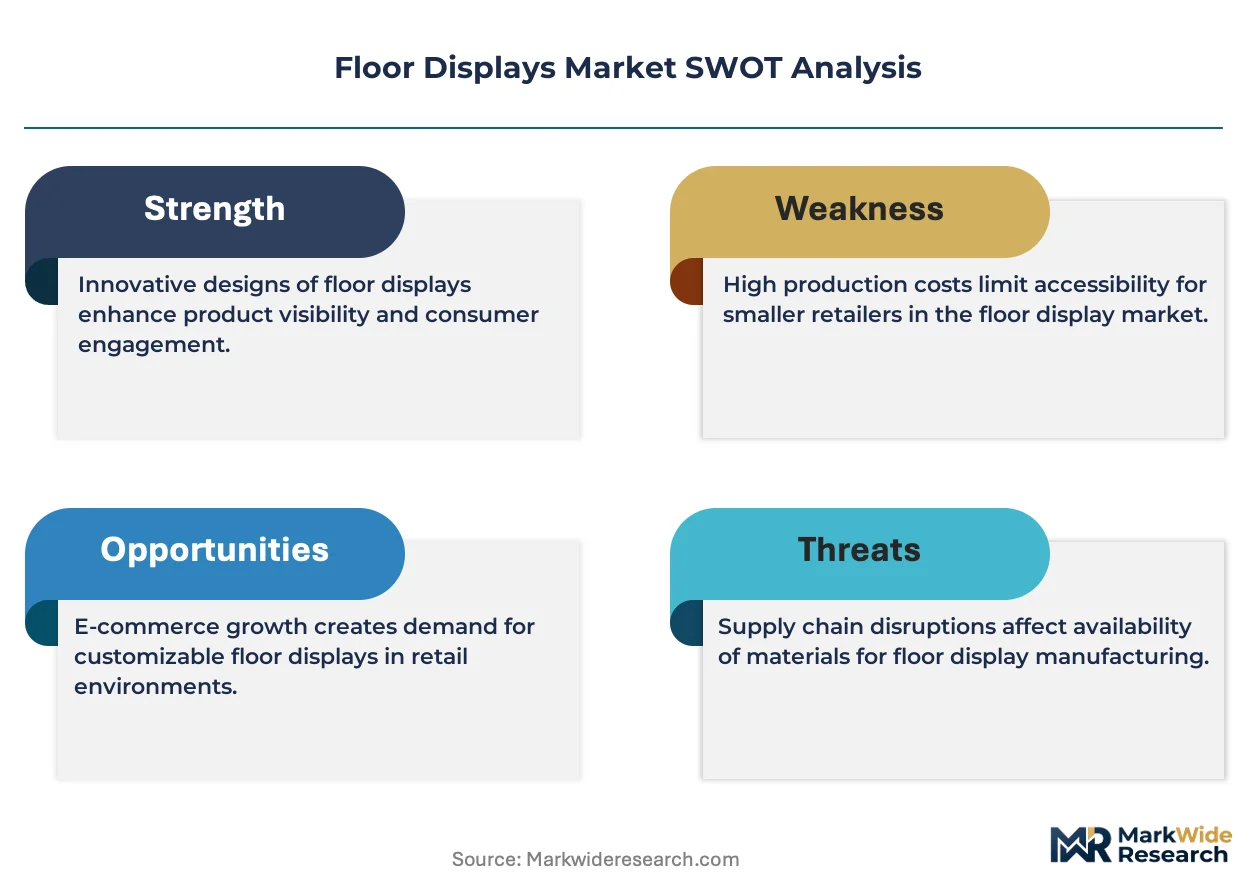
The EU Green Deal is forcing corrugated and rigid plastic display manufacturers to requalify substrate chemistries and coating formulations ahead of tightening material compliance deadlines. Retail chains now require supply-chain documentation for every structural component entering European distribution centers.
Growth Catalysts
- Experiential marketing budgets:Big-box retailers in the United States are expanding floor display deployments to elevate in-store engagement and combat showrooming behavior. These programs prioritize high-visibility LED-integrated units.
- REACH framework expansion:The EU REACH framework restricts hazardous substances in imported display substrates, compelling manufacturers to certify supply chains for European market access and creating premium positioning for compliant producers.
- Touch-enabled interfaces:Interactive Kiosks represent the fastest-expanding application segment as retailers deploy self-service wayfinding and checkout systems that reduce labor costs while capturing consumer analytics.
Market Restraints
- Pulp and resin input volatility:Corrugated fiberboard and rigid plastic display producers face margin compression from fluctuating OCC (old corrugated container) pulp prices and petrochemical feedstock costs.
- Chinese substrate concentration:A significant share of coated paperboard and specialty plastics originates from concentrated manufacturing zones in East Asia, exposing supply chains to tariff and logistics disruptions.
- Digital signage substitution:Wall-mounted and ceiling-suspended LED arrays are capturing share in high-ambient-light retail environments where floor space carries premium lease costs.
Strategic Opportunities
- Mobile Unit penetration:Pop-up retail formats and event promotions in Germany and France are driving demand for reconfigurable displays with rapid deployment capabilities and tool-free assembly.
- Extended producer responsibility tailwinds:California and New York state-level EPR laws will govern end-of-life recovery obligations for temporary displays, creating first-mover advantages for closed-loop material recovery programs.
- IoT sensor convergence:Integration of foot-traffic counters and dwell-time analytics into display housings is enabling outcome-based rental pricing models for brand marketers.
Industry Challenges
- Structural engineering talent scarcity:The specialized skill set combining corrugated mechanics, load-bearing physics, and retail ergonomics is concentrated among aging specialists in legacy packaging firms.
- Multi-jurisdiction certification timelines:Displays requiring electrical integration must simultaneously satisfy FCC emissions rules in the United States, CE marking in Europe, and GB standards in China, extending product development cycles.
- Legacy ERP integration friction:Real-time inventory synchronization between display fulfillment systems and retailer POS networks demands middleware investment that mid-tier producers struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor Displays Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Screens, LCD Panels, OLED Displays, E-Ink Screens, Projection Displays Application: Point of Sale, Event Promotions, Exhibitions, Wayfinding, Interactive Kiosks End User: Retailers, Event Organizers, Hospitality Providers, Educational Institutions, Museums Installation Type: Free-Standing, Wall-Mounted, Ceiling Suspended, Mobile Units |
| Companies Covered | Sonoco Products Company, DS Smith Plc, Smurfit Kappa Group Plc, WestRock Company, International Paper Company, Menasha Packaging Company LLC, FFR Merchandising, Pratt Industries, Creative Displays Now, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor Displays Market Shifts & Advancements
NFC-enabled product authentication and edge-computing sensors are digitizing how brands track display performance and consumer interaction patterns. These embedded capabilities are shifting vendor relationships from transactional unit sales toward ongoing data-service contracts.
Printed electronics on corrugated substrates is digitizing the economics of temporary promotional displays by enabling dynamic price updates and promotional messaging without substrate replacement. Grocery and club retailers in the United States are piloting these units in high-velocity categories. The technology is compressing the traditional 12-week display refresh cycle toward continuous content adaptation.
The EPA's stationary source rules on volatile organic compound emissions in display coatings and adhesives are tightening compliance windows for domestic manufacturers. These regulations are accelerating water-based adhesive adoption and UV-cured coating migration. Corrugated converters serving California and Texas markets are investing in regenerative thermal oxidizer upgrades to maintain production permits.
Aftermarket content management and remote monitoring services are unbundling from hardware procurement, allowing brand marketers to lease display infrastructure while purchasing software subscriptions separately. This procurement model is displacing capital-intensive ownership structures among mid-market CPG firms. The shift is most visible in the United States, where experiential marketing agencies now bundle creative, hardware, and analytics as integrated service offerings.
Floor Displays Market Segmentation
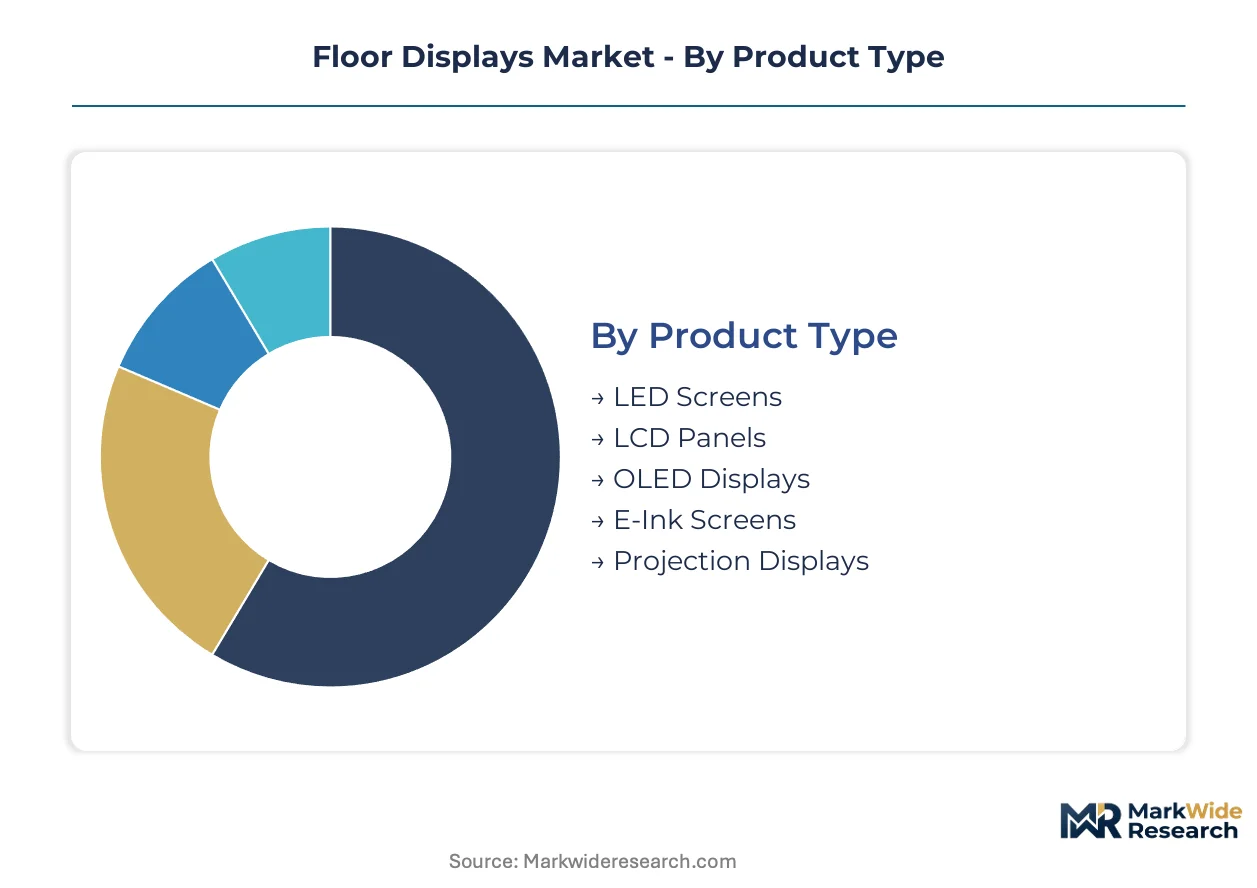
Floor displays serve heterogeneous deployment contexts ranging from permanent retail fixtures to temporary event infrastructure. Segmentation reveals divergent margin profiles, with hardware-intensive categories requiring aftermarket service contracts while modular formats command premium rental economics.
Product Type:
After-sales service intensity varies sharply across display technologies, with LED and OLED units demanding field calibration and thermal management support while E-Ink and projection systems require minimal ongoing intervention.
- LED Screens:High-brightness diode arrays dominate high-ambient-light retail environments. Demand concentrates in United States big-box deployments where visibility requirements override energy considerations. These units generate recurring revenue through brightness degradation monitoring and module replacement programs.
- LCD Panels:Liquid crystal configurations balance cost against performance in moderate-light settings. European grocery and club retailers specify these for semi-permanent promotional programs where 24/7 operation is unnecessary.
- OLED Displays:Organic emissive technology delivers superior contrast ratios for luxury brand presentations.
- E-Ink Screens:Bistable electrophoretic surfaces enable ultra-low-power static messaging in warehouse club environments.
- Projection Displays:Short-throw laser systems suit temporary exhibition layouts requiring rapid reconfiguration.
LED Screens hold the largest share; momentum sits with Interactive Kiosks as touch-enabled interfaces expand.
Application:
Cost tier stratification separates capital-intensive permanent installations from operational-budget event deployments, with hybrid rental-purchase models emerging in the mid-tier.
- Interactive Kiosks:Touch-enabled self-service terminals integrate wayfinding, checkout, and analytics capture. United States experiential marketing budgets prioritize these units for showrooming defense and labor cost reduction. Hardware-software bundling creates sticky vendor relationships through content management subscriptions.
- Point of Sale:Transaction-adjacent displays drive impulse conversion at checkout zones. Demand clusters in United States mass merchant and drug chains where dwell-time extension justifies floor space allocation.
- Event Promotions:Temporary brand activations require rapid-deployment units with tool-free assembly.
- Exhibitions:Trade show environments specify modular systems supporting repeated teardown and reconstruction cycles.
- Wayfinding:Directional displays reduce staff intervention in large-format retail and hospitality venues.
Point of Sale retains dominant volume; Interactive Kiosks are expanding most quickly as self-service interfaces proliferate.
End User:
Customer type determines procurement rhythm, with retailers operating annual planning cycles while event organizers purchase on project timelines with compressed lead times.
- Retailers:Big-box and grocery chains deploy permanent and semi-permanent fixtures across high-velocity categories. United States retail consolidation creates volume concentration among national account buyers with standardized specification programs.
- Event Organizers:Pop-up and experiential agencies demand mobile units with rapid reconfiguration capabilities. German and French event markets specify tool-free assembly for same-day deployment requirements.
- Hospitality Providers:Hotels and resorts integrate displays into lobby and conference environments.
- Educational Institutions:Campus wayfinding and digital signage programs prioritize durability and vandal resistance.
- Museums:Cultural institutions specify conservation-grade enclosures with controlled thermal output.
Retailers command the largest share; Event Organizers are gaining share fastest as experiential marketing budgets expand.
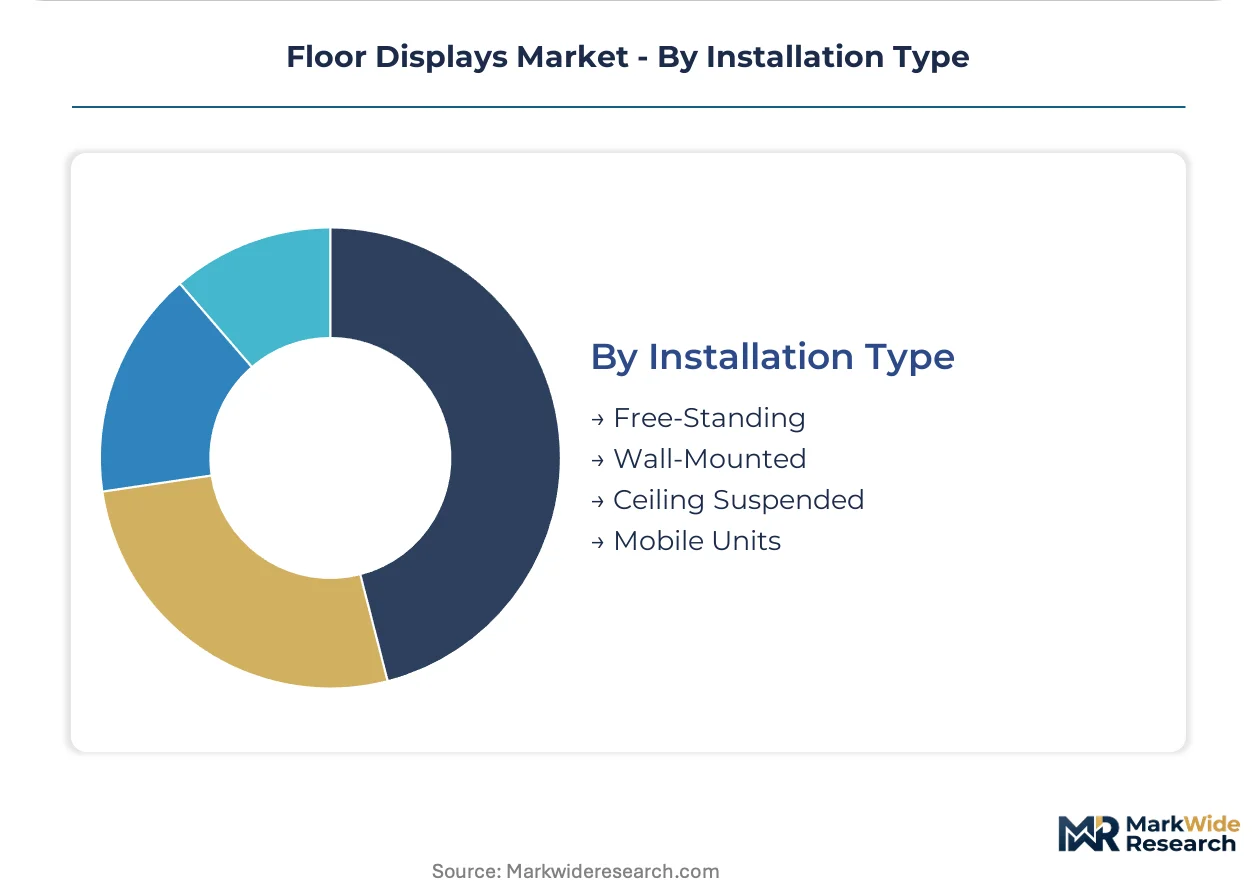
Installation Type:
Volume concentration favors permanent fixtures, though mobile formats capture premium pricing through rental economics and reduced capital burden on brand marketers.
- Free-Standing:Self-supporting structures anchor permanent retail programs without structural modification to host facilities. United States big-box retailers specify these for seasonal promotional cycles with 12-16 week deployment windows.
- Mobile Units:Castor-mounted or modular systems enable rapid repositioning across retail floors and event venues. Pop-up formats in Germany and France drive specification of tool-free assembly and compact shipping footprints.
- Wall-Mounted:Fixed vertical installations preserve floor space in high-rent urban retail environments.
- Ceiling Suspended:Overhead positioning eliminates traffic interference in dense merchandising zones.
Free-Standing installations hold the largest share; Mobile Units are climbing the fastest as temporary and pop-up formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France demonstrate low price elasticity for compliant mobile units, while United States mass merchants negotiate aggressively on corrugated permanent fixtures. Demand concentrates where experiential marketing budgets and regulatory stringency intersect.
United States
Big-box retailers in Texas and California deploy LED-integrated floor displays to combat showrooming behavior. EPA stationary source rules on volatile organic compounds in coatings and adhesives tighten compliance windows for domestic manufacturers. Chicago-area corrugated converters invest in regenerative thermal oxidizer upgrades to maintain production permits.
Germany
Pop-up retail formats in Berlin and Munich drive specification of tool-free assembly mobile units with rapid reconfiguration capabilities. EU REACH framework restrictions on hazardous substances in imported display substrates compel manufacturers to certify supply chains. Bavarian packaging clusters specialize in circular design protocols for temporary promotional units.
France
Event promotion agencies in Paris and Lyon prioritize compact shipping footprints and same-day deployment specifications. EU Green Deal material compliance deadlines force requalification of substrate chemistries and coating formulations. Rhône-Alpes industrial zones concentrate expertise in corrugated structural mechanics for grocery and club retail programs.
China
Manufacturing concentration in Yangtze River Delta and Pearl River Delta supplies coated paperboard and specialty plastics to global display producers. GB standards on electrical safety and electromagnetic compatibility govern exports of LED-integrated units. Shenzhen-based fabricators face margin pressure from tariff exposure and logistics disruptions on North American-bound shipments.
United Kingdom
London experiential marketing agencies bundle creative, hardware, and analytics as integrated service offerings. CE marking requirements for electrical integration extend product development cycles for displays with embedded sensors. Midlands packaging corridors sustain competitive positioning through circular design protocols that reduce material waste.
Floor Displays Market Competitive Landscape
Capability concentration sits with corrugated structural specialists possessing deep retail ergonomics expertise; scale advantage sits with integrated paperboard producers with captive pulp supply. The vendor base stratifies into three tiers: multinational packaging conglomerates with display-to-shelf fulfillment networks, mid-tier regional converters focused on temporary promotional units, and boutique fabricators serving experiential marketing agencies. Dominant competitive moves include backward integration into recycled pulp supply and technology licensing partnerships for printed electronics on fiberboard substrates.
Among the multinational packaging tier, Smurfit Kappa Group Plc, DS Smith Plc, and WestRock Company occupy positions that exemplify divergent strategic archetypes. Smurfit Kappa represents the corrugated structural specialist model leveraging permanent display program expertise. DS Smith exemplifies circular design protocol leadership for temporary promotional applications. WestRock anchors the North American scale position through integrated fulfillment capabilities. These three entities collectively illustrate how geographic footprint and substrate specialization determine competitive positioning in fragmented retail display procurement.
| Leading Market Players |
|---|
| Sonoco Products Company |
| DS Smith Plc |
| Smurfit Kappa Group Plc |
| WestRock Company |
| International Paper Company |
| Menasha Packaging Company LLC |
| FFR Merchandising |
| Pratt Industries |
| Creative Displays Now |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese coated paperboard manufacturing is compressing export pricing while simultaneously eroding margin buffers for European and North American converters serving retail display procurement. This utilization imbalance forces suppliers into longer payment terms and speculative inventory positions to maintain volume commitments.
Pricing Analysis
After-sales service revenue from brightness monitoring, module replacement, and content management subscriptions drives lifetime value in LED-integrated floor displays. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked European-compliant units from basic FCC-certified configurations and uncertified economy imports. Cost compression in corrugated fiberboard displays is intensifying because OCC pulp price volatility and regenerative thermal oxidizer compliance investments are squeezing converter margins. United States mass merchants exhibit highest price sensitivity through centralized national account procurement, while German pop-up retail agencies demonstrate low elasticity for rapid-deployment mobile units with tool-free assembly.
Supply Chain Analysis
Export-control restrictions on semiconductor manufacturing equipment are tightening scrutiny of LED driver component flows from Chinese fabricators to global display assemblers. Manufacturing gravity centers on the Yangtze River Delta and Pearl River Delta for coated paperboard and specialty plastics, with Bavarian packaging clusters and Chicago-area corrugated converters anchoring regional fulfillment. Raw material dependencies include OCC pulp, petrochemical feedstocks for rigid plastics, and rare-earth phosphors for LED modules. Single-source vulnerability concentrates in Chinese substrate supply for North American-bound shipments. Distribution runs through integrated display-to-shelf fulfillment networks serving big-box retail consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interactive kiosk proliferation and EU Green Deal material compliance deadlines are accelerating competitive disruption across traditional corrugated display economics. This technological-regulatory convergence compresses product lifecycles while elevating service-attachment requirements.
For Market Incumbents: Build captive pulp supply moats through backward integration into OCC recovery networks and regenerative thermal oxidizer capacity. Smurfit Kappa and WestRock should consolidate regional converter capacity in Texas and California to defend against Chinese substrate price volatility. DS Smith must accelerate circular design protocol certification ahead of REACH framework expansion deadlines. For New Entrants and Emerging Players: Pursue white-space penetration in mobile unit rental services for German and French event promotion agencies, where same-day deployment specifications command premium economics. Target IoT sensor integration partnerships with experiential marketing firms seeking outcome-based pricing models. Lead with hardware-software bundling to displace capital-intensive ownership structures among mid-market CPG firms. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with embedded content management subscriptions and remote monitoring service contracts. Long-term viability favors corrugated structural specialists with deep retail ergonomics expertise rather than commodity substrate producers. Monitor EPA stationary source rule enforcement intensity in California and Texas as inflection signal for domestic manufacturing cost structure shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Pulp Supply | Captive OCC sourcing insulates margins from commodity volatility in Texas and California markets. |
| Printed Electronics Technology Licensing | Corrugated substrate digitization compresses 12-week display refresh cycles toward continuous adaptation. |
| Circular Design Protocol Certification | EU Green Deal compliance creates premium positioning for temporary promotional unit producers. |
| IoT Sensor Platform Integration | Foot-traffic analytics enable outcome-based rental pricing for brand marketers. |
| Mobile Unit Rapid Deployment Capability | Tool-free assembly specifications capture German and French pop-up retail expansion. |
Research Methodology
Cross-validation between primary interviews with corrugated converters, retail procurement directors, and experiential marketing agency executives anchors the qualitative findings. Secondary validation draws from EPA stationary source rule filings, EU REACH substance restriction databases, customs trade data on coated paperboard flows, and SEC 10-K disclosures from integrated paperboard producers. Bottom-up demand modeling across LED screen, LCD panel, and interactive kiosk categories triangulates against top-down market sizing.
Calibration against historical deployment cycles in United States big-box retail and European grocery chains refines the analytical framework across the projection horizon. Segmentation dimensions include product type, application, installation format, and end-user procurement rhythm. CAGRs derive from unit shipment trajectories weighted by average selling price evolution and service-attachment rates. Forecast inputs incorporate EU Green Deal compliance cost pass-through assumptions and experiential marketing budget allocation shifts.
Sensitivities concentrate around tariff exposure on Chinese substrate imports, pulp price volatility, and EPA enforcement intensity variations. Forecasts reflect documented assumptions on retail consolidation pace and pop-up format adoption. Material shifts in REACH framework substance restrictions or extended producer responsibility law implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Furniture Rental Service Market
Retailing
Consumer Shopping Cart Market
Retailing
Asia-Pacific Duty-Free Retailing Market
Retailing
Australia Retail Bags Market
Retailing
Department Stores Market
Retailing
In Store Signage Market
Retailing
Out-Door Signage Market
Retailing
Retail Display Racks Market
Retailing
Out Store Signage Market
Retailing
Consumer Products and Retail Market
Retailing
Global Food and Non-Food Retail Market
Retailing
Philippines Retail Industry Market
Retailing
Gift Baskets Market
Retailing
United Kingdom Hardware Stores Retail Market
Retailing
Clothing Retail Market
Retailing
Retail Signage Market