
 Camping Beds and Mats Market | 2026-2036
Camping Beds and Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Camping Beds and Mats Market Analytics
Backpackers and ultralight trekkers is unwinding the historical dominance of car-camping families as the primary revenue archetype in camping beds and mats. Therm-a-Rest leverages its Seattle-based R&D campus to anchor innovation in heat-reflective baffle architectures. Coleman sustains mass-market channel control through big-box retail partnerships across North America. Klymit differentiates via body-mapping air chambers that reduce packed volume without sacrificing insulation value.
Camping beds and mats comprise portable sleep systems engineered from laminated fabrics, open-cell or closed-cell foams, and pneumatic chambers, with thermal resistance measured by R-value ratings that quantify insulation against conductive heat loss to ground surfaces. Their primary purpose is to deliver thermal protection, skeletal support, and packed-volume efficiency for users sleeping outside fixed structures. Self-inflating pads occupy the premium-mid tier where margin pools remain deepest due to polyurethane foam core complexity and brand loyalty among repeat buyers. Air mattresses lead absolute unit volume through low-cost PVC and TPU constructions targeting casual campers and festival attendees. Foldable cots remain structurally mature with slower growth but defend position in basecamp and vehicle-accessible applications where elevation from cold ground outweighs packed-weight penalties.
FDA oversight of antimicrobial fabric treatments, EPA scrutiny of PVC plasticizer formulations, and REACH chemical restrictions across Europe collectively constrain material sourcing and add compliance cost layers for manufacturers serving multiple jurisdictions. California's Proposition 65 labeling requirements and evolving state-level flame-retardant rules further fragment the regulatory map for brands distributing nationally within the United States. Stakeholders must monitor how diverging chemical standards between North America and Europe reshape supplier qualification timelines and whether recycled-content mandates in outdoor gear retail channels accelerate material substitution before compliance deadlines harden.
Market Dynamics
Weight minimization imperatives among backpackers and ultralight trekkers are compressing traditional comfort hierarchies and forcing material substitution toward TPU laminates and halogen-free foams across manufacturing footprints.
Growth Catalysts
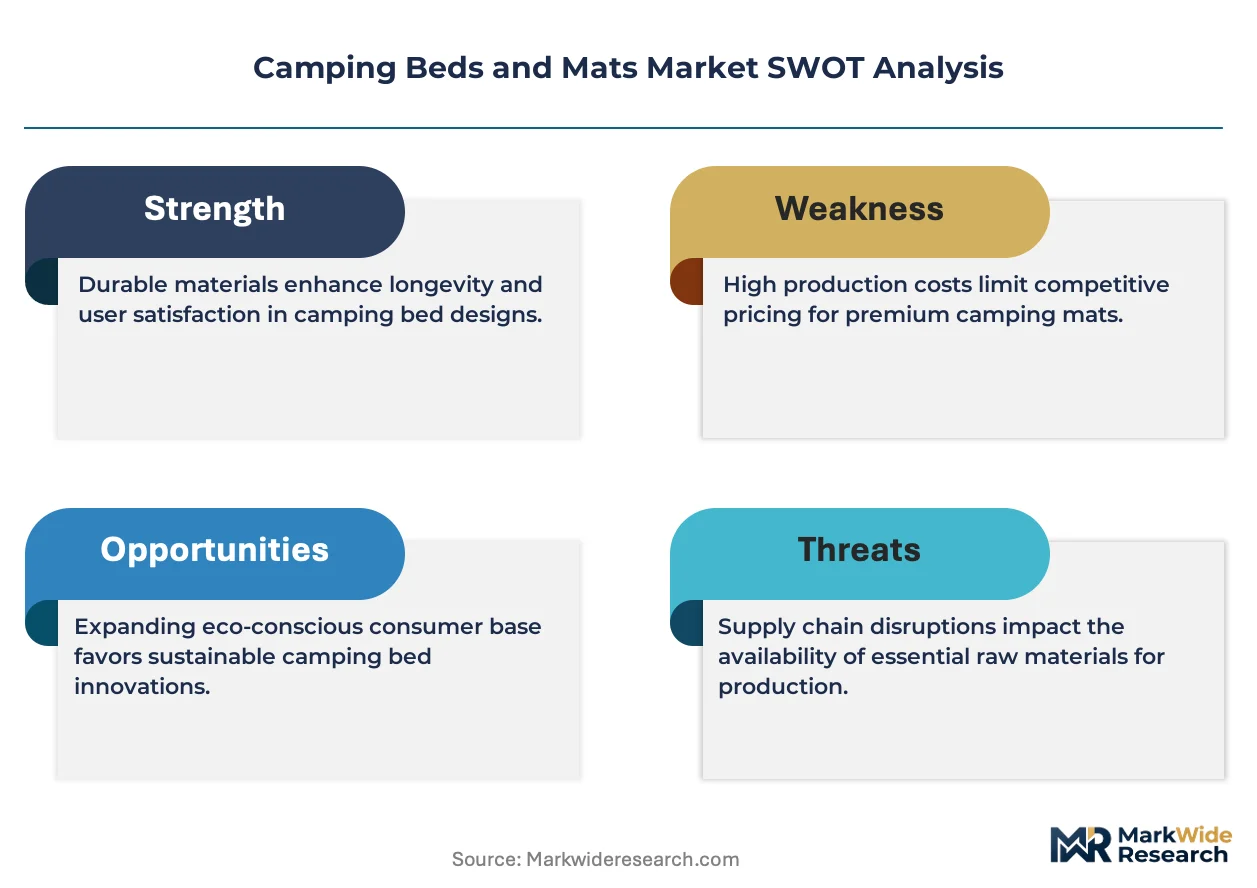
- REACH chemical restrictions:ECHA's tightening substance controls are accelerating halogen-free foam adoption among European manufacturers seeking preemptive compliance ahead of 2025 deadline clusters.
- Alpine tourism infrastructure:Germany's festival camping culture and mountain hut networks sustain premium equipment turnover through repeat replacement cycles among serious outdoor enthusiasts.
- Heat-reflective baffle architectures:Advanced metallized film layering is extending usable temperature ranges without weight penalties, attracting technical buyers in four-season segments.
Market Restraints
- Petrochemical input volatility:TPU and specialized foam feedstocks face price instability tied to crude derivative markets, compressing margin predictability for mid-tier producers.
- Supplier concentration in East Asian coating facilities:Laminated fabric production clusters in specific industrial zones create single-source vulnerability for Western brands.
- R-value measurement standardization gaps:Inconsistent thermal resistance testing protocols across jurisdictions fragment product positioning and consumer comparison.
Strategic Opportunities
- Recycled-content mandates:EU Green Deal procurement requirements for outdoor gear retail channels are opening first-mover positioning for post-consumer TPU sourcing.
- Body-mapping pneumatic chambers:Klymit-style anatomical channel designs represent white space for expansion into women's-specific and senior camper segments.
- Direct-to-consumer warranty programs:Lifetime repair services bypass traditional retail intermediaries and capture customer lifetime value in repeat outdoor buyers.
Industry Challenges
- Multijurisdictional chemical compliance:Simultaneous FDA antimicrobial oversight, EPA PVC plasticizer scrutiny, and REACH substance restrictions require dedicated regulatory affairs staffing.
- California Proposition 65 labeling complexity:State-level disclosure requirements fragment national packaging runs and demand SKU proliferation for US distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camping Beds and Mats Market |
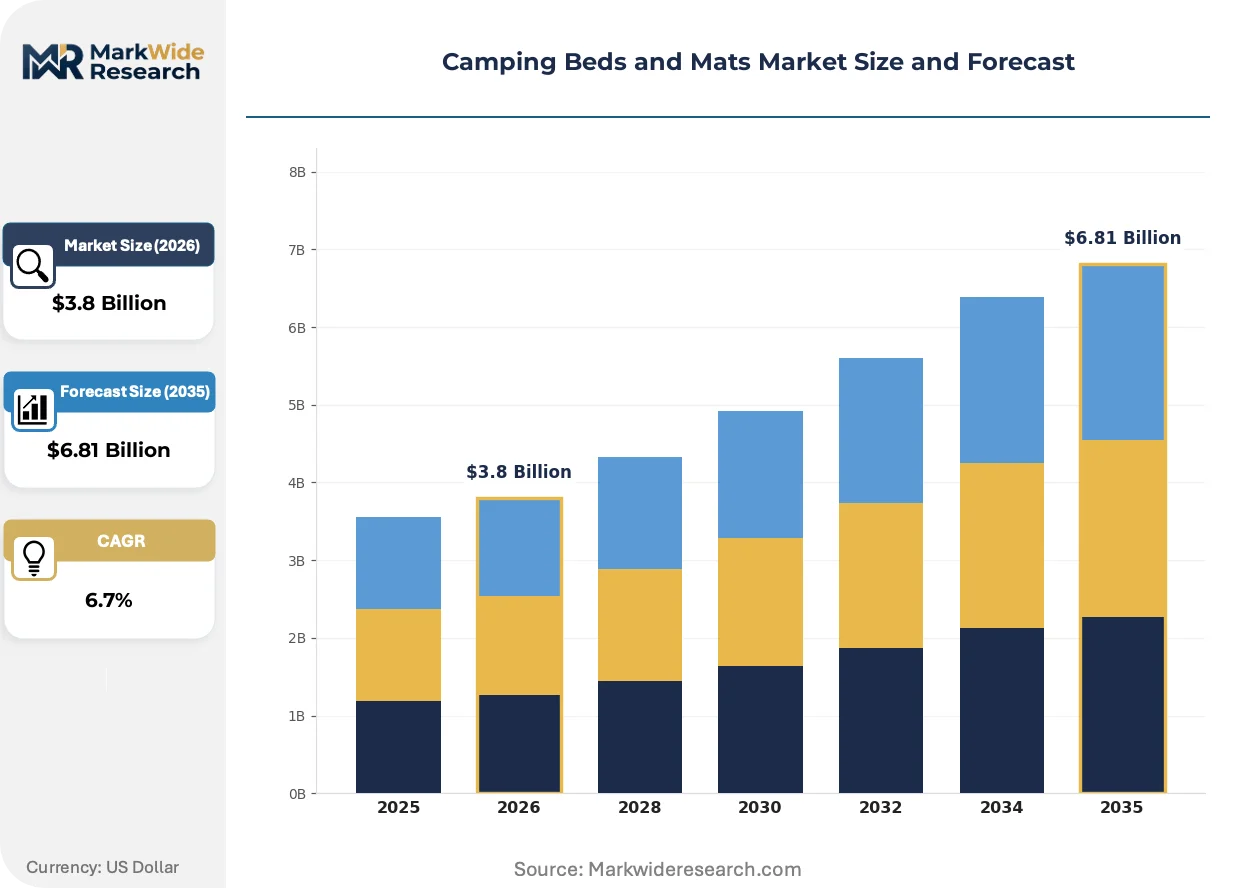
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Mattresses, Self-Inflating Pads, Foldable Cots, Foam Sleeping Pads Material: Polyester, PVC, Nylon, Cotton Size: Single, Double, Queen, Compact End User: Outdoor Enthusiasts, Campers, Backpackers, Festival Goers |
| Companies Covered | Therm-a-Rest, Coleman, Klymit, Teton Sports, ALPS Mountaineering, Cascade Designs, Vango, Big Agnes, Exped, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camping Beds and Mats Market Evolving Landscape
Material science advances and regulatory chemistry constraints are converging to redefine competitive positioning in portable sleep systems, with thermal efficiency and packed-volume metrics overtaking legacy comfort benchmarks.
Closed-cell foam cores laminated with TPU vapor barriers are supplanting open-cell polyurethane constructions in mid-premium self-inflating pads. Ultralight trekkers and thru-hikers are accelerating adoption as packed-volume thresholds compress below two-liter benchmarks. This transition is collapsing the historical premium-mid tier boundary and forcing legacy foam suppliers to retool coating lines or exit technical segments entirely.
ECHA's evolving SVHC candidate list under REACH is redirecting European sourcing away from brominated flame retardants and phthalate plasticizers. Manufacturers serving Germany, France, and Benelux markets are qualifying halogen-free alternatives eighteen to twenty-four months ahead of formal restriction dates. Self-inflating pad production lines face the steepest reformulation costs due to bonded foam-adhesive complexity.
Festival campers and casual outdoor users are consolidating purchase decisions around single-platform digital channels with embedded comparison tools. Traditional big-box retail partnerships that anchored Coleman-style mass-market distribution are losing traffic to specialized outdoor e-commerce with virtual R-value calculators. Germany's outdoor retail landscape exhibits this channel compression most visibly, where alpine-focused digital natives capture share from heritage sporting goods chains.
Camping Beds and Mats Market Segmentation
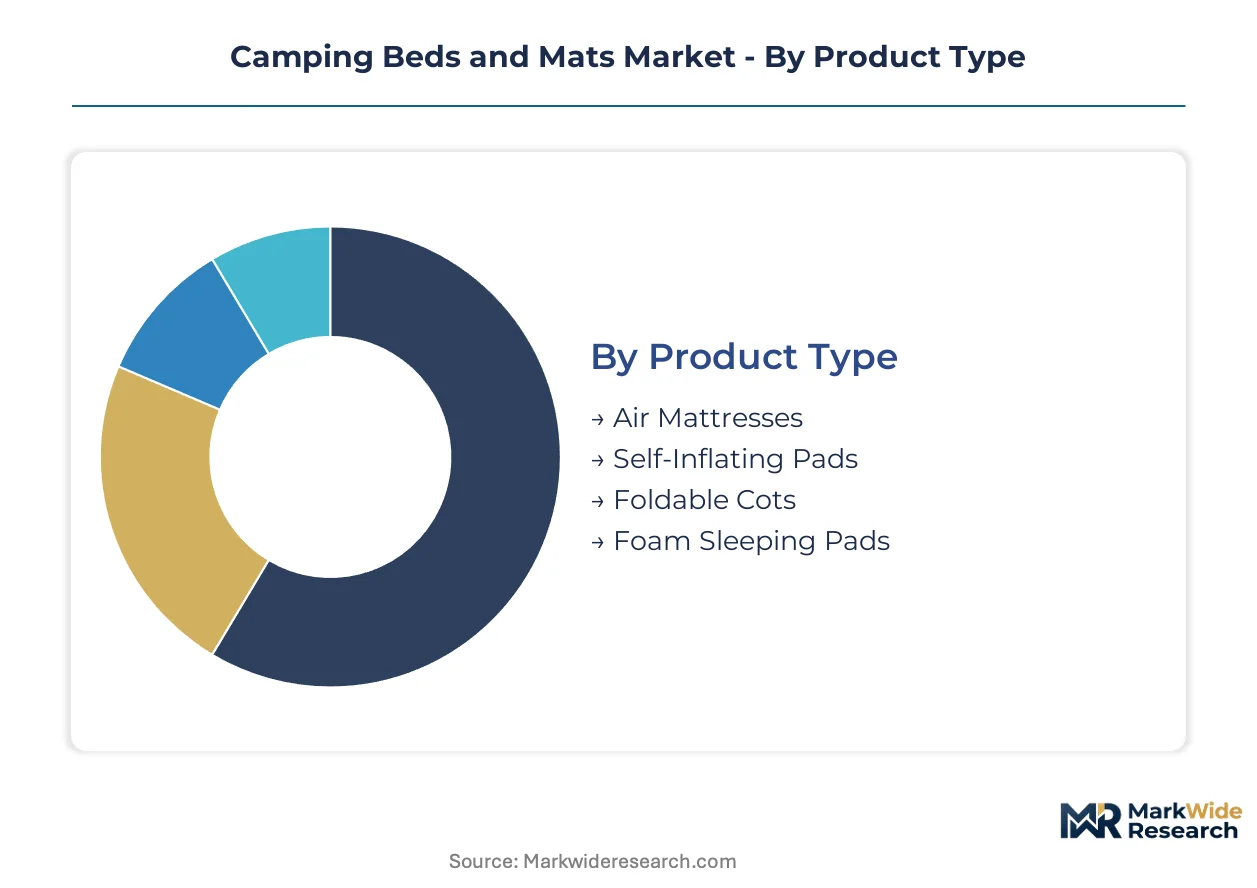
Segmentation in camping beds and mats reflects divergent thermal performance requirements, packed-volume constraints, and regulatory compliance burdens across use cases. Manufacturers configure production lines around material certification tiers rather than universal specifications.
Product Type:
REACH substance restrictions and California Proposition 65 labeling rules fragment compliance pathways, forcing distinct manufacturing footprints for European and North American product variants.
- Air Mattresses:TPU-laminated pneumatic chambers with welded seams deliver packed volumes below three liters for casual campers and festival attendees. Demand concentrates in Germany's outdoor retail channels where alpine tourism infrastructure sustains premium turnover through repeat replacement cycles.
- Self-Inflating Pads:Open-cell polyurethane foam cores bonded to vapor-barrier fabrics create the deepest margin pools through technical complexity and brand loyalty among repeat buyers. Backpackers and ultralight trekkers compress traditional comfort hierarchies here, forcing heat-reflective baffle architectures into mid-premium positioning.
- Foldable Cots:Aluminum or steel frame structures with tensioned fabric decks elevate sleepers from cold ground in basecamp applications.
- Foam Sleeping Pads:Closed-cell EVA or polyethylene constructions target ultralight purists accepting minimal insulation for sub-two-liter packed volumes.
Established volume favors Air Mattresses; emerging adoption favors Self-Inflating Pads.
Material:
Cost tier stratification determines coating line allocation, with premium laminates commanding dedicated production slots and commodity fabrics filling excess capacity.
- Polyester:Woven base fabrics with PU or TPU coatings dominate mid-tier self-inflating pads, balancing abrasion resistance against lamination cost.
- PVC:Phthalate-plasticized constructions face EPA scrutiny and ECHA SVHC candidate list pressure, accelerating substitution in North American and European sourcing.
- Nylon:High-tenacity ripstop weaves with silicone or hybrid coatings anchor ultralight segments where tear strength-to-weight ratios dictate specification.
- Cotton:Natural fiber decks persist in foldable cots for vehicle-accessible camping where moisture absorption penalties matter less than tactile comfort.
Margin concentration sits with Nylon; volume scale sits with Polyester.
Size:
Application context drives dimensional specification, with solo wilderness travel demanding minimal footprints and vehicle-based camping permitting expansive sleep surfaces.
- Single:20-25 inch widths target backpackers and ultralight trekkers where every gram displaces food or safety equipment.
- Double:40-50 inch widths serve couples in car-camping and festival contexts where shared warmth offsets individual insulation requirements.
- Queen:60-inch widths dominate air mattress segments for basecamp luxury and glamping infrastructure.
- Compact:Torso-length or three-quarter designs for thru-hikers accepting leg dangle in exchange for sub-pound base weights.
Unit economics favor Single; average selling price expansion favors Queen.
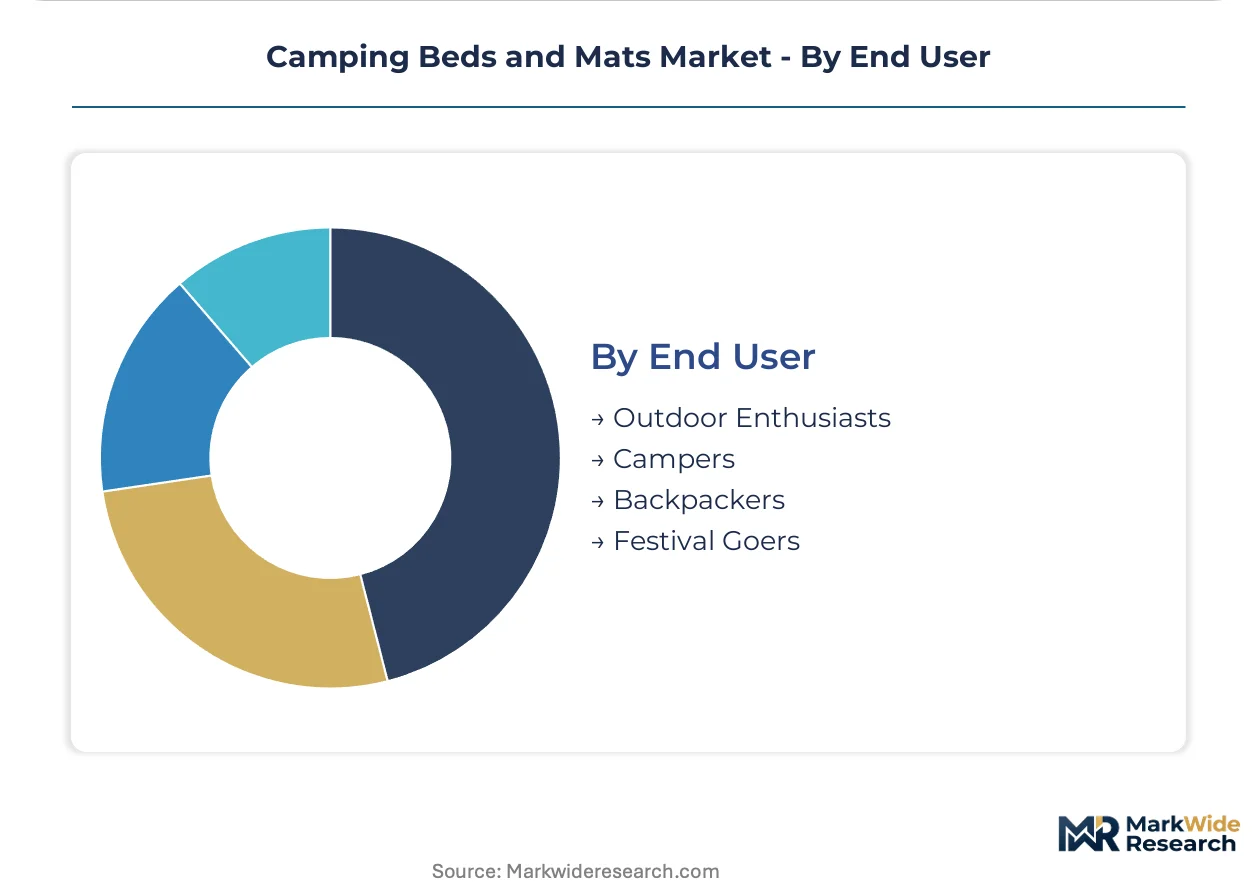
End User:
Customer type determines channel strategy and warranty positioning, with technical buyers seeking direct-to-consumer repair services and casual users defaulting to big-box retail.
- Outdoor Enthusiasts:Repeat buyers with high equipment turnover and strong brand loyalty, concentrated in Germany's alpine regions and Pacific Northwest trail networks.
- Campers:Vehicle-accessible recreationists prioritizing comfort over packed weight, sustaining foldable cot and queen-size air mattress demand.
- Backpackers:Weight minimization imperatives compress R-value thresholds and force material substitution toward TPU laminates and halogen-free foams.
- Festival Goers:Price-sensitive occasional users driving air mattress volume through seasonal purchase spikes and low replacement-cycle expectations.
Lifetime value concentration sits with Outdoor Enthusiasts; absolute unit volume sits with Festival Goers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput connects German outdoor manufacturers to East Asian coating facilities, anchoring Europe's premium camping equipment distribution. Alpine tourism corridors in Bavaria and Baden-Württemberg sustain replacement-cycle demand for technical sleep systems.
Germany
Festival camping culture and mountain hut networks drive premium equipment turnover in Bavaria and North Rhine-Westphalia. ECHA's REACH SVHC candidate list pressures manufacturers to qualify halogen-free foam alternatives eighteen months ahead of formal deadlines. Munich and Stuttgart host R&D clusters where heat-reflective baffle architectures undergo field testing.
United States
Pacific Northwest trail networks and national park infrastructure sustain high equipment turnover among repeat buyers. EPA scrutiny of PVC plasticizer formulations and California Proposition 65 labeling requirements fragment compliance pathways for national distribution. Seattle anchors thermally efficient pad innovation through concentrated outdoor industry employment.
China
Domestic outdoor recreation participation and cross-border e-commerce expansion create dual demand channels for TPU-laminated products. SAMR enforcement of GB standards for textile safety and environmental compliance redirects export-oriented production lines. Guangdong and Zhejiang industrial zones concentrate laminated fabric coating capacity for Western brand supply.
Japan
METI promotion of outdoor wellness tourism and aging-population camping participation expands addressable market beyond traditional alpine demographics. JIS standards for textile flammability and chemical content constrain material sourcing from non-certified Asian suppliers. Nagoya and Osaka manufacturing clusters specialize in precision-welded pneumatic chamber production.
United Kingdom
Post-pandemic staycation patterns and festival circuit expansion sustain air mattress volume through seasonal purchase spikes. Divergence from EU REACH alignment creates parallel compliance obligations for brands serving continental and domestic markets. Manchester and Sheffield distribution hubs manage cross-channel logistics for European outdoor retail partnerships.
Camping Beds and Mats Market Competitive Landscape
Concentration sits with heritage outdoor brands that have accumulated technical credibility through decades of alpine and backcountry field validation. The vendor base spans three structural tiers: Seattle-centered R&D specialists, Midwest-rooted mass-market distributors, and European alpine-equipment houses. Competitive maneuvering centers on direct-to-consumer warranty programs that capture lifetime customer value, and preemptive material certification that locks in supplier relationships ahead of regulatory deadline clusters.
Within the R&D-intensive tier, Therm-a-Rest and Cascade Designs occupy positions defined by thermal engineering specialization and Pacific Northwest manufacturing heritage. Klymit represents the pneumatic-innovation archetype with body-mapping chamber architectures. Coleman anchors the mass-market vector through big-box retail channel control. European alpine specialists Exped and Vango exemplify regional premium positioning tied to mountain rescue and expedition supply relationships.
| Leading Market Players |
|---|
| Therm-a-Rest |
| Coleman |
| Klymit |
| Teton Sports |
| ALPS Mountaineering |
| Cascade Designs |
| Vango |
| Big Agnes |
| Exped |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day coating line lead times for TPU-laminated fabrics tether pricing power to Guangdong and Zhejiang production slots, compressing margin buffers for Western brands when festival-season demand spikes collide with fixed capacity.
Pricing Analysis
Volume-discount tiering separates expedition-grade self-inflating pads from mass-market PVC air mattresses from ultralight closed-cell foam strips. Price differentiation hinges on R-value certification tiers and brand equity accumulated through alpine field validation. Cost compression in mid-tier polyester laminates is intensifying because REACH-compliant halogen-free foam reformulation adds per-unit conversion overhead. Festival goers exhibit highest price sensitivity; four-season mountaineers accept premium positioning for proven thermal efficiency.
Supply Chain Analysis
The Port of Hamburg transit underwrites European premium equipment distribution, creating single-point vulnerability for German and Benelux outdoor retail channels. Raw material flows draw from Chinese TPU coating facilities, South Korean metallized film suppliers, and German foam chemical specialists. Tariff exposure on laminated fabric imports from East Asian industrial zones threatens margin predictability for North American brands. Distribution runs through alpine-specialist digital channels and heritage sporting goods chains in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story because REACH regulatory entrenchment locks in eighteen-to-twenty-four-month supplier qualification timelines that new entrants cannot compress.
For Market Incumbents: Fortify supplier relationships through preemptive halogen-free foam certification ahead of ECHA deadline clusters. Lock in dedicated coating line capacity at Guangdong facilities to defend against emerging direct-to-consumer entrants capturing festival-camper volume through embedded R-value comparison tools. For New Entrants and Emerging Players: Differentiate on women's-specific body-mapping architectures where Klymit-style anatomical channels remain underdeveloped. Target senior camper segments in Germany's aging outdoor participation base with elevated sleep platforms that trade packed weight for joint support. For Investors and Strategic Acquirers: Long-term, this sits as a brand-loyalty compounder play because repeat replacement cycles among alpine enthusiasts generate predictable cash flows. Watch for recycled-content mandate acceleration in EU Green Deal procurement as the signal indicating first-mover TPU sourcing advantages crystallizing.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Preemptive Certification | Eighteen-month early qualification locks in supplier relationships before halogen-free foam restrictions harden. |
| Direct-to-Consumer Warranty Programs | Lifetime repair services bypass retail intermediaries and capture customer lifetime value in repeat outdoor buyers. |
| Heat-Reflective Baffle R&D Investment | Metallized film layering extends usable temperature ranges without weight penalties in four-season segments. |
| Post-Consumer TPU Sourcing Partnership | EU Green Deal procurement requirements open first-mover positioning for recycled-content outdoor gear. |
| Women's-Specific Product Line Extension | Body-mapping pneumatic chambers represent white space expansion into underserved demographic segments. |
Research Methodology
A standing panel of outdoor equipment R&D directors, alpine guide service procurement managers, festival camping event organizers, and laminated fabric coating specialists provided ongoing calibration against secondary validation from customs trade records, ECHA SVHC candidate list updates, and outdoor retail channel sales audits. Primary fieldwork combined structured interviews with supply chain stakeholders and technical product managers with bottom-up demand modeling and top-down macroeconomic triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by product type, material certification tier, end-user archetype, and regional regulatory cluster. CAGRs were derived from modeled replacement-cycle frequencies and per-capita equipment penetration rates in alpine tourism corridors. Forecast inputs incorporated REACH compliance cost pass-through assumptions and petrochemical feedstock volatility indices.
The analysis sits within stated boundaries; outcomes outside sustained alpine tourism infrastructure investment or abrupt REACH enforcement acceleration would require recalibration. Forecasts reflect documented assumptions about replacement-cycle stability and channel migration velocity. Practitioners should keep alternative scenarios live as ECHA substance restriction timelines and EU Green Deal procurement thresholds evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Australia Kids Scooter Market
Outdoor & Sports
Paintball Field Service Market
Outdoor & Sports
Skimboard Market
Outdoor & Sports
Portable Kayaks Market
Outdoor & Sports
Cold Plunge Pools Market
Outdoor & Sports
Camping Lights and Lanterns Market
Outdoor & Sports
Garden Solar Lights Market
Outdoor & Sports
Australia Horse Riding Equipment Market
Outdoor & Sports
Golf Stand Bag Market
Outdoor & Sports
Sleeper Pads Market
Outdoor & Sports
Fishing Line Market
Outdoor & Sports
Swimming Pool Accessories Market
Outdoor & Sports
Swimming Pool Equipment Market
Outdoor & Sports
Global Baseball Gloves Market
Outdoor & Sports
Kayak Accessories Market
Outdoor & Sports
Inflatable Pool Market