
 Electronics Retailing Market | 2026-2036
Electronics Retailing Market Size, Share, and Industry Trends Forecast 2026-2036
Electronics Retailing Market Foresight
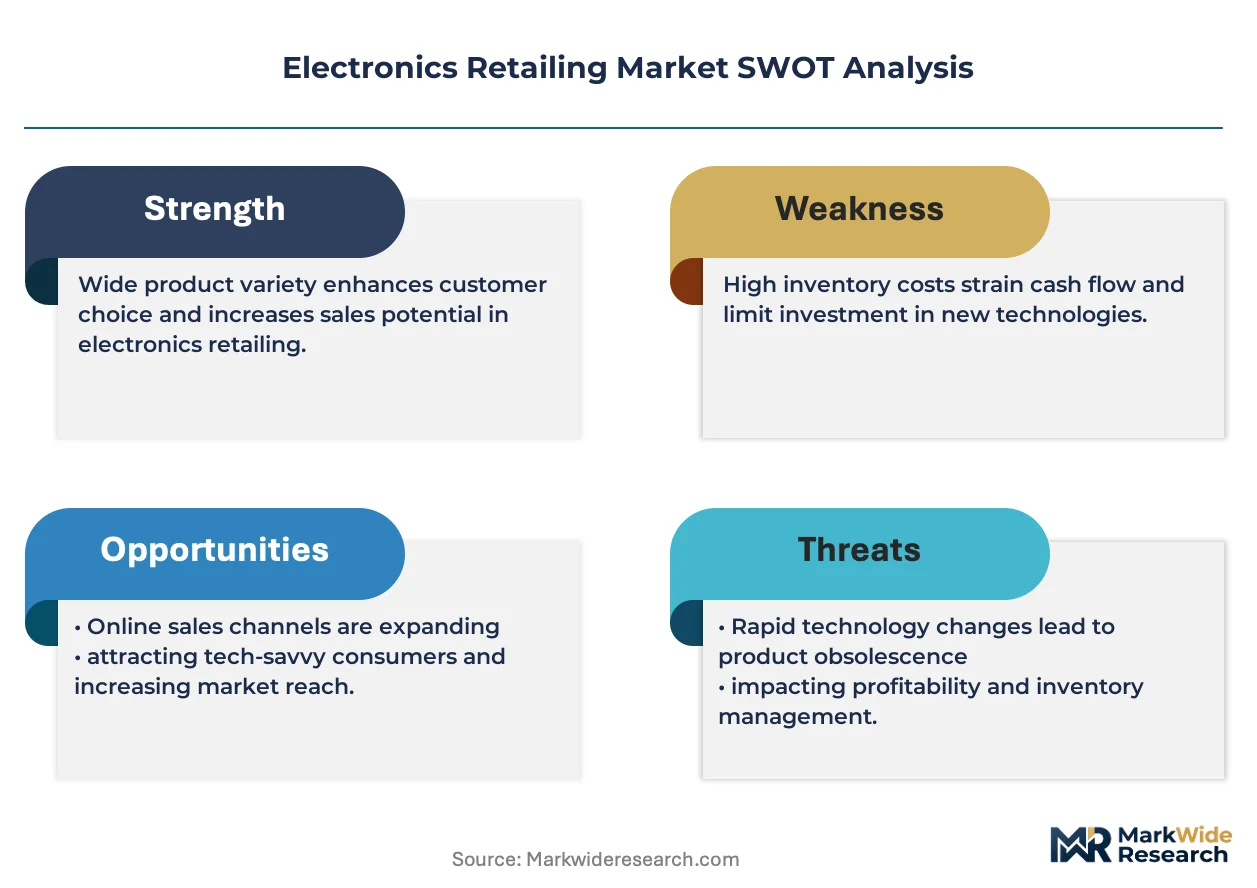
Subscription-based protection plans and software-defined warranty tiers is consolidating the traditional hardware-only transaction into recurring revenue relationships. Best Buy leverages its Geek Squad service infrastructure to anchor customer lifetime value beyond initial device sales. Amazon competes through integrated Prime benefits that extend logistics speed into electronics fulfillment. Walmart sustains price positioning across mass-market categories while navigating thinner margins on entry-level devices.
Electronics retailing encompasses the commercial distribution of consumer electronic goods through multiple touchpoints, involving inventory management of semiconductor-dependent products with specifications ranging from 5-nanometer chip architectures to OLED display panels, primarily serving end-users seeking computing, communication, and entertainment functionality. Smartphones and laptops command the largest volume pools within product type categories, though accessories generate disproportionate margin contributions through high turnover and lower fulfillment costs. Online sales channels are capturing the fastest expansion trajectory, while brick-and-mortar locations retain critical roles for high-consideration purchases where tactile evaluation influences conversion.
The US Federal Trade Commission monitors deceptive pricing and advertising practices in electronics retail, while the EU's REACH and RoHS frameworks restrict hazardous substance thresholds in imported devices, directly affecting inventory sourcing decisions for cross-border sellers. China's SAMR enforces anti-monopoly and consumer protection standards that shape platform retailer conduct in that jurisdiction. Stakeholders must weigh regulatory compliance investments against channel expansion priorities as sustainability and digital commerce mandates intensify across operating geographies.
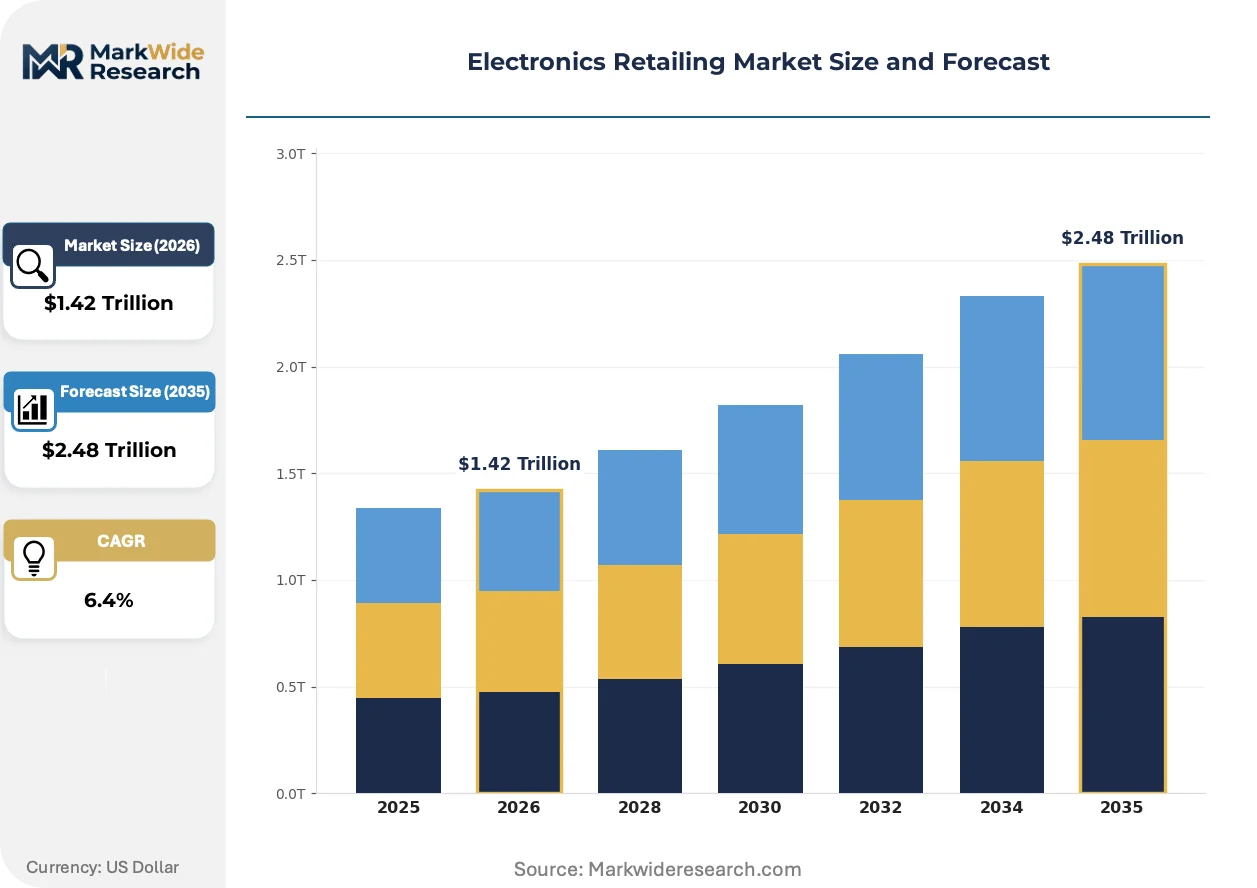
Market Dynamics
Semiconductor supply concentration in Taiwan and South Korea is forcing electronics retailers to restructure inventory models around extended lead times and dual-sourcing mandates, compressing working capital cycles while elevating the strategic value of distribution partnerships.
Growth Catalysts
- Smart home device proliferation:Residential consumers in India's tier-1 and tier-2 cities are accelerating purchases of connected appliances as disposable incomes rise and digital payment infrastructure matures.
- Ecodesign for Sustainable Products Regulation:The EU framework mandates circular economy criteria across member states, compelling retailers to source repairable and recyclable inventory that commands premium positioning.
- 5-nanometer chip architectures:Advanced semiconductor nodes enable higher-performance laptops and smartphones that drive replacement cycles among professional and gaming segments.
Market Restraints
- Neon gas supply concentration:Ukrainian and Russian suppliers historically dominated semiconductor-grade neon production, creating input volatility for chip fabrication that ripples through finished goods availability.
- REACH and RoHS compliance costs:The EU's hazardous substance thresholds require expensive testing and documentation for cross-border sellers, elevating landed costs for entry-level devices with thinner margins.
- OLED panel yield limitations:Manufacturing complexity at Gen 8.5 and Gen 10.5 substrate sizes constrains supply elasticity for premium television and monitor categories during demand spikes.
Strategic Opportunities
- Subscription protection plan expansion:Software-defined warranty tiers transform one-time transactions into recurring revenue relationships, with Geek Squad-style service infrastructure anchoring customer lifetime value.
- Prime-integrated fulfillment:Logistics speed convergence with membership benefits creates channel differentiation that mass-market retailers struggle to replicate without comparable infrastructure investment.
- Tier-2 city penetration in India:Underpenetrated urban clusters beyond Delhi, Mumbai, and Bangalore present white-space expansion as regional warehousing networks mature.
Industry Challenges
- Semiconductor procurement expertise gap:Retail buyers lack technical depth to evaluate 3-nanometer versus 5-nanometer node trade-offs, creating inventory mismatches against actual consumer performance requirements.
- Multi-jurisdiction compliance synchronization:Simultaneous adherence to US FTC pricing rules, EU Ecodesign mandates, and China's SAMR platform conduct standards fragments legal and operational resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronics Retailing Market |
| Market Size in 2026 | $1.42 Trillion |
| Market Size in 2035 | $2.48 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Laptops, Televisions, Accessories Customer Type: Individuals, Small Businesses, Corporates, Educational Institutions Sales Channel: Online, Brick-and-Mortar, Wholesale, Direct Sales Service Type: Warranty Services, Repair Services, Installation Services, Maintenance Services |
| Companies Covered | B&H Photo & Electronics, Costco, Amazon, Micro Center, Target, Best Buy, Crutchfield, Newegg, Walmart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronics Retailing Market Shifts & Advancements
Retail operations are compressing around predictive inventory systems that anticipate semiconductor availability windows, while regulatory sustainability mandates and shifting consumer financing preferences restructure how electronics move from fabrication to end-user.
Artificial intelligence-driven demand forecasting is automating purchase order generation across multi-channel inventories. Mid-sized electronics retailers in Germany and France are deploying these systems to reduce safety stock holdings by twenty to thirty percent. The technology is automating the traditional buyer role, compressing headcount in procurement functions while elevating data science staffing requirements.
REACH substance restriction expansions under the EU Green Deal are tightening hazardous material thresholds in imported devices. Cross-border sellers must now document full material disclosure for batteries, displays, and circuit boards prior to customs clearance. Small-format retailers with limited compliance infrastructure are consolidating supplier bases to reduce audit burden, favoring larger distributors with established certification pipelines.
Buy-now-pay-later financing is displacing traditional credit card penetration in electronics purchasing. Younger consumers in Brazil and Mexico are adopting installment platforms for smartphone and laptop transactions that previously required upfront payment. This behavioral shift is elevating conversion rates for higher-ASP categories while increasing retailer exposure to default risk and platform fee compression.
Electronics Retailing Market Segmentation
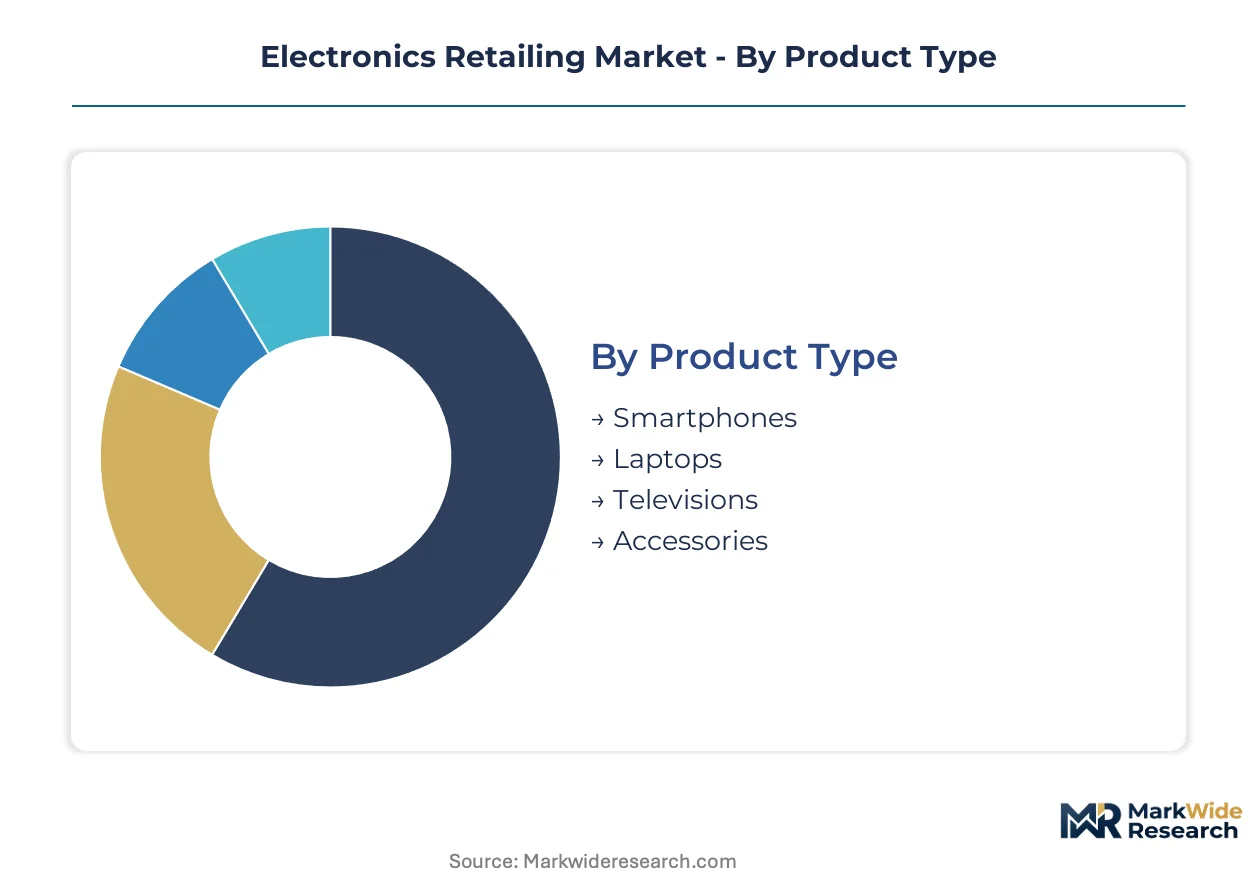
Electronics retailers structure inventory and channel investments around distinct buyer profiles and transaction patterns. Understanding how product specifications, procurement authority, and service expectations vary across segments enables margin optimization and working capital allocation.
Product Type:
Buyers in this category differentiate by replacement cycle urgency, performance sensitivity, and margin contribution potential.
- Smartphones:These devices integrate 5-nanometer and emerging 3-nanometer chip architectures with OLED or AMOLED display panels. Demand concentrates among residential consumers in India's tier-1 cities where digital payment infrastructure maturity enables frequent upgrade cycles.
- Laptops:Form factors range from ultraportables with ARM-based processors to workstation-class machines with discrete GPUs. Professional segments in Germany and France are accelerating replacement as hybrid work policies stabilize.
- Televisions:Display technology spans QLED, OLED, and Mini-LED backlighting across 55-inch to 85-inch diagonal sizes.
- Accessories:Cables, cases, chargers, and peripherals generate disproportionate margin contributions through high inventory turnover and minimal fulfillment complexity.
Volume sits with Smartphones; growth tilts toward Accessories as retailers expand private-label sourcing.
Customer Type:
Procurement scale and decision authority separate buyers, from individual discretionary spending to institutional vendor qualification requirements.
- Individuals:Single-unit purchasers with price sensitivity concentrated in entry-level and mid-tier device categories. India's tier-2 cities are emerging as volume expansion zones as disposable incomes rise.
- Small Businesses:Firms with 10-100 employees purchasing 5-50 units annually through B2B portals or contracted dealers. Brazil and Mexico show accelerating adoption of buy-now-pay-later platforms for fleet smartphone refreshes.
- Corporates:Enterprise accounts with centralized IT procurement and standardized device configurations requiring volume pricing and dedicated support tiers.
- Educational Institutions:Schools and universities procuring Chromebooks and tablets through government tender processes or direct OEM relationships.
Revenue concentrates with Corporates; expansion tilts toward Educational Institutions as government digitization programs mature.
Sales Channel:
Fulfillment speed and tactile evaluation access drive channel selection, with inventory positioning and return logistics determining retailer economics.
- Online:E-commerce platforms and direct-to-consumer websites capturing the steepest expansion trajectory through integrated logistics networks. Amazon Prime benefits in the US extend delivery speed expectations across electronics categories.
- Brick-and-Mortar:Physical storefronts retaining critical roles for high-consideration purchases where display quality assessment influences conversion. Best Buy's Geek Squad service anchors customer lifetime value beyond initial transactions.
- Wholesale:B2B distributors supplying independent retailers and regional chains with consolidated procurement and credit terms.
- Direct Sales:Manufacturer-owned stores and enterprise field sales teams targeting corporate and institutional accounts with customized configurations.
Transaction volume flows through Online; margin protection tilts toward Brick-and-Mortar for high-ASP categories.
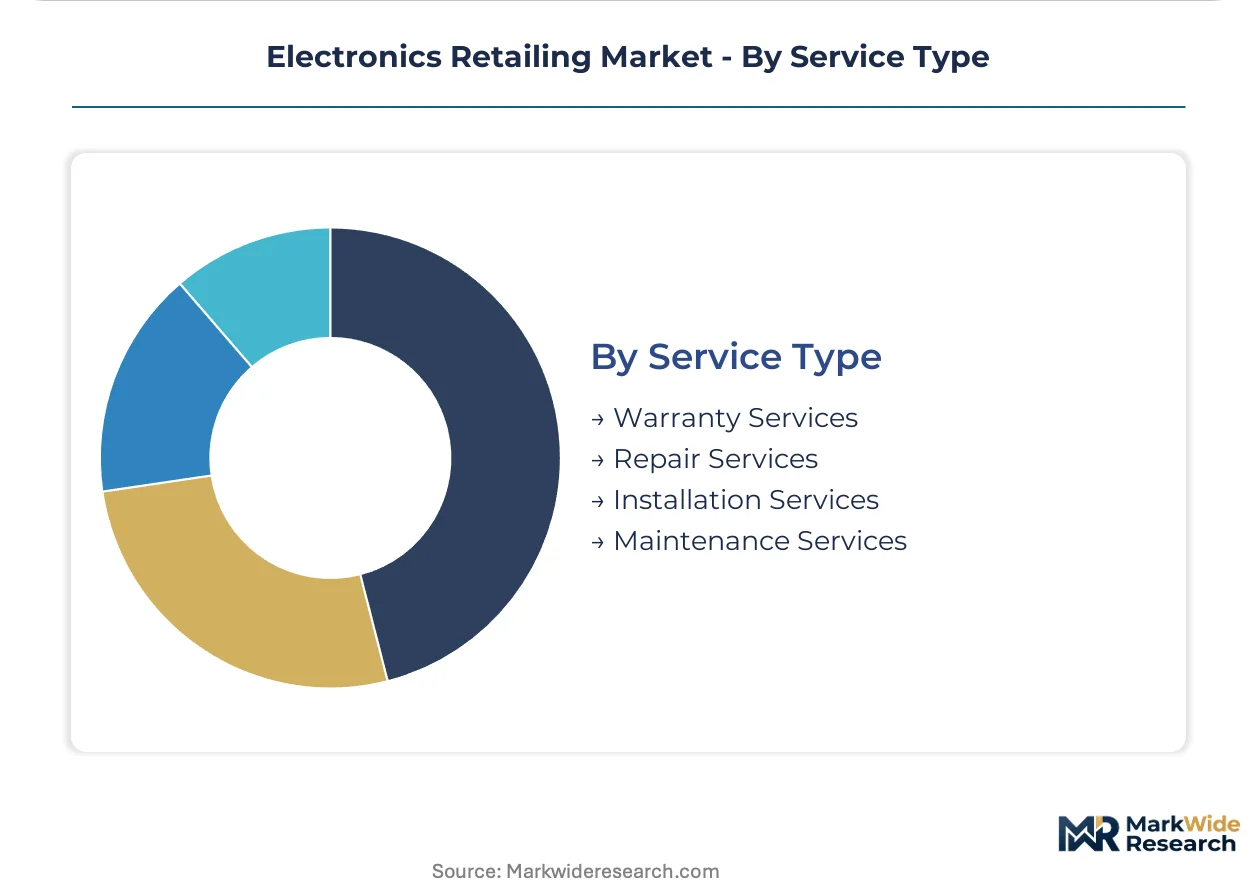
Service Type:
Post-purchase revenue attachment rates and technician utilization economics separate service offerings, transforming one-time hardware transactions into recurring relationships.
- Warranty Services:Extended protection plans and accidental damage coverage sold at point-of-sale or through subscription tiers. Software-defined warranty structures are consolidating traditional hardware-only transactions into recurring revenue models.
- Repair Services:Component-level diagnostics and replacement operations, with EU Ecodesign mandates driving demand for repairable inventory. The regulation's right-to-repair provisions are reshaping service infrastructure investments across member states.
- Installation Services:White-glove setup for home theater systems, smart home devices, and enterprise networking equipment.
- Maintenance Services:Preventive cleaning, software updates, and performance optimization for commercial and institutional device fleets.
Attachment rates are highest for Warranty Services; technician utilization growth tilts toward Repair Services as sustainability regulations expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics fabrication concentrates in East Asian semiconductor clusters while consumption tilts toward North American and European retail channels. India's domestic assembly capacity is expanding through production-linked incentives, creating a partial bridge between these poles.
United States
Enterprise refresh cycles and hybrid work device procurement drive commercial demand. The FTC monitors deceptive pricing practices across e-commerce platforms. Austin and Phoenix host expanding semiconductor fabrication facilities that will reshape regional inventory flows.
Germany
Professional laptop replacement and smart home automation adoption accelerate among residential consumers. REACH substance restrictions and Ecodesign mandates elevate compliance costs for cross-border sellers. Berlin and Munich retail clusters emphasize repairable inventory to satisfy circular economy criteria.
China
Domestic consumption of premium smartphones and OLED televisions sustains volume despite export headwinds. SAMR enforces anti-monopoly standards that constrain platform retailer conduct. Shenzhen and Shanghai maintain concentration in both manufacturing and high-velocity distribution infrastructure.
India
Tier-1 and tier-2 city consumers are accelerating electronics purchases as disposable incomes rise and UPI payment infrastructure matures. The PLI scheme subsidizes domestic assembly of smartphones and components. Bangalore and Hyderabad retail networks are expanding warehousing capacity to serve underpenetrated southern markets.
South Korea
Advanced node semiconductor production supports premium device export demand. Domestic consumers exhibit rapid replacement cycles for 5-nanometer and 3-nanometer flagship smartphones. Seoul's retail corridor integrates manufacturer flagship stores with specialized gaming and professional workstation dealers.
Electronics Retailing Market Competitive Landscape
Top-tier vendors anchor mass-market scale through integrated logistics networks, while specialized dealers occupy premium service tiers. The structure splits between platform retailers with membership-based fulfillment advantages and physical retailers with technician-staffed service infrastructure. Three archetypes dominate: omnichannel generalists, specialized electronics dealers, and membership-based warehouse clubs. Competitive moves center on protection plan subscription attachment and same-day fulfillment speed expansion.
Within the specialized dealer tier, B&H Photo & Electronics and Crutchfield exemplify consultative sales models that emphasize technical specification depth over transaction velocity. Amazon and Walmart represent scale-driven omnichannel positions where logistics integration compresses delivery windows. Best Buy occupies a bridging position between physical service infrastructure and digital fulfillment, with its technician network anchoring customer lifetime value beyond initial hardware transactions.
| Leading Market Players |
|---|
| B&H Photo & Electronics |
| Costco |
| Amazon |
| Micro Center |
| Target |
| Best Buy |
| Crutchfield |
| Newegg |
| Walmart |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap electronics retailers across Germany and France are consolidating procurement functions to absorb REACH compliance documentation costs, compressing supplier bases while elevating pricing discipline through reduced audit fragmentation. Their ownership structure enables patient capital deployment into circular-economy inventory that commands premium positioning under EU Ecodesign mandates.
Pricing Analysis
Margin tightening in entry-level smartphone tiers traces to REACH and RoHS testing overhead that elevates landed costs without commensurate price elasticity. Three-tier pricing structure across premium, standard, and economy levels separates repairable EU-compliant inventory from disposable alternatives, with brand premium and certification level as primary differentiation drivers. Cost-down pressure accelerates because India's tier-2 city consumers exhibit highest price sensitivity, while corporate fleet buyers show lowest sensitivity due to standardized procurement budgets.
Supply Chain Analysis
India's PLI scheme and domestic-content assembly mandates are reshaping sourcing patterns for smartphones and components, drawing inventory flows toward Bangalore and Hyderabad warehousing clusters. Semiconductor fabrication concentrates in Taiwan and South Korea, with OLED panel production anchored in South Korea and China. Neon gas from Ukrainian and Russian suppliers, plus advanced node wafers, remain critical dependencies. Single-source vulnerability in semiconductor-grade noble gases fragments distribution through dual-sourcing mandates and extended safety stock cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU's Ecodesign for Sustainable Products Regulation erects a cost-of-compliance moat that consolidates market share among retailers with established certification pipelines and repair service infrastructure, marginalizing small-format competitors.
For Market Incumbents: Hedge against semiconductor procurement expertise gaps by embedding technical buyers capable of evaluating 3-nanometer versus 5-nanometer node trade-offs, reducing inventory mismatches. Build backward integration into refurbishment and repair operations to capture circular-economy revenue streams as right-to-repair provisions expand across member states.
For New Entrants and Emerging Players: India's tier-2 city educational institutions represent an underserved buyer archetype with accelerating Chromebook and tablet demand through government digitization tenders. Penetrate this segment through B2B portal partnerships offering buy-now-pay-later financing options that displace traditional credit requirements for institutional procurement.
For Investors and Strategic Acquirers: Expansion of AI-driven demand forecasting deployments among mid-sized German and French retailers is the leading indicator that procurement automation is compressing headcount while elevating data science staffing requirements. Target acquisition candidates with established technician-staffed service infrastructure, as software-defined warranty tiers transform hardware transactions into recurring revenue relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Protection Plan Expansion | Geek Squad-style service infrastructure anchors customer lifetime value beyond initial device sales. |
| Prime-Integrated Fulfillment Investment | Amazon's logistics speed convergence with membership benefits creates channel differentiation mass-market retailers cannot replicate. |
| Tier-2 City Warehousing Buildout | Bangalore and Hyderabad retail networks expand capacity to serve underpenetrated southern Indian markets. |
| AI-Driven Demand Forecasting Deployment | German and French mid-sized retailers reduce safety stock holdings by automating purchase order generation. |
| Repair Service Infrastructure Scaling | EU Ecodesign right-to-repair provisions reshape technician utilization economics toward component-level diagnostics. |
Research Methodology
Multi-period observation of semiconductor lead time fluctuations, smart home device adoption curves, and regulatory enforcement patterns anchored the trend analysis, supplemented by interviews with electronics retail procurement directors, supply chain planners at B2B distributors, Geek Squad-style service operations managers, and platform marketplace sellers. Secondary validation drew from EU Ecodesign implementation guidance, REACH substance restriction updates, India's PLI scheme disbursement records, and US FTC enforcement actions. Bottom-up channel volume estimates and top-down macroeconomic indicators underwent triangulation to resolve discrepancies.
Segment-weighting approaches modeled product type stratification across smartphones, laptops, televisions, and accessories alongside customer type differentiation between individual, small business, corporate, and educational procurement patterns. Sales channel dynamics incorporated online, brick-and-mortar, wholesale, and direct sales fulfillment economics. CAGRs derived from regression analysis of historical replacement cycles, income elasticity estimates, and payment infrastructure penetration rates across India's tier-1 and tier-2 urban clusters.
Revisions become necessary when semiconductor fabrication concentration shifts, neon gas supply disruptions materialize, or EU substance restriction thresholds tighten beyond current compliance infrastructure capacity. Forecasts reflect documented assumptions regarding regulatory enforcement intensity, disposable income trajectories, and logistics network expansion timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Out-Door Signage Market
Retailing
Retail Display Racks Market
Retailing
Furniture Rental Service Market
Retailing
In Store Signage Market
Retailing
United States Hardware Stores Retail Market
Retailing
Thailand Retail Market
Retailing
Asia-Pacific Duty-Free Retailing Market
Retailing
Floor Mat Rental Service Market
Retailing
European Discount Retail Market
Retailing
Gift Baskets Market
Retailing
Subscription Box Market
Retailing
Global Food and Non-Food Retail Market
Retailing
Retail Vending Machine Market
Retailing
Australia Retail Bags Market
Retailing
Home Shopping Market
Retailing
Out Store Signage Market