
 Skimboard Market | 2026-2036
Skimboard Market Size, Share, and Industry Trends Forecast 2026-2036
Skimboard Market Analytics
Carbon fiber is repositioning product economics across the skimboard landscape as manufacturers trade weight reduction against raw material cost inflation. Exile Skimboards leverages in-house lamination expertise to sustain margin control on premium layups. Victoria Skimboards anchors its position through deep ties with California coastal retailers. Zap Skimboards competes on price-accessible polyethylene entry boards without sacrificing durability ratings.
A skimboard is a thin, hydrodynamic planing board typically measuring 30 to 60 inches in length, constructed from foam cores wrapped in fiberglass or carbon fiber composites, designed to glide across the thin wash of receding waves before intercepting deeper water for maneuvering. Its primary commercial purpose centers on coastal recreation and competitive flatland and wave riding disciplines. Fiberglass constructions occupy the volume-leading tier due to balanced cost-performance profiles across amateur and rental channels. Carbon fiber segments command premium positioning among professionals seeking stiffness-to-weight ratios that polyethylene cannot replicate. Wood variants retain niche appeal in artisanal and eco-positioned product lines where sustainability signaling drives purchase intent.
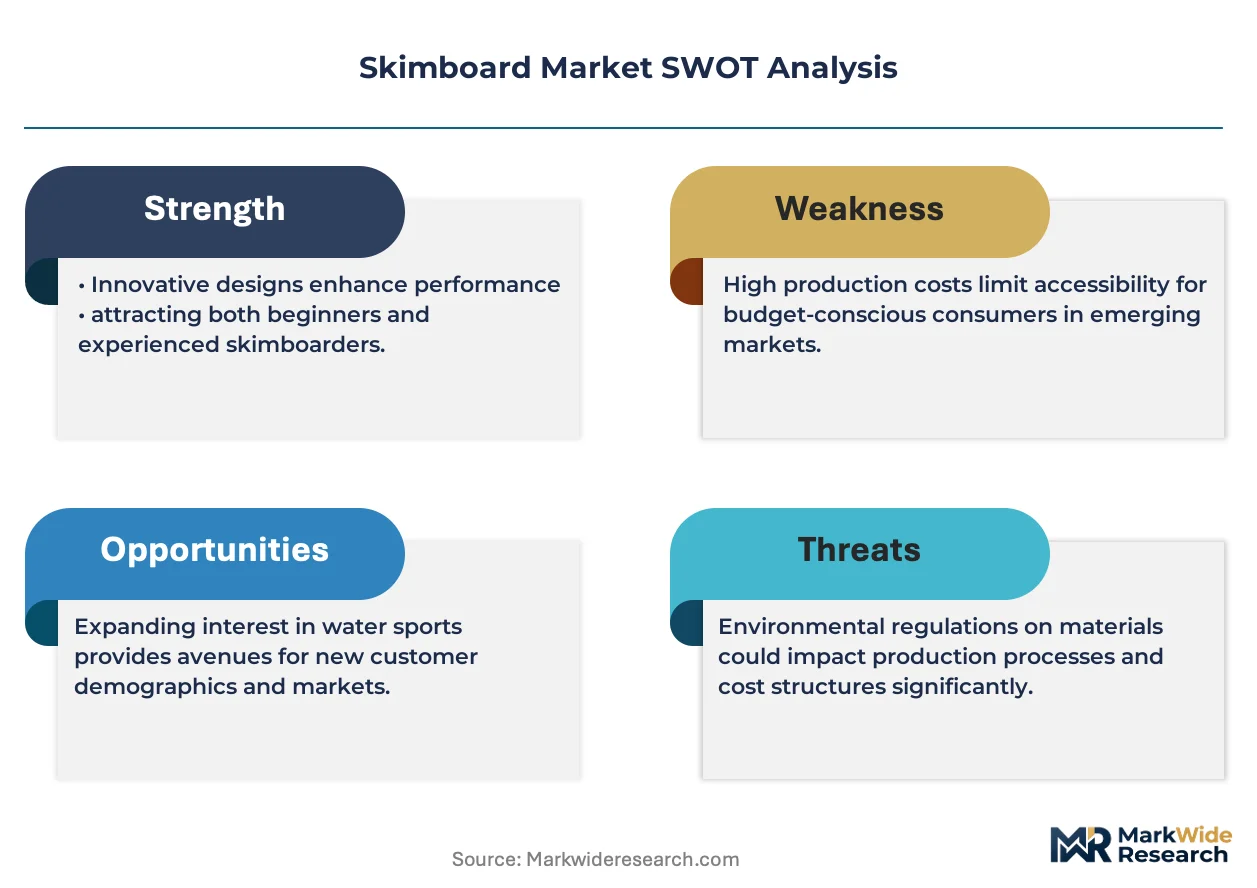
EPA emissions standards constrain fiberglass resin curing operations, pushing manufacturers toward low-VOC formulations or outsourced overseas lamination. ISO 9001 quality frameworks govern production consistency for boards entering competitive event certification pipelines. California's Proposition 65 labeling requirements add compliance layers for products sold through West Coast specialty stores. Stakeholders must weigh carbon fiber supply concentration against emerging bio-composite alternatives as they calibrate portfolio exposure across price tiers and geographic demand clusters.
Market Dynamics
Carbon fiber supply concentration in Japan and South Korea is compressing margin structures for premium skimboard manufacturers while EPA emissions enforcement reshapes domestic lamination economics.
Growth Catalysts
- REACH-compliant low-VOC resins:European manufacturers adopting water-based epoxy formulations bypass traditional solvent curing bottlenecks, expanding production capacity for fiberglass-wrapped foam cores.
- Coastal tourism board sponsorships:Florida and California municipal recreation departments allocate equipment budgets toward skimboard rental fleets, driving volume demand for durable polyethylene entry models.
- Competitive event certification pipelines:United Skim Tour and European Skimboard League mandate ISO 9001 traceability for official equipment, creating pull-through demand for certified construction tiers.
Market Restraints
- Carbon fiber feedstock concentration:Toray Industries and Mitsubishi Chemical control 70% of aerospace-grade precursor supply, exposing skimboard manufacturers to price volatility and allocation rationing.
- California Proposition 65 labeling friction:Styrene emissions warnings required for polyester resin products create shelf-space penalties at West Coast specialty retailers, compressing distribution reach.
- Polyethylene performance ceiling:Amateur-grade boards lack the stiffness-to-weight ratios required for aerial maneuvers, capping price realization in the rental and mass-retail channel.
Strategic Opportunities
- Bio-composite material convergence:Flax fiber and mycelium-based core technologies intersect with sustainability signaling to unlock premium positioning in eco-conscious coastal markets.
- Direct-to-consumer channel expansion:Custom board configurators with 3D rail profiling bypass traditional specialty retailer markups, capturing margin from performance-oriented buyers.
- IRA clean manufacturing tax credits:US-based lamination facilities investing in electric curing ovens qualify for production incentives, offsetting compliance costs from EPA emissions rules.
Industry Challenges
- Artisan lamination skill scarcity:Hand-layup expertise for carbon fiber vacuum infusion concentrates among aging workforces in San Clemente and Laguna Beach, constraining premium output scaling.
- Multi-standard certification complexity:Simultaneous compliance with ISO 9001, CE marking for EU imports, and California Air Resources Board emissions protocols extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skimboard Market |
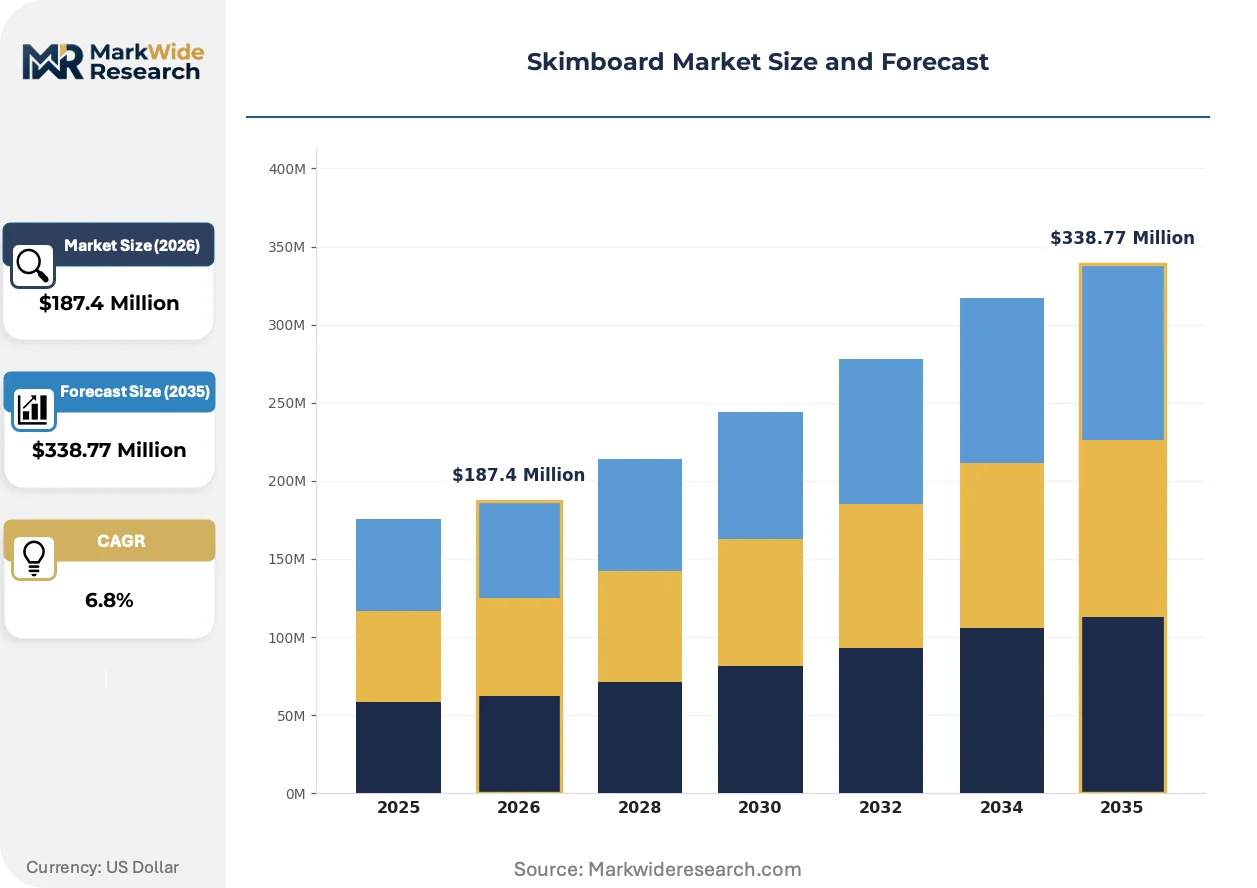
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Fiberglass, Wood, Carbon Fiber Use Case: Recreational Use, Competitive Events, Training, Beach Activities Customer Type: Amateurs, Professionals, Schools, Rental Services Distribution Channel: Specialty Stores, Online Retailers, Sports Shops, Supermarkets |
| Companies Covered | Waze Zone, Drift Sun Skimboards, Exile Skimboards, South Bay Board Co., Morey, Zap Skimboards, Wave Zone Skimboards, Liquid Force, Victoria Skimboards, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skimboard Market Evolving Landscape
Digital fabrication tools and bio-based materials are fragmenting traditional manufacturing hierarchies while regulatory pressure on resin chemistry accelerates formulation turnover across supply tiers.
Closed-mold vacuum infusion systems are decentralizing production geography by enabling smaller-scale facilities to achieve aerospace-grade carbon fiber compaction without autoclave infrastructure. Regional custom builders in Portugal and Brazil adopt these systems to serve local competitive scenes, compressing lead times against centralized Asian manufacturing. The technology is decentralizing brand power toward maker-networks with direct rider relationships.
EPA National Emission Standards for Hazardous Air Pollutants for reinforced plastic composites mandate thermal oxidizer installation at curing facilities, raising fixed cost thresholds for domestic manufacturers. Small-batch laminators respond by consolidating production runs or outsourcing to Mexican border facilities under USMCA provisions. California-based brands face the steepest compliance gradient given Proposition 65 layering.
Rental fleet procurement now favors modular rail systems allowing quick edge replacement rather than full board retirement. Coastal recreation departments in Florida and Australia's Gold Coast pilot subscription-based equipment refresh programs, transferring ownership risk to manufacturers. This consumption-pattern shift concentrates volume with suppliers offering lifecycle service bundles rather than transactional sales.
Skimboard Market Segmentation
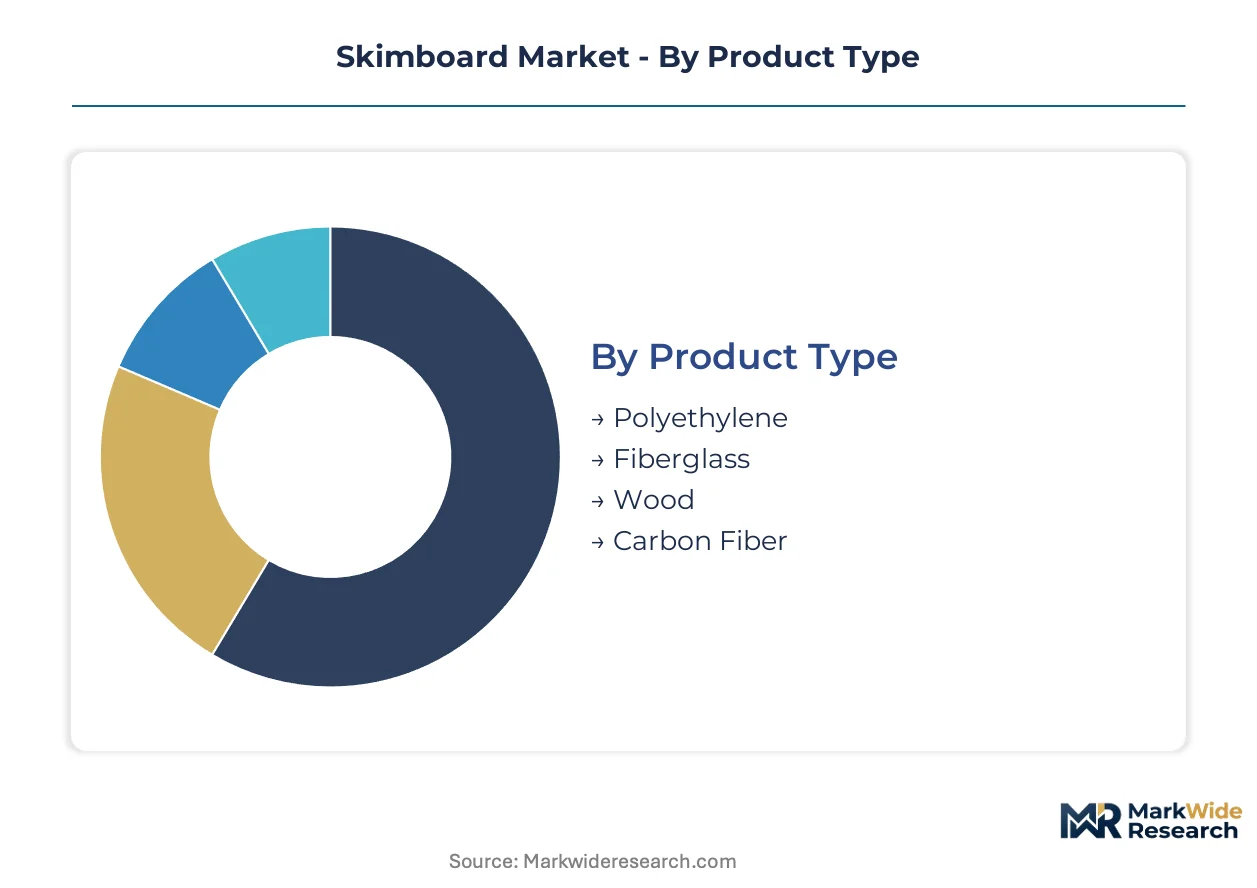
Product architecture and end-use certification requirements fragment the skimboard market into distinct procurement channels. Material selection and competitive eligibility standards create tiered pricing structures that manufacturers must navigate across recreational and professional customer bases.
Product Type:
ISO 9001 certification governs fiberglass and carbon fiber constructions entering competitive pipelines, while polyethylene and wood variants face lighter regulatory burdens for recreational channels.
- Fiberglass:Foam cores wrapped in woven fiberglass cloth with polyester or epoxy resin binders deliver balanced stiffness-to-weight ratios for intermediate riders. Demand concentrates in California and Florida rental fleets where durability requirements intersect with moderate price sensitivity. EPA emissions standards on resin curing constrain domestic production economics for this volume-leading tier.
- Carbon Fiber:Aerospace-grade pre-preg layups achieve superior stiffness-to-weight performance through vacuum infusion processing. Professional riders on the United Skim Tour and European Skimboard League drive concentrated demand despite Toray Industries and Mitsubishi Chemical controlling precursor supply. Proposition 65 labeling requirements add compliance friction for West Coast distribution.
- Polyethylene:Rotomolded or compression-molded plastic constructions serve entry-level beach recreation with maximum impact resistance.
- Wood:Laminated hardwood or bamboo cores retain artisanal positioning in eco-conscious coastal markets with sustainability signaling.
Leading the category by volume: Fiberglass. Growing fastest: Carbon Fiber.
Use Case:
Application context determines performance specifications, with competitive disciplines demanding certified constructions that recreational beach use does not require.
- Recreational Use:Casual flatland and shore-break riding by vacationers and weekend enthusiasts. Florida and California coastal tourism boards procure durable polyethylene fleets for public beach programs. Price accessibility dominates purchase criteria over technical performance metrics.
- Competitive Events:Wave riding and flatland disciplines governed by United Skim Tour and European Skimboard League equipment standards. ISO 9001 traceability mandates create pull-through demand for fiberglass and carbon fiber certified constructions. Professional athletes prioritize stiffness-to-weight optimization for aerial maneuver execution.
- Training:Structured skill development programs at coastal schools and youth camps. Procurement favors fiberglass intermediate boards that bridge recreational durability with competitive performance characteristics.
- Beach Activities:Unstructured casual use including sand sliding and shallow water play. Lowest performance requirements enable polyethylene dominance with minimal regulatory compliance overhead.
Volume concentrates in Recreational Use. Steepest expansion trajectory: Competitive Events.
Customer Type:
Buyer sophistication and procurement scale create distinct service requirements across the customer spectrum.
- Amateurs:Individual recreational riders purchasing through specialty retailers or direct-to-consumer channels. Sensitivity to price-to-durability ratios drives polyethylene and entry fiberglass selection. California Proposition 65 labeling influences purchase decisions at West Coast point-of-sale.
- Professionals:Sponsored athletes and competitive tour participants requiring custom rail profiles and layup specifications. Direct relationships with San Clemente and Laguna Beach laminators enable bespoke carbon fiber constructions. IRA clean manufacturing tax credits incentivize domestic sourcing for this premium tier.
- Schools:Institutional coastal education programs with fleet refresh cycles and maintenance service requirements.
- Rental Services:Municipal recreation departments and commercial beach operators in Florida and Australia's Gold Coast piloting subscription-based equipment lifecycle programs.
Amateurs generate highest unit volume. Professionals command steepest per-unit pricing.
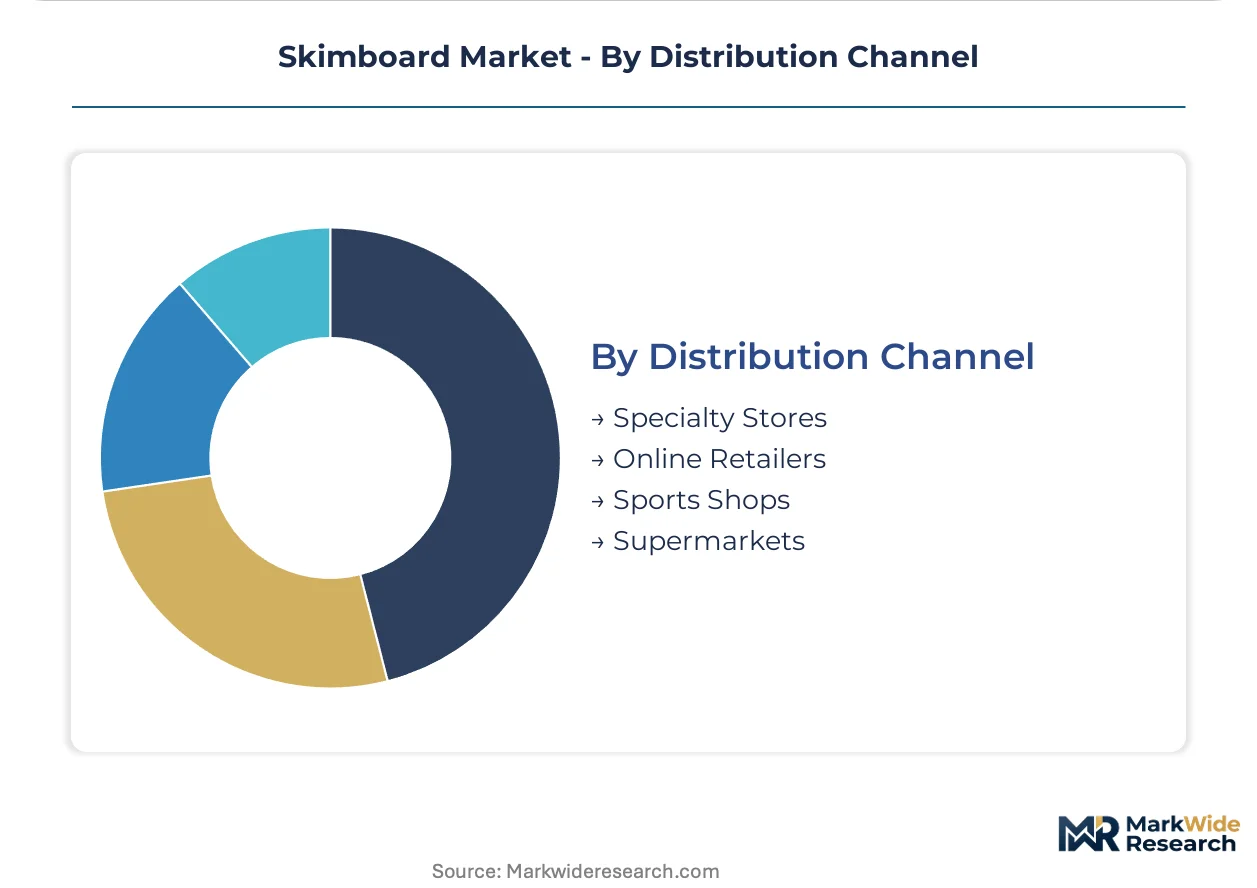
Distribution Channel:
Channel selection determines margin capture and regulatory exposure for manufacturers.
- Specialty Stores:California coastal retailers like those tied to Victoria Skimboards anchor premium brand positioning. Proposition 65 compliance requirements create shelf-space friction for polyester resin products.
- Online Retailers:Direct-to-consumer configurators with 3D rail profiling bypass traditional retail markups. Custom board builders in Portugal and Brazil leverage digital channels to serve local competitive scenes.
- Sports Shops:General sporting goods retailers carrying entry-level polyethylene inventory for mass-market beach recreation.
- Supermarkets:Seasonal retail placement of low-cost polyethylene boards in coastal tourism markets.
Specialty Stores retain premium positioning. Online Retailers gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Enterprise Zone tax credits concentrate skimboard lamination facilities along the San Clemente-Laguna Beach corridor, creating a coastal manufacturing cluster that serves competitive riders and rental fleets across North America.
United States
Florida's coastal tourism boards procure polyethylene rental fleets for public beach programs while California's Proposition 65 labeling requirements constrain polyester resin distribution through West Coast specialty retailers. The IRA clean manufacturing tax credits incentivize domestic electric curing oven investments. San Clemente hosts the densest concentration of carbon fiber vacuum infusion laminators serving professional athletes.
Brazil
Rio de Janeiro and São Paulo municipal recreation departments expand skimboard rental infrastructure ahead of coastal tourism seasons. Brazil's national environmental regulator enforces resin emissions standards at composite manufacturing facilities. Custom builders in Florianópolis adopt closed-mold vacuum infusion systems to serve local competitive scenes with reduced lead times.
Portugal
The Algarve region's coastal tourism authorities sponsor equipment procurement for beach recreation programs driving polyethylene volume demand. Portugal's environmental agency implements REACH-aligned chemical safety protocols for composite manufacturing. Regional custom builders in Lisbon and Porto leverage digital fabrication tools to serve European competitive riders through direct-to-consumer channels.
Australia
Queensland's Gold Coast municipal recreation departments pilot subscription-based equipment lifecycle programs for rental fleets. Australia's Therapeutic Goods Administration framework does not govern recreational equipment, though state-level environmental regulations apply to resin curing operations. Sydney and Melbourne specialty retailers anchor premium brand positioning for competitive-grade constructions.
Japan
Shonan and Chiba coastal prefectures maintain active skimboard communities with demand concentrated in fiberglass intermediate constructions. Japan's Ministry of Economy, Trade and Industry supports advanced materials manufacturing through regional industrial policy. Tokyo-based distributors import certified competitive equipment while domestic laminators serve recreational segments with cost-optimized formulations.
Skimboard Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium carbon fiber constructions concentrating among California-based laminators while entry-level polyethylene boards flow through mass-market sporting goods channels. The vendor base organizes into three strategic archetypes: heritage coastal brands with deep retailer relationships, direct-to-consumer custom configurators, and contract manufacturers serving private-label rental fleet procurement. Competitive moves center on geographic consolidation of lamination expertise and portfolio diversification into lifecycle service bundles.
Within the heritage brand tier, Victoria Skimboards and Zap Skimboards exemplify contrasting approaches to coastal market penetration, with the former anchoring California specialty retail relationships and the latter competing on price-accessible entry constructions. Exile Skimboards occupies a position representing in-house lamination expertise and premium custom layup capabilities. These three companies collectively illustrate the strategic divergence between margin-protected premium positioning and volume-driven recreational market capture.
| Leading Market Players |
|---|
| Waze Zone |
| Drift Sun Skimboards |
| Exile Skimboards |
| South Bay Board Co. |
| Morey |
| Zap Skimboards |
| Wave Zone Skimboards |
| Liquid Force |
| Victoria Skimboards |
| Others |
Value Network & Pricing Analysis
Closed-mold vacuum infusion systems are redistributing production economics across the skimboard landscape by enabling smaller-scale facilities to achieve aerospace-grade carbon fiber compaction without capital-intensive autoclave infrastructure. This manufacturing transition simultaneously compresses per-unit fixed costs for regional custom builders and fragments supply concentration away from centralized Asian lamination hubs.
Pricing Analysis
Volume concentrates in polyethylene entry boards while margins accrue to carbon fiber custom layups. Three-tier pricing structure across premium, standard, and economy levels separates professional-grade vacuum-infused constructions from intermediate fiberglass rentals and mass-market rotomolded plastic. Price differentiation rests on ISO 9001 certification status and in-house lamination capability. Cost compression in the fiberglass tier is intensifying because EPA emissions compliance raises domestic curing facility overhead. Amateur recreational riders exhibit highest price sensitivity; professional athletes on competitive tours demonstrate lowest sensitivity to per-unit cost.
Supply Chain Analysis
Reverse-logistics flows are emerging through subscription-based equipment lifecycle programs that transfer board retirement and refurbishment responsibility from municipal recreation departments back to manufacturers. Raw material supply draws from Japan and South Korea for aerospace-grade carbon fiber precursor, China for woven fiberglass cloth and foam core substrates, and Mexico for outsourced lamination under USMCA provisions. Feedstock concentration around Toray Industries and Mitsubishi Chemical creates single-source vulnerability for premium construction tiers. Distribution runs through California specialty retailers anchoring premium positioning, direct-to-consumer digital channels gaining share, and mass-market sporting goods for polyethylene volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The skimboard market is navigating a technology-transition phase as closed-mold vacuum infusion and bio-composite materials displace traditional hand-layup polyester resin constructions.
For Market Incumbents: To counter margin erosion from carbon fiber feedstock concentration and EPA emissions compliance costs, prioritize backward integration into low-VOC resin formulation capabilities and consolidate lamination expertise through targeted acquisition of San Clemente and Laguna Beach vacuum infusion specialists. For New Entrants and Emerging Players: Begin with underserved regional competitive scenes in Portugal and Brazil where closed-mold systems enable quality parity with shorter lead times against established California brands. Target direct-to-consumer digital channels with custom rail configurators to bypass specialty retailer markups and capture margin from performance-oriented riders. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by heritage brands seeking lamination skill scarcity and regional custom builders with established rider relationships. Long-term viability favors vertically integrated operations with in-house vacuum infusion and bio-composite R&D pipelines. Monitor carbon fiber precursor allocation rationing and EPA enforcement intensity as inflection indicators for premium tier margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Composite Material Development | Flax fiber and mycelium core technologies unlock premium positioning in eco-conscious coastal markets. |
| Direct-to-Consumer Channel Expansion | Custom board configurators with 3D rail profiling bypass traditional specialty retailer markups. |
| Low-VOC Resin Formulation Investment | REACH-compliant water-based epoxy bypasses solvent curing bottlenecks and EPA compliance costs. |
| Lifecycle Service Bundling | Subscription-based equipment refresh programs transfer ownership risk from rental fleets to manufacturers. |
| Vacuum Infusion Capability Acquisition | Consolidation of San Clemente and Laguna Beach laminators secures scarce hand-layup expertise. |
Research Methodology
Multi-period observation of carbon fiber precursor pricing, EPA enforcement actions, and competitive event certification standards anchored the trend analysis, supplemented by interviews with skimboard laminators, coastal tourism procurement officers, specialty retail buyers, and professional athletes on the United Skim Tour. Secondary validation drew from customs trade data for composite material imports, SEC filings of carbon fiber suppliers, California Air Resources Board emissions protocols, and ISO certification registries. Bottom-up demand modeling across rental fleet procurement, direct-to-consumer sales, and competitive equipment pipelines triangulated against top-down market sizing from regional tourism board budgets and sporting goods distribution data.
Input-output matrices mapped material cost structures and production capacity constraints across fiberglass, carbon fiber, polyethylene, and wood construction tiers through the projection horizon. Segmentation dimensions modeled include product architecture, use case certification requirements, customer sophistication tiers, and distribution channel economics. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion schedules. Industry-specific forecast inputs incorporated EPA National Emission Standards compliance timelines and United Skim Tour equipment rule modifications.
Underlying measurement precision varies by segment; carbon fiber professional-grade constructions carry tighter precision than artisanal wood variants due to concentrated supply and transparent pricing. Forecasts reflect documented assumptions regarding carbon fiber allocation continuity, low-VOC resin adoption rates, and coastal tourism board budget stability. Practitioners should monitor Toray Industries and Mitsubishi Chemical precursor pricing, EPA enforcement intensity in California, and United Skim Tour certification rule changes for early signals of forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Autonomous Golf Caddy Market
Outdoor & Sports
Swimming Pool Accessories Market
Outdoor & Sports
Fishing Tackle Box Market
Outdoor & Sports
Fishing Line Market
Outdoor & Sports
Swimming Pool Equipment Market
Outdoor & Sports
Lawn Roller Market
Outdoor & Sports
Fishing Reels Market
Outdoor & Sports
China Fishing Reels Market
Outdoor & Sports
Artificial Turf Market
Outdoor & Sports
Kids Scooter Market
Outdoor & Sports
Sleeper Pads Market
Outdoor & Sports
Camping Beds and Mats Market
Outdoor & Sports
Global Swimming Pool Market
Outdoor & Sports
Hunting Blinds Market
Outdoor & Sports
Cold Plunge Pools Market
Outdoor & Sports
Freshwater Fishing Rod Market