
 Kayak Accessories Market | 2026-2036
Kayak Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Kayak Accessories Market Outlook
Aftermarket service revenue is fragmenting across independent repair shops, brand-authorized service centers, and direct-to-consumer parts platforms. Wilderness Systems leverages its dealer network to control warranty fulfillment and capture recurring paddle and outfitting sales. Hobie anchors its position through proprietary MirageDrive component ecosystems that lock in replacement-part demand. NRS specializes in swiftwater rescue accessories, occupying a defensible niche where technical certification requirements limit price-based competition.
Kayak accessories encompass functional add-ons and safety equipment engineered to enhance watercraft performance, user safety, and cargo management during paddle-powered navigation. Rotomolded polyethylene hulls typically pair with UV-stabilized nylon deck rigging and closed-cell foam flotation inserts rated to specific buoyancy standards. Paddles and life jackets command the largest product-type revenue pools, though dry bags and storage solutions are gaining share as multi-day touring participation rises. Fishing use cases now drive premium material adoption, with aluminum-framed rudder systems and reinforced nylon tackle mounts outpacing recreational-grade plastic alternatives in margin contribution.
EPA marine debris regulations and state-level extended producer responsibility frameworks in the United States are tightening material recovery requirements for end-of-life kayaks and accessories. The EU REACH regulation restricts certain phthalates in flexible PVC components, pushing European suppliers toward TPU-coated nylon laminates. ISO 12402 buoyancy standards govern life jacket certification across export markets, creating compliance cost barriers for new entrants. Stakeholders must monitor how regulatory divergence between North American and European chemical safety regimes reshapes sourcing decisions and product line architectures.
Market Dynamics
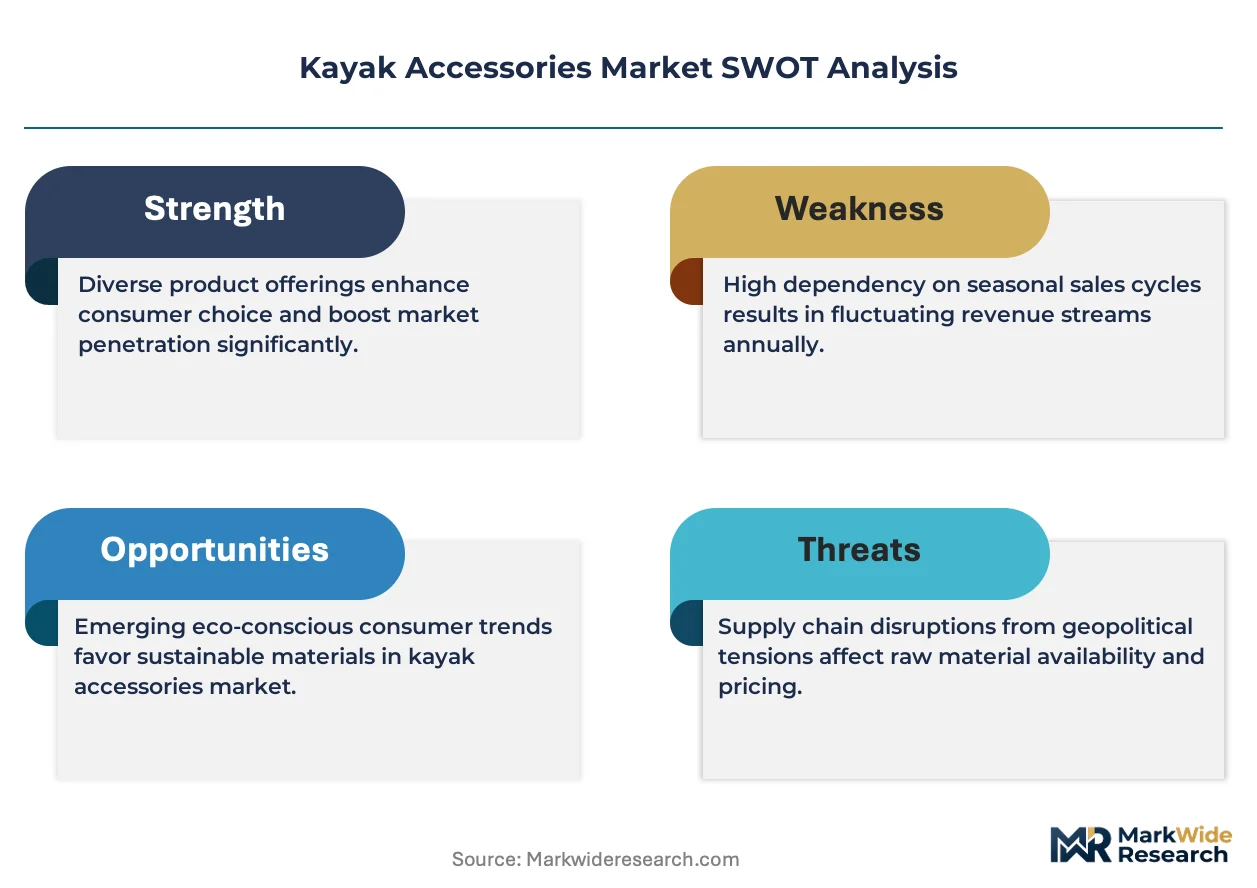
Polyethylene rotomolding advances are compressing hull weights while tightening EPA marine debris regulations force material recovery redesigns across the accessories value chain.
Growth Catalysts
- Extended Producer Responsibility frameworks:California and Oregon mandate end-of-life kayak recovery, creating certified refurbishment demand and secondary parts markets.
- Multi-day touring participation:Dry bag and deck storage attachment sales accelerate as expedition-grade outfitting replaces day-trip minimalism.
- Seattle-Portland retail cluster density:Specialty paddle sports distributors anchor Pacific Northwest demand concentration with immediate inventory access.
Market Restraints
- Petroleum-based resin price volatility:Rotomolded polyethylene hull production faces input cost swings tied to ethylene feedstock markets.
- TPU-coated nylon laminate conversion costs:EU REACH phthalate restrictions force European suppliers into higher-cost material substitutions without price recovery mechanisms.
- ISO 12402 certification timelines:Life jacket export compliance creates six-to-twelve month market entry barriers for new buoyancy equipment entrants.
Strategic Opportunities
- Swiftwater rescue certification requirements:Technical accreditation standards limit price competition in professional-grade safety accessories.
- Direct-to-consumer parts platforms:E-commerce fulfillment is capturing warranty replacement paddle and outfitting volume from traditional dealer networks.
- Fishing kayak premiumization:Aluminum-framed rudder systems and reinforced tackle mounts command margin premiums over recreational plastic alternatives.
Industry Challenges
- Rotomolding technician scarcity:Skilled polyethylene hull fabrication labor pools concentrate in legacy manufacturing geographies with limited training pipeline expansion.
- Dealer network warranty fulfillment complexity:Brand-authorized service centers compete with independent repair shops for aftermarket service revenue fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kayak Accessories Market |
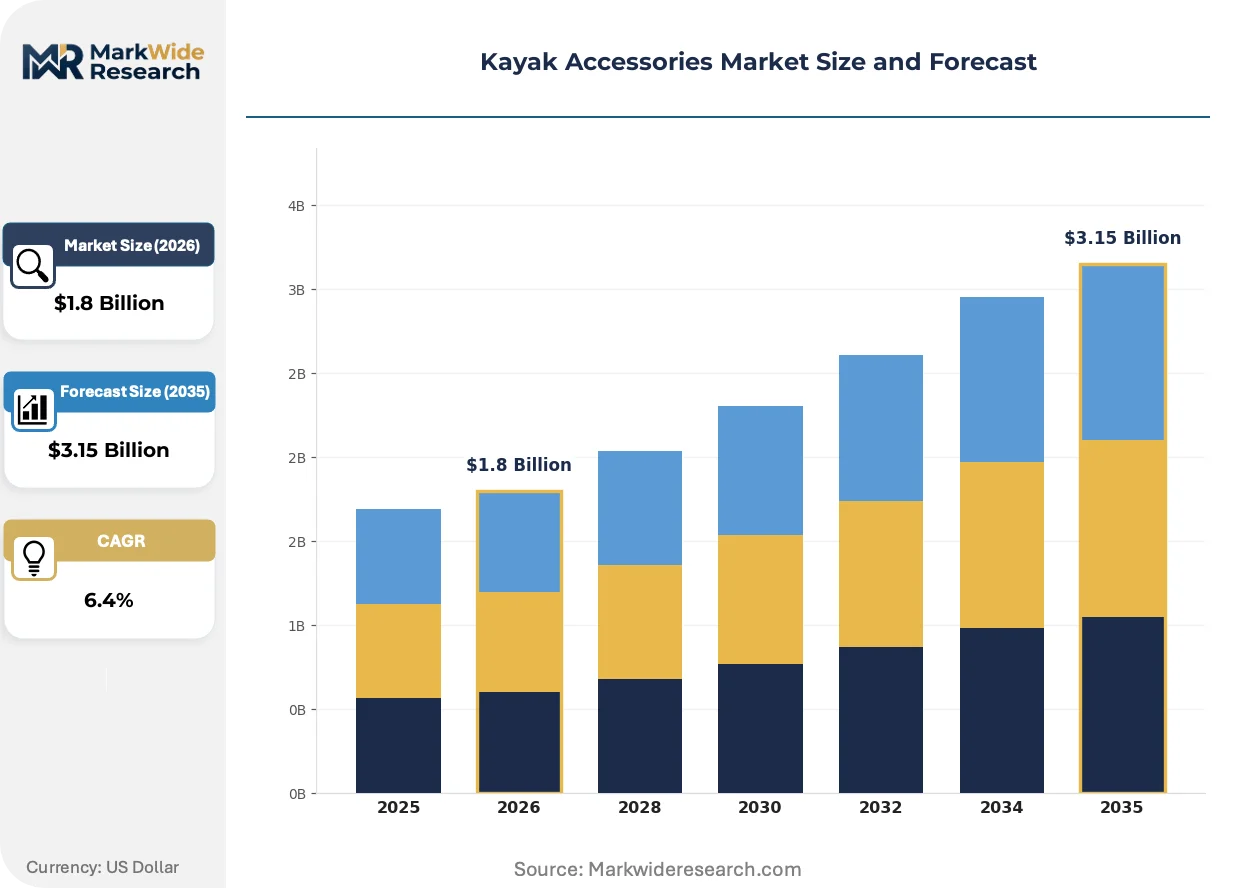
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paddles, Life Jackets, Dry Bags, Storage Solutions Material: Plastic, Nylon, Foam, Aluminum Use Case: Recreational, Fishing, Touring, Surfing End User: Outdoor Enthusiasts, Rental Companies, Tour Operators, Trainers |
| Companies Covered | Wilderness Systems, Perception Kayaks, Hobie, Ocean Kayak, Johnson Outdoors, Pelican International, NRS, YakAttack, Scotty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kayak Accessories Market Strategic Shifts
Accessories engineering now prioritizes weight reduction and modularity as rental fleet refresh cycles compress and user customization expectations intensify.
Smart paddle sensors embedded with stroke-rate and efficiency analytics are digitizing performance feedback for touring and fitness paddlers. High-end outfitters and competitive training programs adopt these connected accessories fastest. The technology is digitizing how manufacturers differentiate premium paddle tiers beyond material specifications alone.
EPA marine debris regulations and state-level extended producer responsibility frameworks are tightening material recovery requirements for end-of-life kayaks and accessories. Suppliers must redesign attachment systems for disassembly and polymer separation. Pacific Northwest manufacturers face the earliest compliance deadlines as Washington and Oregon implement the strictest recovery mandates.
Aftermarket service unbundling is fragmenting repair revenue across independent shops, brand-authorized centers, and direct parts platforms. Traditional dealer networks lose exclusive warranty fulfillment rights as manufacturers build proprietary e-commerce channels. This channel shift concentrates in coastal metropolitan markets where digital-native paddlers dominate replacement purchasing.
Kayak Accessories Market Segmentation
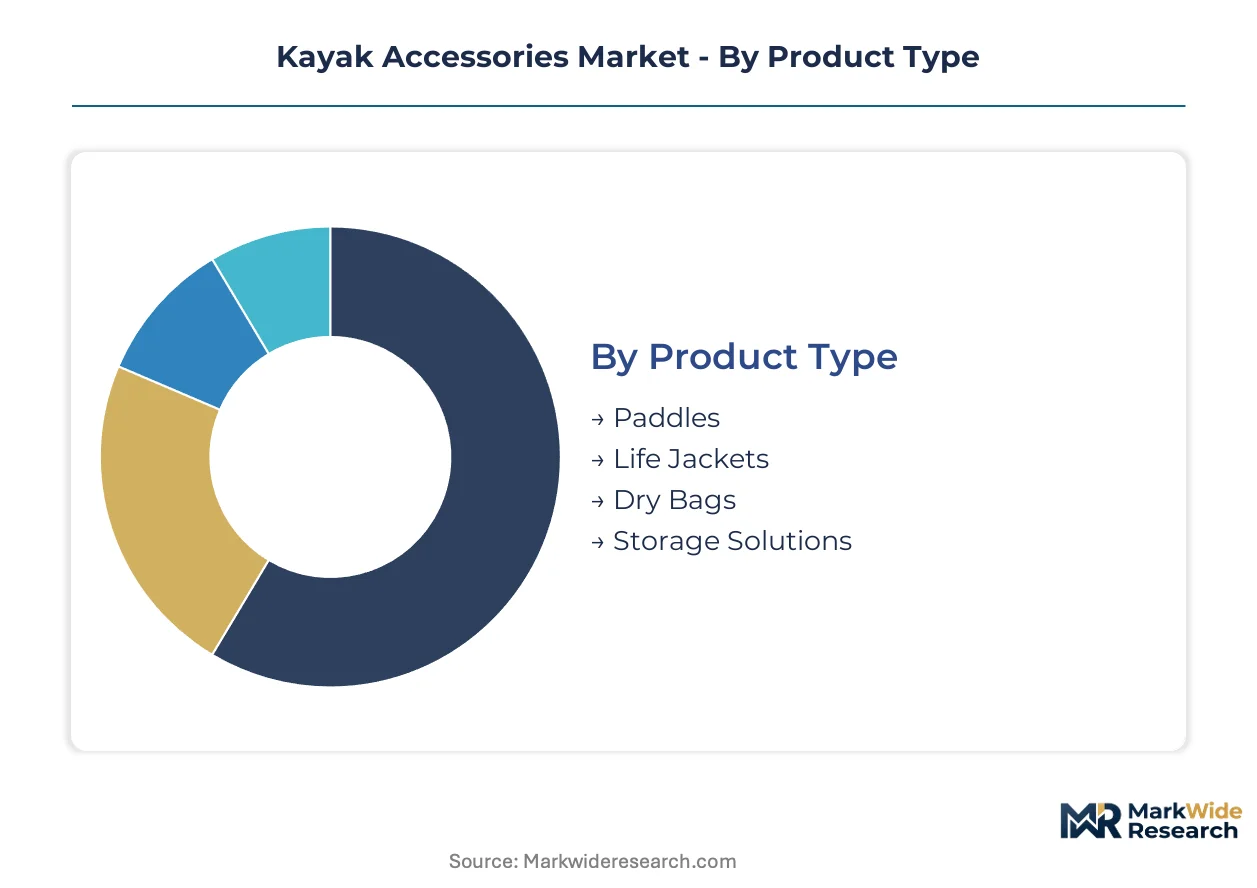
Segmentation in kayak accessories reflects divergent performance requirements across water conditions and user expertise levels. Material specifications and certification standards fragment demand into distinct procurement channels with incompatible technical specifications.
Product Type:
Cost tier stratification separates commodity accessories from expedition-grade equipment with ISO-certified buoyancy ratings.
- Paddles:Carbon fiber and fiberglass shaft constructions dominate premium tiers with indexed ferrule systems enabling length adjustment. Seattle-Portland specialty retailers anchor North American demand concentration as rental fleet refresh cycles compress replacement intervals.
- Life Jackets:Closed-cell foam inserts rated to ISO 12402 buoyancy standards govern certification timelines across export markets. EPA marine debris regulations in the United States force redesign of attachment hardware for end-of-life polymer separation.
- Dry Bags:TPU-coated nylon laminates replace phthalate-containing PVC under EU REACH restrictions.
- Storage Solutions:UV-stabilized deck rigging systems pair with rotomolded polyethylene hulls in touring configurations.
Paddles hold installed capacity. Dry bags are rotating up the share rankings.
Material:
Application-specific loading requirements drive material selection between recreational day-tripping and expedition-grade durability.
- Plastic:Rotomolded polyethylene hull fabrication relies on petroleum-based resin feedstocks with price volatility tied to ethylene markets. California and Oregon extended producer responsibility mandates force recovery system redesigns for end-of-life accessories.
- Nylon:UV-stabilized deck rigging and mesh storage components require additive packages for hydrolysis resistance in saltwater environments. Pacific Northwest manufacturers face earliest compliance deadlines under Washington state recovery mandates.
- Foam:Closed-cell flotation inserts deliver specified buoyancy per ISO 12402 certification tiers.
- Aluminum:Framed rudder systems command margin premiums in fishing kayak configurations.
Plastic holds installed capacity. Aluminum is rotating up the share rankings.
Use Case:
Customer type differentiation separates casual recreational users from technical specialists requiring certified safety equipment.
- Recreational:Day-trip minimalism drives volume in entry-level paddles and basic flotation devices. Independent repair shops capture aftermarket service revenue as warranty fulfillment fragments across direct-to-consumer parts platforms.
- Fishing:Reinforced nylon tackle mounts and aluminum-framed rudder systems outpace recreational plastic alternatives in margin contribution. Hobie MirageDrive component ecosystems lock in replacement-part demand through proprietary attachment standards.
- Touring:Multi-day expedition participation accelerates dry bag and deck storage attachment sales.
- Surfing:Swiftwater rescue certification requirements limit price competition in professional-grade safety accessories.
Recreational holds installed capacity. Fishing is rotating up the share rankings.
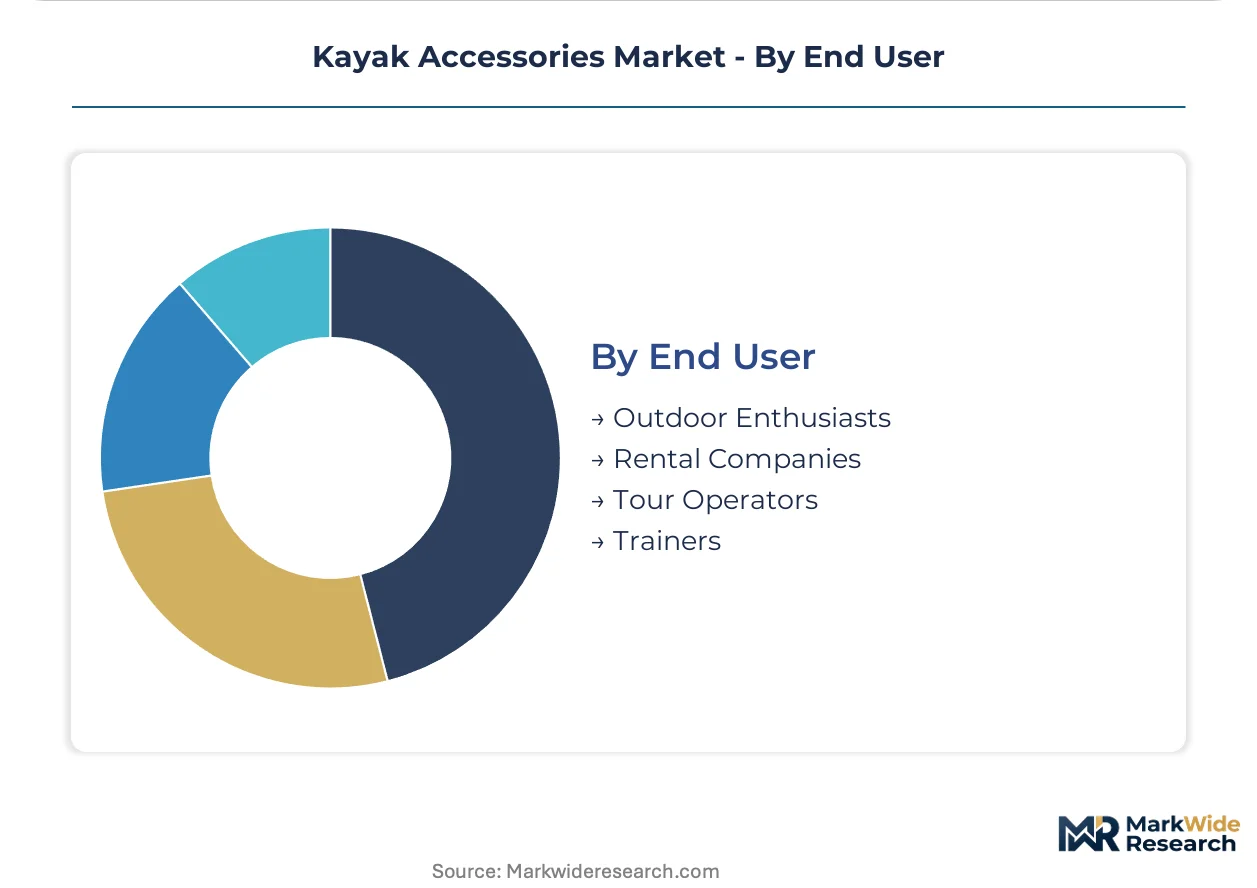
End User:
Volume concentration varies between individual consumers and fleet-scale procurement with divergent service expectations.
- Outdoor Enthusiasts:Digital-native paddlers in coastal metropolitan markets dominate replacement purchasing through proprietary e-commerce channels. Wilderness Systems leverages dealer networks to control warranty fulfillment and capture recurring paddle sales.
- Rental Companies:Fleet refresh cycles compress as polyethylene rotomolding advances reduce hull weight. Rotomolding technician scarcity concentrates skilled labor in legacy manufacturing geographies with limited training pipeline expansion.
- Tour Operators:Expedition-grade outfitting replaces day-trip minimalism as multi-day touring participation rises.
- Trainers:NRS specializes in swiftwater rescue accessories where technical certification requirements create defensible niche positioning.
Outdoor Enthusiasts holds installed capacity. Rental Companies is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between coastal metropolitan clusters where expedition-grade outfitting dominates and inland lake regions where recreational day-tripping drives volume. The Pacific Northwest anchors premium demand through dense specialty retailer networks, while the US Southeast concentrates rental fleet procurement. European markets prioritize REACH-compliant material substitutions, and Asia-Pacific growth centers on emerging coastal tourism infrastructure.
United States
The Pacific Northwest corridor between Seattle and Portland hosts the densest concentration of specialty paddle sports distributors in North America. EPA marine debris regulations and California's extended producer responsibility framework mandate end-of-life kayak recovery systems, creating certified refurbishment demand. Washington state implements the strictest recovery mandates, forcing Pacific Northwest manufacturers to redesign attachment hardware for polymer separation ahead of national deadlines.
Canada
British Columbia's coastal tourism economy drives demand for multi-day touring outfitting and expedition-grade safety equipment. Health Canada enforces buoyancy certification standards aligned with ISO 12402 for cross-border equipment compatibility. Vancouver anchors the western Canadian retail cluster with immediate inventory access to Alaskan and Pacific Northwest tour operators.
Germany
EU REACH phthalate restrictions force German suppliers toward TPU-coated nylon laminates in flexible components, eliminating PVC alternatives from export-bound product lines. The Bavarian and North Rhine-Westphalia manufacturing regions concentrate rotomolding capacity serving central European rental fleets. ECHA compliance timelines create six-month material conversion windows that disadvantage smaller fabricators.
Australia
The TGA-aligned therapeutic goods framework governs rescue equipment certification for commercial tour operators, while state-level marine safety regulations vary across Queensland, New South Wales, and Victoria. Sydney and Melbourne metropolitan markets dominate direct-to-consumer replacement purchasing through digital channels. The Great Barrier Reef tourism corridor concentrates premium outfitting demand among professional guide services.
Japan
METI industrial standards for marine leisure equipment create certification barriers for imported accessories, favoring domestic fabricators with established JIS compliance pathways. The Kanto region around Tokyo concentrates recreational paddling participation through artificial lagoon facilities and coastal day-trip infrastructure. Osaka-based distributors anchor Kansai region procurement for Seto Inland Sea tour operations.
Kayak Accessories Market Competitive Environment
Capability concentration sits with specialized safety equipment manufacturers; scale advantage sits with diversified paddle sports conglomerates. The market structures around three tiers: full-line kayak manufacturers with captive accessory ecosystems, independent accessory specialists with technical certification depth, and contract fabricators serving private-label retail programs. Strategic moves center on dealer network warranty control and direct-to-consumer channel construction.
Within the integrated manufacturer tier, Wilderness Systems and Hobie exemplify divergent ecosystem strategies. Wilderness Systems leverages dealer network density to control warranty fulfillment and capture recurring outfitting revenue. Hobie anchors replacement-part demand through proprietary MirageDrive component standards that lock in accessory compatibility. NRS occupies the specialist position in swiftwater rescue equipment, where technical certification requirements create defensible niche positioning against price-based competition.
| Leading Market Players |
|---|
| Wilderness Systems |
| Perception Kayaks |
| Hobie |
| Ocean Kayak |
| Johnson Outdoors |
| Pelican International |
| NRS |
| YakAttack |
| Scotty |
| Others |
Value Chain & Pricing Dynamics
The Tacoma-to-Portland freight corridor concentrates polyethylene resin shipments for rotomolded hull production, with container drayage costs compressing margins for Pacific Northwest fabricators while enabling price premiums for rapid-turnaround specialty retailers. This logistics geography concentrates supply-side leverage among distributors with bonded warehouse access, forcing smaller dealers into longer inventory cycles and narrower product assortments.
Pricing Analysis
Long-term offtake agreements dominate fleet procurement for rental companies and tour operators, while spot purchasing governs individual consumer replacement paddle sales. Three-tier pricing structure across premium, standard, and economy levels separates carbon fiber expedition paddles from fiberglass recreational models and aluminum entry-grade shafts. Cost compression in standard-tier paddles is intensifying because Chinese shaft imports face elevated Pacific container rates. Rental fleet buyers exhibit lowest price sensitivity due to total-cost-of-ownership calculations, while independent outdoor enthusiasts drive hardest bargain on accessory bundles.
Supply Chain Analysis
Ethylene feedstock for rotomolded polyethylene hulls draws from Gulf Coast petrochemical complexes, with TPU-coated nylon laminates sourcing from German and South Korean textile mills. Closed-cell foam flotation inserts rely on specialty chemical producers in Belgium and Japan for blowing-agent formulations. Single-source vulnerability concentrates in MirageDrive pedal system castings, where Hobie's proprietary tooling locks alternative suppliers out of replacement-part markets. Distribution runs through Seattle-anchored specialty retailers for premium tiers, while big-box outdoor chains and direct-to-consumer platforms capture recreational-grade volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rotomolding technician scarcity constrains hull production expansion, with skilled labor pools concentrated in legacy Great Lakes manufacturing geographies where training pipeline expansion lags fleet refresh demand. This capability gap rewards firms that capture technician apprenticeship channels or automate low-complexity fabrication.
For Market Incumbents: Insulate proprietary component ecosystems through backward integration into pedal-drive casting and rudder-system machining, mirroring Hobie's MirageDrive lock-in strategy. Capture Pacific Northwest dealer network warranty fulfillment rights before direct-to-consumer platforms erode service revenue. Invest in ISO 12402 certification depth for life jacket export markets, creating six-to-twelve month compliance barriers against emerging Asian competitors.
For New Entrants and Emerging Players: Build out swiftwater rescue accessory lines where NRS's technical certification requirements limit price-based competition and create defensible niche positioning. Target German and Austrian alpine river tour operators with REACH-compliant TPU-coated nylon laminates, exploiting ECHA conversion windows that disadvantage smaller European fabricators. Pursue white-label partnerships with artificial lagoon facility operators in Japan's Kanto region, bypassing METI certification barriers through domestic distributor relationships.
For Investors and Strategic Acquirers: Specialist safety equipment manufacturers with ISO 12402 depth and swiftwater rescue certification pathways represent the most defensible acquisition archetype, given technical barriers and limited price competition. Long-term viability hinges on regulatory divergence between EPA marine debris mandates and EU REACH phthalate restrictions, which favors suppliers with dual-compliance product architectures. Watch for Washington state recovery mandate acceleration as the earliest signal of national extended producer responsibility expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Warranty Control | Wilderness Systems leverages authorized service centers to capture recurring paddle and outfitting revenue from fleet operators. |
| Proprietary Component Ecosystem Lock-in | Hobie's MirageDrive attachment standards force replacement-part demand through captive supply chains. |
| REACH-Compliant Material Conversion | TPU-coated nylon laminate adoption eliminates phthalate-containing PVC from EU-bound product lines. |
| Direct-to-Consumer Parts Platform Buildout | E-commerce fulfillment captures warranty replacement volume from traditional Seattle-Portland specialty retailers. |
| Swiftwater Rescue Certification Investment | NRS's technical accreditation depth creates defensible positioning against price-based competition in professional safety accessories. |
Study Parameters
Desk research of EPA regulatory filings, state extended producer responsibility frameworks, and ISO 12402 buoyancy certification databases preceded structured interviews with rotomolding plant managers, Pacific Northwest specialty retailer buyers, tour operator fleet procurement leads, and swiftwater rescue equipment technical directors. Secondary validation drew from customs trade data for polyethylene resin imports, SEC 10-K disclosures from diversified paddle sports conglomerates, and ECHA REACH compliance notifications. Bottom-up demand modeling triangulated against top-down market sizing from rental fleet refresh cycle analysis.
Assumptions held petroleum-based resin price volatility within historical ethylene feedstock bands and EPA marine debris regulation timelines as enacted, while varying multi-day touring participation growth and direct-to-consumer channel penetration rates. Segmentation dimensions modeled across the analysis window included product type tier, material specification grade, use case technicality, and end user procurement scale. CAGRs derived from fleet replacement interval compression and expedition-grade outfitting mix shifts, with fishing kayak premiumization and smart paddle sensor adoption as scenario-weighted inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified outdoor conglomerates or accelerated EPA enforcement timelines would shift outcomes. Cross-checking against Pacific Northwest specialty retailer inventory turnover benchmarks and German TPU laminate conversion cost disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Sleeper Pads Market
Outdoor & Sports
Australia Horse Riding Equipment Market
Outdoor & Sports
Camping Lights and Lanterns Market
Outdoor & Sports
Freshwater Fishing Rod Market
Outdoor & Sports
Hunting Blinds Market
Outdoor & Sports
Swimming Pool Accessories Market
Outdoor & Sports
Global Swimming Pool Market
Outdoor & Sports
Lawn Roller Market
Outdoor & Sports
LED Fishing Light Market
Outdoor & Sports
Skateboard Ramp Market
Outdoor & Sports
Global Sailing Dinghy Masts Market
Outdoor & Sports
North America Fire Pits Market
Outdoor & Sports
Australia Kids Scooter Market
Outdoor & Sports
Fish Hunting Equipment Market
Outdoor & Sports
Europe Swimming Pools and Spas Market
Outdoor & Sports
Kids Scooter Market