
 Fishing Line Market | 2026-2036
Fishing Line Market Size, Share, and Industry Trends Forecast 2026-2036
Fishing Line Market Analysis
Japanese fluorocarbon resin supply is hardening as domestic petrochemical feedstock allocations tighten. Pure Fishing, Inc. leverages its vertical integration across North American retail channels to sustain volume leadership in big-box distribution. Daiwa Corporation anchors its position through captive manufacturing of high-modulus polyethylene braids in Japan. Sunline Co., Ltd. competes on specialized fluorocarbon formulations for tournament-grade freshwater applications.
Fishing line comprises extruded synthetic polymer filaments—typically nylon, fluorocarbon, or ultra-high-molecular-weight polyethylene—engineered for tensile strength, abrasion resistance, and refractive index matching to water. Monofilament lines, formed through single-extrusion processes, remain the default for general recreational use due to cost accessibility and knot reliability. Braided lines command premium positioning among saltwater and big-game specialists where diameter-to-strength ratios determine performance. Fluorocarbon segments extract margin from low-visibility demands in clear-water freshwater fisheries and leader applications.
EPA guidelines on perfluorinated compound discharge constrain fluorocarbon manufacturing site expansion in the United States. Japan's METI chemical substance reporting requirements shape reformulation timelines for domestic producers including Momoi Fishing Net Mfg. Co., Ltd. and Yo-Zuri America, Inc. China's MEE environmental compliance protocols are raising capital thresholds for new entrant line extrusion facilities. Stakeholders must monitor regulatory divergence between fluorocarbon and polyethylene chemistries as material substitution pressures intensify across major manufacturing jurisdictions.
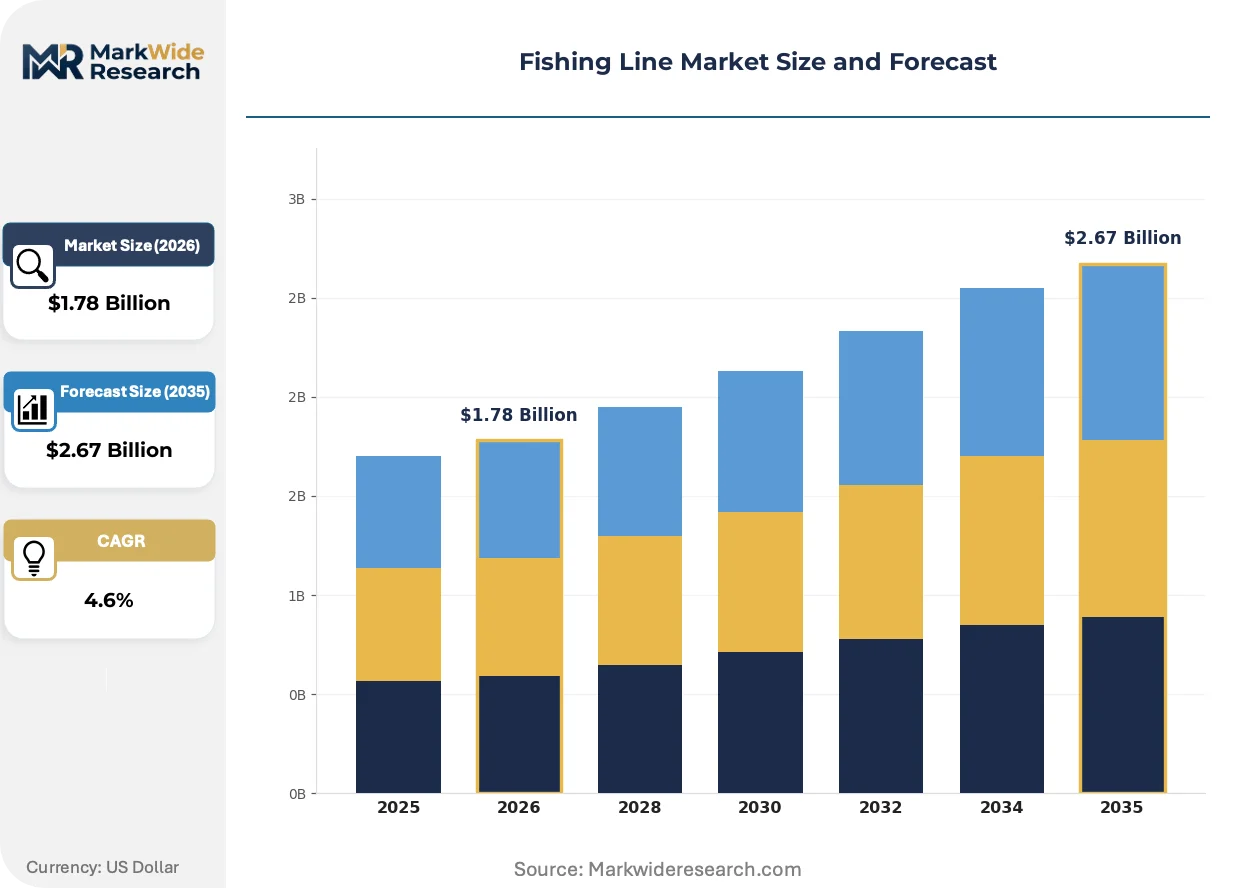
Market Dynamics
Material substitution is compressing traditional monofilament margins as fluorocarbon and braided polyethylene formulations capture performance-sensitive angler segments across North American and Asian tournament circuits.
Growth Catalysts
- Recreational participation surge:Tournament fishing registrations in the United States and Japan are climbing, pulling premium line demand through specialty retail channels.
- REACH chemical transparency mandates:European ECHA disclosure requirements are accelerating reformulation investments that yield performance advantages in abrasion resistance and refractive index matching.
- Ultra-high-molecular-weight polyethylene braids:Saltwater big-game specialists are adopting thinner-diameter alternatives that enable deeper trolling depths and extended casting range.
Market Restraints
- Petrochemical feedstock volatility:Japanese domestic resin allocations are tightening, constraining fluorocarbon raw material availability for extrusion facilities.
- EPA perfluorinated compound discharge limits:United States manufacturing site expansion faces permitting delays as environmental compliance thresholds harden.
- Monofilament commodity lock-in:General recreational anglers retain cost-driven purchasing patterns that resist premium material conversion.
Strategic Opportunities
- China marine leisure expansion:Coastal province development programs are building charter boat infrastructure that demands specialized saltwater line inventories.
- Direct-to-consumer subscription models:Tournament-grade anglers in the United States are accepting automated resupply arrangements for leader material and specialty formulations.
- ISO knot-strength certification:Third-party testing protocols are creating premium tier differentiation that rewards consistent manufacturing quality.
Industry Challenges
- Polymer science talent scarcity:Extrusion engineering and fluorocarbon formulation expertise concentrates among aging specialists in Japan and Germany.
- Multi-jurisdiction compliance synchronization:Producers must reconcile EPA discharge rules with METI substance reporting and MEE facility standards simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fishing Line Market |
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $2.67 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monofilament, Braided, Fluorocarbon, Wire End User: Recreational Anglers, Commercial Fishers, Sporting Goods Retailers, Fisheries Application: Fishing Tackle, Saltwater Fishing, Freshwater Fishing, Ice Fishing Distribution Channel: Online Retail, Specialty Stores, Big Box Retailers, Direct Sales |
| Companies Covered | Sunline Co., Ltd., P-Line, Pure Fishing, Inc., Yo-Zuri America, Inc., Maxima USA Inc., Daiwa Corporation, Momoi Fishing Net Mfg. Co., Ltd., Eposeidon Outdoor Adventure Inc., Rapala VMC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fishing Line Market Emerging Trajectories
Performance-driven material science is fragmenting the competitive landscape into chemistry-specific specialists while digital channels reshape how technical specifications reach end-users.
Braided ultra-high-molecular-weight polyethylene is overtaking conventional monofilament in saltwater and big-game applications where strength-to-diameter ratios determine catch success. Charter operators and competitive offshore anglers are converting rapidly, compressing shelf space for legacy nylon formulations at coastal tackle distributors. This shift is enabling premium pricing tiers that reward specialized manufacturing capabilities over commodity extrusion scale.
EPA guidelines on perfluorinated compound discharge are constraining fluorocarbon manufacturing site expansion in the United States. Industrial consequence includes extended permitting timelines for new extrusion capacity and accelerated capital deployment toward pollution control infrastructure. Freshwater tournament segments in clear-water fisheries are responding by stockpiling leader material and diversifying supplier relationships across Japanese and European sources.
Specialty retailers are unbundling after-sales technical consultation from product transactions, creating standalone service revenue streams. Tournament-grade anglers in the United States and Japan are purchasing line primarily through pro-staff relationships and direct manufacturer channels, bypassing traditional big-box intermediaries. This pattern is most visible in fluorocarbon leader categories where knot-tying instruction and species-specific application guidance drive repeat purchase loyalty.
Fishing Line Market Segmentation
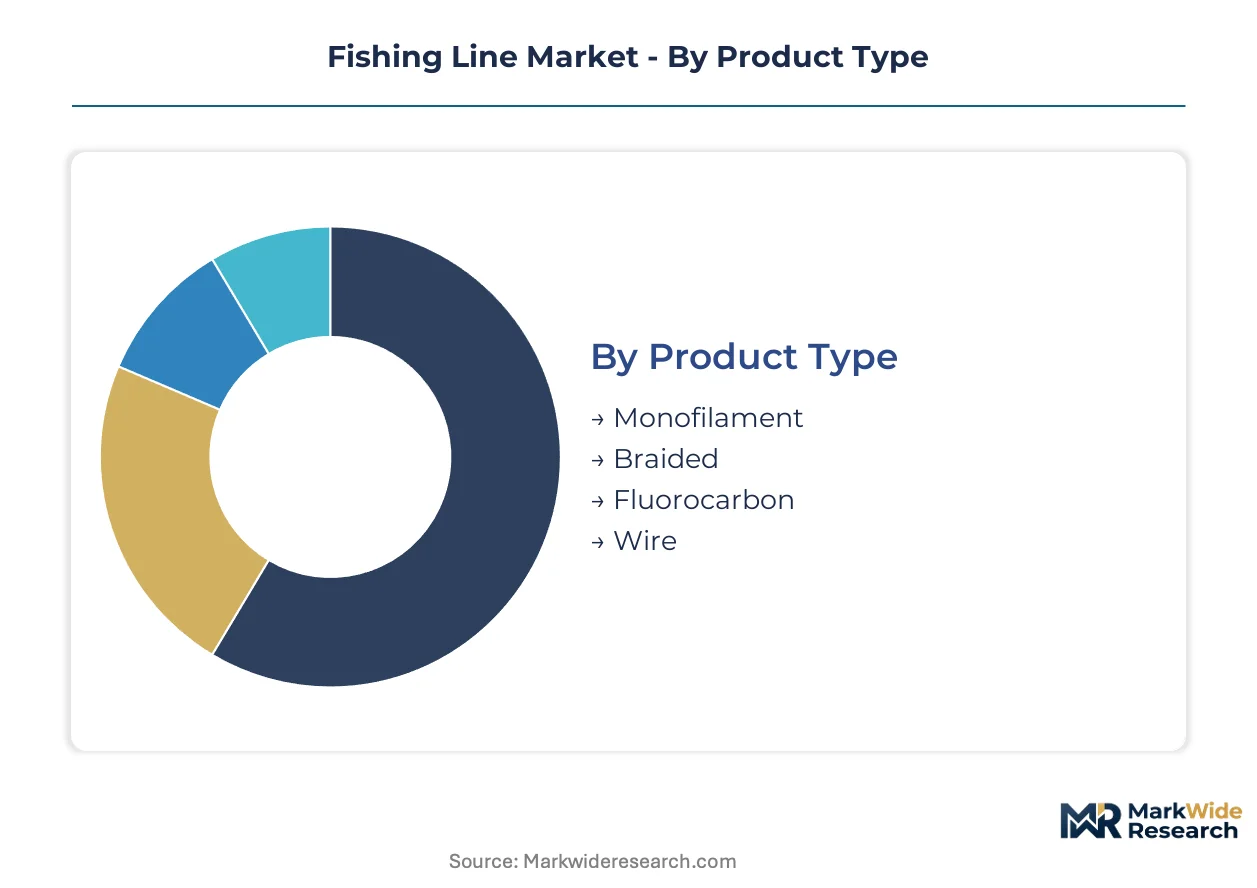
Segmentation in fishing line markets tracks how chemistry specialization, end-use intensity, and channel control interact to determine margin capture. Material formulation splits the competitive landscape between commodity extruders and performance specialists.
Product Type:
Customization intensity spans from standardized single-extrusion outputs to precision-engineered multi-filament constructions with species-specific refractive properties.
- Monofilament:Single-extrusion nylon formulations dominate general recreational volumes through cost accessibility and knot reliability. Demand concentrates among weekend anglers in the United States and China where price sensitivity resists premium conversion despite known performance limitations.
- Braided:Ultra-high-molecular-weight polyethylene multi-filament constructions deliver superior strength-to-diameter ratios for saltwater big-game applications. Charter operators across Florida and California are displacing monofilament inventories rapidly as deeper trolling depths become technically achievable.
- Fluorocarbon:Specialized resin formulations match water refractive index for low-visibility leader applications in clear-water freshwater fisheries.
- Wire:Stainless steel and titanium single-strand or multi-strand constructions target toothy species applications where abrasion resistance exceeds polymer capabilities.
Leading the category by volume: Monofilament. Growing fastest: Braided.
End User:
Purchasing sophistication varies from transaction-driven retail replenishment to specification-driven procurement with captive technical consultation.
- Recreational Anglers:Tournament participants in the United States and Japan drive premium fluorocarbon and braided line demand through specialty retail channels with high repeat purchase frequency.
- Commercial Fishers:Industrial-scale longline and net operations in Alaska and Massachusetts specify high-durability monofilament and wire constructions for mechanical deployment systems where unit economics dominate material selection.
- Sporting Goods Retailers:Big-box distributors in the United States consolidate volume purchasing power across multiple brand portfolios, compressing supplier margins through centralized procurement negotiations.
- Fisheries:Government and private hatchery operations in Washington and Oregon procure specialized line for research tagging and broodstock collection where biocompatibility specifications constrain supplier pools.
Volume leadership sits with Recreational Anglers. Steepest expansion trajectory: Commercial Fishers upgrading from natural fiber to synthetic durability.
Application:
Environmental exposure severity determines material performance thresholds from controlled freshwater conditions to corrosive saltwater abrasion.
- Fishing Tackle:Rod-and-reel system integration demands line-reel compatibility across diameter ranges and backing capacities. Manufacturers in South Carolina and Arkansas coordinate spool specifications with reel OEMs to ensure optimal cast performance.
- Saltwater Fishing:UV degradation and corrosion resistance requirements favor braided polyethylene and fluorocarbon leader combinations. Gulf Coast charter fleets in Louisiana and Texas are standardizing on thinner-diameter braids to maximize line capacity on conventional reels.
- Freshwater Fishing:Clear-water tournament circuits in Minnesota and Wisconsin drive fluorocarbon leader demand where visibility suppression determines competitive outcomes.
- Ice Fishing:Sub-zero flexibility and low-memory requirements favor specialized monofilament and fluorocarbon formulations. Anglers across Minnesota and North Dakota prioritize cold-weather knot reliability over open-water castability.
Dominant application by revenue: Freshwater Fishing. Climbing the fastest: Saltwater Fishing as coastal leisure participation expands.
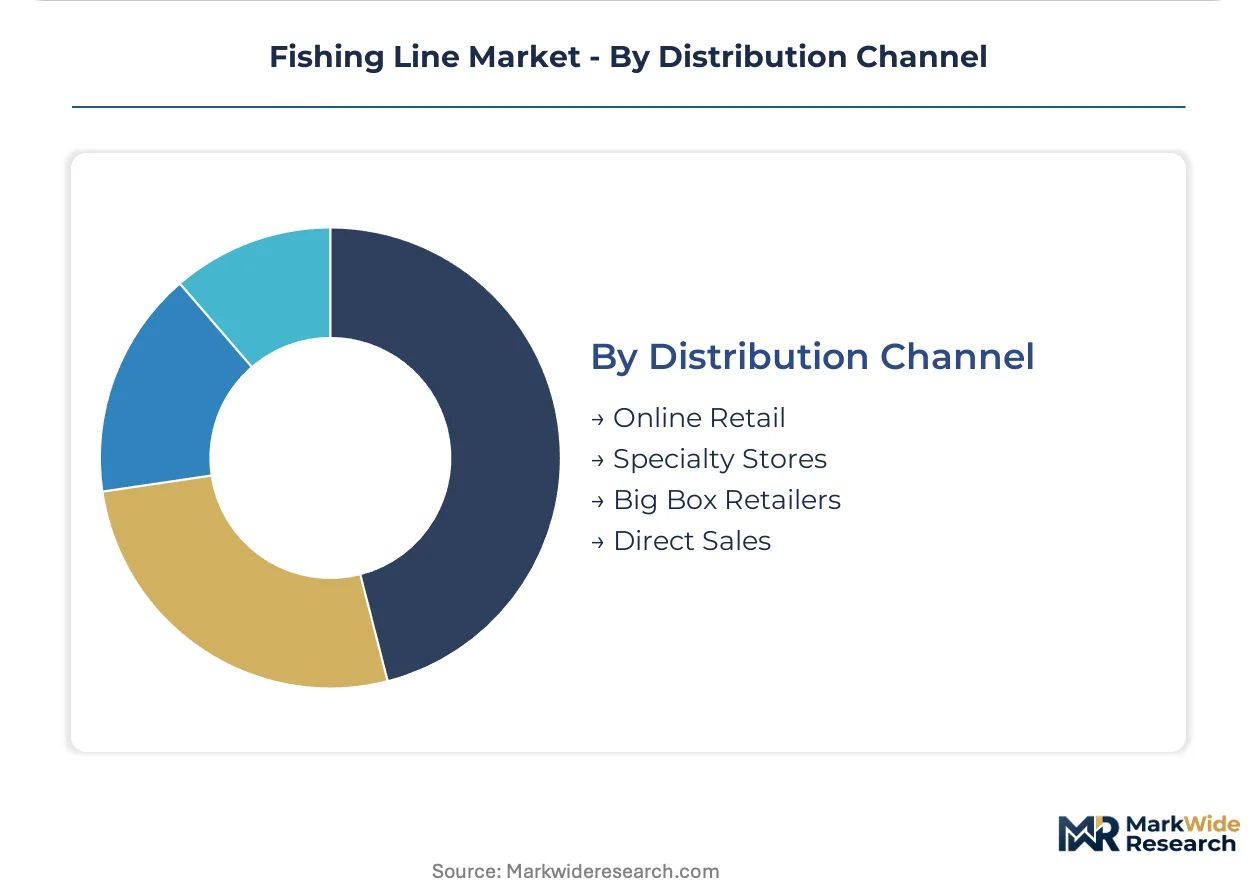
Distribution Channel:
Channel control determines margin retention from manufacturer-captured direct relationships to retailer-mediated price competition.
- Online Retail:Amazon and direct-to-consumer platforms capture growing share of replenishment purchasing for established anglers with specification confidence. Tournament-grade buyers in the United States increasingly bypass physical inspection for convenience and subscription automation.
- Specialty Stores:Independent tackle shops in Florida and California maintain relevance through technical consultation, knot-tying instruction, and species-specific application guidance that drives fluorocarbon leader loyalty.
- Big Box Retailers:Walmart and Dick's Sporting Goods consolidate monofilament volume through private label and national brand placement with aggressive promotional pricing.
- Direct Sales:Pro-staff relationships and manufacturer-owned channels capture premium segment margin by embedding technical service within the transaction.
Highest volume channel: Big Box Retailers. Gaining share fastest: Direct Sales as manufacturers build captive customer relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese fluorocarbon resin supply anchors the fishing line industry's geographic footprint, with petrochemical feedstock allocations tightening across domestic extrusion facilities. Tournament fishing registrations and marine leisure participation are pulling demand concentration toward specific coastal and freshwater clusters in three distinct markets.
United States
Tournament fishing registrations across Minnesota and Florida are climbing, pulling premium fluorocarbon and braided line demand through specialty retail channels. EPA perfluorinated compound discharge limits are extending permitting timelines for new extrusion capacity in South Carolina and Arkansas. Gulf Coast charter fleets in Louisiana and Texas are standardizing on thinner-diameter braids to maximize line capacity on conventional reels.
Japan
Domestic recreational angler participation is expanding across coastal zones and tournament circuits, sustaining demand for high-modulus polyethylene braids and specialized fluorocarbon formulations. METI chemical substance reporting requirements are shaping reformulation timelines for domestic producers including Momoi Fishing Net Mfg. Co., Ltd. and Yo-Zuri America, Inc. Captive manufacturing clusters in Japan concentrate fluorocarbon resin extrusion and braid engineering expertise.
China
Coastal province development programs are building charter boat infrastructure that demands specialized saltwater line inventories across marine leisure expansion zones. MEE environmental compliance protocols are raising capital thresholds for new entrant line extrusion facilities. Manufacturing capacity is concentrating in industrial zones serving both domestic consumption and export-oriented production of braided polyethylene formulations.
Germany
REACH chemical transparency mandates from ECHA are accelerating reformulation investments that yield performance advantages in abrasion resistance and refractive index matching. European tournament-grade anglers are sourcing specialized fluorocarbon leader material through direct manufacturer channels. Industrial clusters in southern Germany host polymer science expertise for ultra-high-molecular-weight polyethylene processing.
Australia
Saltwater big-game fishing participation is expanding across Queensland and New South Wales, driving adoption of braided polyethylene for offshore trolling applications. National environmental regulations govern discharge from synthetic polymer extrusion facilities. Coastal tackle distributors in Sydney and Brisbane are compressing shelf space for legacy monofilament formulations as charter operators convert to thinner-diameter braids.
Fishing Line Market Vendor Landscape
Global majors compete with regional champions across chemistry-specific manufacturing capabilities and channel control dimensions. The vendor base separates into consolidated players with vertical manufacturing control and specialized regional formulators serving tournament-grade segments. Three archetypes dominate: integrated resin-to-retail operators, captive braid engineering specialists, and fluorocarbon formulation pure-plays. Competitive moves center on direct-to-consumer channel expansion and pollution control infrastructure deployment to secure permitting for capacity additions.
Within the integrated operator tier, Pure Fishing, Inc. and Daiwa Corporation exemplify contrasting geographic anchoring strategies. Pure Fishing, Inc. occupies a position leveraging North American retail channel presence, while Daiwa Corporation represents Japanese captive manufacturing of high-modulus polyethylene constructions. Among fluorocarbon specialists, Sunline Co., Ltd. sits within the tournament-grade formulation segment, and Yo-Zuri America, Inc. anchors the reformulation-responsive tier navigating METI reporting requirements.
| Leading Market Players |
|---|
| Sunline Co., Ltd. |
| P-Line |
| Pure Fishing, Inc. |
| Yo-Zuri America, Inc. |
| Maxima USA Inc. |
| Daiwa Corporation |
| Momoi Fishing Net Mfg. Co., Ltd. |
| Eposeidon Outdoor Adventure Inc. |
| Rapala VMC Corporation |
| Others |
Supply Flow & Price Mechanics
Family-owned Japanese resin specialists anchor upstream fluorocarbon supply, their conservative capital allocation tightening feedstock availability while reinforcing premium pricing discipline across tournament-grade formulations. This ownership pattern concentrates pricing power among legacy producers who ration capacity expansion against EPA and METI compliance burdens.
Pricing Analysis
Warranty and technical consultation bundling separates specialty retailer pricing from stripped-down online transactions, with knot-tying instruction and species-specific guidance commanding 15-25% premiums at Florida and California independents. Three-tier pricing structure across premium fluorocarbon, mid-grade braided, and economy monofilament reflects ISO knot-strength certification status and reel compatibility testing. Cost compression in monofilament commodity tiers is intensifying because big-box procurement consolidation squeezes supplier margins through centralized negotiations. Weekend anglers in the United States and China exhibit highest price sensitivity, while tournament participants accept automated subscription resupply at premium tiers.
Supply Chain Analysis
Single-source vulnerability sits with Japanese domestic petrochemical feedstock allocations, where resin extrusion capacity concentrates in legacy facilities serving Pure Fishing and Daiwa captive operations. Raw material dependencies span fluorocarbon resin from Kureha and Mitsui, ultra-high-molecular-weight polyethylene from DSM and Honeywell, and nylon 6/6 from domestic polymer producers. Tariff exposure on Chinese braided line imports into the United States threatens margin structures for mid-tier distributors. Distribution runs through vertically integrated manufacturer-direct channels for premium segments, while big-box retailers consolidate monofilament volume through centralized procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
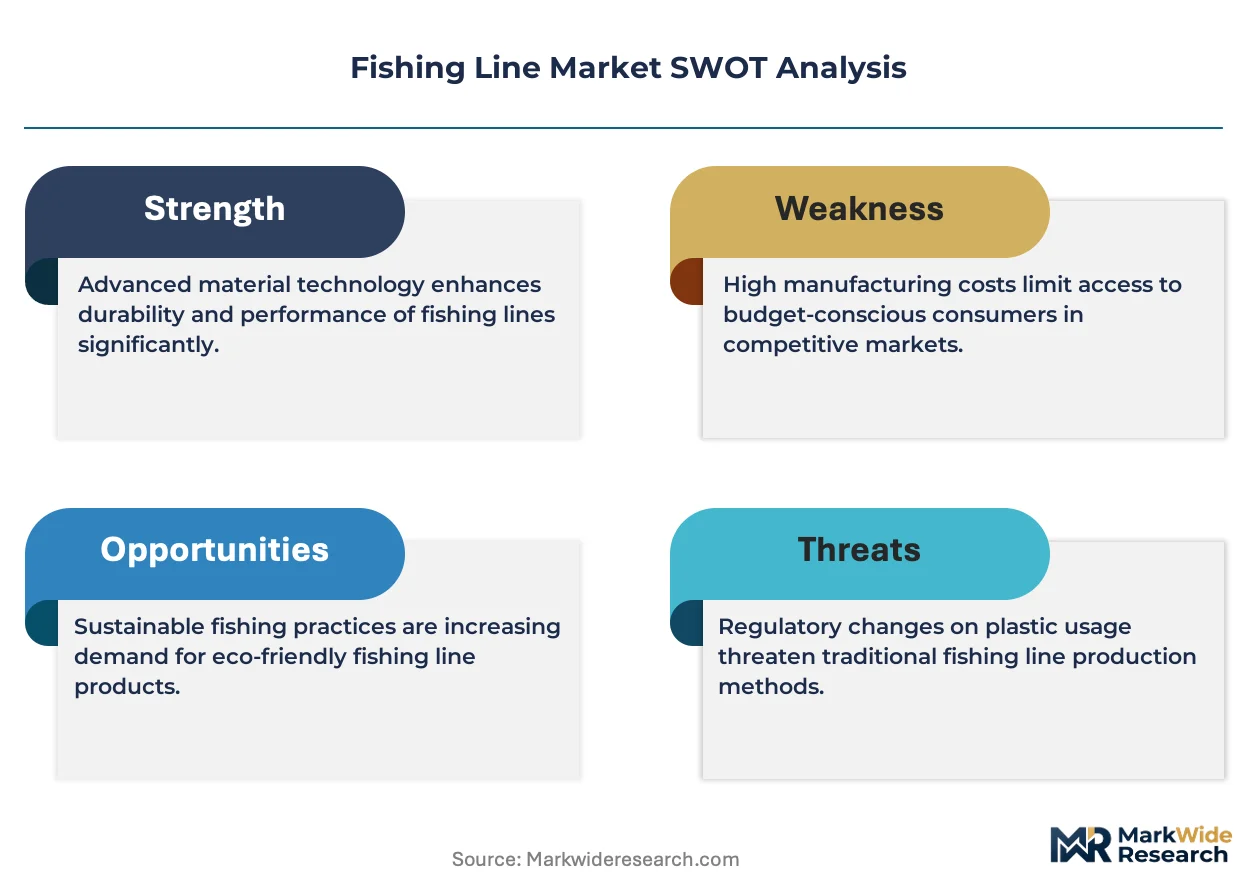
EPA perfluorinated compound discharge limits have erected a cost-of-compliance moat that rewards incumbent players with pollution control infrastructure already deployed, while raising capital thresholds beyond reach for prospective entrants.
For Market Incumbents: Deploy ISO knot-strength certification investment to differentiate manufacturing consistency and capture tournament-grade loyalty. Consolidate position through backward integration into fluorocarbon resin supply as Japanese feedstock allocations tighten. Defend against direct-to-consumer channel erosion by embedding technical service within pro-staff relationships. For New Entrants and Emerging Players: Braided polyethylene formulation innovation offers entry leverage into saltwater charter segments where diameter-to-strength ratios drive rapid conversion from monofilament. Target China's coastal province marine leisure expansion zones, where MEE compliance protocols have slowed domestic capacity additions. Pursue automated subscription models for leader material replenishment among United States tournament anglers. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized fluorocarbon formulators with METI-compliant reformulation capabilities and captive Japanese resin relationships. Long-term viability centers on chemistry-specific expertise scarcity as polymer science talent concentrates among aging specialists in Japan and Germany. Monitor EPA permitting timelines for United States extrusion capacity as inflection signal for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive fluorocarbon feedstock from Japanese petrochemical allocations secures margin against tightening supply. |
| Direct-to-Consumer Channel Expansion | Pro-staff relationships bypass big-box intermediaries and embed technical consultation within transactions. |
| Pollution Control Infrastructure Deployment | EPA-compliant discharge systems enable permitting for United States extrusion capacity additions. |
| ISO Knot-Strength Certification Investment | Third-party testing protocols create premium tier differentiation rewarding consistent manufacturing quality. |
| Specialized Fluorocarbon Reformulation | METI-responsive chemistry capabilities maintain market access under tightening Japanese substance reporting. |
Methodological Framework
Document review covered EPA discharge filings, METI chemical substance reports, and customs trade data, complemented by interviews with extrusion plant managers, specialty tackle shop owners, tournament angling organizers, and fluorocarbon resin procurement leads. Secondary validation drew from SEC 10-K disclosures of listed fishing equipment manufacturers, ECHA REACH registration databases, and coastal charter operator association surveys. Bottom-up demand modeling triangulated against top-down petrochemical feedstock allocation analysis.
Segment-level outputs across product type, end user, application, and distribution channel were generated through the projection horizon, with chemistry-specific manufacturing cost curves informing margin structure assumptions. CAGRs were derived from regression analysis against recreational participation indices and tournament registration trajectories. Key inputs included Japanese resin allocation schedules, EPA permitting timelines, and marine leisure infrastructure investment pipelines across Chinese coastal provinces.
Several conditions sit outside the modeled scope, including sudden petrochemical feedstock disruption, trade policy shifts affecting braided line tariffs, and technological substitution beyond fluorocarbon and polyethylene chemistries. Forecasts reflect documented assumptions about regulatory stability and recreational participation continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
China Fishing Reels Market
Outdoor & Sports
Fire Pits Market
Outdoor & Sports
Swimming Pool Liner Market
Outdoor & Sports
Golf Trolley Market
Outdoor & Sports
Camping Lights and Lanterns Market
Outdoor & Sports
Riding Multi-Purpose Lawn Mower Market
Outdoor & Sports
Mexico Fishing Reels Market
Outdoor & Sports
North America Fire Pits Market
Outdoor & Sports
Global Canoe and Kayak Market
Outdoor & Sports
Global Paintball Equipment Market
Outdoor & Sports
Walkbehind Lawnmower Market
Outdoor & Sports
Skimboard Market
Outdoor & Sports
Cold Plunge Pools Market
Outdoor & Sports
Fish Hunting Equipment Market
Outdoor & Sports
Swimming Pool and Spa Market
Outdoor & Sports
Global Scuba Diving Equipment Market