
 Electronic Equipment Repair Service Market | 2026-2036
Electronic Equipment Repair Service Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Equipment Repair Service Market Intelligence
Modular service bundling is pivoting how buyers structure repair contracts, shifting from single-incident fixes to integrated diagnostic-preventive packages. uBreakiFix leverages its retail footprint to anchor same-day consumer electronics repair across North American metros. Geek Squad competes through in-home service integration with major electronics retailers. iFixit differentiates via open-source repair documentation and parts distribution that sustains independent technician networks.
Electronic equipment repair service encompasses the technical restoration, calibration, and maintenance of malfunctioning electronic devices to specified operational parameters, typically involving component-level diagnostics, solder rework, firmware updates, and performance verification against manufacturer tolerances. Its primary commercial purpose is extending asset life cycles while minimizing downtime for dependent operations. Diagnostic testing and preventive maintenance command the largest share of service type revenue, while refurbishment is expanding fastest as circular economy mandates tighten. On-site repair dominates delivery model selection for industrial control systems and medical instruments where equipment immobility creates premium pricing, though remote assistance is displacing simple software-related incidents.
FCC equipment authorization rules shape repair eligibility for communication devices, while FDA quality system regulations govern servicing of medical instruments in the United States. The EU F-Gas Regulation and REACH chemical restrictions constrain solvent and refrigerant use in European repair depots, elevating compliance costs. Stakeholders must monitor whether right-to-repair legislation expands OEM parts access obligations or reinforces proprietary service channel control.
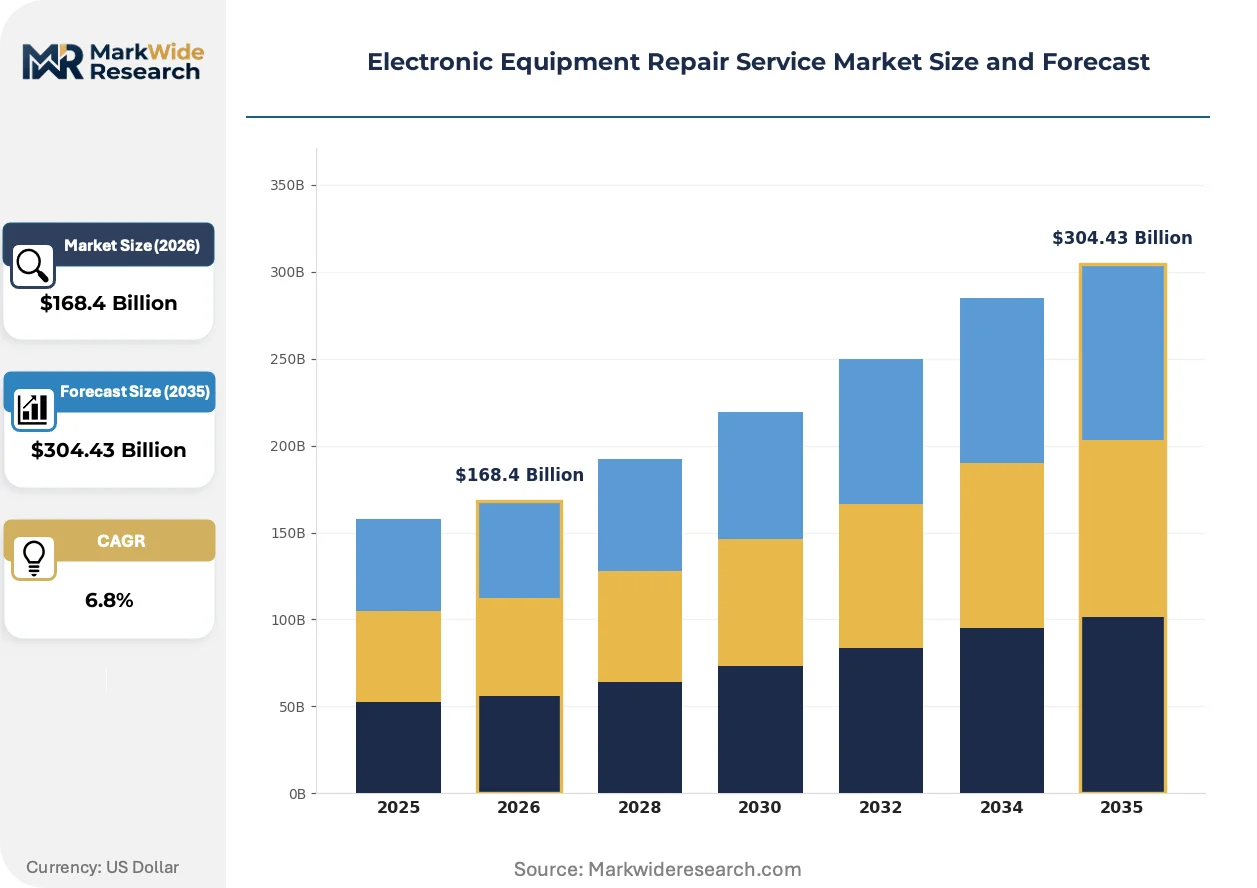
Market Dynamics
Modular service bundling is compressing incident-based repair economics as healthcare facilities and industrial operators consolidate vendor relationships into multi-year diagnostic-preventive contracts.
Growth Catalysts
- EU F-Gas Regulation:Tightened refrigerant handling mandates for diagnostic equipment are forcing healthcare facilities into certified service contracts, expanding recurring revenue pools for depots holding environmental compliance credentials.
- Precision manufacturing clusters:Germany's industrial control system density sustains high-volume maintenance demand, with automotive and semiconductor fabs requiring 24/7 uptime guarantees that lock in premium service tiers.
- Remote diagnostics:Software-enabled troubleshooting is expanding addressable incident volume by resolving firmware and configuration errors without physical dispatch, improving technician utilization rates.
Market Restraints
- Component supply concentration:Specialized ICs and sensors for medical and industrial equipment concentrate among Asian foundries, creating parts availability bottlenecks that extend repair turnaround times.
- REACH chemical restrictions:Solvent limitations in European depots elevate compliance costs for cleaning and rework processes, compressing margins on standard-tier service offerings.
- Proprietary firmware locks:Manufacturer-controlled software authentication blocks independent repair access to calibration and security functions, constraining price competition in consumer electronics.
Strategic Opportunities
- Refurbishment acceleration:Circular economy mandates in the European Union are diverting end-of-life equipment from disposal into certified rebuild channels, creating secondary revenue streams for depots with ISO 14001 environmental management systems.
- India electronics manufacturing:Production-linked incentive schemes are expanding domestic device assembly, building installed bases that will require localized repair infrastructure within three to five years.
- AI-assisted diagnostics:Machine vision and pattern-recognition tools are converging with technician workflows to compress fault isolation time, enabling higher-value service pricing for complex industrial systems.
Industry Challenges
- Microsoldering expertise scarcity:Component miniaturization in medical imaging and mobile devices demands specialized BGA rework skills that outpace vocational training program output.
- Cross-border certification reciprocity:FDA quality system regulations for medical device servicing lack mutual recognition with EU MDR requirements, forcing multi-regional operators to maintain duplicate compliance infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Equipment Repair Service Market |
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $304.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Diagnostic Testing, Preventive Maintenance, Fault Repair, Calibration, Refurbishment Equipment Type: Consumer Electronics, Communication Devices, Medical Instruments, Industrial Control Systems, Measurement Tools Delivery Model: On-site Repair, Depot Repair, Mail-in Service, Remote Assistance, Warranty Service Client Type: Telecommunication Firms, Healthcare Facilities, Manufacturing Plants, Research Laboratories, Educational Institutions |
| Companies Covered | uBreakiFix, Geek Squad, iFixit, Encompass Supply Chain Solutions, Electronix Services, iCracked, B2X Care Solutions, Asurion, ModusLink, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Equipment Repair Service Market Strategic Shifts & Innovations
Diagnostic-preventive service packages are displacing break-fix models across capital-intensive end-uses, compressing vendor count while elevating technical capability requirements for retained suppliers.
Predictive maintenance platforms are expanding into industrial control system servicing, embedding vibration, thermal, and electrical signature monitoring to forecast component degradation before failure. Automotive and semiconductor fabs in Germany and South Korea are adopting these systems fastest, converting unplanned downtime into scheduled maintenance windows that reduce emergency dispatch premiums.
REACH chemical restrictions and EU F-Gas Regulation amendments are reshaping depot operations by banning specific solvents and refrigerants used in cleaning and cooling system repair. European service providers are reformulating process chemistry and investing in closed-loop recovery systems, with medical instrument depots facing the steepest compliance cost escalation due to sterility requirements.
Hospital procurement departments are consolidating imaging equipment service contracts under single-source agreements that bundle parts, labor, and uptime guarantees, displacing fragmented multi-vendor arrangements. This concentration favors depots with OEM-authorized status and 24/7 response capabilities, most visible in US metropolitan hospital systems where equipment density justifies dedicated on-site technician placement.
Electronic Equipment Repair Service Market Segmentation
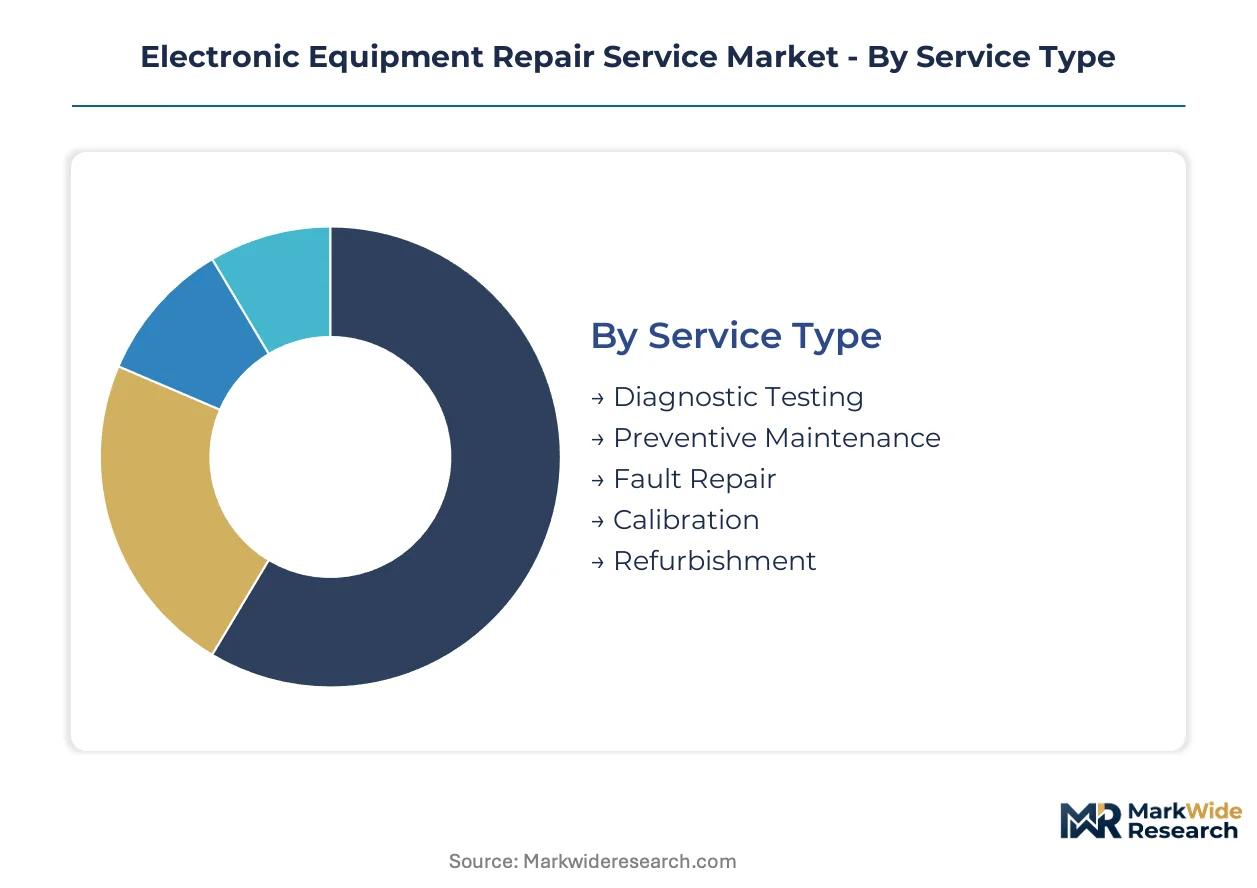
Service bundling patterns in electronic equipment repair diverge sharply between high-frequency, low-margin consumer work and capital-intensive industrial contracts. Segment boundaries increasingly blur as depot operators cross-train technicians across equipment categories to capture multi-year agreements.
Service Type:
Diagnostic testing and preventive maintenance dominate contract value, while refurbishment climbs fastest under circular economy mandates.
- Diagnostic Testing:Systematic fault isolation using oscilloscopes, spectrum analyzers, and protocol analyzers to pinpoint component-level failures. German automotive fabs and South Korean semiconductor plants require 24-hour diagnostic turnaround to maintain line uptime, locking in premium service tiers with dedicated technician placement.
- Preventive Maintenance:Scheduled inspection, cleaning, and component replacement based on manufacturer-specified intervals or predictive analytics. Healthcare facilities in the United States consolidate imaging equipment contracts under single-source agreements that bundle parts, labor, and uptime guarantees, displacing fragmented multi-vendor arrangements.
- Fault Repair:Corrective restoration of failed subsystems to operational specifications.
- Calibration:Adjustment of measurement accuracy against traceable standards.
- Refurbishment:Comprehensive rebuilding of end-of-life equipment to certified functional status.
Today's leader: Preventive Maintenance. Tomorrow's challenger: Refurbishment.
Equipment Type:
Medical instruments command the steepest service premiums due to regulatory compliance burdens, while industrial control systems generate the highest absolute contract volumes.
- Medical Instruments:Servicing of diagnostic imaging, patient monitoring, and therapeutic equipment subject to FDA quality system regulations and EU MDR requirements. Cross-border certification reciprocity gaps force multi-regional operators to maintain duplicate compliance infrastructures, elevating barriers for independent depots.
- Industrial Control Systems:Maintenance of PLCs, SCADA systems, robotics, and process automation hardware. Germany's precision manufacturing clusters sustain the densest service demand globally, with automotive and semiconductor fabs requiring round-the-clock uptime guarantees.
- Consumer Electronics:Repair of smartphones, laptops, tablets, and personal devices.
- Communication Devices:Restoration of network infrastructure and terminal equipment governed by FCC equipment authorization rules.
- Measurement Tools:Calibration and repair of laboratory and field instrumentation.
Industrial Control Systems anchor current revenue. Medical Instruments show the steepest expansion trajectory.
Delivery Model:
Physical proximity requirements stratify pricing power, with immobile equipment justifying on-site premiums and software incidents migrating to remote channels.
- On-site Repair:Technician dispatch to customer premises for equipment that cannot be transported without operational disruption or sterilization breach. Hospital procurement departments in US metropolitan systems justify dedicated on-site placement through equipment density and criticality.
- Remote Assistance:Software-enabled troubleshooting of firmware, configuration, and connectivity errors without physical dispatch. This channel is displacing simple incidents and improving technician utilization rates across all equipment categories.
- Depot Repair:Centralized facility processing of transportable equipment.
- Mail-in Service:Consumer-facing logistics for small electronics.
- Warranty Service:OEM-authorized repair under manufacturer guarantee terms.
On-site Repair holds pricing power. Remote Assistance scales fastest.
Client Type:
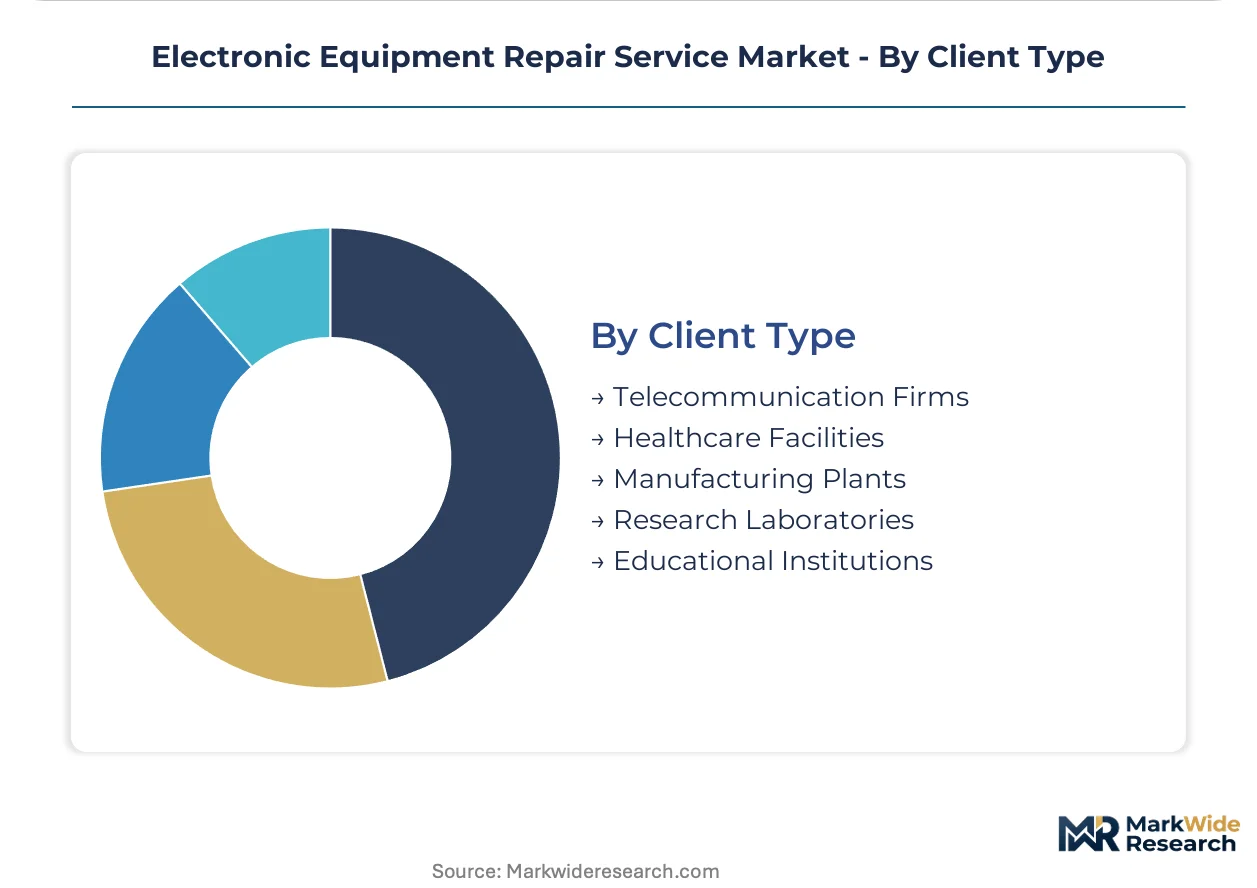
Healthcare and manufacturing procurement departments are consolidating vendor relationships, squeezing mid-tier independents while rewarding multi-capability service integrators.
- Healthcare Facilities:Hospitals, clinics, and diagnostic centers with stringent uptime requirements and regulatory exposure. EU F-Gas Regulation tightening refrigerant handling requirements for diagnostic equipment is forcing these clients into certified service contracts with environmental compliance credentials.
- Manufacturing Plants:Automotive, semiconductor, and precision engineering operations with continuous production schedules. Germany's industrial density sustains the highest maintenance volumes globally.
- Telecommunication Firms:Network operators with distributed infrastructure repair needs.
- Research Laboratories:Academic and commercial R&D facilities with specialized instrument portfolios.
- Educational Institutions:Universities and technical schools with mixed equipment bases.
Healthcare Facilities concentrate premium spend. Manufacturing Plants drive volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronic equipment repair services trace their industrial-scale origins to post-war Germany's precision manufacturing renaissance, where machine tool maintenance contracts formalized the sector's commercial architecture. That Teutonic foundation established technician certification standards and service-level agreements that spread through European engineering culture before migrating to North American and Asian industrial economies.
Germany
Automotive and semiconductor fabs in Baden-Württemberg and Bavaria sustain the densest industrial control system maintenance demand globally. The EU F-Gas Regulation tightens refrigerant handling mandates for diagnostic equipment, compelling healthcare facilities into certified service contracts. Stuttgart's precision manufacturing clusters require 24/7 uptime guarantees that lock in premium service tiers with dedicated technician placement.
United States
Hospital procurement departments in metropolitan systems consolidate imaging equipment contracts under single-source agreements bundling parts, labor, and uptime guarantees. FDA quality system regulations govern medical device servicing, elevating compliance burdens for multi-regional operators. The Boston-Cambridge corridor's medical technology concentration drives specialized instrument repair demand with stringent response-time requirements.
China
Domestic electronics assembly expansion under production-linked incentive schemes builds installed bases requiring localized repair infrastructure. MIIT equipment standards and NMPA medical device regulations shape service eligibility for communication and diagnostic devices. Shenzhen's hardware manufacturing ecosystem generates high-volume consumer electronics repair demand alongside industrial automation maintenance contracts.
India
Production-linked incentive schemes for electronics manufacturing expand domestic device assembly, creating repair infrastructure requirements within three to five years. BIS certification mandates and CDSCO medical device rules constrain depot operations for imported equipment. Karnataka's Bengaluru-Tumkur industrial corridor concentrates semiconductor and precision engineering operations with emerging maintenance contract demand.
South Korea
Semiconductor fabs in the Seoul Capital Area and Busan-Ulsan region adopt predictive maintenance platforms fastest, converting unplanned downtime into scheduled maintenance windows. MFDS medical device regulations govern diagnostic equipment servicing, while METI-aligned industrial standards shape automation system maintenance. Samsung and SK hynix supply chain proximity generates specialized technician training programs for advanced node equipment repair.
Electronic Equipment Repair Service Market Key Industry Players
The competitive structure tilts toward multi-capability service integrators capable of spanning consumer, medical, and industrial equipment categories. Fragmented independent depots compete alongside OEM-authorized networks and retail-anchored consumer chains. Three archetypes dominate: vertically integrated OEM service divisions, independent depot operators with environmental certifications, and retail-footprint consumer repair chains. Geographic expansion and strategic partnerships constitute the primary competitive moves, with certification acquisition serving as a secondary vector for market access.
Within the retail-anchored tier, uBreakiFix occupies a position exemplifying same-day consumer electronics repair across North American metropolitan markets. Geek Squad represents in-home service integration with major electronics retailers, while iFixit anchors independent technician networks through open-source documentation and parts distribution. These three entities collectively illustrate the segmentation between proprietary channel control and independent repair access that shapes competitive dynamics across consumer electronics servicing.
| Leading Market Players |
|---|
| uBreakiFix |
| Geek Squad |
| iFixit |
| Encompass Supply Chain Solutions |
| Electronix Services |
| iCracked |
| B2X Care Solutions |
| Asurion |
| ModusLink |
| Others |
Cost & Logistics Intelligence
AI-assisted diagnostic tools are compressing fault isolation timelines while simultaneously concentrating technician training investments among depots with machine vision capabilities, reshaping cost economics and supplier tiering across service categories.
Pricing Analysis
Subscription-based preventive maintenance contracts dominate high-value segments, with three-tier pricing structure across premium, standard, and economy levels separating OEM-authorized depots from certified independents and uncertified operators. Price differentiation rests on ISO 13485 medical certification and EPA Section 608 refrigerant credentials. Cost compression in standard-tier consumer electronics runs through parts availability bottlenecks from Asian foundries. Healthcare facilities show lowest price sensitivity due to uptime guarantees, while educational institutions concentrate demand in economy tiers.
Supply Chain Analysis
Reverse-logistics flows for refurbishment channel end-of-life medical imaging and industrial control equipment back through certified rebuild facilities in Germany, the United States, and South Korea. Specialized ICs and sensors draw from Taiwan, Japan, and South Korean foundries. Single-source vulnerability concentrates in BGA rework stations and spectrum analyzer calibration sources. Distribution runs through OEM-authorized networks for regulated equipment and independent depot consignment for consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electronic equipment repair service market compounds steadily as capital-intensive end-uses extend asset life cycles through mandatory compliance maintenance.
For Market Incumbents: Hedge proprietary firmware authentication exposure by building certified refurbishment capabilities under ISO 14001 environmental management systems. Deepen backward integration into parts distribution through direct sourcing agreements with Taiwanese and South Korean component suppliers. Defend against independent technician networks by embedding predictive maintenance platforms into multi-year hospital contracts.
For New Entrants and Emerging Players: Launch via mail-in depot models targeting underserved consumer electronics segments in India's Bengaluru-Tumkur corridor and secondary US metropolitan markets. Capture white-space in AI-assisted diagnostics for small and mid-sized manufacturing plants lacking in-house biomedical engineering. Penetrate fastest through environmental compliance certification arbitrage as EU F-Gas Regulation tightens.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent depot operators with ISO 13485 credentials and established healthcare facility relationships. Long-term viability over a five-to-ten year horizon favors multi-regional operators with duplicate FDA and EU MDR compliance infrastructures already amortized. Monitor right-to-repair legislative momentum in US statehouses and European Parliament as the critical inflection signal for parts access economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Environmental Certification Acquisition | ISO 14001 and EPA Section 608 credentials unlock EU F-Gas regulated service contracts. |
| Predictive Maintenance Platform Deployment | Vibration and thermal monitoring converts emergency dispatches to scheduled windows at German automotive fabs. |
| Cross-Border Compliance Infrastructure | Dual FDA quality system and EU MDR capabilities capture hospital procurement consolidation. |
| AI-Assisted Diagnostic Tool Integration | Machine vision compression of fault isolation time enables premium pricing for complex industrial systems. |
| Refurbishment Channel Development | Certified rebuild operations capture circular economy mandates diverting end-of-life equipment from disposal. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with depot operations managers, hospital biomedical engineers, OEM service contract directors, and industrial maintenance directors with secondary validation against FDA 483 inspection observations, EU MDR technical documentation filings, and EPA Section 608 enforcement records. Customs data on diagnostic equipment imports and hospital procurement database extracts anchored volume estimates. Bottom-up service contract value aggregation triangulated against top-down equipment installed base depreciation schedules.
Comparable historical periods anchored the projection horizon across diagnostic-preventive, fault repair, calibration, and refurbishment service types, further segmented by medical instruments, industrial control systems, consumer electronics, communication devices, and measurement tools. CAGRs derived from technician labor cost escalations, parts price indices, and contract renewal rate assumptions. Industry-specific forecast inputs incorporated EU F-Gas Regulation amendment timelines and India production-linked incentive scheme facility commissioning schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated right-to-repair legislation or semiconductor export control expansion. Practitioners should monitor FDA guidance document releases on servicing quality systems and REACH chemical restriction amendment proposals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic and Electrical
Global Power Adapter Market
Electronic and Electrical
Europe Gaming Accessories Market
Electronic and Electrical
Electronic Weighing Scale Market
Electronic and Electrical
Mobile Phone Power Accessories Market
Electronic and Electrical
Electronic Insect Killer Market
Electronic and Electrical
Active Damping Smartphone Case Market
Electronic and Electrical
Video Doorbell Market
Electronic and Electrical
USB Power Strips Market
Electronic and Electrical
A/V Cassette Housings & Parts Market
Electronic and Electrical
Audio Jack Market
Electronic and Electrical
Sports Electronics Devices Market
Electronic and Electrical
Air Conditioner Remote Control Market
Electronic and Electrical
Computer Keyboard Market
Electronic and Electrical
Global Personal Care Electrical Appliances Market
Electronic and Electrical
3D Glasses Chargers Market
Electronic and Electrical
Wireless Keyboard Market