
 Artificial Turf Market | 2026-2036
Artificial Turf Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Turf Market Intelligence
Skilled installer shortages across certified sports-field contractors is redrawing competitive dynamics in the artificial turf sector. FieldTurf leverages its vertically integrated manufacturing network to secure large municipal stadium contracts in North America. TenCate Grass anchors European demand through its dominance in FIFA- and World Rugby-certified pitch systems. CCGrass competes aggressively on polyethylene turf cost structures, sustaining volume leadership across Asia-Pacific markets.
Artificial turf comprises synthetic fiber surfaces—typically polyethylene, nylon, or polypropylene filaments tufted into permeable backings with sand and rubber infill—engineered to replicate natural grass performance for athletic, recreational, and aesthetic applications. Polyethylene turf dominates residential and commercial landscaping segments due to softer texture and UV stability, while nylon turf retains structural leadership in high-traffic sports installations where abrasion resistance is paramount. Sports clubs and municipal authorities represent the fastest-growing end-user pools, driven by lifecycle cost advantages and all-weather playability requirements.
FIFA Quality Programme standards, REACH chemical compliance in Europe, and EPA infill material assessments in the United States collectively shape product certification pathways and market access thresholds. The EU Green Deal's synthetic material recycling mandates and California's SB 47 crumb rubber disclosure requirements are forcing reformulation strategies across polyethylene and hybrid turf portfolios. Stakeholders must monitor evolving state-level procurement rules and polymer recycling infrastructure buildouts to anticipate which fiber-backfill combinations will retain specification eligibility.
Market Dynamics
Water scarcity mandates and lifecycle cost pressures are compressing procurement cycles for certified synthetic surfaces across municipal and institutional buyers. Polyethylene fiber thermal performance improvements and cooler infill chemistry advances are resetting baseline safety specifications while installer certification bottlenecks concentrate project execution risk among qualified contractors.
Growth Catalysts
- REACH chemical compliance frameworks:European ECHA registration requirements for crumb rubber infill components are accelerating reformulation investments toward bio-based and mineral alternatives, opening specification windows for compliant product lines.
- Municipal drought-scaping programs:California SB 47 disclosure mandates and parallel state-level water restriction ordinances are redirecting public landscape budgets toward synthetic turf installations with verified low-embodied-water credentials.
- Cooler infill technology diffusion:Advanced ceramic-coated sand and organic coconut-husk blends are reducing surface temperature deltas versus traditional rubber infill, expanding residential adoption in sun-belt climates.
Market Restraints
- Petroleum-derived input cost volatility:Polyethylene resin prices track naphtha and ethylene feedstock swings, compressing margin visibility for tufting manufacturers without captive polymer supply.
- Specialized installer concentration:FIFA- and World Rugby-certified field contractors cluster in Germany, the United States, and the Netherlands, creating geographic execution bottlenecks for complex stadium projects.
- Natural grass performance gap:Elite football and rugby leagues in England and Spain maintain hybrid grass preference for broadcast aesthetics, capping synthetic penetration in top-tier professional venues.
Strategic Opportunities
- India municipal sports infrastructure:Khelo India program allocations and Smart Cities Mission funding are creating tender pipelines for multi-sport synthetic surfaces with BIS certification compliance.
- EU Green Deal recycling mandates:End-of-life turf recovery infrastructure buildout requirements are positioning chemical depolymerization and mechanical recycling ventures for vertical integration into circular supply chains.
- Pickleball court conversion wave:Tennis facility retrofits across Florida, Arizona, and Texas are generating demand for specialized low-pile synthetic surfaces with distinct bounce characteristics.
Industry Challenges
- Certified installation technician scarcity:Field construction unions and specialized trade schools in the United States and Germany cannot match output to municipal stadium upgrade timelines, extending project backlogs.
- Multi-standard compliance complexity:Simultaneous FIFA Quality Programme, World Rugby Regulation 22, and EN 15330-1 testing requirements create certification timeline conflicts for product development teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Turf Market |
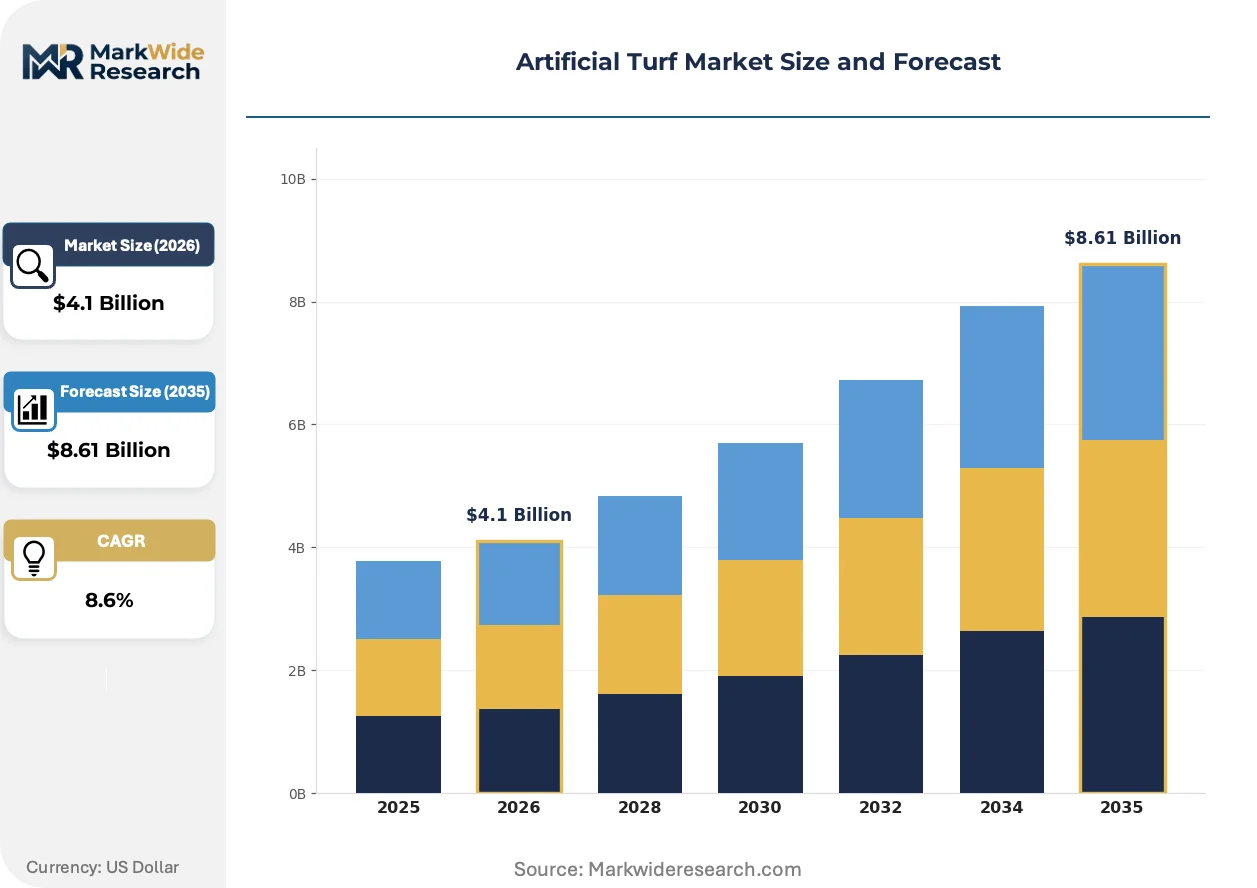
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.61 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Turf, Nylon Turf, Polypropylene Turf, Hybrid Turf Application: Sports Fields, Residential Landscaping, Commercial Landscaping, Playgrounds, Pet Areas End User: Municipal Authorities, Private Homeowners, Sports Clubs, Landscaping Firms, Educational Institutions Installation Type: Infill Turf, Carpet Turf, Foam Backing, Prefabricated Tiles, Artificial Sod Rolls |
| Companies Covered | Tarkett, Shaw Industries Group, FieldTurf, TenCate Grass, CCGrass, AstroTurf, Act Global, SIS Pitches, Limonta Sport, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Turf Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry constraints are splitting product development pathways into distinct performance tiers. Synthetic surface manufacturers now face parallel pressures to demonstrate thermal safety, circular end-of-life credentials, and playability metrics that satisfy divergent buyer segments.
Polyethylene monofilament cross-section engineering is bifurcating residential and professional product architectures. Flattened diamond-shaped profiles with matte surface treatments now dominate home landscaping channels for softness perception, while reinforced C-shaped monofilaments with central spine structures retain specification leadership in high-frequency sports applications. Municipal procurement officers in Texas and Nevada are specifying thermal reflectance coefficients above 0.35, forcing fiber suppliers to reformulate masterbatch additives.
California SB 47 crumb rubber disclosure requirements and parallel EPA infill material assessments are restructuring supply chain liability frameworks. Manufacturers serving the United States market must now maintain batch-level chemical testing documentation for zinc, polycyclic aromatic hydrocarbons, and volatile organic compound emissions. Product liability insurers are demanding ISO 14001 environmental management certification as a condition of coverage for installations above ten thousand square meters.
Buyer preference is consolidating around extended-warranty bundled service contracts that transfer maintenance liability to manufacturers. Sports clubs and school districts in Australia and the United Kingdom are displacing traditional capital-expenditure-only procurement with ten-year performance guarantees covering infill replenishment, seam repair, and G-max shock attenuation testing. This shift favors vertically integrated suppliers with captive installation and aftermarket service networks over pure-play fiber producers.
Artificial Turf Market Segmentation
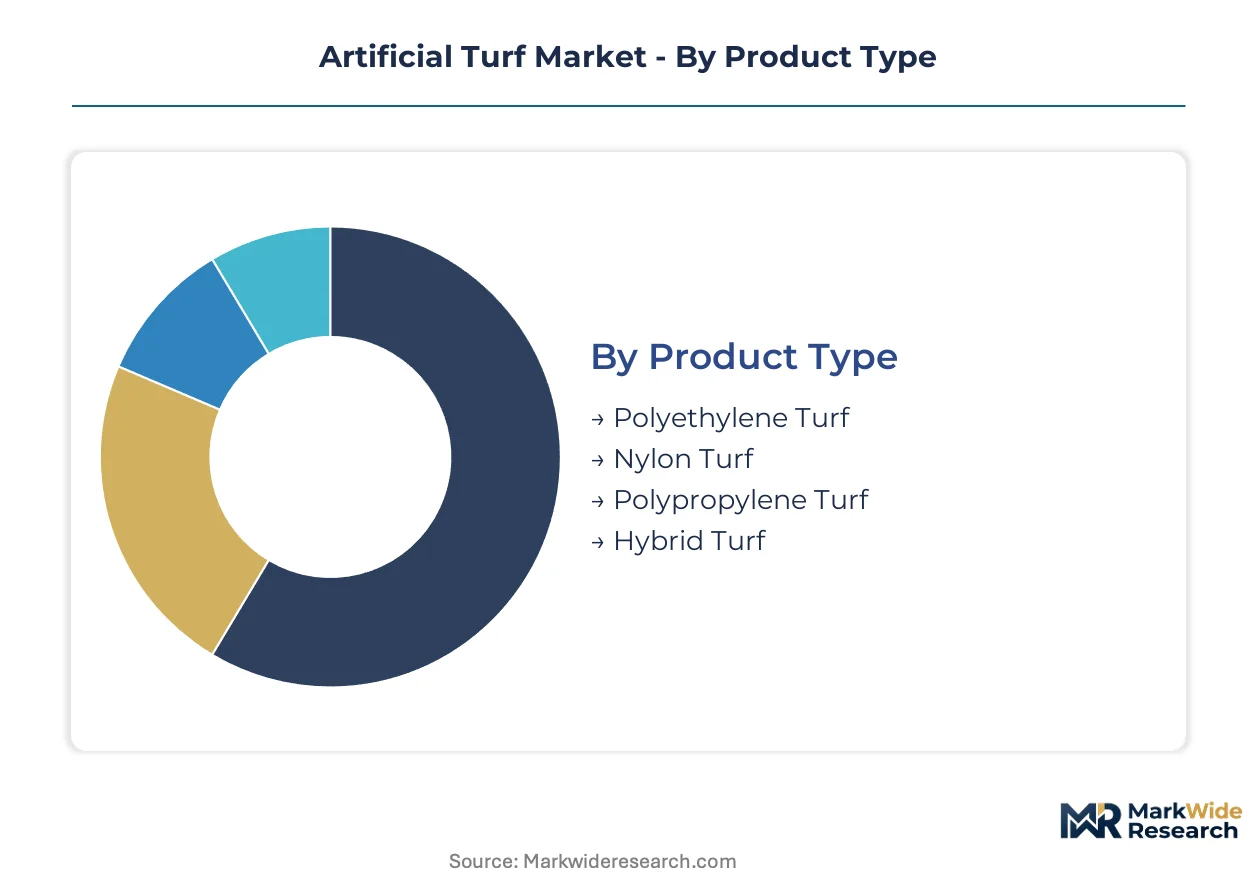
Segmentation in the artificial turf market reveals how fiber chemistry, installation architecture, and buyer procurement authority reshape competitive positioning. Manufacturers must align product portfolios with distinct performance requirements across athletic, residential, and institutional use cases.
Product Type:
Domestic consumption concentrates on polyethylene formulations in the United States and China, while European export demand pulls nylon and hybrid systems toward certified sports infrastructure projects.
- Polyethylene Turf:Soft monofilament construction with UV-stabilized masterbatch additives dominates residential channels. Municipal drought-scaping programs in California and Nevada specify thermal reflectance thresholds above 0.35, forcing additive reformulation.
- Nylon Turf:High-tenacity fiber with superior abrasion resistance retains specification leadership in FIFA- and World Rugby-certified stadiums. German sports clubs and English rugby venues specify nylon for high-frequency match schedules despite premium pricing.
- Polypropylene Turf:Lower-cost slit-film construction serves budget-constrained playground and temporary event applications.
- Hybrid Turf:Reinforced backing systems combining synthetic fiber with natural grass reinforcement target elite football venues seeking broadcast aesthetics.
Polyethylene turf holds the largest share; momentum sits with hybrid systems as professional leagues test reinforced natural-synthetic combinations.
Application:
Volume concentration varies sharply by climate stress and maintenance budget availability, with water-scarce regions prioritizing sports field conversions over aesthetic landscaping.
- Sports Fields:Full-size pitch installations with shock pads and drainage systems command the highest certification requirements. Texas school districts and Australian municipal authorities are compressing procurement cycles for certified surfaces.
- Residential Landscaping:Smaller-format installations with cooler infill chemistry are expanding fastest in Arizona, Florida, and Nevada sun-belt markets.
- Commercial Landscaping:Corporate campus and retail exterior applications prioritize rapid installation turnaround.
- Playgrounds:Fall-height-rated systems with expanded polyethylene foam underlayment serve school districts and park departments.
- Pet Areas:Antimicrobial-treated polyethylene with specialized drainage backing targets veterinary facilities and residential kennel installations.
Sports fields generate the highest revenue per square meter; residential landscaping is climbing the fastest as single-family housing construction rebounds in water-restricted states.
End User:
Procurement authority determines specification complexity, with institutional buyers demanding extended warranties and certified installer networks unavailable to individual consumers.
- Municipal Authorities:Public works departments in Germany, the United States, and Australia bundle synthetic turf into multi-year capital improvement programs with lifecycle cost modeling.
- Sports Clubs:Professional and amateur leagues drive FIFA Quality Programme and World Rugby Regulation 22 compliance requirements.
- Private Homeowners:Direct-to-consumer channels emphasize aesthetic samples and installation financing.
- Landscaping Firms:Commercial contractors specify bulk polyethylene rolls with training support from manufacturers.
- Educational Institutions:K-12 districts and universities prioritize G-max safety testing and infill replenishment service contracts.
Municipal authorities hold the largest share; momentum sits with sports clubs as broadcast revenue pressures force all-weather playability upgrades.
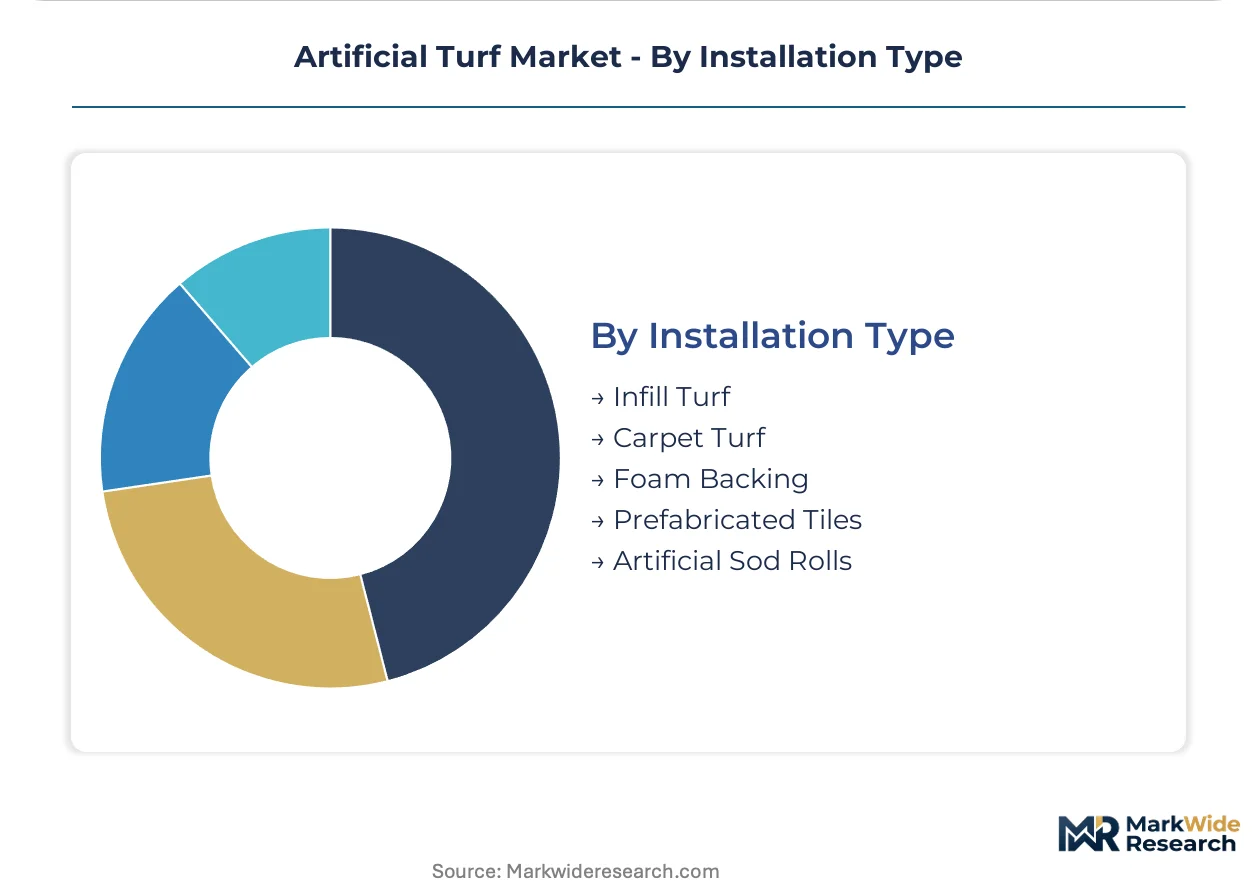
Installation Type:
Technical sophistication and labor intensity separate premium installed systems from modular alternatives targeting rapid deployment and seasonal flexibility.
- Infill Turf:Sand and rubber or organic infill systems with permeable backing represent the dominant installed base. EPA infill assessments and California SB 47 disclosure mandates are accelerating ceramic-coated sand and coconut-husk blend adoption.
- Carpet Turf:Glue-down systems without infill serve indoor training facilities and temporary exhibition spaces.
- Foam Backing:Pre-attached shock pad systems reduce installation labor and improve fall-height ratings for playground specifications.
- Prefabricated Tiles:Interlocking modular systems enable rapid court conversion for tennis-to-pickleball retrofits in Florida and Arizona.
- Artificial Sod Rolls:Lightweight rolled formats target rental event markets and seasonal sports field overlays.
Infill turf holds the largest share; momentum sits with prefabricated tiles as multi-sport facility conversions accelerate across sun-belt retirement communities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between water-stressed regions favoring municipal sports conversions and temperate zones where residential landscaping drives procurement. The United States concentrates demand in drought-scaping programs, while European markets prioritize certified pitch installations under FIFA and World Rugby standards.
United States
Texas and California school districts are compressing procurement cycles for certified sports surfaces as municipal water restrictions tighten. The EPA maintains active infill material assessments while California's SB 47 mandates crumb rubber disclosure, reshaping supplier liability frameworks. Phoenix and Las Vegas anchor sun-belt residential demand where cooler infill technologies penetrate single-family housing developments.
Germany
FIFA- and World Rugby-certified pitch installations dominate municipal capital programs across North Rhine-Westphalia and Bavaria. REACH chemical compliance through ECHA registration requirements accelerates reformulation toward bio-based infill alternatives. Cologne and Munich cluster specialized installation contractors who command premium pricing for complex stadium projects.
China
Municipal stadium upgrades and residential drought-scaping in water-scarce northern provinces drive polyethylene turf volume. GB standards and MIIT industrial guidelines shape product certification pathways for domestic manufacturers. Zhejiang and Jiangsu provinces concentrate tufting and backing production capacity serving Asia-Pacific export markets.
Australia
Sports clubs and school districts in New South Wales and Queensland are displacing traditional procurement with ten-year performance guarantee contracts. The country's national environmental regulator assesses synthetic material recycling mandates aligned with circular economy frameworks. Melbourne and Sydney anchor vertically integrated suppliers with captive installation and aftermarket service networks.
India
Khelo India program allocations and Smart Cities Mission funding create tender pipelines for multi-sport synthetic surfaces. BIS certification compliance shapes market access thresholds for domestic and imported products. Maharashtra and Karnataka states concentrate municipal sports infrastructure spending with accelerating procurement timelines.
Artificial Turf Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier that competes on certification depth and regional installation density. The upper tier commands municipal stadium contracts through captive manufacturing and service networks, while mid-scale players differentiate on FIFA Quality Programme compliance and cooler infill chemistry portfolios. Two dominant competitive moves define current positioning: backward integration into polymer supply and geographic expansion through certified installer network buildouts.
Within the integrated manufacturing tier, FieldTurf and TenCate Grass exemplify divergent regional anchoring strategies. FieldTurf occupies a position tied to North American municipal procurement, while TenCate Grass represents European certification leadership through FIFA- and World Rugby-approved pitch systems. CCGrass sits within the Asia-Pacific volume-driven segment, competing on polyethylene cost structures across export markets. These three anchors illustrate how geographic certification requirements and regional procurement authority reshape competitive positioning without requiring uniform global scale.
| Leading Market Players |
|---|
| Tarkett |
| Shaw Industries Group |
| FieldTurf |
| TenCate Grass |
| CCGrass |
| AstroTurf |
| Act Global |
| SIS Pitches |
| Limonta Sport |
| Others |
Cost & Logistics Intelligence
Ceramic-coated sand and organic coconut-husk infill substitution for crumb rubber is redrawing supply geography toward Southeast Asian mineral processors while compressing pricing premiums for traditional rubber-backed systems. This material transition simultaneously elevates inbound logistics costs from new sourcing nodes and erodes legacy supplier pricing power in established markets.
Pricing Analysis
Long-term performance-guarantee contracts bundling installation, maintenance, and warranty coverage dominate municipal and institutional procurement, displacing pure capital-expenditure transactions. Three-tier pricing structure across FIFA-certified premium, standard institutional, and economy residential levels reflects certification depth and service bundling intensity. Cost compression in economy polyethylene residential tiers is intensifying because Chinese tufting capacity expansion outpaces brand differentiation. School districts and municipal authorities exhibit lowest price sensitivity due to lifecycle cost modeling, while individual homeowners in drought-scaping programs drive hardest bargain negotiation.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability fluctuations from Zhejiang and Jiangsu provinces are elevating landed costs for European sports infrastructure projects. Polyethylene resin supply concentrates in China, Saudi Arabia, and the United States, while specialized FIFA-certified installer networks cluster in Germany, the Netherlands, and the American Southwest. Raw material procurement draws from naphtha-derived ethylene feedstocks, UV-stabilized masterbatch additives, and permeable polyurethane backings. Single-source vulnerability sits with German and Dutch installation contractors for complex stadium certifications. Distribution runs through manufacturer-direct municipal contracting, specialized sports-field construction firms, and landscaping contractor wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified installation technician shortages and captive polymer supply constraints are concentrating competitive advantage among vertically integrated manufacturers with controlled service networks. This capability gap rewards firms that internalize both fiber production and field construction expertise.
For Market Incumbents: Compound certification depth by acquiring FIFA- and World Rugby-accredited installation contractors in Germany and the American Southwest before competitor lock-up accelerates. Prioritize backward integration into polyethylene resin supply through offtake agreements with Saudi Arabian and American Gulf Coast petrochemical producers to defend margin position against feedstock volatility. Bio-based infill reformulation investments represent the critical defensive lever against REACH chemical compliance tightening. For New Entrants and Emerging Players: Aftermarket service contract white-space in Australian and Indian municipal markets offers penetrable entry where incumbents under-serve on ten-year performance guarantees. Target Khelo India program allocations and Smart Cities Mission tenders with BIS-certified polyethylene systems bundled with local installation partnerships. Lead with cooler infill chemistry differentiation and rapid deployment capabilities to bypass entrenched certification hierarchies. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated mid-cap specialists with captive installer networks and circular recycling capabilities. Five-to-ten year viability hinges on EU Green Deal end-of-life recovery infrastructure positioning. Monitor ceramic-coated sand and organic infill adoption rates as the signal indicating which formulation portfolios will retain specification eligibility against tightening chemical disclosure mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Installer Network Acquisition | Captive access to FIFA-certified contractors in Germany and the Netherlands secures municipal stadium contract flow. |
| Bio-Based Infill Reformulation | Coconut-husk and ceramic-coated sand portfolios satisfy California SB 47 and REACH ECHA compliance thresholds. |
| Polyethylene Resin Integration | Upstream control over naphtha-derived feedstocks insulates margin visibility from petrochemical price swings. |
| End-of-Life Recycling Infrastructure | Chemical depolymerization capabilities align with EU Green Deal circular economy mandates and extended producer responsibility. |
| Cooler Infill Technology Licensing | Thermal reflectance coefficient improvements above 0.35 unlock Arizona and Nevada residential drought-scaping demand. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal procurement officers, FIFA-certified field contractors, polyethylene resin procurement managers, sports club facilities directors, and cooler infill technology R&D leads. Secondary validation drew from EPA infill material assessment documentation, ECHA REACH registration databases, California SB 47 regulatory filings, FIFA Quality Programme certification records, and municipal capital improvement program disclosures. Bottom-up volume modeling across fiber chemistry tiers and top-down value reconciliation against disclosed contract values were triangulated to ensure cross-verification.
Across the analysis window, projections integrate polyethylene turf, nylon turf, and hybrid system demand trajectories segmented by sports field, residential landscaping, and municipal application channels. Modeled dimensions include fiber chemistry grade, certification tier, installation architecture, and regional water restriction intensity. CAGRs were derived from installation volume run-rates, replacement cycle analysis, and procurement pipeline assessment across drought-scaping program jurisdictions. Forecast inputs incorporate cooler infill technology diffusion curves and end-of-life recycling infrastructure buildout timelines.
Material uncertainties — petroleum feedstock price volatility, installer certification bottleneck duration, and state-level procurement rule evolution — sit outside the modeled envelope. Forecasts reflect assumptions regarding REACH compliance trajectory stability and municipal budget continuity for capital improvement programs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Portable Kayaks Market
Outdoor & Sports
Global Baseball Gloves Market
Outdoor & Sports
Walkbehind Lawnmower Market
Outdoor & Sports
Hunting Blinds Market
Outdoor & Sports
Camping Beds and Mats Market
Outdoor & Sports
Swimming Pool Liner Market
Outdoor & Sports
Global Artificial Grass Market
Outdoor & Sports
Global Pool Floats Market
Outdoor & Sports
Australia Kids Scooter Market
Outdoor & Sports
Freshwater Fishing Rod Market
Outdoor & Sports
Fishing Tackle Box Market
Outdoor & Sports
Inflatable Pool Market
Outdoor & Sports
Camping Lights and Lanterns Market
Outdoor & Sports
Camping Cookware Market
Outdoor & Sports
Golf Trolley Market
Outdoor & Sports
Kids Scooter Market