
 Sexual Lubricant Market | 2026-2036
Sexual Lubricant Market Size, Share, and Industry Trends Forecast 2026-2036
Sexual Lubricant Market Analysis
Plant-derived glycerin and fermented squalane are consolidating share from petroleum-based formulations, compressing unit costs for mid-tier producers while elevating clean-label premiums. Church & Dwight leverages its household chemistry infrastructure to control raw material sourcing across North American manufacturing. Pjur Group anchors its position through concentrated silicone expertise and Berlin-based formulation R&D. Reckitt Benckiser Group competes through mass-channel distribution density and pharmacy retail partnerships.
Sexual lubricants comprise viscous or gel-phase topical preparations formulated with humectants, polymers, and emollients to reduce friction during intimate contact, typically specified within pH ranges of 3.8 to 4.5 to maintain mucosal compatibility. Water-based formulations dominate volume due to condom compatibility and easy cleanup, though silicone-based variants command margin pools through extended-duration performance and medical-application premiums. Hybrid formats are gaining shelf space as retailers seek to reduce SKU complexity while capturing consumers seeking dual-benefit positioning.
FDA oversight of personal lubricants as Class II medical devices shapes formulation stability requirements and labeling claims in the United States, while REACH compliance in Europe restricts certain preservatives and drives substitution toward bio-based alternatives. The EU Medical Device Regulation extends scrutiny to lubricants marketed with therapeutic indications, tightening market access for non-compliant suppliers. Stakeholders must monitor evolving classification thresholds that could resegment competitive boundaries between cosmetic and medical-grade positioning.
Market Dynamics
Formulation chemistry is pivoting toward bio-based humectants as REACH restrictions on petroleum-derived preservatives force reformulation cycles across European manufacturing. This single regulatory pressure is redrawing raw material sourcing networks and compressing margins for suppliers unable to secure certified plant-derived alternatives.
Growth Catalysts
- REACH compliance deadlines:The EU's 2025-2027 restriction schedules on synthetic preservatives are accelerating substitution toward fermented glycerin and squalane derivatives, pulling through capacity investments in bio-refinery infrastructure.
- Medical device reclassification:The EU Medical Device Regulation's extension to therapeutic-indication lubricants is consolidating demand around certified manufacturers with notified-body relationships, squeezing out cosmetic-grade suppliers.
- Pharmacy retail expansion:German pharmacy chains are expanding intimate health shelf space as patient comfort protocols standardize across urology and gynecology clinics, creating pull-through for pharmacy-grade SKUs.
Market Restraints
- Silicone feedstock concentration:Medical-grade silicone fluid supply concentrates among three German and US specialty chemical producers, exposing formulators to allocation risk during semiconductor-industry demand spikes.
- Preservative substitution costs:Bio-based preservation systems cost 40-60% more per kilogram than paraben alternatives, compressing gross margins for mid-tier water-based formulations.
- Condom compatibility testing:Latex integrity validation requires ISO 4074 compliance expenditure that blocks small regional formulators from condom-partnership distribution.
Strategic Opportunities
- Telehealth channel integration:Direct-to-patient platforms are bypassing pharmacy retail for discrete subscription delivery, capturing consumers who prioritize privacy over immediate availability.
- Hybrid format innovation:Water-silicone hybrid chemistries are capturing shelf space from dual-SKU households, reducing retailer complexity while commanding premium positioning.
- Menopause wellness vertical:Vaginal atrophy symptom management is expanding lubricant use cases beyond sexual application into daily comfort regimens, opening clinical endorsement pathways.
Industry Challenges
- Formulation stability expertise:pH-buffered aqueous systems require cosmetic chemists with mucosal-biocompatibility specialization, a talent pool concentrated among Swiss and German contract manufacturers.
- Notified-body queue delays:EU MDR certification timelines stretch 18-24 months for Class IIb intimate devices, freezing product pipeline velocity for non-compliant suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sexual Lubricant Market |
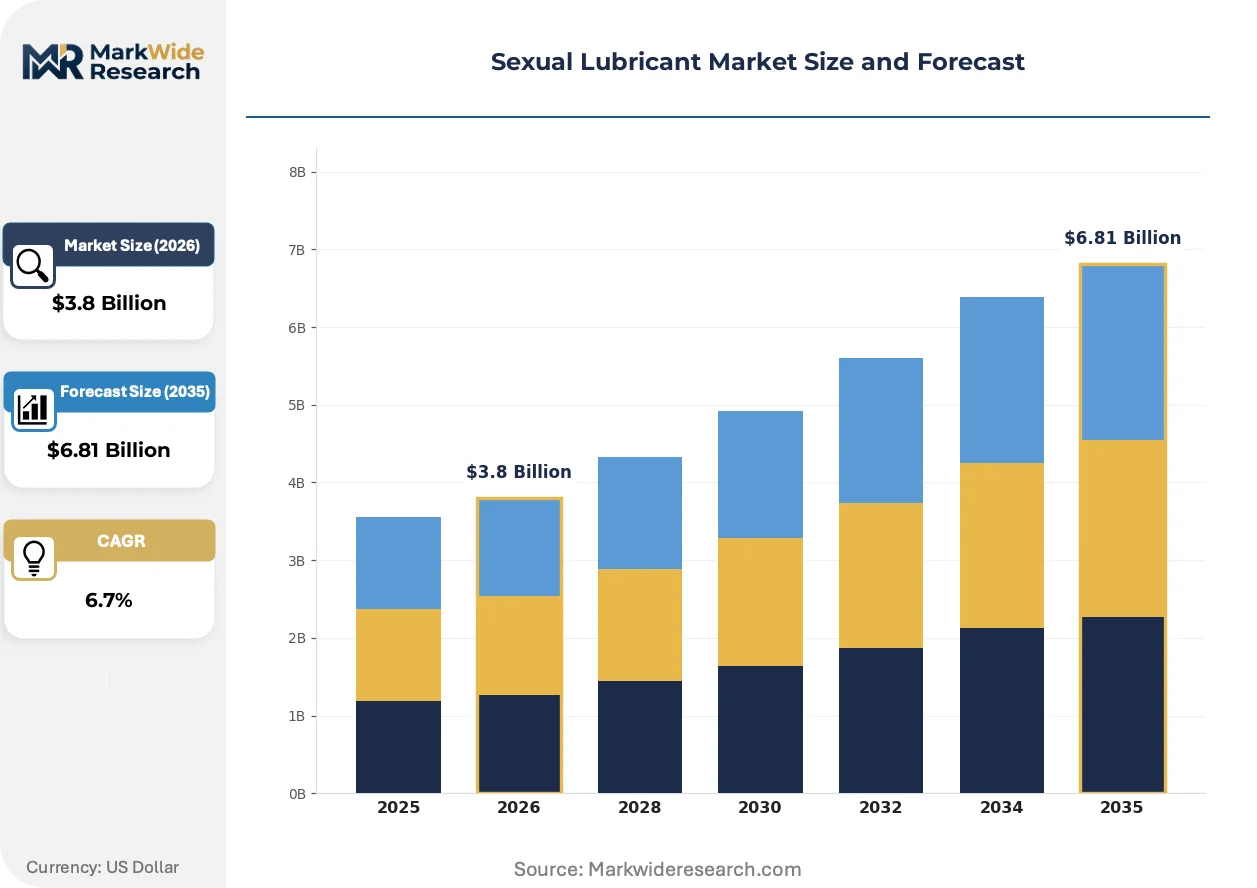
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Silicone-Based, Oil-Based, Hybrid End User: Individuals, Couples, Retailers, Wholesalers Application: Intimate Use, Massage, Medical, Recreational Packaging Type: Single-Use Packets, Bottles, Tubes, Pump Dispensers |
| Companies Covered | Reckitt Benckiser Group, Church & Dwight, LifeStyles Healthcare, BioFilm, Lovehoney Group, Mayer Laboratories, Trigg Laboratories, Pjur Group, Good Clean Love, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sexual Lubricant Market Emerging Trajectories
Bio-fermentation platforms are displacing petrochemical feedstocks across personal care supply chains, with intimate lubricants serving as an early-adopter category due to mucosal-safety sensitivities. This shift is compressing legacy supplier relationships while elevating clean-label premiums.
Fermented squalane derived from sugarcane feedstock is expanding into premium water-based formulations as Brazilian and European biotechnology suppliers scale production. Gynecology clinics in Germany and France are specifying this material for patient samples, compressing acceptance timelines for conventional petroleum-derived emollients. The technology is expanding into mid-tier positioning as unit costs fall below silicone fluid parity.
REACH Annex XVII restrictions on isothiazolinone preservatives are forcing reformulation of shelf-stable aqueous products across European manufacturing. Formulators are substituting toward phenoxyethanol and organic acid systems, with stability-testing burdens falling heaviest on small regional suppliers lacking in-house microbiology labs. German notified bodies are reporting 30% increases in preservation-change technical file submissions.
Subscription-based replenishment is displacing pharmacy impulse purchasing among urban consumers aged 25-40. Direct-to-consumer platforms in France and the UK are capturing repeat-purchase loyalty through discrete packaging and auto-ship algorithms, forcing pharmacy retailers to expand private-label offerings or cede volume. The shift is most visible in London and Paris metropolitan zones where same-day delivery infrastructure concentrates.
Sexual Lubricant Market Segmentation
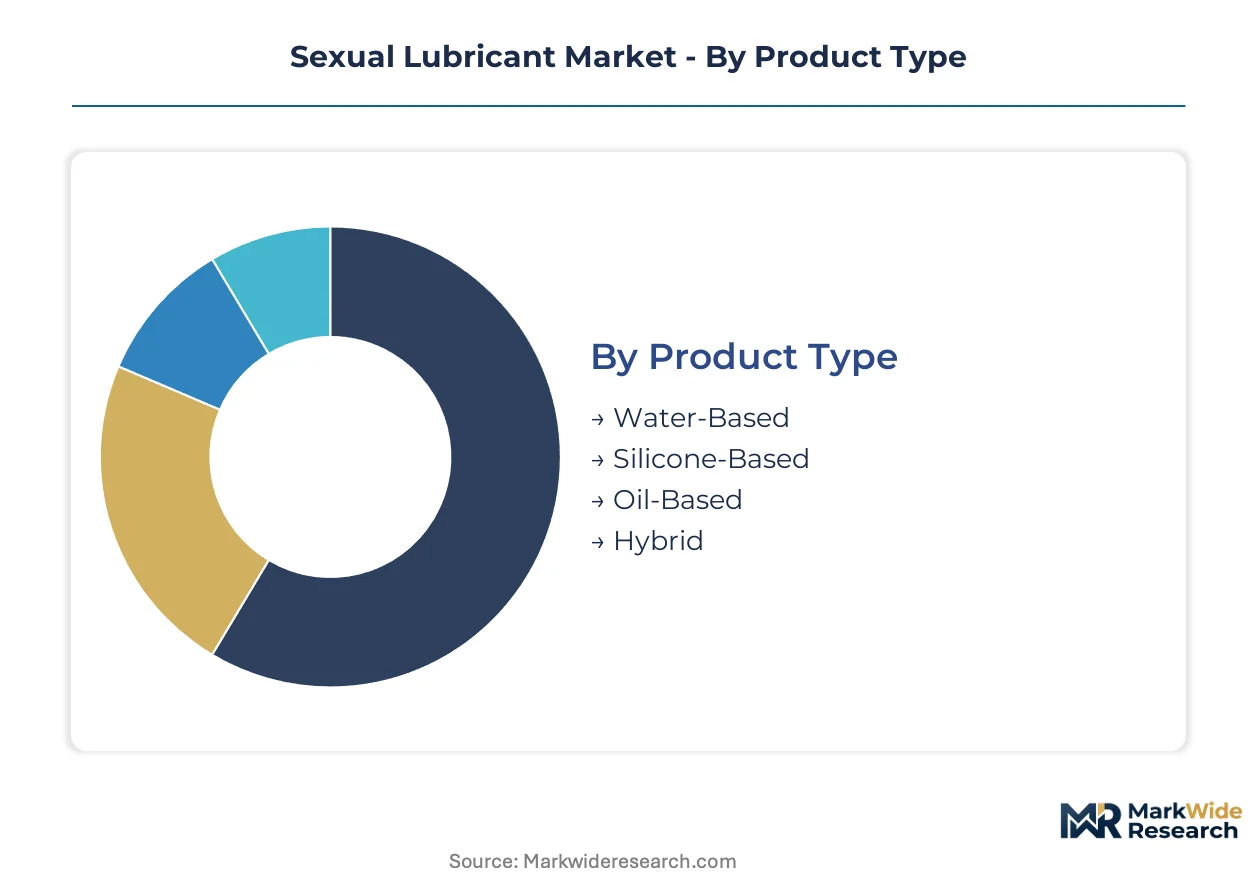
Segmentation in the sexual lubricant market separates volume-scale commodity production from premium-positioned specialty formulations. Distinct buyer requirements across intimacy, medical, and wellness applications create parallel demand tracks with divergent margin structures and regulatory obligations.
Product Type:
Buyers differentiate primarily by duration requirement, cleanup preference, and condom compatibility rather than price sensitivity alone.
- Water-Based:Aqueous formulations employing glycerin, cellulose derivatives, and pH buffers dominate pharmacy and mass retail distribution. German urology clinics specify these for patient compliance programs due to condom compatibility and mucosal pH alignment, though preservative substitution costs under REACH compress margins for regional European formulators.
- Silicone-Based:Dimethicone and cyclomethicone fluid systems deliver extended lubricity without reapplication. Demand concentrates in medical-device partnerships and premium intimacy retail, where Berlin-based formulation houses command pricing power through German silicone feedstock relationships.
- Oil-Based:Plant-derived and petroleum emollient systems serve massage and non-latex intimate applications. Coconut and jojoba variants gain traction in clean-label wellness channels despite latex degradation limitations.
- Hybrid:Water-dispersible silicone emulsions merge cleanup convenience with prolonged performance. French and UK direct-to-consumer platforms are expanding hybrid SKU representation to reduce household multi-product purchasing.
Volume sits with water-based formulations; growth tilts toward hybrid chemistries capturing dual-benefit positioning.
End User:
Channel structure separates discrete direct purchasing from institutional procurement with divergent packaging and certification requirements.
- Individuals:Single consumers purchasing through pharmacy, mass retail, or subscription platforms. Auto-replenishment algorithms at Paris and London metro direct-to-consumer services are displacing impulse pharmacy purchasing among urban professionals aged 25-40.
- Couples:Dual-user households showing elevated willingness to pay for premium positioning and aesthetic packaging. This segment drives demand for gift-format presentations and travel-compatible sizing.
- Retailers:Pharmacy chains, drugstores, and intimacy boutiques sourcing through wholesale or direct manufacturer relationships. German pharmacy retail is expanding intimate health shelf space as clinic protocols standardize patient comfort recommendations.
- Wholesalers:Distribution intermediaries serving independent pharmacies, hotel amenities programs, and clinical sample suppliers. Consolidation among European pharmaceutical wholesalers is narrowing supplier access for small regional formulators.
Procurement volume concentrates with retailers; subscription-driven individual purchasing is expanding most quickly.
Application:
Regulatory classification separates cosmetic-grade intimacy products from medical-device therapeutic indications with divergent compliance burdens.
- Intimate Use:Primary sexual wellness application requiring pH-buffered mucosal compatibility. FDA Class II medical device oversight in the United States and EU MDR extension to therapeutic claims are consolidating demand around certified manufacturers with notified-body relationships.
- Massage:Bodywork and wellness applications emphasizing glide properties over mucosal safety specifications. This segment escapes medical-device classification but faces clean-label ingredient scrutiny in European wellness retail.
- Medical:Vaginal atrophy symptom management, surgical lubrication, and diagnostic procedure applications. Gynecology clinics in Germany and France are specifying fermented squalane formulations for patient samples, compressing acceptance timelines for petroleum-derived alternatives.
- Recreational:Novelty and lifestyle positioning emphasizing sensory experience and aesthetic packaging. This segment shows highest channel fragmentation across adult retail, e-commerce, and hospitality amenities.
Intimate use commands current volume share; medical applications are gaining share fastest through menopause wellness vertical expansion.
Packaging Type:
Usage context and discretion requirements separate single-occasion portability from household-scale economy purchasing.
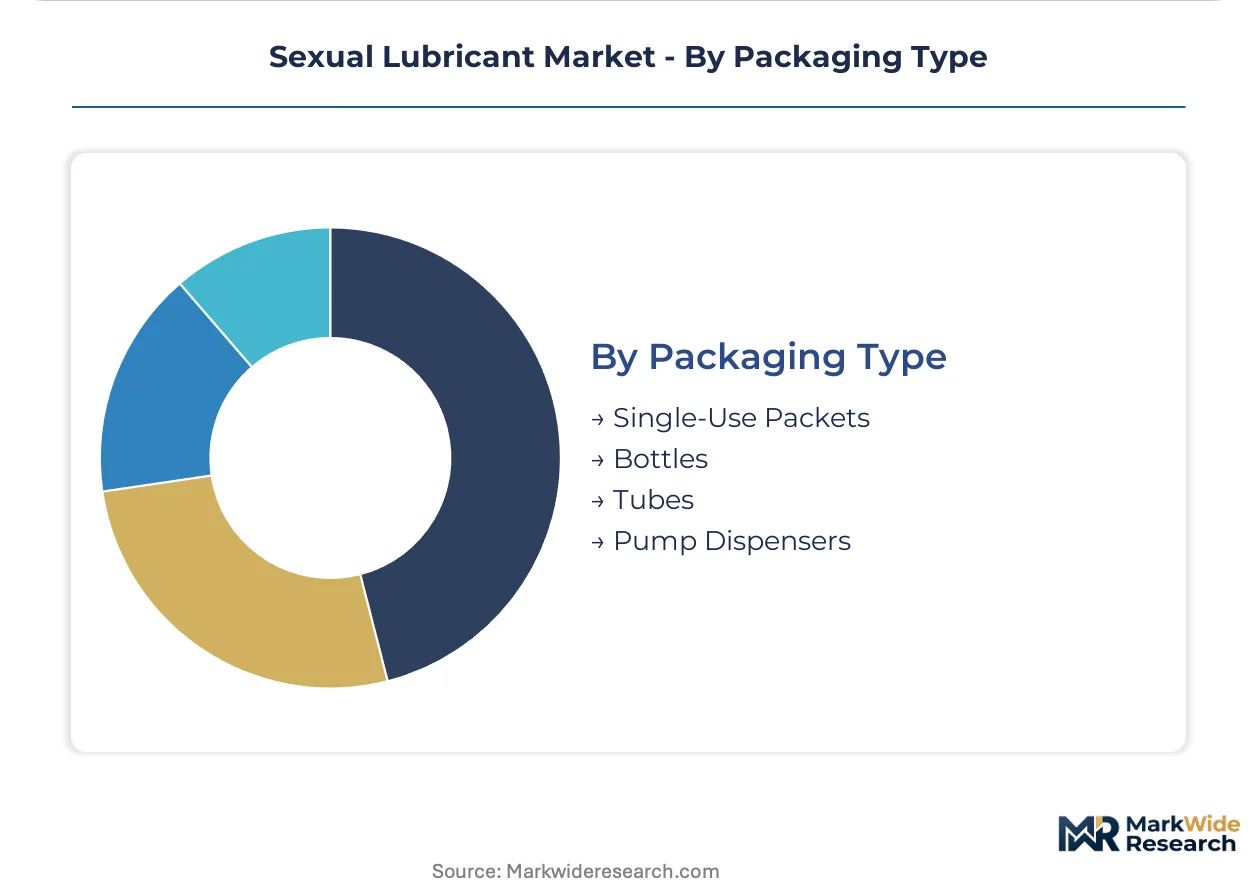
- Single-Use Packets:Foil or laminate sachets delivering metered doses for travel, clinical sampling, and hospitality amenities. Hotel and airline amenity programs in France and the UK are standardizing packet formats for brand consistency.
- Bottles:Rigid or squeeze containers for household replenishment purchasing. Standard pharmacy and mass retail format with lowest unit packaging cost but highest shipping weight burden.
- Tubes:Collapsible aluminum or laminate cylinders combining portability with multi-dose capacity. Preferred format for premium positioning and travel retail.
- Pump Dispensers:Metered-dose systems reducing contamination risk and enabling one-handed application. German pharmacy-grade SKUs increasingly specify pump formats for clinical recommendation alignment.
Bottle formats anchor current volume; pump dispensers are expanding most steeply through pharmacy-grade certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates pharmacy-grade demand through its clinic-protocol standardization, while the United States and United Kingdom drive direct-to-consumer channel innovation. France and Japan complete the geographic footprint with distinct regulatory and retail specialization patterns.
United States
FDA Class II medical device classification shapes formulation stability requirements and labeling claims for intimate-use products. The agency's oversight compresses market access for non-compliant suppliers while consolidating demand around certified manufacturers. California-based direct-to-consumer platforms are capturing subscription-driven repeat purchasing among urban professionals.
Germany
Pharmacy chains are expanding intimate health shelf space as urology and gynecology clinics standardize patient comfort protocols. REACH Annex XVII restrictions on synthetic preservatives are accelerating reformulation toward bio-based alternatives among domestic formulators. Berlin-based formulation houses command pricing power through concentrated silicone feedstock relationships.
United Kingdom
London metropolitan direct-to-consumer services are displacing impulse pharmacy purchasing through discrete packaging and auto-ship algorithms. The Medicines and Healthcare products Regulatory Agency extends scrutiny to lubricants marketed with therapeutic indications. Subscription platforms in the capital are capturing repeat-purchase loyalty through same-day delivery infrastructure.
France
Paris direct-to-consumer channels are expanding hybrid SKU representation to reduce household multi-product purchasing. ANSM notification requirements for medical-device classification tighten market access for cosmetic-grade suppliers. Gynecology clinics in the Île-de-France region are specifying fermented squalane formulations for patient samples.
Japan
Pharmaceutical Affairs Law oversight creates parallel cosmetic and quasi-drug classification tracks for intimate wellness products. METI guidance on bio-based personal care ingredients is accelerating substitution toward plant-derived humectants. Tokyo-based retailers are expanding clean-label intimate health shelf space as consumer safety consciousness intensifies.
Sexual Lubricant Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmacy-grade certification consolidating demand around notified-body relationships while mass-channel distribution rewards scale economies. The vendor base organizes into three strategic archetypes: household chemistry conglomerates leveraging raw material sourcing infrastructure, concentrated silicone specialists anchoring premium positioning, and direct-to-consumer platforms capturing subscription loyalty. Dominant competitive moves include telehealth channel integration bypassing traditional pharmacy retail and hybrid format innovation reducing retailer SKU complexity.
Among mass-channel distributors, Reckitt Benckiser Group exemplifies the pharmacy retail partnership archetype, while Church & Dwight occupies a position representing household chemistry infrastructure players. Pjur Group anchors the concentrated silicone specialist tier through Berlin-based formulation capabilities.
| Leading Market Players |
|---|
| Reckitt Benckiser Group |
| Church & Dwight |
| LifeStyles Healthcare |
| BioFilm |
| Lovehoney Group |
| Mayer Laboratories |
| Trigg Laboratories |
| Pjur Group |
| Good Clean Love |
| Others |
Supply Flow & Price Mechanics
Captive silicone sourcing among Berlin-based formulation houses anchors premium positioning while compressing margin pools for water-based competitors dependent on volatile glycerin spot markets. REACH-driven preservative substitution costs flow directly into mid-tier pricing, forcing a bifurcation between pharmacy-certified premiums and mass-channel commodities.
Pricing Analysis
Volume concentrates in water-based pharmacy formats where condom compatibility drives standardization, while margins pool in silicone-based medical-device partnerships commanding extended-duration premiums. Certification grade separates pharmacy-grade pump dispensers from mass-market squeeze bottles, with FDA Class II compliance adding measurable cost layers. Cost compression in mid-tier water-based formulations intensifies as bio-based preservation systems displace paraben alternatives. Individual subscription purchasers show lowest price sensitivity, while hospital procurement committees and pharmaceutical wholesalers negotiate hardest on volume contracts.
Supply Chain Analysis
Dual-sourcing mandates from German pharmacy chains and French hospital systems require qualified backup suppliers for silicone fluids and fermented squalane, extending qualification timelines. Medical-grade dimethicone concentrates among German and US specialty chemical producers, while Brazilian biotechnology suppliers scale sugarcane-derived squalane. Feedstock allocation risk spikes during semiconductor-industry demand surges. Distribution runs through consolidated pharmaceutical wholesalers in Germany and direct-to-consumer platforms in France and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-fermentation platforms are displacing petrochemical feedstocks across intimate lubricant supply chains, with plant-derived squalane and glycerin substituting for petroleum-based emollients and preservatives. This technology transition compresses legacy supplier relationships while elevating clean-label premiums.
For Market Incumbents: Hedge silicone feedstock exposure through long-term offtake agreements with German specialty chemical producers before semiconductor demand spikes trigger allocation freezes. Secure notified-body relationships for EU MDR compliance to defend pharmacy-grade positioning against cosmetic-grade entrants facing 18-24 month certification queues. Prioritize backward integration into bio-refinery partnerships as REACH Annex XVII restrictions deepen. For New Entrants and Emerging Players: Telehealth subscription platforms offer the lowest barrier to pharmacy bypass, capturing urban professionals aged 25-40 through discrete auto-replenishment algorithms in London and Paris metropolitan zones. Target menopause wellness applications with fermented squalane formulations specified by French and German gynecology clinics. Pursue direct-to-consumer launch with hybrid water-silicone chemistry to reduce household SKU duplication. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to household chemistry conglomerates seeking intimate health vertical expansion. Five-to-ten year viability hinges on notified-body certification density rather than brand equity alone. Watch German pharmacy chain private-label expansion rates as the inflection signal for margin compression in mass-channel positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Notified-Body Certification Investment | EU MDR compliance locks in pharmacy-grade access while freezing out cosmetic-tier competitors. |
| Bio-Refinery Supply Agreement | Fermented squalane offtake secures REACH-compliant feedstock ahead of petroleum-derived substitution deadlines. |
| Telehealth Channel Integration | Direct-to-patient platforms bypass pharmacy retail capture in Paris and London metro zones. |
| Hybrid Format R&D Program | Water-silicone emulsions reduce retailer SKU complexity while commanding dual-benefit premiums. |
| Menopause Wellness Line Extension | Vaginal atrophy positioning opens clinical endorsement pathways beyond sexual application. |
Methodological Framework
Trade publications, customs databases, and regulatory filing repositories formed the secondary backbone, cross-referenced against primary interviews with formulation chemists at contract manufacturers, procurement leads at German pharmacy chains, regulatory affairs specialists navigating EU MDR pathways, and category buyers at French direct-to-consumer platforms. Bottom-up and top-down triangulation validated volume estimates across product tiers.
Bottom-up modeling anchored forecasts to individual SKU velocity through pharmacy retail audits and subscription platform disclosures, while top-down analysis cross-checked against macro-level personal care expenditure patterns. Segmentation dimensions included formulation chemistry, certification grade, distribution channel, and end-use application. CAGRs derived from fitted growth curves calibrated to regulatory milestone impacts and feedstock substitution timelines.
Inputs from notified-body technical file databases and pharmaceutical wholesale transaction records were available through the study window; gaps in small regional formulator cost structures introduce uncertainty bands around margin compression estimates. Deviation in REACH enforcement intensity or silicone feedstock allocation priority would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Insoles Market
Personal Grooming Products
Massage Fascia Gun Market
Personal Grooming Products
Organic Tampons Market
Personal Grooming Products
Heated Razor Starter Kit Market
Personal Grooming Products
Asia Pacific Hair Styling Tools Market
Personal Grooming Products
Shoe Insert Market
Personal Grooming Products
Baby Oil Market
Personal Grooming Products
United States Electric Toothbrush Market
Personal Grooming Products
Electric Massagers Market
Personal Grooming Products
Latin America Professional Liquid Soap Market
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Electric Toothbrush Market
Personal Grooming Products
Global Beard Balm Market
Personal Grooming Products
Insect Repellent Wipes Market
Personal Grooming Products
Toothbrush Market
Personal Grooming Products
Antibacterial Soap Market