
 Freshwater Fishing Rod Market | 2026-2036
Freshwater Fishing Rod Market Size, Share, and Industry Trends Forecast 2026-2036
Freshwater Fishing Rod Market Insights
Rod warranty and repair subscription programs is repositioning how manufacturers monetize customer relationships beyond the initial purchase. Shimano Inc. leverages its extensive service network across North American retail partners to sustain repeat engagement. Daiwa Corporation anchors its competitive stance through proprietary blank technology and domestic Japanese manufacturing scale. St. Croix Rods differentiates via American-made positioning and direct-to-consumer channel control.
A freshwater fishing rod is a tapered, flexible lever designed to cast lines, absorb fish strikes, and enable controlled retrieval; modern variants employ carbon fiber pre-preg layups with modulus ratings from 30 to 80 million psi to optimize strength-to-weight ratios for specific lure weights and fighting techniques. Spinning rods dominate volume sales due to their accessibility for novice anglers across diverse freshwater species, while fly rods command premium positioning within specialized trout and salmon fisheries. Carbon fiber and graphite materials capture the fastest growth trajectory as anglers pursue lighter blanks with enhanced sensitivity, whereas fiberglass maintains stable demand among traditionalist segments prioritizing durability over responsiveness.
The U.S. Fish and Wildlife Service administers Sport Fish Restoration excise taxes that fund habitat programs indirectly stimulating equipment demand, while EPA regulations on resin emissions shape domestic manufacturing compliance costs. Japan's Ministry of Economy, Trade and Industry (METI) oversees industrial standards for carbon fiber production that influence blank sourcing decisions across Asia-Pacific supply chains. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and state-level lead restrictions in U.S. jurisdictions as these regulations increasingly dictate material specifications and market access requirements for imported finished goods.
Market Dynamics
Carbon fiber modulus differentiation is fragmenting competitive positioning across price tiers, as Japanese Toray T1100G and intermediate-modulus alternatives force manufacturers to choose between premium sensitivity credentials and accessible performance positioning.
Growth Catalysts
- Angler demographic expansion:Tournament bass fishing circuits in the United States and China are accelerating equipment replacement cycles among competitive participants.
- REACH compliance adaptation:European Union chemical regulations on epoxy resin formulations are compelling manufacturers to reformulate blank adhesives with lower VOC profiles.
- Direct-to-consumer channel maturation:Specialized rod builders in Taiwan are bypassing traditional retail markups through Instagram and TikTok commerce platforms.
Market Restraints
- Carbon fiber supply concentration:Toray Industries, Mitsubishi Chemical, and Teijin control approximately 70% of global aerospace-grade pre-preg supply, constraining blank manufacturers' sourcing flexibility.
- Import tariff friction:Section 301 duties on Chinese-manufactured finished rods elevate landed costs for U.S. distributors by 10-25% depending on HS code classification.
- Fiberglass substitution ceiling:Traditionalist segments in southern U.S. crappie and catfish fisheries resist modulus-driven sensitivity premiums, capping graphite penetration in volume segments.
Strategic Opportunities
- Indian freshwater aquaculture adjacent:Carp culture pond management creates rod-and-reel demand among commercial operators transitioning to recreational angling tourism.
- Extended producer responsibility frameworks:EU battery directive analogs for composite materials could reward manufacturers with closed-loop recycling programs through preferential market access.
- Subscription warranty platforms:Annual repair-and-replacement programs transform one-time transactions into recurring revenue relationships with high-lifetime-value tournament anglers.
Industry Challenges
- Composite layup technician scarcity:Master rod builders with 15+ years of mandrel-wrapping experience command premium wages in Osaka and Dongguan manufacturing clusters.
- Multi-jurisdiction lead compliance:California Proposition 65 and pending New York State restrictions on fishing tackle components require SKU-level traceability systems.
- Legacy ERP integration:Small-batch custom rod builders struggle to connect Shopify storefronts with carbon fiber inventory management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freshwater Fishing Rod Market |
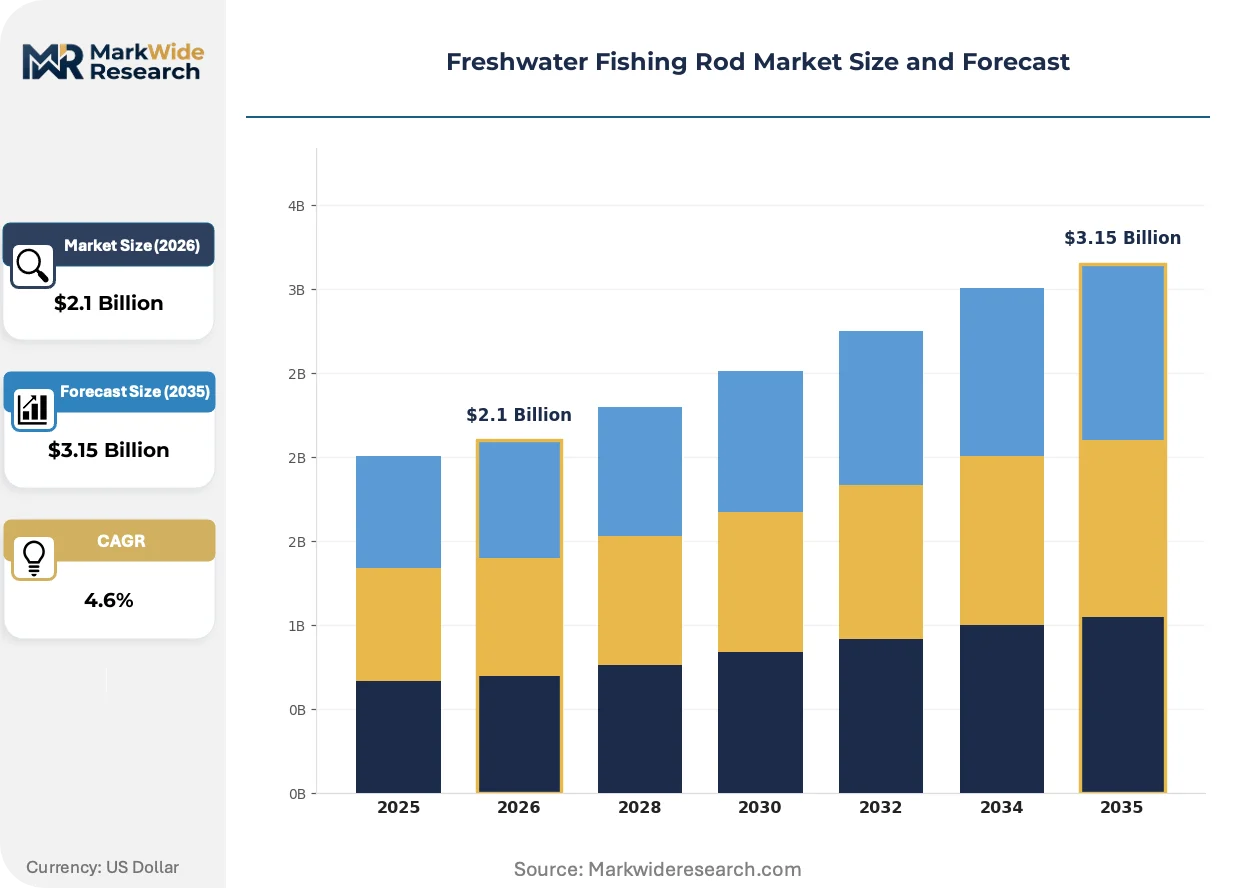
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spinning Rods, Baitcasting Rods, Fly Rods, Trolling Rods Material: Carbon Fiber, Fiberglass, Graphite, Composite Length: Short Rods, Medium Rods, Long Rods, Ultra Long Rods Action: Fast Action, Moderate Action, Slow Action, Moderate-Fast Action |
| Companies Covered | Shimano Inc., Daiwa Corporation, St. Croix Rods, Abu Garcia, G. Loomis Inc., Orvis Company, Ugly Stik, Shakespeare, Eagle Claw, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freshwater Fishing Rod Market Trends and Innovations
Material science breakthroughs and regulatory chemistry mandates are converging to redefine blank construction protocols, while digital channels reshape how specialized equipment reaches end-users.
Ultra-high-modulus carbon fiber pre-preg is overtaking intermediate-modulus standards in premium freshwater bass rod segments. Competitive tournament anglers in the United States and Japan are adopting 65-80 Msi blanks for enhanced bite detection during deep-structure fishing. This modulus escalation is compressing profit margins for second-tier manufacturers lacking Toray direct supply relationships.
EPA resin emission standards under the National Emission Standards for Hazardous Air Pollutants are forcing domestic blank manufacturers to invest in thermal oxidizer systems or outsource curing to compliant facilities. The compliance burden falls disproportionately on small-batch American custom builders versus offshore competitors with consolidated finishing operations. Texas and Florida rod shops are responding by forming cooperative purchasing agreements for shared curing oven capacity.
Social commerce discovery is displacing traditional pro-staff influencer models among younger anglers. TikTok Shop and Instagram Checkout enable direct manufacturer-to-consumer relationships that bypass tackle shop distribution entirely. This channel compression is most visible in the Japanese domestic market, where younger trout anglers purchase JDM-labeled rods through LINE Shopping integrations rather than legacy retail chains.
Freshwater Fishing Rod Market Segmentation
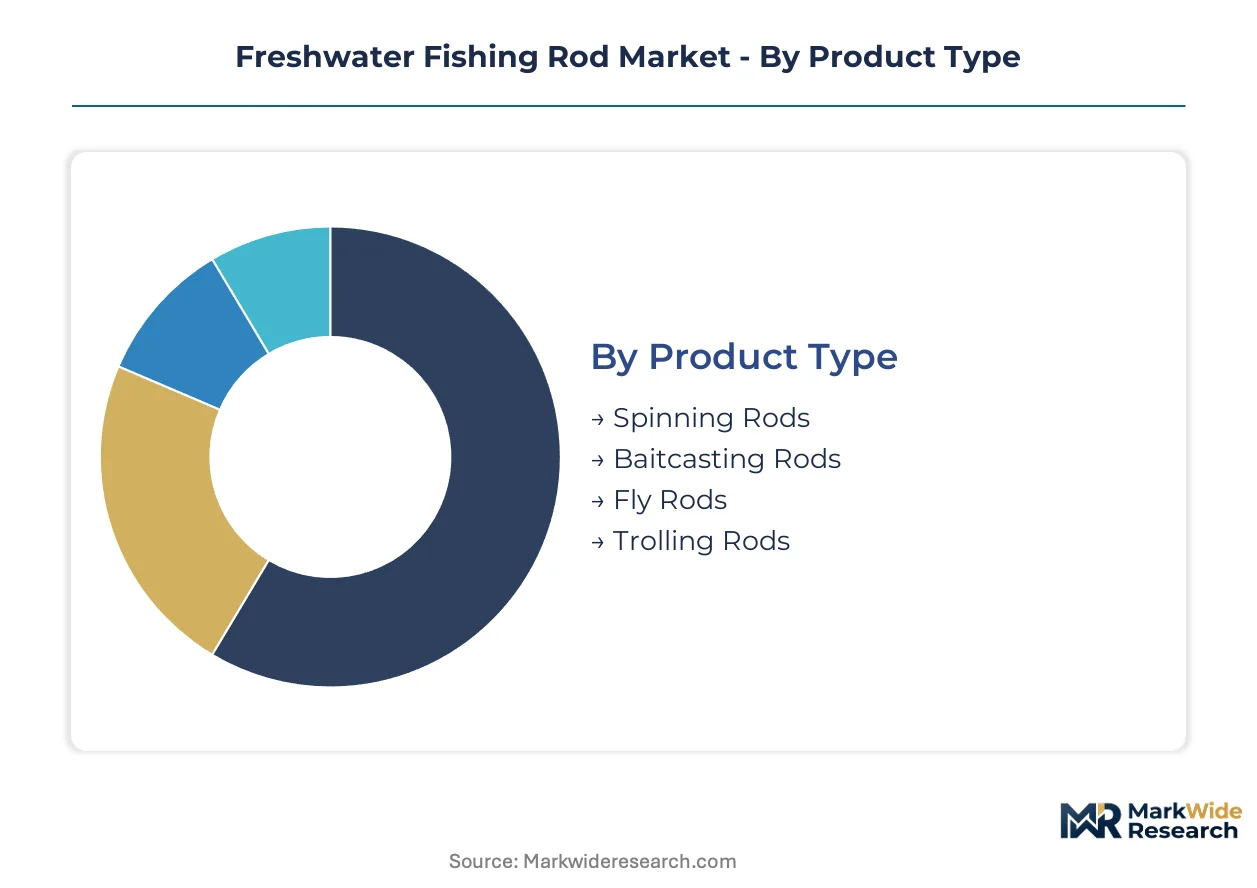
Freshwater fishing rod segmentation reflects divergent angling techniques, material science capabilities, and performance specifications that manufacturers must balance against cost targets. Rod builders configure blank modulus, taper profiles, and guide spacing to match specific lure presentations and fighting styles.
Product Type:
Technical sophistication and casting mechanics differentiate competitive positioning across rod categories.
- Spinning Rods:Open-face reel mounting and larger guide trains accommodate monofilament and braided line versatility for novice to intermediate anglers. Volume demand concentrates in United States bass fisheries and Japanese mountain stream trout operations where accessibility drives replacement frequency.
- Baitcasting Rods:Trigger-style grips and low-profile guide spacing optimize for accurate lure placement and power fishing techniques. Tournament circuits in Texas and Guangdong Province accelerate equipment turnover as competitive anglers pursue sensitivity advantages.
- Fly Rods:Specialized taper designs load line weight classes for precise dry-fly and nymph presentations.
- Trolling Rods:Heavy-duty blank construction and roller guides withstand downrigger and planer board stress.
Mature deployment sits with spinning configurations. Newer deployment is concentrated in baitcasting variants.
Material:
Blank composition determines strength-to-weight ratios, vibration transmission, and manufacturing cost structures.
- Carbon Fiber:Toray T1100G and intermediate-modulus pre-preg layups deliver 65-80 Msi ratings for tournament-grade sensitivity. Premium positioning in Japanese domestic market bass rods and competitive angler segments in Florida drives fastest expansion.
- Graphite:IM6 through IM12 modulus classifications balance performance and accessibility for dedicated recreational anglers.
- Fiberglass:E-glass and S-glass composites maintain durability advantages for crappie and catfish specialists in southern United States waters.
- Composite:Carbon-glass hybrid layups blend sensitivity with forgiveness for multi-species generalists.
Established volume sits with graphite formulations. Emerging preference concentrates in carbon fiber variants.
Length:
Rod span dictates casting distance leverage, transportability constraints, and storage logistics.
- Medium Rods:Six-foot-six to seven-foot configurations dominate retail volume through versatility across dock, bank, and boat fishing scenarios.
- Long Rods:Seven-foot-six to eight-foot spans enable extended casting reach for surf-influenced freshwater applications and kayak angling.
- Short Rods:Five-foot to six-foot compact designs serve brush-lined creek fishing and airline travel constraints.
- Ultra Long Rods:Eight-foot-six and longer blanks target specialized Euro-nymphing and long-distance casting disciplines.
Mainstream adoption centers on medium lengths. Specialized deployment is expanding in long rod configurations.
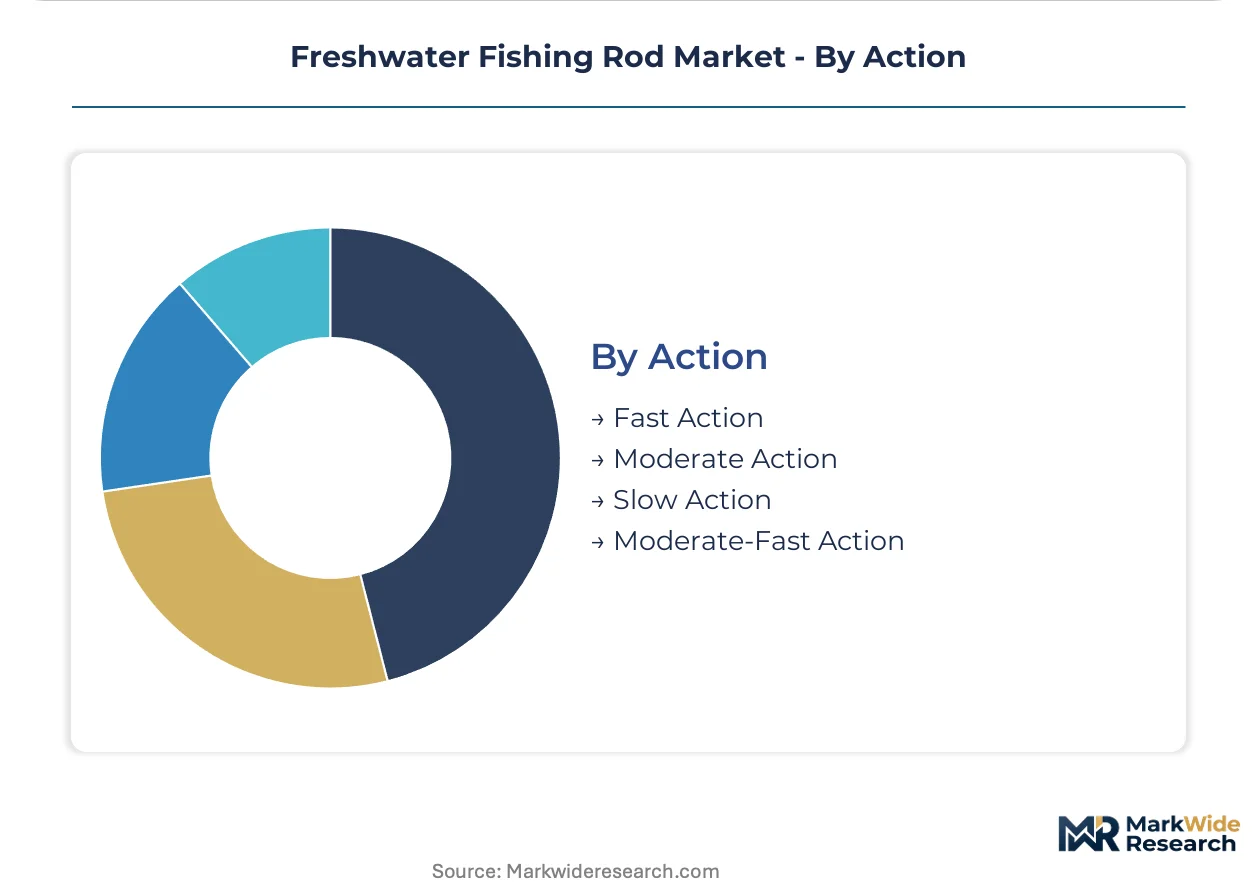
Action:
Blank flex characteristics determine hook-setting efficiency and fish-fighting control.
- Fast Action:Tip-flex designs transmit immediate hook penetration for single-hook lure presentations. Bass tournament anglers in Alabama and California fisheries prioritize this responsiveness for worm and jig techniques.
- Moderate-Fast Action:Blended taper profiles accommodate treble-hook crankbaits and spinnerbaits with reduced pull-out risk.
- Moderate Action:Mid-blank flex curves cushion light line and treble-hook applications for panfish and trout.
- Slow Action:Full-flex parabolic bends protect tippet integrity in delicate dry-fly presentations.
Volume concentration rests with fast action designs. Niche expansion is occurring in moderate-fast configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing gravity clusters in East Asian carbon fiber hubs, while consumption concentrates in North American and Japanese recreational fisheries. This geographic split shapes sourcing strategies and regulatory compliance burdens across the value chain.
United States
Tournament bass fishing circuits in Texas and Florida accelerate equipment replacement cycles among competitive anglers. The U.S. Fish and Wildlife Service administers Sport Fish Restoration excise taxes that fund habitat programs indirectly stimulating equipment demand. Rod assembly operations concentrate in Wisconsin and South Carolina manufacturing clusters serving domestic retail distribution.
Japan
Domestic mountain stream trout fisheries sustain specialized JDM rod demand among dedicated recreational anglers. The Ministry of Economy, Trade and Industry oversees industrial standards for carbon fiber production that influence blank sourcing decisions across Asia-Pacific supply chains. Osaka-based manufacturing clusters house master rod builders with specialized mandrel-wrapping expertise.
China
Competitive angling tournaments in Guangdong Province expand equipment turnover among bass fishing participants. EPA-equivalent emissions standards under the Ministry of Ecology and Environment shape resin curing compliance costs for domestic blank manufacturers. Dongguan production clusters supply intermediate-modulus pre-preg layups for global rod assembly operations.
Taiwan
Specialized rod builders leverage Instagram and TikTok commerce platforms to bypass traditional retail markups in direct-to-consumer channels. Bureau of Standards, Metrology and Inspection certifications govern carbon fiber quality specifications for export-oriented manufacturers. Taichung industrial districts host consolidated finishing operations with thermal oxidizer compliance advantages.
Freshwater Fishing Rod Market Competitive Landscape
Top-tier vendors anchor premium positioning through proprietary blank technology, while mid-tier specialists compete on manufacturing scale and channel access. The vendor base stratifies across three tiers: integrated carbon fiber-to-rod manufacturers, blank specialists supplying third-party assemblers, and retail-private-label operators. Two strategic archetypes dominate: technology licensors leveraging materials science IP, and channel controllers owning direct consumer relationships. Competitive moves concentrate on strategic partnerships with carbon fiber suppliers and geographic expansion through e-commerce platforms.
Within the integrated manufacturing tier, Shimano Inc. and Daiwa Corporation exemplify vertical control from raw material sourcing through retail service networks. St. Croix Rods occupies a position representing American-made positioning and direct-to-consumer channel strategies. These three entities anchor distinct competitive vectors: Japanese industrial scale, proprietary domestic manufacturing, and regional brand authenticity.
| Leading Market Players |
|---|
| Shimano Inc. |
| Daiwa Corporation |
| St. Croix Rods |
| Abu Garcia |
| G. Loomis Inc. |
| Orvis Company |
| Ugly Stik |
| Shakespeare |
| Eagle Claw |
| Others |
Pricing and Supply Chain Analysis
EPA National Emission Standards for Hazardous Air Pollutants compliance gates qualified blank manufacturing capacity and premium-tier pricing access, as thermal oxidizer investments separate compliant domestic producers from tariff-exposed offshore alternatives serving cost-sensitive volume segments.
Pricing Analysis
Margin tightening in economy-tier finished rods reflects Section 301 tariff exposure on Chinese-manufactured blanks and downstream distribution markups. Three-tier pricing structure across premium carbon fiber, intermediate graphite, and economy fiberglass levels stratifies by modulus rating and domestic assembly credentials. Shimano and Daiwa command brand premiums through proprietary Toray T1100G supply relationships. Tournament anglers exhibit lowest price sensitivity; novice spinning rod buyers in mass retail channels drive cost-down pressure.
Supply Chain Analysis
Master rod builder scarcity in Osaka and Dongguan manufacturing clusters constrains high-modulus blank output expansion. Carbon fiber pre-preg supply concentrates in Japan, Taiwan, and China, with Toray Industries, Mitsubishi Chemical, and Teijin anchoring aerospace-grade feedstock. Blank curing depends on thermal oxidizer-equipped facilities facing EPA compliance costs. Single-source vulnerability sits with Toray T1100G for premium tournament-grade rods. Distribution runs through tackle shop retail networks, direct-to-consumer social commerce, and OEM private-label channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around carbon fiber supply access and compliance-capable manufacturing scale, with REACH adaptation costs and EPA emission standards forcing sub-scale custom builders toward acquisition or exit.
For Market Incumbents: Hedge against Toray supply concentration by securing intermediate-modulus alternatives from Mitsubishi Chemical or Teijin for mid-tier product lines. Deepen backward integration into mandrel-wrapping technician training programs in South Carolina and Wisconsin assembly clusters to offset Osaka wage inflation. Acquire distressed custom rod shops with EPA-compliant curing capacity to block new entrant expansion. For New Entrants and Emerging Players: The $150-$400 price-point gap between premium Japanese carbon fiber rods and mass-market Chinese graphite alternatives offers white-space positioning for Taiwan-based direct-to-consumer specialists. Target Indian carp angling tourism operators transitioning from commercial aquaculture with durable composite blanks and repair subscription bundling. Bypass traditional retail markups through Instagram and TikTok commerce platforms with JDM-labeled positioning. For Investors and Strategic Acquirers: Shimano warranty program expansion into annual repair-and-replacement subscriptions is the leading indicator that recurring revenue models are displacing transactional rod sales. Frame long-term viability around captive carbon fiber supply relationships and closed-loop recycling program deployment for EU market access. Target acquisition archetype: mid-tier American custom builders with EPA-compliant thermal oxidizer capacity and direct-to-consumer channel infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Supply Agreement | Toray T1100G direct relationships lock in premium-tier blank access against competitor sourcing constraints. |
| Repair Subscription Platform | Annual warranty programs transform tournament angler relationships into recurring revenue with lifetime value expansion. |
| Thermal Oxidizer Compliance Investment | EPA NESHAP-compliant curing capacity separates domestic manufacturers from tariff-exposed offshore alternatives. |
| Direct-to-Consumer Channel Launch | TikTok Shop and Instagram Checkout bypass traditional tackle retail markups for margin recovery. |
| Closed-Loop Recycling Program | EU extended producer responsibility frameworks reward composite material recovery with preferential market access. |
Research Methodology
Independent corroboration across rod manufacturer executives, carbon fiber procurement leads, and tournament angler equipment managers underwrites the qualitative findings in this study. Primary interviews with blank engineering directors, retail category buyers, and EPA compliance officers combined with secondary validation from U.S. Fish and Wildlife Service Sport Fish Restoration data, customs import records, and METI industrial standard filings. Bottom-up SKU-level demand modeling and top-down equipment replacement cycle analysis provided triangulation across the freshwater fishing rod value chain.
Comparable-period anchoring to historical tournament participation rates and carbon fiber modulus adoption curves shaped the projection horizon analytical framework. Segmentation dimensions modeled include rod type, material modulus tier, length configuration, and action rating across United States, Japanese, Chinese, and Indian demand clusters. CAGRs derived from equipment replacement frequency acceleration in competitive angling circuits and social commerce channel penetration trajectories. Blank adhesive formulation chemistry shifts and REACH compliance adaptation timelines served as industry-specific forecast inputs.
Inputs from rod manufacturer financial disclosures and carbon fiber producer supply announcements were available through the study window; gaps in real-time tournament participation telemetry and social commerce transaction data introduce uncertainty bands around direct-to-consumer channel projections. Forecasts reflect documented assumptions regarding EPA enforcement consistency and tariff classification stability. Material deviation in carbon fiber supply allocation priorities or EU extended producer responsibility implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
North America Fire Pits Market
Outdoor & Sports
Australia Horse Riding Equipment Market
Outdoor & Sports
Golf Trolley Market
Outdoor & Sports
Global Slingshot Market
Outdoor & Sports
Fishing Tackle Box Market
Outdoor & Sports
Global Sailing Dinghy Masts Market
Outdoor & Sports
Golf Stand Bag Market
Outdoor & Sports
Global Artificial Grass Market
Outdoor & Sports
Cold Plunge Pools Market
Outdoor & Sports
Global Baseball Gloves Market
Outdoor & Sports
Riding Multi-Purpose Lawn Mower Market
Outdoor & Sports
Fish Hunting Equipment Market
Outdoor & Sports
Skimboard Market
Outdoor & Sports
Global Pool Floats Market
Outdoor & Sports
Sleeper Pads Market
Outdoor & Sports
Camping Utensils Market