
 Walkbehind Lawnmower Market | 2026-2036
Walkbehind Lawnmower Market Size, Share, and Industry Trends Forecast 2026-2036
Walkbehind Lawnmower Market Insights
Aftermarket service revenue is reconfiguring margin capture across the walkbehind lawnmower value chain. Deere & Company leverages its dealership network to control parts and servicing income. Husqvarna Group anchors its position through battery platform standardization across professional and residential lines. The Toro Company specializes in commercial-grade deck engineering for landscaping contractors.
A walkbehind lawnmower is a pedestrian-operated turf-cutting machine with a rotary or reel blade system, typically powered by an internal combustion engine or electric motor with cutting decks ranging from 20 to 30 inches in width, designed for grass maintenance across residential lawns, commercial grounds, and sports turf. Self-propelled models command premium positioning as operator fatigue reduction drives professional uptake, while electric segments gain fastest traction where noise ordinances and emissions restrictions tighten. Gasoline configurations remain the mature volume base in regions with limited charging infrastructure or large lot sizes.
The EPA regulates exhaust emissions from small spark-ignition engines under Title 40 CFR Part 90, compelling manufacturers to invest in catalytic aftertreatment or electrification. California Air Resources Board imposes stricter state-level standards that effectively set the compliance ceiling for North American product planning. The EU Green Deal and F-Gas Regulation accelerate battery-electric transition timelines across European markets. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded product development or certification duplication.
Market Dynamics
Battery-electric powertrains are restructuring competitive positioning across the walkbehind lawnmower value chain as California Air Resources Board and European F-Gas Regulation compliance deadlines compress gasoline engine development timelines.
Growth Catalysts
- Professional landscaping fleet expansion:Commercial grounds maintenance contractors in the United States are standardizing equipment procurement around battery platforms to reduce fuel logistics and noise compliance exposure.
- REACH substance restrictions:European chemical regulations on small engine coatings and lubricants are accelerating manufacturer investment in electrified product lines.
- Lithium-ion cell cost curves:Falling battery pack economics are narrowing the upfront price gap between cordless electric and gasoline walkbehind units for residential buyers.
Market Restraints
- Steel and aluminum input volatility:Deck and chassis fabrication costs fluctuate with commodity metal pricing, compressing OEM margin predictability.
- Charging infrastructure gaps:Rural property owners in Australia and Canada face range anxiety on large lot sizes where battery runtime remains insufficient.
- Small engine supplier concentration:A limited base of certified gasoline powertrain vendors in China creates supply bottleneck risk for hybrid product strategies.
Strategic Opportunities
- Robotic mower convergence:Autonomous navigation software and walkbehind form factor hybridization opens residential premium segments in Germany and Japan.
- Direct-to-contractor distribution:Bypassing traditional retail channels to sell fleet packages through landscaping trade associations captures recurring revenue streams.
- IRA clean energy incentives:United States federal tax credits for commercial electrification equipment reduce effective acquisition costs for professional buyers.
Industry Challenges
- Battery technician certification gaps:Dealer service networks lack standardized training protocols for high-voltage powertrain diagnostics and warranty repair.
- Dual powertrain SKU complexity:Maintaining parallel gasoline and electric product lines strains inventory management and forecasting accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Walkbehind Lawnmower Market |
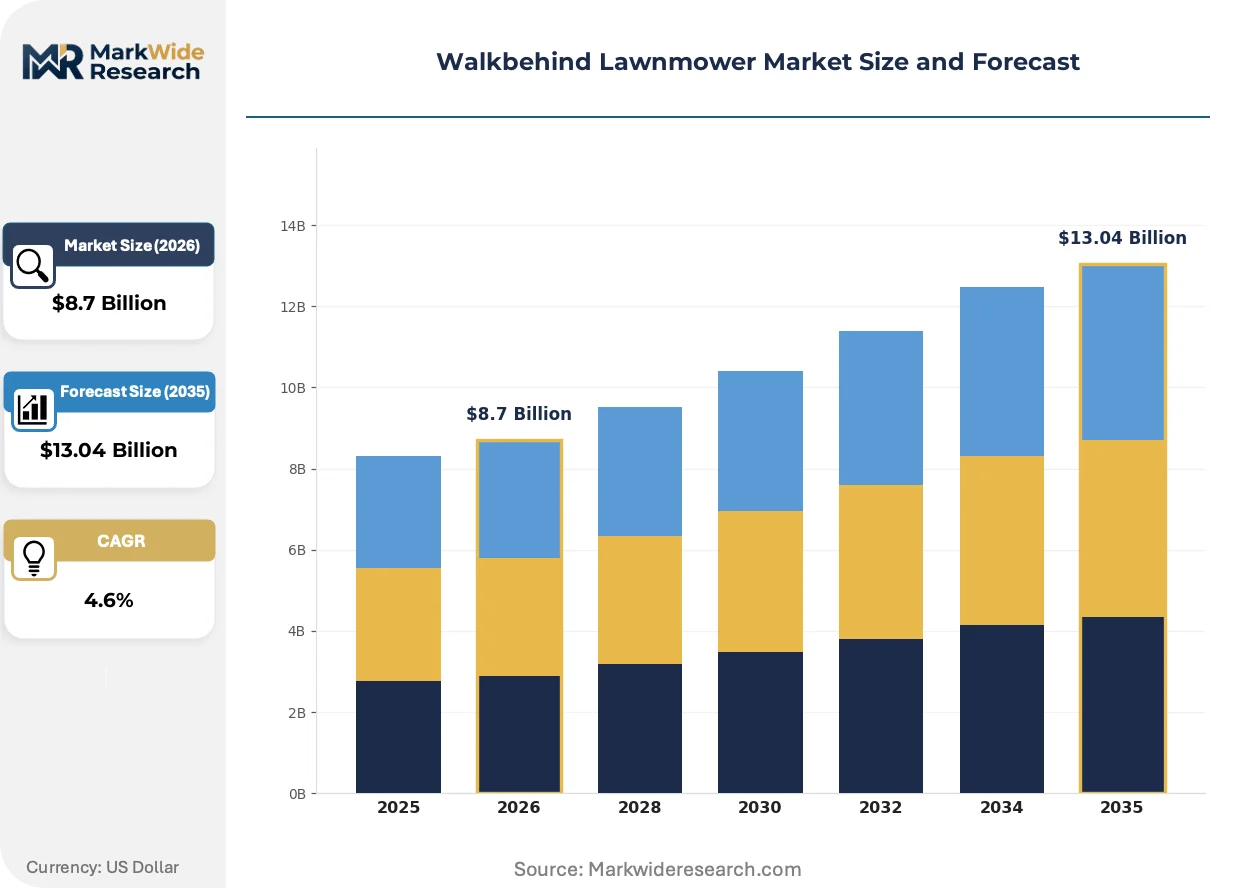
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Propelled, Push Mower, Electric, Gasoline Engine Power: Under 150cc, 150cc-200cc, 200cc-250cc, Above 250cc Deck Size: 20-22 inches, 23-25 inches, 26-30 inches, 31 inches and above End User: Residential, Commercial Maintenance, Landscaping Services, Golf Courses |
| Companies Covered | Deere & Company, Husqvarna Group, The Toro Company, Honda Motor Company, KUBOTA Corporation, MTD Products, Robert Bosch, STIGA Group, Ariens Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Walkbehind Lawnmower Market Trends and Innovations
Digital connectivity layers are embedding intelligence into pedestrian-operated equipment, shifting value capture from hardware sales toward subscription-enabled fleet management services.
Brushless DC motor controllers with integrated battery management systems are virtualizing the traditional mechanical governor and throttle linkage. Commercial landscaping contractors in the United States are specifying these electronic powertrains for precision speed control on variable terrain. This virtualization is compressing the aftermarket parts business for carburetors and ignition components while expanding firmware update revenue streams.
The EU F-Gas Regulation phase-down schedule for hydrofluorocarbon refrigerants is indirectly pressuring small engine thermal management designs. Manufacturers serving European markets must redesign cooling systems or accelerate pure electric transitions to avoid compliance complexity. Professional-grade walkbehind lines for Germany, France, and the Netherlands are prioritizing battery-electric architectures over emission aftertreatment investments.
Landscaping contractors are consolidating equipment purchasing through cooperative buying groups rather than individual dealer relationships. This channel concentration in the United States and Germany is forcing manufacturers to negotiate volume-tier pricing and extended warranty terms directly with multi-state operators. The shift is most visible in municipal grounds maintenance contracts where procurement standardization reduces total fleet cost of ownership metrics.
Walkbehind Lawnmower Market Segmentation
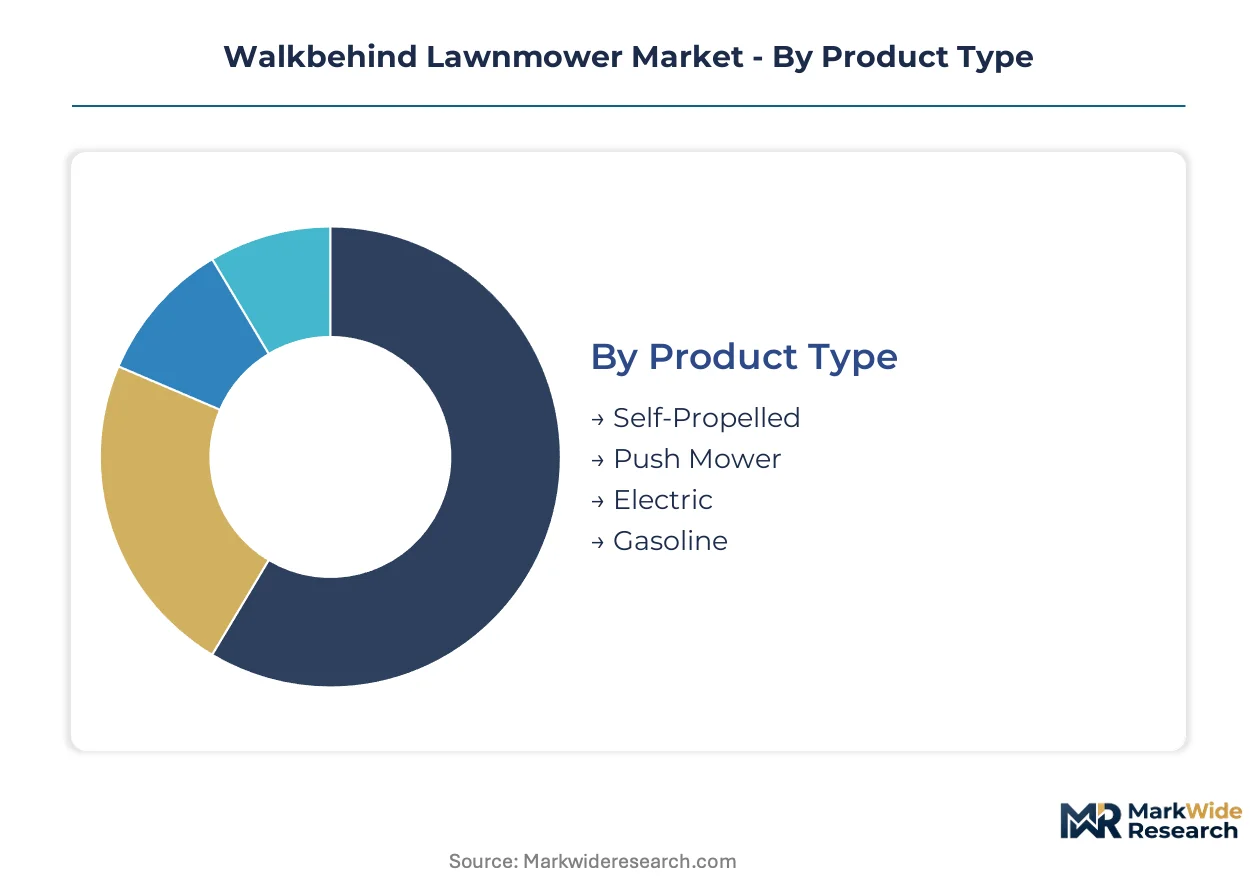
Segmentation in the walkbehind lawnmower market reveals distinct service intensity patterns across product tiers. Professional-grade equipment generates recurring parts and maintenance revenue streams that reshape manufacturer profitability calculations.
Product Type:
After-sales-service intensity varies sharply across propulsion architectures, with battery-electric platforms demanding specialized technician training and diagnostic tooling investments.
- Self-Propelled:Hydrostatic or belt-driven transmission systems transfer engine power to rear wheels, reducing operator fatigue on slopes and uneven terrain. Landscaping contractors in the United States specify these units for daily commercial use where productivity metrics dominate procurement decisions; premium pricing reflects transmission complexity and extended warranty obligations.
- Electric:Brushless DC motor architectures with integrated battery management systems eliminate carburetor maintenance and seasonal storage preparation. Demand concentrates in Germany and California where municipal noise ordinances and CARB emissions restrictions tighten; runtime limitations on large properties remain the primary constraint.
- Push Mower:Human-powered units with simple rotary blade systems serve price-sensitive residential buyers with small, flat lots. Minimal component count translates to lowest service revenue per unit.
- Gasoline:Small spark-ignition engines with recoil start mechanisms retain volume leadership in rural markets with limited charging infrastructure. EPA Title 40 CFR Part 90 compliance costs pressure margin structures.
Gasoline configurations hold the largest share; momentum sits with Electric segments.
Engine Power:
Displacement tiers correlate directly with fuel consumption patterns and seasonal maintenance scheduling density in dealer service bays.
- Under 150cc:Compact single-cylinder engines power residential push mowers on flat terrain under one-third acre. China-based powertrain suppliers dominate this commoditized segment.
- 150cc-200cc:Mid-range displacement balances torque output with weight distribution for self-propelled residential units. Volume concentration in North American big-box retail channels drives procurement standardization.
- 200cc-250cc:Commercial-grade powertrains with overhead valve architectures deliver sustained output for daily landscaping operations. Extended service intervals differentiate premium offerings.
- Above 250cc:V-twin or large single-cylinder engines command professional fleet specifications for dense grass conditions and hill climbing. Highest parts revenue per unit supports dealer profitability.
150cc-200cc segments anchor volume shipments; Above 250cc powertrains claim the steepest expansion trajectory in commercial procurement.
Deck Size:
Fabrication complexity and steel input costs scale non-linearly with cutting swath dimensions, compressing margins on the largest residential formats.
- 20-22 inches:Stamped steel decks suit narrow gates and obstacle-dense residential lawns. Urban property constraints in Japan and the United Kingdom sustain demand.
- 23-25 inches:Mid-size fabricated or stamped decks balance maneuverability with coverage efficiency for half-acre lots. This segment captures the widest residential price elasticity.
- 26-30 inches:Commercial-grade welded decks with reinforced spindle housings withstand daily contractor use. Landscaping services in Germany specify this range for municipal contract efficiency.
- 31 inches and above:Wide-area walkbehind formats approach riding mower productivity without capital expenditure escalation. Golf course maintenance departments utilize these for bunker surrounds and steep banks.
23-25 inch decks dominate unit economics; 26-30 inch configurations are climbing the fastest in professional fleet replacement cycles.
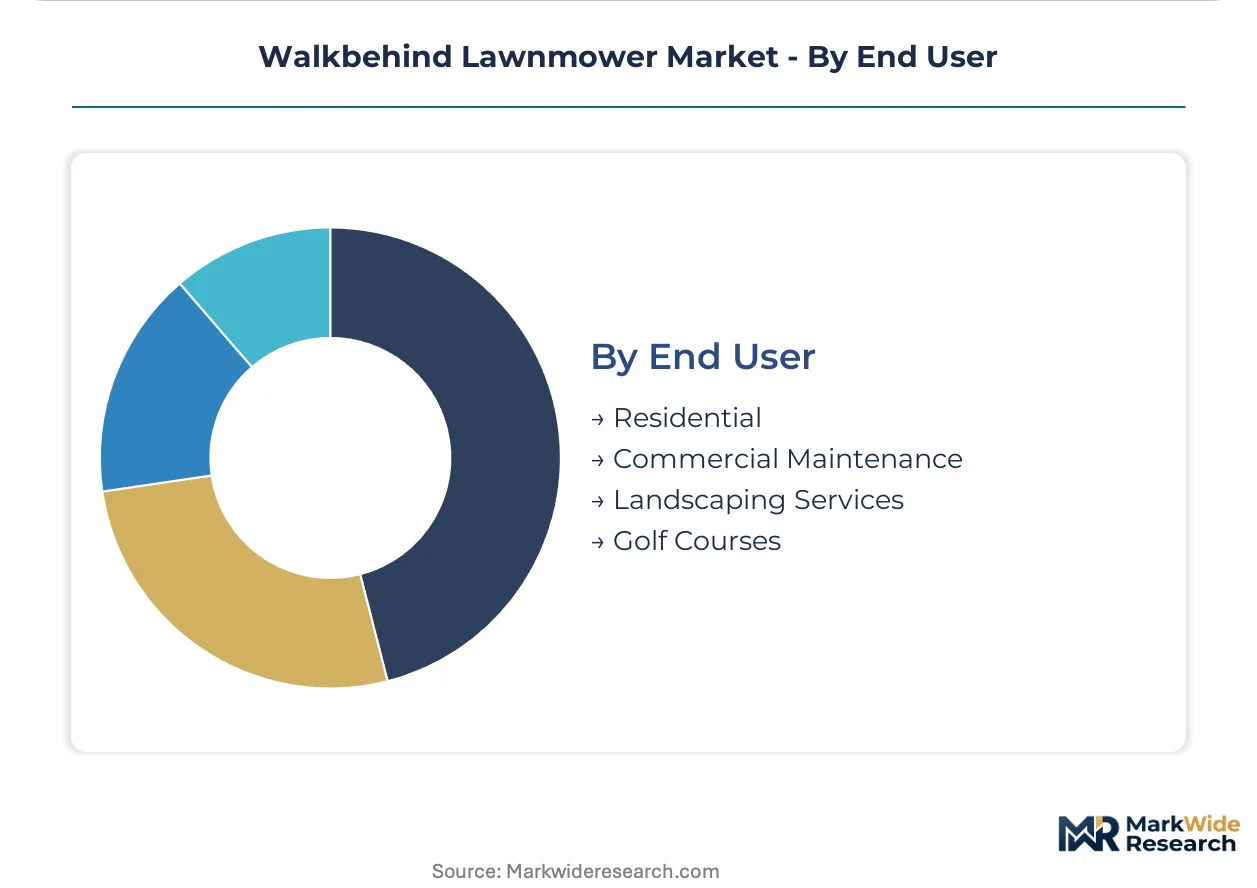
End User:
Customer type determines pricing architecture, with institutional buyers extracting volume-tier concessions unavailable to individual consumers.
- Residential:Individual homeowners purchasing through retail or e-commerce channels prioritize storage footprint and seasonal starting reliability. Price sensitivity peaks in this segment.
- Commercial Maintenance:Property management firms and facility maintenance departments operate mixed fleets with standardized procurement protocols. Total cost of ownership calculations include fuel logistics and downtime penalties.
- Landscaping Services:Independent contractors and multi-state operators drive battery-electric transition timelines to reduce noise compliance exposure and fuel inventory management. Cooperative buying groups concentrate negotiating leverage.
- Golf Courses:Turf management professionals demand precision cutting heights and minimal soil compaction for playability standards. Specialized reel and rotary hybrid configurations command premium positioning.
Residential buyers represent the volume foundation; Landscaping Services are gaining share fastest as fleet electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for walkbehind lawnmowers clusters in industrial zones with established small-engine supply chains and metal fabrication expertise. Demand patterns diverge sharply between mature markets with tightening emissions rules and emerging regions where gasoline units retain cost advantages.
United States
Commercial landscaping contractors in Florida and Texas are electrifying fleets ahead of municipal noise ordinance deadlines. The EPA's Title 40 CFR Part 90 standards pressure gasoline engine redesigns. Manufacturing concentrates in Wisconsin and Ohio, where Deere & Company and MTD Products anchor regional supply chains with vertically integrated stamping and assembly operations.
Germany
Professional grounds maintenance services in Bavaria and North Rhine-Westphalia specify battery-electric walkbehind units for municipal contract compliance. The EU F-Gas Regulation accelerates phase-out timelines for emission-intensive equipment categories. STIGA Group and KUBOTA Corporation maintain engineering centers around Stuttgart, where precision deck fabrication serves premium European demand.
China
Export-oriented manufacturing in Zhejiang and Jiangsu provinces supplies cost-competitive gasoline and electric units to Southeast Asian and Latin American markets. The Ministry of Ecology and Environment enforces dual carbon goals that reshape domestic product mix toward electrification. Zhengzhou Shuli Machinery Co., Ltd. exemplifies the mid-tier fabricator archetype concentrated in Henan Province's metalworking corridor.
Japan
Golf course maintenance departments in Chiba and Saitama prefectures demand precision cutting equipment with minimal soil compaction. METI efficiency standards for small motors exceed baseline international requirements. Honda Motor Company anchors domestic production in Kumamoto, where specialized reel mower engineering serves premium turf management applications.
United Kingdom
Residential buyers in Greater London and the Southeast prioritize compact storage footprints and low-noise operation for small urban gardens. REACH substance restrictions on engine coatings complicate gasoline product compliance. Ariens Company and Robert Bosch distribute through dedicated garden machinery retailers concentrated in the Midlands distribution hub.
Walkbehind Lawnmower Market Competitive Landscape
Full-line diversified manufacturers and specialized turf equipment suppliers split the market into distinct competitive spheres. Consolidation pressure intensifies as battery platform development costs favor scale players with cross-product R&D amortization. Three archetypes dominate: agricultural machinery conglomerates with lawn care divisions, pure-play outdoor power equipment specialists, and diversified industrial conglomerates with consumer appliance roots. M&A activity targets battery technology startups and regional distribution networks, while portfolio diversification moves emphasize robotic and autonomous adjacent categories.
Among diversified industrial players, Deere & Company and Robert Bosch occupy positions spanning professional and residential price tiers through distinct channel strategies. Honda Motor Company exemplifies the integrated powertrain specialist archetype, leveraging internal combustion and electric motor expertise across mobility and stationary applications. Husqvarna Group and The Toro Company sit within the pure-play outdoor power equipment tier, where brand equity in professional landscaping circles commands pricing power independent of parent conglomerate scale.
| Leading Market Players |
|---|
| Deere & Company |
| Husqvarna Group |
| The Toro Company |
| Honda Motor Company |
| KUBOTA Corporation |
| MTD Products |
| Robert Bosch |
| STIGA Group |
| Ariens Company |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-to-Los Angeles container corridor's rate volatility compresses margin predictability for deck and chassis fabricators, concentrating pricing power with steel-intensive suppliers in China while forcing downstream tiering between professional fleet packages and residential retail SKUs.
Pricing Analysis
After-sales service contracts and parts revenue streams now drive lifetime value calculations above initial unit margins. Three-tier pricing structure across premium, standard, and economy levels separates commercial-grade self-propelled units with extended warranties from basic push mowers. Cost compression in battery-electric segments is intensifying because lithium-ion cell economics narrow upfront gaps with gasoline equivalents. Residential buyers exhibit highest price sensitivity; landscaping services demonstrate lowest sensitivity due to total cost of ownership procurement frameworks.
Supply Chain Analysis
Steel coil and aluminum extrusion feedstock costs fluctuate with commodity exchange pricing, anchoring deck fabrication economics in China, the United States, and Germany. Powertrain sourcing draws from Zhejiang Province small-engine suppliers, South Korean battery cell manufacturers, and Wisconsin-based transmission specialists. Single-source vulnerability concentrates in certified gasoline engine vendors serving hybrid product strategies. Distribution runs through dealership networks for professional segments and big-box retail for residential buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The walkbehind lawnmower market functions as a service-attach opportunity where firmware update subscriptions and fleet management platforms expand faster than hardware unit sales.
For Market Incumbents: Harden dealer network control by standardizing battery platform architectures across product lines to capture recurring parts revenue threatened by electronic powertrain virtualization. Invest in technician certification programs for high-voltage diagnostics to defend against independent service entrants. Prioritize backward integration into lithium-ion pack assembly to reduce supplier concentration risk.
For New Entrants and Emerging Players: Establish a beachhead in robotic-walkbehind hybrid segments where autonomous navigation software creates white-space above commoditized gasoline units. Target municipal grounds maintenance cooperatives in Germany and the United States with direct-to-contractor fleet pricing. Leverage IRA clean energy incentives as a go-to-market angle for professional electrification procurement.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized outdoor power equipment divisions lacking battery platform scale. Long-term viability hinges on R&D amortization across robotic and autonomous adjacent categories. Watch battery-electric penetration rates in commercial landscaping fleets as the inflection signal for platform consolidation winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Cross-product R&D amortization accelerates electrification timelines for professional fleet buyers. |
| Direct-to-Contractor Distribution | Bypassing retail channels captures recurring revenue from landscaping cooperative purchasing groups. |
| Technician Certification Investment | High-voltage diagnostic capability defends dealer service revenue against independent repair entrants. |
| Robotic Mower Convergence | Autonomous navigation software opens premium residential segments in noise-restricted German and Japanese markets. |
| Backward Integration into Battery Assembly | In-house pack production reduces supplier concentration risk from South Korean and Chinese cell vendors. |
Research Methodology
The analysis maps self-propelled, electric, push, and gasoline propulsion architectures, each validated through landscaping fleet managers, dealership service directors, OEM procurement leads, and municipal grounds maintenance contractors. Primary interview findings triangulate against EPA Title 40 CFR Part 90 filings, CARB certification databases, EU F-Gas Regulation implementation schedules, and SEC 10-K equipment segment disclosures. Bottom-up unit economics and top-down market sizing converge across the projection horizon.
Assumptions held fixed include regulatory compliance deadlines and lithium-ion cost curve trajectories, while variables encompass steel input volatility and charging infrastructure deployment density. The analytical framework segments by propulsion type, engine displacement tier, deck dimension, and end-user procurement pattern. CAGRs derive from shipment volume modeling and average selling price evolution across professional and residential demand clusters. Forecast inputs incorporate fleet electrification timelines and cooperative buying group consolidation rates.
Macroeconomic conditions sit as an overlay; deviation in construction employment levels and suburban housing starts would shift the trajectory. Material shifts in CARB zero-emission equipment mandates or EU F-Gas phase-down acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Kayak Accessories Market
Outdoor & Sports
Garden Solar Lights Market
Outdoor & Sports
Camping Cookware Market
Outdoor & Sports
Global Pool Floats Market
Outdoor & Sports
Swimming Pool Accessories Market
Outdoor & Sports
Camping Tent Market
Outdoor & Sports
Fishing Line Market
Outdoor & Sports
Global Scuba Diving Equipment Market
Outdoor & Sports
Skimboard Market
Outdoor & Sports
Global Swimming Pool Market
Outdoor & Sports
Global Canoe and Kayak Market
Outdoor & Sports
Australia Kids Scooter Market
Outdoor & Sports
Swimming Pool Equipment Market
Outdoor & Sports
Global Baseball Gloves Market
Outdoor & Sports
Freshwater Fishing Rod Market
Outdoor & Sports
Portable Kayaks Market