
 Fish Hunting Equipment Market | 2026-2036
Fish Hunting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Hunting Equipment Market Intelligence
The integration of smart sensors and GPS technology into fishing equipment is narrowing the gap between professional and amateur angling success. This technological shift pressures traditional manufacturers to innovate beyond mechanical performance. Shimano Inc. leads in precision gear engineering for high-performance reels, while Pure Fishing Inc. leverages a diverse brand portfolio to serve multiple market segments. Orvis specializes in the premium fly fishing niche, focusing on heritage and quality.
Fish hunting equipment comprises the mechanical tools used for catching fish, primarily for sport or recreation. These products, including rods and reels, are engineered with materials like carbon fiber to achieve specific flex, strength, and weight characteristics. Rods and reels represent the largest product segments, with significant innovation focused on material science. Price differentiation is notable in the saltwater fishing application segment, which demands higher-margin, corrosion-resistant equipment compared to the volume-driven freshwater market.
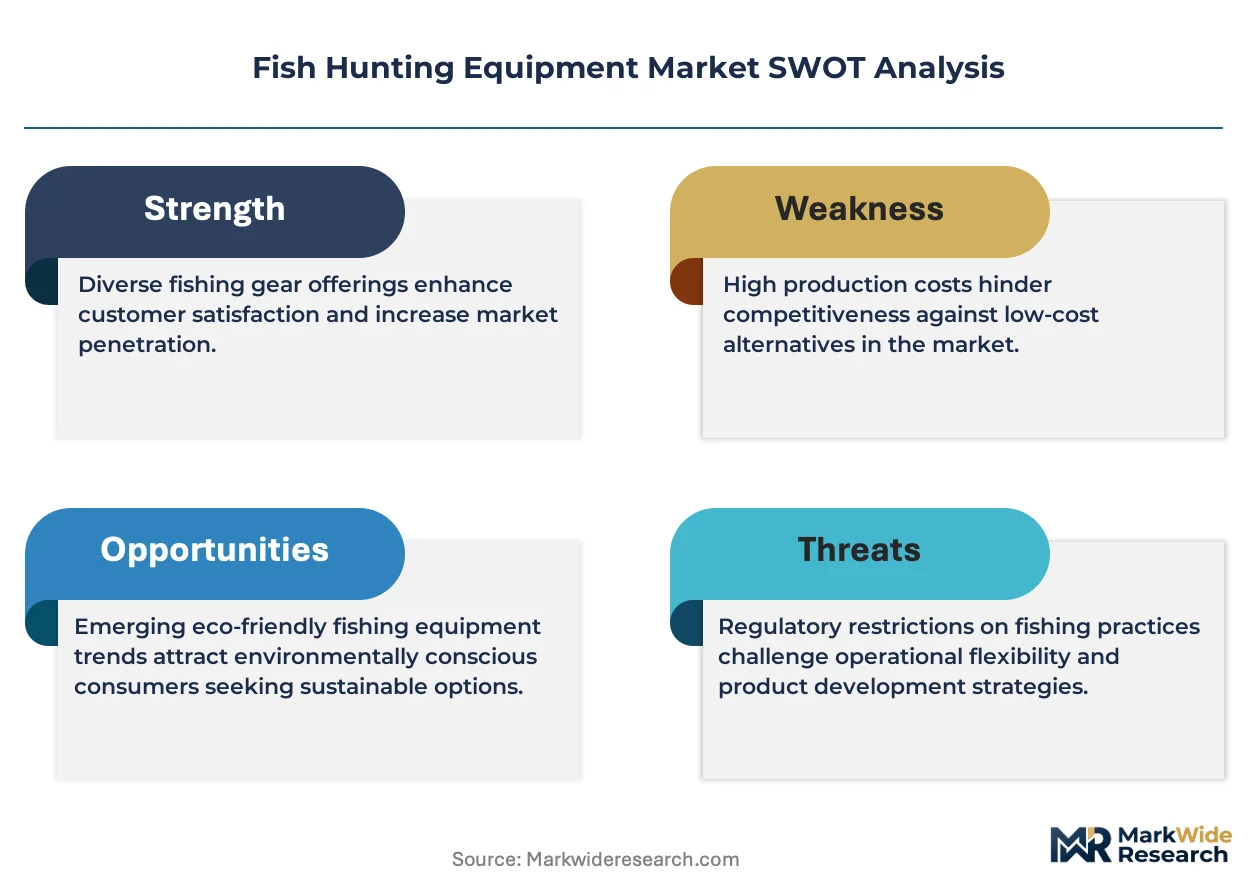
Product design is shaped by national and regional environmental regulations. In the United States, state fish and wildlife agencies dictate permissible gear, while some European countries are phasing out lead-based lures under environmental protection mandates. These rules directly influence material selection and product development cycles. Consequently, manufacturers must navigate a complex regulatory environment while adapting to consumer demand for more sustainable equipment.
Market Dynamics
The central dynamic shaping the fish hunting equipment market is the conflict between rising consumer demand for technologically advanced, high-performance gear and mounting regulatory pressure for environmentally sustainable fishing practices, forcing material and design innovation across the product lifecycle.
Growth Catalysts
- Advanced Composites:The adoption of carbon fiber and proprietary polymer blends in rod and reel manufacturing enables the production of lighter, stronger, and more sensitive equipment, enhancing angler performance and justifying premium price points for experienced hobbyists.
- Recreational Fishing Participation:A sustained interest in outdoor recreational activities, particularly in developed markets like the United States and Australia, expands the addressable market of hobbyist anglers seeking entry-level to mid-range equipment for leisure.
- E-commerce Channel Expansion:The growth of online retail platforms and direct-to-consumer websites makes specialized fishing equipment more accessible to a wider audience, breaking the geographical constraints of traditional brick-and-mortar sporting goods stores.
Market Restraints
- Input Material Price Volatility:Fluctuations in the cost of raw materials, especially carbon fiber, high-grade aluminum, and specialized polymers, create margin pressure for manufacturers. This is acute for manufacturers sourcing specialized polymers and carbon fiber precursors globally.
- Fragmented Environmental Regulations:A complex web of rules, such as lead-lure restrictions under consideration by ECHA in Europe and varying gear specifications dictated by state wildlife agencies in the United States, increases compliance costs and complicates product design.
- Competition from Alternative Leisure Activities:The market faces indirect competition from a wide array of other outdoor and indoor recreational pursuits vying for consumers' discretionary spending and leisure time, which can limit the growth of the angler population.
Strategic Opportunities
- Kayak and Inshore Fishing Niches:The rising popularity of kayak fishing creates demand for specialized equipment, including shorter rods, corrosion-resistant reels, and integrated gear-mounting systems, representing a high-growth product development opportunity.
- Integration of Smart Technology:Incorporating IoT sensors, Bluetooth connectivity, and GPS into reels and fish finders offers a significant opportunity to create new value propositions, particularly for the tech-savvy amateur angler seeking a competitive edge.
- Emerging Market Penetration:Countries in South America and Southeast Asia with extensive coastlines and growing middle-class populations present untapped markets for both freshwater and saltwater fishing equipment, offering long-term growth potential.
Industry Challenges
- Navigating Material Bans:The phase-out of lead and certain plastics in fishing lures and weights, driven by environmental mandates in jurisdictions like Canada and the EU, requires significant R&D investment in viable and cost-effective alternative materials like tungsten and bismuth.
- Prevalence of Counterfeit Goods:The proliferation of counterfeit high-performance rods and reels on online marketplaces erodes brand equity and presents a significant challenge for premium manufacturers. This affects brand value and poses safety risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Hunting Equipment Market |
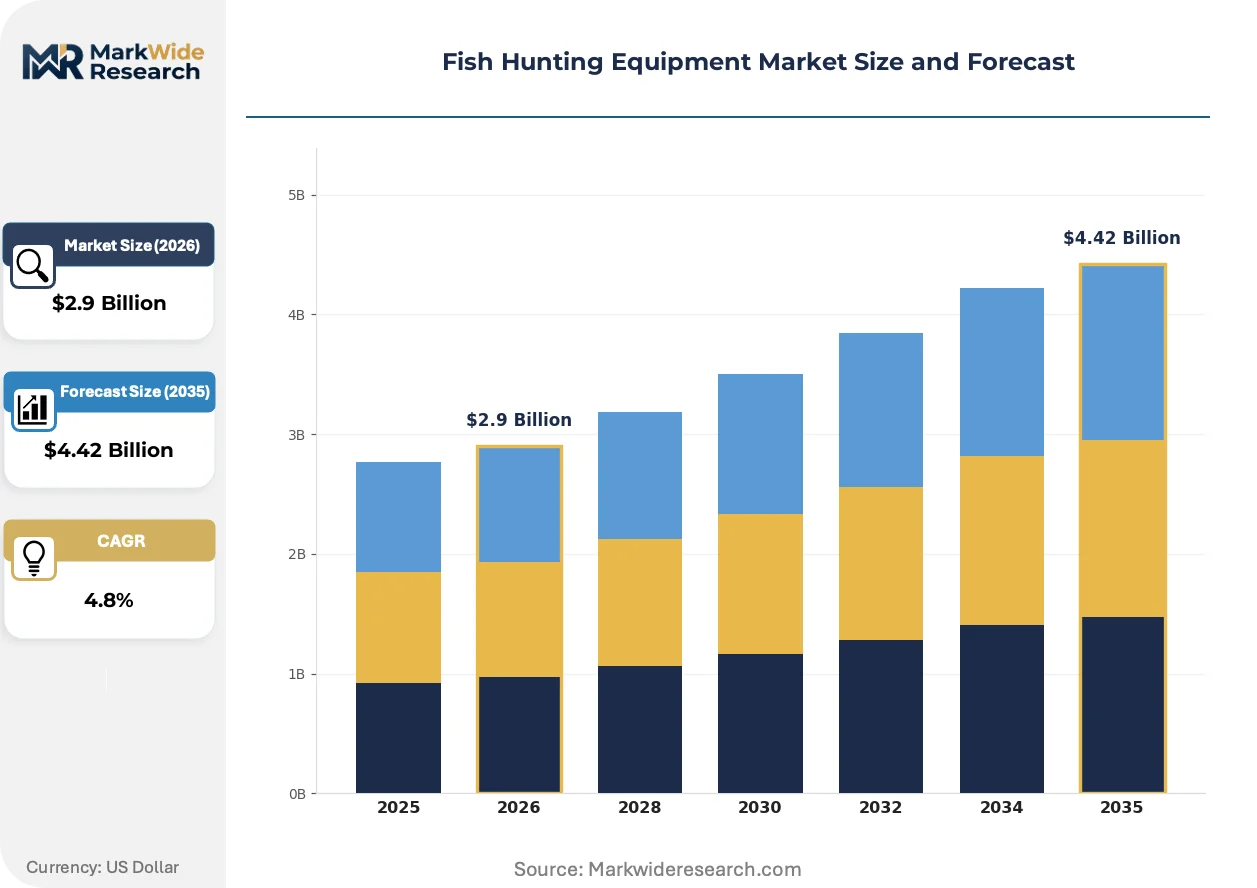
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $4.42 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rods, Reels, Lures, Nets Material: Carbon Fiber, Graphite, Aluminum, Nylon End User: Professional Anglers, Hobbyists, Retailers, Tour Operators Application: Freshwater Fishing, Saltwater Fishing, Ice Fishing, Fly Fishing |
| Companies Covered | Orvis, Pure Fishing Inc., Newell Brands, Globeride Inc., Costa Del Mar Inc., Pradco Outdoor Brands, Eagle Claw, Maver UK Ltd, Shimano Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Hunting Equipment Market Strategic Shifts & Innovations
A fundamental shift toward data-driven angling and sustainable materials is reshaping product design. This pivot moves the core value proposition from purely mechanical durability to a new standard where data-enhanced performance and environmental compliance are paramount for market acceptance.
Embedded sensors and GPS modules are key product innovations. Hobbyist and amateur anglers are rapidly adopting this equipment to gain insights on casting mechanics, lure depth, and water temperature. This technology is digitizing the angling experience, augmenting mechanical skill with real-time environmental data and location tracking, which narrows the performance gap between amateurs and professionals.
European environmental policy is a primary catalyst for material science innovation. Regulations advanced by bodies like ECHA to restrict lead in fishing tackle compel manufacturers to find non-toxic substitutes. This directly impacts the freshwater lure and weight segments, forcing a reformulation of entire product lines with materials like steel, tungsten, and bismuth to maintain market access in the EU.
Direct-to-consumer sales channels are disrupting traditional distribution models. Specialized and premium brands increasingly leverage e-commerce to engage directly with anglers, offering product customization and expert content that bypasses generalist sporting goods retailers. This trend is most advanced in North America, where sophisticated logistics networks enable efficient fulfillment for online-native brands.
Fish Hunting Equipment Market Segmentation
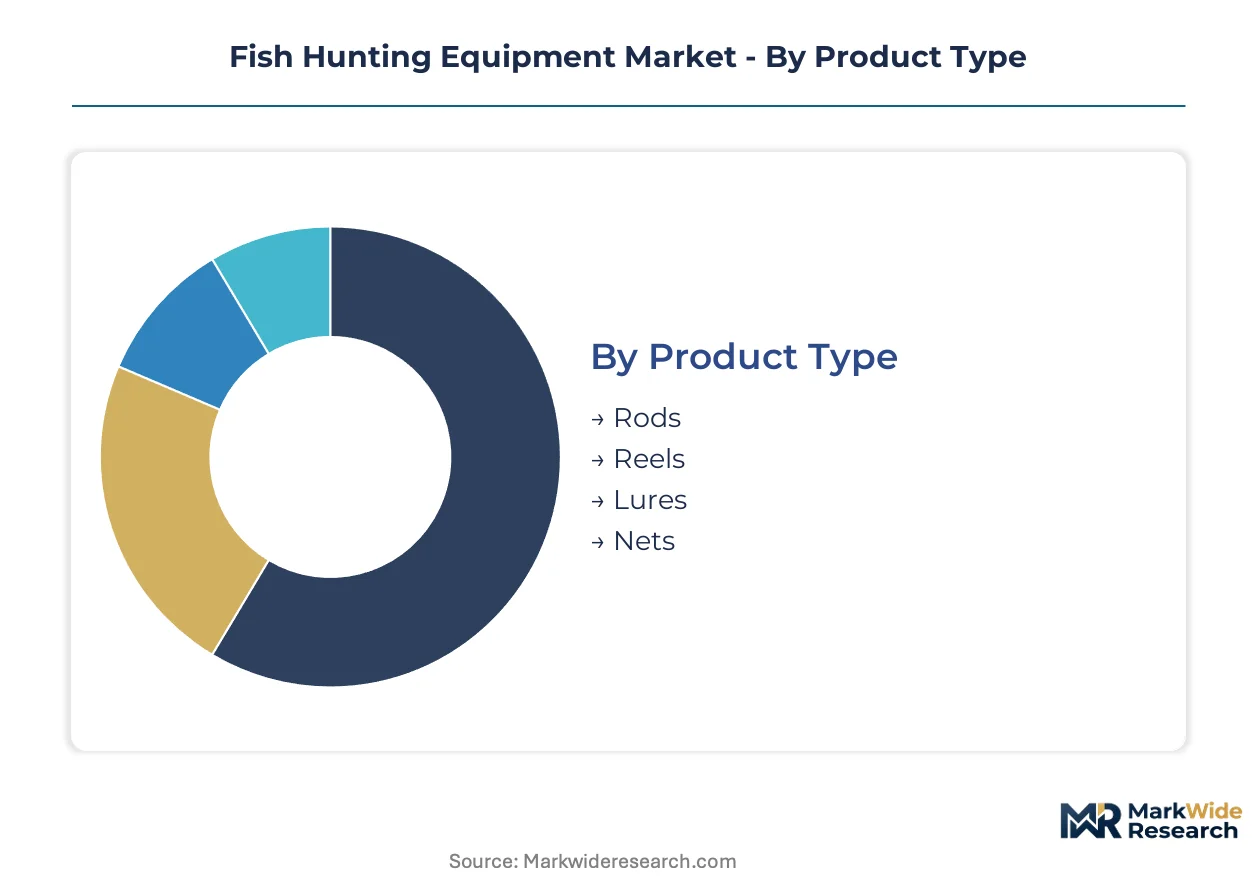
The fish hunting equipment market is fundamentally shaped by how different product categories and materials address specific angler needs and environmental conditions. Understanding these distinct segments allows manufacturers to tailor innovation and distribution strategies effectively, from high-performance gear to mass-market recreational items.
Product Type:
Product types exhibit varying turnover rates, with consumables like lures cycling much faster than durable goods such as rods and reels. This dictates different inventory management and R&D cycles for manufacturers.
- Rods:These are primary tools for casting and fighting fish, engineered with materials like carbon fiber to achieve specific flex and sensitivity. Demand for advanced rod designs is concentrating in the United States, driven by a large hobbyist base seeking enhanced casting precision and durability for diverse fishing environments.
- Reels:Mechanical devices for holding and winding fishing line, integrating precision gears and drag systems for controlling fish. Innovation in reel technology, particularly in corrosion resistance and smooth operation, is critical for saltwater applications where equipment endures harsh marine conditions.
- Lures:Artificial baits designed to attract fish through visual appeal, vibration, or scent, often made from plastics, metal, or wood. These products have a high replacement rate, driven by loss during fishing and consumer desire for new patterns and colors.
- Nets:Tools used for landing fish once they are brought close to the angler, varying in mesh size and handle length for different fish species and fishing styles.
Rods anchors the volume base while Reels gains share at the steepest rate.
Material:
Material selection defines the performance characteristics and cost tiers of fish hunting equipment, with advanced composites commanding premium prices due to superior strength-to-weight ratios.
- Carbon Fiber:A lightweight, high-strength composite material primarily used in premium fishing rods and some reel components, offering superior sensitivity and casting distance. Manufacturers leverage carbon fiber for high-performance gear targeting professional anglers in developed markets like Japan.
- Graphite:Another composite material widely used in fishing rods, providing a good balance of strength, sensitivity, and affordability compared to pure carbon fiber. This material supports mid-range product lines for a broad segment of hobbyist anglers in North America.
- Aluminum:A durable and corrosion-resistant metal frequently used in reel bodies, spools, and some rod components, providing structural integrity.
- Nylon:A versatile synthetic polymer used extensively for fishing lines, nets, and various accessory components due to its strength and flexibility.
Material innovation focuses on advanced composites to improve performance, while traditional materials like nylon provide cost-effective solutions.
End User:
The end-user segmentation highlights distinct purchasing behaviors and product requirements, ranging from high-volume recreational buyers to specialized professional users.
- Hobbyists:Individuals who engage in fishing for leisure and recreation, representing the largest consumer base for entry-level to mid-range equipment. This segment's demand is driven by accessibility and ease of use, particularly in regions with extensive freshwater fishing opportunities like the United States.
- Professional Anglers:Individuals who fish competitively or as a primary source of income, demanding high-performance, durable, and technologically advanced equipment. These users often influence product trends and seek gear that offers a competitive edge, driving innovation in precision engineering.
- Retailers:Businesses that sell fishing equipment directly to consumers, including sporting goods stores and specialized tackle shops. Retailers focus on stocking a diverse product range to meet varied consumer demands.
- Tour Operators:Companies that provide guided fishing trips and experiences, requiring durable and reliable equipment for their clients.
The Hobbyists segment drives volume demand, whereas Professional Anglers influences premium product development.
Application:
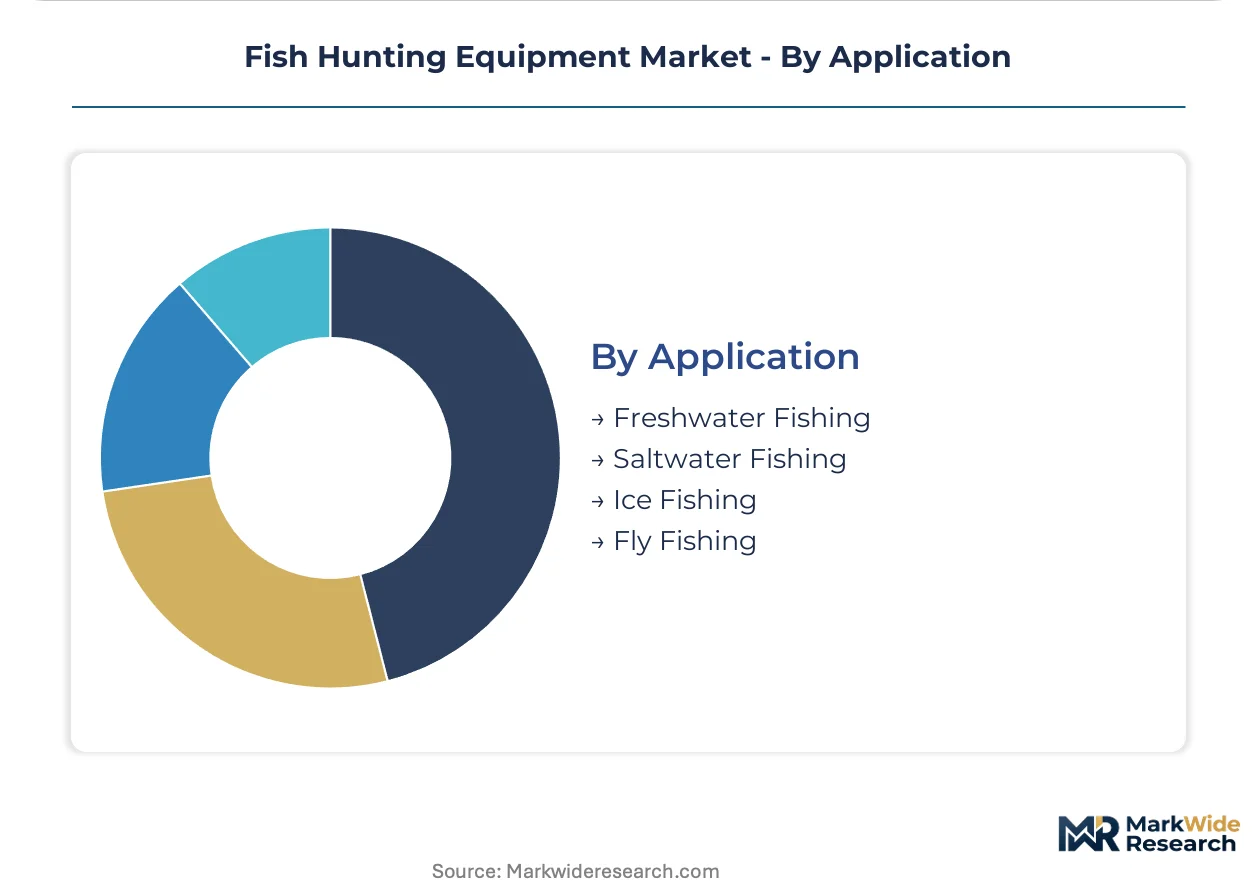
Each application segment imposes unique demands on equipment design, from material selection to corrosion resistance and specialized functionality.
- Saltwater Fishing:This application demands highly corrosion-resistant and robust equipment due to the harsh marine environment and larger, more powerful fish species. Manufacturers focus on durable alloys and sealed components for reels, particularly for coastal regions with active sportfishing communities.
- Freshwater Fishing:This broad application encompasses a wide range of environments, from rivers to lakes, typically requiring lighter and more sensitive gear. The volume of participation in freshwater fishing in regions like Europe drives demand for versatile, accessible equipment.
- Fly Fishing:A specialized technique requiring unique equipment, including lightweight rods, specific reels, and artificial flies designed to mimic insects. This niche segment values craftsmanship and specific casting performance.
- Ice Fishing:A seasonal activity conducted through holes in frozen bodies of water, necessitating specialized short rods, small reels, and insulated gear.
Demand in Saltwater Fishing requires specific material properties, while Freshwater Fishing focuses on recreational accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese manufacturers export high-performance carbon fiber fishing equipment to global markets, including the United States and Europe, driving material science advancements. Regional demand varies significantly, influenced by local recreational habits, environmental regulations, and economic conditions. This creates distinct market dynamics across key geographies for fish hunting equipment.
United States
Demand for advanced rod designs and entry-level to mid-range equipment concentrates in the United States, driven by a large hobbyist base and extensive freshwater fishing opportunities. State fish and wildlife agencies dictate permissible gear types and fishing seasons, directly influencing product development cycles. Florida's coastal cities and the Great Lakes region represent significant clusters for specialized saltwater and freshwater equipment distribution and sales.
Japan
Japanese professional anglers and tech-savvy hobbyists drive the demand for high-performance, precision-engineered reels and rods, particularly those utilizing advanced carbon fiber. The Ministry of Economy, Trade and Industry (METI) supports research into advanced materials, indirectly benefiting fishing equipment manufacturers. Shizuoka Prefecture, home to major industry players, acts as a hub for precision gear engineering and manufacturing innovation.
Germany
Freshwater fishing participation in Germany generates consistent demand for versatile and accessible equipment, alongside a growing interest in sustainable products. Environmental regulations, such as those from the European Chemicals Agency (ECHA) restricting lead in fishing tackle, compel manufacturers to invest in non-toxic alternatives. Bavaria and North Rhine-Westphalia are key regions for outdoor sporting goods manufacturing and R&D into environmentally compliant materials.
Australia
Sustained interest in outdoor recreational activities, including extensive coastline and diverse fish species, fuels demand for both saltwater and freshwater equipment in Australia. State-level fishing regulations govern permissible gear and catch limits, influencing product design for local conditions. Coastal cities like Sydney and Brisbane serve as primary markets for specialized saltwater fishing equipment sales and distribution networks.
Fish Hunting Equipment Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, encompassing global leaders, diversified brand portfolios, and specialized niche players. This structure is shaped by varying levels of technological integration and material science expertise. Strategic archetypes include precision engineering specialists, broad-market portfolio holders, and premium segment innovators. Dominant competitive moves involve continuous product innovation, particularly in advanced materials and smart technology, alongside portfolio diversification to capture multiple market segments.
On the premium-tier vector, Orvis exemplifies a brand focusing on heritage and quality within the fly fishing niche, appealing to discerning anglers. Pure Fishing Inc., leveraging a diverse brand portfolio, occupies a position serving multiple market segments from entry-level to high-performance gear. Shimano Inc. anchors the high-performance segment, specializing in precision gear engineering for reels, which sets a standard for mechanical durability and smooth operation.
| Leading Market Players |
|---|
| Orvis |
| Pure Fishing Inc. |
| Newell Brands |
| Globeride Inc. |
| Costa Del Mar Inc. |
| Pradco Outdoor Brands |
| Eagle Claw |
| Maver UK Ltd |
| Shimano Inc. |
Cost & Logistics Intelligence
Japanese manufacturers' concentration in high-performance carbon fiber production directly influences the premium pricing and margin structures for advanced fishing rods and reels. This upstream specialization dictates pricing power for high-end equipment.
Pricing Analysis
Advanced composite technology creates a distinct pricing gap, separating next-generation smart-integrated equipment from current-generation mechanical gear and prior-generation basic tools. Pricing stratifies across premium, standard, and economy tiers, driven by material science advancements like carbon fiber and established brand reputation. Input material price volatility, particularly for specialized polymers and carbon fiber, exerts margin pressure on manufacturers. Hobbyists exhibit higher price sensitivity compared to professional anglers, who prioritize performance and durability.
Supply Chain Analysis
Upstream feedstock for fish hunting equipment relies heavily on specialized carbon fiber from Japan and high-grade aluminum from global sources. Component manufacturing concentrates in Asian countries, particularly China, due to cost efficiencies. Commodity price volatility for carbon fiber and polymers presents a structural risk for manufacturers. Downstream distribution runs through a hybrid model combining traditional sporting goods retailers with expanding direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fish hunting equipment market presents an early-cycle expansion story, driven by the increasing penetration of smart technology into angling. This technological integration enhances user experience for a broader hobbyist base.
For Market Incumbents:Build intellectual property moats through continuous R&D in advanced composites and smart sensor integration. Diversify product portfolios to mitigate risks from fragmented environmental regulations, such as lead-lure bans. Counterfeit goods on online marketplaces erode brand equity, necessitating strong channel control and brand protection strategies. Investing in sustainable material certifications strengthens market position against evolving consumer preferences.
For New Entrants and Emerging Players:Build out specialized equipment for high-growth niches like kayak and inshore fishing, targeting demand for shorter rods and corrosion-resistant reels. The tech-savvy amateur angler segment represents the most penetrable segment, seeking smart-integrated equipment. Penetrate emerging markets in South America and Southeast Asia with localized product offerings. A direct-to-consumer model, emphasizing product customization and expert content, offers an effective go-to-market angle.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upwards across the advanced materials and smart technology sub-segments, signaling long-term market viability driven by sustained recreational interest. Seek acquisition targets with proprietary material science expertise or established brands in premium fly fishing and saltwater applications. The proliferation of counterfeit goods indicates strong brand value in the premium segment. Increased R&D spending on non-toxic materials, such as tungsten and bismuth alternatives, serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Composite R&D | Enhances rod and reel performance, justifying premium price points for professional anglers. |
| Develop Smart Sensor Integration | Narrows the performance gap between amateur and professional angling success, expanding the user base. |
| Diversify Sustainable Material Portfolio | Ensures market access in Europe and Canada by complying with lead-lure restrictions and environmental mandates. |
| Expand Direct-to-Consumer Channels | Bypasses traditional retailers, allowing specialized brands to offer product customization and expert content. |
| Target Kayak Fishing Equipment | Captures demand in a high-growth niche requiring specialized shorter rods and corrosion-resistant reels. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research for validation. Primary insights were gathered from manufacturing R&D directors, sporting goods retailers, professional anglers, and environmental regulators. Secondary data included industry association reports, government environmental agency publications, and company financial filings. A rigorous bottom-up and top-down triangulation approach ensured data accuracy.
Forecast inputs considered recreational fishing participation rates, advanced composite material costs, and smart technology adoption trends. The analytical framework modeled market dynamics across the analysis window, segmenting by product type, material, end-user, application, and regional regulatory environment. Compound Annual Growth Rates were derived from historical data, projected technology adoption, and anticipated regulatory impacts.
Practitioners should monitor material price volatility and evolving environmental regulations for early signals of market shifts. Forecasts reflect current assumptions regarding technological advancements and consumer behavior. Quarterly review of raw material indices and new regulatory proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Europe Swimming Pools and Spas Market
Outdoor & Sports
Compound Bow and Crossbows Market
Outdoor & Sports
Paintball Field Service Market
Outdoor & Sports
Fishing Tackle Box Market
Outdoor & Sports
Artificial Turf Market
Outdoor & Sports
Above Ground Swimming Pools Market
Outdoor & Sports
Global Paintball Equipment Market
Outdoor & Sports
Global Slingshot Market
Outdoor & Sports
Inflatable Pool Market
Outdoor & Sports
Global Pool Floats Market
Outdoor & Sports
LED Fishing Light Market
Outdoor & Sports
Swimming Pool Accessories Market
Outdoor & Sports
Kayak Accessories Market
Outdoor & Sports
Golf Trolley Market
Outdoor & Sports
Garden Solar Lights Market
Outdoor & Sports
Global Scuba Diving Equipment Market