
 Lawn Roller Market | 2026-2036
Lawn Roller Market Size, Share, and Industry Trends Forecast 2026-2036
Lawn Roller Market Analytics
A shift from single-source supply agreements toward multi-vendor procurement is broadening competitive access for specialty manufacturers. John Deere leverages its dealer network density to control distribution in North American agricultural counties. Husqvarna Group competes through battery-platform compatibility across its landscaping portfolio. Brinly-Hardy Company anchors its position with domestically produced tow-behind models for residential estates.
A lawn roller is a cylindrical implement filled with water or sand to increase mass, typically constructed from steel or polyethylene and measuring 18 to 48 inches in width, designed to compress soil, smooth turf surfaces, and embed seeds through controlled ground pressure. Tow-behind rollers dominate commercial and golf course applications where tractor or utility vehicle compatibility determines equipment selection. Electric rollers represent the fastest-expanding product category as lithium-ion powertrains displace small gasoline engines in noise-restricted municipalities. Polyethylene drum construction captures residential demand through corrosion resistance and reduced transport weight versus steel alternatives.
EPA small engine emissions regulations under the Clean Air Act shape gasoline-powered product development timelines and certification costs. OSHA noise exposure limits for commercial landscaping crews accelerate electric equipment adoption in professional service fleets. Stakeholders must monitor battery energy density improvements and municipal electrification mandates to anticipate powertrain mix shifts in replacement cycles.
Market Dynamics
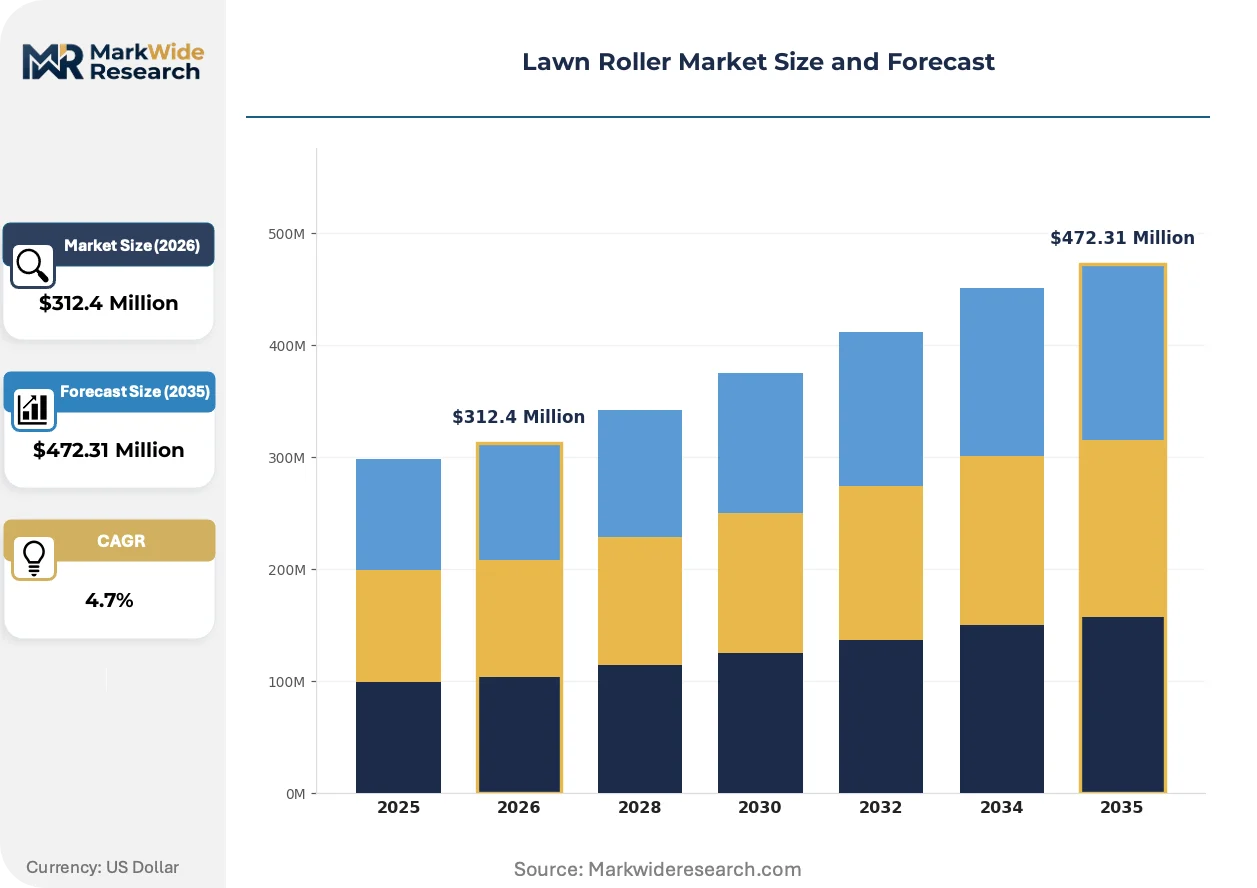
The lawn roller market pivots on powertrain electrification as municipal noise ordinances and EPA small engine emissions rules under the Clean Air Act compress gasoline equipment replacement cycles. Lithium-ion battery platforms are capturing share from legacy gasoline engines across commercial landscaping fleets.
Growth Catalysts
- EPA Clean Air Act Phase 3 Standards:Small gasoline engine emissions limits are forcing equipment turnover, accelerating electric roller adoption in professional service fleets.
- Golf Course Renovation Cycles:Municipal and private course maintenance budgets are expanding across the American Midwest, sustaining tow-behind equipment procurement.
- Lithium-Ion Energy Density Gains:Battery chemistry improvements are extending runtime for electric rollers, enabling single-shift operation without recharge interruption.
Market Restraints
- Steel Price Volatility:Drum manufacturing input costs fluctuate with global ferrous metal markets, compressing margin stability for domestic producers.
- Dealer Network Concentration:Agricultural equipment distribution concentrates in John Deere-aligned retail channels, limiting shelf access for specialty manufacturers.
- Manual Roller Substitution:Push-type polyethylene models serve residential maintenance needs at lower price points, constraining tow-behind unit penetration in the consumer segment.
Strategic Opportunities
- OSHA Noise Exposure Compliance:Commercial landscaping crews face 85 decibel exposure limits, creating regulatory tailwind for zero-emission electric fleet conversion.
- Battery-Platform Convergence:Cross-compatibility with existing landscaping tool ecosystems enables attachment sales to locked-in professional users.
- Smart Irrigation Integration:Sensor-equipped rollers communicating soil compaction data to automated watering systems represent an emerging precision-agriculture application.
Industry Challenges
- Certification Timeline Compression:EPA engine certification cycles for modified powertrains strain product development bandwidth.
- Legacy Fleet Interoperability:Electric roller hitch standards and weight distribution differ from gasoline predecessors, complicating mixed-fleet operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lawn Roller Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Rollers, Electric Rollers, Gas-Powered Rollers, Tow-Behind Rollers Material: Steel, Plastic, Polyethylene, Cast Iron Size: Small, Medium, Large, Extra Large Use Case: Residential, Commercial, Golf Courses, Sports Fields |
| Companies Covered | John Deere, Husqvarna Group, Brinly-Hardy Company, Agri-Fab, Inc., Turfco Manufacturing, Great Plains Manufacturing, Landoll Corporation, Buhler Industries, Goplus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lawn Roller Market Evolving Landscape
Powertrain architecture dominates competitive differentiation as battery chemistry and smart connectivity reshape equipment specifications. Manufacturers are racing to platformize electric systems across landscaping portfolios.
Lithium-ion battery packs are electrifying the commercial roller segment by eliminating gasoline engine maintenance and noise compliance burdens. Golf course superintendents and municipal parks departments are converting fleets ahead of equipment end-of-life. This transition is compressing replacement cycles from seven-year gasoline intervals to five-year electric refresh timelines.
EPA Phase 3 small engine emissions standards are tightening certification requirements for gasoline-powered equipment. Manufacturers face extended development timelines and testing costs for carbureted engine variants. The commercial tow-behind segment is responding fastest, with professional buyers prioritizing electric models to preempt regulatory exposure.
Multi-vendor procurement contracts are displacing single-source supply agreements among municipal parks departments. Procurement officers are fragmenting equipment purchases across specialty manufacturers to secure price competition and redundancy. This pattern is most visible in Midwestern counties with large-acreage maintenance obligations and expanding maintenance budgets.
Lawn Roller Market Segmentation
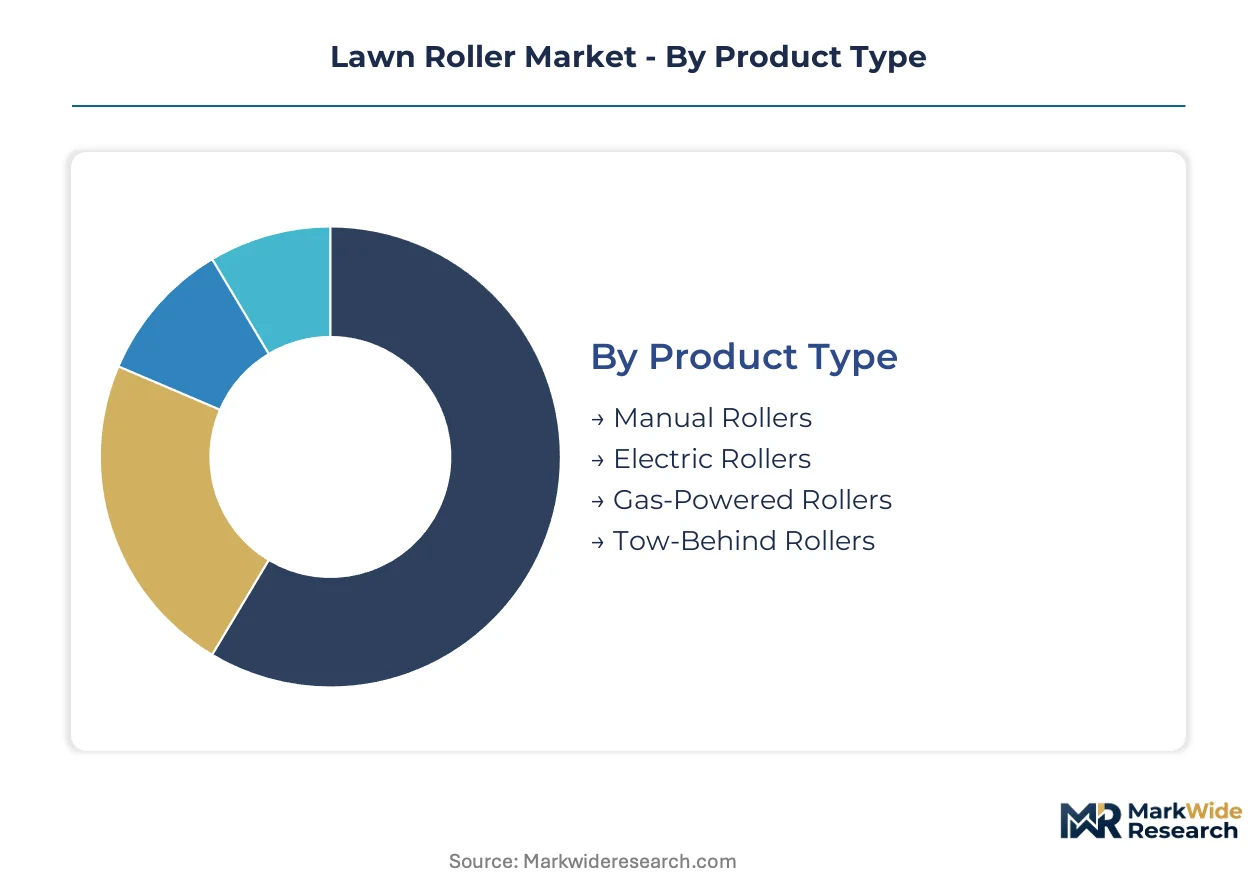
Lawn roller procurement patterns diverge sharply across powertrain technologies, drum materials, and scale of turf maintenance operations. Equipment specification directly determines compatibility with existing fleet infrastructure and regulatory exposure to municipal noise ordinances.
Product Type:
Powertrain architecture separates equipment categories by emissions compliance burden and operational runtime characteristics.
- Manual Rollers:Human-powered cylindrical drums typically 18-24 inches wide, constructed from polyethylene or steel, requiring no fuel or electrical infrastructure. Demand clusters in residential estates under 2 acres across the American Midwest where property owners prioritize capital expenditure minimization over labor efficiency.
- Electric Rollers:Lithium-ion battery systems driving motorized drum rotation with zero direct emissions and sub-75 decibel operation. Municipal parks departments in noise-restricted jurisdictions are converting professional fleets ahead of gasoline equipment end-of-life to preempt OSHA exposure limit violations.
- Gas-Powered Rollers:Small gasoline engines providing untethered runtime for extended commercial applications without recharge dependency. EPA Phase 3 Clean Air Act certification costs and extended development timelines are compressing manufacturer commitment to new carbureted powertrain releases.
- Tow-Behind Rollers:Hitch-mounted implements designed for tractor or utility vehicle compatibility, ranging 36-48 inches in width with water-fillable drums achieving 400-1000 pound operating mass. Golf course superintendents and sports field managers in the American Midwest sustain procurement through dedicated maintenance budget expansion.
Mature deployment sits with tow-behind configurations. Newer deployment is concentrated in electric rollers.
Material:
Drum composition determines corrosion resistance, transport weight, and surface finish quality for specific turf applications.
- Steel:Welded cylindrical shells with powder-coated or galvanized finishes providing maximum durability and ground pressure concentration. Commercial landscaping fleets in high-salinity coastal regions face accelerated corrosion failure, constraining steel drum lifecycle economics.
- Plastic:Injection-molded polymer drums offering reduced mass for manual transport and residential storage convenience. Price-sensitive consumer segments in suburban markets substitute plastic models for occasional seasonal use.
- Polyethylene:Rotationally molded hollow drums with UV-stabilized resin construction resisting denting and chemical degradation. Residential demand concentrates in corrosion-prone climates where steel alternatives require accelerated replacement cycles.
- Cast Iron:Solid or thick-walled drum construction delivering maximum mass density for professional soil compaction without water filling. Heritage golf courses and estate properties specify cast iron for ceremonial or aesthetic equipment visibility.
Volume concentration favors polyethylene for residential substitution. Margin stability tracks with steel input cost volatility.
Size:
Drum width and diameter specifications align equipment productivity with property scale and storage constraints.
- Small:18-24 inch drum width, manually operated or compact electric, suited to suburban lawns under 0.5 acres. Storage limitations in attached-garage homes restrict larger equipment acceptance.
- Medium:24-36 inch configurations spanning push-type and small tow-behind categories, capturing the transition zone between residential and light commercial maintenance. Rental yards specify medium units for maximum customer addressability.
- Large:36-48 inch tow-behind drums requiring tractor or utility vehicle compatibility, standard equipment for municipal parks departments and school district grounds maintenance. Fleet standardization around large formats enables attachment interchangeability.
- Extra Large:48+ inch specialized drums for golf course fairways and sports stadium turf, often custom-ordered through direct manufacturer relationships. Limited production volumes constrain aftermarket parts availability.
Procurement volume peaks in medium and large formats. Extra large specifications remain captive to custom fabrication lead times.
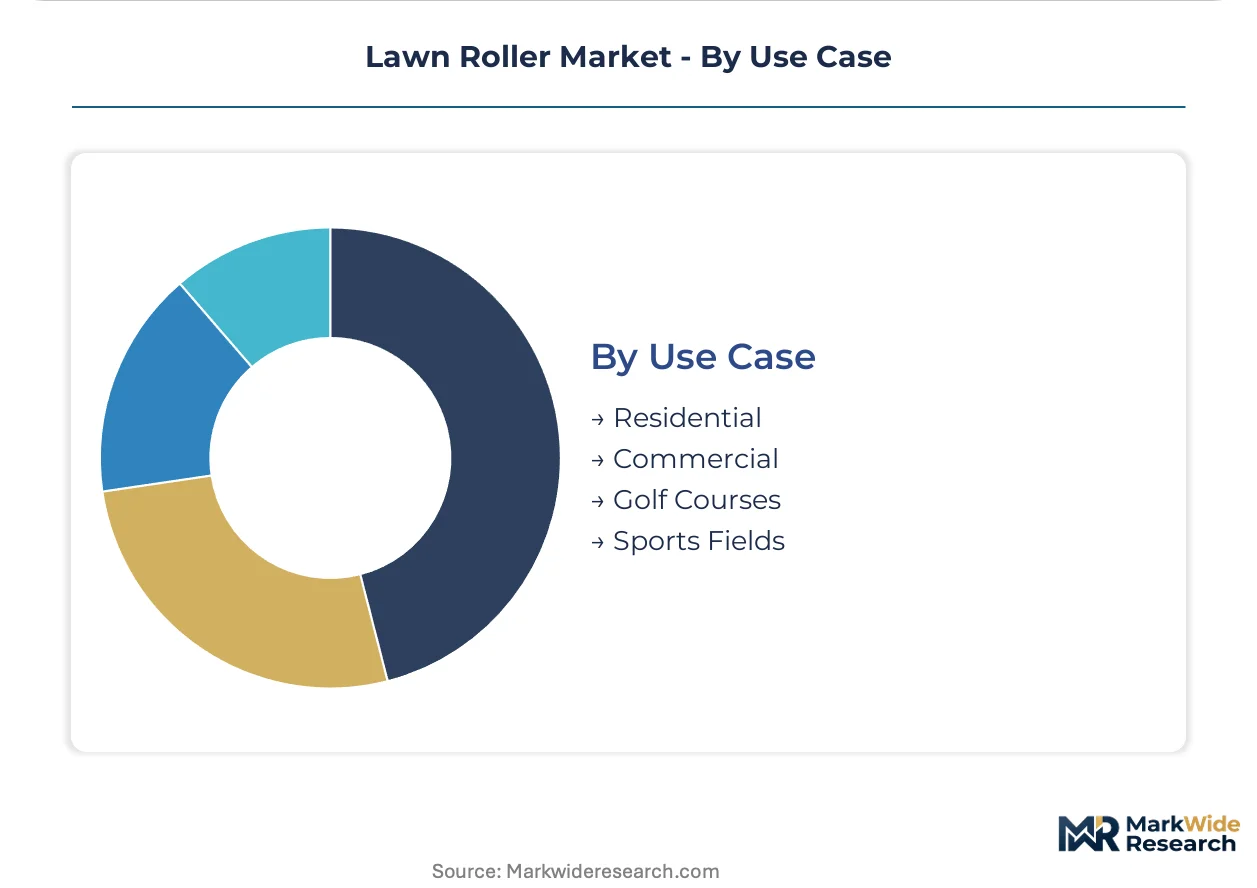
Use Case:
End-use environment dictates equipment durability specifications, operating hour intensity, and procurement authority structure.
- Residential:Seasonal use patterns with sub-20 annual operating hours, price-elastic demand, and retail channel preference. Big-box home improvement retailers dominate distribution through spring promotional cycles.
- Commercial:Professional landscaping services requiring 500+ annual operating hours, fleet standardization, and total cost of ownership optimization. OSHA noise exposure compliance is accelerating electric conversion in crew-operated equipment pools.
- Golf Courses:Precision turf management with superintendent-directed procurement, brand loyalty to agricultural equipment heritage, and integration with existing tractor fleets. Private equity consolidation of course ownership is centralizing purchasing authority.
- Sports Fields:Municipal and school district maintenance with bonded funding cycles, multi-vendor procurement mandates, and safety surface compliance requirements. American Midwest counties with expanding parks budgets are sustaining tow-behind equipment refresh programs.
Equipment longevity requirements are highest in golf course deployment. Fastest expansion is occurring in commercial fleet electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel drum manufacturing inputs concentrate in the Great Lakes industrial corridor, where ferrous metal processing infrastructure supports North American equipment fabrication. Regional demand patterns diverge sharply between municipal fleet electrification mandates and legacy gasoline equipment replacement cycles.
United States
Midwestern counties with expanding parks budgets sustain tow-behind equipment procurement through dedicated maintenance funding streams. EPA Phase 3 Clean Air Act standards compress gasoline engine certification timelines, accelerating electric roller adoption in professional landscaping fleets. Ohio and Illinois manufacturing clusters produce polyethylene drum components for residential distribution channels.
Canada
Municipal parks departments in Ontario and Quebec prioritize corrosion-resistant polyethylene drums for salt-exposed coastal maintenance operations. Health Canada and Environment Canada coordinate small engine emissions standards with US EPA benchmarks, simplifying cross-border equipment certification. Prairie Provinces agricultural equipment dealers stock tow-behind configurations for large-acreage estate properties.
Germany
Precision turf management at heritage golf courses drives demand for cast iron drum specifications with extended operational lifecycles. EU Green Deal electrification targets and national noise ordinances in Bavaria and North Rhine-Westphalia accelerate battery-powered equipment conversion. Baden-Württemberg industrial clusters specialize in lithium-ion powertrain integration for landscaping machinery.
United Kingdom
Private equity consolidation of golf course ownership in Southeast England centralizes purchasing authority toward fleet standardization agreements. Environment Agency water runoff regulations influence drum fill specifications for soil compaction operations. Midlands manufacturing regions supply steel drum fabrications to domestic agricultural equipment assemblers.
Australia
Extended drought cycles in New South Wales and Victoria shift sports field maintenance toward water-efficient turf establishment practices requiring precise soil compaction. State-level environmental protection agencies implement noise restrictions in metropolitan Sydney and Melbourne, constraining gasoline equipment operation windows. Queensland coastal regions specify UV-stabilized polyethylene construction for corrosion resistance in tropical climates.
Lawn Roller Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment manufacturers align battery platform compatibility with broader landscaping tool ecosystems. Market structure exhibits tiered consolidation, with agricultural equipment conglomerates controlling distribution density while specialty fabricators occupy niche specification segments. Three archetypes define competitive positioning: dealer-network-dependent agricultural equipment suppliers, battery-platform convergent landscaping specialists, and domestically focused tow-behind fabricators. Portfolio diversification and geographic expansion constitute the primary competitive vectors, with secondary emphasis on technology licensing for electric powertrain integration.
Among North American equipment suppliers, John Deere exemplifies the dealer-network-dependent archetype through its agricultural county distribution density. Husqvarna Group occupies a position within the battery-platform convergence tier, leveraging cross-compatible powertrain architecture. Brinly-Hardy Company anchors the domestic specialty fabricant segment with regionally concentrated production positioning.
| Leading Market Players |
|---|
| John Deere |
| Husqvarna Group |
| Brinly-Hardy Company |
| Agri-Fab, Inc. |
| Turfco Manufacturing |
| Great Plains Manufacturing |
| Landoll Corporation |
| Buhler Industries |
| Goplus |
| Others |
Value Network & Pricing Analysis
Electric-gasoline powertrain bifurcation splits the lawn roller market into divergent pricing architectures and sourcing configurations. Premium lithium-ion models command bundled service contracts through dealer networks while commodity gasoline units compete on unbundled transactional pricing through mass retail channels.
Pricing Analysis
Warranty and service-bundling separates electric from gasoline equipment value propositions. Three-tier pricing structure across premium, standard, and economy levels tracks powertrain certification grade and drum material specification. Steel drum input cost volatility compresses margin stability for domestic fabricators. Residential buyers exhibit highest price sensitivity, substituting manual polyethylene models for tow-behind configurations.
Supply Chain Analysis
Steel sheet supply rests on Great Lakes ferrous metal processing infrastructure and Chinese rolled steel imports. Lithium-ion cell production concentrates in South Korea, China, and Japan. Polyethylene resin draws from Gulf Coast petrochemical complexes and Canadian feedstock. Tariff exposure on Chinese steel components threatens margin stability for drum fabricators. Distribution runs through John Deere-aligned agricultural dealer networks and Big Box retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lawn roller market sits in a powertrain transition phase as lithium-ion battery systems displace small gasoline engines across commercial landscaping fleets. This technology replacement cycle compresses equipment refresh timelines and reshapes competitive positioning.
For Market Incumbents: Deepen battery-platform compatibility across landscaping portfolios to lock in professional user ecosystems. Expand polyethylene drum production capacity in Ohio and Illinois manufacturing clusters to capture residential substitution demand. Preempt EPA Phase 3 certification cost exposure by accelerating electric model development bandwidth.
For New Entrants and Emerging Players: The premium-economy price-point gap in commercial electric rollers offers white-space entry opportunity. Target municipal parks departments in noise-restricted Midwestern counties with multi-vendor procurement mandates. Pursue direct-to-superintendent sales channels bypassing concentrated dealer networks.
For Investors and Strategic Acquirers: Exit pathways concentrate in battery-platform convergent landscaping specialists with cross-compatible powertrain architecture. Five-to-ten year viability favors manufacturers with captive lithium-ion supply agreements and municipal fleet conversion exposure. Watch battery energy density improvement trajectories as fleet electrification inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Cross-compatible lithium-ion systems lock professional landscaping fleets into repeat attachment purchases. |
| Backward Integration into Drum Fabrication | In-house steel and polyethylene drum production insulates margin stability from ferrous metal price volatility. |
| Municipal Fleet Electrification Partnership | Direct procurement relationships with parks departments accelerate electric roller adoption ahead of regulatory mandates. |
| Smart Irrigation Integration Development | Sensor-equipped rollers communicating soil compaction data enable precision-agriculture premium pricing. |
| Corrosion-Resistant Material Expansion | UV-stabilized polyethylene construction captures coastal and salt-exposed maintenance operations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this lawn roller market analysis. Primary interviews with golf course superintendents, municipal parks procurement officers, commercial landscaping fleet managers, and agricultural equipment dealers combined with EPA certification databases, OSHA noise exposure guidelines, and municipal budget appropriations records. Bottom-up equipment unit shipment estimates triangulated against top-down maintenance expenditure allocations across the analysis window.
Data-stream reconciliation across powertrain technology, drum material specification, and use case segmentation generated volume and value outputs. Modeled dimensions spanned manual-electric-gasoline-tow-behind powertrain categories, steel-polyethylene-cast iron material grades, and residential-commercial-golf course-sports field end-use environments. CAGRs derived from replacement cycle compression analysis and municipal budget expansion trajectories. Battery chemistry improvement curves and EPA regulatory timeline assumptions shaped powertrain mix projections.
Underlying measurement precision varies by segment; electric roller forecasts carry tighter precision than gasoline equipment given visible municipal procurement pipeline data. Forecasts reflect documented assumptions on battery cost decline trajectories and regulatory enforcement intensity. Supply chain disruption from steel tariff policy shifts or lithium-ion cell allocation constraints warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Australia Kids Scooter Market
Outdoor & Sports
Fishing Tackle Box Market
Outdoor & Sports
Global Canoe and Kayak Market
Outdoor & Sports
Hunting Blinds Market
Outdoor & Sports
Inflatable Pool Market
Outdoor & Sports
Swimming Pool Liner Market
Outdoor & Sports
Camping Utensils Market
Outdoor & Sports
LED Fishing Light Market
Outdoor & Sports
Paintball Field Service Market
Outdoor & Sports
Cold Plunge Pools Market
Outdoor & Sports
Global Paintball Equipment Market
Outdoor & Sports
Global Baseball Gloves Market
Outdoor & Sports
Camping Beds and Mats Market
Outdoor & Sports
Fishing Line Market
Outdoor & Sports
Global Sailing Dinghy Masts Market
Outdoor & Sports
Freshwater Fishing Rod Market