
 Battery Free Wireless Sensor Market | 2026-2036
Battery Free Wireless Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Free Wireless Sensor Market Outlook
Industrial automation buyers are redrawing procurement priorities toward maintenance-free sensing architectures. EnOcean GmbH leverages proprietary energy-harvesting protocols to dominate building-automation channels across Europe. ON Semiconductor sustains R&D intensity in ultra-low-power RF transceivers that anchor its position in industrial IoT deployments.
Battery free wireless sensors harvest ambient kinetic, thermal, or electromagnetic energy to power microelectronic measurement and transmission circuits without chemical storage. These devices typically operate at sub-milliwatt power budgets, transmitting data via RFID backscatter or proprietary short-range protocols to eliminate battery replacement cycles in inaccessible installations. Energy Harvesting Sensors command the deepest margin pools due to custom transducer engineering, while RFID Technology segments compete on reader infrastructure compatibility. Thermal Energy Harvesting applications are concentrating in process industries where waste heat differentials exceed twenty degrees Celsius.
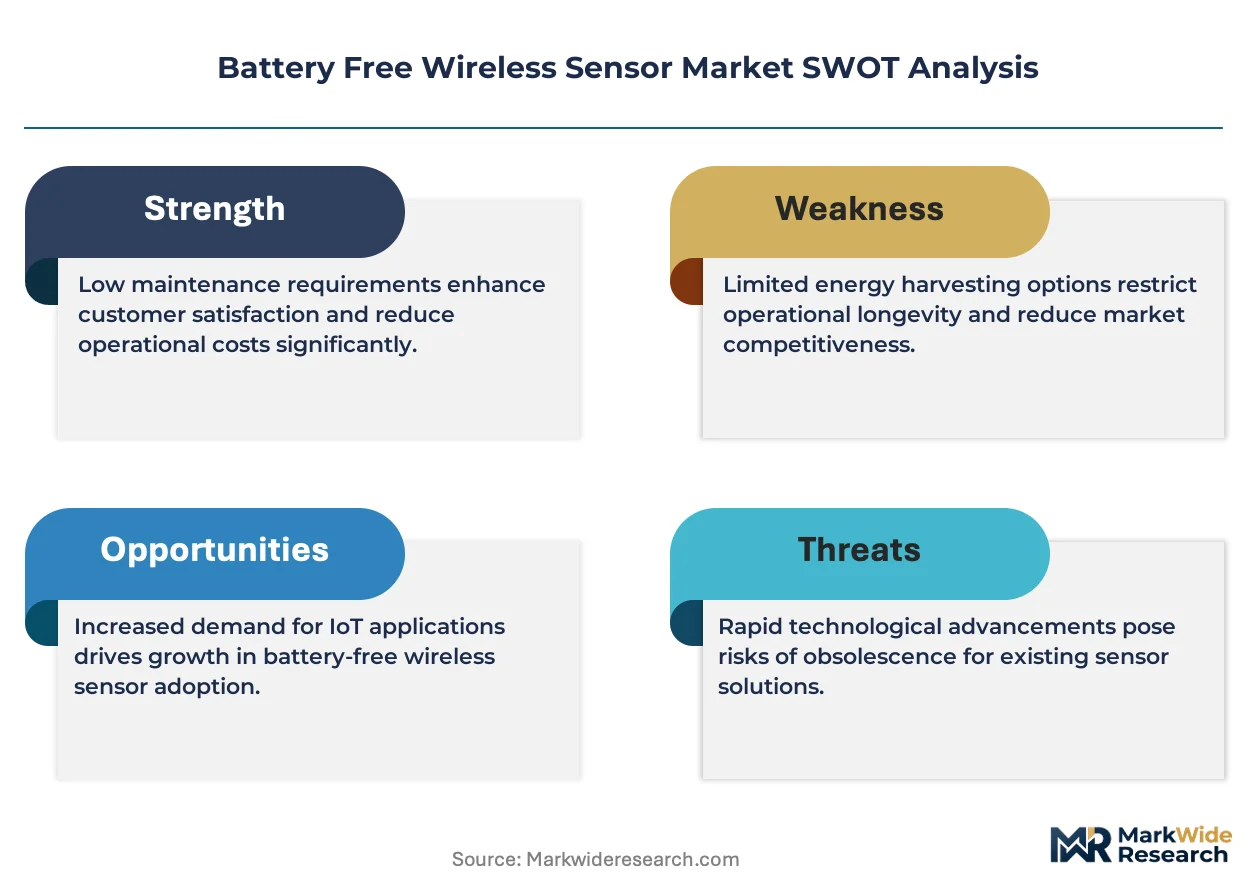
The EPA regulates hazardous battery waste streams under Resource Conservation and Recovery Act provisions, indirectly accelerating substitution toward batteryless architectures in US industrial facilities. REACH restrictions on lithium-ion cell chemistries, combined with CE marking mandates for electromagnetic compatibility, shape product qualification pathways for European market access. Stakeholders must monitor evolving ISO energy-harvesting performance standards and decide whether to certify for multi-regional compliance or specialize in single-jurisdiction deployments.
Market Dynamics
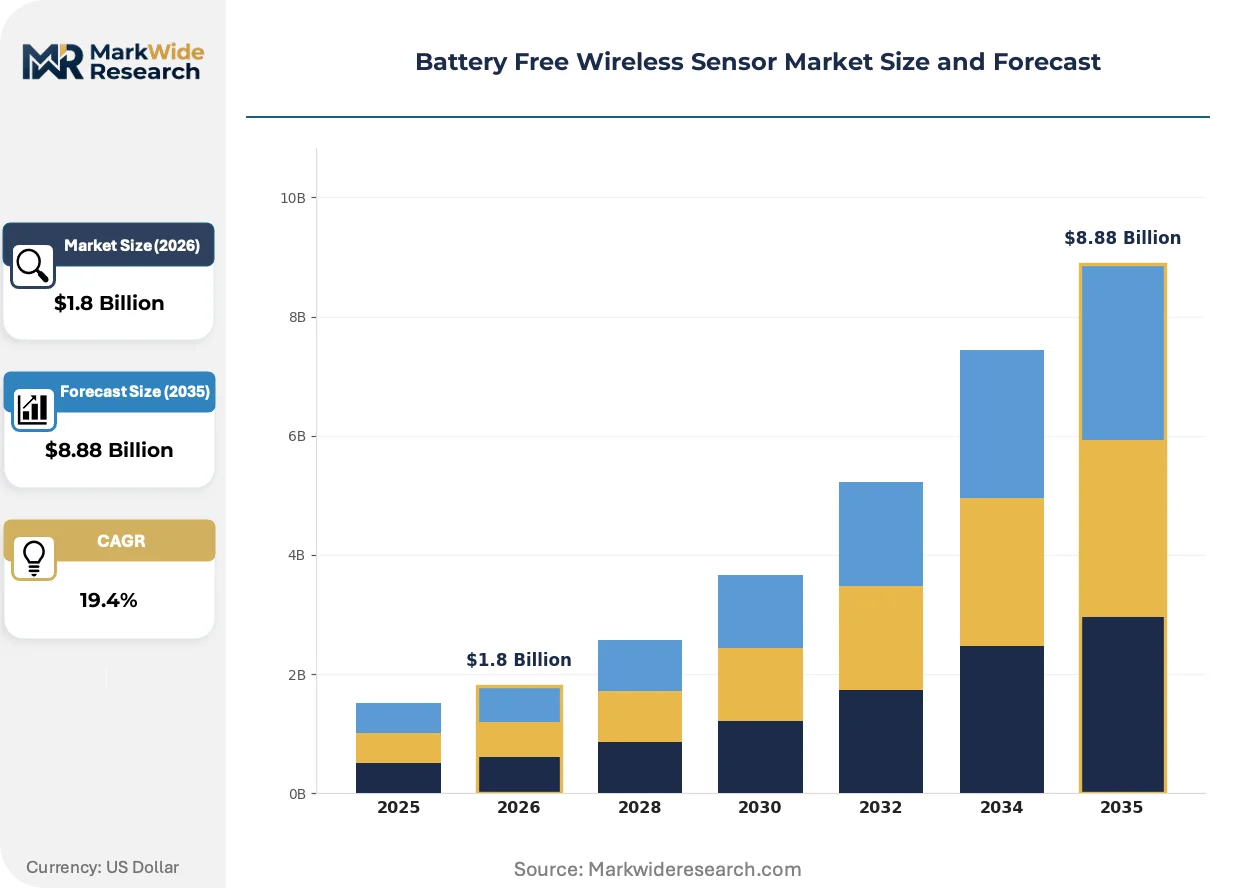
Energy-harvesting microelectronics are compressing replacement cycles for industrial sensing infrastructure, as predictive maintenance buyers prioritize zero-touch deployments over battery-dependent architectures requiring scheduled service interventions.
Growth Catalysts
- EU Green Deal battery disposal mandates:REACH chemical restrictions and member-state landfill directives are accelerating substitution toward batteryless sensor architectures in German and French process manufacturing facilities.
- RFID backscatter protocol maturation:Ultra-low-power communication standards now enable reliable data transmission across metallic industrial environments previously hostile to wireless signal propagation.
- Smart manufacturing clusters:Industrial automation investments in Japan's Aichi Prefecture and Michigan's automotive corridor are concentrating demand for maintenance-free kinetic energy harvesting devices.
Market Restraints
- Custom transducer engineering costs:Thermal gradient and piezoelectric harvester designs require application-specific optimization that inflates unit economics versus commodity battery alternatives.
- Reader infrastructure dependency:RFID Technology segments face deployment friction where legacy industrial Ethernet architectures lack compatible gateway hardware for backscatter signal processing.
- Sub-milliwatt power budget constraints:Measurement fidelity and transmission range trade-offs limit sensor applicability in high-resolution vibration monitoring applications.
Strategic Opportunities
- Process industry waste heat recovery:Thermal Energy Harvesting applications remain underpenetrated in Gulf Coast petrochemical facilities where stack exhaust differentials exceed harvestable thresholds.
- CE marking electromagnetic compatibility harmonization:Streamlined qualification pathways for multi-jurisdiction deployments reduce certification overhead for European market access expansion.
- Building automation retrofits:Kinetic switch and solar-powered occupancy sensors address sustainability mandates in aging commercial real estate stock across German metropolitan zones.
Industry Challenges
- ISO energy-harvesting performance standardization delays:Absence of unified test protocols complicates buyer evaluation of vendor claims for power output and reliability metrics.
- Legacy SCADA integration complexity:Batteryless sensor deployments require protocol translation layers that extend commissioning timelines in brownfield industrial environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Free Wireless Sensor Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Harvesting Sensors, Radio-Frequency Devices, Ultra-Low Power Transmitters, Energy-Scavenging Modules Technology: RFID Technology, Vibration Energy Harvesting, Thermal Energy Harvesting, Solar Energy Collectors End User: Industrial Automation, Smart Homes, Healthcare, Retail Environments Installation: Surface-Mounted Sensors, Embedded Sensors, Wall-Mounted Units, Ceiling Installations |
| Companies Covered | EnOcean GmbH, ON Semiconductor, Axzon, Farsens, Inductosense, Phase IV Engineering, Powercast, Distech Controls, DCO Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Free Wireless Sensor Market Strategic Shifts
Photovoltaic-enhanced kinetic harvesters are expanding addressable applications beyond traditional thermal-gradient niches, while regulatory chemistry restrictions reshape component sourcing strategies across industrial sensor supply chains.
Multi-source energy harvesting is supplanting single-transducer designs in mission-critical predictive maintenance deployments. German automotive OEMs now specify hybrid photovoltaic-piezoelectric architectures for conveyor monitoring. This convergence is compressing vendor differentiation around power management silicon rather than transducer mechanics alone.
EPA Resource Conservation and Recovery Act enforcement is tightening hazardous waste documentation for lithium-primary cell disposal in US manufacturing facilities. Industrial EHS managers face audit exposure from legacy battery-powered sensor populations. Process industries in Texas and Louisiana are prioritizing batteryless retrofits during scheduled turnaround windows.
Buyer specification behavior is hardening around total-cost-of-ownership metrics that internalize battery replacement labor and disposal compliance. Procurement teams in Japanese electronics manufacturing now weight ten-year maintenance forecasts above upfront hardware expenditure. This calculus favors energy-harvesting architectures despite premium unit pricing.
Battery Free Wireless Sensor Market Segmentation
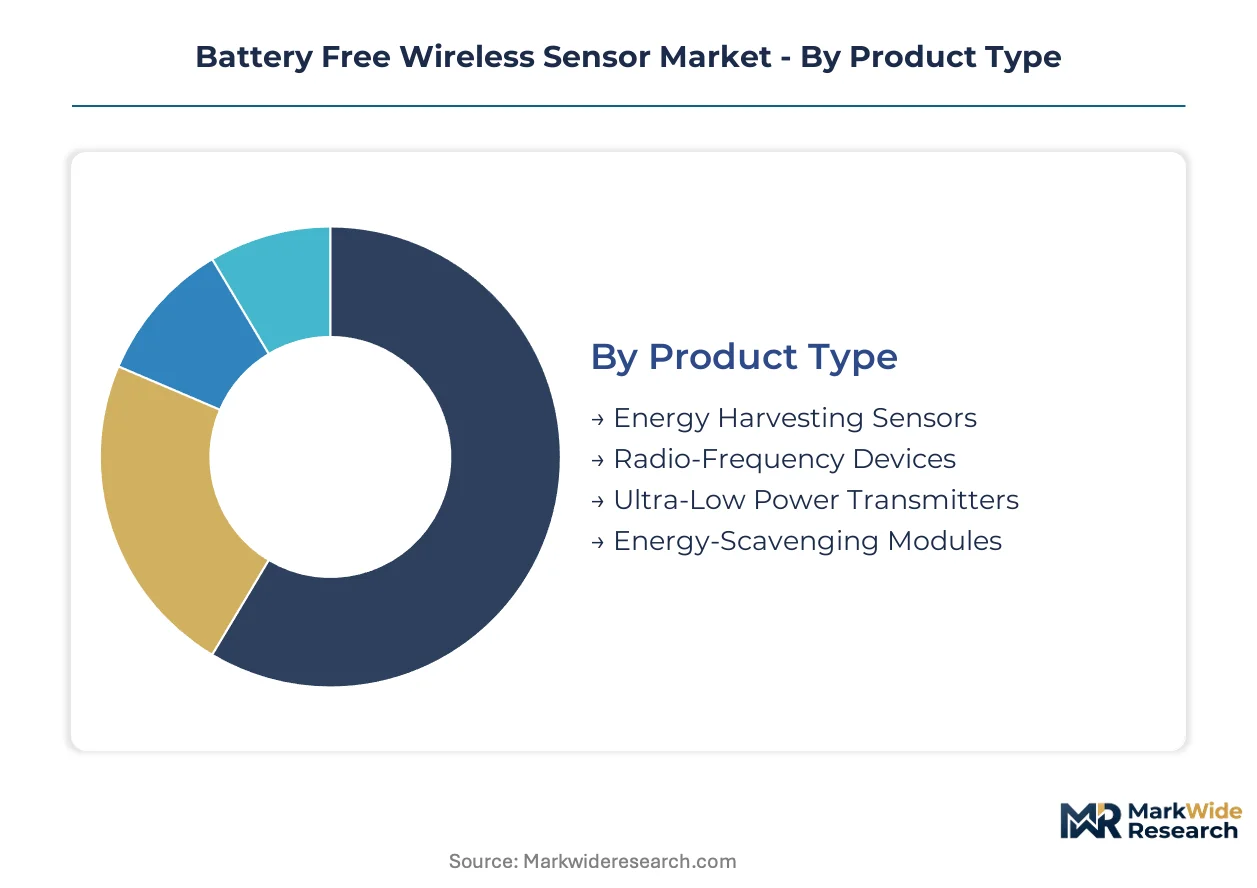
Segmentation in the battery free wireless sensor market exposes how margin pools concentrate in energy-harvesting transducers versus commodity RF components. Buyers prioritize architectures that eliminate maintenance cycles over lowest upfront hardware cost.
Product Type:
Margin pools sit deepest in custom transducer engineering where application-specific optimization commands pricing premiums over standardized modules.
- Energy Harvesting Sensors:Piezoelectric, thermoelectric, and electromagnetic transducers convert ambient kinetic or thermal gradients into electrical power for microelectronic circuits. German automotive OEMs specify these for conveyor monitoring in Aichi Prefecture smart manufacturing clusters where zero-touch maintenance is mandatory.
- Radio-Frequency Devices:Backscatter communication modules transmit data via reflected carrier waves from external reader infrastructure. Deployment concentrates in US process facilities facing EPA Resource Conservation and Recovery Act enforcement on lithium-primary cell disposal documentation.
- Ultra-Low Power Transmitters:Sub-milliwatt RF transceivers optimized for proprietary short-range protocols.
- Energy-Scavenging Modules:Integrated power management circuits combining multiple harvester inputs with storage capacitors.
Energy Harvesting Sensors hold installed capacity. Ultra-Low Power Transmitters is rotating up the share rankings.
Technology:
Application requirements across metallic industrial environments and building automation retrofits determine which harvester physics dominate deployment decisions.
- RFID Technology:Passive backscatter systems eliminate onboard power storage through electromagnetic coupling with reader infrastructure. Reader compatibility constraints create deployment friction in legacy industrial Ethernet architectures lacking gateway hardware for signal processing.
- Thermal Energy Harvesting:Thermoelectric generators exploit temperature differentials exceeding twenty degrees Celsius in process industry exhaust streams. Gulf Coast petrochemical facilities in Texas and Louisiana prioritize these retrofits during scheduled turnaround windows.
- Vibration Energy Harvesting:Piezoelectric cantilevers capture mechanical oscillation from rotating machinery.
- Solar Energy Collectors:Photovoltaic cells power indoor sensors under artificial lighting conditions.
Thermal Energy Harvesting holds installed capacity. Vibration Energy Harvesting is rotating up the share rankings.
End User:
Procurement sophistication varies sharply between industrial predictive maintenance buyers and consumer-facing smart home installers.
- Industrial Automation:Predictive maintenance deployments in smart manufacturing corridors demand maintenance-free kinetic architectures. Japanese electronics manufacturers now weight ten-year maintenance forecasts above upfront hardware expenditure in total-cost-of-ownership calculations.
- Healthcare:Patient monitoring and asset tracking applications require electromagnetic compatibility certification under CE marking and FDA device regulations.
- Smart Homes:Kinetic switch and solar-powered occupancy sensors address sustainability mandates in aging commercial real estate.
- Retail Environments:Cold chain monitoring and inventory tracking leverage RFID backscatter for battery-free operation.
Industrial Automation holds installed capacity. Healthcare is rotating up the share rankings.
Installation:
Physical mounting constraints determine harvester accessibility to ambient energy sources and signal propagation characteristics.
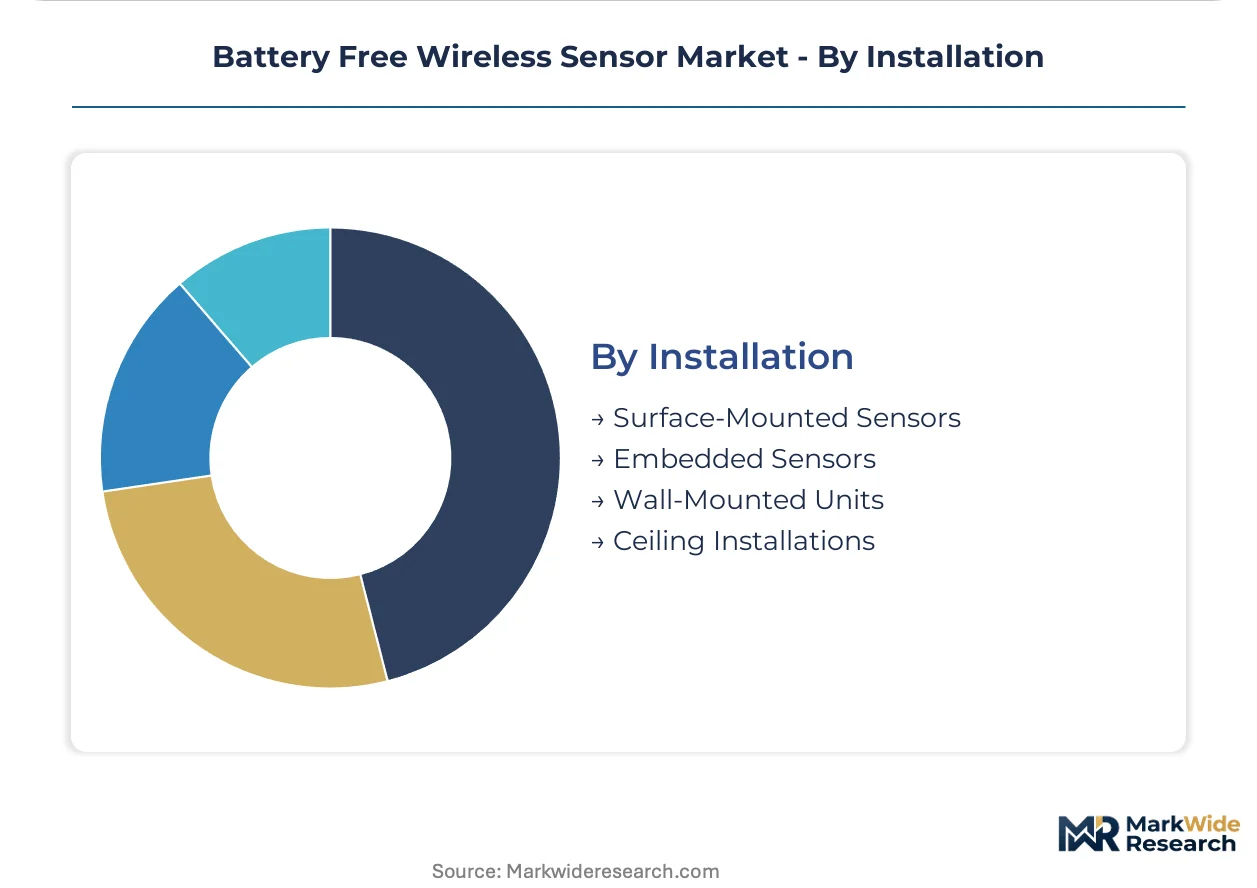
- Surface-Mounted Sensors:Exposed installations on machinery housings optimize vibration energy capture from rotating equipment. Brownfield industrial environments require protocol translation layers that extend commissioning timelines for these deployments.
- Embedded Sensors:Integration within structural elements or equipment enclosures protects transducers from environmental exposure. REACH chemical restrictions on lithium-ion cell chemistries accelerate substitution toward these batteryless architectures in German and French process manufacturing facilities.
- Wall-Mounted Units:Building automation applications for occupancy detection and climate control.
- Ceiling Installations:Overhead positioning optimizes solar harvester exposure to artificial lighting.
Surface-Mounted Sensors hold installed capacity. Embedded Sensors is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports energy-harvesting sensor components to Japanese automotive OEMs, while US process manufacturers import thermal harvesting systems from European suppliers to meet EPA disposal mandates.
United States
Industrial automation buyers in Michigan's automotive corridor and Texas petrochemical facilities drive demand for maintenance-free kinetic architectures. EPA Resource Conservation and Recovery Act enforcement tightens hazardous waste documentation for lithium-primary cell disposal. Gulf Coast process industries in Louisiana prioritize batteryless retrofits during scheduled turnaround windows.
Germany
Smart manufacturing investments concentrate in Bavaria and Baden-Württemberg where automotive OEMs specify zero-touch maintenance protocols. EU Green Deal battery disposal mandates and REACH chemical restrictions accelerate substitution toward batteryless architectures. Aichi Prefecture-bound exports from German suppliers serve Japanese electronics manufacturers.
Japan
Electronics manufacturers in Aichi Prefecture and Kanto region weight ten-year maintenance forecasts above upfront hardware expenditure in procurement calculations. METI industrial standards shape electromagnetic compatibility requirements for building automation deployments. Nagoya-area automotive clusters demand hybrid photovoltaic-piezoelectric conveyor monitoring systems.
United Kingdom
Building automation retrofits in London metropolitan zones address sustainability mandates through kinetic switch and solar-powered occupancy sensors. CE marking electromagnetic compatibility harmonization streamlines qualification pathways for European market access. Midlands-based process manufacturers evaluate thermal harvesting for waste heat recovery applications.
France
Process manufacturing facilities in Auvergne-Rhône-Alpes respond to REACH restrictions on lithium-ion cell chemistries with embedded sensor deployments. ANSM and CNIL oversight extends to healthcare asset tracking applications requiring electromagnetic compatibility certification. Île-de-France commercial real estate operators pilot batteryless climate control installations.
Battery Free Wireless Sensor Market Competitive Environment
Player mix skews toward specialized energy-harvesting protocol developers and ultra-low-power semiconductor fabricators rather than diversified industrial conglomerates. The competitive terrain separates into three strategic archetypes: proprietary protocol licensors, RF transceiver specialists, and integrated building automation providers. M&A activity concentrates on protocol stack acquisitions, while capacity expansion targets multi-source harvester manufacturing for hybrid photovoltaic-piezoelectric architectures.
Among European protocol developers, EnOcean GmbH exemplifies the proprietary energy-harvesting licensor archetype, while ON Semiconductor occupies a position within the RF transceiver specialist tier. Powercast represents the integrated power management approach. These three anchors illustrate how competitive positioning depends on whether vendors control protocol standards, semiconductor components, or complete subsystem integration.
| Leading Market Players |
|---|
| EnOcean GmbH |
| ON Semiconductor |
| Axzon |
| Farsens |
| Inductosense |
| Phase IV Engineering |
| Powercast |
| Distech Controls |
| DCO Systems |
| Others |
Value Chain & Pricing Dynamics
CE marking electromagnetic compatibility harmonization gates both European market access and price tiering for battery-free wireless sensor vendors, compressing qualification timelines for premium-certified architectures while relegating non-compliant modules to project-specific economy tiers.
Pricing Analysis
Next-generation hybrid photovoltaic-piezoelectric harvesters command 40-60% premiums over single-transducer prior-generation units, while legacy RFID backscatter modules face commoditization in high-volume building automation deployments. Three-tier pricing structure across premium, standard, and economy levels separates ISO-certified industrial-grade sensors from commercial building automation units and unbranded retrofit modules. Cost compression in standard-tier piezoelectric harvesters is intensifying because German automotive OEMs are consolidating supplier panels around qualified vendors. Healthcare asset tracking buyers exhibit lowest price sensitivity due to FDA and CE dual-certification requirements, while retail cold chain operators drive hardest bargain negotiations on per-unit RFID tag economics.
Supply Chain Analysis
Inventory lead times for thermoelectric generator substrates have extended from German specialty materials suppliers to Japanese electronics manufacturers, creating buffer stock pressure across Aichi Prefecture smart manufacturing corridors. Manufacturing concentrates in Germany, Japan, and the United States, with Taiwan anchoring power management semiconductor fabrication. Raw material dependencies center on bismuth telluride for thermoelectric transducers, PZT ceramics for piezoelectric harvesters, and ultra-low-power RF silicon. Single-source vulnerability persists in proprietary energy-harvesting protocol licensing from European developers. Distribution runs through industrial automation system integrators in Michigan and Texas, building automation distributors in German metropolitan zones, and direct OEM supply agreements for Japanese automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-free wireless sensor adoption sits in early-cycle expansion as EU Green Deal disposal mandates and EPA enforcement actions simultaneously eliminate battery-dependent alternatives across industrial facilities.
For Market Incumbents: Consolidate proprietary protocol licensing positions through exclusive partnerships with German automotive OEMs specifying zero-touch maintenance architectures. Deepen backward integration into custom transducer manufacturing to defend margin pools against emerging RF transceiver specialists. Capacity addition in Baden-Württemberg serves Aichi Prefecture export demand while insulating against REACH chemical restriction compliance costs. For New Entrants and Emerging Players: CE marking fast-track pathways for electromagnetic compatibility certification unlock building automation retrofits in aging London and Frankfurt commercial real estate as the most penetrable white-space target. Gulf Coast petrochemical thermal harvesting applications remain underpenetrated due to incumbent focus on kinetic architectures. Go-to-market through industrial EHS managers facing EPA audit exposure from legacy battery populations accelerates initial traction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across multi-source harvester manufacturing as hybrid photovoltaic-piezoelectric designs supplant single-transducer engineering. Five-to-ten-year viability favors acquisition targets with captive protocol stacks and qualified transducer fabrication rather than commodity RF module assemblers. Signal to monitor: Japanese electronics manufacturer procurement teams shifting ten-year total-cost-of-ownership weightings above upfront hardware expenditure in RFP evaluations.| Strategic Initiative | Industry Significance |
|---|---|
| Protocol Stack Acquisition | Proprietary energy-harvesting licensure from EnOcean GmbH anchors European building automation channel control. |
| Multi-Source Harvester Manufacturing Scale-Up | Hybrid photovoltaic-piezoelectric capacity expansion serves Nagoya-area automotive conveyor monitoring specifications. |
| CE Marking Harmonization Investment | Streamlined electromagnetic compatibility qualification reduces certification overhead for German-French cross-border deployments. |
| Industrial EHS Manager Direct Engagement | EPA Resource Conservation and Recovery Act audit exposure drives batteryless retrofit urgency in Texas and Louisiana facilities. |
| RF Transceiver R&D Intensification | Ultra-low-power silicon development sustains competitive positioning in Michigan automotive corridor predictive maintenance. |
Study Parameters
The analysis maps energy-harvesting transducer engineering, RFID backscatter protocol deployment, and ultra-low-power RF semiconductor fabrication, each validated through maintenance directors at process manufacturing facilities, procurement leads at German automotive OEMs, building automation system integrators, and industrial EHS compliance officers. Primary interview findings cross-reference customs data on thermoelectric generator substrate trade flows, SEC filings from RF semiconductor fabricators, EPA enforcement action databases, and EU Green Deal implementation progress reports. Bottom-up unit economics triangulate against top-down smart manufacturing investment tracking across Aichi Prefecture, Bavaria, and Michigan.
Consistency checks validated volume and value outputs against industrial automation capex disclosures from Japanese electronics manufacturers, German automotive OEM supplier panel announcements, and US process industry turnaround schedules. Segmentation dimensions span harvester physics type, communication protocol architecture, end-use industry vertical, installation mounting configuration, and regional regulatory cluster. CAGRs derive from adoption curve modeling calibrated to procurement specification behavior shifts. Forecast inputs incorporate REACH chemical restriction phase-in timelines and METI industrial standard evolution pathways.
Underlying assumptions cover EPA enforcement continuity, EU member-state landfill directive harmonization, and ISO energy-harvesting performance standard finalization, with deviation risk concentrated in legacy SCADA integration complexity delays and reader infrastructure upgrade cycles. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Mexico Digital Thermometer Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
Meteorological Devices Market
Sensors and Controls
Pressure Sensor Market
Sensors and Controls
Bulk Acoustic Wave Sensors Market
Sensors and Controls
Battery Module Sensors Market
Sensors and Controls
Motion Sensor Market
Sensors and Controls
Environmental Noise Cancellation Microphones Market
Sensors and Controls
Nano Positioning System Market
Sensors and Controls
Depth Sensing Market
Sensors and Controls
North America Nano Sensors Market
Sensors and Controls
Piece-Level Inventory Tracking and Vision Systems Market
Sensors and Controls
On-Board Magnetic Sensors Market
Sensors and Controls
MEMS for Mobile Devices Market
Sensors and Controls
Sensor Development Kit Market
Sensors and Controls
APAC Vibration Sensors Market