
 Fertility Tourism Market | 2026-2036
Fertility Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Fertility Tourism Market Intelligence
Cross-border egg donation programs is reshaping margin distribution within reproductive healthcare networks. IVI RMA Global leverages its pan-European clinic infrastructure to coordinate donor-recipient matching across multiple jurisdictions. Bumrungrad International Hospital anchors medical tourism flows from Australia and the Middle East through Bangkok's established hospitality-healthcare ecosystem. Barcelona IVF specializes in donor anonymity protocols that comply with Spanish legislation while serving Northern European patients.
Fertility tourism encompasses the travel of individuals or couples across national borders to access assisted reproductive technologies, donor gametes, or gestational surrogacy arrangements unavailable, prohibited, or cost-prohibitive in their home jurisdictions. The practice typically involves coordination between fertility clinics, legal advisors, travel logistics providers, and cross-border medical record systems to manage treatment cycles, donor matching, and parental establishment procedures. IVF services command the largest revenue share among service types due to higher per-cycle pricing and repeat treatment requirements, while fertility preservation segments expand fastest among younger patients deferring parenthood. LGBTQ+ couples and single parents represent the most structurally underserved customer base, creating concentrated demand in destinations with inclusive eligibility criteria.
Spain's Ministry of Health regulates donor anonymity and compensation limits under national assisted reproduction law, while Greece permits altruistic surrogacy for foreign nationals under specific judicial pre-approvals. Thailand's Medical Council enforces restrictions on commercial surrogacy that redirect regional demand toward legitimate clinical pathways. Stakeholders must monitor evolving citizenship and parentage recognition rules in patients' home countries, as legal retroactivity risks strand completed treatments without valid family status documentation.
Market Dynamics
Cross-border reproductive care is restructuring around regulatory arbitrage, as patients from restrictive jurisdictions systematically redirect demand toward clinical corridors with permissive donor anonymity laws and altruistic surrogacy frameworks. This geographic sorting of demand is compressing treatment timelines and fragmenting margin pools across international clinic networks.
Growth Catalysts
- Spain's donor anonymity statutes:Spanish assisted reproduction law shields egg and sperm donor identities, attracting Northern European patients from jurisdictions with identity disclosure mandates. This regulatory differential sustains Barcelona and Madrid as Mediterranean fertility hubs.
- Altruistic surrogacy judicial pathways:Greece permits court-preapproved gestational surrogacy for foreign nationals, channeling Middle Eastern and Asian demand into Athens-based clinical networks with established legal coordination protocols.
- Elective fertility preservation:Social egg freezing among professionals deferring parenthood is expanding cryostorage utilization rates in urban clinic clusters, particularly among patients aged 28-35 seeking future optionality.
Market Restraints
- Donor gamete supply constraints:Compensation caps under Spanish and Greek donor regulations limit recruitment pools, creating waitlist bottlenecks for phenotype-matched egg donations in high-demand periods.
- Parentage recognition retroactivity:Citizenship and family status documentation in patients' home countries often fails to recognize foreign birth certificates or surrogacy judgments, stranding completed treatments without valid legal standing.
- Clinical accreditation fragmentation:Absence of harmonized cross-border quality standards permits uneven success rate reporting, complicating patient decision-making and inflating due diligence costs.
Strategic Opportunities
- Thailand's legitimate clinical pathway redirection:Medical Council enforcement against commercial surrogacy is consolidating demand around accredited Bangkok hospitals with integrated legal advisory services, creating defensible positioning for compliant operators.
- Telemedicine-enabled cycle coordination:Remote monitoring protocols allow patients to complete ovarian stimulation at home before brief surgical travel, reducing accommodation costs and expanding addressable patient geography.
- LGBTQ+ inclusive eligibility frameworks:Destinations permitting same-sex couple and single-parent access without medical infertility prerequisites capture structurally underserved demand from restrictive home markets.
Industry Challenges
- Embryologist talent scarcity:Specialized laboratory personnel with vitrification and PGT-A competencies command premium compensation, constraining clinic expansion velocity in secondary markets.
- Cross-border medical record interoperability:Fragmented electronic health data standards between originating and destination jurisdictions delay treatment initiation and elevate clinical risk during handoff protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fertility Tourism Market |
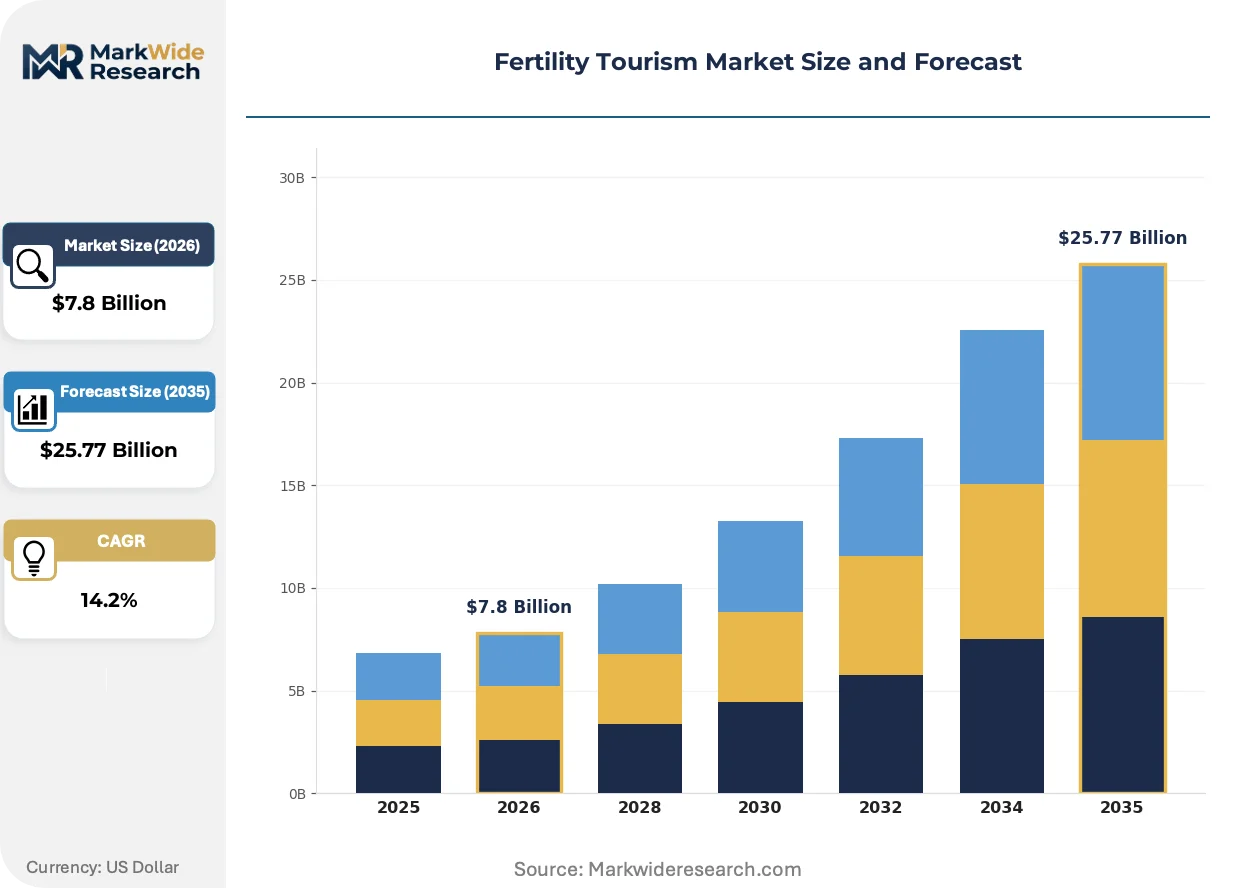
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $25.77 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: IVF, Egg Donation, Surrogacy, Fertility Preservation Customer Type: Individual Couples, LGBTQ+ Couples, Single Parents, Foreign Nationals Destination Type: Clinics, Hospitals, Wellness Resorts, Private Practices Payment Model: Direct Pay, Insurance Coverage, Package Deals, Funded Programs |
| Companies Covered | IVI RMA Global, San Diego Fertility Center, IVF-Life, Barcelona IVF, Eva Fertility Clinics, The Surrey Park Clinic, Bumrungrad International Hospital, Assisted Reproduction and Gynecology Centre, Sincere IVF Center, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fertility Tourism Market Strategic Shifts & Innovations
Reproductive healthcare delivery is converging with hospitality logistics and legal advisory services into integrated cross-border care platforms. This bundling is compressing patient coordination friction while elevating service differentiation requirements for clinic operators.
Artificial intelligence-driven embryo selection algorithms are digitizing morphokinetic assessment workflows, replacing manual grading by embryologists with time-lapse imaging analysis. European and Southeast Asian clinics with high-volume IVF programs are adopting these platforms to standardize transfer decisions. This digitizing of selection criteria is reducing inter-operator variability and compressing the multiple-cycle burden on patients.
GDPR's cross-border health data provisions are reshaping how EU-originating patient records transfer to non-EU treatment destinations, with Spanish clinics investing in EU-standard data architecture to maintain compliance. The regulation's extraterritorial reach is elevating infrastructure costs for Mediterranean operators serving Northern European demand. Smaller Greek clinics without dedicated data protection officers are outsourcing record management to compliant third-party platforms.
Patient acquisition is fragmenting away from traditional referral networks toward direct-to-consumer digital channels with transparent pricing and outcome data. Fertility aggregators and comparison platforms are displacing general practitioner and obstetrician gatekeeping, particularly among younger patients researching options independently. This channel shift is most pronounced in English-speaking source markets with high digital health literacy and limited domestic treatment access.
Fertility Tourism Market Segmentation
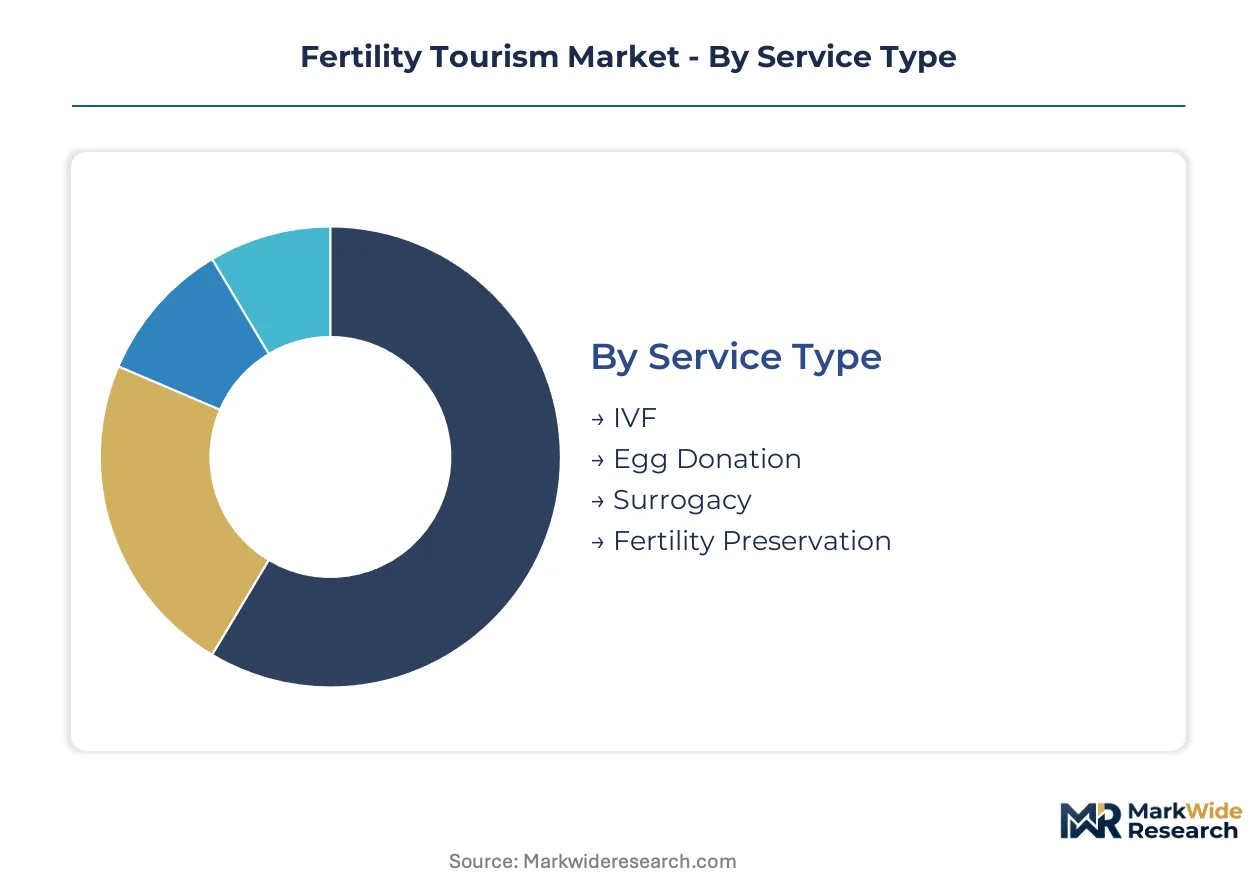
Service type segmentation determines margin capture velocity in fertility tourism, with treatment complexity dictating cycle duration and repeat visit frequency. Customer origin and destination configuration shape regulatory exposure and pricing power across clinic networks.
Service Type:
IVF cycles turn over fastest with compressed stimulation-to-retrieval timelines, while surrogacy arrangements extend across 12-18 month coordination horizons involving judicial pre-approval and gestational carrier matching.
- IVF:Ovarian stimulation, egg retrieval, laboratory fertilization, and embryo transfer protocols constitute the technical core of cross-border reproductive care. Demand concentrates in Spanish and Greek clinical corridors where donor anonymity statutes and altruistic surrogacy frameworks attract Northern European patients facing restrictive home jurisdiction regulations.
- Egg Donation:Anonymous donor-recipient matching programs operate under Spain's assisted reproduction law with compensation caps and phenotype screening protocols. Athens and Barcelona clinics report waitlist compression during peak demand periods as phenotype-matched donor pools face recruitment constraints under altruistic compensation structures.
- Surrogacy:Court-preapproved gestational arrangements in Greece channel Middle Eastern and Asian demand through specialized legal coordination protocols.
- Fertility Preservation:Social egg freezing among professionals aged 28-35 drives cryostorage utilization in urban clinic clusters.
IVF dominates installed base. Fertility preservation is where expansion concentrates.
Customer Type:
Cost tier stratification separates premium self-pay segments from insurance-reimbursed flows, with single parents and LGBTQ+ couples typically operating outside coverage networks.
- Individual Couples:Heterosexual couples with diagnosed infertility constitute the traditional core demand base, often seeking cost differentials between home and destination jurisdictions.
- LGBTQ+ Couples:Same-sex male couples requiring gestational surrogacy and egg donation face structural exclusion from domestic treatment access in restrictive jurisdictions, redirecting demand toward Spain, Greece, and Thailand corridors with inclusive eligibility criteria.
- Single Parents:Unmarried individuals pursuing autonomous parenthood represent the steepest expansion trajectory, particularly among professional women accessing donor insemination and egg freezing services.
- Foreign Nationals:Cross-border patients from Australia, the Middle East, and East Asia leverage Bangkok and Mediterranean clinical networks for regulatory arbitrage and cost optimization.
Individual couples dominate installed base. LGBTQ+ couples and single parents represent where expansion concentrates.
Destination Type:
Volume concentration varies by care intensity, with high-complexity IVF and surrogacy consolidating in hospital-based platforms while wellness-adjacent services fragment across resort configurations.
- Clinics:Specialized reproductive medicine centers in Barcelona, Madrid, and Athens coordinate pan-European donor networks with integrated legal advisory services.
- Hospitals:Bumrungrad International Hospital anchors Bangkok's medical tourism corridor with accreditation standards and hospitality-healthcare integration that capture Australian and Middle Eastern flows.
- Wellness Resorts:Recovery-oriented accommodations adjacent to clinical facilities serve ovarian stimulation monitoring and post-retrieval recuperation demand.
- Private Practices:Boutique reproductive endocrinology operations serve high-net-worth patients with personalized coordination and expedited donor matching.
Hospitals dominate installed base. Clinics represent where expansion concentrates.
Payment Model:
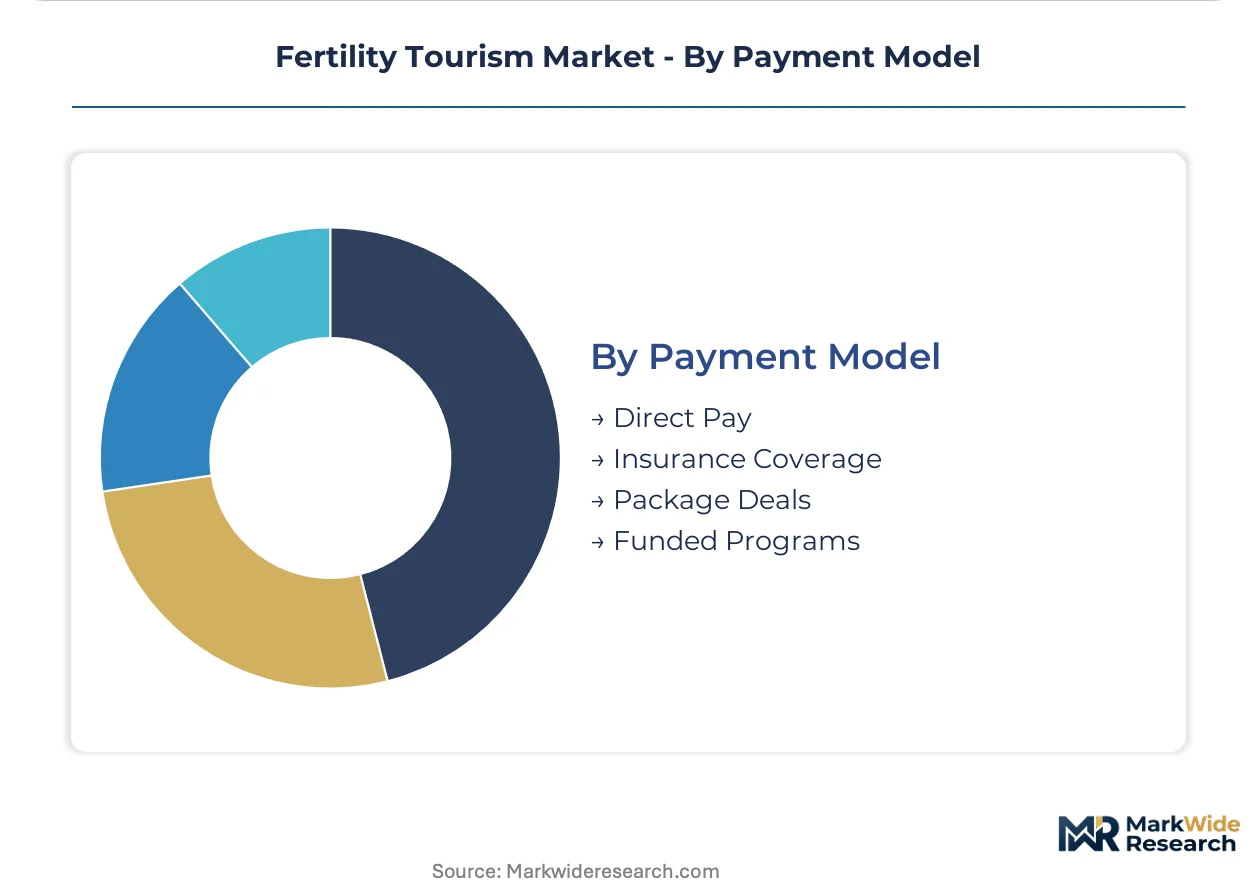
Margin structure diverges sharply between direct-pay premium pricing and package-deal bundling, with insurance coverage penetration remaining geographically fragmented.
- Direct Pay:Self-funded patients absorb full treatment costs plus travel logistics, enabling price transparency and immediate scheduling without pre-authorization delays.
- Insurance Coverage:Reimbursement eligibility varies by home jurisdiction mandate, with some Northern European systems permitting partial cross-border fertility treatment claims under EU directive frameworks.
- Package Deals:Multi-cycle bundles with guaranteed refund provisions reduce per-visit coordination friction and lock in patient commitment across extended treatment horizons.
- Funded Programs:Employer-sponsored fertility benefits and crowdfunding platforms expand addressable demand among younger patient segments with limited liquid savings.
Direct pay dominates installed base. Package deals represent where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns in fertility tourism diverge sharply by home jurisdiction restrictiveness. Patients from countries with donor identity disclosure mandates or surrogacy prohibitions systematically redirect demand toward Mediterranean and Southeast Asian clinical corridors where regulatory arbitrage compresses treatment timelines and expands eligibility criteria.
Spain
Same-sex couples and single parents from Northern Europe drive demand for anonymous egg donation cycles. The country's assisted reproduction law shields donor identities under Ministry of Health oversight, while compensation caps limit recruitment pools. Barcelona and Madrid clinic clusters coordinate pan-European donor-recipient matching with integrated legal advisory services.
Greece
Middle Eastern and Asian patients seek court-preapproved altruistic surrogacy arrangements unavailable in home jurisdictions. Judicial authorization frameworks permit gestational carrier agreements for foreign nationals under specific protocols. Athens-based clinical networks specialize in legal coordination pathways that channel regional demand through established surrogacy corridors.
Thailand
Australian and Middle Eastern patients leverage Bangkok's hospitality-healthcare ecosystem for cost-optimized IVF and fertility preservation. Medical Council enforcement against commercial surrogacy redirects demand toward accredited hospitals with compliant clinical pathways. Bumrungrad International Hospital anchors this corridor with integrated travel logistics and accreditation standards.
United States
International patients from restrictive jurisdictions access gestational surrogacy and advanced reproductive technologies in California and New York fertility hubs. FDA oversight of assisted reproductive technology products ensures quality standards, while state-level surrogacy permissiveness varies. San Diego and New York Metro clinic clusters attract cross-border demand through specialized legal frameworks and high-complexity laboratory services.
United Kingdom
Domestic patients facing NHS waiting lists or donor shortages seek treatment in Spain and Greece under EU directive frameworks permitting partial cross-border reimbursement. HFEA regulation of fertility treatment and donor identity disclosure mandates create outbound demand pressure. London and Southeast clinic networks coordinate referral partnerships with Mediterranean destinations.
Fertility Tourism Market Key Industry Players
Capability concentration sits with specialized reproductive medicine networks; scale advantage sits with integrated hospital platforms. The market structures around pan-European clinic chains with coordinated donor pools, destination hospital anchors with hospitality-healthcare integration, and boutique operations serving high-net-worth segments with personalized coordination. Strategic archetypes include regulatory arbitrage specialists, volume-driven IVF factories, and concierge surrogacy coordinators. Competitive moves center on geographic expansion through clinic acquisitions and technology licensing for embryo selection algorithms.
Within the pan-European network tier, IVI RMA Global and IVF-Life exemplify coordinated donor-recipient matching across multiple jurisdictions. Barcelona IVF occupies a position within the Mediterranean anonymity-specialist archetype, leveraging Spanish legislative frameworks to serve Northern European demand. Bumrungrad International Hospital anchors the Southeast Asian hospital-integrated model, capturing Australian and Middle Eastern flows through Bangkok's established medical tourism infrastructure.
| Leading Market Players |
|---|
| IVI RMA Global |
| San Diego Fertility Center |
| IVF-Life |
| Barcelona IVF |
| Eva Fertility Clinics |
| The Surrey Park Clinic |
| Bumrungrad International Hospital |
| Assisted Reproduction and Gynecology Centre |
| Sincere IVF Center |
| Others |
Cost & Logistics Intelligence
Barcelona's clinic cluster concentrates cryostorage capacity and embryology laboratory infrastructure, translating localized supply scarcity into premium pricing power for phenotype-matched donor cycles. Cost compression in Bangkok's hospital-integrated corridors feeds from Thailand's Medical Council enforcement redirecting demand toward compliant operators with hospitality-healthcare bundling.
Pricing Analysis
Project-based contracting dominates fertility tourism, with multi-cycle bundles incorporating guaranteed refund provisions reducing per-visit coordination friction. Price differentiation centers on donor phenotype matching precision and judicial pre-approval speed for surrogacy arrangements. Pricing pressure stems from compensation caps under Spanish and Greek donor regulations limiting recruitment pools. Self-funded patients absorb full treatment costs without pre-authorization delays, while insurance-reimbursed segments exhibit elevated price sensitivity due to partial cross-border claim eligibility.
Supply Chain Analysis
Donor gamete supply draws from Spain, Greece, and the United States as primary recruitment jurisdictions under varying compensation frameworks. Cryopreservation media, time-lapse incubators, and PGT-A testing kits constitute critical input dependencies. Single-source vulnerability concentrates in specialized embryologist talent pools with vitrification competencies. Distribution runs through pan-European clinic networks coordinating donor-recipient matching across multiple jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among digitally empowered patients researching options independently, fragmenting traditional physician referral gatekeeping. This shift elevates price transparency demands and compresses margin capture for clinic operators lacking direct-to-consumer channel control.
For Market Incumbents: Insulate donor pool access through exclusive recruitment partnerships in high-phenotype-diversity geographies, countering compensation-cap constraints. Deepen backward integration into cryostorage infrastructure to reduce third-party logistics dependency. Barcelona IVF and IVI RMA Global exemplify this defensive positioning through pan-European donor network coordination. For New Entrants and Emerging Players: Establish a beachhead in telemedicine-enabled cycle coordination, allowing patients to complete ovarian stimulation at home before brief surgical travel. Target LGBTQ+ inclusive eligibility frameworks in secondary Mediterranean markets underserved by Athens and Barcelona saturation. Deploy transparent outcome data platforms displacing traditional referral networks. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory arbitrage play because jurisdictional divergence in donor anonymity and surrogacy permissiveness creates durable demand corridors. Acquisition targets should display integrated legal advisory capabilities and EU-standard data architecture for GDPR compliance. Watch parentage recognition retroactivity rulings in Northern European home jurisdictions as inflection indicators for demand redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Pan-European Donor Network Expansion | IVI RMA Global leverages coordinated matching across Spanish and Greek jurisdictions to compress waitlist bottlenecks. |
| Telemedicine Cycle Coordination Platform | Remote ovarian stimulation monitoring expands addressable patient geography beyond traditional medical tourism corridors. |
| GDPR-Compliant Data Architecture Investment | Spanish clinics deploying EU-standard infrastructure capture Northern European demand facing cross-border health data restrictions. |
| Integrated Legal Advisory Service Bundling | Athens-based clinical networks channel Middle Eastern surrogacy demand through court-preapproved judicial pathways. |
| AI-Driven Embryo Selection Algorithm Licensing | Time-lapse imaging analysis platforms standardize transfer decisions across high-volume IVF programs in Bangkok and Barcelona. |
Research Approach
A standing panel of reproductive endocrinologists, fertility clinic operations directors, cross-border legal advisors, and medical tourism logistics coordinators provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against national assisted reproduction law filings, Medical Council enforcement records, hospital accreditation databases, and EU health data protection guidance. Bottom-up clinic capacity estimates triangulated against top-down demand flow analysis across Mediterranean and Southeast Asian corridors.
Scenario-bracketing framed projections across regulatory tightening and permissiveness pathways, with segmentation modeling across service type, customer origin jurisdiction, and destination clinical configuration. CAGRs derived from treatment cycle volume trajectories and per-cycle pricing evolution, incorporating donor availability constraints and parentage recognition policy shifts as industry-specific forecast inputs across the projection horizon.
Stress conditions across donor recruitment rate variability, judicial pre-approval timeline volatility, and home jurisdiction documentation retroactivity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and cross-border reimbursement continuity. Cross-checking against national health ministry policy announcements and GPO contract disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
Asia-Pacific Medical Tourism Market
Medical Tourism
Italy Medical Tourism Market
Medical Tourism
Thailand Medical Tourism Market
Medical Tourism
UK Medical Tourism Market
Medical Tourism
Dental Tourism Market
Medical Tourism
Switzerland Healthcare and Medical Tourism Market
Medical Tourism
North America Outbound Medical Tourism Services Market
Medical Tourism
France Medical Tourism Market
Medical Tourism
Japan Medical Tourism Market
Medical Tourism
India Medical Tourism Market
Medical Tourism
Malaysia Medical Tourism Market
Medical Tourism
China Medical Tourism Market
Medical Tourism
GCC Countries Medical Tourism Market
Medical Tourism
Medical Tourism Market
Medical Tourism
Outbound Medical Tourism Services Market
Medical Tourism
Europe Medical Tourism Market