
 UK Medical Tourism Market | 2026-2036
UK Medical Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
UK Medical Tourism Market Outlook
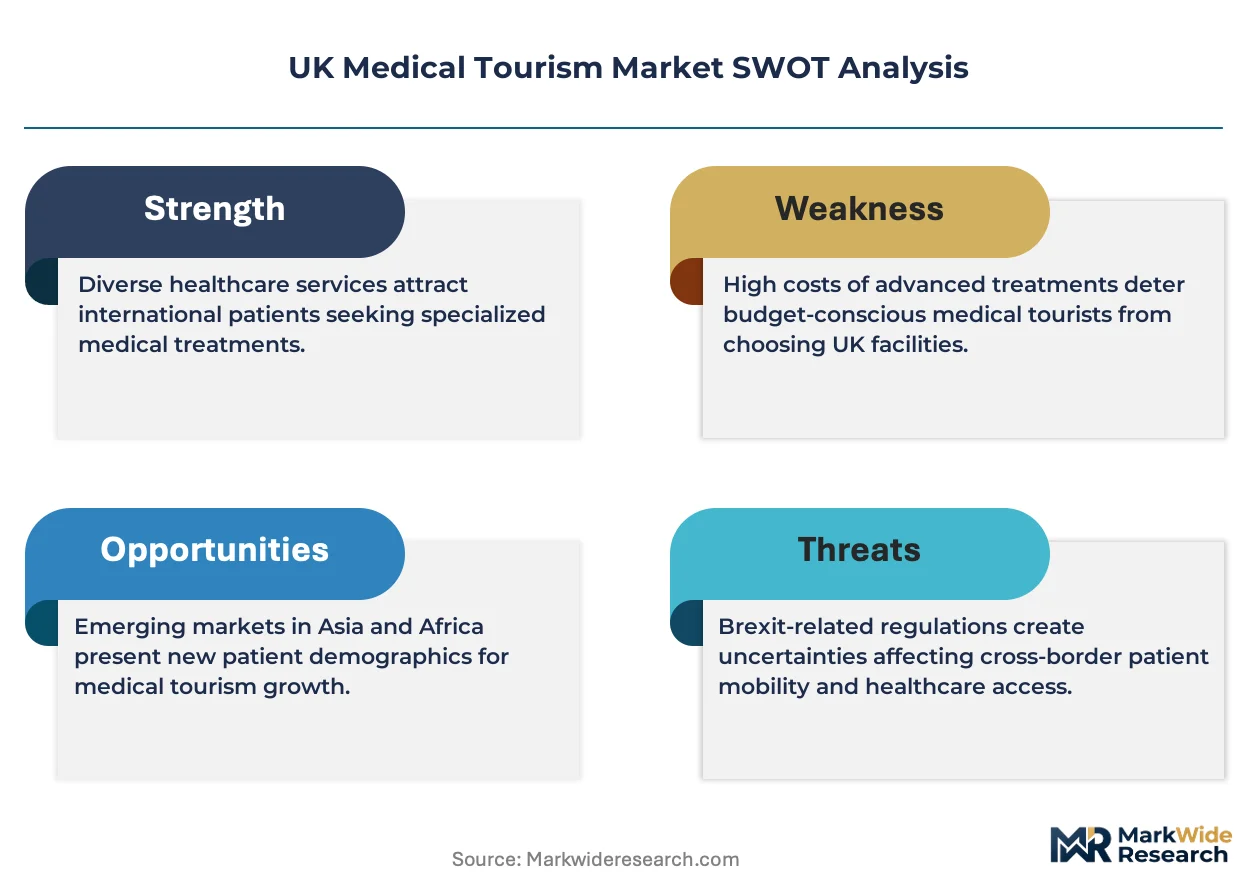
The NHS Long Term Workforce Plan is rebalancing patient flows toward private alternatives as public waiting lists stretch capacity. Spire Healthcare leverages its nationwide hospital network to capture redirected elective demand. The Harley Street Clinic anchors premium positioning through concentrated specialist expertise in cardiac and oncology services. Nuffield Health differentiates via integrated fitness-to-surgery pathways that reduce post-operative complications.
UK medical tourism encompasses cross-border and domestic patient travel for elective, diagnostic, and restorative health services delivered outside standard residence-based care pathways. Procedures typically require pre-authorization, clinical eligibility screening, and coordinated aftercare protocols spanning 7-30 day recovery windows. Cosmetic surgery and dental procedures command the largest service-type volume pools, though cardiac surgery generates disproportionate revenue per case. International patients dominate the highest-margin segment, while self-paying domestic buyers represent the fastest-expanding payer category as NHS rationing intensifies.
CQC registration requirements and GMC specialist accreditation shape facility-level market access, with non-compliant operators excluded from insurance networks. MHRA device standards and NHS England commissioning frameworks further constrain which providers can treat internationally mobile patients. Stakeholders must monitor evolving post-Brexit mutual recognition agreements with EU regulators that could restore or restrict cross-border care flows.
Market Dynamics
NHS waiting list pressures exceeding 7.5 million cases are redirecting domestic patients toward private elective pathways, compressing traditional referral timelines and fragmenting care coordination across England's mixed public-private infrastructure.
Growth Catalysts
- Elective Procedure Backlogs:NHS England's diagnostic and surgical waiting lists are pushing self-paying patients toward Harley Street clinics and Spire Healthcare facilities for hip replacements, cataract surgery, and hernia repairs.
- GMC Specialist Accreditation:The General Medical Council's credentialing framework creates quality signaling that attracts Middle Eastern and North African patients seeking cardiac and oncology expertise unavailable in home markets.
- Telemedicine Pre-Assessment:Remote clinical eligibility screening is collapsing traditional 8-12 week referral windows into 7-14 day treatment pathways for international arrivals.
Market Restraints
- CQC Registration Burden:Care Quality Commission compliance costs and inspection timelines exclude smaller independent clinics from insurance network participation, concentrating supply among capital-rich hospital groups.
- Post-Brexit Visa Friction:Removal of EU reciprocal healthcare arrangements under the UK-EU Trade and Cooperation Agreement has eliminated streamlined reimbursement for European patients, diverting flows to Switzerland and Germany.
- Clinical Workforce Scarcity:NHS consultant retention pressures and GMC registration backlogs for overseas-trained specialists constrain capacity expansion at private facilities despite patient demand.
Strategic Opportunities
- Manchester Specialist Cluster Development:NHS England's "Manchester Devolution" health investment zone is creating infrastructure for private providers to co-locate diagnostic and surgical capacity adjacent to reduced-cost recovery facilities.
- Fitness-to-Surgery Integration:Prehabilitation partnerships with private health clubs and physiotherapy networks are opening bundled payment models that reduce post-operative complications and length-of-stay.
- Medical Visa Streamlining:Home Office proposals for dedicated medical visitor visa categories could restore competitive positioning against Dubai and Bangkok for elective surgical tourism from Gulf Cooperation Council states.
Industry Challenges
- Aftercare Coordination Complexity:International patient discharge protocols require 7-30 day local recovery monitoring before air travel clearance, straining hotel and nursing accommodation supply in London's W1 and Manchester city center corridors.
- Malpractice Jurisdiction Ambiguity:Cross-border clinical negligence claims involving overseas patients create insurance coverage gaps and legal cost uncertainty that complicates pricing and risk allocation for high-complexity procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Medical Tourism Market |
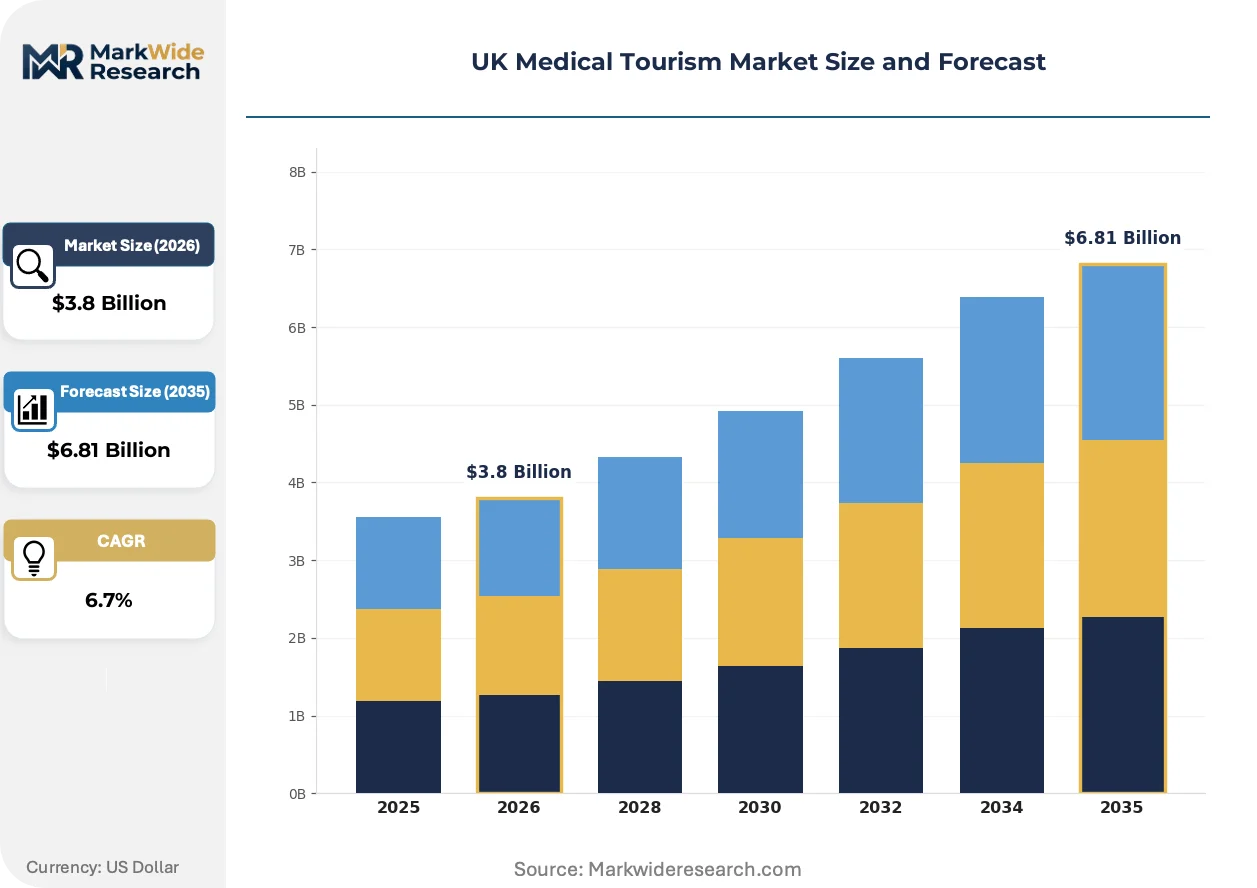
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cosmetic Surgery, Dental Procedures, Cardiac Surgery, Orthopedic Surgery Patient Type: Domestic Patients, International Patients, Insurance Funded, Self-Paying Procedure Type: Minimally Invasive, Elective Surgery, Health Screening, Rehabilitation Facility Type: Private Hospitals, Clinics, Specialized Centers, Wellness Resorts |
| Companies Covered | Your Medical Travel, Medigo, The Harley Street Clinic, MediGence, Healthbase, Spire Healthcare, PlacidWay, Manchester Fertility Clinics, Nuffield Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Medical Tourism Market Strategic Shifts
Digital health infrastructure and regulatory recalibration are compressing traditional care pathways while elevating quality transparency as a competitive differentiator in patient destination selection.
Remote patient monitoring platforms with wearable-enabled post-operative tracking are overtaking conventional in-person follow-up models for international cardiac and orthopedic cases. Harley Street providers are deploying these systems to monitor Middle Eastern patients upon return to Riyadh, Doha, and Kuwait City, reducing readmission liability while extending service revenue into home-market recovery periods. This capability is compressing the minimum stay requirement for complex procedures from 14 days toward 7 days.
CQC's forthcoming "Digital-first" inspection framework will mandate real-time outcome reporting for internationally registered patients, aligning with NHS England's commissioning data standards. Private hospital groups are investing in interoperable electronic health record systems to satisfy this convergence, with smaller independent clinics facing exclusion from tier-one insurance panels. The cardiac surgery segment is responding fastest, driven by malpractice premium differentiation tied to transparent outcome registries.
Self-paying domestic buyers are fragmenting traditional GP referral channels by booking direct-to-specialist consultations through provider-owned digital platforms. Spire Healthcare and Nuffield Health are capturing this behavior shift with same-week video triage and fixed-price procedure packages that bypass NHS waiting list protocols. This pattern concentrates in London's commuter belt and Greater Manchester, where household savings rates and employer private medical insurance penetration support discretionary surgical expenditure.
UK Medical Tourism Market Segmentation
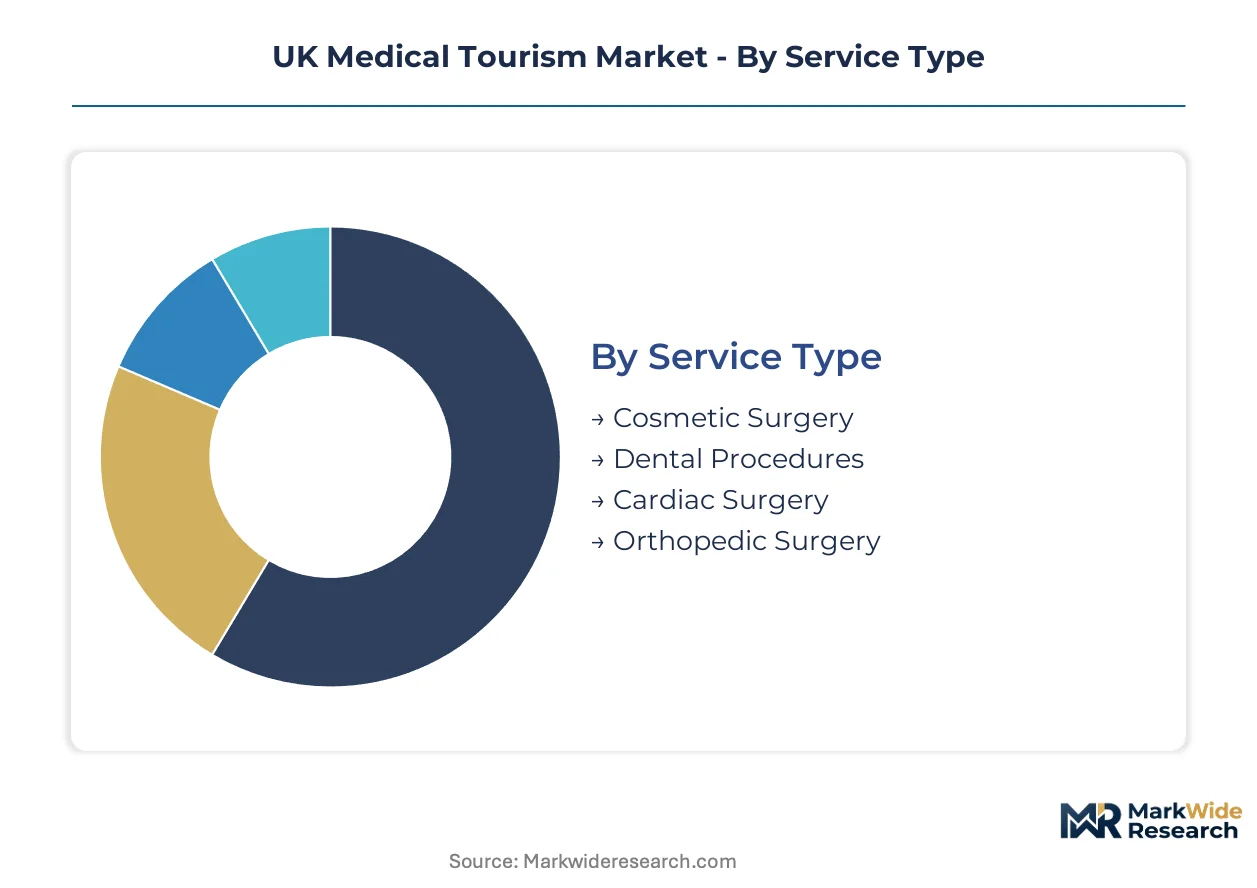
Patient flow patterns across the UK medical tourism market fragment sharply by service intensity, payer source, and facility infrastructure. Segmentation reveals where capital deployment concentrates and which patient categories command premium pricing power.
Service Type:
Supply concentration in cardiac and orthopedic surgery clusters around GMC-accredited specialist units with intensive care backup, while cosmetic and dental procedures disperse across lower-barrier clinic networks.
- Cosmetic Surgery:Breast augmentation, rhinoplasty, and body contouring procedures dominate volume through Harley Street and Manchester clinic networks. Demand concentrates among Middle Eastern private payers seeking discreet recovery environments unavailable in home markets.
- Dental Procedures:Full-mouth reconstruction and implantology drive cross-border flows from Ireland and Scandinavia where domestic costs exceed UK private rates by 40-60%. Dublin and Oslo commuter corridors feed same-day and short-stay treatment pathways.
- Cardiac Surgery:Coronary artery bypass grafting and valve replacement procedures generate highest revenue per case through concentrated specialist expertise.
- Orthopedic Surgery:Hip and knee replacements capture redirected NHS waiting list demand across Spire and Nuffield hospital networks.
Cardiac surgery absorbs the bulk of installed capacity; cosmetic procedures are expanding most quickly.
Patient Type:
Cost tier stratification separates internationally mobile high-net-worth individuals from domestically stranded NHS queue-jumpers, with insurance networks occupying a narrowing middle band.
- International Patients:Gulf Cooperation Council nationals and Nigerian private payers dominate high-complexity cardiac and oncology referrals. GMC specialist accreditation and English-language clinical communication drive destination selection over price sensitivity.
- Self-Paying:Households with £15,000-£40,000 liquid savings bypass NHS waiting lists for hip replacements, cataract surgery, and hernia repairs. Employer private medical insurance penetration in London's commuter belt and Greater Manchester accelerates this category.
- Domestic Patients:UK residents accessing private care through NHS referral redirection or direct self-referral.
- Insurance Funded:Bupa, Axa Health, and Vitality policyholders accessing pre-authorized elective procedures within network constraints.
International patients absorb the bulk of premium pricing power; self-paying domestic buyers are climbing the fastest.
Procedure Type:
Application intensity varies from single-visit diagnostic throughput to month-long rehabilitation residencies, dictating facility capital requirements and staffing ratios.
- Elective Surgery:Planned hip replacements, spinal fusion, and bariatric procedures command block-booked operating theatre time. NHS waiting list pressures exceeding 7.5 million cases redirect patient flow toward private hospitals with 2-4 week admission guarantees.
- Minimally Invasive:Laparoscopic hernia repair and arthroscopic knee surgery enable 23-hour discharge protocols. Harley Street day-case units and Manchester specialist clusters compete on recovery hotel partnerships and nursing accommodation packages.
- Health Screening:Executive medical assessments and cancer surveillance packages attract corporate wellness budgets.
- Rehabilitation:Post-operative physiotherapy and cardiac recovery programs extend length-of-stay revenue.
Elective surgery absorbs the bulk of operating theatre utilization; minimally invasive procedures are gaining share fastest.
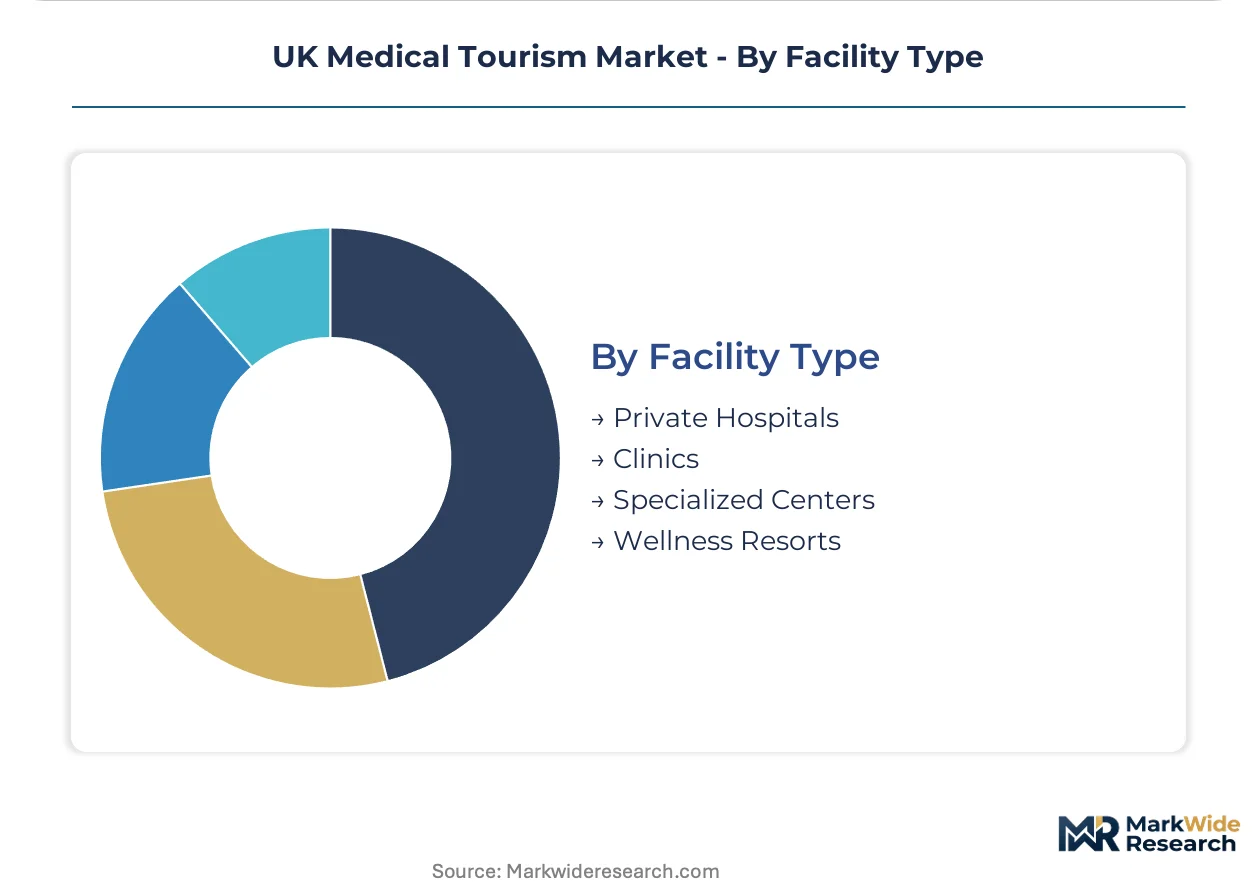
Facility Type:
Margin structure separates capital-intensive hospital groups with CQC-registered intensive care from asset-light clinic operators dependent on referral networks.
- Private Hospitals:Spire Healthcare and Circle Health sites with 50+ beds, on-site imaging, and Level 2 critical care capability capture complex surgical referrals. CQC registration and NHS England commissioning framework compliance restrict market entry to capital-rich groups.
- Specialized Centers:Cardiac and oncology-focused units such as The Harley Street Clinic concentrate GMC-accredited consultants and device-intensive procedure volume. MHRA device standards and specialist nursing ratios elevate fixed cost bases.
- Clinics:Day-case cosmetic and dental operators with lower regulatory barriers and minimal overnight capacity.
- Wellness Resorts:Recovery-focused accommodation bridging medical discharge and air travel clearance.
Private hospitals absorb the bulk of capital deployment; specialized centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's Harley Street corridor anchors UK medical tourism activity through concentrated specialist expertise and premium recovery infrastructure. Manchester's emerging specialist clusters are capturing redirected NHS demand and international patient flows. Regional variation reflects uneven distribution of GMC-accredited consultants and CQC-registered intensive care capacity.
London and the Southeast
Gulf Cooperation Council nationals and Nigerian private payers drive cardiac and oncology referrals to Harley Street clinics. CQC registration requirements and NHS England commissioning frameworks restrict market entry to capital-rich hospital groups. The Harley Street Clinic and surrounding W1 corridor concentrate GMC-accredited cardiac surgeons and device-intensive procedure volume.
Greater Manchester
NHS England's "Manchester Devolution" health investment zone is creating infrastructure for private providers to co-locate diagnostic and surgical capacity. Self-paying domestic buyers with employer private medical insurance bypass NHS waiting lists for hip replacements and cataract surgery. Manchester Fertility Clinics anchor reproductive tourism from Ireland and Northern England.
Scotland
Edinburgh and Glasgow private hospitals capture dental tourism flows from Scandinavia where domestic costs exceed UK private rates. The country's national health regulator enforces CQC-equivalent standards for internationally registered patients. Specialist orthopedic units in Aberdeen service North Sea oil sector employees with employer-funded surgical pathways.
Wales
Cardiff-based private clinics attract cross-border demand from Bristol and Southwest England commuter corridors. Welsh Government health policy diverges from NHS England commissioning frameworks, creating regulatory friction for multi-site hospital groups. Recovery hotel partnerships in Cardiff city center extend length-of-stay revenue for minimally invasive procedures.
Northern Ireland
Belfast private hospitals service Republic of Ireland patients seeking reduced-cost dental implants and cosmetic procedures. Post-Brexit regulatory alignment with UK CQC standards maintains access to NHS England referral networks. The city's airport connectivity constraints limit complex cardiac surgery tourism compared to London and Manchester hubs.
UK Medical Tourism Market Competitive Environment
Premium-margin players sit above commodity-margin players across GMC specialist accreditation and CQC registration tiers. Hospital groups with intensive care backup capture complex surgical referrals while day-case clinics compete on recovery hotel partnerships. Three archetypes dominate: integrated fitness-to-surgery providers, concentrated specialist centers, and digital-first medical travel platforms. M&A activity consolidates independent clinics into hospital networks; strategic partnerships with physiotherapy networks expand prehabilitation service bundles.
Within the integrated hospital group tier, Spire Healthcare and Nuffield Health occupy positions as nationwide networks with CQC-registered Level 2 critical care. The Harley Street Clinic exemplifies the concentrated specialist center archetype through cardiac and oncology expertise. Among digital medical travel platforms, Medigo and PlacidWay represent intermediaries collapsing traditional referral windows through remote pre-assessment capabilities.
| Leading Market Players |
|---|
| Your Medical Travel |
| Medigo |
| The Harley Street Clinic |
| MediGence |
| Healthbase |
| Spire Healthcare |
| PlacidWay |
| Manchester Fertility Clinics |
| Nuffield Health |
| Others |
Value Chain & Pricing Dynamics
GMC consultant fees cascade through three-tier pricing structures across premium, standard, and economy levels, with Harley Street cardiac units commanding five-fold premiums over Manchester day-case clinics for identical procedure codes. CQC registration costs and MHRA device compliance anchor fixed cost bases that compress margins at independent operators while hospital groups absorb overhead across volume networks.
Pricing Analysis
Outcome-linked pricing for cardiac surgery bundles 30-day readmission liability into upfront procedure fees, differentiating Harley Street providers from commodity day-case operators. GMC specialist accreditation and CQC inspection ratings drive price stratification alongside aftercare hotel partnerships. Pricing pressure stems from NHS waiting list redirection saturating mid-tier capacity. Self-paying domestic buyers exhibit highest price sensitivity; Gulf Cooperation Council nationals show lowest.
Supply Chain Analysis
Dual-sourcing requirements for cardiac device implants mandate MHRA-approved suppliers from Germany, Switzerland, and the USA alongside domestic inventory buffers. Prosthetic joints, diagnostic imaging equipment, and specialist nursing labor feed from concentrated European manufacturing hubs. Single-source vulnerability in pacemaker component supply creates exposure to Swissmedic regulatory delays. Distribution runs through CQC-registered hospital networks with direct-to-clinic logistics bypassing wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consultant recruitment bottlenecks and GMC registration backlogs constrain private hospital expansion, propping pricing power for incumbent operators with accredited specialist benches.
For Market Incumbents: Cement market position through exclusive GMC consultant employment contracts that lock cardiac and oncology expertise away from emerging Manchester clusters. Acquire independent day-case clinics in Greater London to capture redirected NHS demand and block new entrant scale. Vertical integration into recovery hotel partnerships extends length-of-stay revenue while raising rival cost structures. For New Entrants and Emerging Players: Launch via telemedicine pre-assessment platforms that collapse traditional referral windows and capture self-paying domestic buyers before they reach established hospital websites. Target Northern Ireland dental tourism corridors where Belfast airport constraints limit incumbent defensive response. Pursue CQC registration for minimally invasive day-case units with 23-hour discharge protocols to bypass capital-intensive critical care requirements. For Investors and Strategic Acquirers: Home Office medical visa policy announcements are the leading indicator that Gulf Cooperation Council patient flows will accelerate or divert to Dubai competitors. Long-term viability hinges on CQC-registered hospital groups with installed imaging and Level 2 critical care rather than asset-light clinic operators. Watch Manchester Devolution infrastructure spend as the signal for private provider co-location opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| GMC Specialist Recruitment | Exclusive consultant contracts lock cardiac expertise away from emerging Manchester clusters. |
| Telemedicine Pre-Assessment Platform | Remote eligibility screening collapses 8-12 week referral windows to 7-14 days. |
| Recovery Hotel Partnership | Post-discharge accommodation extends revenue capture while satisfying air travel clearance protocols. |
| CQC Registration Acquisition | Buying compliant clinics bypasses 18-month inspection timelines for new market entry. |
| Fitness-to-Surgery Integration | Prehabilitation partnerships with Nuffield Health reduce post-operative complications and length-of-stay. |
Study Parameters
Document review covered CQC inspection reports, NHS England commissioning data, and Home Office visa statistics, complemented by interviews with private hospital operations directors, GMC-registered cardiac consultants, medical travel platform executives, and international patient coordinators. Secondary validation drew from hospital procurement databases, GPO contracts, and MHRA device registration filings. Bottom-up facility capacity modeling and top-down patient flow estimates were triangulated against payer mix disclosures.
Market sizing outputs reflect segmentation across service type, patient origin, and facility infrastructure tiers over the projection horizon. Modeled dimensions include procedure complexity, payer category, and regional cluster concentration. CAGRs were derived from patient volume trajectory analysis calibrated against NHS waiting list pressure indicators and Gulf Cooperation Council outbound medical travel surveys.
Post-Brexit reciprocal healthcare negotiations, GMC registration processing delays, and medical visa policy reversals are the dominant revision risks to patient flow assumptions. Deviation in Home Office medical visitor visa implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
India Medical Tourism Market
Medical Tourism
Turkey Medical Tourism Market
Medical Tourism
Italy Medical Tourism Market
Medical Tourism
China Medical Tourism Market
Medical Tourism
France Medical Tourism Market
Medical Tourism
Asia-Pacific Medical Tourism Market
Medical Tourism
Medical Tourism Market
Medical Tourism
Europe Medical Tourism Market
Medical Tourism
Malaysia Medical Tourism Market
Medical Tourism
Thailand Medical Tourism Market
Medical Tourism
Fertility Tourism Market
Medical Tourism
Dental Tourism Market
Medical Tourism
Europe Dental Tourism Market
Medical Tourism
Spain Medical Tourism Market
Medical Tourism
Japan Medical Tourism Market
Medical Tourism
North America Outbound Medical Tourism Services Market