
 GCC Countries Medical Tourism Market | 2026-2036
GCC Countries Medical Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Countries Medical Tourism Market Foresight
JCI accreditation cycle time is collapsing from eighteen months to under twelve for greenfield hospital projects in the Gulf. American Hospital Dubai leverages its long-standing Joint Commission certification to sustain premium positioning for cardiac and orthopedic inbound cases. Zulekha Healthcare anchors volume across Dubai and Sharjah through multispecialty capacity that competes on price for South Asian referral flows.
GCC medical tourism denotes the organized cross-border movement of patients into Gulf Cooperation Council states for elective surgical, diagnostic, or rehabilitative care, typically requiring pre-arranged visas, bundled procedure-and-accommodation packages, and English-Arabic medical interpretation. Cosmetic surgery and dental treatments command the highest margin pools due to discretionary pricing power and short recovery windows, while cardiac surgery segments occupy capital-intensive infrastructure that differentiates only at tertiary throughput scale. Specialty hospitals dominate procedural complexity, yet wellness centers capture extending stays for post-operative rehabilitation and aesthetic maintenance.
Dubai Health Authority facility licensing and Saudi Commission for Health Specialties practitioner credentialing jointly determine which institutions qualify for government-sanctioned medical visitor visas. UAE mandatory health insurance frameworks for expatriates create a parallel domestic base that subsidizes fixed costs for internationally marketed service lines. Stakeholders must monitor how Saudi Vision 2030 hospital privatization timelines redistribute patient flow between Riyadh clusters and established Dubai corridors.
Market Dynamics
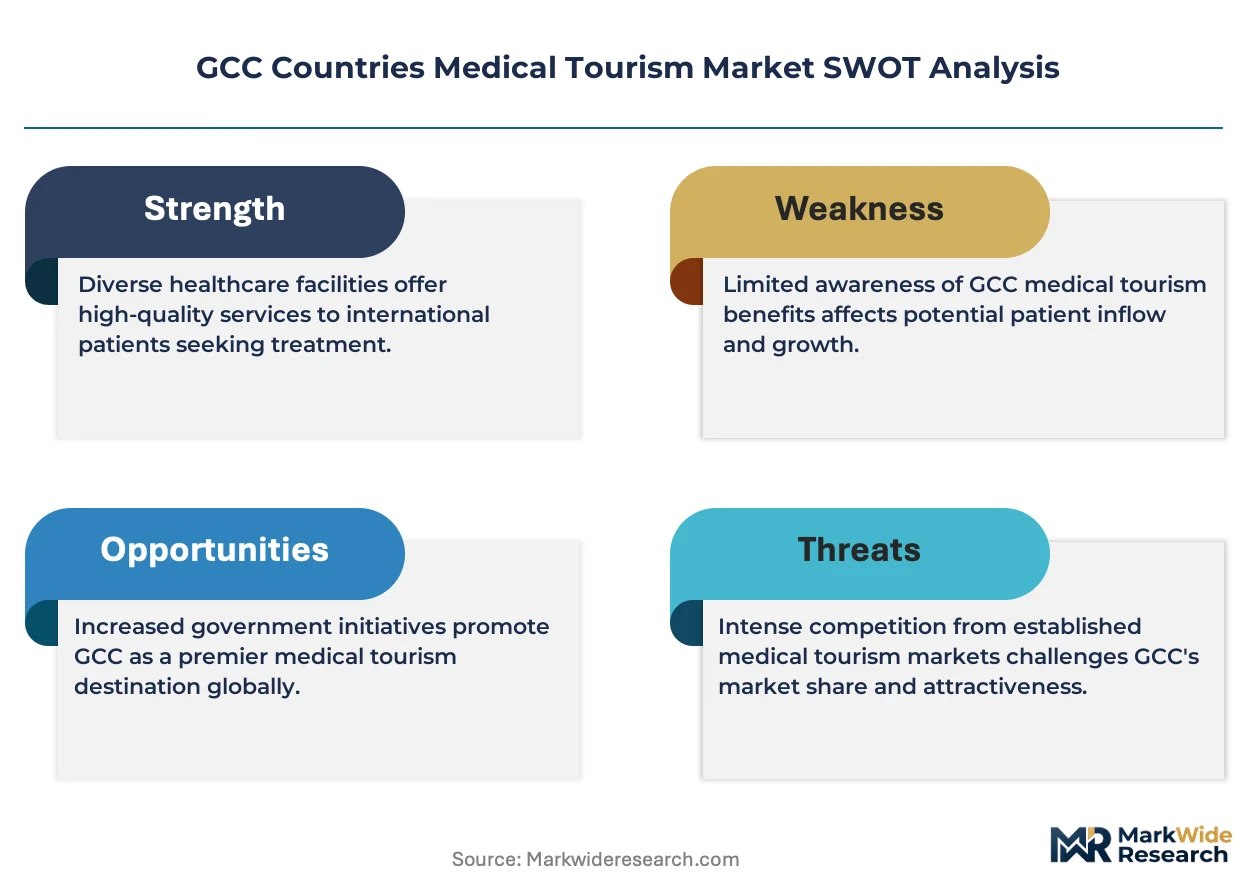
GCC medical tourism is restructuring around compressed JCI accreditation timelines and visa-linked facility licensing, which concentrates patient flow into Dubai and Abu Dhabi corridors while squeezing marginal operators from government-sanctioned referral networks.
Growth Catalysts
- SFDA fast-track licensing:Saudi Arabia's streamlined facility approvals under Vision 2030 hospital privatization are accelerating bed capacity expansion for inbound cardiac and orthopedic cases.
- Cosmetic surgery tourism:European demand for discretionary aesthetic procedures is concentrating in Dubai's JCI-accredited day-surgery centers with bundled recovery packages.
- Telemedicine pre-consultation:Remote diagnostic screening is collapsing patient decision cycles and expanding catchment zones into North African and South Asian source markets.
Market Restraints
- Practitioner credentialing bottlenecks:Saudi Commission for Health Specialties licensing delays create six-to-nine month staffing gaps for new specialty hospitals.
- Fixed-cost intensity:Tertiary cardiac catheterization labs and proton therapy suites require capital deployment that only amortizes at throughput volumes exceeding regional demand density.
- Domestic insurance subsidization:UAE mandatory expatriate health coverage frameworks divert marketing resources toward resident populations rather than pure medical visitor acquisition.
Strategic Opportunities
- Sharjah wellness corridor:Post-operative rehabilitation and aesthetic maintenance stays remain underdeveloped relative to Dubai's surgical throughput, creating margin capture potential.
- MOHAP visa category expansion:Abu Dhabi's emerging medical visitor visa tiers for extended-stay rehabilitation could unlock month-long recovery tourism revenue streams.
- AI-assisted surgical planning:Convergence of pre-operative imaging analytics with robotic-assisted procedures is enabling premium positioning for complex orthopedic interventions.
Industry Challenges
- Arabic-English medical interpretation capacity:Certified clinical translators remain scarce across GCC facilities, creating liability exposure and patient experience friction.
- JCI re-survey compression:Three-year accreditation cycles are tightening to eighteen-month interim reviews, straining quality documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Countries Medical Tourism Market |
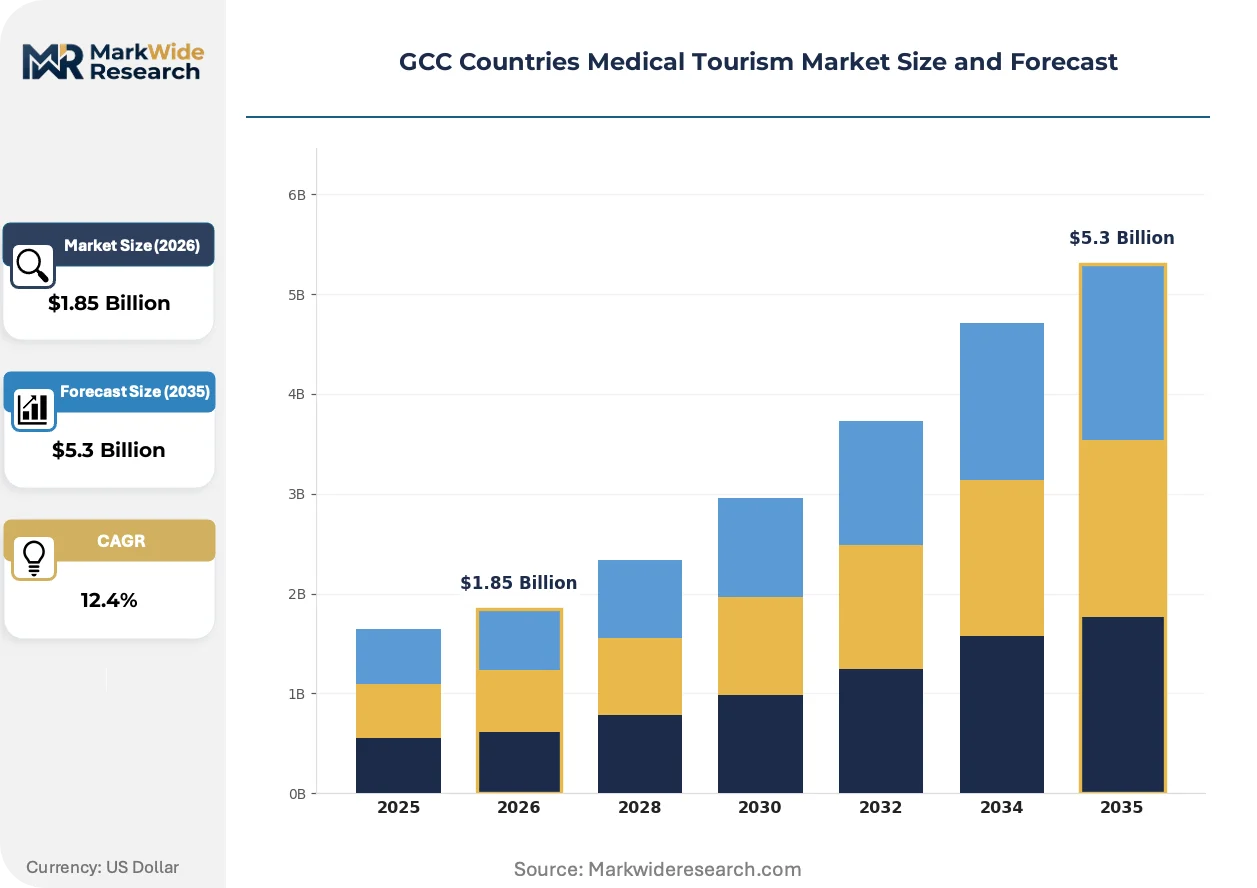
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.3 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Medical Procedure Type: Cardiac Surgery, Orthopedic Surgery, Cosmetic Surgery, Dental Treatments, Fertility Treatments Patient Origin: Middle Eastern Nationals, South Asian Visitors, European Clients, North African Patients, East Asian Travelers Healthcare Facility Type: Specialty Hospitals, Multispecialty Clinics, Wellness Centers, Private Hospitals, Rehabilitation Centers Service Offering: Pre-Travel Consultation, Post-Operative Care, Accommodation Arrangements, Transport Services, Interpreter Support |
| Companies Covered | Thumbay Medical Tourism, Shifa International Hospitals, American Hospital Dubai, Lyfboat Technologies Pvt. Ltd, VAID Health Care Services, Fortis Healthcare, Zulekha Healthcare, PlacidWay Medical Tourism, Apollo Hospitals Enterprise Limited, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Countries Medical Tourism Market Shifts & Advancements
Technology adoption and regulatory recalibration are compressing patient decision cycles while fragmenting traditional referral channels. Facilities now compete on pre-arrival digital touchpoints and post-discharge remote monitoring rather than bed capacity alone.
Robotic-assisted surgical platforms are fragmenting procedural complexity thresholds across GCC specialty hospitals. Mid-tier facilities in Sharjah and Al Ain are acquiring da Vinci systems for routine prostate and gynecologic procedures previously concentrated in Dubai's tertiary centers. This capability diffusion is compressing price premiums for standard robotic interventions while forcing established players toward super-specialized cardiac and neurologic applications.
MOHAP's 2024 facility licensing amendments now mandate real-time outcome reporting to maintain medical visitor visa eligibility. Dubai Health Authority is synchronizing its own disclosure requirements with Abu Dhabi's framework, creating unified compliance obligations across UAE emirates. Cosmetic surgery and dental centers face the steepest documentation burdens due to discretionary procedure volumes and higher complaint incidence.
Patients are booking through direct-to-facility digital portals rather than medical travel intermediaries. European cosmetic surgery demand is bypassing traditional agencies and negotiating package pricing through hospital-owned platforms. This channel disintermediation is most pronounced in Dubai, where American Hospital Dubai and Zulekha Healthcare have invested in Arabic-German-French booking interfaces.
GCC Countries Medical Tourism Market Segmentation
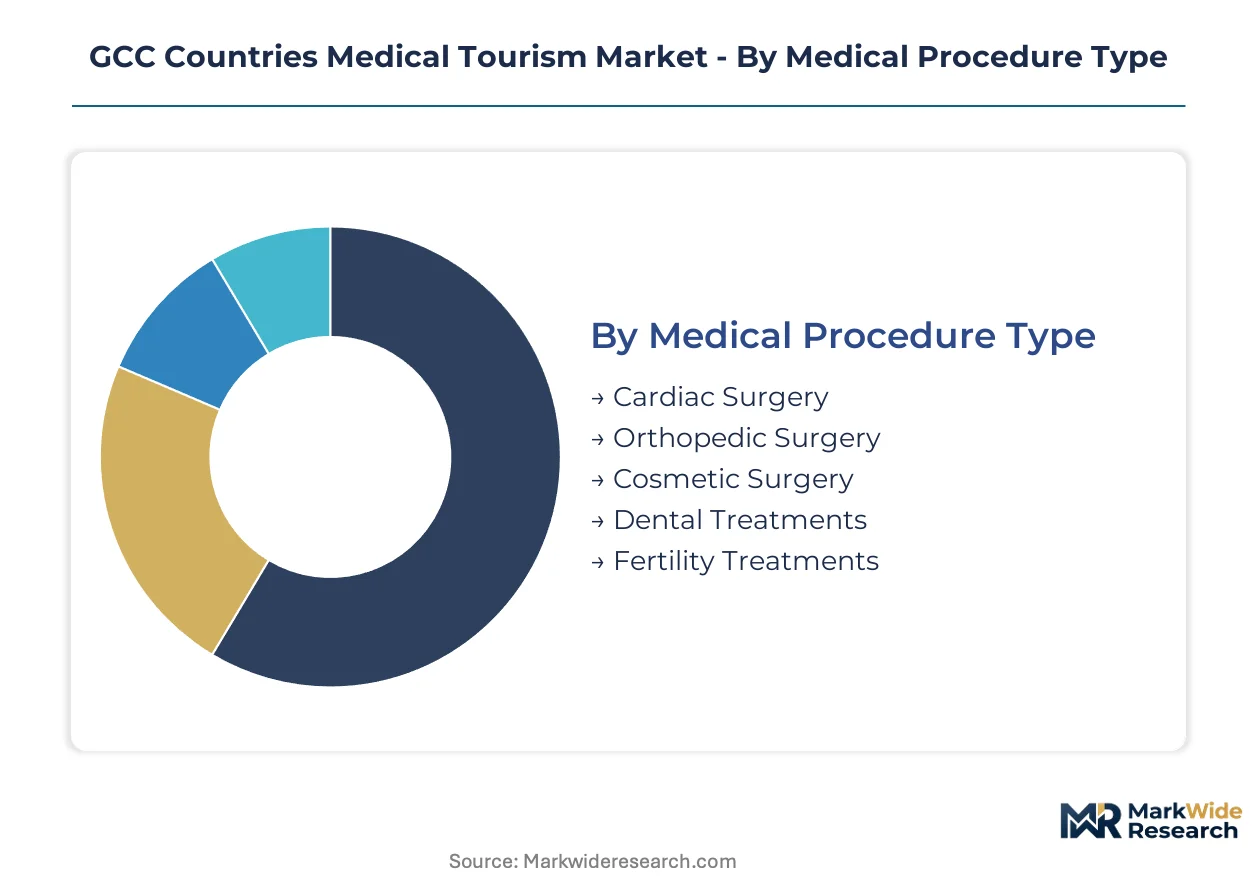
Regulatory frameworks across Gulf jurisdictions segment patient flows by visa-linked facility licensing, creating distinct competitive zones for procedure types and origin markets. Dubai Health Authority and MOHAP credentialing tiers determine which institutions capture European high-margin cases versus South Asian volume segments.
Medical Procedure Type:
SFDA fast-track approvals and JCI accreditation timelines differentiate capital-intensive tertiary procedures from discretionary day-surgery offerings across Saudi and UAE markets.
- Cosmetic Surgery:Discretionary aesthetic procedures command premium pricing power through bundled recovery packages and short hospitalization windows. European clients concentrate in Dubai's JCI-accredited day-surgery centers where MOHAP outcome reporting requirements are lightest for elective procedures.
- Cardiac Surgery:Capital-intensive infrastructure requiring tertiary throughput scale amortizes fixed costs only at high patient volumes. Demand clusters in Abu Dhabi specialty hospitals where SFDA-aligned licensing permits extended-stay medical visitor visas for complex interventions.
- Orthopedic Surgery:Robotic-assisted platforms are fragmenting procedural thresholds across mid-tier Sharjah facilities.
- Dental Treatments:Highest margin pools per chair-hour with minimal regulatory documentation burden.
- Fertility Treatments:Specialized reproductive medicine requiring distinct practitioner credentialing from Saudi Commission for Health Specialties.
Established volume favors cardiac surgery infrastructure; emerging adoption favors cosmetic surgery day-procedure centers.
Patient Origin:
Visa category structures and bilateral health agreements shape geographic demand concentration across GCC corridors.
- European Clients:German and French cosmetic surgery demand bypasses traditional intermediaries through direct hospital booking portals. Dubai Health Authority's German-language licensing requirements create entry barriers that protect incumbent JCI-accredited facilities.
- South Asian Visitors:Price-sensitive referral flows from India and Pakistan concentrate in Sharjah and Al Ain multispecialty clinics. Zulekha Healthcare anchors this segment through volume-based pricing that competes below Dubai premium tiers.
- Middle Eastern Nationals:Intra-GCC patient movement driven by specialty procedure availability gaps.
- North African Patients:Telemedicine pre-consultation is collapsing decision cycles for Egyptian and Moroccan source markets.
- East Asian Travelers:Emerging segment requiring Mandarin and Korean interpretation capacity investments.
Revenue concentration sits with European clients; steepest expansion trajectory belongs to North African patients through remote screening adoption.
Healthcare Facility Type:
Capital deployment intensity and fixed-cost structures determine competitive positioning across facility categories.
- Specialty Hospitals:Concentrate procedural complexity at tertiary scale with cardiac catheterization labs and proton therapy suites. American Hospital Dubai sustains premium positioning through long-standing Joint Commission certification that qualifies for government-sanctioned medical visitor visas.
- Wellness Centers:Post-operative rehabilitation and aesthetic maintenance stays remain underdeveloped relative to surgical throughput. Sharjah corridor offers margin capture potential for extended recovery tourism revenue streams.
- Multispecialty Clinics:Volume-based competition for South Asian referral flows across Dubai and Sharjah.
- Private Hospitals:Hybrid domestic-expatriate base subsidizes internationally marketed service lines.
- Rehabilitation Centers:Month-long recovery stays eligible under Abu Dhabi's emerging extended-stay visa tiers.
Margin protection favors specialty hospitals; capacity expansion favors wellness centers in underserved rehabilitation corridors.
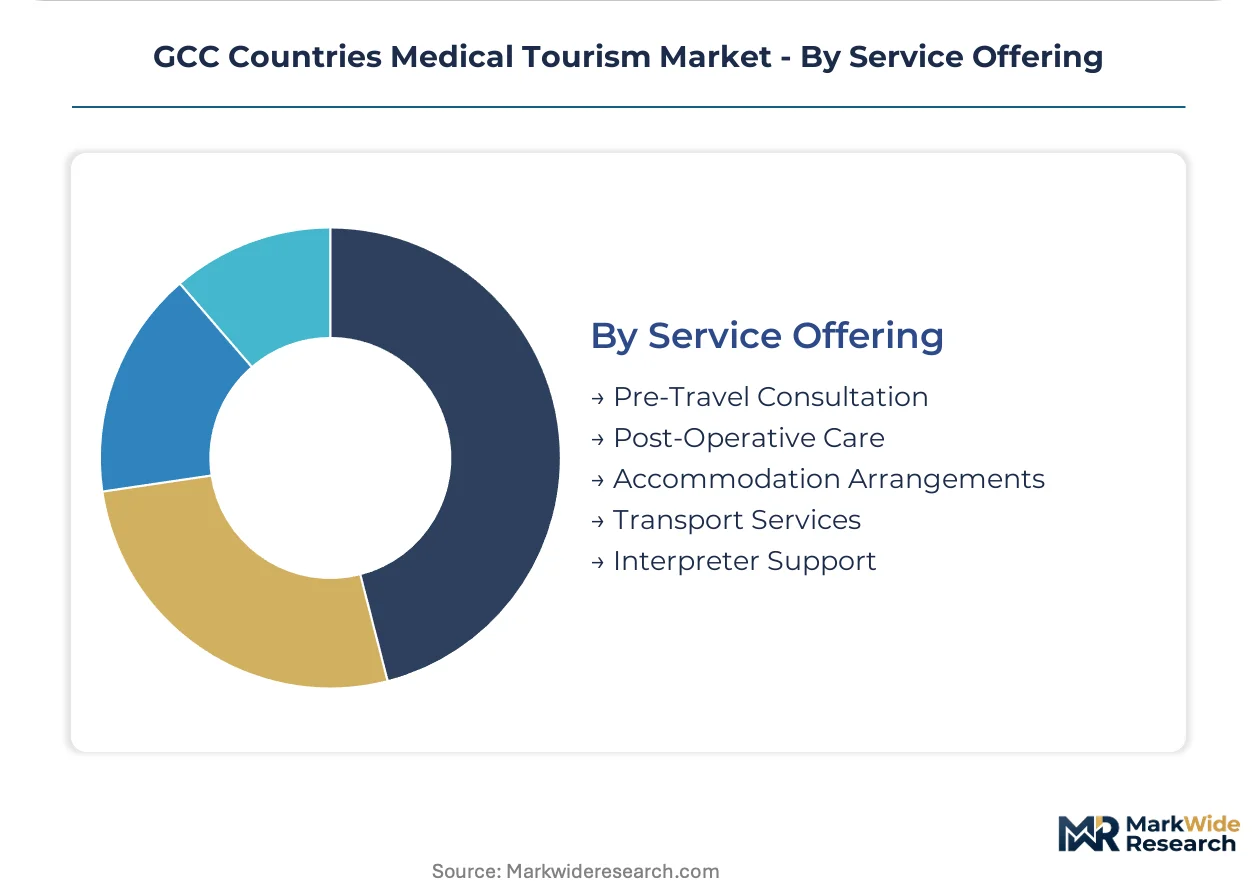
Service Offering:
Digital touchpoint investment and remote monitoring capabilities now differentiate competitive positioning beyond bed capacity alone.
- Pre-Travel Consultation:Telemedicine diagnostic screening collapses patient decision cycles from months to weeks. North African and South Asian catchment zones expand through remote physician assessment without intermediary travel agencies.
- Interpreter Support:Certified Arabic-English clinical translators remain scarce across GCC facilities, creating liability exposure. European cosmetic surgery demand requires German-French booking interfaces that only American Hospital Dubai and Zulekha Healthcare have deployed.
- Post-Operative Care:Remote monitoring extends revenue capture beyond discharge through subscription-based follow-up.
- Accommodation Arrangements:Bundled procedure-and-recovery packages concentrate in Dubai's hospitality-integrated facilities.
- Transport Services:Airport-clinic logistics standardized across government-sanctioned visa networks.
Operational necessity favors interpreter support infrastructure; technology leverage favors pre-travel consultation platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA fast-track licensing and MOHAP visa-linked facility approvals are redistributing patient flows across Gulf jurisdictions, with Dubai Health Authority and Saudi Commission for Health Specialties credentialing tiers determining competitive access.
United Arab Emirates
European cosmetic surgery demand concentrates in Dubai's JCI-accredited day-surgery centers with bundled recovery packages. MOHAP outcome reporting mandates now apply uniformly across emirates, tightening documentation for discretionary procedures. Abu Dhabi specialty hospitals capture extended-stay cardiac cases through emerging visa tiers for complex interventions.
Saudi Arabia
Vision 2030 hospital privatization timelines are accelerating bed capacity expansion for inbound orthopedic and cardiac volumes. SFDA streamlined facility approvals compress project timelines from twenty-four to fourteen months for greenfield developments. Riyadh clusters compete with established Dubai corridors for government-sanctioned medical visitor referrals.
Qatar
Specialty infrastructure investments target cardiac and fertility segments requiring distinct practitioner credentialing pathways. The national health regulator maintains stringent JCI alignment requirements that limit new entrant participation in visa-eligible networks. Doha medical city concentrates tertiary throughput for intra-GCC patient movement.
Kuwait
Domestic capacity constraints drive outbound referral leakage to Dubai and Riyadh corridors for complex interventions. The national medical tourism framework remains underdeveloped relative to UAE and Saudi licensing maturity. Private hospital groups pursue partnerships with established JCI-accredited UAE facilities.
Bahrain
Proximity to Eastern Province demand pools positions the kingdom as a secondary destination for Saudi patient overflow. Regulatory harmonization with SFDA standards remains incomplete, limiting visa-linked facility eligibility. Manama specialty clinics compete on price for South Asian referral flows below Dubai premium tiers.
GCC Countries Medical Tourism Market Competitive Landscape
Listed hospital groups compete with private specialists across JCI accreditation timelines and visa-linked licensing eligibility. Market structure concentrates around three tiers: long-standing Joint Commission-certified institutions sustaining premium positioning, multispecialty volume players competing on price, and emerging digital-first intermediaries disintermediating traditional travel agencies. Dominant competitive moves include telemedicine platform deployment for pre-arrival patient capture and robotic surgical platform acquisition for procedural complexity differentiation.
Within the established certification tier, American Hospital Dubai and Zulekha Healthcare occupy positions defined by credentialing longevity and geographic coverage breadth. Thumbay Medical Tourism anchors the digital intermediary archetype, while Apollo Hospitals Enterprise Limited represents the cross-border hospital group model extending Indian-origin capacity into Gulf patient flows. Shifa International Hospitals exemplify the specialty-focused private operator pursuing SFDA-aligned licensing for Saudi market access.
| Leading Market Players |
|---|
| Thumbay Medical Tourism |
| Shifa International Hospitals |
| American Hospital Dubai |
| Lyfboat Technologies Pvt. Ltd |
| VAID Health Care Services |
| Fortis Healthcare |
| Zulekha Healthcare |
| PlacidWay Medical Tourism |
| Apollo Hospitals Enterprise Limited |
| Others |
Supply & Pricing Matrix
Bundled procedure-and-accommodation packages lock in patient commitment and revenue visibility for GCC facilities, connecting MOHAP visa-linked pricing tiers to Dubai Health Authority facility licensing requirements that determine which institutions qualify for government-sanctioned medical visitor flows.
Pricing Analysis
JCI accreditation tier creates the primary spread between premium cardiac surgery corridors and volume-driven cosmetic day-procedures. Three-tier pricing structure across premium, standard, and economy levels segments European high-margin aesthetic cases from South Asian referral flows concentrated in Sharjah. Cost compression in mid-tier robotic-assisted orthopedic interventions is intensifying because da Vinci capability diffusion erodes procedural premiums. Price-sensitive South Asian visitors anchor volume segments, while European cosmetic surgery clients exhibit lowest sensitivity to bundled recovery package premiums.
Supply Chain Analysis
SFDA fast-track licensing bottlenecks constrain Saudi greenfield hospital equipment procurement timelines. Medical device imports draw from Germany, USA, and Japan for robotic surgical platforms and cardiac catheterization labs. Single-source vulnerability concentrates in proton therapy suite manufacturers with limited regional service networks. Distribution runs through Dubai Health Authority-cleared logistics corridors that synchronize with visa-eligible facility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC medical tourism is recovering from pandemic-era visa restrictions and capital deployment freezes, with JCI accreditation cycle compression and telemedicine adoption serving as the cyclical demand drivers resetting patient decision timelines.
For Market Incumbents: Secure long-standing Joint Commission certification renewals ahead of eighteen-month re-survey compression to defend premium positioning against emerging Riyadh clusters. Anchor backward integration into Arabic-English clinical interpreter training pipelines to mitigate liability exposure from scarce certified translator capacity.
For New Entrants and Emerging Players: Anchor in Sharjah wellness corridor post-operative rehabilitation stays, the most penetrable segment relative to Dubai's saturated surgical throughput. Deploy direct-to-facility German-French booking interfaces to bypass traditional medical travel intermediaries and capture European cosmetic surgery demand.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among JCI-accredited specialty hospitals with extended-stay visa eligibility and remote monitoring subscription attach rates. Target acquisition archetypes are digital-first intermediaries with telemedicine pre-consultation platforms and proven North African patient capture. Watch SFDA-MOHAP regulatory harmonization progress as the inflection signal for cross-Gulf patient flow redistribution.
| Strategic Initiative | Industry Significance |
|---|---|
| JCI Accreditation Fast-Track | Compresses eighteen-month cycles to secure visa-linked facility eligibility ahead of competitors. |
| Telemedicine Pre-Consultation Platform | Collapses patient decision cycles and expands Egyptian and Moroccan catchment zones. |
| Robotic Surgical Platform Acquisition | Enables premium positioning for complex orthopedic interventions beyond standard procedures. |
| Extended-Stay Visa Tier Development | Unlocks month-long rehabilitation revenue streams through MOHAP category expansion. |
| Direct Booking Interface Localization | Bypasses travel intermediaries with Arabic-German-French portals for European demand capture. |
Research Methodology
A spread of perspectives from hospital licensing officers, medical travel coordinators, GPO contracts managers, and biomedical procurement leads converged on the working assumptions shaping GCC patient flow projections. Primary fieldwork combined structured interviews with Dubai Health Authority and MOHAP regulatory affairs specialists alongside secondary validation through Saudi Commission for Health Specialties credentialing databases, JCI accreditation records, and hospital procurement disclosures. Bottom-up facility capacity assessments and top-down visa issuance data were triangulated to anchor volume estimates.
Procedure type, patient origin geography, facility certification tier, and service offering digitization were modeled as the core segmentation dimensions across the projection horizon. CAGRs were derived from throughput scaling assumptions tied to SFDA fast-track licensing timelines and JCI re-survey compression effects. Forecast inputs incorporated telemedicine adoption curves for North African pre-consultation and robotic surgical platform deployment rates across Sharjah and Al Ain mid-tier facilities.
Material uncertainties — Saudi Vision 2030 hospital privatization delays, MOHAP outcome reporting mandate enforcement intensity, and European economic softness affecting discretionary cosmetic surgery demand — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as regulatory harmonization between SFDA and Dubai Health Authority frameworks evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
Japan Medical Tourism Market
Medical Tourism
Europe Medical Tourism Market
Medical Tourism
Asia-Pacific Medical Tourism Market
Medical Tourism
Thailand Medical Tourism Market
Medical Tourism
China Medical Tourism Market
Medical Tourism
South Korea Medical Tourism Market
Medical Tourism
Europe Dental Tourism Market
Medical Tourism
North America Health Tourism Market
Medical Tourism
Outbound Medical Tourism Services Market
Medical Tourism
UK Medical Tourism Market
Medical Tourism
Fertility Tourism Market
Medical Tourism
Spain Medical Tourism Market
Medical Tourism
Turkey Medical Tourism Market
Medical Tourism
North America Outbound Medical Tourism Services Market
Medical Tourism
Switzerland Healthcare and Medical Tourism Market
Medical Tourism
France Medical Tourism Market