
 Medical Tourism Market | 2026-2036
Medical Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Tourism Market Analysis
Post-operative care subscription models are expanding the addressable revenue per patient beyond the initial procedure. Apollo Hospitals leverages its integrated pharmacy and rehabilitation network to capture extended patient value chains. Bumrungrad International Hospital anchors Bangkok's reputation through JCI-accredited specialty centers. Fortis Healthcare competes on cardiac surgery volume with dedicated international patient coordination units.
Medical tourism encompasses the organized travel of patients across national borders to access healthcare services, typically involving pre-trip consultation, procedure execution, and recovery monitoring at accredited foreign facilities. Surgery dominates service type revenue, while cosmetic and orthopedic procedure types attract the highest self-pay margins from North American and European source markets. Insurance providers represent the fastest-growing end user segment as employers seek cost arbitrage on high-acuity treatments excluded from domestic network contracts.
Thailand's Medical Hub designation, India's NABH accreditation framework, and Mexico's COFEPRIS facility licensing collectively shape patient routing and facility investment decisions. FDA and EMA device approval reciprocity influences which implant technologies travel with patients versus get sourced locally. Stakeholders must monitor accreditation portability and liability jurisdiction evolution as virtual pre-consultation dissolves traditional destination selection barriers.
Market Dynamics
Post-operative care subscription models are compressing patient lifetime value capture timelines, forcing facilities to integrate rehabilitation and pharmacy networks before competitors lock in recurring revenue streams.
Growth Catalysts
- JCI Accreditation Standards:Thailand's Medical Hub designation elevates facility certification requirements across Southeast Asian corridors. Patients from North American source markets route toward accredited centers with transparent outcome reporting.
- Employer Self-Insurance Expansion:Corporate wellness programs now cover cross-border cardiac and orthopedic procedures excluded from domestic network contracts. Cost arbitrage on high-acuity treatments drives insurance provider segment expansion.
- Virtual Pre-Consultation Platforms:Telemedicine infrastructure dissolves traditional destination selection barriers. Patients conduct specialist interviews across multiple countries before committing to travel.
Market Restraints
- Implant Sourcing Fragmentation:FDA and EMA device approval reciprocity remains incomplete. Patients must verify whether implant technologies travel with them or require local sourcing at destination facilities.
- Liability Jurisdiction Ambiguity:Cross-border malpractice claims face uncertain legal resolution between patient home countries and procedure destinations. Insurance underwriters price this uncertainty into coverage premiums.
- Accreditation Portability Gaps:India's NABH framework and Mexico's COFEPRIS licensing lack mutual recognition with US Joint Commission standards. Patients bear verification burden for credential equivalence.
Strategic Opportunities
- Costa Rican Recovery Tourism Corridors:Post-operative wellness integration with ecotourism infrastructure attracts extended-stay cardiac patients from US markets. Recovery periods monetize through hospitality partnerships.
- ISO 15189 Laboratory Convergence:Pre-trip diagnostic standardization enables seamless handoffs between home-country testing and destination procedure scheduling. Facilities adopting this protocol reduce patient preparation friction.
- Direct Employer Contracting Channels:Self-insured employers negotiate bundled procedure rates directly with accredited foreign hospitals. This bypasses traditional insurance intermediaries and captures margin for both parties.
Industry Challenges
- International Patient Coordination Talent:Bilingual care navigators with clinical training and cultural competency command premium compensation. Facilities compete for limited talent pools across Bangkok, Mexico City, and Delhi clusters.
- Legacy Electronic Health Record Integration:Destination hospitals must reconcile disparate data formats from patient origin countries. Interoperability investments strain mid-tier facility capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Tourism Market |
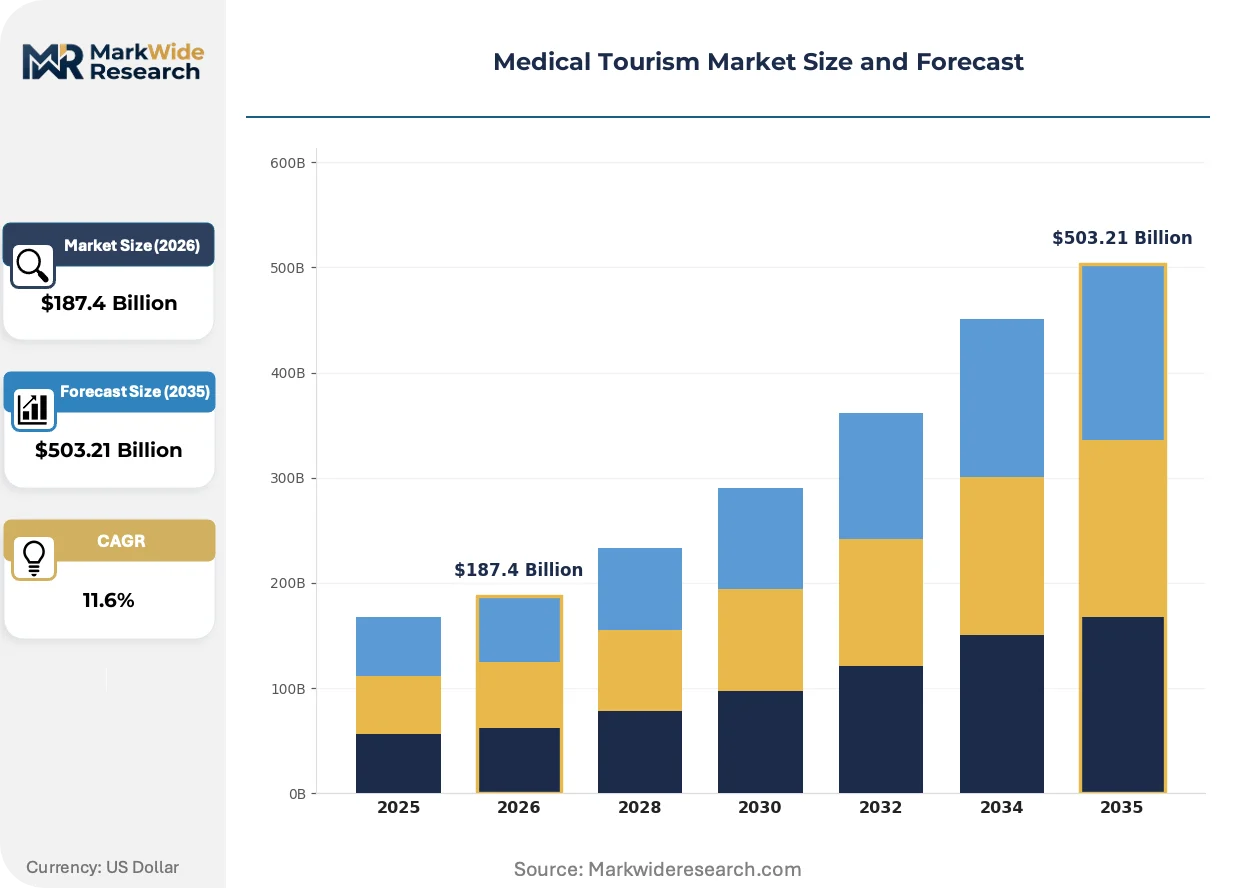
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $503.21 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Surgery, Wellness, Dentistry, Fertility Procedure Type: Cardiac Surgery, Orthopedic Surgery, Cosmetic Surgery, Organ Transplant End User: Individuals, Corporations, Insurance Providers, Government Programs Destination: Thailand, India, Mexico, Costa Rica |
| Companies Covered | Apollo Hospitals, Bumrungrad International Hospital, Fortis Healthcare, KPJ Healthcare Berhad, Raffles Medical Group, Bangkok Hospital, Prince Court Medical Centre, Mount Elizabeth Hospitals, Gleneagles Global Hospitals Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Tourism Market Emerging Trajectories
Digital infrastructure and regulatory reciprocity negotiations are compressing the traditional medical tourism decision cycle from months to weeks, while post-operative monitoring technology extends facility-patient relationships across borders.
Remote patient monitoring wearables with biometric streaming capability are rewriting post-discharge care economics. Destination hospitals now track recovery metrics for North American patients after return flights. Apollo Hospitals and Bumrungrad International anchor subscription revenue through continuous vital sign surveillance. This technology compresses readmission risk while extending addressable relationship duration.
EMA Medical Device Regulation harmonization with FDA 510(k) pathways is accelerating implant technology portability. European patients now travel with approved cardiac stents and orthopedic hardware to matched-approval destinations. Mexican facilities under COFEPRIS licensing leverage this convergence to reduce procurement complexity. The regulation most affects cardiac surgery corridors where device compatibility determines destination feasibility.
Employer direct contracting is displacing traditional insurance brokerage for high-acuity procedures. Self-insured corporations negotiate fixed bundles with JCI-accredited centers in Thailand and India. Benefits administrators cite cost transparency and outcome predictability as primary drivers. This pattern concentrates among Fortune 500 manufacturers with substantial blue-collar workforces requiring orthopedic interventions.
Medical Tourism Market Segmentation
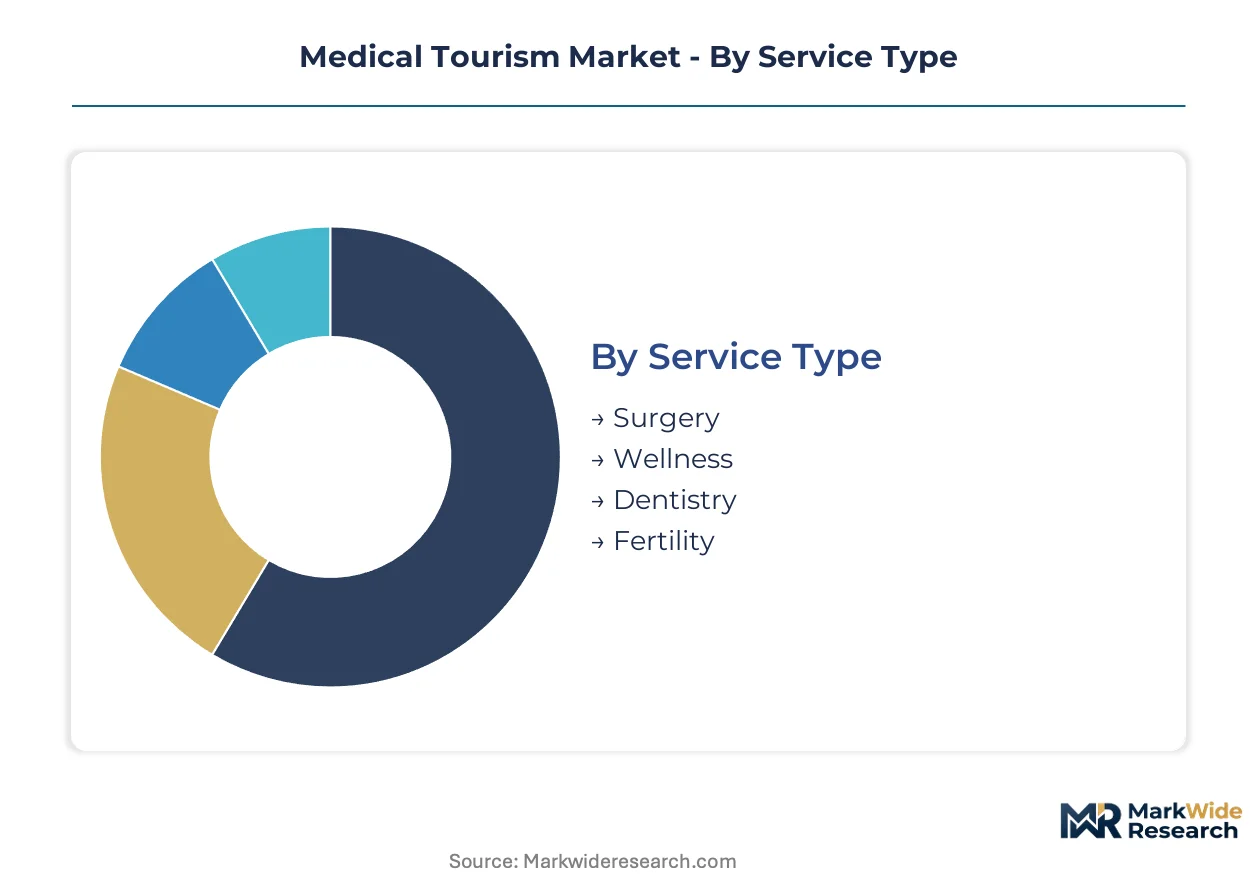
Medical tourism segmentation reveals distinct patient routing patterns where service complexity, procedure acuity, and payer type determine destination selection and facility economics. Understanding these intersections enables stakeholders to optimize capacity allocation and partnership structures across source and destination markets.
Service Type:
Customization intensity varies sharply across this spectrum, from standardized dental protocols to highly personalized surgical itineraries requiring multi-disciplinary coordination.
- Surgery:Invasive procedures requiring hospital admission and anesthesia support generate the highest revenue per episode. Cardiac and orthopedic corridors from US source markets to Mexican and Costa Rican facilities concentrate volume here, driven by employer self-insurance cost arbitrage on excluded domestic network treatments.
- Wellness:Preventive and diagnostic packages integrate hospitality and clinical services for extended-stay monetization. Thai Medical Hub facilities bundle executive health screening with recovery tourism infrastructure, attracting corporate wellness program allocations from European multinationals.
- Dentistry:Implant and cosmetic dental work commands strong self-pay margins with shorter decision cycles. Mexican border clinics capture routine procedures through proximity to US source markets.
- Fertility:Assisted reproductive technology cycles require multiple visits and medication coordination. Indian NABH-accredited centers compete on cycle pricing and donor availability for Middle Eastern and European patients.
Most installed capacity flows through Surgery. Expansion is steepest in Wellness.
Procedure Type:
Margin structure inverts across this category, with elective cosmetic work commanding premium self-pay pricing versus transplant procedures constrained by organ availability and regulatory complexity.
- Cardiac Surgery:Coronary bypass and valve replacement procedures require intensive care infrastructure and device compatibility verification. Mexican COFEPRIS-licensed facilities leverage FDA device reciprocity to reduce procurement friction for North American patients.
- Orthopedic Surgery:Joint replacement and spinal procedures generate predictable episode economics with standardized rehabilitation protocols. Apollo Hospitals and Fortis Healthcare compete on volume through dedicated international patient coordination units.
- Cosmetic Surgery:Elective aesthetic procedures attract the highest self-pay margins with minimal insurance intermediation. Thai facilities anchor Bangkok's reputation through JCI-accredited specialty centers serving European and Australian source markets.
- Organ Transplant:Liver and kidney transplantation faces strict regulatory oversight and donor matching logistics. Indian centers navigate CDSCO and international ethics frameworks to attract authorized cross-border cases.
Revenue concentration sits with Orthopedic Surgery. Cosmetic Surgery gains share fastest.
End User:
Payer sophistication determines contracting structure, from retail individual bookings to complex corporate risk arrangements with outcome guarantees.
- Individuals:Self-funded patients make destination decisions based on online reputation and price transparency. Virtual pre-consultation platforms now compress their decision cycles from months to weeks.
- Corporations:Self-insured employers negotiate bundled rates directly with accredited foreign hospitals. Fortune 500 manufacturers with substantial blue-collar workforces drive orthopedic intervention volumes through this channel.
- Insurance Providers:Benefits administrators seek cost arbitrage on high-acuity treatments excluded from domestic network contracts. This segment is expanding most quickly as corporate wellness programs extend cross-border coverage.
- Government Programs:Public payer involvement remains limited to bilateral agreements and authorized referral pathways rather than systematic program design.
Transaction volume flows through Individuals. Steepest expansion is occurring in Insurance Providers.
Destination:
Accreditation portability and liability frameworks differentiate destination competitiveness for risk-averse patient segments.
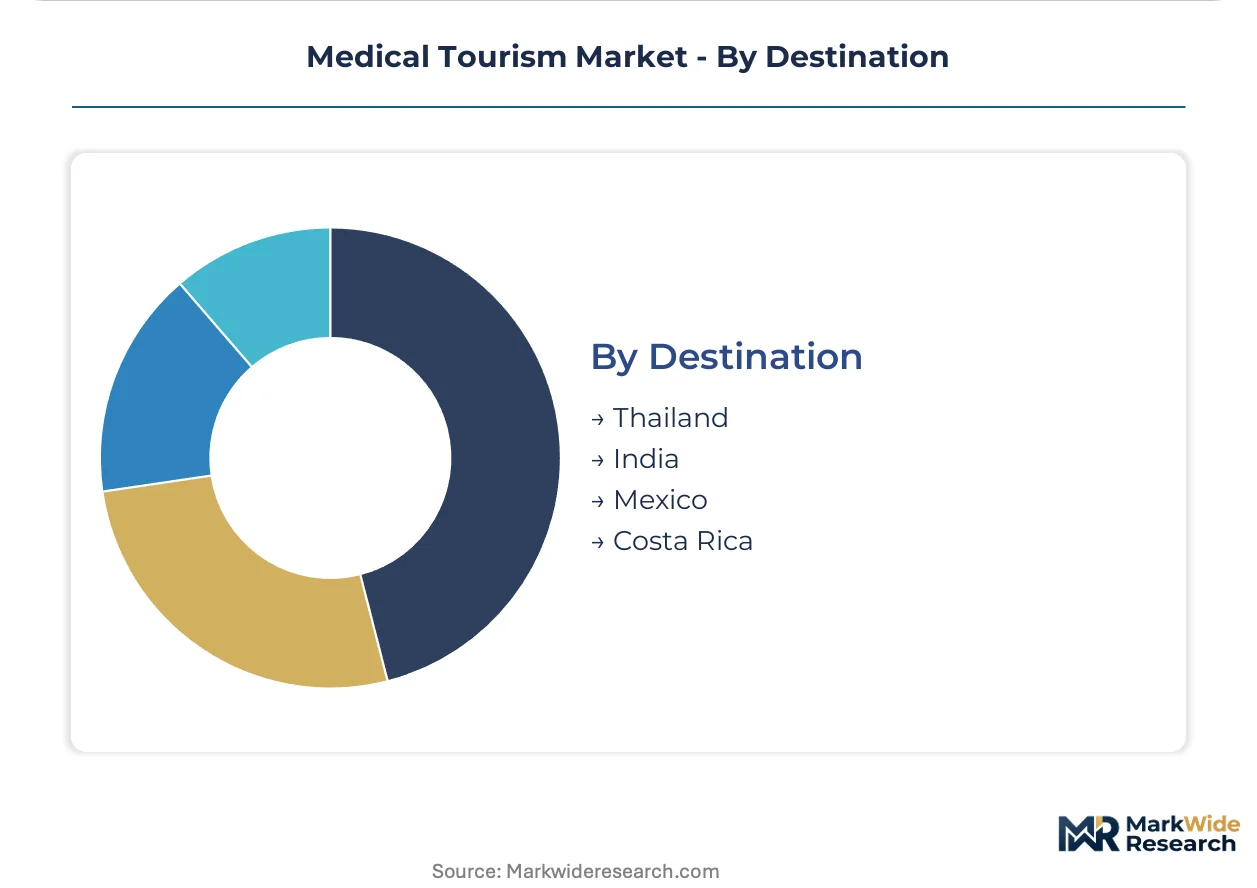
- Thailand:Medical Hub designation by the national tourism authority shapes JCI accreditation standards across Southeast Asian corridors. Bumrungrad International Hospital anchors Bangkok's premium positioning.
- India:NABH accreditation framework and Apollo Hospitals' integrated pharmacy networks capture extended patient value chains. Cardiac surgery volume competes with cost-advantaged pricing.
- Mexico:COFEPRIS facility licensing and FDA device reciprocity reduce procurement complexity for North American patients. Border proximity drives dental and routine procedure volume.
- Costa Rica:Ecotourism infrastructure integration attracts extended-stay cardiac patients through post-operative wellness monetization. Recovery periods generate hospitality partnership revenue.
Established capacity concentrates in Thailand. Steepest growth trajectory belongs to Costa Rica.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand commands premium positioning through Medical Hub designation while Mexico captures volume through border proximity and FDA device reciprocity. India and Costa Rica compete on extended-stay recovery integration. Facility investment clusters around accreditation portability and liability framework clarity.
Thailand
Medical Hub designation by the national tourism authority elevates JCI certification requirements across Southeast Asian corridors. Bumrungrad International Hospital anchors Bangkok's premium positioning through specialty center concentration. European and Australian source markets route toward accredited centers with transparent outcome reporting.
India
NABH accreditation framework and Apollo Hospitals' integrated pharmacy networks capture extended patient value chains. CDSCO regulates implant technology compatibility for cardiac surgery corridors. Delhi and Mumbai clusters compete on cost-advantaged pricing for Middle Eastern and European patients.
Mexico
COFEPRIS facility licensing and FDA device reciprocity reduce procurement complexity for North American patients. Border clinics capture dental and routine procedure volume through proximity to US source markets. Tijuana and Cancún anchor medical corridors linking employer self-insurance programs.
Costa Rica
Ecotourism infrastructure integration attracts extended-stay cardiac patients through post-operative wellness monetization. Recovery periods generate hospitality partnership revenue. San José anchors the corridor with facilities leveraging ISO 15189 laboratory standardization for seamless pre-trip diagnostic handoffs.
Singapore
Raffles Medical Group and Mount Elizabeth Hospitals anchor high-acuity positioning through premium pricing and outcome guarantees. The city-state's regulatory framework emphasizes liability clarity for risk-averse patient segments. Specialist concentration in oncology and cardiac surgery attracts regional referral traffic.
Medical Tourism Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated hospital networks capturing extended patient value while standalone specialty centers compete on procedure volume. Market structure tilts toward consolidation around accreditation-heavy players with international patient coordination capabilities. Three archetypes dominate: integrated multi-specialty hospital networks, standalone JCI-accredited specialty centers, and hospitality-linked recovery facilities. Competitive moves concentrate on M&A for pharmacy network integration and direct employer contracting channel development.
Within the integrated network tier, Apollo Hospitals and Fortis Healthcare exemplify vertical control over pharmacy and rehabilitation value chains. Bumrungrad International Hospital anchors the standalone specialty center archetype through JCI-accredited concentration in Bangkok. These three entities represent distinct strategic positions: Apollo captures extended patient relationships through subscription monitoring, Fortis competes on cardiac surgery volume with dedicated coordination units, and Bumrungrad leverages Thailand's Medical Hub designation for premium international positioning.
| Leading Market Players |
|---|
| Apollo Hospitals |
| Bumrungrad International Hospital |
| Fortis Healthcare |
| KPJ Healthcare Berhad |
| Raffles Medical Group |
| Bangkok Hospital |
| Prince Court Medical Centre |
| Mount Elizabeth Hospitals |
| Gleneagles Global Hospitals Group |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed hospital networks in Thailand and India anchor supply concentration through state-supported Medical Hub designations and NABH accreditation frameworks, translating policy backing into pricing discipline across cardiac and orthopedic corridors. Private-equity-rolled-up specialty clinics in Mexican border zones compete on spot pricing for dental and cosmetic procedures, fragmenting price floors in proximity-driven segments.
Pricing Analysis
Capacity additions in Costa Rica are reshaping price floors for post-operative recovery packages as ecotourism infrastructure expands. Three-tier pricing structure across JCI-accredited premium centers, NABH-standard facilities, and COFEPRIS-licensed volume clinics separates Bangkok's Bumrungrad International from Delhi's Apollo Hospitals from Tijuana's border clinics. Cost compression in the standard tier is intensifying because employer direct contracting channels bypass traditional insurance markups. Insurance providers demonstrate highest price sensitivity through bundled rate negotiations, while self-funded individuals in cosmetic surgery show lowest sensitivity to premium tier pricing.
Supply Chain Analysis
Reverse-logistics flows for implant devices and rehabilitation equipment remain underdeveloped, constraining circular economy capture in destination facilities. Supply concentrates in Thailand, India, and Mexico for JCI-accredited procedure capacity, with Costa Rica emerging for recovery-integrated corridors. Raw material dependencies center on FDA- and EMA-approved cardiac stents, orthopedic hardware, and biologic implants sourced through manufacturer-direct channels. Single-source vulnerability in device approval reciprocity creates procurement friction when patients travel with non-matched hardware. Distribution runs through hospital-integrated pharmacy networks and direct-to-employer contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where cardiac bypass procedures in Mexican COFEPRIS-licensed facilities undercut US domestic network rates by leveraging FDA device reciprocity and lower labor cost structures.
For Market Incumbents: Deploy post-operative subscription monitoring to lock in extended patient relationships before competitors capture recurring revenue streams. Incumbents must defend against virtual pre-consultation platforms dissolving destination loyalty by integrating telemedicine infrastructure into existing JCI-accredited specialty centers. Backward integration into rehabilitation pharmacy networks captures margin leakage to third-party dispensaries. For New Entrants and Emerging Players: Capture white-space in Costa Rican recovery tourism corridors where ecotourism infrastructure remains underutilized for cardiac patient extended stays. New entrants should target employer direct contracting channels for Fortune 500 manufacturers with substantial blue-collar orthopedic intervention needs. A go-to-market angle through ISO 15189 laboratory standardization enables seamless pre-trip diagnostic handoffs from US source markets. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier COFEPRIS-licensed Mexican facilities lacking international patient coordination capabilities. Long-term viability across the analysis window rests on accreditation portability convergence between NABH, JCI, and national licensing frameworks. Acquisition targets should show dedicated bilingual care navigator teams and EHR interoperability investments. The signal to watch is EMA-FDA device regulation harmonization accelerating implant technology portability for European patient segments.| Strategic Initiative | Industry Significance |
|---|---|
| JCI Accreditation Investment | Elevates facility certification requirements across Southeast Asian corridors to attract North American routing. |
| Direct Employer Contracting | Bypasses traditional insurance intermediaries and captures margin for self-insured corporations and accredited hospitals. |
| Post-Operative Subscription Launch | Extends addressable relationship duration through Apollo Hospitals' continuous vital sign surveillance model. |
| Virtual Pre-Consultation Platform | Dissolves traditional destination selection barriers by enabling specialist interviews across multiple countries. |
| ISO 15189 Laboratory Adoption | Reduces patient preparation friction through seamless pre-trip diagnostic handoffs between origin and destination facilities. |
Methodological Framework
Direct dialogue with hospital international patient coordinators, employer benefits administrators, insurance underwriters, and accreditation body officials grounded qualitative findings in operational reality. Secondary validation drew from JCI accreditation databases, COFEPRIS facility registries, employer self-insurance plan filings, and medical device approval reciprocity documentation. Bottom-up procedure volume estimates triangulated against top-down market sizing across service type, procedure type, and end user segments.
Bottom-up modeling aggregated facility-level capacity and utilization rates across Thailand, India, Mexico, and Costa Rica, while top-down analysis calibrated against employer wellness program expenditure patterns and insurance provider cost arbitrage strategies. Segmentation dimensions included service complexity tiers, payer sophistication levels, and destination accreditation portability clusters. CAGRs derived from regression analysis of historical routing patterns and projected employer self-insurance expansion. Forecast inputs incorporated virtual consultation adoption curves and EMA-FDA harmonization timelines.
Underlying measurement precision varies by segment; surgery and orthopedic procedure volumes carry tighter precision than wellness and fertility categories where self-pay reporting lags. Forecasts reflect assumptions on accreditation mutual recognition evolution, liability framework clarity, and implant technology portability convergence. Periodic stress-testing of base assumptions is recommended against regulatory reciprocity negotiations and virtual care platform disruption vectors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
North America Outbound Medical Tourism Services Market
Medical Tourism
North America Health Tourism Market
Medical Tourism
Asia-Pacific Medical Tourism Market
Medical Tourism
France Medical Tourism Market
Medical Tourism
Thailand Medical Tourism Market
Medical Tourism
UK Medical Tourism Market
Medical Tourism
Europe Dental Tourism Market
Medical Tourism
Fertility Tourism Market
Medical Tourism
Malaysia Medical Tourism Market
Medical Tourism
Turkey Medical Tourism Market
Medical Tourism
South Korea Medical Tourism Market
Medical Tourism
India Medical Tourism Market
Medical Tourism
Barbados Healthcare and Medical Tourism Market
Medical Tourism
Europe Medical Tourism Market
Medical Tourism
Switzerland Healthcare and Medical Tourism Market
Medical Tourism
Spain Medical Tourism Market