
 India Medical Tourism Market | 2026-2036
India Medical Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
India Medical Tourism Market Outlook
Accreditation-grade hospital infrastructure is unwinding cost barriers for foreign patients seeking complex surgical interventions. Apollo Hospitals leverages its JCI-accredited network to anchor premium cardiac and transplant services across South India. Fortis Healthcare competes through multi-city specialty hubs that sustain high-throughput oncology and orthopedics programs. Max Healthcare differentiates via integrated diagnostics-to-discharge platforms that control patient flow across Delhi-NCR.
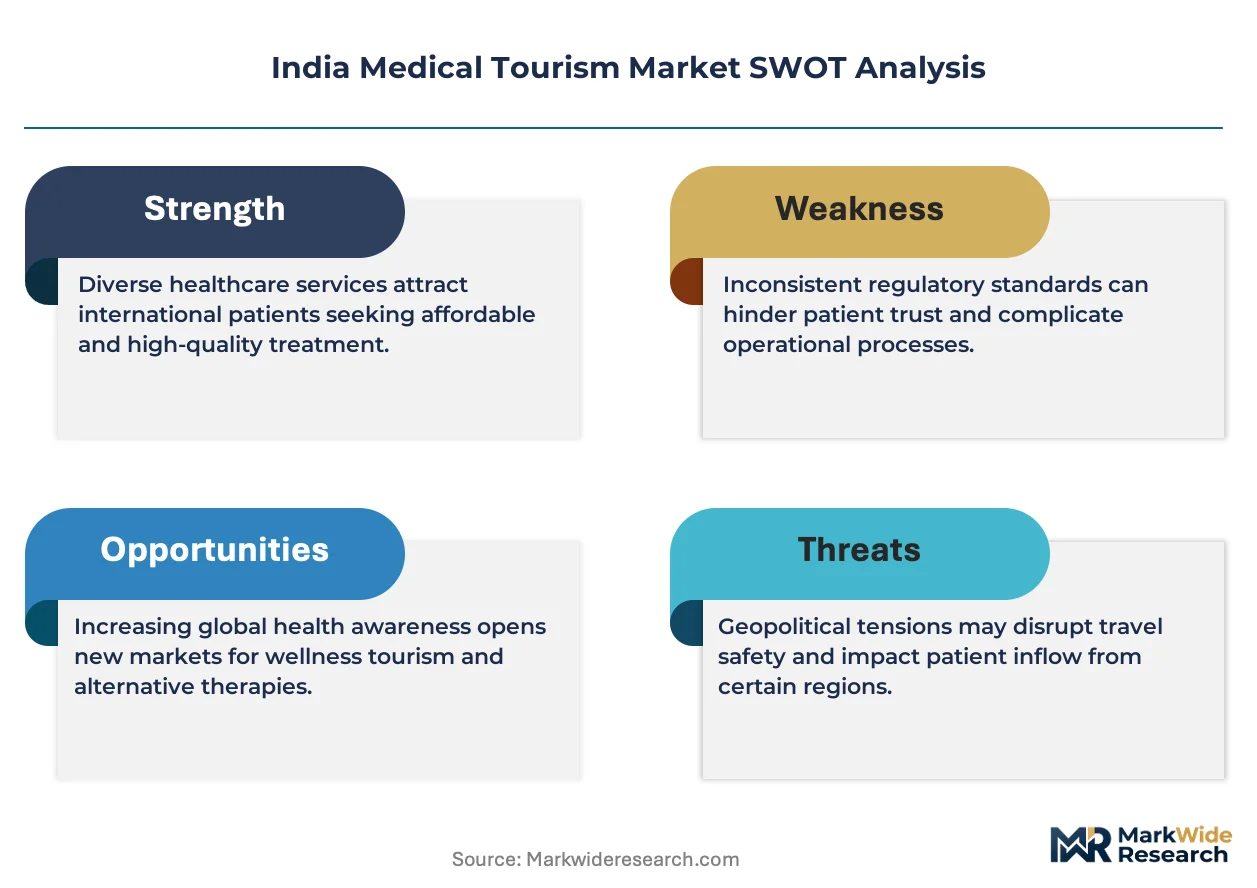
India medical tourism encompasses the organized provision of clinical treatment, surgical intervention, and post-operative rehabilitation to non-resident patients who travel specifically to access care at price points typically 60-80% below Western benchmarks. The sector functions through a triad of accredited hospitals, government-sanctioned visa pathways, and digital facilitator platforms that coordinate logistics across geographies. Cardiac surgery and orthopedic surgery command the deepest procedure volumes, while cosmetic surgery registers the fastest patient inflow acceleration from Gulf Cooperation Council and African source markets. Private hospitals capture the dominant margin pool through direct international billing relationships, whereas medical tourism facilitators occupy a structurally fragmented intermediary layer with limited pricing power.
NABH accreditation and the Ministry of Health's e-Medical Visa program shape market access by establishing baseline quality thresholds and streamlining entry documentation for patients from 166 designated countries. CDSCO oversight of implantable devices and the Medical Council of India's clinical establishment standards further constrain which facilities qualify for international patient intake. Stakeholders must monitor how Ayushman Bharat's cross-border portability experiments and state-level medical value travel policies redistribute patient capture between Kerala's wellness-integrated hospitals and Maharashtra's metropolitan surgical centers.
Market Dynamics
The e-Medical Visa framework and NABH accreditation standards are compressing patient onboarding timelines while redistributing volume toward facilities with dual-certification status.
Growth Catalysts
- CDSCO fast-track pathways:Accelerated device approvals for cardiac stents and orthopedic implants shorten procurement cycles for hospitals serving foreign patients.
- Bangladesh patient corridor:Shared linguistic ties and land border proximity sustain a predictable referral pipeline for cardiac and renal procedures.
- Telemedicine pre-consultation:Remote diagnostic screening reduces in-country stay duration and expands catchment to African source markets previously excluded by travel costs.
Market Restraints
- Implant cost volatility:Imported cardiac stents and knee prostheses face currency-driven price swings that compress margin predictability for fixed-package pricing models.
- Single-city supply concentration:Chennai's hospital corridor controls disproportionate cardiac surgery capacity, creating geographic bottlenecks during peak seasonal demand.
- Medical Council of India licensing friction:Foreign physician credential verification delays limit temporary specialist deployment for complex transplant coordination.
Strategic Opportunities
- Kerala wellness integration:Ayurveda-certified hospitals can capture extended-stay rehabilitation demand from Gulf Cooperation Council patients seeking post-surgical recovery programs.
- PLI scheme medical device manufacturing:Domestic production of orthopedic implants reduces import dependency and enables cost-competitive bundled procedure pricing.
- Digital health facilitator platforms:Blockchain-verified medical records streamline cross-border insurance pre-authorization for African self-pay segments.
Industry Challenges
- Transplant coordinator certification gaps:Shortage of NABH-trained case managers limits patient throughput for multi-organ procedures requiring extended logistics coordination.
- Legacy HIS integration:Hospital information systems at tier-2 facilities lack API compatibility with international insurance clearinghouses, delaying real-time eligibility verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Medical Tourism Market |
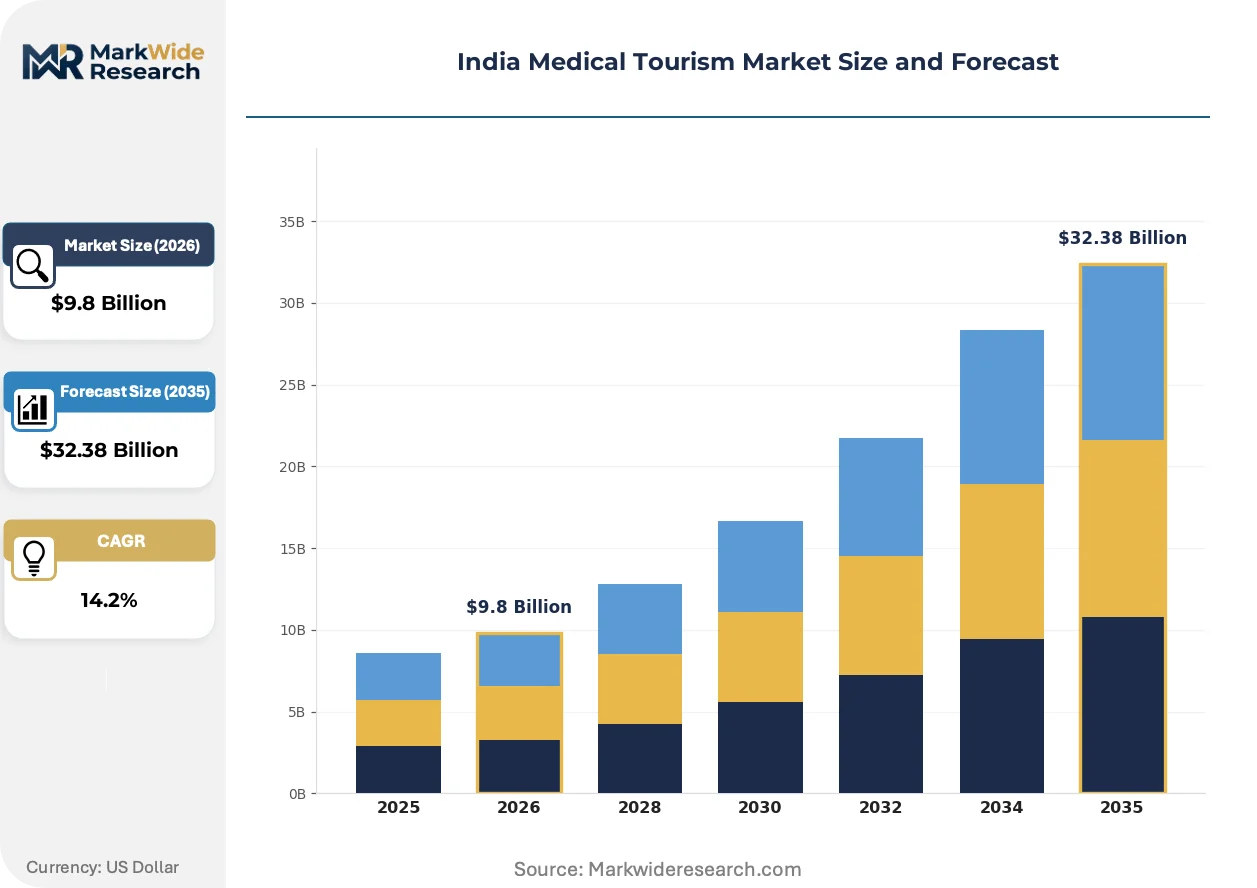
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $32.38 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Cardiac Surgery, Orthopedic Surgery, Cosmetic Surgery, Organ Transplant Visitor Type: International Patients, Domestic Patients, Medical Tourists, Expatriates Payment Mode: Insurance, Out-of-Pocket, Financing, Corporate Sponsorship Hospital Type: Private Hospitals, Public Hospitals, Specialty Clinics, Medical Tourism Facilitators |
| Companies Covered | Apollo Hospitals, Fortis Healthcare, Max Healthcare, Narayana Health, Manipal Hospitals, Clinicspots, Vaidam, Forerunners Healthcare, MediConnect India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Medical Tourism Market Strategic Shifts
Robotic-assisted surgical platforms and AI-powered diagnostic triage are compressing procedure timelines while enabling remote pre-operative planning that reduces patient stay duration.
Da Vinci surgical systems are supplanting conventional laparoscopic approaches in Delhi-NCR oncology units. Apollo Hospitals and Max Healthcare have deployed these platforms across metropolitan clusters, enabling minimally invasive tumor resections that cut recovery time by half. This shift is compressing the economic viability window for hospitals without robotic capital expenditure capacity.
The Ministry of Health's e-Medical Visa extension to 166 countries is standardizing entry documentation while creating digital audit trails for patient outcomes. CDSCO has aligned implantable device registration requirements with this framework, forcing manufacturers to submit real-world performance data. Tier-1 hospitals are responding by consolidating procurement relationships with suppliers possessing dual NABH-CDSCO certification.
Self-pay patients from African source markets are bypassing traditional facilitator intermediaries and booking directly through hospital-owned digital portals. This channel shift is fragmenting the intermediary layer that previously controlled pricing opacity and patient flow allocation. Maharashtra's metropolitan surgical centers are capturing disproportionate share of this disintermediated demand through integrated diagnostics-to-discharge platforms.
India Medical Tourism Market Segmentation
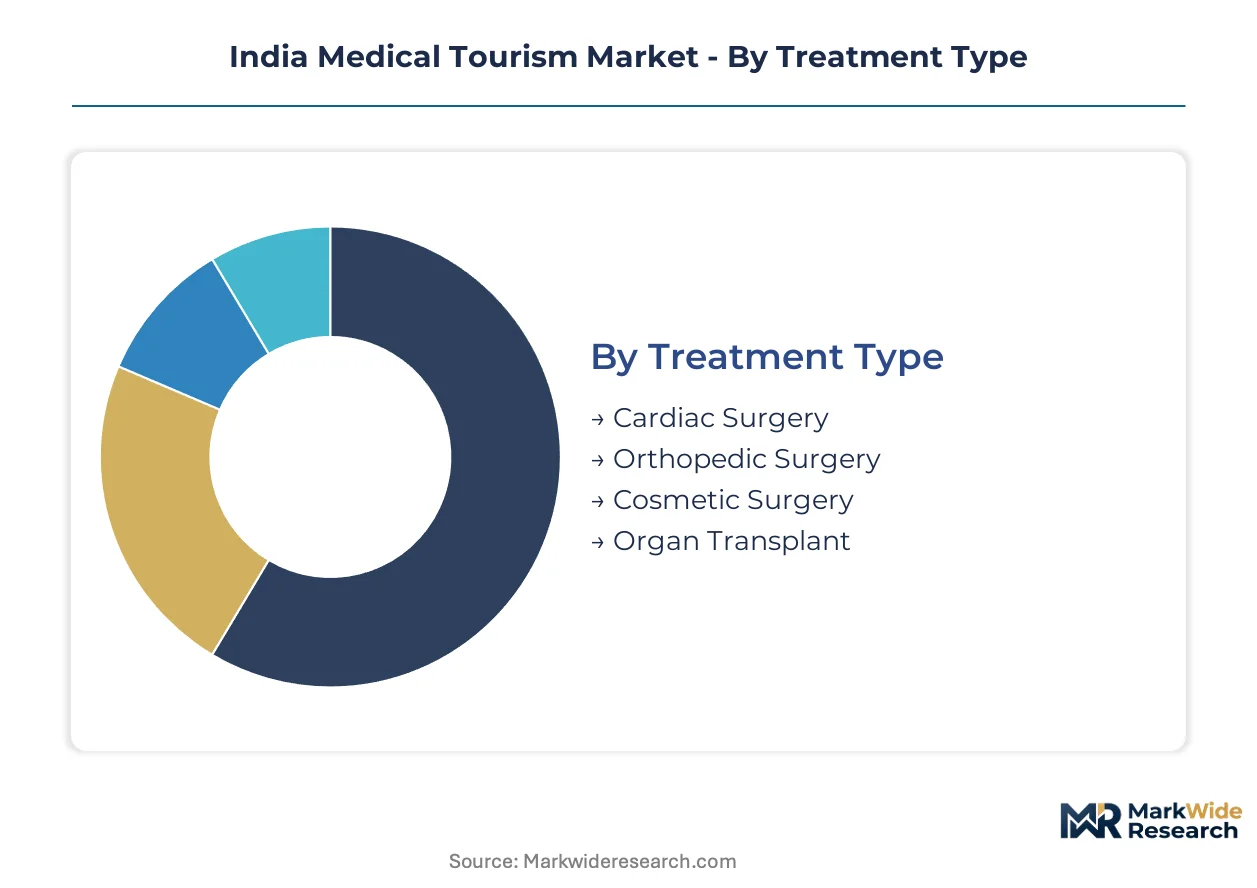
Segmentation in India's medical tourism market reveals how patient flows concentrate around specific clinical specializations and payment capacities. Understanding these divisions exposes where infrastructure investments yield patient capture and which service tiers absorb price sensitivity from Bangladesh, Africa, and Gulf source markets.
Treatment Type:
Cardiac and orthopedic interventions anchor export-led demand from Bangladesh and African markets, while cosmetic procedures draw self-pay Gulf patients; organ transplant volumes remain constrained by domestic regulatory frameworks.
- Cardiac Surgery:Coronary artery bypass grafting and valve replacement procedures dominate hospital throughput at JCI-accredited facilities. Demand concentrates in Chennai's hospital corridor and Delhi-NCR specialty clusters driven by Bangladesh patient referrals seeking 60-80% cost savings versus Dhaka alternatives.
- Orthopedic Surgery:Total knee and hip arthroplasty utilizing imported prostheses from CDSCO-registered manufacturers. Volume clusters in Maharashtra metropolitan centers where PLI scheme domestic implant production is compressing procedure package pricing for African self-pay segments.
- Cosmetic Surgery:Rhinoplasty, hair transplantation, and aesthetic dermatology procedures.
- Organ Transplant:Renal and liver transplantation limited by THOA regulatory constraints and donor availability.
Cardiac surgery holds the largest share; momentum sits with cosmetic surgery.
Visitor Type:
International patient categories split between organized medical tourists using facilitator networks and direct-booking expatriates; domestic patients accessing premium private tiers create internal referral pipelines.
- International Patients:Non-residents holding e-Medical Visas from 166 designated countries seeking complex surgical interventions. Bangladesh nationals generate predictable cardiac and renal procedure volume through land-border access points.
- Domestic Patients:Indian nationals crossing state boundaries to access NABH-accredited facilities with superior outcomes data.
- Medical Tourists:Organized travelers booking through digital facilitator platforms with bundled logistics.
- Expatriates:Overseas Indian workers returning for cost-competitive elective procedures.
International patients command the dominant revenue pool; expatriates are climbing the fastest as direct-booking platforms fragment intermediary control.
Payment Mode:
Payment structures stratify across insurance-backed corporate segments and pure self-pay markets, with financing instruments emerging for high-ticket transplant procedures.
- Insurance:Cross-border health policies and international travel medical coverage requiring blockchain-verified pre-authorization.
- Out-of-Pocket:Direct cash payments from African and Bangladeshi patients bypassing facilitator markups through hospital-owned portals.
- Financing:Medical loans and installment structures for transplant and cardiac surgery packages.
- Corporate Sponsorship:Employer-funded treatment for Gulf Cooperation Council expatriate workers.
Out-of-pocket dominates transaction volume; financing shows steepest expansion trajectory as transplant coordinators develop structured payment plans.
Hospital Type:
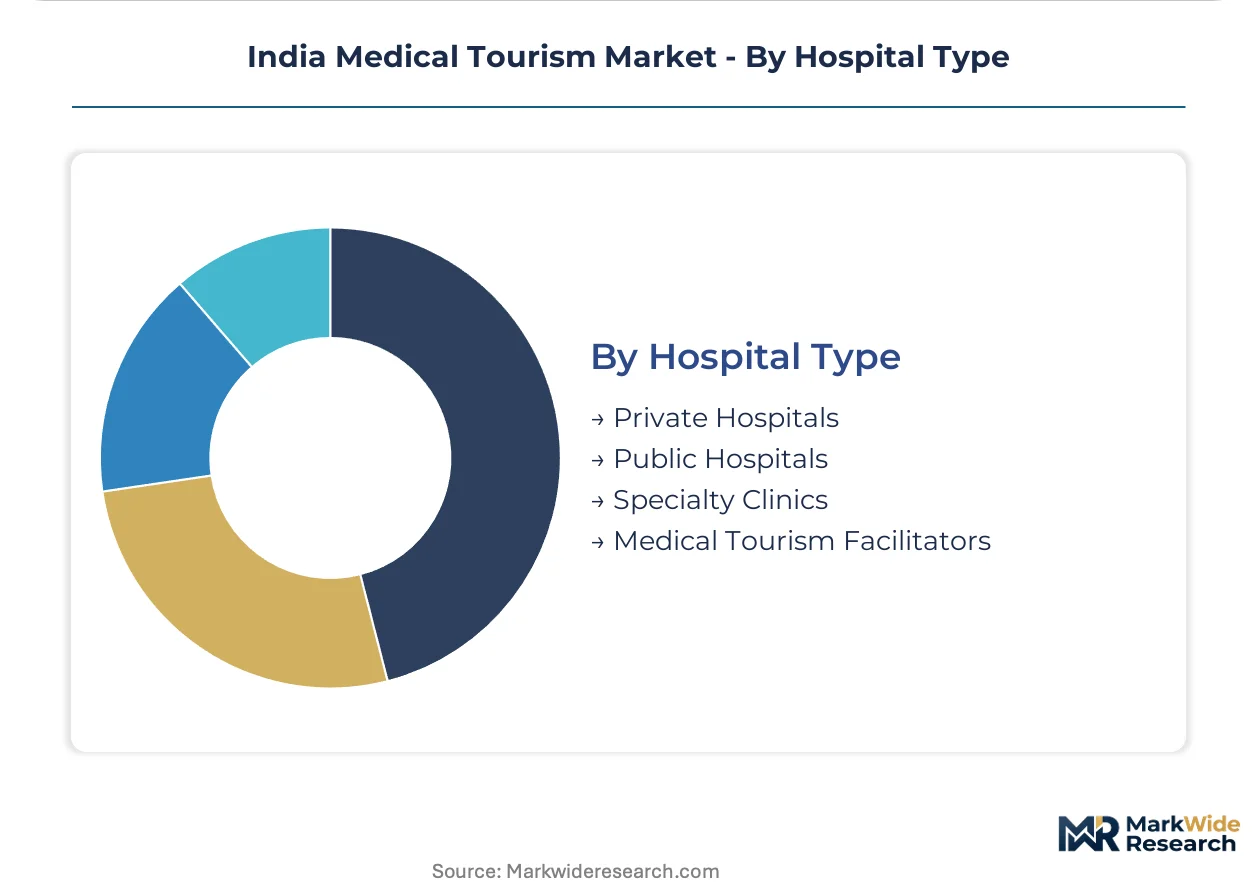
Facility types range from capital-intensive multi-specialty hospitals capturing international billing relationships to fragmented facilitator intermediaries losing pricing power to disintermediation.
- Private Hospitals:JCI and NABH-accredited tertiary centers with robotic surgical platforms and integrated diagnostics-to-discharge systems. Apollo, Fortis, and Max Healthcare networks control premium cardiac and oncology throughput across South India and Delhi-NCR.
- Public Hospitals:Government medical colleges with limited international patient infrastructure constrained by legacy HIS systems lacking API compatibility with insurance clearinghouses.
- Specialty Clinics:Concentrated orthopedics and fertility centers in metropolitan clusters.
- Medical Tourism Facilitators:Intermediary agencies coordinating logistics, visas, and accommodation.
Private hospitals capture the dominant margin pool; specialty clinics gain share fastest as Kerala wellness-integrated facilities target extended-stay rehabilitation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital-grade infrastructure clusters in four Indian states that together capture the bulk of inbound cardiac and orthopedic volume. CDSCO's device registration pathways and state-level medical value travel policies are redistributing patient flows across these corridors.
Maharashtra
Mumbai and Pune metropolitan centers absorb African self-pay demand for total knee arthroplasty and spinal fusion procedures. The state's PLI scheme for medical device manufacturing is attracting domestic orthopedic implant production that compresses procedure package pricing. Navi Mumbai's specialty hospital clusters are integrating robotics platforms to capture disintermediated bookings bypassing traditional facilitators.
Tamil Nadu
Chennai's hospital corridor dominates cardiac surgery throughput for Bangladeshi patients arriving through land-border checkpoints. The state's medical value travel policy framework coordinates with the e-Medical Visa system to streamline entry documentation. Coimbatore's emerging specialty centers are targeting Kerala's wellness-integrated rehabilitation demand for extended-stay post-surgical recovery.
Delhi-NCR
The capital region's JCI-accredited facilities anchor premium oncology and transplant services for Gulf Cooperation Council patients. Haryana's contiguous hospital belt extends capacity for complex multi-organ procedures requiring extended logistics coordination. Gurugram's integrated diagnostics-to-discharge platforms are capturing direct-booking expatriate demand through hospital-owned digital portals.
Karnataka
Bengaluru's technology-enabled hospital networks leverage telemedicine pre-consultation to expand African catchment previously excluded by travel costs. The state's NABH-accredited tertiary centers are deploying AI-powered diagnostic triage to compress patient onboarding timelines. Mysuru's emerging Ayurveda-certified facilities are targeting post-surgical wellness rehabilitation from Middle Eastern source markets.
Kerala
Kochi and Thiruvananthapuram wellness-integrated hospitals capture extended-stay demand from Gulf patients seeking Ayurveda-certified post-operative recovery programs. The state's medical tourism policy framework emphasizes accreditation-grade infrastructure alongside traditional medicine integration. Alleppey's rehabilitation centers are bundling cardiac recovery with wellness protocols that differentiate from metropolitan surgical-only offerings.
India Medical Tourism Market Competitive Environment
Concentration sits with multi-hospital networks possessing dual JCI-NABH certification and robotic surgical platforms. Apollo Hospitals, Fortis Healthcare, and Max Healthcare control premium procedure throughput through metropolitan clusters. Two strategic archetypes dominate: capital-intensive tertiary networks with integrated diagnostics-to-discharge systems, and digital-native facilitator platforms disintermediating traditional intermediaries. Competitive moves center on capacity expansion in tier-2 cities and technology licensing for remote pre-operative planning.
Among hospital-network archetypes, Apollo Hospitals and Fortis Healthcare exemplify the accredited multi-city model, while Max Healthcare occupies a position emphasizing integrated patient flow management. Within the facilitator tier, Clinicspots and Vaidam represent digital-native platforms fragmenting intermediary control through direct-booking portals. Narayana Health and Manipal Hospitals sit within the high-throughput specialty cluster targeting price-sensitive segments with standardized procedure packages.
| Leading Market Players |
|---|
| Apollo Hospitals |
| Fortis Healthcare |
| Max Healthcare |
| Narayana Health |
| Manipal Hospitals |
| Clinicspots |
| Vaidam |
| Forerunners Healthcare |
| MediConnect India |
| Others |
Value Chain & Pricing Dynamics
Domestic orthopedic implant production under India's PLI scheme is displacing imported knee prostheses and cardiac stents, compressing procedure package pricing while redistributing procurement power toward Maharashtra's metropolitan surgical centers and away from Chennai's import-dependent cardiac corridors.
Pricing Analysis
CDSCO's device registration tier structure dictates the pricing stratification across India's medical tourism facilities. Three-tier pricing separates JCI-accredited premium networks from NABH-standard hospitals and non-accredited economy providers, with certification grade and robotic surgical platform availability as primary differentiation drivers. Cost compression in the standard tier is intensifying because African self-pay patients bypass facilitator markups through direct hospital portals. Bangladeshi cardiac patients show highest price sensitivity, while Gulf Cooperation Council cosmetic surgery seekers demonstrate lowest elasticity.
Supply Chain Analysis
Container availability fluctuations at Mumbai's Jawaharlal Nehru Port and Chennai's maritime terminals elevate inbound logistics costs for CDSCO-registered cardiac stents and knee prostheses sourced from Germany, Switzerland, and the United States. Raw material dependencies center on cobalt-chromium alloys for orthopedic implants and drug-eluting polymer coatings for cardiovascular devices. Single-source vulnerability concentrates in Swiss-manufactured precision components. Distribution runs through hospital-owned procurement divisions with direct manufacturer relationships, bypassing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards facilities possessing NABH-trained transplant coordinators and integrated diagnostics-to-discharge platforms, while shortages of these specialized case managers constrain patient throughput for multi-organ procedures requiring extended logistics coordination.
For Market Incumbents: Compound accreditation advantages by deploying robotic surgical platforms across tier-2 city clusters before emerging specialty hospitals capture disintermediated African demand. Defend against digital-native facilitator platforms by integrating blockchain-verified medical records with international insurance clearinghouses. Prioritize backward integration into domestic implant manufacturing through PLI scheme partnerships. For New Entrants and Emerging Players: Anchor in Kerala's wellness-integrated rehabilitation segment, where Ayurveda-certified post-surgical recovery programs for Gulf patients remain underdeveloped relative to metropolitan surgical-only offerings. Target extended-stay cardiac recovery bundled with traditional medicine protocols as the most penetrable white space. Build direct-booking digital portals with telemedicine pre-consultation capabilities to bypass fragmented intermediary control. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors accredited multi-city networks with dual JCI-NABH certification and captive robotic platform deployment. Long-term viability across the next decade rests on controlling patient flow through integrated diagnostics-to-discharge systems rather than fragmented facilitator relationships. Monitor Ayushman Bharat's cross-border portability experiments as the signal indicating whether Kerala's wellness-integrated model or Maharashtra's metropolitan surgical centers will capture redistributed patient volume.| Strategic Initiative | Industry Significance |
|---|---|
| NABH-JCI Dual Certification Pursuit | Dual accreditation unlocks premium cardiac and transplant pricing tiers for Bangladesh and Gulf patient segments. |
| Robotic Surgical Platform Deployment | Da Vinci systems at Delhi-NCR oncology units compress recovery timelines and justify procedure package premiums. |
| Telemedicine Pre-Consultation Buildout | Remote diagnostic screening expands African catchment previously excluded by travel cost barriers. |
| Domestic Implant Manufacturing Integration | PLI scheme orthopedic production reduces import dependency and enables cost-competitive bundled pricing. |
| Blockchain Medical Records Implementation | Verified records streamline cross-border insurance pre-authorization for African self-pay market penetration. |
Study Parameters
A spread of perspectives from hospital international patient coordinators, CDSCO regulatory affairs specialists, NABH accreditation auditors, medical tourism facilitator operators, and biomedical procurement managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against e-Medical Visa issuance statistics, hospital procurement databases, GPO contracts with international insurers, and CDSCO device registration filings. Bottom-up patient volume modeling triangulated against top-down healthcare expenditure projections across the analysis window.
Segmentation dimensions modeled include treatment type specialization, visitor category, payment mode structure, and hospital accreditation tier across the projection horizon. CAGRs derived from procedure volume trajectories weighted by average revenue per patient, with inputs calibrated against e-Medical Visa extension patterns and NABH accreditation pipeline data. Industry-specific forecast inputs incorporated PLI scheme manufacturing capacity announcements and state-level medical value travel policy implementations.
Decision-makers should treat outputs as directional under assumptions of sustained e-Medical Visa framework stability and CDSCO device registration pathway continuity; material deviation in regulatory enforcement or currency volatility would warrant model refresh. Forecasts reflect these base conditions without contingency for THOA transplant regulation amendments or Ayushman Bharat cross-border portability expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
Barbados Healthcare and Medical Tourism Market
Medical Tourism
South Korea Medical Tourism Market
Medical Tourism
Europe Medical Tourism Market
Medical Tourism
North America Outbound Medical Tourism Services Market
Medical Tourism
Italy Medical Tourism Market
Medical Tourism
Fertility Tourism Market
Medical Tourism
Thailand Medical Tourism Market
Medical Tourism
Switzerland Healthcare and Medical Tourism Market
Medical Tourism
Malaysia Medical Tourism Market
Medical Tourism
Outbound Medical Tourism Services Market
Medical Tourism
Asia-Pacific Medical Tourism Market
Medical Tourism
UK Medical Tourism Market
Medical Tourism
Medical Tourism Market
Medical Tourism
Turkey Medical Tourism Market
Medical Tourism
GCC Countries Medical Tourism Market
Medical Tourism
Europe Dental Tourism Market