
 Japan Medical Tourism Market | 2026-2036
Japan Medical Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Medical Tourism Market Insights
Post-operative rehabilitation and long-term follow-up service bundling is shifting how Japanese medical tourism packages are structured and priced. St. Luke's International Hospital leverages its multilingual care coordination to anchor premium inbound patient flows. Keio University Hospital sustains competitive positioning through deep specialization in complex cardiac interventions. JTB navigates the travel-logistics layer by controlling hospital appointment scheduling and accommodation linkages for international visitors.
Japan medical tourism encompasses cross-border travel for elective and essential clinical procedures, typically involving pre-arrival virtual assessment, in-country surgical or therapeutic intervention, and structured recovery protocols before repatriation. The practice relies on Japan's advanced imaging infrastructure, stringent infection control standards, and high surgeon-to-patient ratios in tertiary centers. Cosmetic surgery and orthopedic procedures occupy established revenue positions within the service type dimension, while robotic surgery and telemedicine represent the fastest-expanding technology categories as foreign patients seek pre-consultation validation and minimally invasive options. The delivery mode segment shows virtual consultation gaining structural importance for initial screening, though in-person consultation retains dominance for actual procedural execution.
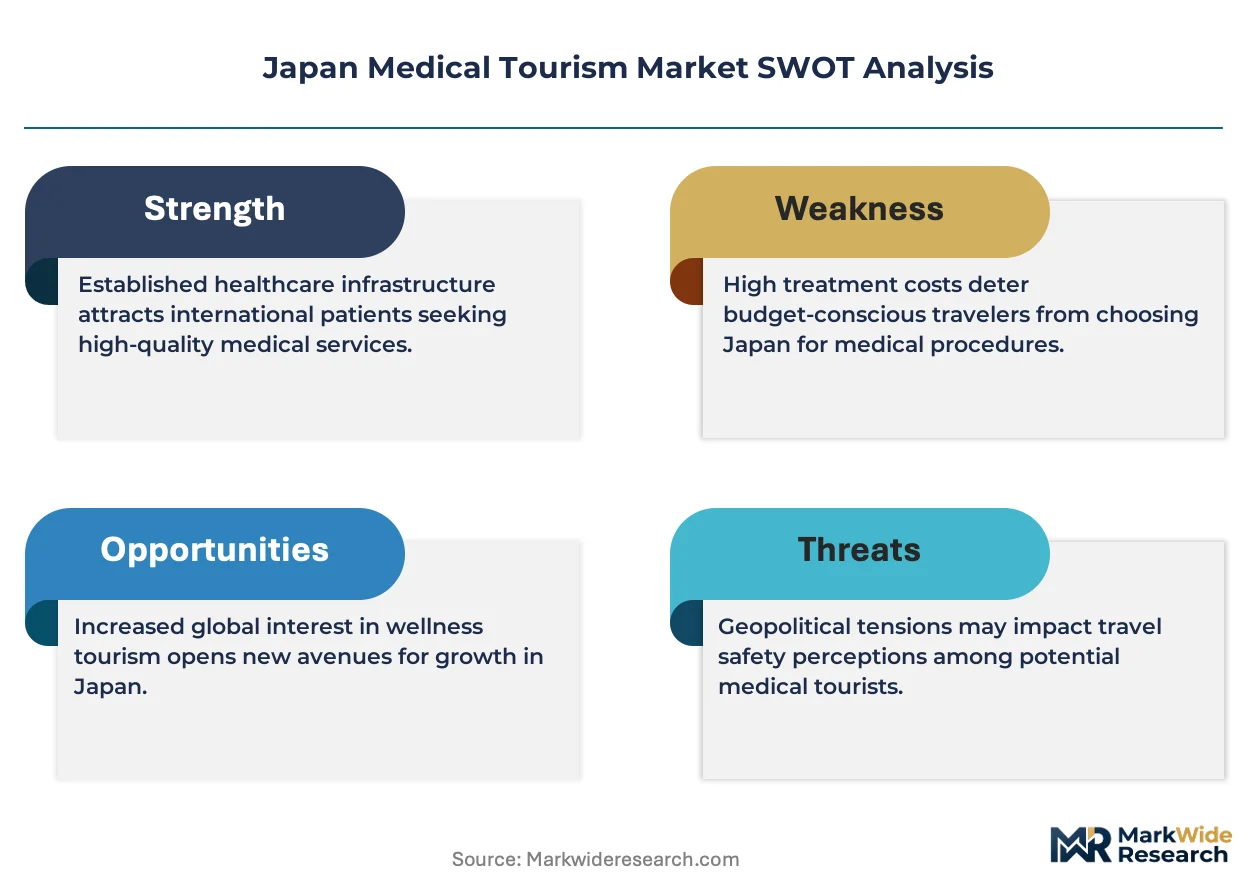
PMDA governs pharmaceutical and device approvals that determine which advanced therapies remain accessible to non-resident patients, while METI coordinates the national medical tourism promotion framework under broader economic revitalization mandates. Japan Medical Service Accreditation standards shape hospital eligibility for government-endorsed inbound patient programs, filtering market access to certified institutions. Stakeholders must monitor how METI's visa facilitation protocols evolve relative to competing medical tourism destinations in South Korea and Singapore.
Market Dynamics
Japan Medical Service Accreditation standards are filtering hospital eligibility for government-endorsed inbound patient programs, concentrating certified capacity in Tokyo's metropolitan cluster while METI coordinates visa facilitation protocols against competing destinations in South Korea and Singapore.
Growth Catalysts
- Regenerative therapy demand:Foreign patients seeking stem cell treatments and cell-based interventions are expanding the addressable patient base beyond traditional oncology flows.
- METI visa streamlining:The economic ministry's coordination of medical stay pathways reduces administrative friction for extended treatment durations requiring multiple entry authorizations.
- Robotic surgery infrastructure:Da Vinci and domestically developed surgical systems enable minimally invasive procedures that attract patients from markets with limited access to comparable technology.
Market Restraints
- Language barrier costs:Mandatory medical interpreter services and translated documentation add fixed overhead to each inbound case that domestic patients do not incur.
- PMDA approval timelines:Pharmaceutical and device regulatory pathways delay availability of novel therapies to non-resident patients relative to competing jurisdictions with accelerated access programs.
- Yen volatility:Exchange rate fluctuations between the Japanese currency and major source-market denominations create pricing unpredictability for package-bound services.
Strategic Opportunities
- Post-operative rehabilitation bundling:Extended recovery stays in onsen-adjacent facilities create ancillary revenue streams beyond the acute intervention phase.
- Telemedicine pre-screening:Virtual consultation platforms enable patient qualification and surgical planning before travel, reducing in-country duration requirements.
- Osaka-Kansai medical cluster:Underdeveloped relative to Tokyo, this region offers certified hospital capacity with lower operational costs and distinct cultural tourism adjacencies.
Industry Challenges
- Medical interpreter certification:The shortage of PMDA-recognized bilingual clinical coordinators limits scalable patient intake at tertiary centers.
- Electronic health record integration:Incompatible data standards between Japanese hospital systems and source-country providers complicate continuity-of-care handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Medical Tourism Market |
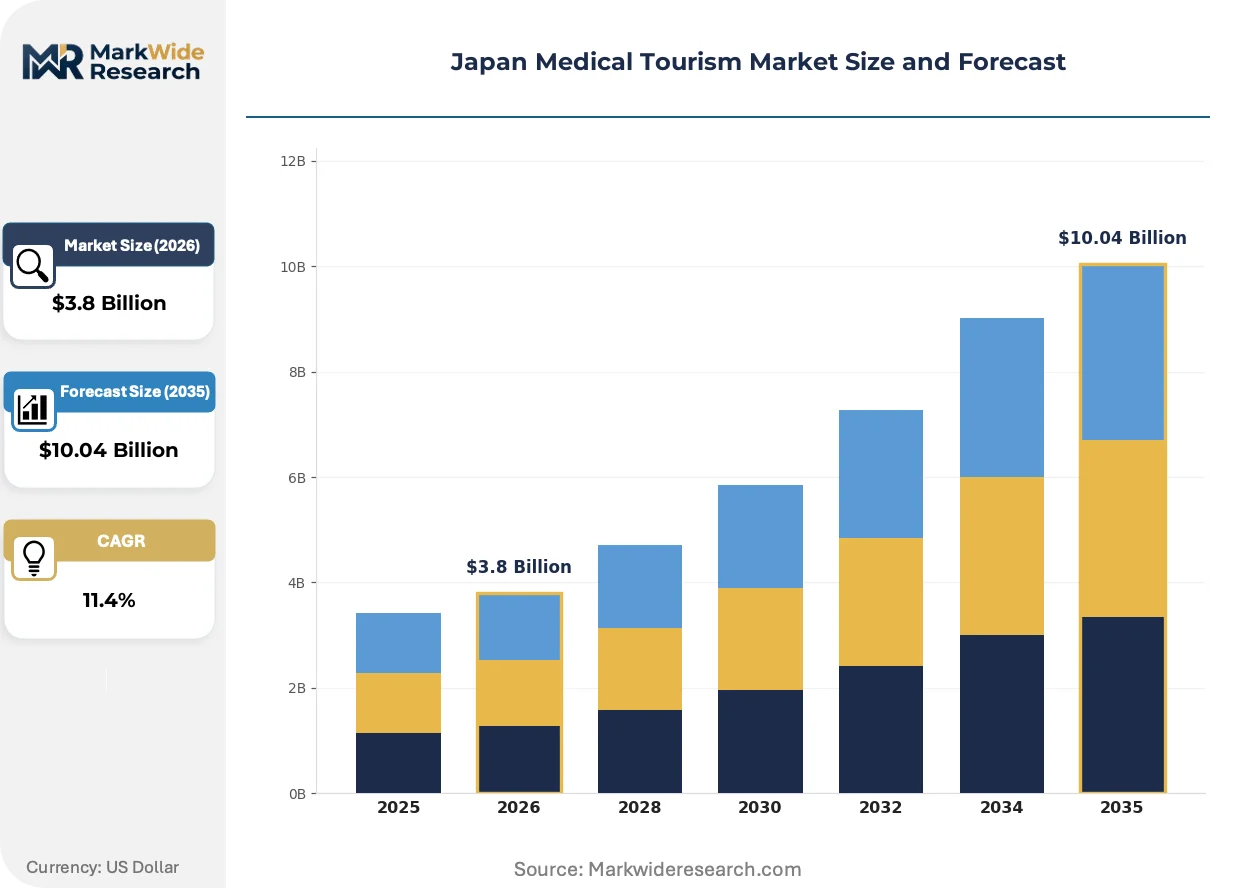
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cosmetic Surgery, Orthopedic Procedures, Dental Treatments, Cardiac Surgery End User: Patients, Insurance Companies, Medical Facilities, Hospitals Technology: Telemedicine, Robotic Surgery, Minimally Invasive Surgery, Anesthesia Techniques Delivery Mode: In-Person Consultation, Virtual Consultation, Follow-Up Care, Emergency Services |
| Companies Covered | St. Luke's International Hospital, Keio University Hospital, Tokyo Medical and Dental University Hospital, Juntendo University Hospital, Kyoto University Hospital, Tokyo Midtown Clinic, The University of Tokyo Hospital, Osaka University Hospital, JTB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Medical Tourism Market Trends and Innovations
Telemedicine infrastructure is restructuring how international patients engage Japanese healthcare providers, compressing pre-arrival assessment timelines and enabling remote follow-up protocols that extend the clinical relationship beyond physical presence.
AI-assisted diagnostic imaging is decentralizing specialist interpretation capacity across Japan's hospital network. Regional medical centers without dedicated radiology departments now access Tokyo-trained algorithmic analysis, enabling distributed care delivery that reduces patient concentration pressure on metropolitan facilities. Foreign patients gain access to university-hospital-grade diagnostics without mandatory centralization.
METI's medical tourism promotion framework is mandating standardized service packaging for accredited institutions. Hospitals must now disclose all-inclusive pricing for defined procedure bundles, eliminating the opacity that previously complicated patient decision-making. This regulatory pressure is forcing competitive transparency on pricing components previously buried in ancillary fees.
Patient acquisition channels are fragmenting away from traditional medical travel agencies. Direct hospital digital marketing and condition-specific online communities now drive initial inquiry volumes, with JTB and comparable intermediaries losing gatekeeper status. Southeast Asian source markets exhibit the fastest channel shift toward hospital-direct engagement through social media physician visibility.
Japan Medical Tourism Market Segmentation
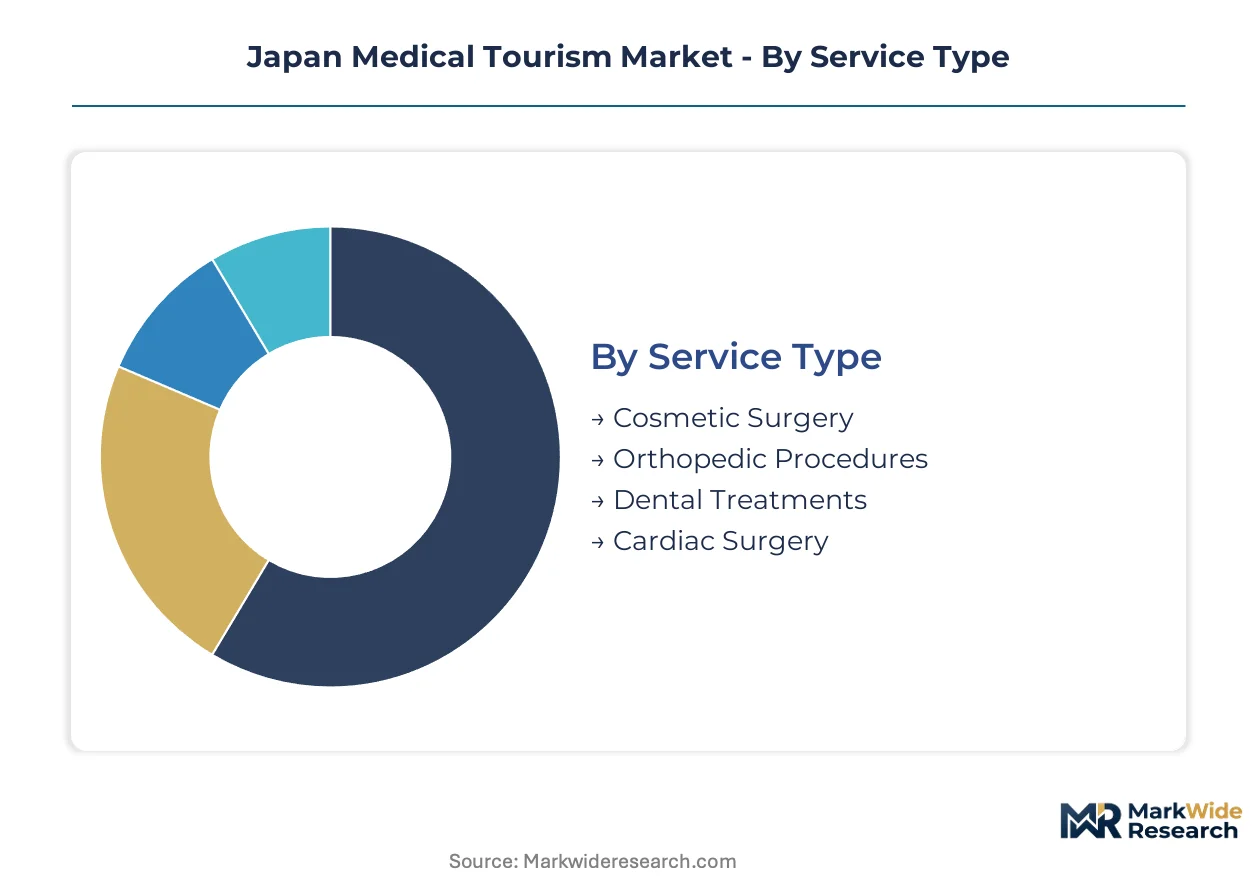
Segmentation in Japan's medical tourism market reveals how service bundling, technology adoption, and patient acquisition channels intersect to determine profitability. Each category exposes distinct operational constraints—from METI accreditation requirements to PMDA device approvals—that shape which segments hospitals can scale.
Service Type:
Customization intensity varies sharply across this category, with elective procedures allowing premium pricing flexibility while essential interventions face tighter standardization.
- Cosmetic Surgery:Procedures span facial contouring, breast augmentation, and body sculpting with recovery protocols tailored to international patient timelines. Demand concentrates among Southeast Asian and Chinese patients seeking surgeons trained in subtle, natural aesthetic techniques unavailable domestically, with METI-accredited clinics in Tokyo's Ginza and Omotesando districts commanding premium positioning.
- Orthopedic Procedures:Joint replacement, spinal fusion, and sports medicine interventions leverage Japan's high surgeon-to-patient ratios and advanced imaging infrastructure. Patients from Australia and the Middle East drive volume, attracted by shorter wait times relative to public health systems and the availability of ceramic-on-ceramic bearing surfaces not universally approved elsewhere.
- Dental Treatments:Implantology and cosmetic dentistry benefit from Japan's stringent infection control standards and digital workflow integration.
- Cardiac Surgery:Complex interventions including valve repair and coronary artery bypass grafting draw patients from markets with limited tertiary cardiac capacity.
Leading the category by volume: Orthopedic Procedures. Growing fastest: Cosmetic Surgery.
End User:
Cost tier stratification dominates this category, with direct-pay patients enabling margin expansion while institutional purchasers extract volume discounts.
- Patients:Individual medical travelers represent the core revenue base, typically self-funding elective procedures or seeking advanced therapies unavailable in home markets. Chinese and Southeast Asian patients dominate inbound flows, with growing segments from the Middle East and Central Asia seeking oncology and regenerative interventions at university hospitals.
- Insurance Companies:International health insurers and corporate benefit programs increasingly cover medically necessary procedures in Japan, particularly for expatriate populations and high-net-worth individuals with global coverage. These arrangements require pre-authorization protocols and fixed reimbursement schedules that compress margins but guarantee patient volume.
- Medical Facilities:Referral partnerships with overseas hospitals and clinics generate secondary patient flows for complex cases requiring Japanese surgical expertise.
- Hospitals:Institutional purchasers including foreign government health systems and hospital networks negotiate bundled service agreements for defined procedure categories.
Highest margin capture: Patients. Expanding most quickly: Insurance Companies.
Technology:
Application focus determines technology adoption patterns, with diagnostic and surgical platforms scaling faster than supportive care systems.
- Telemedicine:Virtual consultation platforms enable pre-arrival assessment, surgical planning, and remote follow-up that extends clinical relationships beyond physical presence. Southeast Asian source markets exhibit the fastest adoption, with direct hospital digital marketing now surpassing traditional medical travel agencies for initial patient acquisition.
- Robotic Surgery:Da Vinci systems and domestically developed platforms enable minimally invasive procedures with reduced recovery timelines that attract patients from markets with limited access to comparable technology. University hospitals in Tokyo anchor this segment, with AI-assisted surgical planning now integrating pre-operative imaging analysis.
- Minimally Invasive Surgery:Laparoscopic and endoscopic techniques reduce in-country recovery duration, lowering total package costs for price-sensitive segments.
- Anesthesia Techniques:Regional anesthesia and enhanced recovery after surgery protocols support same-day discharge for selected procedures.
Widest deployment: Telemedicine. Steepest expansion trajectory: Robotic Surgery.
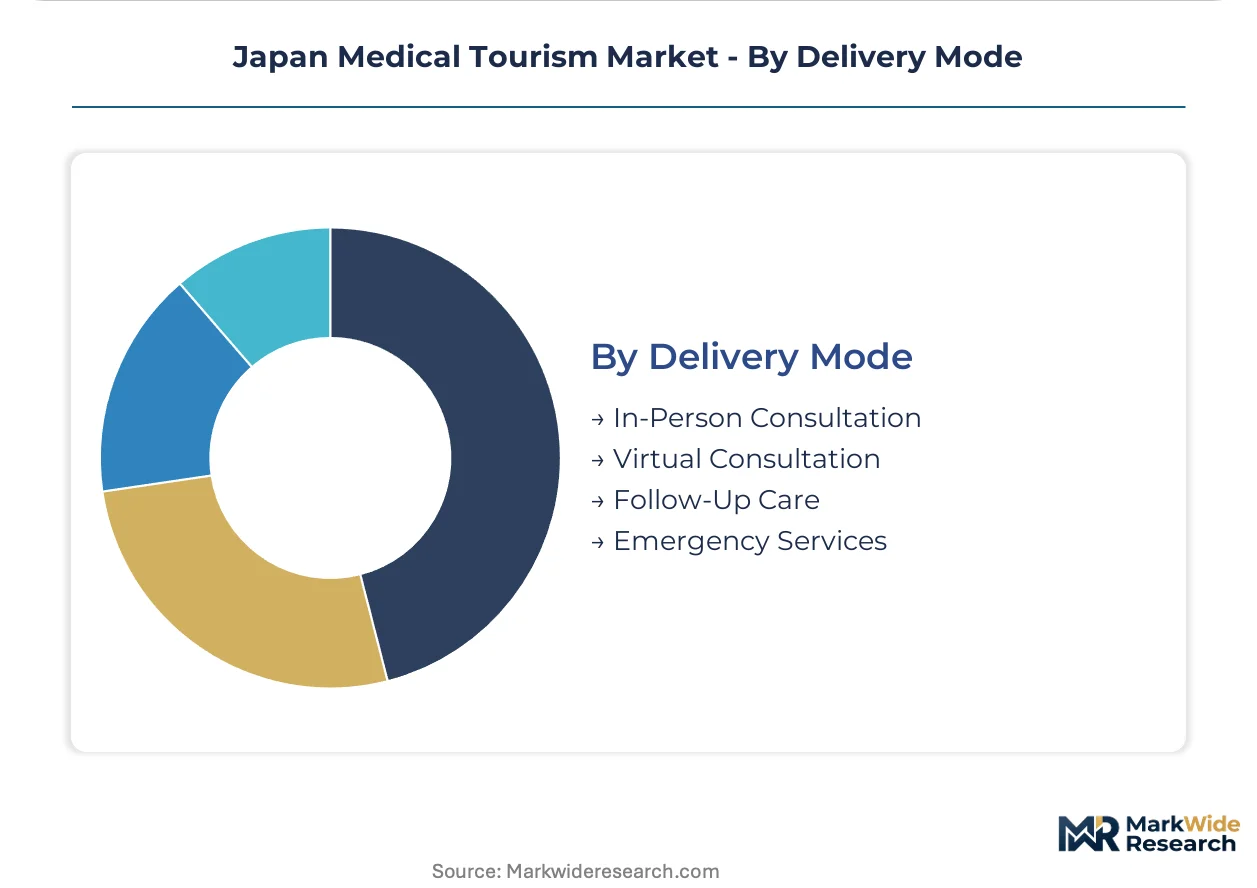
Delivery Mode:
Customer type fragmentation shapes channel strategy, with individual patients demanding seamless digital experiences while institutional purchasers prioritize care coordination reliability.
- In-Person Consultation:Physical examination and procedural execution remain mandatory for surgical interventions, with METI-accredited hospitals required to maintain multilingual care coordination and medical interpreter services. Tokyo's metropolitan cluster concentrates certified capacity, though Osaka-Kansai offers lower operational costs for price-competitive positioning.
- Virtual Consultation:Remote screening and pre-qualification compress pre-arrival timelines, reducing in-country duration requirements and enabling patient self-selection before travel investment. AI-assisted diagnostic imaging now decentralizes specialist interpretation capacity across Japan's hospital network.
- Follow-Up Care:Structured recovery protocols including onsen-adjacent rehabilitation facilities create ancillary revenue streams beyond acute intervention.
- Emergency Services:Unscheduled acute care for complications or trauma represents a contingency layer rather than planned medical tourism flow.
Dominant channel by volume: In-Person Consultation. Gaining share fastest: Virtual Consultation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's medical tourism production concentrates in metropolitan hospital clusters, while consumption originates from Southeast Asia, China, and the Middle East. Tokyo's university hospitals generate the majority of inbound clinical capacity, though regional centers are expanding certified services.
Kanto/Tokyo
Chinese and Southeast Asian patients seeking oncology and regenerative therapies drive demand into this region. METI coordinates visa facilitation protocols specifically for accredited institutions within this cluster. St. Luke's International Hospital and Keio University Hospital anchor specialized care ecosystems in central Tokyo, with multilingual care coordination services expanding patient intake capacity.
Kansai/Osaka
Lower operational costs relative to Tokyo attract price-sensitive segments from Australia and Central Asia. The Japan Medical Service Accreditation system filters hospital eligibility for government-endorsed programs, with several Osaka facilities recently achieving certification. Osaka University Hospital sustains competitive positioning through complex cardiac intervention specialization, while surrounding onsen-adjacent facilities enable post-operative rehabilitation bundling.
Chubu/Nagoya
Robotic surgery infrastructure attracts patients from markets with limited access to Da Vinci systems and domestically developed platforms. PMDA governs device approvals that determine which advanced therapies remain accessible to non-resident patients at regional centers. Nagoya's medical cluster is developing telemedicine pre-screening capabilities to compress pre-arrival assessment timelines for international visitors.
Kyushu
Proximity to Southeast Asian source markets reduces travel friction for patients seeking dental treatments and cosmetic procedures. METI's medical tourism promotion framework mandates standardized service packaging that Kyushu hospitals are implementing to compete with Tokyo-certified institutions. Fukuoka's metropolitan area is developing distinct cultural tourism adjacencies to differentiate its medical offering.
Hokkaido
Seasonal wellness tourism intersects with medical travel demand from Chinese and Russian visitors seeking thermal rehabilitation services. The region's infection control standards and digital workflow integration support dental implantology and cosmetic dentistry flows. Sapporo's medical facilities are investing in AI-assisted diagnostic imaging to decentralize specialist interpretation capacity without mandatory patient referral to Tokyo.
Japan Medical Tourism Market Competitive Landscape
Top-tier vendors anchor university hospital networks, while mid-tier regional medical centers compete on cost-adjusted service bundling. The market structure reflects concentrated certification capacity under METI accreditation standards, with Tokyo's metropolitan cluster holding disproportionate share. Strategic archetypes include: international patient coordinators with embedded travel-logistics control; university-affiliated tertiary centers with deep specialization moats; and emerging regional clusters leveraging cost differentials. Dominant competitive moves encompass post-operative rehabilitation service extension and telemedicine infrastructure deployment for pre-arrival patient qualification.
Among university hospital anchors, St. Luke's International Hospital, Keio University Hospital, and JTB occupy distinct positioning within the competitive architecture. St. Luke's exemplifies the multilingual care coordination archetype, Keio represents deep specialization in complex interventions, and JTB sits within the travel-logistics integration tier controlling hospital appointment scheduling and accommodation linkages for international visitors.
| Leading Market Players |
|---|
| St. Luke's International Hospital |
| Keio University Hospital |
| Tokyo Medical and Dental University Hospital |
| Juntendo University Hospital |
| Kyoto University Hospital |
| Tokyo Midtown Clinic |
| The University of Tokyo Hospital |
| Osaka University Hospital |
| JTB |
| Others |
Pricing and Supply Chain Analysis
Telemedicine infrastructure deployment across Japan's hospital network simultaneously compresses patient acquisition costs and concentrates certified capacity in METI-accredited institutions, reshaping how medical tourism packages are structured and priced relative to regional competitors.
Pricing Analysis
Margin tightening in standard-tier service bundles reflects METI's mandatory all-inclusive pricing disclosure rules that eliminated opacity in ancillary fee structures. Pricing stratifies across premium, standard, and economy tiers based on METI accreditation status and interpreter service bundling. Cost-down pressure accelerates in economy segments as Osaka-Kansai regional centers compete on operational cost differentials against Tokyo's metropolitan cluster. Insurance company purchasers exhibit highest price sensitivity due to fixed reimbursement schedules, while direct-pay patients enable premium-tier margin expansion.
Supply Chain Analysis
Japan's domestic-content mandates for medical interpreter certification and PMDA-accredited device sourcing reshape procurement patterns for inbound patient services. Supply draws from domestic university hospital networks, certified regional medical centers, and onsen-adjacent rehabilitation facilities. Raw material dependencies center on pharmaceutical imports governed by PMDA timelines, Da Vinci surgical systems, and multilingual care coordination labor. Single-source vulnerability concentrates in certified interpreter pools recognized by Japan Medical Service Accreditation standards. Distribution runs through hospital-direct digital channels, JTB-coordinated travel logistics, and insurance company pre-authorization networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's medical tourism market is consolidating around METI-accredited institutions as interpreter certification bottlenecks and standardized pricing disclosure eliminate subscale competitors lacking coordination infrastructure.
For Market Incumbents: Cement multilingual care coordination capabilities through embedded interpreter certification programs that exceed Japan Medical Service Accreditation minimums. Deepen backward integration into telemedicine pre-screening platforms to capture patient acquisition channels fragmenting away from traditional medical travel agencies. Defend against emerging regional clusters in Osaka-Kansai by extending post-operative rehabilitation service bundling into onsen-adjacent facilities that create ancillary revenue moats. For New Entrants and Emerging Players: Capture white-space opportunity in Osaka-Kansai's underdeveloped certified capacity relative to Tokyo's saturated metropolitan cluster. Target price-sensitive Australian and Central Asian patient segments seeking orthopedic procedures with lower operational cost structures. Penetrate through direct digital marketing bypassing JTB's diminishing gatekeeper status, leveraging social media physician visibility in Southeast Asian source markets. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of METI-accredited regional medical centers with telemedicine infrastructure already deployed. Long-term viability across the analysis window favors institutions with interpreter certification pipelines and AI-assisted diagnostic imaging capabilities. Watch PMDA approval timeline acceleration for stem cell therapies as the signal indicating expanded addressable patient base beyond traditional oncology flows.| Strategic Initiative | Industry Significance |
|---|---|
| Interpreter Certification Pipeline Investment | Builds scalable patient intake capacity at tertiary centers beyond METI minimum requirements. |
| Telemedicine Pre-Screening Platform Deployment | Compresses pre-arrival timelines and reduces in-country duration for price-competitive positioning. |
| Onsen-Adjacent Rehabilitation Facility Partnership | Creates ancillary revenue streams extending clinical relationships beyond acute intervention phases. |
| AI-Assisted Diagnostic Imaging Integration | Decentralizes specialist interpretation capacity without mandatory patient referral to Tokyo clusters. |
| Direct Digital Patient Acquisition Channel | Captures Southeast Asian inquiry volumes shifting away from traditional medical travel agencies. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs combining with primary interviews across hospital international patient coordinators, METI policy officials, PMDA regulatory affairs specialists, and medical travel logistics providers. Bottom-up procedure volume estimates triangulated against top-down healthcare expenditure flows from Japan's Ministry of Health, Labour and Welfare disclosures and METI medical tourism promotion framework documentation.
Data-stream reconciliation across service type, technology adoption, delivery mode, and geographic source market dimensions enabled segmentation-level modeling. CAGRs were derived from patient flow trajectories, accreditation expansion timelines, and visa facilitation protocol evolution. Forecast inputs incorporated PMDA device approval pipelines, interpreter certification program scaling, and telemedicine platform penetration rates across Southeast Asian source markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to yen volatility, PMDA regulatory pathway acceleration, and competitive response from South Korean and Singaporean medical tourism destinations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
Europe Dental Tourism Market
Medical Tourism
UK Medical Tourism Market
Medical Tourism
GCC Countries Medical Tourism Market
Medical Tourism
China Medical Tourism Market
Medical Tourism
Turkey Medical Tourism Market
Medical Tourism
North America Health Tourism Market
Medical Tourism
India Medical Tourism Market
Medical Tourism
Fertility Tourism Market
Medical Tourism
Europe Medical Tourism Market
Medical Tourism
North America Outbound Medical Tourism Services Market
Medical Tourism
Italy Medical Tourism Market
Medical Tourism
Asia-Pacific Medical Tourism Market
Medical Tourism
France Medical Tourism Market
Medical Tourism
Barbados Healthcare and Medical Tourism Market
Medical Tourism
Thailand Medical Tourism Market
Medical Tourism
Medical Tourism Market