
 Italy Medical Tourism Market | 2026-2036
Italy Medical Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Medical Tourism Market Foresight
Specialist nursing pools and multilingual patient coordinators is reorganizing how Italian hospitals attract foreign patients. Ospedale San Raffaele leverages its Milan location and research pedigree to dominate high-complexity cardiac and neurological procedures. Istituto Clinico Humanitas sustains competitive positioning through robotic surgery capabilities and dedicated international patient units. Policlinico Universitario A. Gemelli anchors Vatican-adjacent medical tourism flows with its theological hospital heritage and broad subspecialty depth.
Italy medical tourism encompasses cross-border travel for elective and essential healthcare services delivered through accredited public and private facilities, typically involving pre-arrival telemedicine consultation, procedure execution, and post-operative rehabilitation stays of one to four weeks. Cosmetic surgery and dental care command the largest patient volumes among service types, while cardiac surgery and fertility treatment capture disproportionate margin pools due to complexity premiums and limited European supplier density. International patients represent the dominant end-user category, with health insurers and corporate sponsors emerging as faster-growing referral channels that reshape pricing and package structures.
Italy's Ministry of Health accreditation protocols and regional quality frameworks shape facility eligibility for international patient admission, while EU cross-border healthcare directives establish reimbursement pathways for insured travelers from member states. The national pharmaceutical regulator and regional health authorities coordinate on facility inspections and outcome reporting standards that determine market access. Stakeholders must monitor how evolving EU digital health credential standards and bilateral agreements with non-EU source markets reshape patient routing and competitive positioning.
Market Dynamics
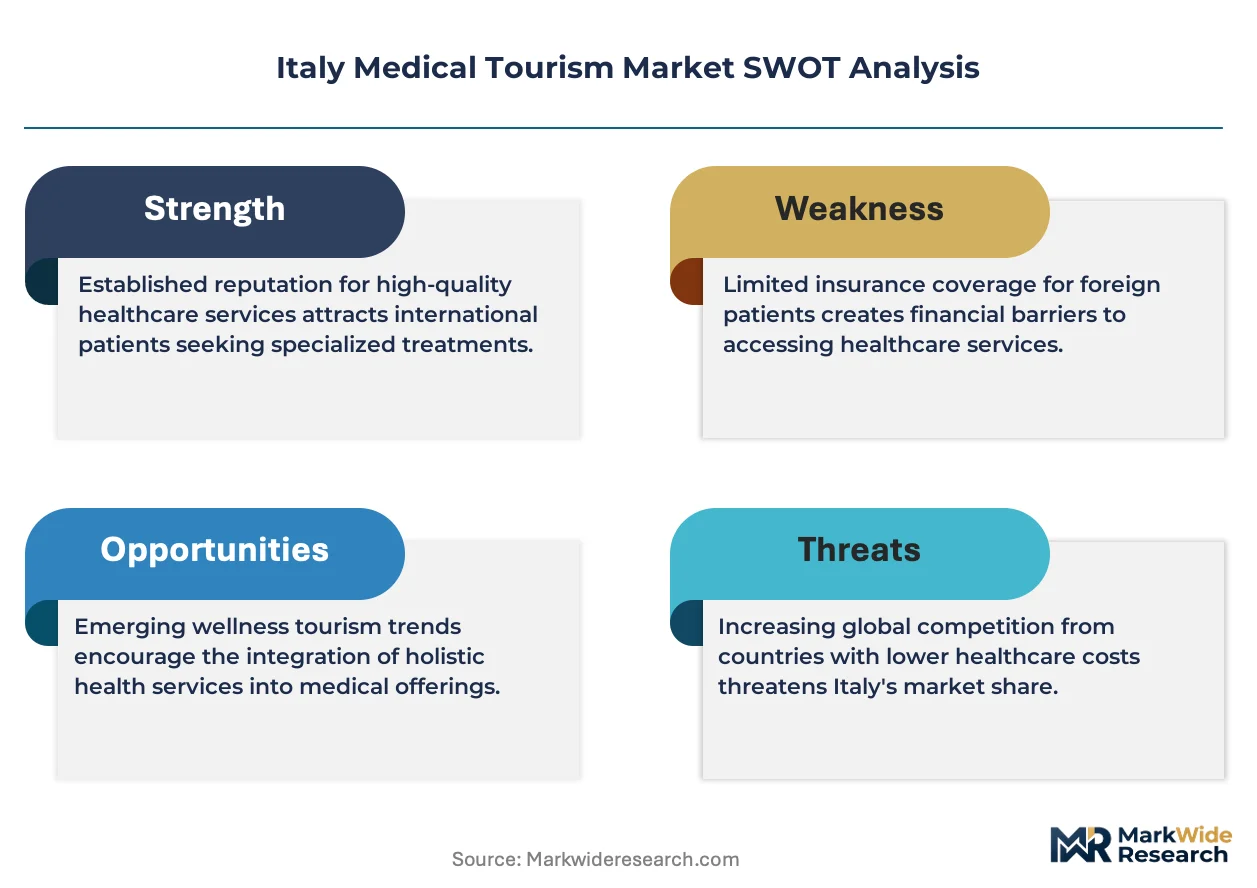
EU cross-border healthcare directives are rewiring patient routing into Italian facilities, compressing pre-authorization timelines and standardizing reimbursement flows that previously fragmented across member-state insurance schemes. This regulatory harmonization is concentrating demand around accredited hospital clusters in Lombardy and Emilia-Romagna.
Growth Catalysts
- EU Cross-Border Healthcare Directive:Streamlined reimbursement pathways for insured German, Swiss, and British patients eliminate prior cash-pay barriers and accelerate admission velocity.
- Robotic Surgery Adoption:Italian private hospital networks are deploying da Vinci systems for cardiac and urological procedures, attracting complexity-seeking international patients from price-sensitive Eastern European markets.
- Lombardy Hospital Cluster Density:Milan's concentration of research-grade facilities creates referral network effects that reduce patient acquisition costs below dispersed national competitors.
Market Restraints
- Regional Accreditation Fragmentation:Italy's 20 regional health authorities maintain divergent facility inspection protocols, creating compliance duplication costs for multi-site operators seeking national patient reach.
- Specialized Nursing Shortages:Cardiac surgery and fertility treatment units face constrained talent pools, extending procedure wait times beyond competitive thresholds against Spanish and Turkish alternatives.
- Non-EU Visa Processing Friction:Schengen medical visa timelines and documentation requirements deter Middle Eastern and North African patient segments with faster-access alternatives in Dubai or Bangkok.
Strategic Opportunities
- Telemedicine Pre-Consultation:Remote diagnostic imaging review and surgical planning via encrypted platforms reduces Italian stay duration, opening price-sensitive segments in Poland and Romania.
- Corporate Wellness Sponsorship:Multinational employers in Germany and Switzerland are contracting bundled executive health screening packages, bypassing traditional insurance channel intermediation.
- Digital Health Credential Harmonization:Emerging EU-wide electronic health record standards enable seamless continuity between home-country primary care and Italian specialist intervention.
Industry Challenges
- Multilingual Patient Coordination:Arabic, Russian, and Chinese language capabilities remain uneven across Italian hospital international desks, creating service gaps in high-growth source markets.
- Post-Operative Rehabilitation Integration:Shortage of accredited recovery facilities in proximity to surgical centers forces extended hospital stays, compressing bed turnover and margin structure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Medical Tourism Market |
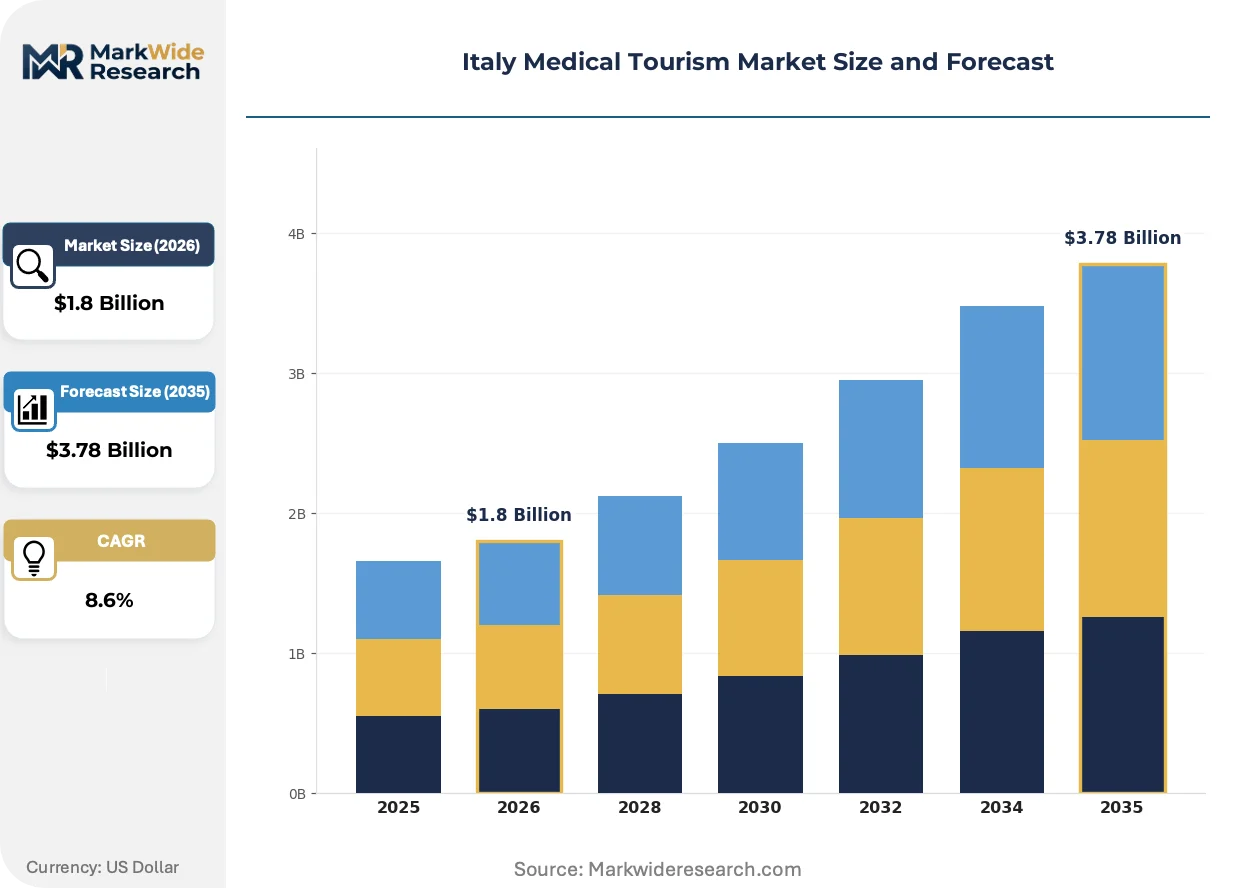
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cosmetic Surgery, Dental Care, Fertility Treatment, Cardiac Surgery End User: International Patients, Health Insurers, Corporates, Retirees Procedure Type: Orthopedic Surgery, Neurological Treatment, Rehabilitation, Bariatric Surgery Technology: Telemedicine, Robotic Surgery, Minimally Invasive Techniques, Traditional Medicine |
| Companies Covered | Ospedale San Raffaele - Gruppo San Donato, Azienda Ospedaliera di Padova, Policlinico Universitario A. Gemelli, Ospedale Policlinico San Matteo, Ospedale Borgo Trento, Grande Ospedale Metropolitano Niguarda, Istituto Clinico Humanitas, IRCCS Arcispedale Santa Maria Nuova, Policlinico Sant'Orsola-Malpighi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Medical Tourism Market Shifts & Advancements
Digital patient journey orchestration is compressing the traditional medical tourism funnel from inquiry to procedure, replacing fragmented broker-mediated booking with direct hospital-controlled platforms and real-time availability transparency.
Portable diagnostic imaging equipment is miniaturizing pre-arrival consultation workflows. Italian cardiac centers now deploy handheld ultrasound and ECG devices through partner clinics in Germany and Switzerland, capturing patient commitment before competitor facilities can intervene. This remote capability is collapsing the traditional multi-week evaluation window into days.
Italy's Ministry of Health is tightening accreditation protocols for international patient admission, mandating outcome reporting standards that align with EU Medical Device Regulation traceability requirements. Private hospital groups are responding by consolidating quality management systems across multi-site networks, treating compliance investment as competitive differentiation against lower-standard regional rivals.
Health insurer channel consolidation is reshaping referral economics. German and Swiss statutory insurers are contracting preferred provider networks with fixed procedure tariffs, displacing traditional fee-for-service relationships. Italian facilities are responding with volume-commitment pricing and dedicated international patient units that streamline administrative throughput.
Italy Medical Tourism Market Segmentation
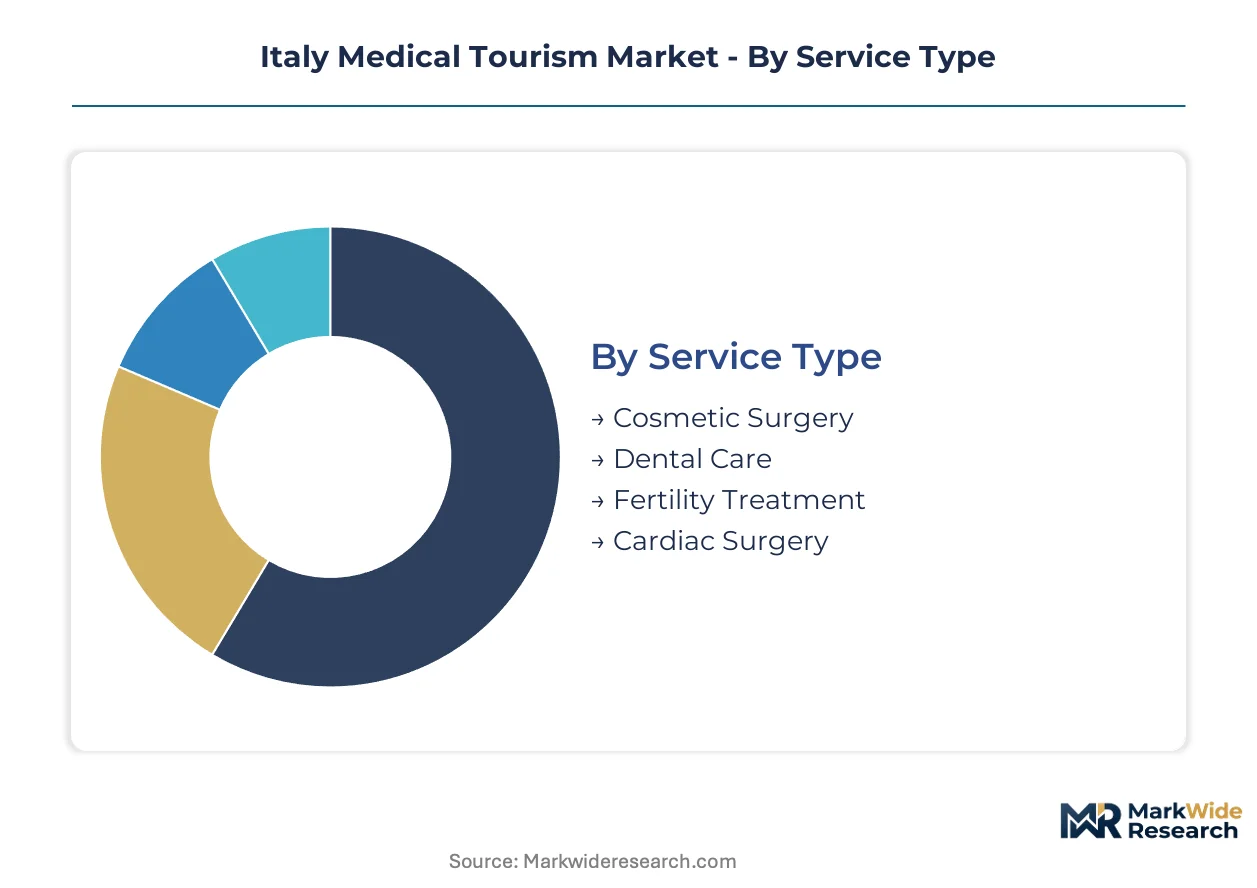
Italy's medical tourism market fragments across service lines, patient categories, and technological capabilities that determine margin capture and competitive positioning. Understanding where value concentrates within each dimension enables targeted investment in accreditation, capacity, and patient acquisition infrastructure.
Service Type:
Margin pools concentrate in complexity-premium procedures where Italian research hospitals command pricing power against regional competitors.
- Cosmetic Surgery:Elective aesthetic procedures including rhinoplasty, breast augmentation, and body contouring attract German and Swiss patients seeking Milan's fashion-adjacent medical aesthetics. Demand clusters in Lombardy facilities with dedicated international patient coordinators and hotel partnerships for extended recovery stays.
- Cardiac Surgery:High-complexity valve replacement and coronary bypass procedures leverage Italy's research-grade cardiac centers. Limited European supplier density for advanced interventions enables margin premiums, though specialized nursing shortages constrain volume expansion against Spanish alternatives.
- Dental Care:Implantology and cosmetic dentistry drive patient volumes from UK and German markets attracted by cost differentials against domestic private care. Regional accreditation fragmentation creates compliance overhead for multi-site dental chains seeking national reach.
- Fertility Treatment:IVF and assisted reproduction services capture disproportionate margins due to regulatory complexity and limited cross-border provider density. Vatican-proximate facilities in Rome anchor religiously-sensitive patient flows seeking theological alignment in care protocols.
Cardiac surgery holds installed capacity. Dental care is rotating up the share rankings.
End User:
Referral channel economics are shifting from cash-pay individuals toward institutional purchasers with volume-commitment leverage.
- International Patients:Self-funded individuals from Germany, Switzerland, and the United Kingdom constitute the foundational demand base. EU cross-border healthcare directives are streamlining reimbursement pathways, converting cash-pay segments into insured volumes with compressed pricing.
- Health Insurers:German and Swiss statutory insurers are consolidating preferred provider networks with fixed procedure tariffs. This channel is expanding most quickly as bilateral agreements displace traditional fee-for-service relationships and reshape hospital administrative infrastructure.
- Corporates:Multinational employers contract bundled executive health screening and intervention packages, bypassing traditional insurance intermediation. Milan-based hospital groups are deploying dedicated corporate liaison units to capture this faster-growing referral stream.
- Retirees:UK pensioners and northern European retirees seek cost-optimized elective procedures combined with extended rehabilitation stays in Italian wellness destinations. Seasonal demand patterns align with Mediterranean climate preferences, creating capacity utilization challenges during winter months.
International patients anchor volume. Health insurers are gaining share fastest.
Procedure Type:
Application-driven segmentation reveals where Italian facilities differentiate against Turkish and Spanish competitors through technology investment.
- Orthopedic Surgery:Joint replacement and sports medicine procedures leverage Italy's rehabilitation infrastructure and thermal spa traditions. Robotic-assisted techniques in Milan and Bologna facilities attract complexity-seeking patients from Eastern European markets.
- Neurological Treatment:Deep brain stimulation and epilepsy surgery concentrate in research-grade university hospitals with intraoperative monitoring capabilities. Limited European capacity for advanced interventions supports pricing power despite extended pre-authorization timelines.
- Rehabilitation:Post-operative and neurological recovery services integrate with Italy's established thermal medicine and physiotherapy traditions. Shortage of accredited recovery facilities near surgical centers forces extended hospital stays, compressing bed turnover economics.
- Bariatric Surgery:Metabolic and weight-loss procedures attract patients from markets with restricted domestic access. Minimally invasive techniques and comprehensive post-operative support programs differentiate Italian providers against lower-cost alternatives.
Orthopedic surgery commands capacity share. Neurological treatment is climbing the fastest.
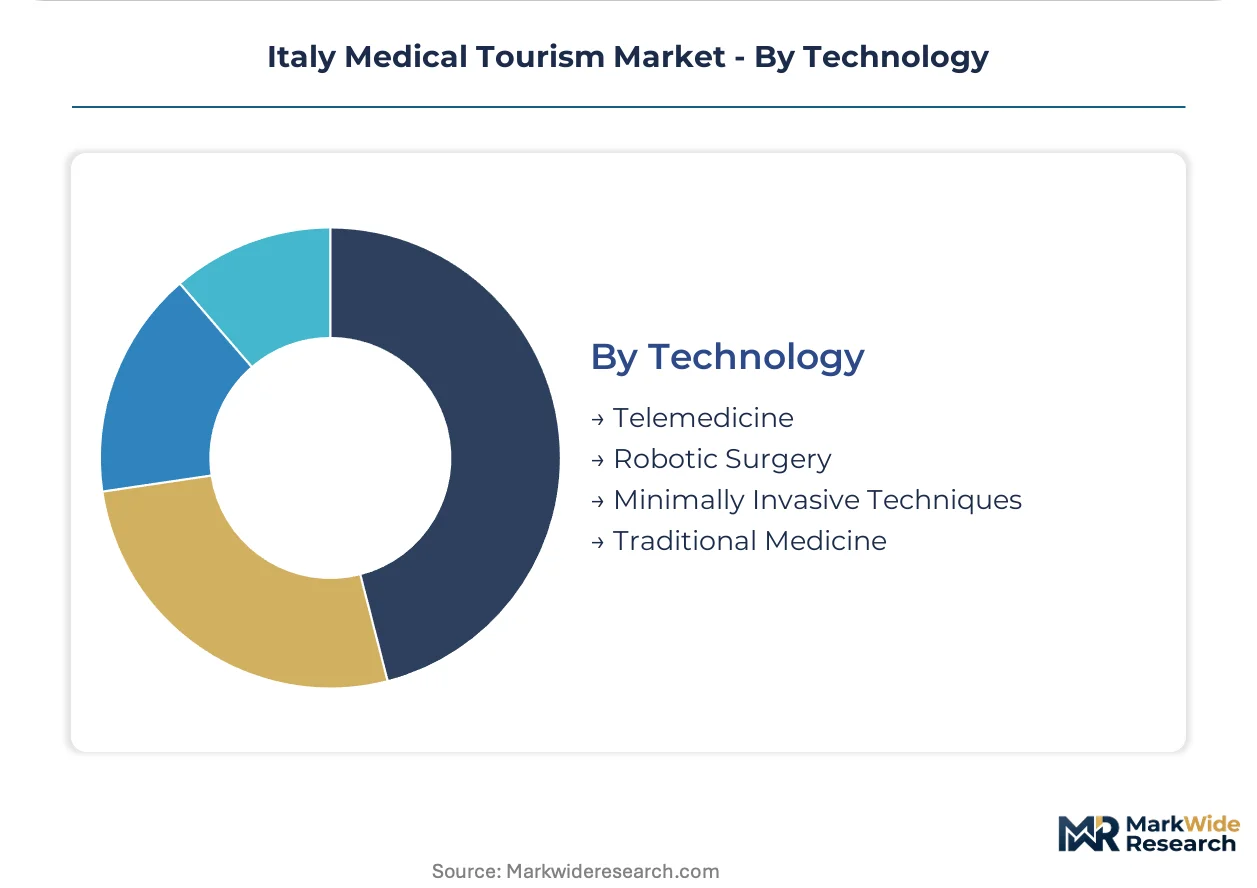
Technology:
Technology adoption curves determine which facilities capture patient flows from digitally-sophisticated source markets.
- Robotic Surgery:Da Vinci system deployment for cardiac, urological, and gynecological procedures anchors competitive positioning in complexity-premium segments. Istituto Clinico Humanitas and Ospedale San Raffaele leverage robotic capabilities to attract patients seeking precision outcomes unavailable in home markets.
- Telemedicine:Remote pre-consultation, diagnostic imaging review, and surgical planning compress traditional multi-week evaluation windows. Encrypted platform deployment enables direct hospital-patient relationships that displace traditional broker-mediated booking channels.
- Minimally Invasive Techniques:Laparoscopic and endoscopic approaches reduce recovery duration and attract cost-conscious patients comparing total episode costs against traditional open surgery alternatives. Regional training disparities create uneven capability distribution across Italy's hospital network.
- Traditional Medicine:Conventional surgical and medical approaches retain relevance in price-sensitive segments and procedures where technology premiums exceed perceived value. Thermal medicine and spa-integrated recovery protocols differentiate Italian offerings against technology-focused competitors.
Traditional medicine retains volume dominance. Telemedicine is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German patients seek cardiac complexity and cosmetic refinement in Italian facilities, while British travelers prioritize dental cost arbitrage and Swiss visitors demand executive health screening protocols that differ materially from Mediterranean wellness traditions.
Lombardy
Milan's concentration of research-grade hospitals attracts German and Swiss cardiac surgery patients seeking robotic-assisted procedures unavailable domestically. Italy's Ministry of Health accreditation protocols govern international patient admission standards across the region's private hospital networks. The Ospedale San Raffaele and Istituto Clinico Humanitas anchor a surgical cluster that generates referral network effects and compresses patient acquisition costs below dispersed national competitors.
Emilia-Romagna
Bologna's orthopedic and rehabilitation infrastructure draws Eastern European patients comparing robotic joint replacement costs against Turkish alternatives. Regional health authorities coordinate facility inspections with the national pharmaceutical regulator to maintain EU cross-border healthcare directive compliance. Specialized thermal medicine facilities in the Apennine foothills integrate post-operative recovery with traditional spa protocols, differentiating the region against technology-focused competitors.
Lazio
Rome's Vatican-proximate hospitals capture religiously-sensitive fertility treatment flows from Catholic European markets seeking theological alignment in care protocols. The city's university hospitals leverage intraoperative monitoring capabilities for complex neurological interventions that command pricing premiums. Policlinico Universitario A. Gemelli anchors this segment through its theological hospital heritage and broad subspecialty depth.
Veneto
Padua's historical medical research tradition supports high-complexity cardiac and transplant procedures attracting insured German patients through streamlined EU reimbursement pathways. The Azienda Ospedaliera di Padova maintains competitive positioning through dedicated international patient units and multilingual coordination capabilities. Regional quality frameworks align with national standards to determine market access for cross-border healthcare flows.
Piedmont
Turin's industrial heritage translates into advanced orthopedic and sports medicine capabilities that attract complexity-seeking patients from price-sensitive Eastern European markets. Local facilities deploy minimally invasive techniques and comprehensive post-operative support programs to differentiate against lower-cost Spanish alternatives. The region's hospital clusters face compliance duplication costs from divergent regional inspection protocols when seeking national patient reach.
Italy Medical Tourism Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Italy's medical tourism market, with research-grade university hospitals and large private groups controlling complexity-premium segments while regional facilities compete on price-sensitive dental and cosmetic volumes. Three archetypes dominate: Milan-centered robotic surgery hubs, Vatican-adjacent theological heritage institutions, and university-affiliated research hospitals with intraoperative monitoring capabilities. Competitive moves concentrate on telemedicine platform deployment for pre-arrival patient capture and dedicated international patient unit expansion to streamline administrative throughput for insurer-contracted volumes.
Within the research hospital tier, Ospedale San Raffaele exemplifies the Milan-centered complexity hub archetype, while Policlinico Universitario A. Gemelli occupies a distinctive position leveraging Vatican proximity for religiously-sensitive patient flows. Istituto Clinico Humanitas represents the private network model with robotic surgery capabilities and dedicated international patient infrastructure. These three institutions anchor the competitive structure through differentiated specialization rather than scale-driven consolidation.
| Leading Market Players |
|---|
| Ospedale San Raffaele - Gruppo San Donato |
| Azienda Ospedaliera di Padova |
| Policlinico Universitario A. Gemelli |
| Ospedale Policlinico San Matteo |
| Ospedale Borgo Trento |
| Grande Ospedale Metropolitano Niguarda |
| Istituto Clinico Humanitas |
| IRCCS Arcispedale Santa Maria Nuova |
| Policlinico Sant'Orsola-Malpighi |
| Others |
Supply & Pricing Matrix
Italy's Ministry of Health accreditation protocols gate both facility qualification for international patient admission and the price premiums that research-grade hospitals command against regional competitors. This dual-gating mechanism concentrates margin capture among accredited Lombardy and Emilia-Romagna clusters while fragmenting pricing power across the twenty regional health authorities.
Pricing Analysis
Long-term preferred provider contracts with German and Swiss statutory insurers are displacing traditional fee-for-service relationships and compressing cash-pay premiums. Pricing stratifies across research-grade, accredited private, and regional hospital tiers, with complexity premiums for cardiac and neurological procedures eroding as bilateral agreements standardize reimbursement tariffs. Cost compression in cosmetic and dental segments intensifies as Turkish and Spanish alternatives expand capacity, while insured German patients demonstrate lowest price sensitivity due to streamlined EU directive reimbursement pathways.
Supply Chain Analysis
Germany and Switzerland anchor diagnostic imaging equipment and robotic surgical system supply, while Italy's domestic production concentrates on rehabilitation infrastructure and thermal medicine assets. Italian cardiac centers draw from German-manufactured da Vinci systems and Swiss-developed patient monitoring platforms, with supply chain vulnerability centering on single-source robotic component dependencies and extended procurement timelines for specialized surgical instrumentation. Distribution runs through hospital-direct procurement channels and consolidated medical device leasing networks serving multi-site private hospital groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's medical tourism market is approaching a platform-economics inflection as telemedicine pre-consultation and encrypted patient journey orchestration displace fragmented broker-mediated booking, with EU digital health credential harmonization enabling seamless interoperability between home-country primary care and Italian specialist intervention.
For Market Incumbents: Secure accreditation pre-emption in emerging EU digital health credential standards to maintain competitive gating against lower-cost Eastern European entrants. Consolidate multilingual patient coordination capabilities in Arabic and Russian to defend against Dubai and Bangkok alternatives capturing Middle Eastern flows. Backward integration into accredited rehabilitation facilities near surgical centers addresses bed turnover compression and margin erosion from extended hospital stays. For New Entrants and Emerging Players: Differentiate on telemedicine-enabled pre-arrival diagnostic workflows that collapse traditional multi-week evaluation windows into days, targeting price-sensitive Polish and Romanian segments with compressed Italian stay durations. White-space opportunity concentrates in corporate wellness sponsorship channels where multinational employers seek bundled executive health screening packages bypassing traditional insurance intermediation. Go-to-market leverage rests on direct hospital-controlled platform deployment with real-time availability transparency displacing fragmented broker channels. For Investors and Strategic Acquirers: Carve-out targets emerge from regional hospital networks with latent international patient infrastructure requiring only accreditation investment and dedicated patient unit activation. Long-term viability hinges on positioning for EU cross-border healthcare directive expansion and bilateral agreement proliferation with non-EU source markets. Monitor German statutory insurer preferred provider network consolidation velocity as the primary inflection signal for pricing power shifts toward institutional purchasers.| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Deployment | Encrypted pre-consultation platforms enable direct patient capture before broker-mediated competitor intervention. |
| EU Digital Health Credential Harmonization | Seamless EHR interoperability between German primary care and Italian specialists accelerates insured patient routing. |
| Preferred Provider Network Contracting | Volume-commitment pricing with Swiss statutory insurers displaces fee-for-service administrative overhead. |
| Accredited Rehabilitation Facility Expansion | Proximity recovery infrastructure addresses bed turnover compression and extends margin capture beyond surgical episodes. |
| Multilingual Patient Unit Scaling | Arabic and Russian coordination capabilities close service gaps against Dubai and Bangkok alternatives in high-growth source markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU cross-border healthcare directive implementation records, Italian Ministry of Health accreditation databases, and German statutory insurer preferred provider network disclosures. Primary interviews engaged hospital international patient unit directors, biomedical equipment procurement managers, GPO contracts specialists, and regulatory affairs leads at regional health authorities. Secondary validation drew from hospital procurement databases, EU Medical Device Regulation traceability filings, and CMS-equivalent reimbursement data. Bottom-up facility capacity modeling triangulates against top-down patient flow estimates from source market insurance scheme reports.
Segmentation dimensions modeled span service type, end-user referral channel, procedure complexity tier, and technology adoption curve across the projection horizon. CAGRs derive from patient volume trajectory analysis by source geography and reimbursement pathway evolution. Industry-specific forecast inputs incorporate robotic surgical system deployment rates and telemedicine platform penetration curves in German and Swiss source markets.
Decision-makers should treat outputs as directional under sustained EU directive harmonization and stable bilateral agreement frameworks; material deviation in Schengen visa processing efficiency or regional accreditation consolidation would warrant model refresh. Recalibration cycles align with material shifts in German statutory insurer contracting patterns and EU digital health credential standard adoption velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
South Korea Medical Tourism Market
Medical Tourism
China Medical Tourism Market
Medical Tourism
Barbados Healthcare and Medical Tourism Market
Medical Tourism
Europe Dental Tourism Market
Medical Tourism
Europe Medical Tourism Market
Medical Tourism
Switzerland Healthcare and Medical Tourism Market
Medical Tourism
GCC Countries Medical Tourism Market
Medical Tourism
Fertility Tourism Market
Medical Tourism
North America Health Tourism Market
Medical Tourism
Dental Tourism Market
Medical Tourism
Spain Medical Tourism Market
Medical Tourism
Asia-Pacific Medical Tourism Market
Medical Tourism
Japan Medical Tourism Market
Medical Tourism
UK Medical Tourism Market
Medical Tourism
Thailand Medical Tourism Market
Medical Tourism
Outbound Medical Tourism Services Market