
 Switzerland Healthcare and Medical Tourism Market | 2026-2036
Switzerland Healthcare and Medical Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Healthcare and Medical Tourism Market Intelligence
Aftermarket service revenue from post-treatment rehabilitation and long-term wellness monitoring is fragmenting across competing delivery models. Hirslanden Private Hospital Group leverages its national clinic network to sustain premium pricing for extended recovery programs. Clinique La Prairie anchors the longevity medicine segment through proprietary diagnostic protocols. University Hospital Zurich competes on academic credibility in complex orthopedic reconstruction cases.
Switzerland Healthcare and Medical Tourism encompasses cross-border patient flows seeking elective procedures, preventive diagnostics, and recuperative services within a federally regulated health system characterized by cantonal licensing and mandatory insurance frameworks. The sector operates through highly orchestrated care pathways where telemedicine pre-consultation, robotic surgical intervention, and electronic health record continuity function as integrated technical standards. Cosmetic surgery and orthopedic treatments command the deepest margin pools due to discretionary pricing flexibility and shorter bed occupancy cycles. Fertility treatments represent the fastest-growing service category as cross-border reproductive medicine restrictions tighten across neighboring EU jurisdictions under EMA-aligned standards.
Swissmedic enforces device and pharmaceutical standards that exceed baseline EU MDR requirements, while cantonal health departments regulate facility accreditation through stricter staffing ratios than those mandated by the FOPH. These layered compliance frameworks elevate operational costs but simultaneously restrict market access for lower-tier competitors. Stakeholders must monitor how the EU AI Act diagnostic imaging provisions interact with Switzerland's bilateral medical technology agreements to anticipate reimbursement and liability shifts.
Market Dynamics
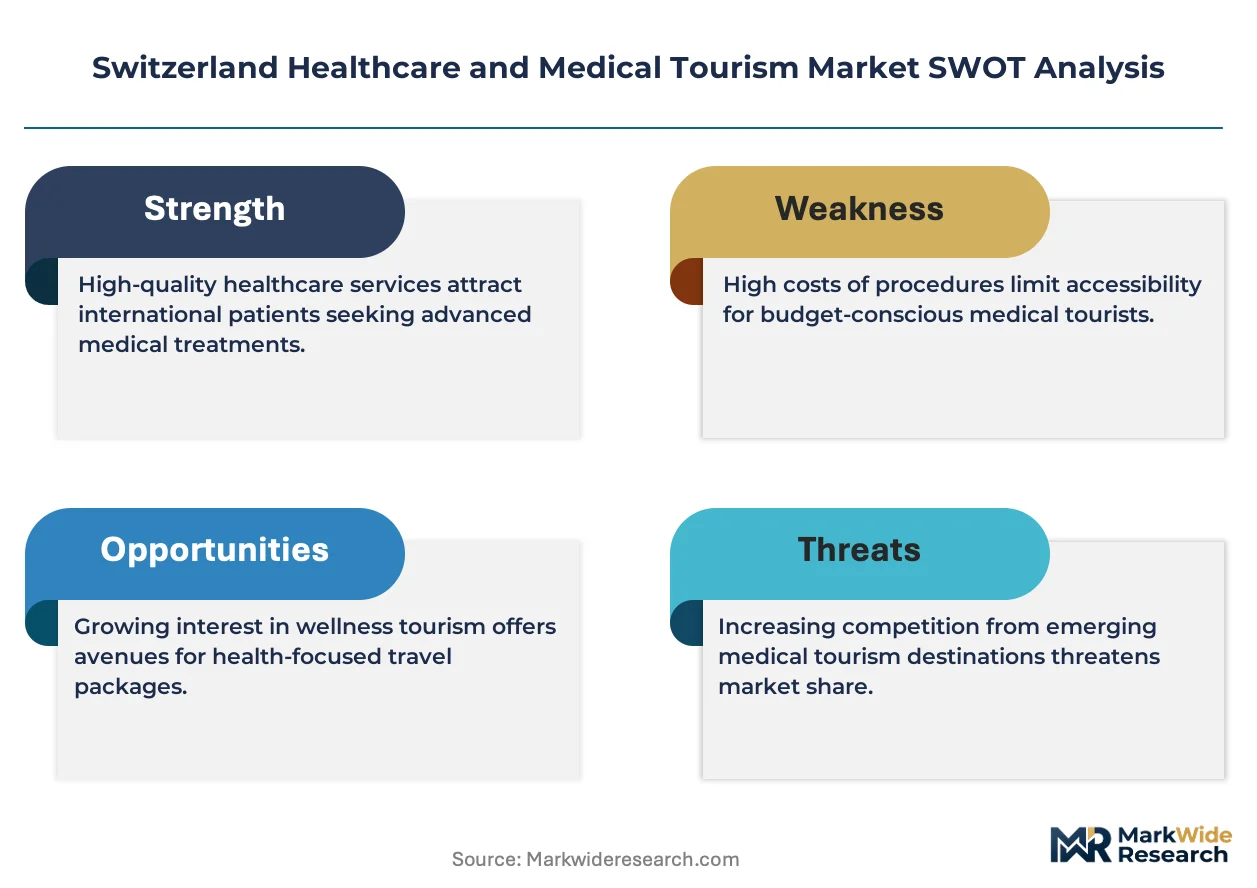
Federally mandated health insurance coverage creates guaranteed payment flows that stabilize facility revenue, while cantonal licensing restrictions compress supply growth and sustain premium pricing power for accredited providers.
Growth Catalysts
- EMA-aligned reproductive medicine restrictions:Tightening EU fertility regulations divert patient flows to Swiss clinics operating under Swissmedic oversight with clearer legal frameworks for cross-border reproductive services.
- Robotic surgical intervention:Adoption of da Vinci and ROSA robotic platforms shortens recovery windows and attracts high-net-worth patients seeking precision orthopedic and cardiac procedures.
- Lake Geneva corridor concentration:University hospitals in Geneva and Lausanne anchor specialized treatment clusters that generate referral networks across Middle Eastern and Asian source markets.
Market Restraints
- Cantonal staffing ratio mandates:FOPH baseline requirements plus stricter cantonal overlays elevate nurse-to-patient ratios above EU averages, compressing bed utilization rates and inflating per-procedure labor costs.
- Swissmedic device certification timelines:Exceeding EU MDR baseline requirements adds 8-14 months to medical technology market entry, delaying revenue recognition for imported diagnostic and surgical equipment.
- Swiss franc appreciation cycles:Currency strength against euro and dollar denominations erodes price competitiveness for elective procedures priced in CHF for Middle Eastern and US patient segments.
Strategic Opportunities
- Ticino and Italian-speaking cantons:Underdeveloped medical tourism infrastructure relative to German and French regions offers first-mover positioning for Mediterranean-market-focused wellness and longevity programs.
- Telemedicine pre-consultation integration:Remote diagnostic triage and virtual specialist consults expand addressable patient pools beyond traditional geographic catchment areas for university hospital networks.
- EU AI Act diagnostic imaging provisions:Bilateral medical technology agreements between Bern and Brussels create pathway harmonization opportunities for AI-enabled radiology and pathology tools seeking dual-market clearance.
Industry Challenges
- Electronic health record interoperability:Cantonal data sovereignty laws fragment patient information systems, complicating continuity of care for cross-border patients treated across multiple Swiss facilities.
- Specialized nursing recruitment:Robotic surgery and longevity medicine protocols require certified technicians with scarce training credentials, extending hiring cycles for expanding clinic networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Healthcare and Medical Tourism Market |
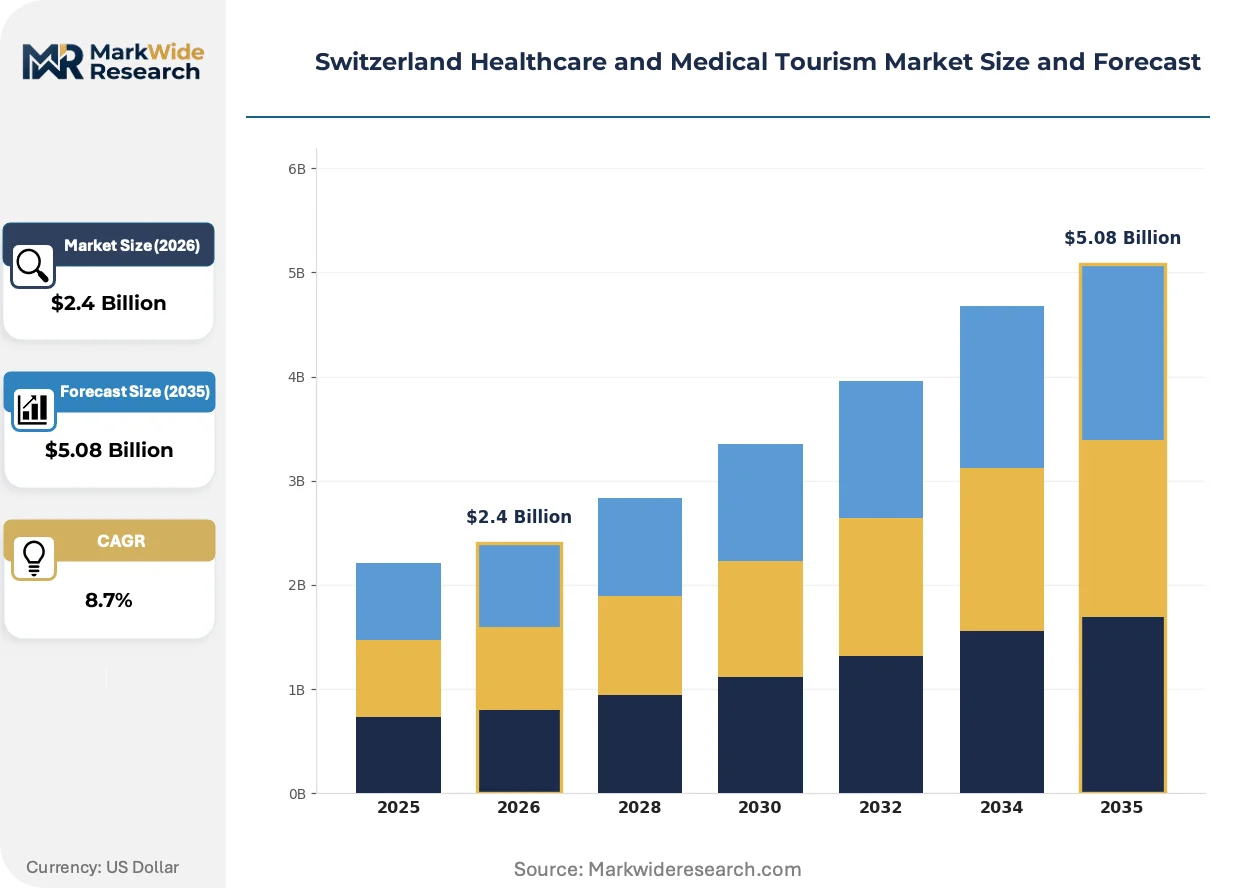
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cosmetic Surgery, Cardiac Procedures, Orthopedic Treatments, Fertility Treatments End User: Individual Patients, Corporate Clients, Health Insurance Providers, Travel Agencies Technology: Telemedicine, Robotic Surgery, Diagnostic Imaging, Electronic Health Records Packaging Type: Travel Packages, Health Packages, Insurance Bundles, Wellness Retreats |
| Companies Covered | Geneva University Hospitals, Lausanne University Hospital, Hirslanden Private Hospital Group, Clinique de Genolier, Clinique Générale-Beaulieu, Swiss Medical Network, Inselspital Bern University Hospital, Clinique La Prairie, University Hospital Zurich, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Healthcare and Medical Tourism Market Strategic Shifts & Innovations
Digital diagnostic platforms and AI-enabled imaging tools are compressing traditional referral pathways, while regulatory harmonization efforts reshape competitive access for foreign device manufacturers.
AI-powered pre-operative planning software is rendering obsolete conventional manual templating for orthopedic implant sizing. Swiss university hospitals in Zurich and Basel deploy machine learning algorithms for joint replacement simulations, reducing revision surgery rates. This capability is rendering obsolete the competitive advantage of historical surgical volume metrics as outcome predictors.
Swissmedic's bilateral alignment negotiations with EU MDR frameworks are creating accelerated review pathways for devices holding prior European certification. Medical technology importers face reduced redundant testing burdens for Class IIa and IIb devices. Cardiac monitoring and implantable device segments are responding by consolidating supplier relationships with manufacturers maintaining dual Swiss-EU technical files.
Direct-to-patient digital marketing channels are displacing traditional medical travel agency intermediaries for elective procedure bookings. Middle Eastern and Asian high-net-worth individuals now research Swiss clinic credentials through telemedicine platforms before committing to treatment travel. This pattern concentrates demand most visibly among Geneva-based cosmetic surgery and Lausanne longevity medicine providers with Mandarin and Arabic digital content capabilities.
Switzerland Healthcare and Medical Tourism Market Segmentation
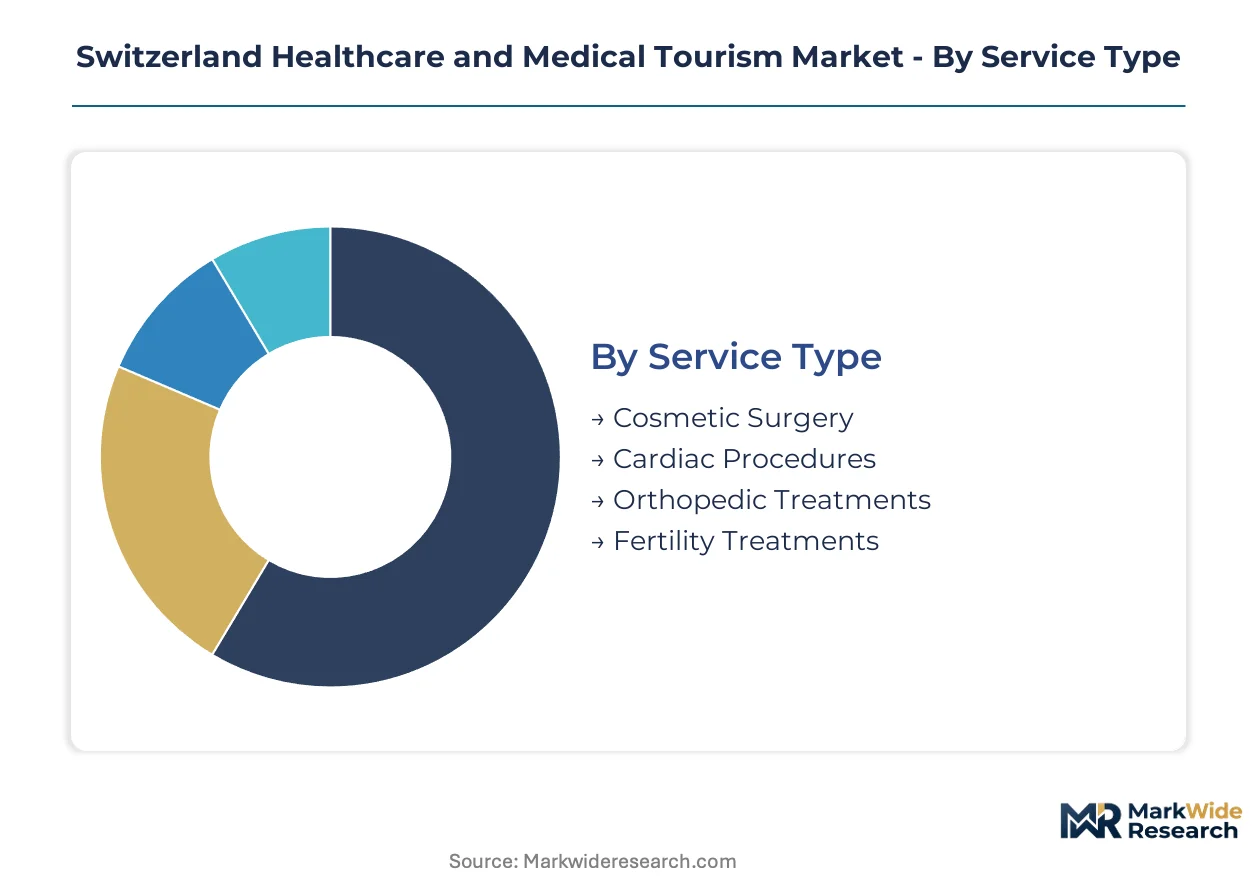
Segmentation reveals how Swiss healthcare providers allocate capital across procedure types with divergent reimbursement profiles and bed occupancy economics. Understanding these splits clarifies where cantonal licensing constraints bite hardest and where premium pricing power concentrates.
Service Type:
Cycle times vary dramatically: cosmetic procedures release beds within 24-48 hours while cardiac interventions demand 5-10 day stays, compressing facility throughput and revenue velocity.
- Cosmetic Surgery:Minimally invasive facial rejuvenation and body contouring procedures dominate this segment. Demand clusters among high-net-worth patients from Gulf states and Southeast Asia seeking discretion and Swissmedic-accredited outcomes.
- Cardiac Procedures:Complex valve replacements and coronary interventions requiring extended ICU monitoring. University Hospital Zurich and Geneva University Hospital anchor referral networks across Middle Eastern sovereign health funds.
- Orthopedic Treatments:Joint replacement and sports medicine procedures leverage robotic surgical platforms for precision outcomes. Lake Geneva corridor facilities command premium positioning for complex revision surgeries.
- Fertility Treatments:Cross-border reproductive medicine services benefit from EMA-aligned regulatory clarity that neighboring EU jurisdictions lack. Swissmedic oversight provides legal certainty for international patients facing restrictive home-country frameworks.
Orthopedic treatments dominate installed base. Fertility treatments are where expansion concentrates.
End User:
Cost tiers separate individual cash-paying patients from corporate wellness program sponsors and insurance intermediaries with divergent price sensitivity and contract structures.
- Individual Patients:High-net-worth international clients booking direct through clinic digital platforms. These buyers accept CHF-denominated pricing and prioritize Swissmedic accreditation over cost minimization.
- Corporate Clients:Multinational employers and sovereign wealth fund health programs negotiating bundled executive health screening contracts. Procurement concentrates through Geneva and Zurich-based clinic relationship managers.
- Health Insurance Providers:Supplementary insurers covering elective procedures excluded from mandatory basic coverage. These intermediaries demand outcome transparency and electronic health record interoperability.
- Travel Agencies:Traditional medical tourism intermediaries losing share to direct-to-patient digital channels. Remaining relevance concentrates on Arabic and Mandarin-language concierge services for first-time Swiss healthcare visitors.
Individual patients generate highest per-case margins. Corporate clients are where volume expansion concentrates.
Technology:
Application maturity varies: telemedicine and electronic health records achieve near-universal deployment while robotic surgery platforms remain concentrated in university hospital networks with capital access.
- Telemedicine:Remote pre-consultation and post-operative monitoring platforms. Geneva-based cosmetic surgery providers deploy Mandarin and Arabic-language interfaces to capture direct international bookings.
- Robotic Surgery:da Vinci and ROSA platforms enabling precision orthopedic and cardiac interventions. Adoption concentrates in Zurich, Basel, and Geneva university hospitals with certified technician pools.
- Diagnostic Imaging:AI-enabled radiology and pathology tools awaiting Swissmedic-EU MDR bilateral harmonization. University Hospital Zurich deploys machine learning algorithms for joint replacement simulations.
- Electronic Health Records:Cantonal data sovereignty laws fragment interoperability. Cross-border patients face continuity gaps when treated across multiple Swiss facilities with incompatible systems.
Diagnostic imaging dominates capital investment pipelines. Telemedicine is where patient acquisition efficiency concentrates.
Packaging Type:
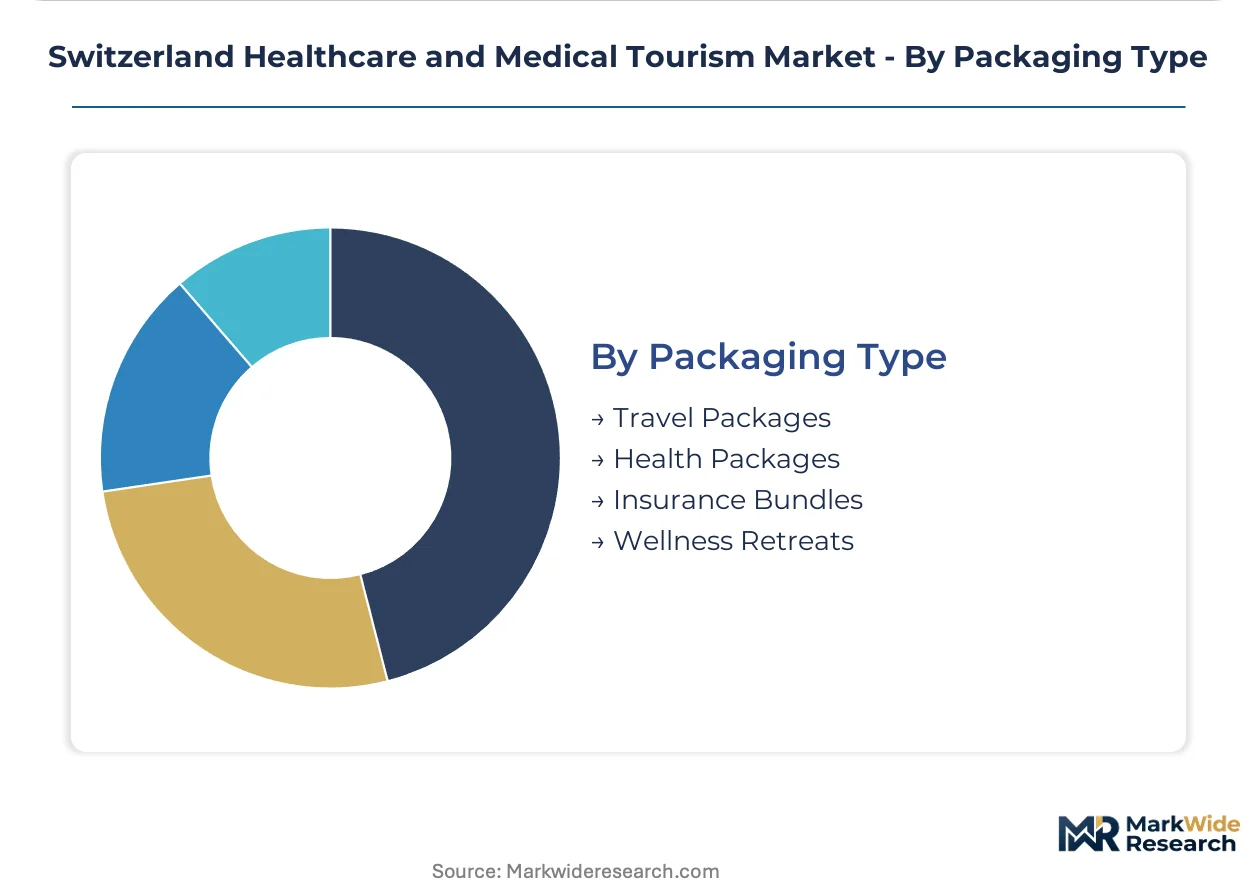
Customer type determines bundle composition: leisure-oriented wellness retreats for discretionary spenders versus clinical health packages for outcome-focused medical travelers.
- Travel Packages:Airfare and accommodation bundled with procedure scheduling. Luxury hospitality partnerships in Montreux and St. Moritz anchor premium positioning for Middle Eastern clientele.
- Health Packages:Procedure, rehabilitation, and follow-up care consolidated under single pricing. Hirslanden Private Hospital Group leverages national clinic network for extended recovery program continuity.
- Insurance Bundles:Supplementary coverage products covering elective procedures and complication contingencies. These products require Swissmedic facility accreditation for policy validity.
- Wellness Retreats:Preventive diagnostics and longevity medicine programs. Clinique La Prairie anchors this segment through proprietary diagnostic protocols and Lake Geneva location.
Health packages dominate revenue concentration. Wellness retreats are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient flows from Gulf states gravitate toward cosmetic and cardiac clusters in the Lake Geneva corridor, while Asian high-net-worth individuals concentrate demand for longevity medicine in Zurich and Ticino cantons. Swissmedic's bilateral alignment with EU MDR frameworks creates regulatory differentiation that neighboring jurisdictions cannot replicate.
Lake Geneva Corridor
Geneva University Hospitals and Lausanne University Hospital anchor cardiac and orthopedic treatment clusters that generate referral networks across Middle Eastern sovereign health funds. Swissmedic facility accreditation requirements exceed FOPH baselines, compressing supply growth and sustaining premium pricing power. Geneva-based cosmetic surgery providers deploy Mandarin and Arabic-language telemedicine interfaces to capture direct international bookings.
Zurich Metropolitan Area
University Hospital Zurich competes on academic credibility in complex orthopedic reconstruction cases utilizing AI-powered pre-operative planning software. Cantonal staffing ratio mandates elevate nurse-to-patient ratios above EU averages, inflating per-procedure labor costs. The city's robotic surgery certified technician pools concentrate adoption of da Vinci and ROSA platforms for precision interventions.
Ticino and Italian-Speaking Cantons
Underdeveloped medical tourism infrastructure relative to German and French regions offers first-mover positioning for Mediterranean-market-focused wellness programs. Swissmedic oversight provides legal certainty for cross-border reproductive services that neighboring EU jurisdictions lack. Lugano and Locarno facilities are expanding longevity medicine capacity to capture Italian and Southern European patient segments.
Basel and Northwestern Switzerland
University Hospital Basel deploys machine learning algorithms for joint replacement simulations that reduce revision surgery rates. The region's pharmaceutical industry density creates spillover demand for clinical trial participation and specialized diagnostic services. Cantonal data sovereignty laws fragment electronic health record interoperability, complicating continuity for cross-border patients treated across multiple facilities.
Bern and Central Switzerland
Inselspital Bern University Hospital anchors referral networks for complex interventions in the national capital region. Fertility treatments represent the fastest-growing service category as Swissmedic regulatory clarity attracts patients facing restrictive home-country frameworks. The region's lower cost structure relative to Zurich and Geneva supports extended rehabilitation program economics.
Switzerland Healthcare and Medical Tourism Market Key Industry Players
Capability concentration sits with university hospital networks possessing robotic surgical platforms and AI-enabled diagnostic tools; scale advantage sits with private hospital groups leveraging national clinic footprints for extended recovery program continuity. The market structures around three tiers: academic medical centers competing on outcome metrics, private hospital groups optimizing bed utilization across cantonal networks, and boutique longevity medicine specialists commanding discretionary pricing. Swissmedic accreditation requirements restrict market access for lower-tier competitors. Dominant competitive moves include telemedicine pre-consultation integration and bilateral EU MDR alignment for accelerated device certification pathways.
Within the academic medical center tier, Geneva University Hospitals, University Hospital Zurich, and Lausanne University Hospital exemplify institutions competing on robotic surgical volume and AI-powered diagnostic capabilities. Among private hospital groups, Hirslanden Private Hospital Group occupies a position representing national network scale advantages for post-treatment rehabilitation continuity. On the boutique specialty vector, Clinique La Prairie anchors longevity medicine segment positioning through proprietary diagnostic protocols and Lake Geneva location premium.
| Leading Market Players |
|---|
| Geneva University Hospitals |
| Lausanne University Hospital |
| Hirslanden Private Hospital Group |
| Clinique de Genolier |
| Clinique Générale-Beaulieu |
| Swiss Medical Network |
| Inselspital Bern University Hospital |
| Clinique La Prairie |
| University Hospital Zurich |
| Others |
Cost & Logistics Intelligence
Swissmedic certification bottlenecks constitute the dominant risk vector, compressing device market entry timelines by 8-14 months beyond EU MDR baselines and forcing three-tier pricing stratification across Swissmedic-accredited premium facilities, FOPH-compliant standard providers, and non-accredited economy alternatives while simultaneously tethering supply chain configuration to cantonal licensing density rather than manufacturing efficiency.
Pricing Analysis
Project-based surgical contracts dominate high-value cardiac and orthopedic procedures, while wellness retreat bookings increasingly shift to subscription-tiered annual membership models. Price differentiation separates Swissmedic-accredited university hospitals commanding CHF-denominated premiums from cantonally licensed standard providers facing margin compression from elevated nurse-to-patient ratios. Pricing pressure stems from Swiss franc appreciation cycles eroding Middle Eastern and US patient competitiveness. Corporate wellness program sponsors exhibit lowest price sensitivity; individual cash-paying patients from neighboring EU jurisdictions demonstrate highest elasticity to currency fluctuations.
Supply Chain Analysis
Upstream medical device and pharmaceutical feedstocks concentrate manufacturing in Germany, the United States, and Japan for robotic surgical platforms and implantable cardiac devices. Swiss clinic networks draw from specialized diagnostic imaging equipment, certified robotic surgery consumables, and proprietary longevity medicine biologics. Single-source vulnerability concentrates in da Vinci and ROSA platform maintenance contracts held by exclusive Swiss distributor agreements. Distribution runs through university hospital procurement consortia and Hirslanden national clinic networks with cantonally fragmented logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Switzerland Healthcare and Medical Tourism Market sits at an AI-enabled diagnostic inflection that is reshaping competitive positioning, with machine learning algorithms for joint replacement simulations rendering obsolete historical surgical volume metrics as outcome predictors.
For Market Incumbents: Build regulatory moats through accelerated Swissmedic-EU MDR bilateral alignment for AI-enabled radiology tools. Incumbents should consolidate supplier relationships with manufacturers maintaining dual Swiss-EU technical files while deploying Mandarin and Arabic-language telemedicine interfaces to capture direct international bookings bypassing traditional medical travel agency intermediaries. For New Entrants and Emerging Players: Ticino and Italian-speaking cantons represent the most penetrable entry point for Mediterranean-market-focused wellness and longevity programs. New entrants should target fertility treatment capacity expansion benefiting from EMA-aligned regulatory clarity that neighboring EU jurisdictions lack, leveraging Swissmedic oversight for legal certainty in cross-border reproductive services. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated clinic networks with robotic surgical platform access and national rehabilitation footprints. Acquisition targets should demonstrate certified technician pools for da Vinci and ROSA platforms alongside proprietary diagnostic protocols. Investors should monitor EU AI Act diagnostic imaging provision harmonization progress as the primary inflection signal for reimbursement and liability shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Swissmedic-EU MDR Bilateral Alignment | Accelerated device certification pathways reduce 8-14 month market entry delays for AI-enabled diagnostic tools. |
| Telemedicine Pre-Consultation Integration | Mandarin and Arabic-language interfaces capture direct Middle Eastern and Asian high-net-worth patient bookings. |
| Robotic Surgery Platform Expansion | da Vinci and ROSA adoption concentrates in university hospitals with certified technician pools for precision interventions. |
| Ticino Wellness Infrastructure Development | First-mover positioning in underdeveloped Italian-speaking cantons targets Mediterranean patient segments. |
| Electronic Health Record Interoperability Investment | Cantonal data sovereignty law navigation enables continuity for cross-border patients treated across multiple facilities. |
Research Approach
Operator-level perspectives from hospital procurement committees, biomedical engineers, GPO contracts managers, and clinic relationship directors anchored the qualitative base. These primary insights combined with secondary validation from Swissmedic device certification databases, FOPH staffing ratio filings, cantonal health department licensing records, and EU AI Act diagnostic imaging provision drafts. Bottom-up procedure volume modeling and top-down market sizing triangulation ensured methodological robustness.
Scenario-bracketing around Swiss franc volatility, regulatory harmonization timelines, and cross-border patient flow disruptions shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, end user archetype, technology deployment maturity, and packaging bundle composition alongside cantonal regulatory cluster differentiation. CAGRs derived from procedure volume trajectories, bed occupancy economics, and premium pricing power persistence. Forecast inputs incorporated robotic surgery adoption curves and telemedicine platform penetration rates.
Practitioners should monitor Swissmedic-EU MDR bilateral negotiation progress, EU AI Act implementation timelines, and Swiss National Bank currency intervention patterns for early signals of forecast revision. Cross-checking against EMA reproductive medicine regulatory divergence trends and Middle Eastern sovereign health fund procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
UK Medical Tourism Market
Medical Tourism
China Medical Tourism Market
Medical Tourism
India Medical Tourism Market
Medical Tourism
Turkey Medical Tourism Market
Medical Tourism
Dental Tourism Market
Medical Tourism
Europe Dental Tourism Market
Medical Tourism
North America Health Tourism Market
Medical Tourism
Spain Medical Tourism Market
Medical Tourism
Italy Medical Tourism Market
Medical Tourism
Europe Medical Tourism Market
Medical Tourism
Japan Medical Tourism Market
Medical Tourism
North America Outbound Medical Tourism Services Market
Medical Tourism
South Korea Medical Tourism Market
Medical Tourism
France Medical Tourism Market
Medical Tourism
Barbados Healthcare and Medical Tourism Market
Medical Tourism
Fertility Tourism Market