
 China Medical Tourism Market | 2026-2036
China Medical Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
China Medical Tourism Market Analysis
International patients from Southeast Asia and Central Asia are reorganizing demand flows across China's hospital network, overtaking traditional domestic medical travel as the fastest-expanding buyer archetype. PLA General Hospital leverages its military-affiliated research pipeline to anchor high-complexity surgical volume. Peking Union Medical College Hospital sustains prestige pricing through century-old brand equity in tertiary care. Shenzhen Qianhai Taikang Hospital competes on cross-border insurance partnerships and streamlined visa-linked admission protocols.
China medical tourism encompasses the organized travel of patients to Chinese healthcare facilities for elective or necessary procedures, encompassing pre-operative consultation, surgical intervention, post-operative rehabilitation, and ancillary wellness services typically delivered through JCI-accredited institutions with English-language care coordination. The primary commercial purpose centers on capturing foreign currency revenue while utilizing excess capacity in advanced diagnostic imaging, robotic surgery suites, and proton therapy centers that outpace domestic utilization rates. Cosmetic surgery and orthopedic procedures dominate treatment type segmentation, with cardiac surgery representing a concentrated margin pool where foreign patients pay three to five times standard domestic rates. Private hospitals and specialty clinics within facility type segmentation attract disproportionate international volume through direct-billing arrangements with insurers in South Korea, Russia, and the United Arab Emirates.
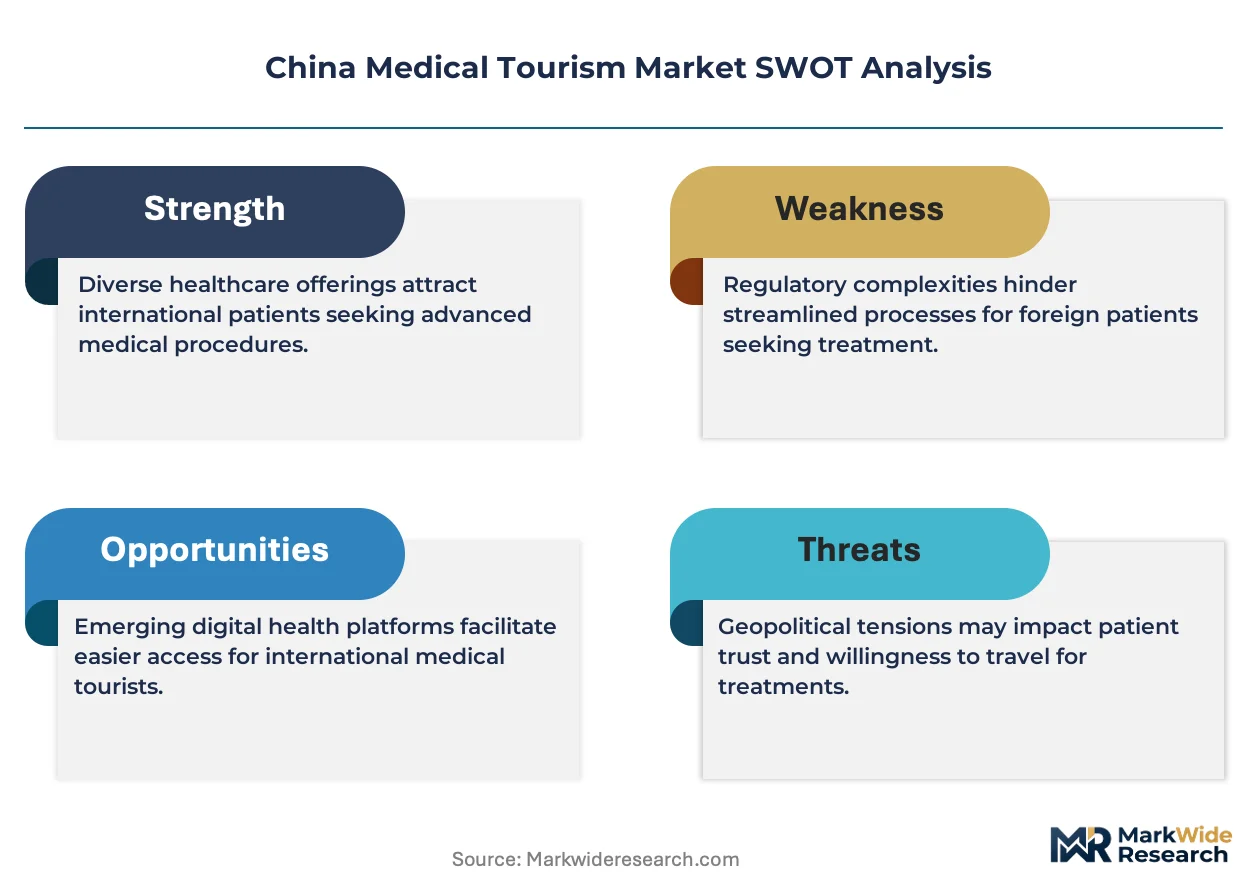
NMPA device approval timelines and GB standards for clinical quality directly shape which hospitals qualify for government-promoted medical tourism zones, while SAMR pricing oversight constrains the premium spread hospitals can charge foreign patients versus domestic counterparts. The country's dual carbon goals pressure facility operators to retrofit surgical centers with energy-efficient HVAC and sterilization systems, adding capital requirements that filter market access. Stakeholders must monitor how Hainan Boao Lecheng International Medical Tourism Pilot Zone regulatory exemptions evolve, as this zone's special status on import permits and foreign physician licensing currently functions as the primary laboratory for policy relaxation that could replicate to Shanghai and Guangdong clusters.
Market Dynamics
International patient flows from Southeast Asia and Central Asia are reorganizing China's hospital network demand patterns, with foreign currency revenue capture now driving capital allocation toward robotic surgery suites and proton therapy centers that operate below domestic utilization thresholds.
Growth Catalysts
- NMPA Streamlined Pathways:Accelerated approval timelines for innovative medical devices enable tertiary hospitals to deploy robotic surgical systems ahead of regional competitors, compressing technology adoption cycles.
- Orthopedic Procedure Demand:Rising incidence of joint replacement needs among aging populations in Kazakhstan and Uzbekistan channels patient volume toward Shanghai's specialty hospital corridor.
- Hainan Boao Lecheng Pilot Zone:Regulatory exemptions on import permits and foreign physician licensing function as a policy laboratory, with replication potential to Guangdong clusters.
Market Restraints
- SAMR Pricing Oversight:Premium spread constraints on foreign versus domestic patient rates compress margin expansion potential for private hospital operators.
- Dual Carbon Capital Requirements:Energy-efficient HVAC and sterilization retrofits add fixed cost burdens that filter market access for smaller facility operators.
- GB Standards Compliance:Clinical quality certification thresholds create qualification barriers for secondary-tier hospitals seeking medical tourism zone designation.
Strategic Opportunities
- Cross-Border Insurance Integration:Direct-billing arrangements with South Korean and UAE insurers represent underpenetrated payment infrastructure ripe for expansion.
- Qianhai Visa-Linked Protocols:Shenzhen's streamlined admission mechanisms offer a template for replication across Pearl River Delta facilities.
- Wellness Service Bundling:Ancillary traditional Chinese medicine rehabilitation packages attract extended-stay medical travelers from Russia and Central Asia.
Industry Challenges
- English-Language Care Coordination:Interpreter staffing gaps at JCI-accredited institutions create service friction during pre-operative consultation phases.
- Legacy System Integration:International patient management platforms require costly retrofitting to interface with domestic hospital information systems.
- Foreign Physician Licensing:Hainan's temporary practice permits face scalability constraints under current Ministry of Health administrative frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Medical Tourism Market |
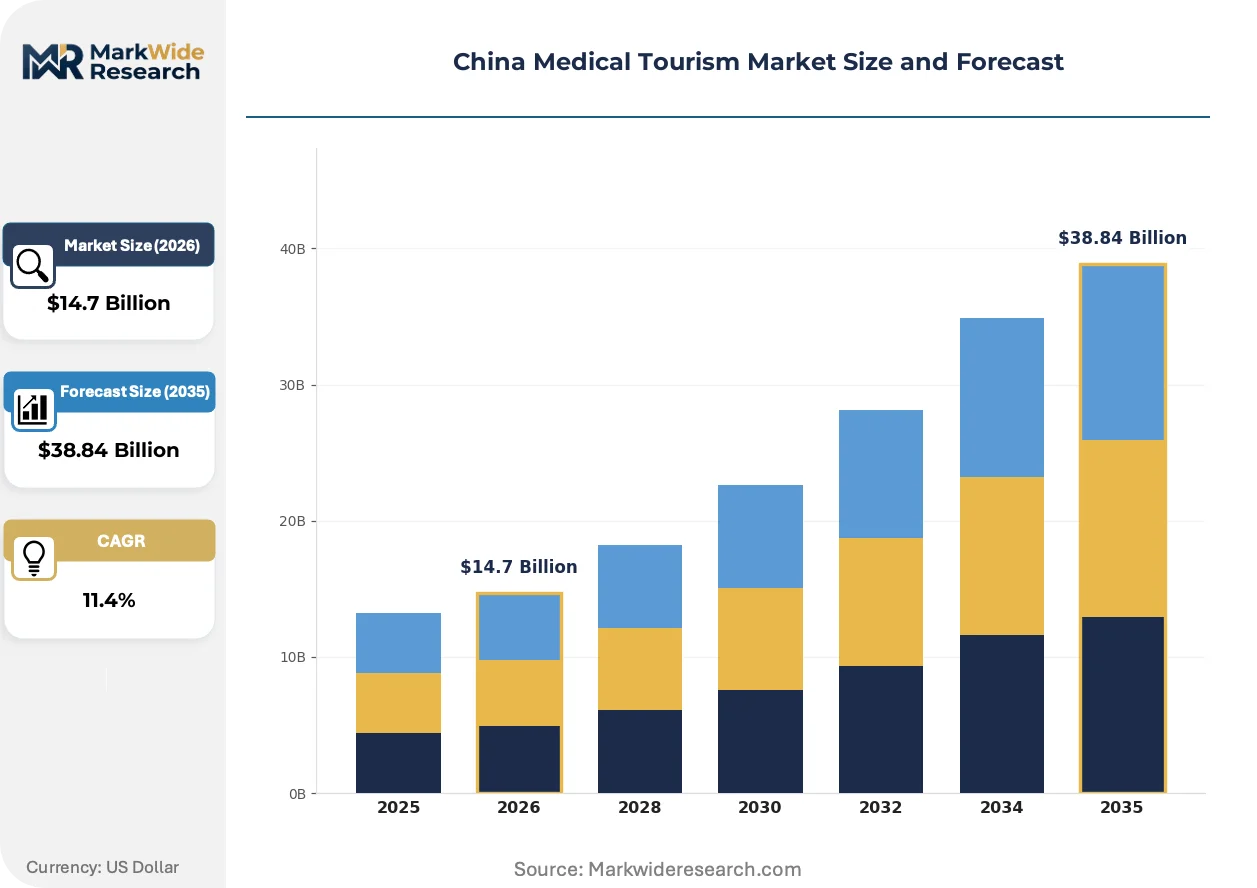
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Cosmetic Surgery, Orthopedic Procedures, Cardiac Surgery, Fertility Treatment Patient Demographics: Domestic Patients, International Patients, Elderly Travelers, Families Service Luxury Level: Economy Services, Mid-Range Services, Premium Services, Luxury Services Facility Type: Public Hospitals, Private Hospitals, Specialty Clinics, Wellness Centers |
| Companies Covered | PLA General Hospital, Shenzhen Qianhai Taikang Hospital, Peking Union Medical College Hospital, China Medical System Holdings Limited, Shanghai Renji Hospital, West China Hospital, Sichuan University, Shulan (Boao) Hospital, Raffles Medical Group, Ruijin Hospital, Shanghai Jiao Tong University, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Medical Tourism Market Emerging Trajectories
Robotic surgical platforms and proton therapy delivery systems are compressing the traditional referral pathway between diagnosis and intervention, while regulatory sandboxes in coastal pilot zones test policy frameworks with national replication potential.
Da Vinci surgical systems and domestically produced orthopedic robotics are decomposing the conventional surgeon-hospital affiliation model. High-complexity procedures now concentrate in facilities with installed robotic suites, regardless of historic academic medical center prestige. PLA General Hospital and Peking Union Medical College Hospital anchor competing volumes through research pipeline access versus century-old brand equity.
NMPA's 2023 medical device innovation pathway revision compresses approval timelines for AI-assisted diagnostic imaging systems. The regulation enables tertiary hospitals to deploy computer-aided detection for cardiac and oncology screening ahead of regional competitors. Shanghai's specialty hospital corridor leverages this regulatory tailwind to market advanced diagnostic packages to Southeast Asian patient brokers.
Patient brokers in Kazakhstan and Uzbekistan now consolidate individual medical travelers into volume contracts with designated Chinese facilities. This channel aggregation displaces fragmented self-directed booking patterns. The shift concentrates negotiating leverage with intermediary networks rather than hospital international departments, compressing margin capture for direct-admission protocols.
China Medical Tourism Market Segmentation
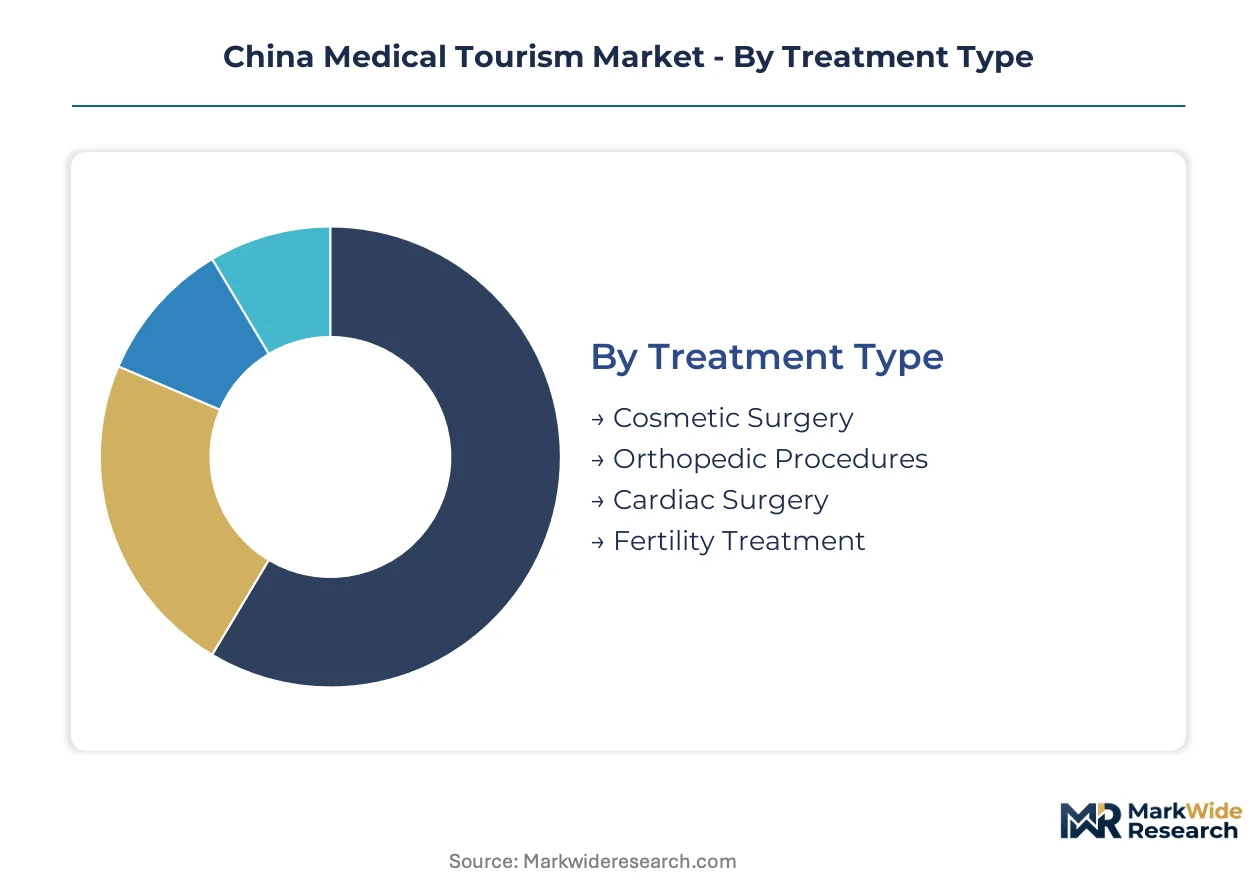
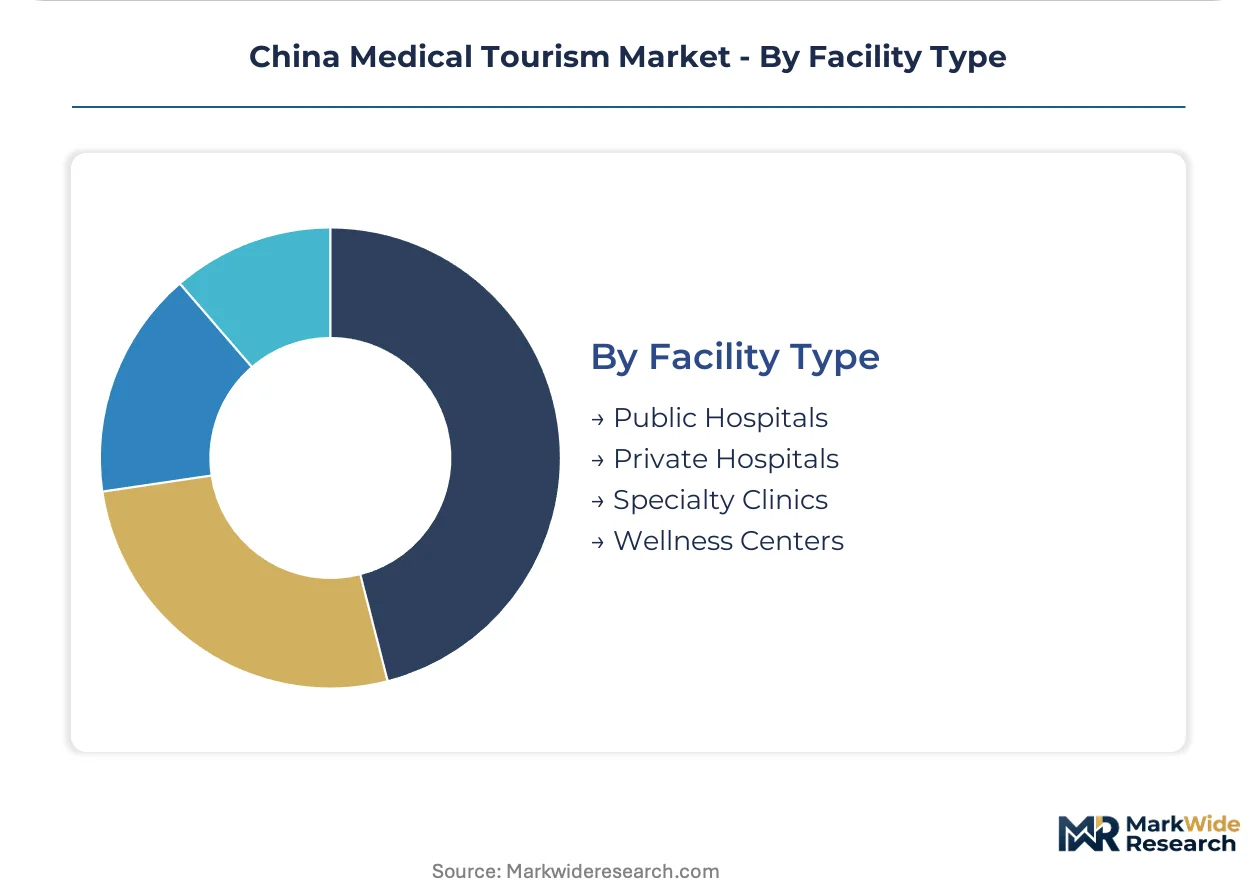
Segmentation in China's medical tourism market reveals how foreign currency revenue concentrates across procedure types and facility tiers. NMPA regulatory pathways and SAMR pricing oversight create divergent competitive dynamics within each category.
Treatment Type:
Substitution pressure from Thailand and South Korea cosmetic clinics forces Chinese providers to differentiate through robotic surgical precision and integrated rehabilitation protocols.
- Cosmetic Surgery:Procedures encompass facial contouring, breast augmentation, and minimally invasive aesthetic interventions delivered through JCI-accredited facilities with English-language nursing staff. Demand concentrates in Shanghai's specialty hospital corridor where direct-billing arrangements with South Korean insurers compress out-of-pocket friction for Southeast Asian patients.
- Orthopedic Procedures:Joint replacement and spinal interventions leverage domestically produced surgical robotics and accelerated rehabilitation protocols. Patient volume from Kazakhstan and Uzbekistan channels toward facilities with installed Da Vinci systems, displacing self-directed booking patterns through broker-consolidated volume contracts.
- Cardiac Surgery:High-complexity coronary bypass and valve replacement procedures.
- Fertility Treatment:IVF and assisted reproductive technology services with traditional Chinese medicine adjuncts.
Orthopedic procedures anchor the volume base while cosmetic surgery gains share at the steepest rate.
Patient Demographics:
Cost tier stratification separates high-complexity surgical travelers from wellness-seeking extended-stay visitors.
- Domestic Patients:Internal medical travel from rural provinces to tertiary urban centers for advanced diagnostic imaging and proton therapy unavailable in home regions.
- International Patients:Foreign currency revenue drivers from Southeast Asia and Central Asia seeking procedures at three-to-five times domestic rate premiums.
- Elderly Travelers:Extended-stay rehabilitation tourists from Russia combining orthopedic recovery with traditional Chinese medicine wellness protocols.
- Families:Multi-generational travel units bundling pediatric specialty consultations with parental cosmetic or wellness services.
International patients anchor the volume base while elderly travelers from Central Asia climb the fastest.
Service Luxury Level:
Margin concentration follows certification grade and English-language care coordination depth rather than pure amenity differentiation.
- Economy Services:Standard ward accommodations with basic interpreter support at public hospital international departments.
- Mid-Range Services:Private rooms with dedicated care coordinators and streamlined admission protocols.
- Premium Services:Concierge-managed itineraries combining surgical intervention with luxury hospitality partnerships.
- Luxury Services:Exclusive villa-style recovery suites with personal nursing staff and traditional Chinese medicine physician house calls.
Mid-range services anchor the volume base while premium offerings expand most quickly.
Facility Type:
Supply concentration in robotic surgery suites and proton therapy centers determines which facilities capture international patient flows regardless of historic prestige.
- Public Hospitals:PLA General Hospital and Peking Union Medical College Hospital anchor high-complexity surgical volume through military-affiliated research pipelines and century-old brand equity.
- Private Hospitals:Shenzhen Qianhai Taikang Hospital competes through cross-border insurance partnerships and visa-linked admission protocols that compress pre-operative consultation friction.
- Specialty Clinics:Concentrated cosmetic and fertility service providers with direct-billing arrangements.
- Wellness Centers:Traditional Chinese medicine rehabilitation facilities catering to extended-stay medical travelers.
Public hospitals anchor the volume base while private hospitals gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Installed robotic surgical suites and proton therapy capacity cluster in coastal megacities with JCI accreditation density, filtering patient flows toward facilities with foreign-language care coordination infrastructure.
Yangtze River Delta
Shanghai's specialty hospital corridor captures orthopedic volume from Kazakhstan and Uzbekistan through broker-consolidated contracts. NMPA streamlined device approvals enable tertiary hospitals to deploy Da Vinci systems ahead of inland competitors. Ruijin Hospital and Renji Hospital anchor high-complexity surgical concentration through century-old academic affiliations.
Pearl River Delta
Shenzhen Qianhai Taikang Hospital competes on visa-linked admission protocols and cross-border insurance partnerships with South Korean carriers. SAMR pricing oversight constrains premium spreads for foreign patients versus domestic rates. The cluster attracts cosmetic surgery demand from Southeast Asia seeking robotic precision differentiation.
Beijing-Tianjin-Hebei
Peking Union Medical College Hospital sustains prestige pricing through brand equity in tertiary care and military-affiliated research pipeline access. GB standards compliance thresholds filter secondary-tier hospitals from medical tourism zone designation. PLA General Hospital anchors cardiac surgery volume through advanced diagnostic imaging capacity.
Hainan Province
Boao Lecheng International Medical Tourism Pilot Zone operates under regulatory exemptions for import permits and foreign physician licensing. Dual carbon goals pressure facility operators to retrofit surgical centers with energy-efficient HVAC systems. The zone functions as policy laboratory with replication potential to Guangdong clusters.
Sichuan-Chongqing
West China Hospital leverages domestically produced orthopedic robotics to capture Central Asian patient flows at compressed cost positions. English-language interpreter staffing gaps create service friction during pre-operative consultation phases. The cluster competes on accelerated rehabilitation protocols bundled with traditional Chinese medicine adjuncts.
China Medical Tourism Market Vendor Landscape
Concentration sits with military-affiliated research hospitals and century-old academic medical centers that anchor high-complexity surgical volume through installed robotic platform density. Private operators compete on cross-border insurance integration and streamlined admission protocols rather than clinical prestige. Three archetypes dominate: legacy academic institutions with brand equity, military-affiliated facilities with research pipeline access, and private hospitals with visa-linked operational efficiency. Competitive moves center on broker-consolidated volume contracting and proton therapy center capacity expansion.
Among Beijing-based academic institutions, Peking Union Medical College Hospital occupies a position exemplifying prestige-tier positioning through century-old tertiary care reputation. PLA General Hospital represents the military-affiliated archetype with research pipeline advantages in high-complexity procedures. Shenzhen Qianhai Taikang Hospital sits within the private operator tier, competing through cross-border insurance partnerships rather than historic clinical equity.
| Leading Market Players |
|---|
| PLA General Hospital |
| Shenzhen Qianhai Taikang Hospital |
| Peking Union Medical College Hospital |
| China Medical System Holdings Limited |
| Shanghai Renji Hospital |
| West China Hospital, Sichuan University |
| Shulan (Boao) Hospital |
| Raffles Medical Group |
| Ruijin Hospital, Shanghai Jiao Tong University |
| Others |
Supply Flow & Price Mechanics
Forty-five-day device procurement cycles for robotic surgical systems concentrate purchasing power among tertiary hospitals with NMPA fast-track eligibility, compressing margin capture for secondary-tier facilities and anchoring price premiums to certification grade rather than pure clinical capacity.
Pricing Analysis
SAMR pricing oversight dictates the pricing tier structure across public and private hospital operators, constraining the premium spread between foreign and domestic patient rates. A three-tier pricing structure across premium, standard, and economy levels stratifies by JCI accreditation status and English-language care coordination depth. Cost compression in economy-tier public hospital international departments is intensifying because broker-consolidated volume contracts concentrate negotiating leverage with intermediary networks. Southeast Asian cosmetic surgery patients demonstrate highest price sensitivity, while cardiac surgery seekers from Central Asia exhibit lowest elasticity due to limited regional alternatives.
Supply Chain Analysis
Port congestion at Shanghai Yangshan and Ningbo-Zhoushan container terminals elevates inbound logistics costs for imported Da Vinci surgical systems and proton therapy components, filtering market access toward capital-rich facility operators. Manufacturing concentration for domestically produced orthopedic robotics rests on Shanghai and Suzhou industrial clusters, with critical component dependencies on German precision motors and Japanese optical sensors. Single-source vulnerability in foreign physician licensing approvals through Hainan Boao Lecheng creates supply chain risk for pilot zone expansion. Distribution runs through broker-consolidated volume contracts rather than direct hospital international departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NMPA's 2023 medical device innovation pathway revision functions as the decisive regulatory inflection, compressing technology adoption cycles and rewarding first-mover tertiary hospitals with sustained volume concentration.
For Market Incumbents: Secure broker-consolidated volume contracts with Kazakhstan and Uzbekistan patient networks before competitor replication erodes margin capture. Deepen backward integration into domestically produced orthopedic robotics manufacturing to offset import dependency on German and Japanese components. Anchor high-complexity surgical volume through accelerated NMPA fast-track applications for AI-assisted diagnostic imaging systems.
For New Entrants and Emerging Players: Lead with cross-border insurance direct-billing infrastructure targeting South Korean and UAE carriers as the most penetrable payment friction point. Target Sichuan-Chongqing cluster facilities where English-language interpreter staffing gaps create service friction ripe for operational differentiation. Deploy visa-linked admission protocol replication from Shenzhen Qianhai template across secondary Pearl River Delta locations.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because Hainan Boao Lecheng's exemption laboratory status carries replication potential to Guangdong and Shanghai clusters under favorable policy continuity. Acquisition targets should concentrate on private hospital operators with installed robotic surgical suites and underdeveloped international patient management platforms. Monitor NMPA device approval timeline compression as the signal for accelerated capital deployment into tertiary hospital technology retrofit cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Fast-Track Device Approval | Accelerates robotic surgical system deployment ahead of regional competitors in Shanghai corridor. |
| Broker-Consolidated Volume Contracting | Concentrates negotiating leverage with Kazakhstan and Uzbekistan patient networks. |
| Cross-Border Insurance Direct-Billing | Compresses out-of-pocket friction for South Korean and Southeast Asian patient segments. |
| Visa-Linked Admission Protocol Replication | Extends Shenzhen Qianhai operational template across Pearl River Delta facility network. |
| Domestic Orthopedic Robotics Manufacturing | Reduces import dependency on German precision motors and Japanese optical sensors. |
Methodological Framework
A standing panel of hospital international department directors, NMPA regulatory affairs specialists, patient broker network operators, and cross-border insurance contracts managers provided ongoing calibration across primary interview cycles. Secondary validation drew from NMPA medical device registration databases, SAMR pricing oversight filings, hospital procurement records, and JCI accreditation status directories. Bottom-up facility capacity assessments triangulated against top-down foreign patient volume estimates from border entry statistics and aviation passenger manifests.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including treatment type, patient demographic archetype, service luxury tier, and facility ownership structure. CAGRs were derived from fitted growth curves anchored to installed robotic surgical suite capacity and proton therapy center expansion pipelines. Forecast inputs incorporated NMPA approval timeline trajectories and Hainan Boao Lecheng regulatory exemption evolution pathways.
Forecasts assume regulatory continuity in NMPA device approval frameworks and SAMR pricing oversight regimes; material policy shifts would require re-modeling. Specific risk factors include foreign physician licensing scalability constraints under Ministry of Health administrative frameworks and dual carbon retrofit capital requirements filtering market access. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
Spain Medical Tourism Market
Medical Tourism
France Medical Tourism Market
Medical Tourism
Europe Medical Tourism Market
Medical Tourism
GCC Countries Medical Tourism Market
Medical Tourism
UK Medical Tourism Market
Medical Tourism
India Medical Tourism Market
Medical Tourism
Japan Medical Tourism Market
Medical Tourism
Switzerland Healthcare and Medical Tourism Market
Medical Tourism
North America Health Tourism Market
Medical Tourism
Fertility Tourism Market
Medical Tourism
Italy Medical Tourism Market
Medical Tourism
Medical Tourism Market
Medical Tourism
North America Outbound Medical Tourism Services Market
Medical Tourism
Europe Dental Tourism Market
Medical Tourism
Dental Tourism Market
Medical Tourism
Outbound Medical Tourism Services Market