
 Dental Tourism Market | 2026-2036
Dental Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Tourism Market Analysis
Cosmetic dentistry revenue is narrowing the margin gap with traditional implantology across leading dental tourism chains. Bangkok International Dental Center leverages its JCI-accredited campus to anchor Thai market share. Apollo Hospitals Enterprise Ltd competes through integrated medical tourism infrastructure spanning diagnostics to post-operative care. Dentakay differentiates via Budapest-based digital smile design studios serving Western European patient flows.
Dental tourism denotes the organized travel of patients across national borders to obtain oral health services at lower cost, higher quality, or reduced wait times than available domestically; procedures typically involve CAD/CAM-milled crowns, titanium implant fixtures, and chairside 3D-printed surgical guides fabricated to ISO 13485 standards. Cosmetic dentistry commands premium pricing due to elective aesthetic demand and short procedural windows, while implantology sustains volume through aging demographics requiring full-arch rehabilitation. Teledentistry platforms are expanding fastest as pre-travel virtual consultations reduce patient acquisition costs and treatment planning cycles.
Thailand's Medical Hub designation under Ministry of Public Health oversight, Hungary's EU-compliant CE-marked device frameworks, and India's NABH accreditation standards collectively shape market access and liability protocols for international dental providers. FDA-cleared laser systems and ISO 9001 quality management requirements further constrain which clinics qualify for insured patient referrals. Stakeholders must monitor evolving reimbursement clawback rules in source-country insurance markets and accreditation portability agreements between destination facilities and European health funds.
Market Dynamics
Digital impression systems and chairside CAD/CAM fabrication are compressing treatment cycles from weeks to single-visit protocols, fundamentally restructuring how dental tourism providers compete on turnaround time and patient throughput.
Growth Catalysts
- JCI Accreditation Frameworks:Thailand's Ministry of Public Health leverages Joint Commission International standards to certify facilities eligible for insured patient referrals from European health funds.
- Laser-Based Soft Tissue Procedures:Erbium and diode laser platforms reduce post-operative recovery windows, enabling compressed travel itineraries for cross-border cosmetic patients.
- Titanium Implant Fixture Manufacturing:ISO 13485-certified machine shops in India and Hungary supply destination clinics with cost-advantaged implant components.
Market Restraints
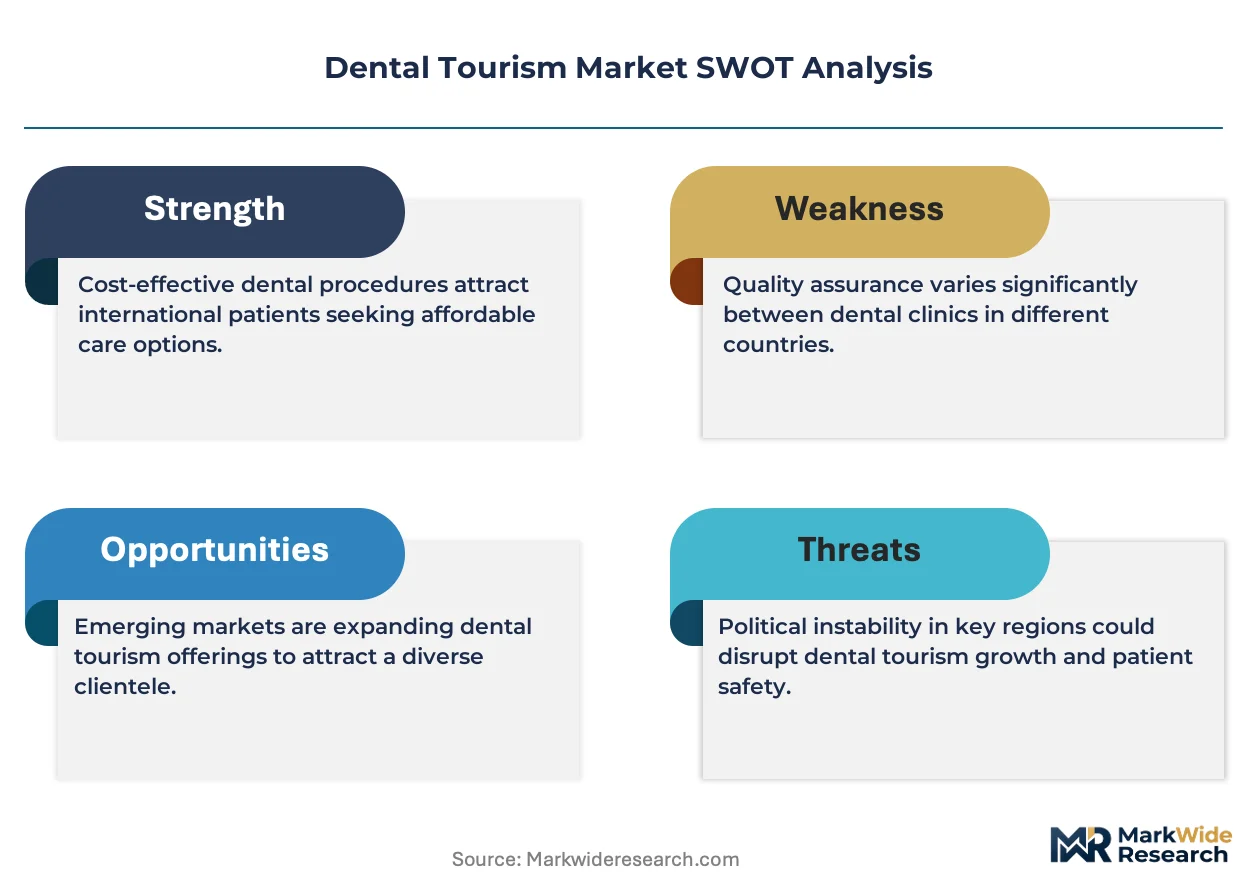
- Reimbursement Clawback Rules:Source-country insurers in Germany and the Netherlands retroactively deny claims when post-operative complications arise abroad, creating liability uncertainty for patients.
- CE-Marked Device Dependency:Hungarian clinics rely on EU-authorized suppliers for laser systems and CAD/CAM mills, exposing margins to euro-denominated input volatility.
- Biocompatibility Testing Bottlenecks:ISO 10993-compliant validation for 3D-printed surgical guides extends procurement lead times by 8-14 weeks.
Strategic Opportunities
- Teledentistry Pre-Travel Consultations:Virtual treatment planning platforms reduce patient acquisition costs and enable remote case acceptance before travel booking.
- Sub-Saharan African Source Markets:Rising middle-class demand in Nigeria and Kenya for cosmetic procedures creates new outbound patient flows toward Indian and Thai providers.
- EU AI Act Compliance Pathways:Automated diagnostic imaging tools that meet European artificial intelligence regulations gain preferential placement in insured referral networks.
Industry Challenges
- Prosthodontist Credential Portability:Specialist qualifications recognized in Thailand often require supplementary examination for practice rights in source-country insurance networks.
- Legacy Practice Management Integration:Teledentistry platforms face interoperability friction with existing patient record systems in mid-sized clinic chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Tourism Market |
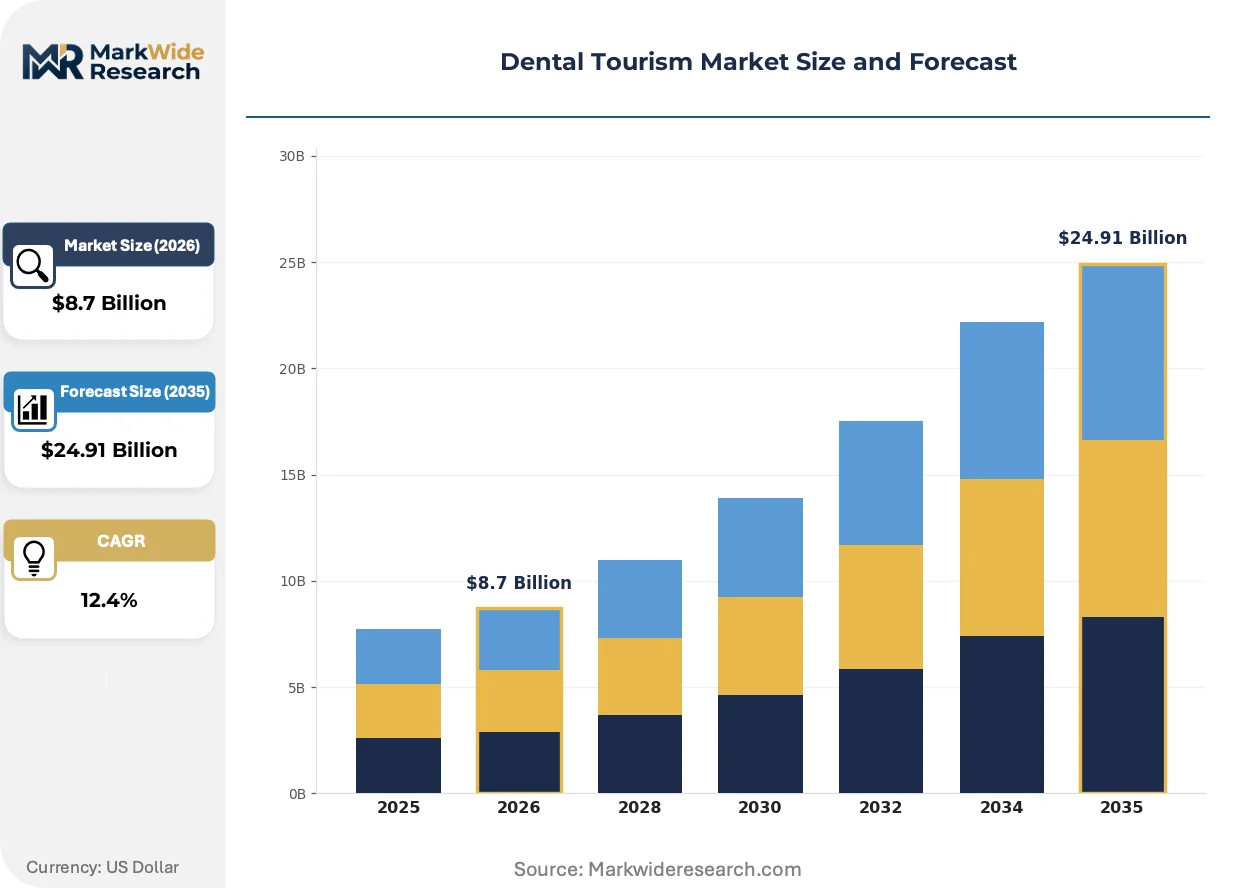
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $24.91 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cosmetic Dentistry, Orthodontics, Implants, Periodontics End User: International Patients, Local Residents, Dental Insurance Holders, Executives Pricing Model: Package Deals, Pay-Per-Procedure, Subscription Plans, Discounts Technology: 3D Printing, Laser Technology, Digital Impressions, Teledentistry |
| Companies Covered | Medlife Group, Clove Dental, Apollo Hospitals Enterprise Ltd, Dentakay, Thantakit International Dental Center, Fortis Healthcare Ltd, Bangkok International Dental Center, Adria Dental Group, Prince Court Medical Centre, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Tourism Market Emerging Trajectories
Clinical digitization and regulatory harmonization across source and destination markets are compressing traditional barriers to cross-border dental care, reshaping competitive advantage around data portability and accreditation interoperability.
Intraoral scanning hardware is hybridizing with cloud-based treatment planning software to enable real-time collaboration between destination specialists and source-country general practitioners. Western European dental chains are deploying these integrated workflows to capture patient referrals earlier in the decision cycle. The technology is hybridizing the traditional boundary between diagnostic and treatment phases, allowing pre-paid case acceptance before travel commitment.
EU Medical Device Regulation (MDR) implementation is forcing non-EU manufacturers of titanium implants and surgical guides to establish authorized representatives within the European Economic Area. Hungarian and Polish dental tourism hubs face supply chain reconfiguration costs as legacy ISO 13485 certificates require MDR supplementation. Implantology-focused clinics in Budapest are consolidating supplier relationships to reduce compliance fragmentation.
Patients are bundling dental procedures with wellness tourism packages, extending average length of stay and per-trip expenditure. Thai hospitality operators are capturing this convergence by packaging JCI-accredited dental campuses with resort recovery facilities. The pattern is most pronounced among Australian and Middle Eastern patients seeking multi-procedure full-arch rehabilitations.
Dental Tourism Market Segmentation
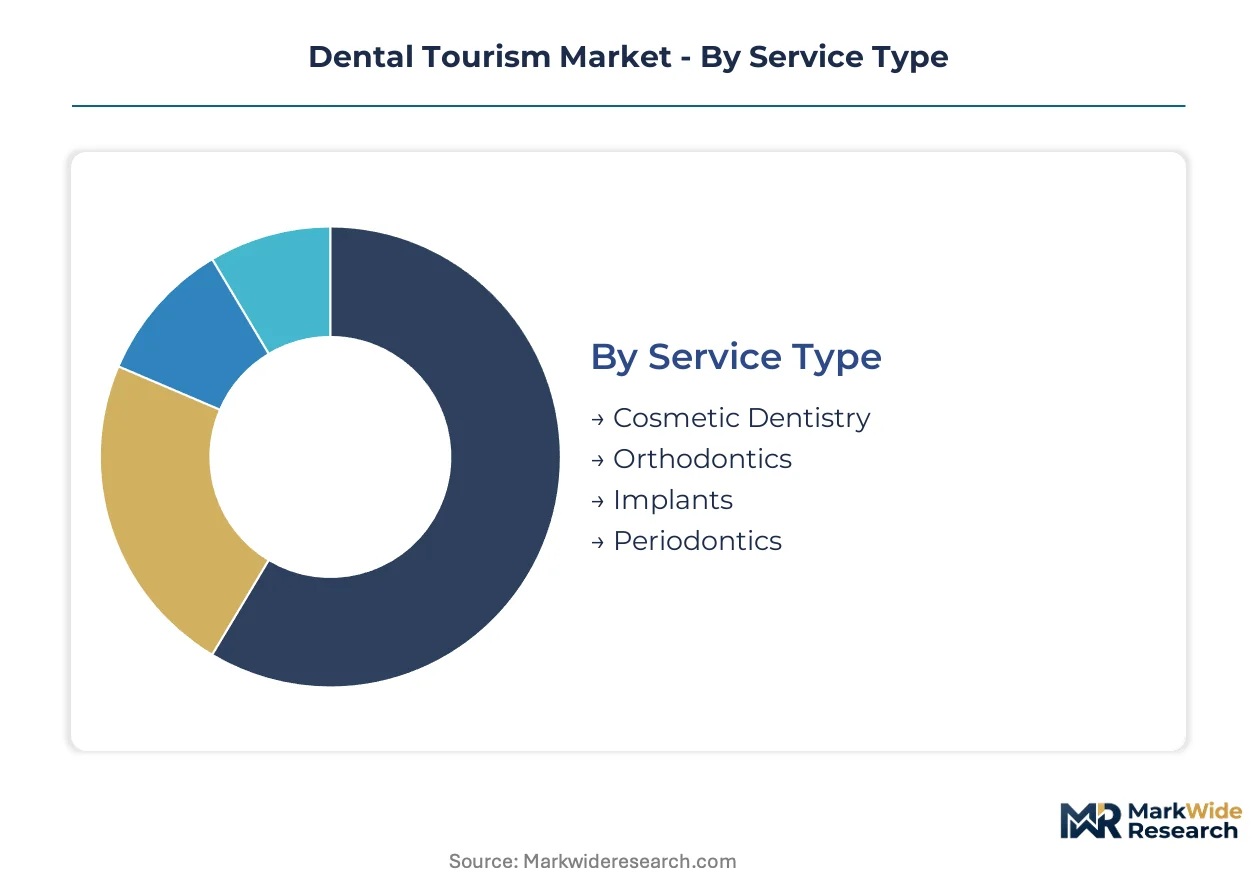
Dental tourism providers structure service portfolios around procedure complexity, patient origin, and technology intensity. Segmentation reveals where margin concentration diverges from volume throughput across destination clinics.
Service Type:
Mature implantology anchors revenue stability while emerging cosmetic protocols capture premium pricing elasticity.
- Cosmetic Dentistry:Veneers, whitening, and smile design procedures command elective pricing multiples. Demand concentrates among Western European and Australian patients seeking rapid aesthetic turnaround during compressed travel windows.
- Implants:Titanium fixture placement and full-arch rehabilitation sustain volume through aging demographics requiring complex oral restoration. Thai and Hungarian clinics process the highest implant caseloads for cross-border patients.
- Orthodontics:Clear aligner therapy and accelerated orthodontic protocols attract younger patient segments.
- Periodontics:Laser-assisted gum contouring and regenerative procedures address soft tissue pathology.
Implants retain volume leadership; cosmetic dentistry holds the steepest expansion curve.
End User:
Premium pricing tiers separate insured referral networks from self-pay segments.
- International Patients:Cross-border travelers from Germany, the Netherlands, and the UK drive procedural volume at JCI-accredited facilities. European health fund portability agreements shape destination selection for this segment.
- Dental Insurance Holders:Reimbursement-eligible patients require pre-authorization compliance and post-operative documentation for claims processing.
- Local Residents:Domestic Thai, Hungarian, and Indian patients access tiered pricing below international rates.
- Executives:Corporate wellness programs and concierge medical tourism packages target C-suite travelers.
International patients retain volume leadership; dental insurance holders hold the steepest expansion curve.
Pricing Model:
Revenue predictability varies sharply across fixed-fee and variable structures.
- Package Deals:Bundled procedure-accommodation-transport offerings reduce patient decision friction. Bangkok and Budapest operators standardize these for full-arch rehabilitation cases spanning 7-14 day itineraries.
- Pay-Per-Procedure:Itemized billing dominates single-visit cosmetic interventions.
- Subscription Plans:Annual maintenance contracts cover follow-up care and complication management.
- Discounts:Volume-based and seasonal pricing targets low-season capacity utilization.
Package deals retain volume leadership; subscription plans hold the steepest expansion curve.
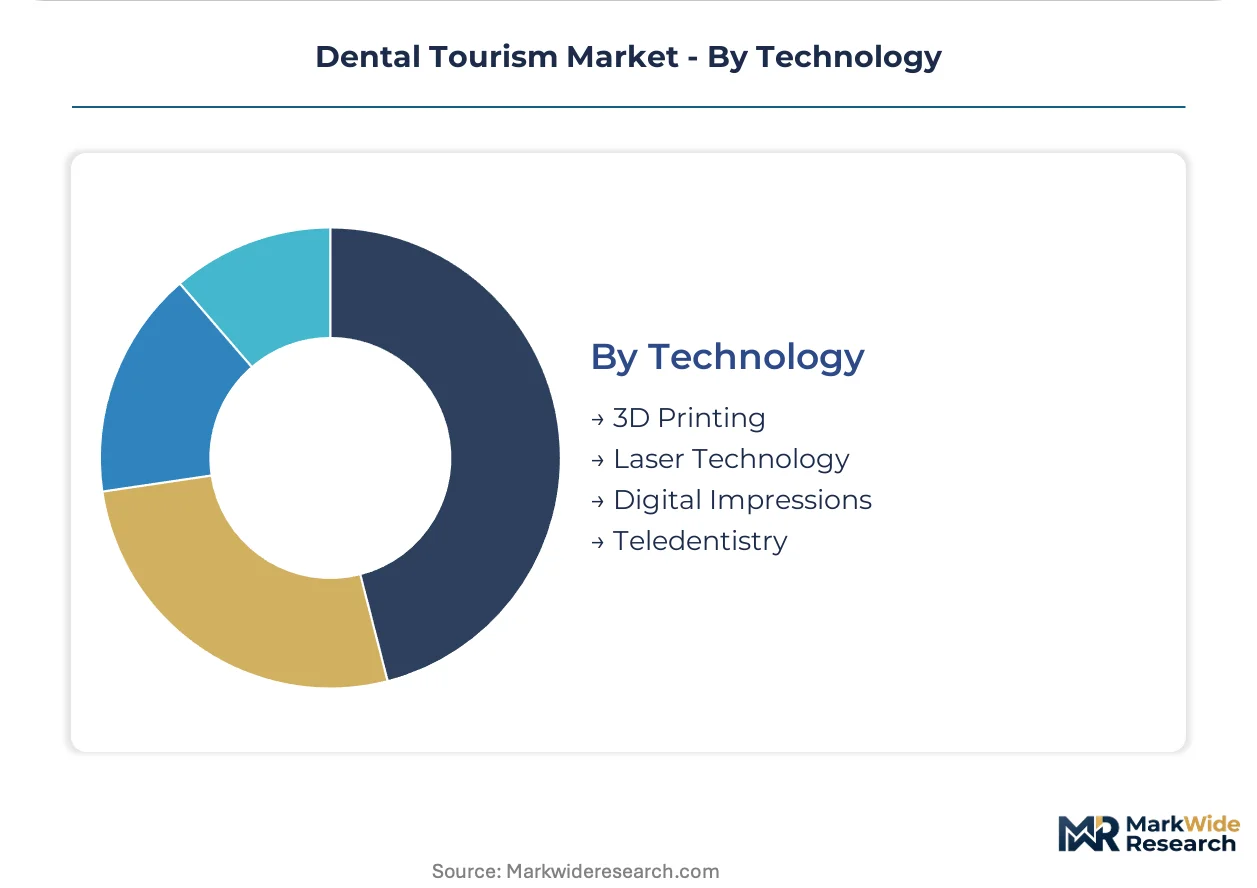
Technology:
Capital intensity separates high-throughput digital clinics from conventional operatories.
- Digital Impressions:Intraoral scanning and chairside CAD/CAM compress treatment cycles from weeks to single visits. Hungarian clinics deploy these workflows to capture Western European same-day crown demand.
- Teledentistry:Virtual consultation platforms reduce patient acquisition costs and enable remote case acceptance before travel booking.
- 3D Printing:Surgical guide fabrication and provisional prosthesis production support implantology accuracy.
- Laser Technology:Erbium and diode platforms enable minimally invasive soft tissue procedures with compressed recovery windows.
Digital impressions retain volume leadership; teledentistry holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for cosmetic procedures peaks in Western European source markets while implantology demand shows greater inelasticity across aging populations. Thai and Hungarian providers capture the widest spreads between domestic and cross-border pricing. Indian clinics compete on titanium implant fixture cost structures.
Thailand
Medical tourism arrivals from Australia and the Middle East concentrate in Bangkok's JCI-accredited dental campuses. The Ministry of Public Health's Medical Hub designation streamlines facility certification for European health fund portability. Bangkok International Dental Center anchors market share through integrated resort-recovery packages.
Hungary
Western European patients seeking same-day CAD/CAM crowns drive volume in Budapest's digital smile design studios. EU Medical Device Regulation compliance requirements force supplier consolidation for CE-marked laser systems. The Budapest cluster processes the highest implant caseloads for German and Dutch cross-border flows.
India
Rising middle-class demand from Nigeria and Kenya converges with inbound medical tourism at Apollo Hospitals' integrated infrastructure. NABH accreditation standards align with ISO 13485-certified domestic titanium implant manufacturing. Mumbai and Delhi clusters compete on full-arch rehabilitation cost structures.
Turkey
Antalya's hospitality-integrated dental facilities capture Russian and UK patient flows seeking compressed treatment itineraries. The country's national health regulator oversees facility licensing for international patient eligibility. Istanbul's aesthetic dentistry centers specialize in veneer and whitening protocols.
Mexico
US border-state patients seeking implantology cost advantages drive Tijuana and Los Algodones clinic throughput. Proximity to California and Texas reduces travel friction for same-week treatment windows. Baja California clusters specialize in package-deal pricing for full-arch rehabilitation cases.
Dental Tourism Market Vendor Landscape
Capability concentration sits with tier-one integrated hospital networks; scale advantage sits with specialized dental clinic chains. The market structures around three archetypes: hospitality-integrated campus operators, multi-specialty hospital dental divisions, and standalone cosmetic dentistry studios. Consolidation pressures favor acquisition of teledentistry platforms and CAD/CAM fabrication capacity. Geographic expansion into Sub-Saharan African source markets represents the dominant competitive move alongside JCI accreditation pursuit.
Among Asia-Pacific integrated providers, Apollo Hospitals Enterprise Ltd and Bangkok International Dental Center occupy positions within the multi-facility hospital network tier. Dentakay exemplifies the European-focused cosmetic specialization archetype from its Budapest base. These three anchors demonstrate how accreditation portability and digital workflow integration separate premium-positioned competitors from price-driven regional operators.
| Leading Market Players |
|---|
| Medlife Group |
| Clove Dental |
| Apollo Hospitals Enterprise Ltd |
| Dentakay |
| Thantakit International Dental Center |
| Fortis Healthcare Ltd |
| Bangkok International Dental Center |
| Adria Dental Group |
| Prince Court Medical Centre |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Bangkok's JCI-accredited dental campuses compresses per-procedure margins while simultaneously pressuring suppliers of titanium implant fixtures and CAD/CAM mills to absorb volume discounts. This utilization dynamic forces Hungarian clinics to front-load equipment depreciation into package-deal pricing, and drives Indian manufacturers toward captive titanium sourcing to defend margin structures.
Pricing Analysis
After-sales revenue from annual maintenance contracts and complication management drives lifetime patient value beyond the initial procedure window. Three-tier pricing structure across JCI-accredited premium, NABH-standard, and non-accredited economy levels segments Western European insured referrals from self-pay cosmetic patients. Cost compression in economy-tier implantology is intensifying because ISO 13485-certified Indian manufacturers are expanding direct-to-clinic distribution. Dental insurance holders demonstrate highest price sensitivity due to pre-authorization compliance burdens, while executive wellness program participants show lowest sensitivity.
Supply Chain Analysis
EU Medical Device Regulation export-control frameworks restrict non-EEA manufacturers of titanium implants and laser systems from supplying Hungarian and Polish clinics without authorized representative establishment. Geographic supply concentration centers on India, Hungary, and Thailand for ISO 13485-certified fabrication capacity. Raw material dependencies rest on titanium alloy feedstock, erbium laser crystals, and dental-grade zirconia blanks. Single-source vulnerability from euro-denominated CE-marked device procurement creates margin exposure for Budapest operators. Distribution runs through hospitality-integrated campus operators and multi-facility hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental tourism operates as high-growth disruption where teledentistry platforms and EU AI Act-compliant diagnostic tools are compressing patient acquisition costs and pre-travel decision cycles. This technological inflection rewards first movers who integrate virtual consultation workflows with accredited destination infrastructure.
For Market Incumbents: Harden JCI accreditation portability across European health fund networks to lock in insured referral volumes. Consolidate CAD/CAM fabrication capacity in-house to reduce supplier fragmentation under EU MDR compliance costs. Acquire teledentistry platforms to capture patients earlier in the decision cycle before travel commitment.
For New Entrants and Emerging Players: Build out Sub-Saharan African source market presence in Nigeria and Kenya where rising middle-class cosmetic demand lacks established referral channels. Partner with Apollo Hospitals or Bangkok International Dental Center for co-branded package deals rather than competing on accreditation timelines. Deploy virtual smile design consultations as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Capital is best deployed toward hospitality-integrated campus operators with existing JCI certification and resort-recovery infrastructure. Long-term viability across the projection horizon hinges on teledentistry platform integration and accreditation interoperability with European health funds. Monitor EU AI Act compliance pathways for automated diagnostic imaging tools as the signal for preferential insured network placement.
| Strategic Initiative | Industry Significance |
|---|---|
| Teledentistry Platform Integration | Virtual consultation workflows reduce patient acquisition costs for Bangkok and Budapest operators. |
| JCI Accreditation Expansion | Thailand's Medical Hub designation streamlines certification for European health fund portability agreements. |
| EU MDR Compliance Pathway | Authorized representative establishment enables continued CE-marked device supply to Hungarian clinics. |
| Sub-Saharan African Market Entry | Nigeria and Kenya outbound flows create first-mover advantage for Indian and Thai providers. |
| CAD/CAM Fabrication Consolidation | In-house chairside milling reduces ISO 13485 supplier dependency and compresses treatment cycles. |
Methodological Framework
Desk research of hospital procurement databases, GPO contracts, and Ministry of Public Health facility registries preceded structured interviews with dental tourism clinic directors, biomedical equipment procurement managers, and European health fund reimbursement specialists. Primary fieldwork with JCI-accredited facility administrators in Bangkok and Budapest was cross-referenced against customs data for titanium implant fixture trade flows. Secondary validation drew from ISO certification registries, EU MDR authorized representative filings, and teledentistry platform user metrics. Bottom-up procedure volume estimates and top-down market sizing were triangulated for convergence.
Assumptions regarding EU AI Act implementation timelines, JCI accreditation renewal rates, and teledentistry platform adoption curves were held fixed across the projection horizon while titanium alloy pricing and euro-rupee exchange rates were stress-tested. The analytical framework segmented by service type, end user category, pricing model, and technology intensity. CAGRs were derived from fitted growth curves applied to procedure volume trajectories and average revenue per case inputs including laser system utilization rates and CAD/CAM equipment depreciation schedules.
Stress conditions across reimbursement clawback rule enforcement, EU MDR compliance cost pass-through, and Sub-Saharan African currency volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding patient flow sustainability and accreditation portability. Material shifts in European health fund portability agreements or FDA-cleared laser system approval timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
Italy Medical Tourism Market
Medical Tourism
North America Outbound Medical Tourism Services Market
Medical Tourism
Barbados Healthcare and Medical Tourism Market
Medical Tourism
Thailand Medical Tourism Market
Medical Tourism
GCC Countries Medical Tourism Market
Medical Tourism
Asia-Pacific Medical Tourism Market
Medical Tourism
Turkey Medical Tourism Market
Medical Tourism
Medical Tourism Market
Medical Tourism
Europe Medical Tourism Market
Medical Tourism
China Medical Tourism Market
Medical Tourism
Malaysia Medical Tourism Market
Medical Tourism
Europe Dental Tourism Market
Medical Tourism
Outbound Medical Tourism Services Market
Medical Tourism
France Medical Tourism Market
Medical Tourism
Japan Medical Tourism Market
Medical Tourism
North America Health Tourism Market